
 Resveratrol Market | 2026-2036
Resveratrol Market Size, Share, and Industry Trends Forecast 2026-2036
Resveratrol Market Analysis
Precision fermentation is rewriting resveratrol production economics by displacing traditional Polygonum cuspidatum root extraction with microbial biosynthesis. Evolva leverages yeast-based biomanufacturing to sustain cost advantages over botanical sourcing. Huisong Pharmaceuticals anchors Asia-Pacific supply through integrated extraction and purification operations. dsm-firmenich differentiates via synthetic biology platforms that compete on purity consistency and traceability.
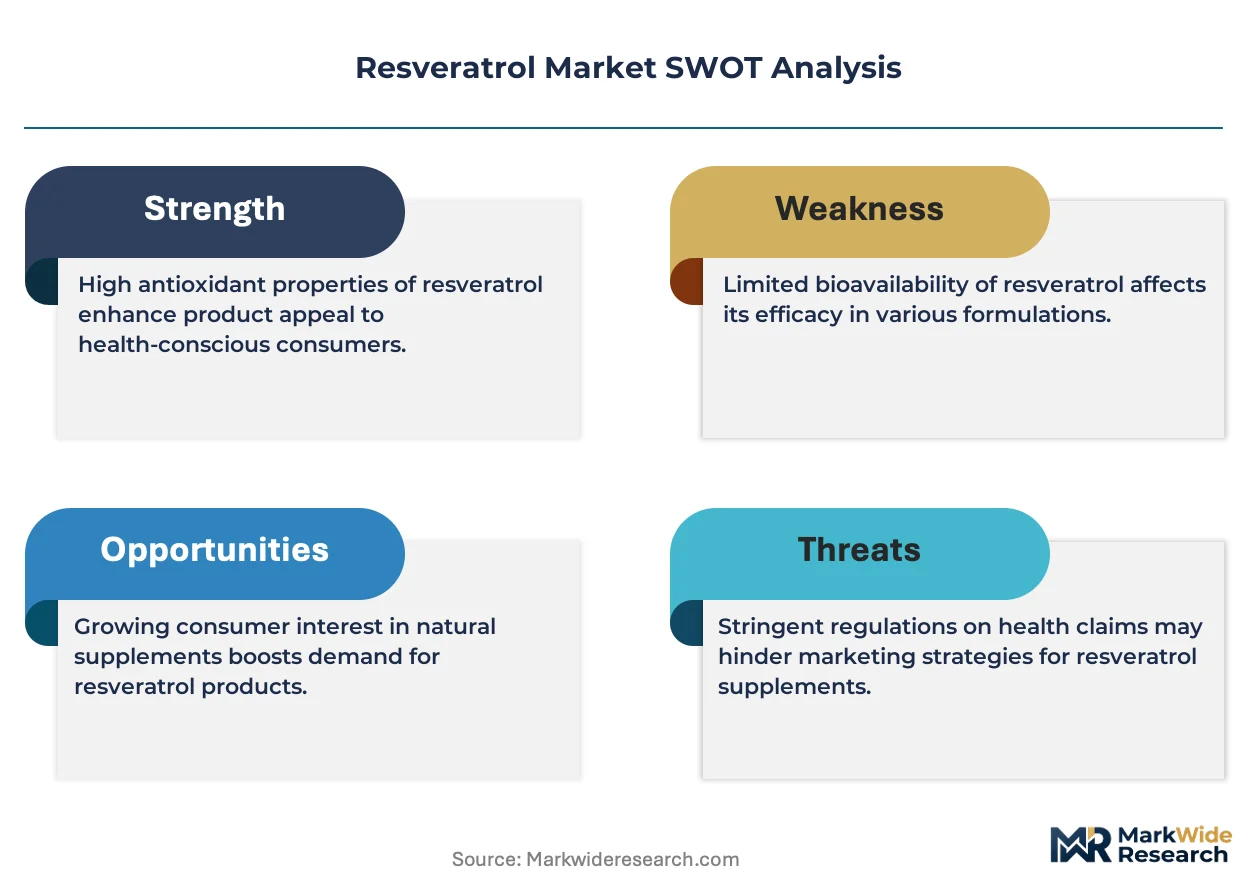
Resveratrol is a stilbenoid polyphenol, trans-3,5,4'-trihydroxystilbene, typically manufactured through solvent extraction from Japanese knotweed root or via recombinant microbial fermentation with titers reaching multiple grams per liter; it functions primarily as a bioactive ingredient in formulations targeting oxidative stress modulation and cellular senescence pathways. Powder formulations dominate active pharmaceutical ingredient procurement due to blending flexibility and dosage form adaptability, while capsule finished products capture margin pools in direct-to-consumer channels. Pharmaceutical Companies represent the most quality-stringent end user segment, with specifications tightening around residual solvent limits and isomeric purity.
FDA New Dietary Ingredient notifications and EFSA Novel Food opinions shape market access timelines for new resveratrol sourcing technologies, while ISO 17025 accreditation requirements filter contract manufacturers capable of supplying regulated industries. China's NMPA and SAMR jointly oversee health food registration, creating dual compliance obligations for domestic and export-oriented producers. Stakeholders must monitor regulatory divergence between fermentation-derived and plant-extracted resveratrol classification schemes across major jurisdictions.
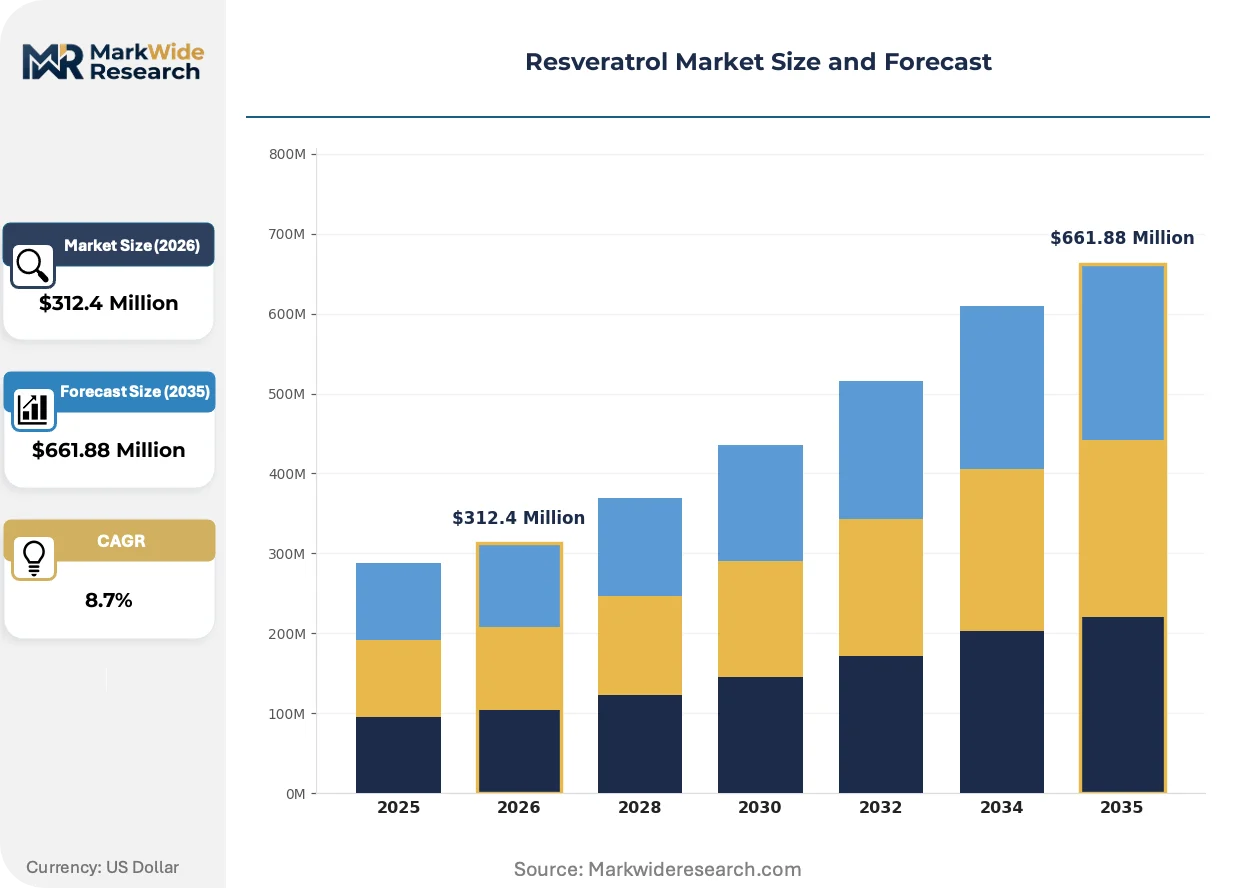
Market Dynamics
Precision fermentation is compressing production costs for resveratrol while simultaneously fragmenting supply-side control between biotech platforms and traditional botanical extractors.
Growth Catalysts
- EFSA Novel Food pathway:Fermentation-derived resveratrol gains expedited safety clearance for EU functional food applications, accelerating ingredient supplier qualification timelines.
- Cellular senescence research:Pharmaceutical pipelines targeting longevity pathways drive API-grade demand with specifications tightening around trans-resveratrol isomeric purity.
- China's dual carbon goals:Domestic fermentation capacity expansion displaces solvent-intensive root extraction, lowering carbon intensity for export-oriented nutraceutical supply.
Market Restraints
- Input cost volatility:Glucose and yeast extract feedstock prices fluctuate with agricultural commodity cycles, squeezing fermentation platform margins.
- Supply concentration risk:Huisong Pharmaceuticals and Evolva collectively control majority fermentation capacity, creating single-source vulnerability for downstream formulators.
- Regulatory friction:FDA New Dietary Ingredient notifications require 75-day pre-market submission windows, delaying commercialization for novel sourcing technologies.
Strategic Opportunities
- Underpenetrated India:FSSAI health food registration framework remains underutilized by foreign resveratrol suppliers, creating first-mover positioning in ayurvedic-functional hybrid formulations.
- Regulatory tailwind:China's SAMR health food registration reforms streamline dual-use ingredient claims for domestic and export markets simultaneously.
- Technology convergence:Synthetic biology platforms integrating CRISPR-edited yeast strains with continuous bioprocessing collapse unit economics below botanical extraction floors.
Industry Challenges
- Bioprocess engineering talent scarcity:Fermentation scale-up expertise concentrates in pharmaceutical hubs, constraining mid-tier nutraceutical manufacturer technology transfer.
- ISO 17025 accreditation timelines:Contract testing laboratory qualification stretches 12-18 months, bottlenecking supply chain validation for regulated end-uses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resveratrol Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Liquid, Cream End User: Pharmaceutical Companies, Nutraceuticals, Cosmetics, Research Institutions Application: Antioxidant, Anti-inflammatory, Anti-aging, Heart Health Distribution Channel: Online Retail, Health Stores, Pharmacies, Specialty Stores |
| Companies Covered | Huisong Pharmaceuticals, Shaanxi Fairir Biotech Co., Ltd., Evolva, Laurus Labs, dsm-firmenich, Verdure Sciences, Foodchem International Corporation, Maypro Industries, Sabinsa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resveratrol Market Emerging Trajectories
Biomanufacturing platforms are collapsing the traditional extraction-to-formulation value chain while regulatory jurisdictions diverge on classification frameworks for novel production methods.
Continuous bioprocessing systems are digitizing resveratrol manufacturing by replacing batch fermentation with perfusion bioreactors that maintain real-time metabolite monitoring. Pharmaceutical API buyers are adopting these platforms fastest, driven by lot-to-lot consistency requirements. The technology is digitizing quality assurance workflows, compressing release testing cycles from weeks to days.
REACH registration requirements for stilbenoid substances are tightening residual solvent disclosure thresholds for imported resveratrol. European formulators now demand comprehensive substance volume tracking from extraction or fermentation origin through finished product. Dietary supplement brands targeting EU distribution are restructuring supplier qualification protocols to preempt authorization delays.
Direct-to-consumer capsule brands are unbundling from traditional distributor networks, building captive e-commerce channels with subscription replenishment models. This channel shift compresses working capital cycles for finished goods manufacturers while concentrating marketing spend on performance claims verification. North American nutraceutical brands exhibit the most aggressive disintermediation, bypassing wholesale entirely for clinically-positioned resveratrol SKUs.
Resveratrol Market Segmentation
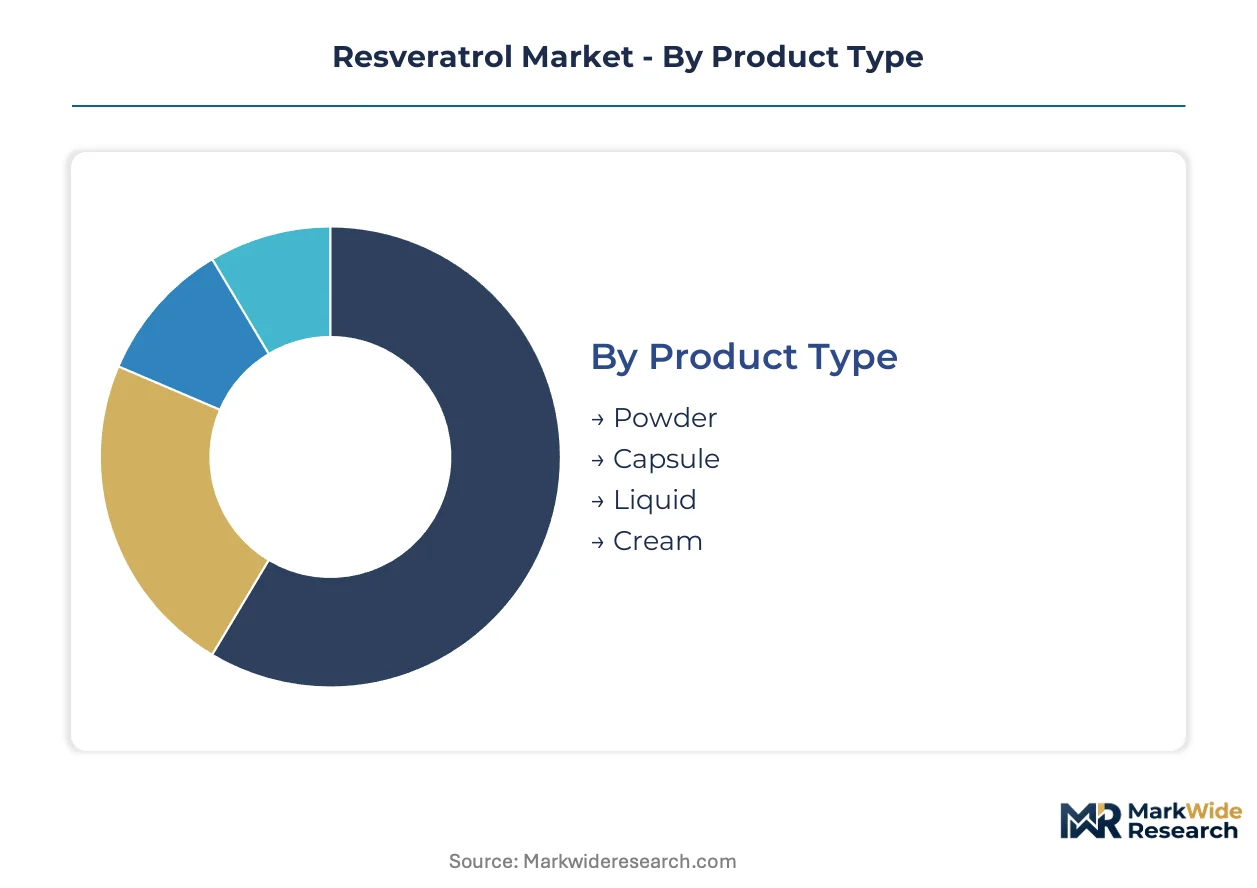
Resveratrol segmentation reflects divergent purity requirements and channel economics across pharmaceutical, nutraceutical, and cosmetic end-uses. Each category captures distinct specification thresholds, from API-grade isomeric purity to finished-product bioavailability claims.
Product Type:
Formulation flexibility spans bulk active ingredients through consumer-ready delivery systems, with powder and capsule formats commanding divergent margin structures.
- Powder:Bulk active pharmaceutical ingredient supplied in crystalline or amorphous form with trans-resveratrol purity specifications exceeding 98%. Pharmaceutical compounders in Switzerland and Germany concentrate procurement here, driven by lot-to-lot consistency requirements for clinical trial materials.
- Capsule:Finished dietary supplement delivery in gelatin or vegetarian shells with standardized 250-500mg unit doses. Direct-to-consumer brands in the United States bypass wholesale channels, capturing margin pools through subscription replenishment models.
- Liquid:Liposomal or micellar suspension formulations targeting enhanced bioavailability. Functional beverage manufacturers in Japan integrate these into ready-to-drink longevity positioning.
- Cream:Topical delivery systems with transdermal penetration enhancers. Korean cosmetics formulators lead incorporation into anti-aging skincare lines.
The dominant share belongs to Powder, while Capsule is closing the gap fastest.
End User:
Quality-stringency tiers separate regulated pharmaceutical procurement from discretionary consumer channels.
- Pharmaceutical Companies:API buyers enforce ISO 17025-accredited testing, residual solvent limits below 50ppm, and chiral purity verification. FDA New Dietary Ingredient notifications and EMA centralized procedures shape supplier qualification timelines for investigational drug applications.
- Nutraceuticals:Dietary supplement manufacturers blend resveratrol with coenzyme Q10, quercetin, or pterostilbene for synergistic antioxidant claims. China's SAMR health food registration creates dual compliance obligations for domestic and export-oriented producers.
- Cosmetics:Formulators prioritize photostability and oxidation resistance in emulsion systems. EU REACH registration requirements tighten substance volume tracking from fermentation or extraction origin through finished product.
- Research Institutions:Academic and contract research organizations procure gram-to-kilogram quantities for cellular senescence and sirtuin pathway studies. Specifications emphasize batch documentation for reproducibility.
Pharmaceutical Companies retain the most demanding specification tier, though Nutraceuticals is expanding volume most rapidly.
Application:
Mechanism-of-action positioning determines formulation complexity and clinical substantiation requirements.
- Antioxidant:Primary positioning for neutralizing reactive oxygen species through Nrf2 pathway activation. Sports nutrition brands in Australia emphasize post-exercise recovery applications.
- Anti-inflammatory:NF-κB modulation claims supported by in vitro and limited human trial data. Functional food developers in the Netherlands target metabolic health positioning.
- Anti-aging:Sirtuin-1 activation and cellular senescence modulation drive premium pricing. Longevity clinics in Switzerland prescribe pharmaceutical-grade formulations.
- Heart Health:Endothelial function and vascular compliance claims align with cardiovascular supplement demand. Health Canada Natural Health Product licensing shapes permissible indications.
Antioxidant commands baseline volume, while Anti-aging is gaining share fastest.
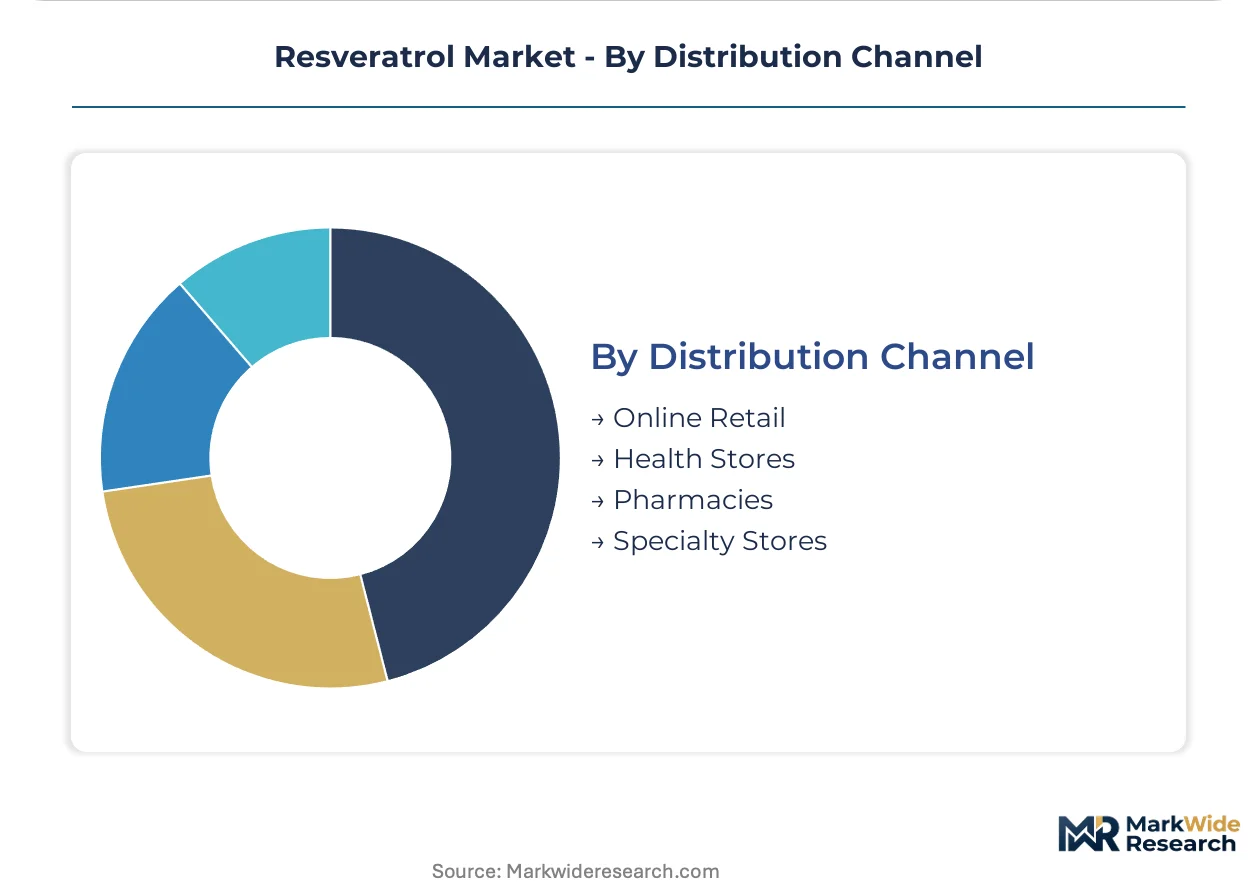
Distribution Channel:
Channel selection reflects consumer education requirements and regulatory oversight intensity.
- Online Retail:Direct-to-consumer platforms with subscription models and performance claims verification. North American brands exhibit the most aggressive disintermediation, bypassing wholesale entirely for clinically-positioned SKUs.
- Health Stores:Specialty retailers with trained staff for ingredient education and stacking recommendations. GNC and Vitamin Shoppe in the United States maintain dedicated longevity sections.
- Pharmacies:Behind-counter or pharmacist-recommended positioning with drug-interaction screening. German Apotheken enforce documentation requirements for high-dose resveratrol.
- Specialty Stores:Aesthetic medicine clinics, longevity centers, and functional medicine practices. Swiss and Austrian clinics prescribe compounded formulations with personalized dosing protocols.
Online Retail leads volume contribution, though Specialty Stores is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese fermentation facilities export resveratrol API to European pharmaceutical compounders and North American nutraceutical brands, creating a trade-flow corridor that concentrates supply-side control in Asia-Pacific while demand fragments across regulated end-markets.
United States
FDA New Dietary Ingredient notifications govern resveratrol commercialization timelines, with 75-day pre-market submission windows delaying novel sourcing technologies. Direct-to-consumer capsule brands in California and New York disintermediate wholesale channels through subscription replenishment models. Boston-area longevity clinics prescribe compounded pharmaceutical-grade formulations.
China
NMPA and SAMR jointly oversee health food registration, creating dual compliance obligations for domestic producers and export-oriented suppliers. Dual carbon goals accelerate fermentation capacity expansion in Zhejiang and Jiangsu provinces, displacing solvent-intensive Polygonum cuspidatum root extraction. Huisong Pharmaceuticals anchors integrated extraction and purification operations in the Yangtze River Delta.
Switzerland
Swissmedic enforces stringent API-grade specifications for investigational drug applications, with pharmaceutical compounders in Basel and Zurich demanding trans-resveratrol isomeric purity exceeding 98%. Longevity clinics in Geneva and Lausanne prescribe personalized dosing protocols. The country's precision fermentation startups compete on traceability and lot-to-lot consistency.
Germany
EMA centralized procedures and REACH registration requirements tighten residual solvent disclosure thresholds for imported resveratrol. Apotheken in Munich and Hamburg enforce documentation requirements for high-dose formulations. Functional food developers in the Netherlands adjacent market target metabolic health positioning with NF-κB modulation claims.
India
FSSAI health food registration framework remains underutilized by foreign resveratrol suppliers, creating first-mover positioning opportunities in ayurvedic-functional hybrid formulations. Laurus Labs anchors domestic API manufacturing capacity in Hyderabad and Visakhapatnam. Contract research organizations in Bangalore procure gram-to-kilogram quantities for cellular senescence studies.
Resveratrol Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. Fermentation platforms and botanical extractors fragment supply-side control, with biotechnology firms displacing traditional root-sourcing operations. Three archetypes dominate: precision fermentation specialists, integrated botanical extractors, and synthetic biology platforms. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure feedstock agreements and qualification timelines.
Within the precision fermentation tier, Evolva and dsm-firmenich exemplify yeast-based biomanufacturing approaches that compete on purity consistency. Among Asia-Pacific integrated extractors, Huisong Pharmaceuticals occupies a position representing traditional botanical sourcing combined with purification scale. These three anchors illustrate the competitive tension between novel bioproduction and established extraction methodologies.
| Leading Market Players |
|---|
| Huisong Pharmaceuticals |
| Shaanxi Fairir Biotech Co., Ltd. |
| Evolva |
| Laurus Labs |
| dsm-firmenich |
| Verdure Sciences |
| Foodchem International Corporation |
| Maypro Industries |
| Sabinsa Corporation |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Chinese fermentation capacity compresses pricing tier spreads while forcing downstream formulators toward dual-sourcing strategies. FDA New Dietary Ingredient notification timelines and EFSA Novel Food pathways determine which production technologies command premium qualification costs versus commodity botanical extraction.
Pricing Analysis
The fermentation-versus-extraction technology gap drives three-tier pricing stratification across pharmaceutical-grade, nutraceutical-grade, and economy botanical tiers. Pharmaceutical compounders in Switzerland and Germany pay premiums for trans-resveratrol purity exceeding 98% with ISO 17025-accredited batch documentation, while direct-to-consumer capsule brands compete on subscription pricing with standardized 250-500mg doses. Cost compression in the botanical extraction tier intensifies as Chinese domestic capacity scales under dual carbon goals. Nutraceutical manufacturers exhibit highest price sensitivity, switching between fermentation-derived and Polygonum cuspidatum-sourced material based on glucose feedstock volatility.
Supply Chain Analysis
Extended payment terms from European pharmaceutical compounders strain working capital for mid-tier fermentation platforms. Supply concentrates in China, with Zhejiang and Jiangsu provinces anchoring integrated extraction and purification operations alongside emerging precision fermentation capacity. The supply chain draws from glucose and yeast extract feedstocks vulnerable to agricultural commodity cycles. Single-source vulnerability persists as Huisong Pharmaceuticals and Evolva control majority fermentation output. Distribution runs through API procurement channels for pharmaceutical end-users and direct-to-consumer e-commerce for finished supplement brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pterostilbene and synthetic stilbenoid analogs threaten resveratrol's positioning in longevity formulations, forcing incumbents to defend through bioavailability differentiation and clinical substantiation investments.
For Market Incumbents: Build regulatory qualification moats by securing EFSA Novel Food opinions for fermentation-derived material ahead of botanical competitors. Pursue backward integration into yeast strain development to reduce licensing exposure. Capacity addition in India leverages underutilized FSSAI registration pathways while hedging Chinese supply concentration. For New Entrants and Emerging Players: Liposomal liquid formulations for functional beverage manufacturers in Japan represent the most penetrable entry point with limited incumbent specialization. CRISPR-edited yeast platforms targeting continuous bioprocessing collapse unit economics below extraction floors. Go-to-market through contract manufacturing partnerships with established ISO 17025-accredited facilities accelerates pharmaceutical qualification timelines. For Investors and Strategic Acquirers: FDA guidance clarification on fermentation-derived New Dietary Ingredient classification reshapes the acquisition landscape toward platforms with pre-submission dossiers. Synthetic biology specialists with validated production strains offer 5-10 year viability as extraction economics deteriorate. The signal to watch is SAMR health food registration reform implementation in China, which would unlock dual-use export positioning for domestic fermentation assets.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioprocessing Scale-Up | Pharmaceutical API buyers demand lot-to-lot consistency that perfusion bioreactors deliver through real-time metabolite monitoring. |
| EFSA Novel Food Dossier Submission | Fermentation-derived resveratrol gains expedited EU market access ahead of slower botanical safety evaluations. |
| Yeast Strain IP Development | CRISPR-edited platforms with elevated titers collapse production costs below Polygonum cuspidatum extraction economics. |
| India FSSAI Registration Entry | First-mover positioning in ayurvedic-functional hybrid formulations captures underpenetrated health food demand. |
| Direct-to-Consumer Channel Buildout | Subscription replenishment models bypass wholesale margin capture in North American nutraceutical distribution. |
Methodological Framework
Cross-validation between primary interviews with fermentation platform executives, pharmaceutical procurement managers, and regulatory affairs specialists anchors the qualitative findings against secondary validation from FDA New Dietary Ingredient notifications, EFSA Novel Food opinions, and SAMR health food registration databases. Bottom-up modeling of production capacity by technology type triangulates against top-down demand estimates from pharmaceutical API procurement and nutraceutical formulation trends.
Calibration against historical capacity expansion patterns and regulatory approval timelines shapes the analytical framework across the projection horizon. Segmentation dimensions include product type, end user quality tier, application mechanism, and distribution channel. CAGRs derive from supply-demand balance modeling incorporating fermentation titer improvements and extraction yield trajectories. Forecast inputs capture glucose feedstock price cycles and dual carbon policy implementation in Chinese manufacturing provinces.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, currency volatility in API trade corridors, or regulatory timeline extensions would shift the trajectory. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Global Citrus Aurantium Extract Market
Food Enhancers and Additives
Fortified Eggs Market
Food Enhancers and Additives
Emulsion Stabilizer for Beverages Market
Food Enhancers and Additives
Liquid Water Enhancers Market
Food Enhancers and Additives
Flavonoid Phytogenic Feed Additive Market
Food Enhancers and Additives
Flour Improvers Market
Food Enhancers and Additives
North America Food Flavor and Enhancer Market
Food Enhancers and Additives
Food Thickeners Market
Food Enhancers and Additives
Food Thickening Agents Market
Food Enhancers and Additives
Asia-Pacific Flavor Enhancer Market
Food Enhancers and Additives
Fortifying Agent Market
Food Enhancers and Additives
United Kingdom Interesterified Fats Market
Food Enhancers and Additives
Australia Water Enhancer Market
Food Enhancers and Additives
North America Vinegar Market
Food Enhancers and Additives
Australia & New Zealand Food Flavors and Enhancers Market
Food Enhancers and Additives
Europe Water Enhancer Market