
 Australia Water Enhancer Market | 2026-2036
Australia Water Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Water Enhancer Market Outlook
Asset-light contract manufacturing is narrowing the capital barrier for new entrants in Australia's beverage additive space. The Coca-Cola Company leverages its national bottling partnerships to secure shelf space across supermarket chains. Nestlé S.A. sustains R&D intensity through its applied nutrition labs in Sydney. PepsiCo, Inc. anchors its position via direct-to-consumer subscription models that bypass traditional wholesale margins.
Australia water enhancers comprise concentrated liquid or powdered formulations designed to flavor, fortify, or functionally modify plain water through the addition of electrolytes, vitamins, natural or artificial sweeteners, and flavor compounds; these products typically achieve dilution ratios of 1:10 to 1:20 and serve commercial purposes spanning hydration optimization, sugar reduction, and micronutrient supplementation. Liquid concentrate formulations dominate volume throughput in supermarket channels due to consumer familiarity and portion control convenience, while electrolyte additives capture the fastest trajectory among athletes and fitness participants seeking sodium, potassium, and magnesium fortification. Powdered mix sachets occupy a mature position in family-oriented bulk purchasing, whereas flavor drops concentrate margin pools in premium health store positioning where natural ingredient claims command price premiums.
FSANZ governs novel food ingredient approvals and labeling standards for water enhancers sold in Australia, while the Therapeutic Goods Administration intersects where products make therapeutic claims about hydration or nutrient delivery. The ACCC monitors advertising compliance around natural ingredient positioning and sugar reduction assertions. Stakeholders must monitor evolving FSANZ consultations on caffeine content thresholds and front-of-pack labeling reforms that could reshape permissible claims and reformulation requirements.
Market Dynamics
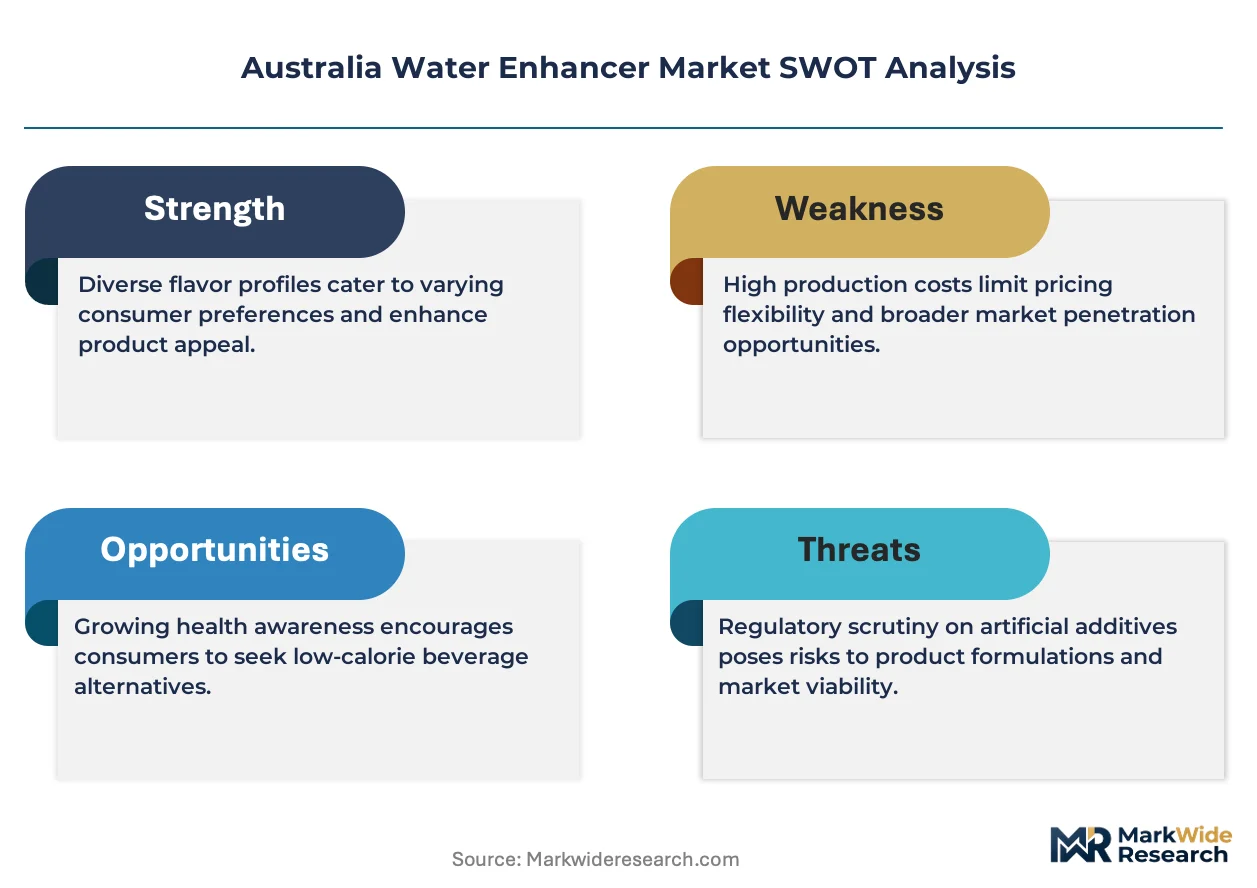
FSANZ consultations on caffeine thresholds and front-of-pack labeling reforms are compressing formulation cycles across Australia's water enhancer sector, forcing manufacturers to pre-emptively reformulate portfolios before final rulings crystallize.
Growth Catalysts
- Sugar reduction mandates:Australia's Health Star Rating system incentivizes beverage reformulation, pushing manufacturers toward zero-sugar water enhancers that retain palatability through natural sweetener blends.
- Melbourne and Sydney fitness clusters:Concentrated athlete populations in these metropolitan zones sustain demand for electrolyte-fortified formulations with sodium, potassium, and magnesium profiles.
- Asset-light contract manufacturing:Third-party production networks reduce capital requirements for new entrants, enabling rapid scale-up without dedicated facility investment.
Market Restraints
- Stevia and monk fruit price volatility:Natural sweetener supply chains face agricultural yield fluctuations that compress margins on premium-positioned clean-label products.
- Therapeutic Goods Administration intersection:Products crossing into therapeutic hydration claims trigger additional compliance layers, extending time-to-market by 12-18 months for functional positioning.
- Tap water quality perception:Municipal water taste variability in regional Queensland and Western Australia limits baseline appeal for flavor-dependent enhancer categories.
Strategic Opportunities
- Western Australia underpenetration:Perth and regional mining corridors show lower water enhancer penetration than eastern seaboard metros, presenting first-mover whitespace for electrolyte-focused distribution.
- Direct-to-consumer subscription channels:Recurring revenue models bypass supermarket slotting fees and capture higher lifetime value from health-conscious urban professionals.
- FSANZ novel ingredient pathway:Accelerated approval frameworks for fermented botanical extracts enable differentiation through proprietary functional ingredient stacks.
Industry Challenges
- Food technologist talent scarcity:Formulation expertise spanning flavor chemistry, stability science, and regulatory navigation concentrates among senior professionals in Sydney and Melbourne, constraining R&D expansion.
- ACCC natural claim substantiation:Advertising compliance requires extensive documentation chains for botanical sourcing and processing methods, elevating legal review costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Water Enhancer Market |
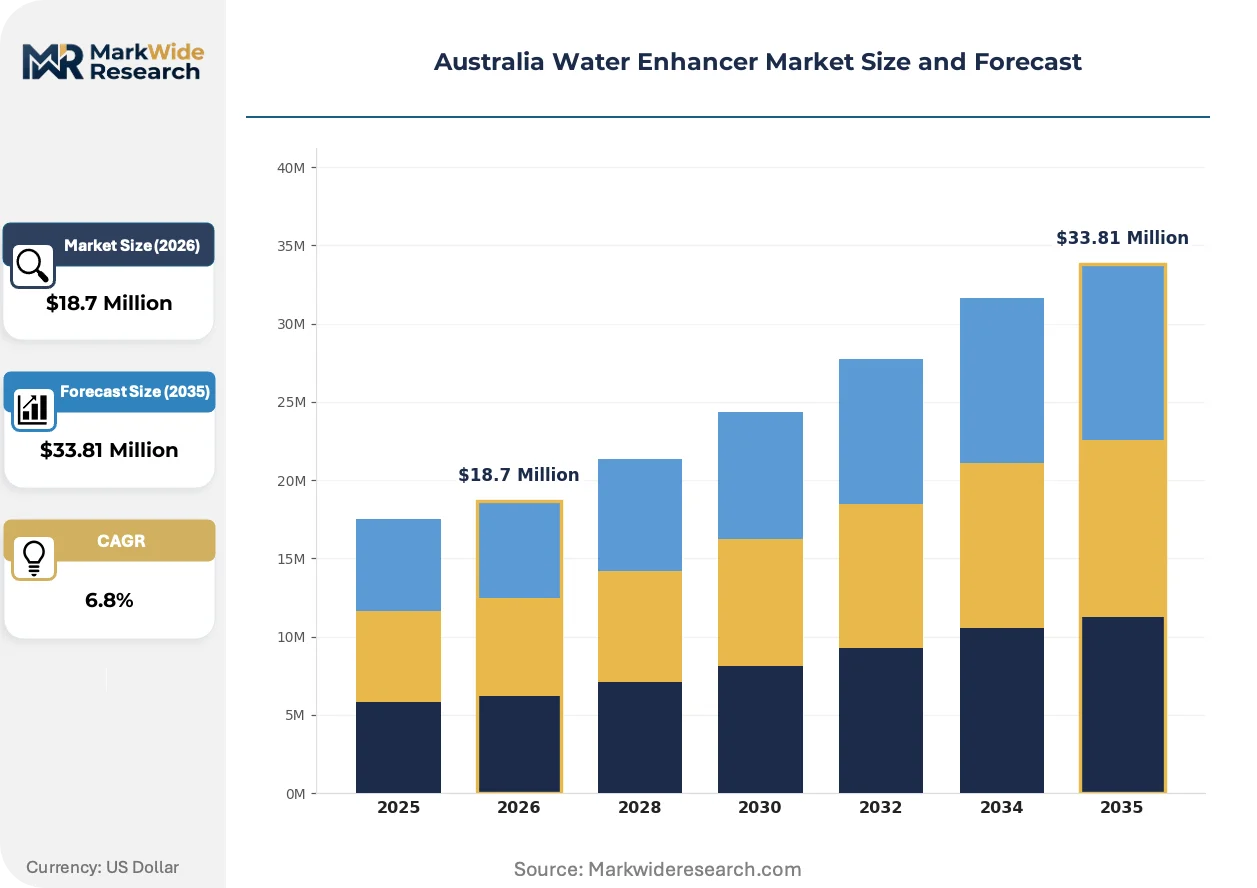
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $33.81 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Concentrate, Powdered Mix, Flavor Drops, Electrolyte Additives Distribution Channel: Supermarkets, Online Retailers, Health Stores, Convenience Stores Consumer Type: Health Conscious, Athletes, Families, Children Ingredient Type: Naturally Derived, Artificial Sweeteners, Vitamins, Caffeine, Others |
| Companies Covered | The Coca-Cola Company, Nestlé S.A., PepsiCo, Inc., Keurig Dr Pepper, Inc., The Kraft Heinz Company, Bolero Drink Australia, Wisdom Natural Brands, Dyla LLC, Arizona Beverages USA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Water Enhancer Market Strategic Shifts
Digital traceability platforms and precision fermentation are converging to reshape how Australian water enhancer manufacturers validate ingredient provenance and compress development timelines.
Blockchain-enabled supply chain verification is digitizing documentation workflows for natural ingredient sourcing. Mid-tier manufacturers in Victoria and New South Wales are adopting these systems to preempt ACCC scrutiny on clean-label claims. The technology is digitizing audit costs while compressing supplier qualification cycles from quarters to weeks.
FSANZ front-of-pack labeling reforms are mandating simplified sugar disclosure formats that favor single-serve portion positioning. Reformulation teams are rebalancing sweetness systems to maintain palatability under stricter visual scrutiny. Family-oriented bulk formats face structural disadvantage against pocket-sized liquid concentrates in supermarket planogram negotiations.
Fitness enthusiasts are consolidating purchasing around electrolyte-specific subscription bundles that displace supermarket impulse buying. Direct channels capture these consumers through personalized hydration profiling based on activity intensity and climate exposure. This behavioral pivot concentrates margin pools away from wholesale-dependent incumbents toward vertically integrated digital-native brands.
Australia Water Enhancer Market Segmentation
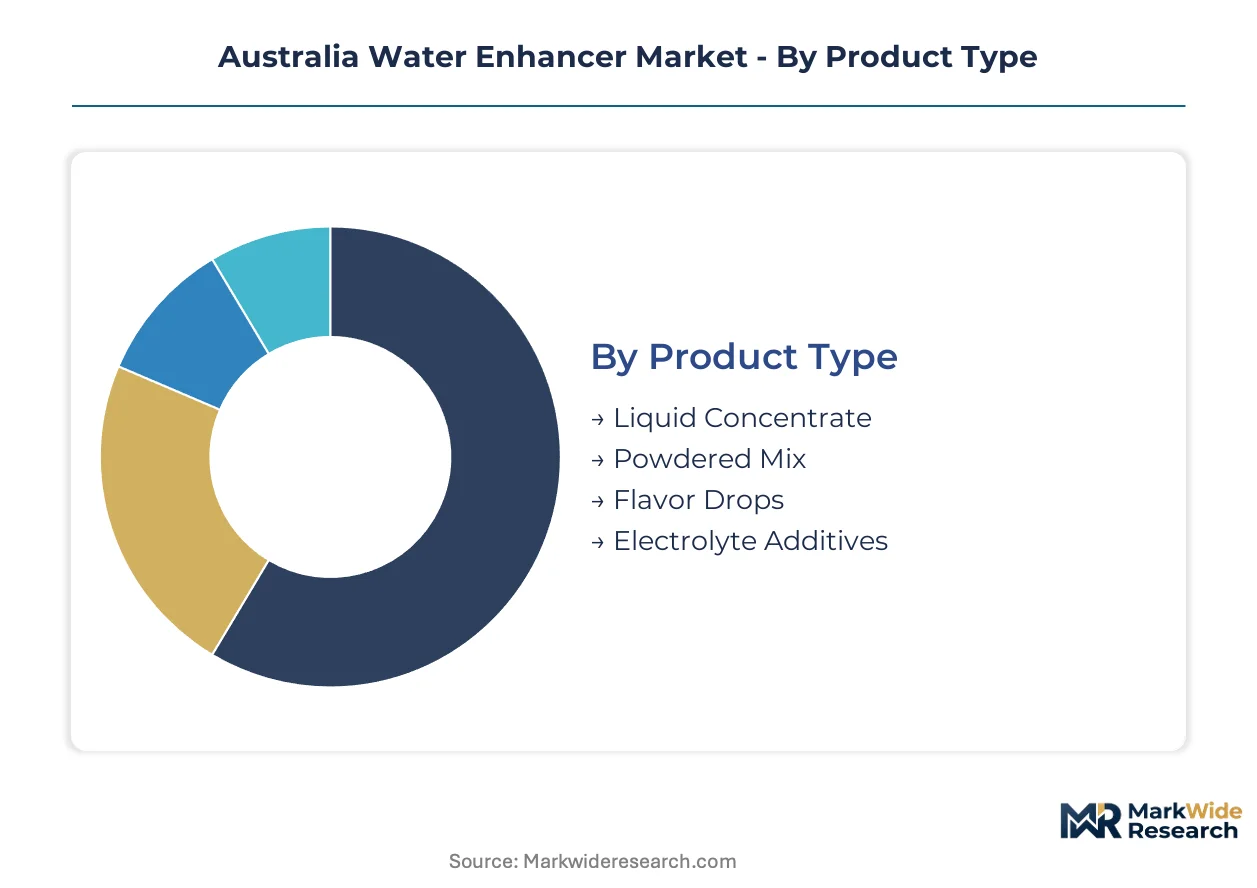
Segmentation reveals how water enhancer manufacturers must align formulation architecture with distinct consumption rituals across Australian households. Each dimension—product format, purchase venue, user profile, and ingredient sourcing—carries divergent margin structures and regulatory exposure.
Product Type:
After-sales service intensity varies sharply across formats, with liquid concentrates demanding minimal consumer support while electrolyte additives require educational onboarding about dosing protocols and athletic timing.
- Liquid Concentrate:Pre-diluted formulations packaged in squeezable bottles with calibrated dispensing caps achieve 1:10 to 1:20 dilution ratios. Melbourne and Sydney supermarket channels move the highest throughput volumes due to portion control familiarity among urban professionals seeking desk-side hydration solutions.
- Electrolyte Additives:Sodium-potassium-magnesium fortified concentrates target sweat-loss replacement for endurance athletes. Demand concentrates in Victoria's fitness clusters where triathlon and marathon training cultures sustain premium pricing for clinically-dosed mineral profiles.
- Powdered Mix:Bulk sachets serve family-oriented purchasing in Queensland regional centers where value-per-serve calculations dominate buying decisions.
- Flavor Drops:Ultra-concentrated natural extracts command shelf positioning in premium health stores where clean-label claims justify elevated price points against synthetic alternatives.
By volume, Liquid Concentrate leads. By growth pace, Electrolyte Additives is climbing the fastest.
Distribution Channel:
Cost tier separation across channels creates distinct margin pools, with health stores capturing premium positioning while convenience stores optimize for impulse velocity at lower per-unit economics.
- Supermarkets:Coles and Woolworths control planogram access through slotting fee structures that favor established brands with national distribution scale. Shelf positioning near bottled water categories drives trial conversion among habitual hydration purchasers.
- Online Retailers:Direct-to-consumer platforms bypass wholesale margin stacking while enabling subscription bundling for electrolyte-focused athletes. New South Wales urban professionals show highest digital adoption rates for recurring delivery models.
- Health Stores:Specialty retailers in Sydney and Brisbane filter assortments through natural ingredient certification requirements, elevating products with organic botanical sourcing.
- Convenience Stores:Petrol station and transit-adjacent locations in Perth and Adelaide capture on-the-go replenishment with single-serve liquid concentrate impulse purchases.
Supermarkets dominate absolute volume throughput. Online Retailers are gaining share fastest through subscription lock-in mechanics.
Consumer Type:
Application-driven usage patterns separate occasional flavor seekers from ritualistic hydration optimizers, with athletes showing highest lifetime value through repeat purchase frequency.
- Athletes:Structured training regimens in Melbourne's triathlon communities and Sydney's CrossFit boxes create predictable demand cycles for electrolyte-specific formulations with mineral content transparency.
- Health Conscious:Urban professionals across New South Wales and Victoria prioritize zero-sugar positioning and natural sweetener systems, accepting price premiums for clean-label credentials.
- Families:Multi-person households in Queensland and Western Australia favor bulk powdered formats with child-friendly flavor profiles and visible vitamin fortification claims.
- Children:School-lunch-compatible sachets with reduced caffeine and controlled sweetness levels target parental purchasing in suburban Melbourne and Sydney.
Health Conscious consumers provide the broadest addressable base. Athletes deliver the steepest expansion trajectory through sport-specific subscription bundling.
Ingredient Type:
Supply concentration for natural extracts versus synthetic alternatives creates divergent sourcing risk profiles, with stevia and monk fruit harvest variability compressing margins on premium-positioned lines.
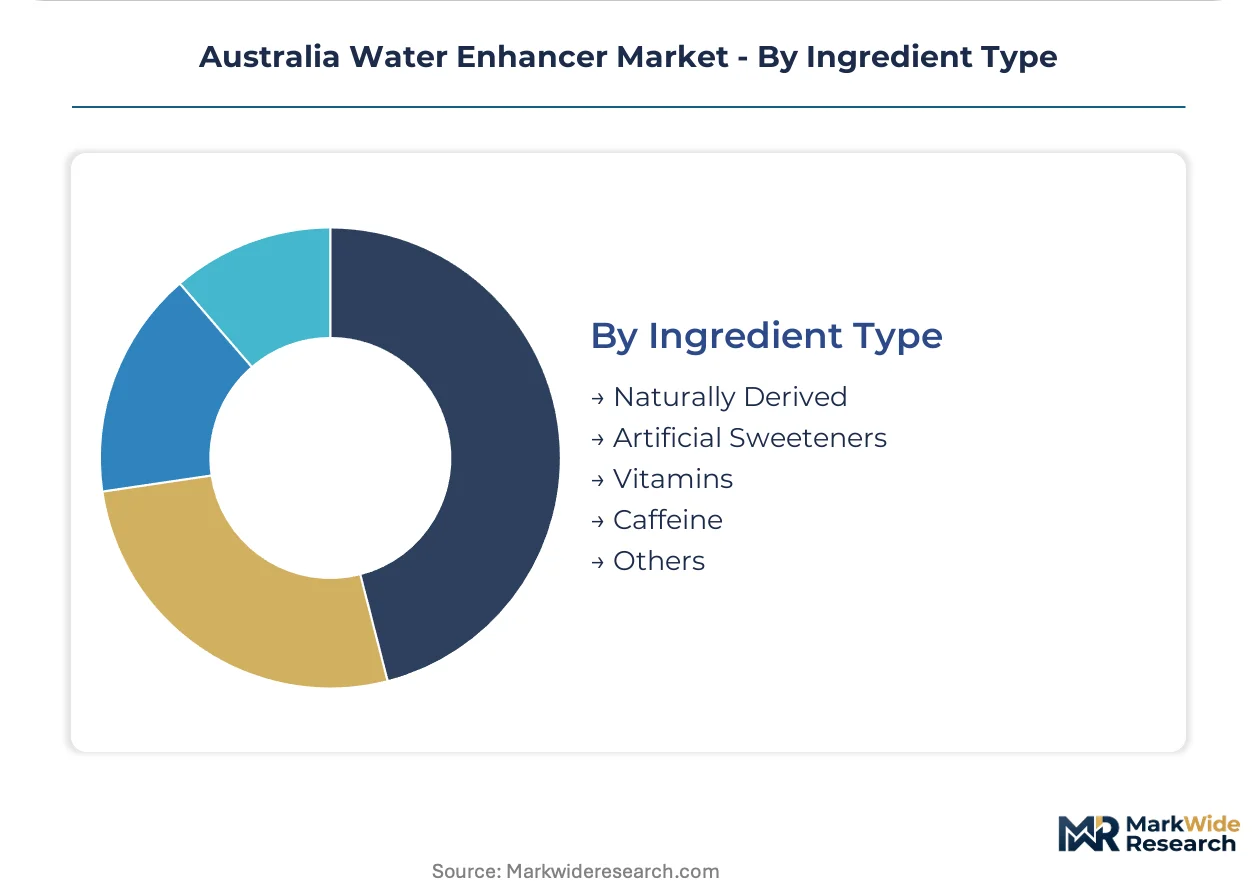
- Naturally Derived:Stevia, monk fruit, and botanical extracts command FSANZ scrutiny on novel food ingredient pathways. Victorian manufacturers invest in blockchain traceability to substantiate clean-label claims against ACCC advertising compliance requirements.
- Artificial Sweeteners:Sucralose and aspartame formulations retain cost competitiveness for price-sensitive segments in regional Western Australia and Queensland where natural positioning carries less purchase influence.
- Vitamins:B-complex and vitamin C fortification targets immune positioning among health-conscious professionals, requiring stability science expertise to prevent degradation in liquid matrices.
- Caffeine:Energy-positioned enhancers face FSANZ consultation uncertainty on threshold limits, forcing pre-emptive reformulation cycles ahead of finalized rulings.
- Others:Amino acid and adaptogen inclusions occupy emerging functional positioning with therapeutic claim boundaries monitored by TGA intersection.
Naturally Derived ingredients dominate premium shelf positioning. Caffeine-enhanced variants face regulatory compression that may accelerate displacement toward vitamin-focused alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious urban professionals concentrate demand in New South Wales and Victoria, while fitness clusters in Melbourne and Sydney drive electrolyte adoption. Regional disparities in tap water quality perception and distribution infrastructure create divergent growth trajectories across Australian states.
New South Wales
Sydney's corporate workforce sustains premium liquid concentrate demand through desk-side hydration rituals. FSANZ front-of-pack labeling reforms pressure manufacturers to reformulate sweetness systems ahead of implementation deadlines. The Eastern Suburbs fitness corridor anchors electrolyte subscription growth among triathlon training communities.
Victoria
Melbourne's CrossFit boxes and marathon clubs generate predictable demand cycles for clinically-dosed mineral formulations. The state's applied nutrition R&D infrastructure supports rapid prototype-to-shelf timelines for novel botanical extracts. Inner-city health stores in Fitzroy and South Yarra filter assortments through strict natural certification requirements.
Queensland
Regional family households favor bulk powdered formats with value-per-serve purchasing calculations. Municipal water taste variability in Townsville and Cairns limits baseline appeal for flavor-dependent categories. The Gold Coast's tourist economy creates seasonal impulse purchase velocity through convenience store channels.
Western Australia
Perth and Pilbara mining corridors show underpenetrated whitespace for electrolyte-focused distribution targeting fly-in-fly-out workers. Isolated geography elevates shipping costs that compress margins on low-weight-high-volume products. Direct-to-consumer subscription models bypass retail infrastructure gaps in regional centers.
South Australia
Adelaide's smaller metropolitan scale constrains national brand planogram access through Coles and Woolworths slotting fee structures. Local boutique manufacturers occupy premium health store positioning with small-batch botanical formulations. Barossa Valley tourism traffic creates limited seasonal demand spikes for portable single-serve formats.
Australia Water Enhancer Market Competitive Environment
Channel-controlling players compete with product-specialist players across Australia's water enhancer sector. The market structure shows moderate consolidation around beverage conglomerates with national bottling networks, while mid-tier digital-native brands fragment subscription channel share. Three archetypes dominate: multinational beverage conglomerates leveraging existing distribution infrastructure, specialist health brands commanding premium positioning through clean-label credentials, and direct-to-consumer disruptors bypassing wholesale margin stacking. Competitive moves concentrate on portfolio diversification into functional electrolyte positioning and geographic expansion into underpenetrated western states.
Among multinational beverage conglomerates, The Coca-Cola Company and PepsiCo, Inc. occupy positions defined by national bottling partnership scale and supermarket shelf space control. Nestlé S.A. represents the applied nutrition specialist archetype with Sydney-based R&D infrastructure supporting rapid formulation iteration. These three entities exemplify divergent strategic postures: Coca-Cola's channel dominance, PepsiCo's direct-to-consumer subscription experimentation, and Nestlé's technical formulation depth.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| Nestlé S.A. |
| PepsiCo, Inc. |
| Keurig Dr Pepper, Inc. |
| The Kraft Heinz Company |
| Bolero Drink Australia |
| Wisdom Natural Brands |
| Dyla LLC |
| Arizona Beverages USA |
| Others |
Value Chain & Pricing Dynamics
Sydney's contract manufacturing cluster anchors national production capacity, with third-party bottling networks in Parramatta and Blacktown converting raw concentrate inputs into finished liquid formulations that flow through Coles and Woolworths distribution centers. This geographic concentration of toll manufacturing capacity grants established brands leverage over slotting fee negotiations while compressing margins for new entrants lacking volume commitments.
Pricing Analysis
Certification level creates the primary spread between premium and economy tiers, with FSANZ novel food ingredient approvals and organic botanical sourcing credentials commanding shelf price premiums at health stores. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling, with electrolyte additives requiring educational support that elevates their positioning above flavor-only drops. Cost compression in the natural sweetener tier is intensifying because stevia and monk fruit harvest variability feeds through to clean-label product margins. Family-oriented bulk purchasers in Queensland show highest price sensitivity, while Melbourne's fitness clusters accept premiums for clinically-dosed mineral transparency.
Supply Chain Analysis
Export-control regimes on precision fermentation equipment limit domestic capacity expansion for novel botanical extract production, forcing Australian manufacturers to source proprietary ingredient stacks from established suppliers in the United States and Switzerland. Raw material dependencies center on stevia leaf extracts from China, natural flavor compounds from France, and electrolyte mineral salts from Germany. Single-source vulnerability concentrates in the natural sweetener tier where agricultural yield fluctuations disrupt formulation planning. Distribution runs through supermarket chain-controlled logistics networks that favor national scale over regional fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's water enhancer sector sits in early-cycle expansion, with Western Australia's underpenetrated mining corridors and direct-to-consumer subscription mechanics offering dual tailwinds for volume penetration beyond eastern seaboard saturation.
For Market Incumbents: Entrench supermarket planogram control through exclusive flavor variant launches that preempt competitor shelf resets, while deepening captive supply of stevia and monk fruit extracts via backward integration into Southeast Asian agricultural partnerships. The TGA's therapeutic claim boundary enforcement represents the primary regulatory threat requiring pre-emptive reformulation reserves.
For New Entrants and Emerging Players: Perth and Pilbara fly-in-fly-out workers represent the most penetrable entry point, with electrolyte-focused subscription bundles bypassing retail infrastructure gaps and capturing recurring revenue from isolated workforces. Direct-to-consumer hydration profiling based on activity intensity offers a defensible go-to-market angle against wholesale-dependent incumbents.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors digital-native brands with vertically integrated subscription infrastructure over asset-heavy manufacturing plays. Long-term viability hinges on proprietary formulation pipelines and regulatory navigation capabilities. The signal to watch is FSANZ finalization of caffeine threshold rulings, which will force portfolio-wide reformulation and consolidate advantage toward players with pre-positioned alternative ingredient stacks.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Recurring revenue models bypass Coles and Woolworths slotting fees while capturing higher lifetime value from Melbourne fitness clusters. |
| Electrolyte Portfolio Extension | Sodium-potassium-magnesium fortification targets Victoria's triathlon and CrossFit communities with clinically-dosed mineral transparency claims. |
| Western Australia Distribution Expansion | Perth and Pilbara mining corridors present first-mover whitespace for electrolyte-focused brands with fly-in-fly-out worker targeting. |
| Natural Ingredient Certification Investment | Organic botanical sourcing credentials justify shelf price premiums at Sydney and Brisbane health stores filtering through strict certification requirements. |
| Blockchain Traceability Implementation | Digitized supply chain verification preempts ACCC scrutiny on clean-label claims while compressing supplier qualification cycles for Victorian manufacturers. |
Study Parameters
Cross-validation between primary interviews with beverage formulation chemists, supermarket category buyers, FSANZ regulatory affairs specialists, and fitness community purchasing coordinators anchors the qualitative findings against secondary validation from FSANZ consultation documents, ACCC advertising compliance rulings, Therapeutic Goods Administration guidance notes, and Coles and Woolworths annual supplier reports. Bottom-up demand modeling across product format, distribution channel, and consumer type segments triangulates against top-down market sizing from trade flow analysis and customs records.
Calibration against historical volume trajectories and elasticity assumptions shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product format architecture, distribution channel economics, consumer ritual patterns, and ingredient sourcing certification tiers. CAGRs were derived from trend extrapolation adjusted for regulatory intervention timelines and adoption curve inflection points. Forecast inputs incorporate FSANZ reformulation cycle assumptions and subscription channel migration rates from traditional wholesale.
Stress conditions across stevia and monk fruit price volatility, TGA therapeutic claim enforcement intensity, and Western Australia distribution infrastructure development were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory timeline crystallization and fitness community adoption velocity. Material shifts in FSANZ caffeine threshold finalization or supermarket chain consolidation dynamics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Isoprenol Market
Food Enhancers and Additives
Crumb Softener Market
Food Enhancers and Additives
Africa Food Flavor and Enhancer Market
Food Enhancers and Additives
Isomalt Market
Food Enhancers and Additives
Kaempferol Market
Food Enhancers and Additives
Fortified Salts Market
Food Enhancers and Additives
Asia-Pacific Feed Palatability Enhancers Market
Food Enhancers and Additives
North America Water Enhancer Market
Food Enhancers and Additives
Global Citrus Aurantium Extract Market
Food Enhancers and Additives
Japan Water Enhancer Market
Food Enhancers and Additives
Australia Food Flavor and Enhancer Market
Food Enhancers and Additives
Germany Water Enhancer Market
Food Enhancers and Additives
United Kingdom Interesterified Fats Market
Food Enhancers and Additives
North America Food Thickeners Market
Food Enhancers and Additives
Liquid Water Enhancers Market
Food Enhancers and Additives
Spain Food Flavor and Enhancer Market