
 Emulsifier Alternatives Market | 2026-2036
Emulsifier Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
Emulsifier Alternatives Market Analytics
Asset-light contract manufacturing and toll-processing arrangements are tilting competitive dynamics toward firms that can scale without owning fermentation or extraction infrastructure. Cargill leverages its integrated oilseed processing network to secure cost-advantaged lecithin feedstocks across multiple geographies. Kerry Group anchors its position through specialized emulsion science laboratories that co-develop clean-label solutions with multinational food brands. Palsgaard differentiates by controlling the full value chain from palm oil sourcing to fractionated monoglyceride output.
Emulsifier alternatives encompass surface-active compounds—monoglycerides, diglycerides, lecithin fractions, and polysorbate variants—that stabilize oil-water interfaces through hydrophilic-lipophilic balance modulation, typically requiring HLB values between 3 and 16 for food-grade applications. Plant-based sources dominate volume due to soybean and sunflower lecithin availability, though microbial fermentation is gaining traction for tailored hydrocolloid functionality. Within applications, food and beverages represents the mature revenue base where margin pools have compressed, while nutritional supplements offers faster expansion as protein-fortified beverages demand superior mouthfeel without synthetic additives.
The European Food Safety Authority enforces strict purity criteria for food emulsifiers under EU Regulation 1333/2008, while the FDA maintains GRAS notification requirements that delay novel alternative introductions. China's National Health Commission and SAMR are converging toward GB standards alignment with Codex Alimentarius, easing export pathways for compliant suppliers. Stakeholders must monitor regulatory divergence between jurisdictions where microbial-sourced alternatives face divergent novel food approval timelines.
Market Dynamics
Clean-label mandates from European retailers are compressing reformulation timelines, forcing food processors to replace synthetic emulsifiers ahead of regulatory deadlines. This pressure cascades through ingredient supply chains, privileging suppliers with verified sustainable sourcing and rapid certification turnaround.
Growth Catalysts
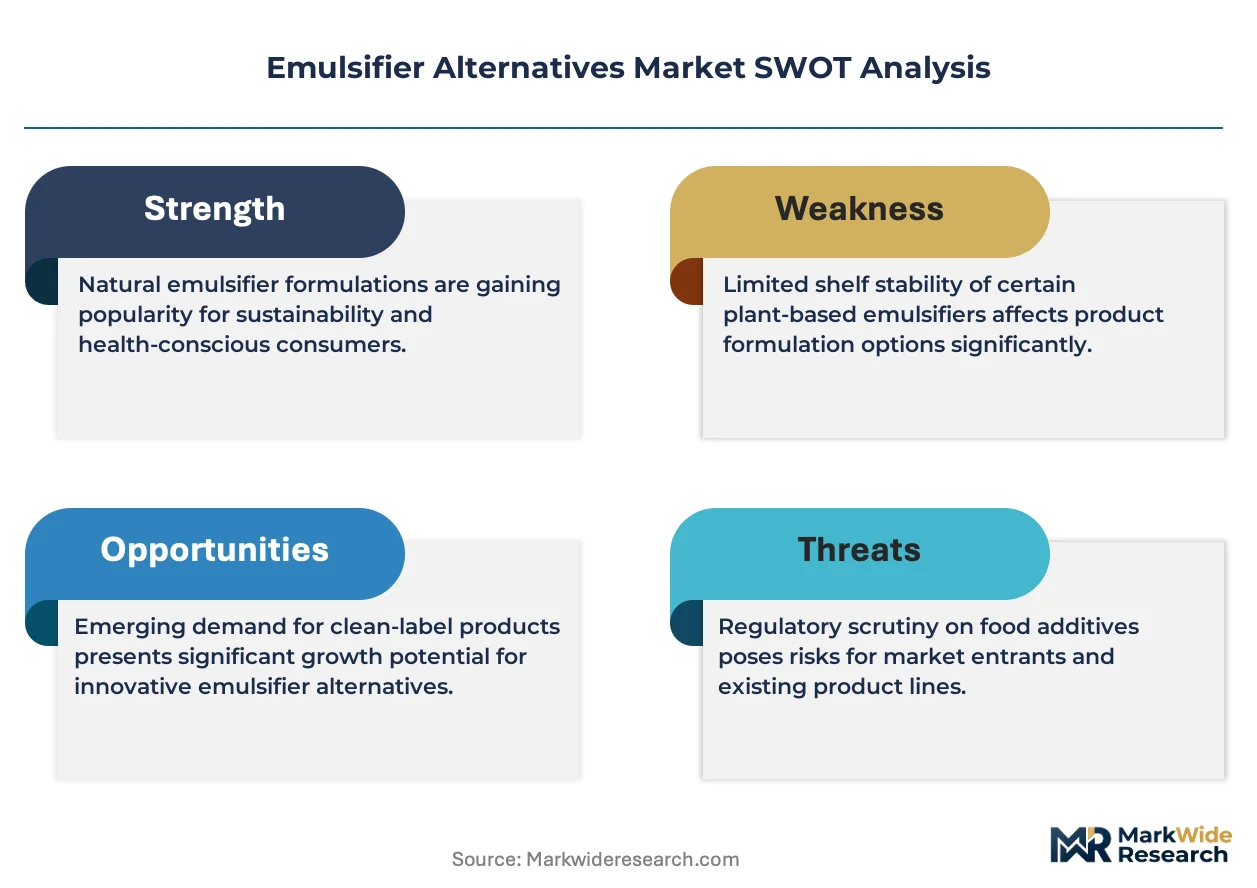
- EU F-Gas Regulation:Chemical disclosure requirements under REACH are accelerating substitution of petroleum-derived emulsifiers in German dairy and bakery operations.
- Plant-based protein beverages:Mouthfeel stabilization demands in nutritional supplements are pulling microbial-sourced hydrocolloids into formulations previously dependent on polysorbates.
- Sunflower lecithin:Non-GMO supply chains from Eastern European oilseed processors are displacing soybean alternatives in premium confectionery segments.
Market Restraints
- Feedstock concentration:Palm oil dependency for fractionated monoglycerides exposes processors to Malaysian and Indonesian supply volatility.
- Functional equivalence gaps:Microbial emulsifiers lack the HLB range coverage of synthetic alternatives, limiting deployment in high-fat bakery applications.
- Novel food approval timelines:EFSA's extended safety evaluation protocols delay fermentation-derived ingredient launches by 18-24 months versus GRAS-notified equivalents.
Strategic Opportunities
- India FSSAI alignment:Convergence of Indian food additive standards with Codex Alimentarius opens export pathways for Codex-compliant European suppliers.
- Cell-culture media:Precision fermentation byproduct streams offer pharmaceutical-grade lecithin fractions for parenteral nutrition applications.
- Direct-to-processor digital platforms:B2B ingredient marketplaces are collapsing distributor layers in mid-tier bakery and meat processing segments.
Industry Challenges
- Emulsion science specialization:Shortage of formulation chemists capable of bridging clean-label constraints with industrial-scale stability requirements constrains co-development throughput.
- Multi-jurisdiction certification:Divergent novel food pathways between EFSA, FDA, and China's SAMR force parallel dossier preparation, inflating regulatory affairs overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emulsifier Alternatives Market |
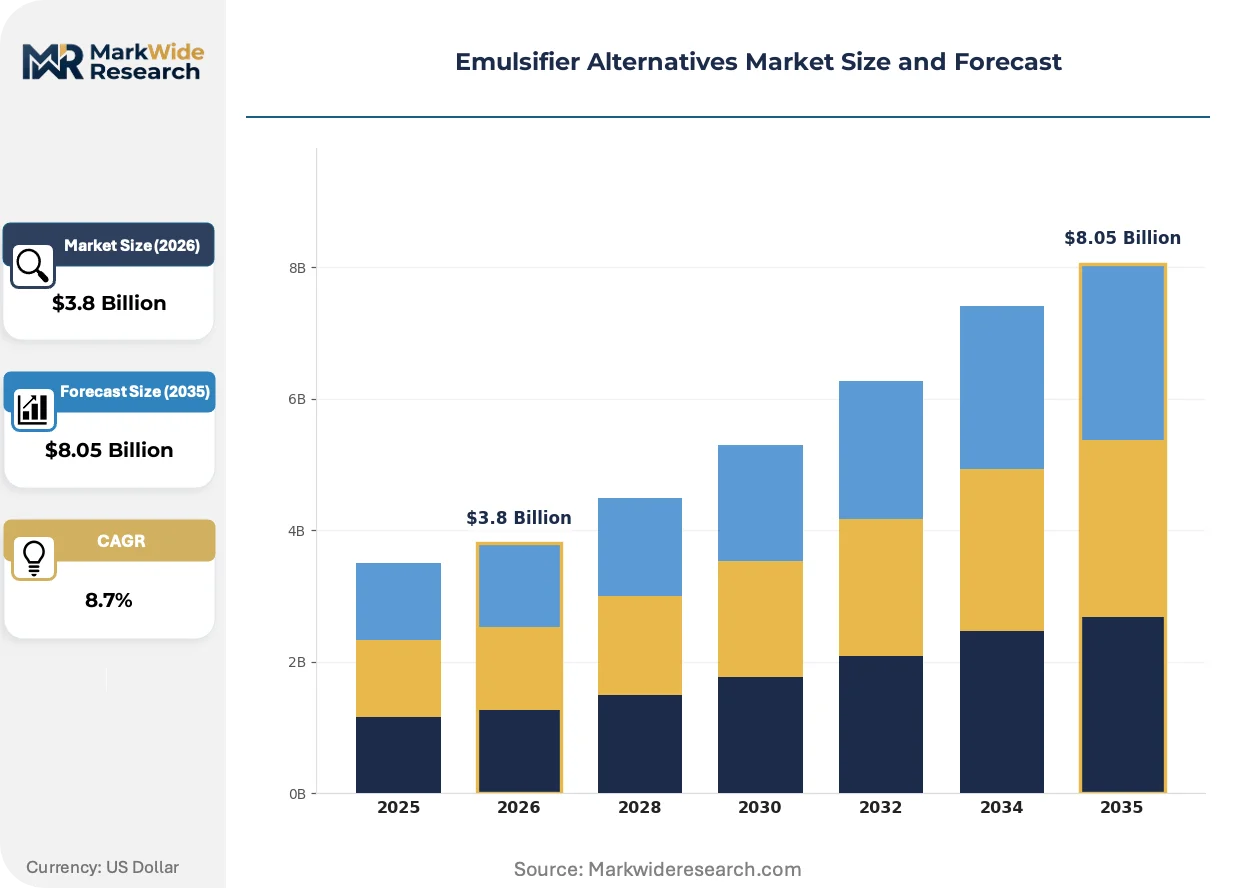
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoglycerides, Diglycerides, Lecithin, Polysorbates Source: Plant-Based, Animal-Based, Synthetic, Microbial Application: Food & Beverages, Cosmetics, Pharmaceuticals, Nutritional Supplements Form: Liquid, Powder, Granules, Paste |
| Companies Covered | Ingredion Incorporated, CP Kelco, Kerry Group, Corbion, Nexira, Cargill, DuPont Nutrition & Biosciences, Palsgaard, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emulsifier Alternatives Market Evolving Landscape
Bioprocess engineering advances are collapsing the cost gap between fermentation-derived and plant-extracted emulsifiers. Three interconnected developments are restructuring competitive advantage around scale flexibility and application-specific functionality.
Precision fermentation of tailored glycolipids is rendering obsolete the one-size-fits-all HLB matching that constrained synthetic emulsifier substitution. Multinational beverage brands in Western Europe are piloting batch-customized biosurfactants for protein-fortified oat milk, compressing formulation iteration cycles from months to weeks.
REACH authorization timelines for existing synthetic emulsifiers are forcing anticipatory reformulation across EU food manufacturing. The European Food Safety Authority's 2023 re-evaluation of polysorbate safety profiles has triggered active sourcing of lecithin and monoglyceride alternatives in German processed meat and French patisserie segments.
Retailer sustainability scorecards are rewiring procurement criteria toward verified deforestation-free palm and certified organic oilseed supply chains. Discounters in the Netherlands and Belgium are delisting suppliers unable to demonstrate mass-balance traceability, concentrating volume with integrated processors controlling origination through fractionation.
Emulsifier Alternatives Market Segmentation
Emulsifier alternatives demand diverges sharply across end-use specifications, with food-grade purity standards, pharmaceutical-grade lecithin fractions, and cosmetic HLB requirements creating non-overlapping procurement criteria. Manufacturers must align production assets to distinct certification pathways rather than pursuing universal formulations.
Product Type:
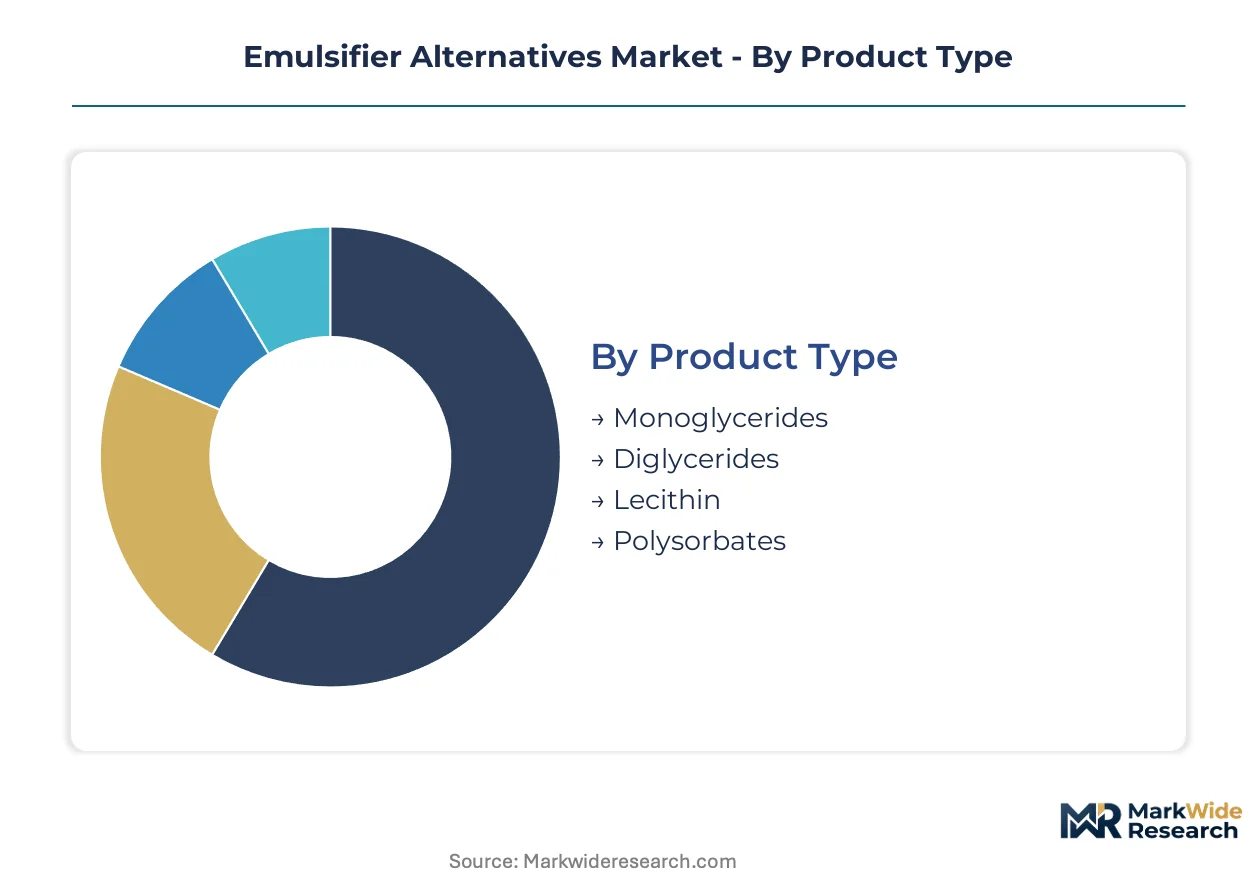
Surface-active compounds span a functional spectrum from lipophilic monoglycerides to hydrophilic polysorbates, each occupying specific HLB ranges and stability windows.
- Monoglycerides:Fractionated palm oil derivatives deliver HLB values of 3-5, anchoring bakery and confectionery applications where aeration stability proves critical. German dairy processors source these for whipped topping reformulations under retailer clean-label mandates.
- Lecithin:Phospholipid mixtures from soybean and sunflower oil exhibit HLB 7-9, enabling dual oil-water affinity in chocolate and margarine. Eastern European oilseed processors are expanding non-GMO sunflower fractionation capacity to serve premium confectionery segments.
- Diglycerides:Partial glycerides function as co-emulsifiers and anti-spattering agents in frying applications.
- Polysorbates:Sorbitan ester ethoxylates provide HLB 15-16 for beverage emulsions, though EFSA safety re-evaluations are accelerating substitution timelines.
The dominant share belongs to lecithin, while monoglycerides are closing the gap fastest through fractionation technology advances.
Source:
Feedstock origin determines regulatory pathway complexity, certification burden, and deforestation risk exposure across supply chains.
- Plant-Based:Soybean and sunflower lecithin dominate volume through established oilseed crushing infrastructure. Mass-balance traceability requirements from Dutch and Belgian retailers are concentrating procurement with integrated processors controlling origination.
- Microbial:Precision fermentation of tailored glycolipids enables batch-customized HLB matching for protein-fortified beverages. EFSA novel food approval timelines extend commercialization by 18-24 months versus GRAS-notified equivalents.
- Synthetic:Petroleum-derived emulsifiers face REACH authorization pressure and F-Gas disclosure requirements.
- Animal-Based:Egg yolk phospholipids serve niche pharmaceutical and infant nutrition applications with stringent purity specifications.
Plant-based sources command the installed base, though microbial alternatives are expanding most quickly through bioprocess cost reductions.
Application:
End-use specifications fragment demand across food safety, cosmetic tolerability, and pharmaceutical purity standards with minimal formulation overlap.
- Food & Beverages:Clean-label reformulations in processed meat, bakery, and dairy represent the mature revenue base. EU retailer sustainability scorecards are compressing synthetic emulsifier replacement timelines ahead of regulatory deadlines.
- Nutritional Supplements:Protein-fortified beverages demand mouthfeel stabilization without synthetic additives, pulling microbial hydrocolloids into formulations. Multinational brands in Western Europe pilot batch-customized biosurfactants for oat milk applications.
- Cosmetics:Skin tolerability and natural positioning drive polysorbate substitution in emulsion skincare.
- Pharmaceuticals:Parenteral nutrition and liposomal drug delivery require pharmaceutical-grade lecithin fractions with documented impurity profiles.
Food and beverages retains the volume concentration, while nutritional supplements is gaining share fastest through protein beverage proliferation.
Form:
Physical presentation dictates handling equipment, dispersion kinetics, and storage stability across manufacturing environments.
- Liquid:Fluid lecithin and monoglyceride preparations enable direct dosing into continuous processing lines. Bakery and margarine operations favor liquid forms for automated metering.
- Powder:Spray-dried and plated variants improve flowability and dust-free handling in dry mix applications.
- Granules:Agglomerated forms balance dispersibility with reduced caking tendency in intermediate moisture foods.
- Paste:High-viscosity preparations suit small-batch artisanal production and manual incorporation.
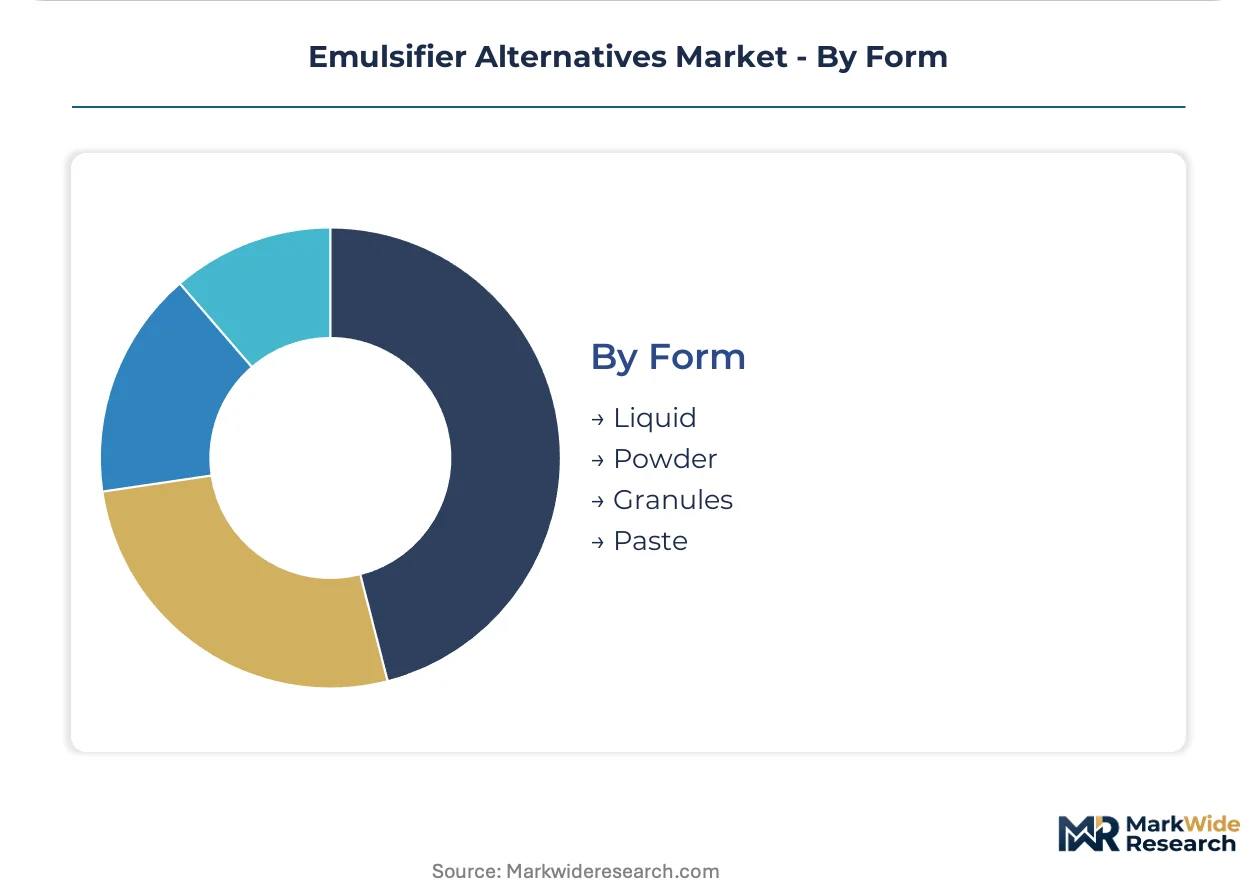
Liquid forms hold the processing preference, while powder is climbing the fastest through dry beverage premix expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics are restructuring supply chain configurations as European processors source sunflower lecithin from Eastern European oilseed crushers while Asian fermentation facilities ship microbial hydrocolloids to protein beverage manufacturers in Western markets.
Germany
Clean-label mandates from Aldi and Lidl are compressing reformulation timelines for dairy and bakery processors. The F-Gas Regulation and REACH framework enforce chemical disclosure requirements that accelerate petroleum-derived emulsifier substitution. Industrial clusters in North Rhine-Westphalia and Bavaria host active sourcing of lecithin and monoglyceride alternatives to meet retailer sustainability protocols.
United States
Protein-fortified beverage brands drive mouthfeel stabilization demand without synthetic additives. The FDA maintains GRAS notification requirements that delay novel alternative introductions versus European timelines. Chicago and Minneapolis-St. Paul processing corridors concentrate reformulation activity for whipped toppings and margarine applications.
China
Domestic oilseed crushing capacity expansion supports soybean lecithin fractionation for domestic food manufacturing. The National Health Commission and SAMR are converging toward GB standards alignment with Codex Alimentarius, easing export pathways for compliant suppliers. Yangtze River Delta beverage processors pilot microbial hydrocolloids in oat milk formulations.
India
Mid-tier bakery and confectionery manufacturers seek cost-advantaged emulsifier alternatives as FSSAI standards align with Codex Alimentarius. The Food Safety and Standards Authority of India opens export pathways for European suppliers meeting converged additive specifications. Maharashtra and Gujarat processing hubs concentrate procurement through direct-to-processor digital platforms.
Netherlands
Retailer sustainability scorecards from Albert Heijn and Jumbo delist suppliers lacking mass-balance traceability for palm-derived monoglycerides. The EU Green Deal and deforestation-free supply chain regulations concentrate volume with integrated processors controlling origination through fractionation. Rotterdam and Amsterdam corridors anchor European lecithin trading and toll-processing arrangements.
Emulsifier Alternatives Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream where fermentation science and oilseed fractionation determine functional performance. The vendor base organizes around three archetypes: integrated agribusinesses with captive oilseed supply, specialized emulsion science laboratories, and precision fermentation startups with batch-customization capabilities. Dominant competitive moves include backward integration into palm oil origination and strategic partnerships between ingredient suppliers and multinational beverage brands for co-development agreements.
Among integrated agribusinesses with global oilseed networks, Cargill and Archer Daniels Midland occupy positions anchored by crushing infrastructure that secures cost-advantaged lecithin feedstocks. Kerry Group exemplifies the specialized emulsion science archetype through laboratory facilities that co-develop clean-label solutions. Palsgaard represents the vertically integrated processor model with control from palm sourcing through fractionated monoglyceride output.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| CP Kelco |
| Kerry Group |
| Corbion |
| Nexira |
| Cargill |
| DuPont Nutrition & Biosciences |
| Palsgaard |
| Archer Daniels Midland Company |
| Others |
Value Network & Pricing Analysis
Rotterdam's lecithin toll-processing corridors concentrate European fractionation capacity, translating origination control into pricing power over downstream bakery and confectionery buyers. REACH disclosure mandates and F-Gas Regulation compliance costs cascade through contract structures, privileging integrated processors with verified mass-balance traceability.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with three-tier pricing stratification across pharmaceutical-grade, food-grade, and feed-grade lecithin fractions. Price differentiation hinges on certification tier (EFSA novel food approval versus GRAS notification status) and volume scale, with multinational beverage brands commanding 15-20 point spreads over mid-tier meat processors. Cost compression in standard-grade monoglycerides is intensifying because Malaysian palm oil supply volatility feeds directly into fractionation input costs. Mid-tier bakery manufacturers in India and Southeast Asia exhibit highest price sensitivity, while pharmaceutical parenteral nutrition suppliers accept premium positioning for documented impurity profiles.
Supply Chain Analysis
Upstream soybean and sunflower oilseed crushing draws from Argentina, Brazil, and Eastern European Black Sea corridors, with phospholipid extraction tethered to agribusiness origination networks. Fractionated monoglycerides rest on Malaysian and Indonesian palm oil plantations, while precision fermentation feedstocks center on glucose and yeast extract inputs from North American and European biorefineries. Single-source vulnerability concentrates in palm-derived surfactants, where EU deforestation-free regulations threaten supply continuity for non-compliant processors. Distribution runs through integrated agribusiness trading desks and B2B ingredient marketplaces, with toll-processing arrangements collapsing asset-heavy requirements for mid-tier entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label regulatory entrenchment builds defensive moats around suppliers with pre-certified novel food dossiers, as EFSA approval timelines create 18-24 month switching costs for downstream formulators.
For Market Incumbents: Pre-empt microbial fermentation entrants by locking exclusive co-development agreements with protein beverage brands in Western Europe, where batch-customized biosurfactant demand is accelerating. Secure backward integration into Eastern European non-GMO sunflower origination before Black Sea supply concentrates with rival crushers. Certification investment in parallel EFSA-FDA-SAMR dossiers preserves margin position against regulatory divergence risks. For New Entrants and Emerging Players: Establish a beachhead in Indian mid-tier bakery and confectionery segments, where FSSAI-Codex alignment opens import pathways for Codex-compliant European suppliers lacking local crushing infrastructure. Precision fermentation startups should target pharmaceutical-grade lecithin fractions for parenteral nutrition, where documented impurity profiles command pricing power inaccessible to commodity lecithin traders. Direct-to-processor digital platforms offer the most penetrable go-to-market angle, collapsing distributor layers in Maharashtra and Gujarat processing hubs. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because jurisdictional approval timeline divergence creates acquisition premiums for multi-certified asset bases. Target precision fermentation specialists with existing EFSA novel food approvals and scalable bioprocess platforms, avoiding pre-revenue startups facing 24-month commercialization delays. Watch EFSA safety re-evaluation schedules for polysorbate alternatives as the inflection signal triggering accelerated reformulation procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Origination | Cargill and ADM crushing networks secure cost-advantaged lecithin feedstocks across multiple geographies. |
| Precision Fermentation Scale-Up | Corbion and specialty biotech firms collapse cost gaps between microbial and plant-extracted emulsifiers. |
| Novel Food Dossier Parallel Preparation | Kerry Group and Palsgaard accelerate multi-jurisdiction certification to outpace regulatory divergence. |
| Direct-to-Processor Digital Platform Launch | B2B marketplaces disintermediate distributor layers in Indian and Southeast Asian mid-tier segments. |
| Mass-Balance Traceability Certification | Albert Heijn and Jumbo sustainability scorecards delist suppliers lacking verified deforestation-free palm documentation. |
Research Methodology
Cross-validation between primary interviews with emulsion science directors, procurement leads at multinational beverage brands, regulatory affairs specialists, and toll-processing operators anchors the qualitative findings. Secondary validation draws from EFSA safety evaluations, FDA GRAS notifications, customs and trade flow data, and SEC filings of listed agribusinesses. Bottom-up segmentation modeling triangulates against top-down market sizing from oilseed crushing capacity and fractionation throughput estimates.
Calibration against historical novel food approval timelines and reformulation cycle data from European dairy and bakery processors shapes the projection framework. Segmentation dimensions span product type (monoglycerides, lecithin, diglycerides, polysorbates), source origin (plant-based, microbial, synthetic, animal-based), application vertical, and geographic regulatory cluster. CAGRs derive from elasticity-adjusted demand curves for clean-label substitution, with fermentation cost-reduction curves and REACH authorization pressure as industry-specific forecast inputs.
Stress conditions across palm oil supply disruption scenarios, EFSA approval timeline extensions, and protein beverage formulation failure rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory convergence timelines and bioprocess cost trajectories. Cross-checking against customs data on lecithin import volumes and crushing margin reports from major oilseed processors is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Africa Food Flavor and Enhancer Market
Food Enhancers and Additives
Africa Water Enhancer Market
Food Enhancers and Additives
Flour Improvers Market
Food Enhancers and Additives
Feed Palatability Enhancers and Modifiers Market
Food Enhancers and Additives
Australia & New Zealand Food Flavors and Enhancers Market
Food Enhancers and Additives
Natural Taste Enhancers and Modifiers Market
Food Enhancers and Additives
Italy Anti-Caking Market
Food Enhancers and Additives
Vegetable Shortening Market
Food Enhancers and Additives
Water Enhancer Market
Food Enhancers and Additives
Fortified Eggs Market
Food Enhancers and Additives
Raising Agents Market
Food Enhancers and Additives
Mexico Water Enhancer Market
Food Enhancers and Additives
Isomalt Market
Food Enhancers and Additives
South Korea Fat Replacers Market
Food Enhancers and Additives
Crumb Softener Market
Food Enhancers and Additives
Dough Conditioners Market