
 Enriched Yeast Extract Market | 2026-2036
Enriched Yeast Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Enriched Yeast Extract Market Analytics
Pharmaceutical-grade autolyzed yeast specifications are redrawing procurement priorities across the enriched yeast extract value chain. Lallemand Inc. leverages captive fermentation capacity across North American facilities to sustain consistent beta-glucan yields. Kerry Group Plc anchors European supply through specialized extraction infrastructure in the United Kingdom and Ireland. Angel Yeast Co., Ltd. dominates Asian volume with integrated molasses-to-extract operations in Hubei province.
Enriched yeast extract comprises concentrated soluble components derived from Saccharomyces cerevisiae cell lysis, typically standardized to protein contents between 40% and 70% and nucleotide levels exceeding 10%. Manufacturers deploy autolysis or plasmolysis at controlled temperature and pH to rupture cell walls, then concentrate the hydrolysate for use as natural flavor enhancers, nutrient supplements, and fermentation media. Dry extract and powder formats lead value capture due to extended shelf stability and lower logistics costs, while liquid extract competes in high-volume beverage and savory base applications where dissolution speed matters. Food and beverage applications command the deepest margin pools as clean-label umami demand from processed food manufacturers intensifies specification premiums.
FDA GRAS self-determination frameworks and EFSA novel food evaluations shape cross-border market access for yeast-derived ingredients, with divergent documentation burdens between jurisdictions. China's SAMR food production licensing and GB standards for yeast products impose additional compositional testing requirements on imported extracts. Stakeholders must monitor evolving maximum residue limits for heavy metals and mycotoxins as regulatory harmonization remains incomplete across major consuming regions.
Market Dynamics
Plant-based meat manufacturers are expanding specifications for umami delivery systems, pulling enriched yeast extract into formulation pipelines previously dominated by hydrolyzed vegetable proteins and synthetic flavor enhancers. This demand rotation is compressing qualification timelines and forcing ingredient processors to synchronize beta-glucan standardization with clean-label positioning.
Growth Catalysts
- EU F-Gas Regulation:Tightening specifications for food-grade biotech inputs are accelerating adoption of fermentation-derived alternatives to petrochemical flavor precursors in Central European savory product manufacturing.
- Molasses-to-extract integration:Captive substrate supply chains in major producing regions are stabilizing nucleotide yield consistency and reducing lot-to-lot variation for pharmaceutical-grade autolyzed yeast.
- Clean-label umami:Processed food manufacturers are reformulating away from MSG and I+G toward yeast-derived alternatives that satisfy EFSA novel food evaluation frameworks without synthetic additive declarations.
Market Restraints
- Molasses price volatility:Sugar beet and cane supply fluctuations in India and Brazil transmit directly to substrate costs, compressing margins for non-integrated extract processors.
- Heavy metal residue limits:Divergent maximum residue limits for arsenic and cadmium between China's SAMR GB standards and FDA GRAS self-determination frameworks create cross-border documentation friction.
- Enzymatic hydrolysis substitutes:Fungal protease-derived flavor systems from Aspergillus oryzae fermentation are capturing share in mid-tier savory applications where nucleotide specificity matters less.
Strategic Opportunities
- Cell-culture media expansion:Biopharmaceutical serum-free formulation trends are opening high-margin demand for yeastolate products with defined peptide profiles and low endotoxin specifications.
- Pet food premiumization:Palatant manufacturers in Germany and the Netherlands are sourcing pharmaceutical-grade autolyzed yeast to replace synthetic attractants in natural-positioned premium kibble and wet food.
- Carbon accounting integration:EU Green Deal corporate sustainability reporting requirements are favoring fermentation-derived ingredients with verified lifecycle assessments over petrochemical alternatives.
Industry Challenges
- Autolysis parameter control:Temperature and pH precision requirements for consistent cell wall rupture demand specialized bioprocess engineering talent that concentrates in established fermentation clusters.
- Dual certification timelines:Simultaneous FDA GRAS self-determination and EFSA novel food evaluation processes extend market access preparation by 18-24 months for new extract variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enriched Yeast Extract Market |
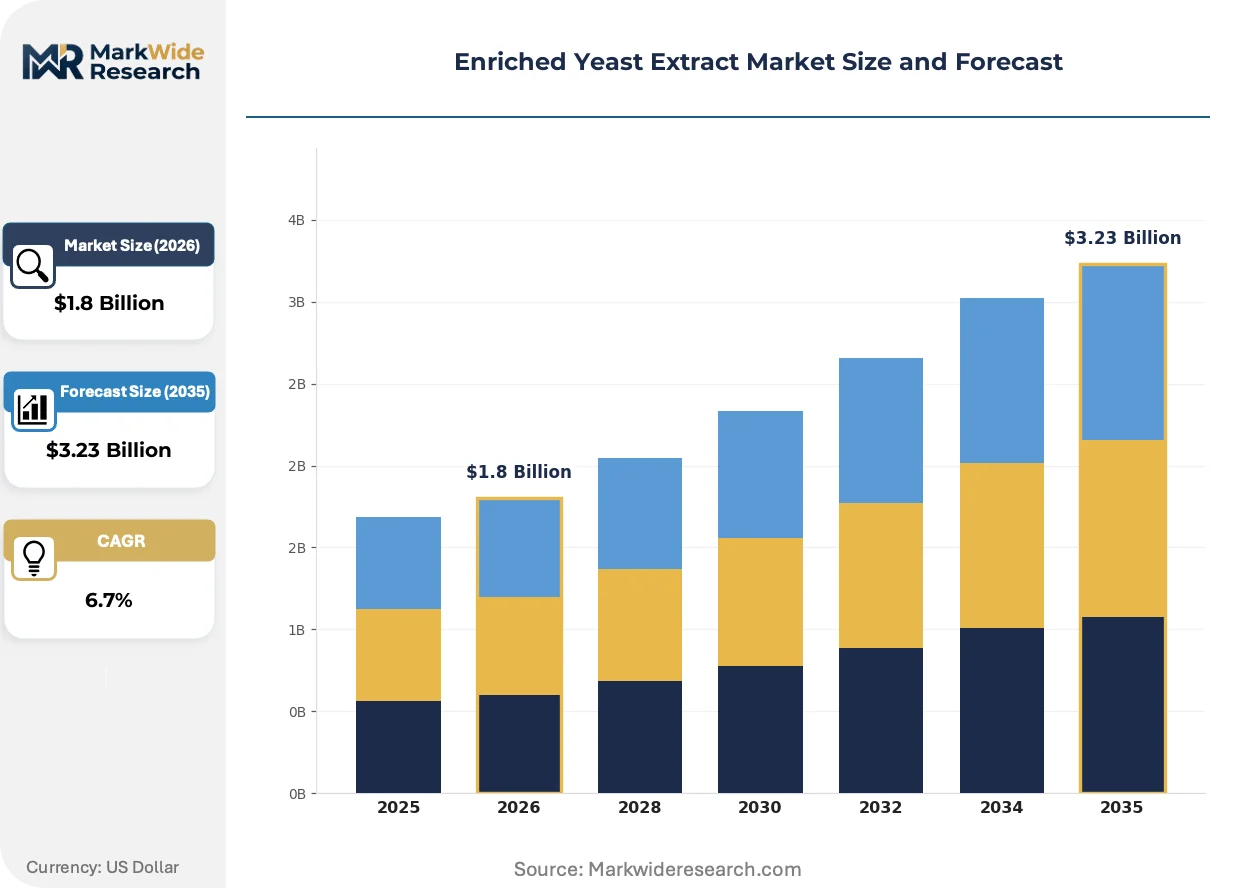
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Extract, Liquid Extract, Paste, Powder Application: Food & Beverage, Animal Feed, Nutraceuticals, Seasonings End User: Food Manufacturers, Feed Producers, Supplement Brands, Restaurants Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Lallemand Inc., Associated British Foods plc, Lesaffre Group, Biorigin, Chr. Hansen A/S, Angel Yeast Co., Ltd., Kerry Group Plc, Titan Biotech Ltd., Koninklijke DSM N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enriched Yeast Extract Market Evolving Landscape
Bioprocess intensification and regulatory harmonization pressures are converging to reshape how enriched yeast extract moves from fermentation tank to formulated end-product. Technology providers and ingredient processors are racing to compress development cycles while expanding application scope beyond traditional savory bases.
Continuous fermentation systems with real-time metabolite monitoring are supplanting batch autolysis operations in nucleotide-standardized extract production. North American pharmaceutical media suppliers are adopting these platforms to secure peptide consistency for serum-free cell culture applications. The shift is compressing capital recovery timelines for integrated processors while raising barriers for batch-dependent competitors.
REACH compliance documentation requirements for food-grade biotech inputs are forcing ingredient processors to map substance identity down to the peptide fraction level. Industrial consequence includes mandatory supply chain disclosure for toll manufacturers and co-packers using yeast extracts in EU-exported products. German savory base formulators are responding by consolidating supplier lists to processors with established ECHA registration dossiers.
Direct procurement relationships between plant-based meat startups and fermentation facilities are displacing traditional distributor intermediaries in high-specification umami sourcing. Contract manufacturing organizations with captive extraction infrastructure are capturing volume previously flowing through ingredient trading houses. This channel compression is most visible in California and the Netherlands where alternative protein venture density concentrates buying power.
Enriched Yeast Extract Market Segmentation
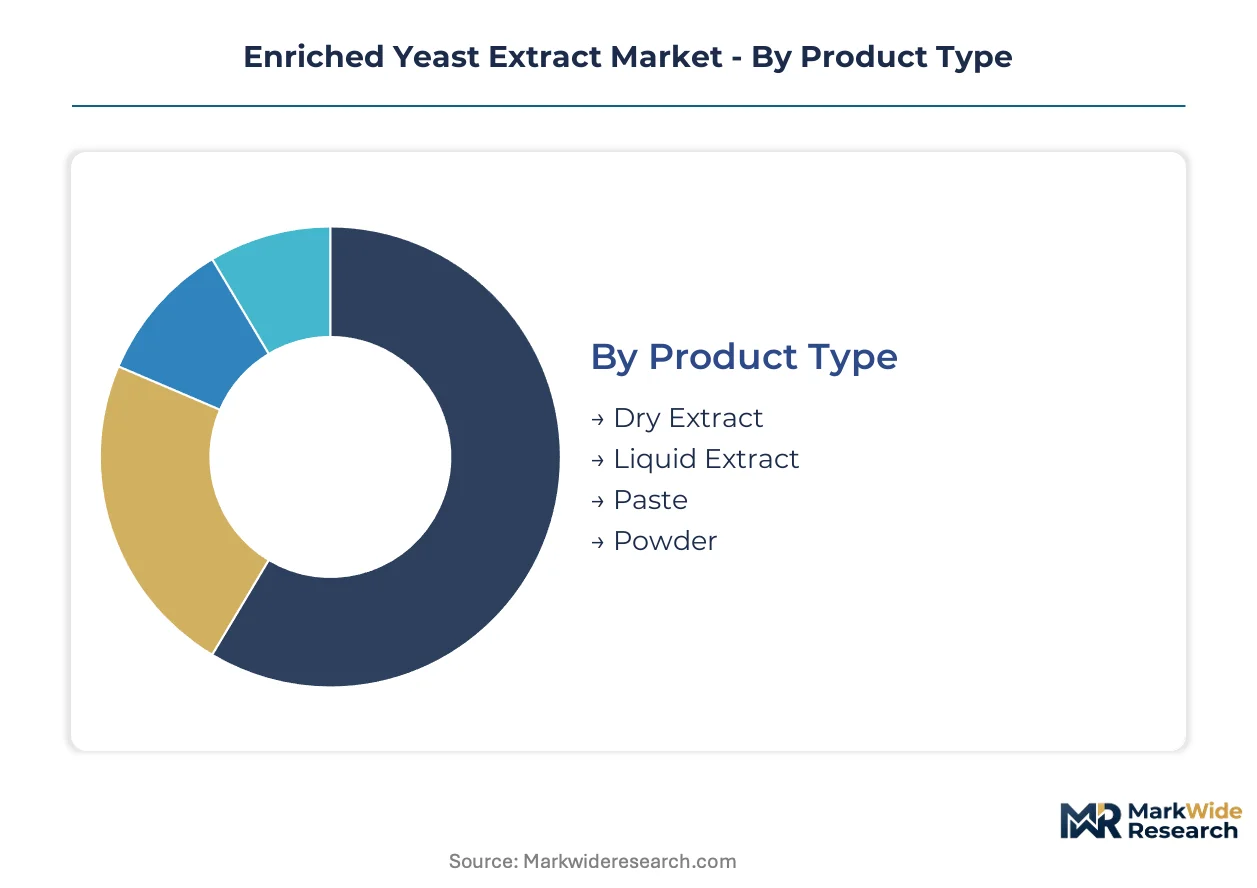
Segmentation in the enriched yeast extract market reveals distinct channel preferences and specification tiers that determine margin capture. Dry and powder formats dominate long-haul distribution networks, while liquid variants concentrate in regional savory base manufacturing where dissolution speed commands premium positioning.
Product Type:
Dry extract and powder flow through wholesale channels to food manufacturers seeking extended shelf stability, while liquid extract moves through specialty stores to high-volume beverage formulators.
- Dry Extract:Concentrated soluble components standardized to 40-70% protein content with nucleotide levels exceeding 10%. Demand concentrates in Central European savory product manufacturing where REACH compliance documentation for food-grade biotech inputs has tightened procurement specifications. German ingredient processors favor dry formats for cross-border distribution efficiency.
- Liquid Extract:Hydrolysate concentrate optimized for rapid dissolution in high-volume beverage and savory base applications. California plant-based meat startups source directly from fermentation facilities, displacing traditional distributor intermediaries in high-specification umami sourcing. Dissolution speed matters more than shelf stability in this channel.
- Paste:Semi-solid concentrate targeting restaurant and foodservice applications where portion control and handling convenience outweigh logistics costs.
- Powder:Spray-dried format capturing extended shelf stability and lower logistics costs in international trade lanes, particularly for supplement brands with multi-market distribution.
By volume, Dry Extract leads. By growth pace, Liquid Extract is ahead.
Application:
Cost tier differentiation separates pharmaceutical-grade autolyzed yeast specifications from commodity flavor enhancement, with margin pools deepest in segments requiring EFSA novel food evaluation frameworks.
- Food & Beverage:Clean-label umami demand from processed food manufacturers intensifies specification premiums. Reformulation away from MSG and I+G toward yeast-derived alternatives satisfies EFSA requirements without synthetic additive declarations. This tier commands the deepest margin pools.
- Animal Feed:Pet food premiumization in Germany and the Netherlands drives sourcing of pharmaceutical-grade autolyzed yeast to replace synthetic attractants in natural-positioned premium kibble and wet food.
- Nutraceuticals:Beta-glucan standardization for immune health positioning targets supplement brands with dual-certification tolerance for extended FDA GRAS and EFSA timelines.
- Seasonings:Mid-tier savory applications where nucleotide specificity matters less face competitive pressure from fungal protease-derived flavor systems.
Food & Beverage generates the highest absolute margins. Nutraceuticals shows the steepest expansion trajectory.
End User:
Customer type determines procurement sophistication, with integrated food manufacturers demanding captive fermentation capacity while feed producers prioritize substrate cost stability.
- Food Manufacturers:Processed food manufacturers with reformulation mandates drive clean-label umami specifications. Direct procurement relationships with fermentation facilities are compressing channel structures.
- Feed Producers:Palatant manufacturers seek pharmaceutical-grade autolyzed yeast with defined peptide profiles, consolidating supplier lists to processors with established ECHA registration dossiers.
- Supplement Brands:Immune health positioning requires beta-glucan standardization that synchronizes with clean-label marketing.
- Restaurants:Foodservice operators favor paste formats for handling convenience in high-turnover kitchen environments.
Food Manufacturers dominate procurement volume. Feed Producers are expanding specifications fastest.
Distribution Channel:
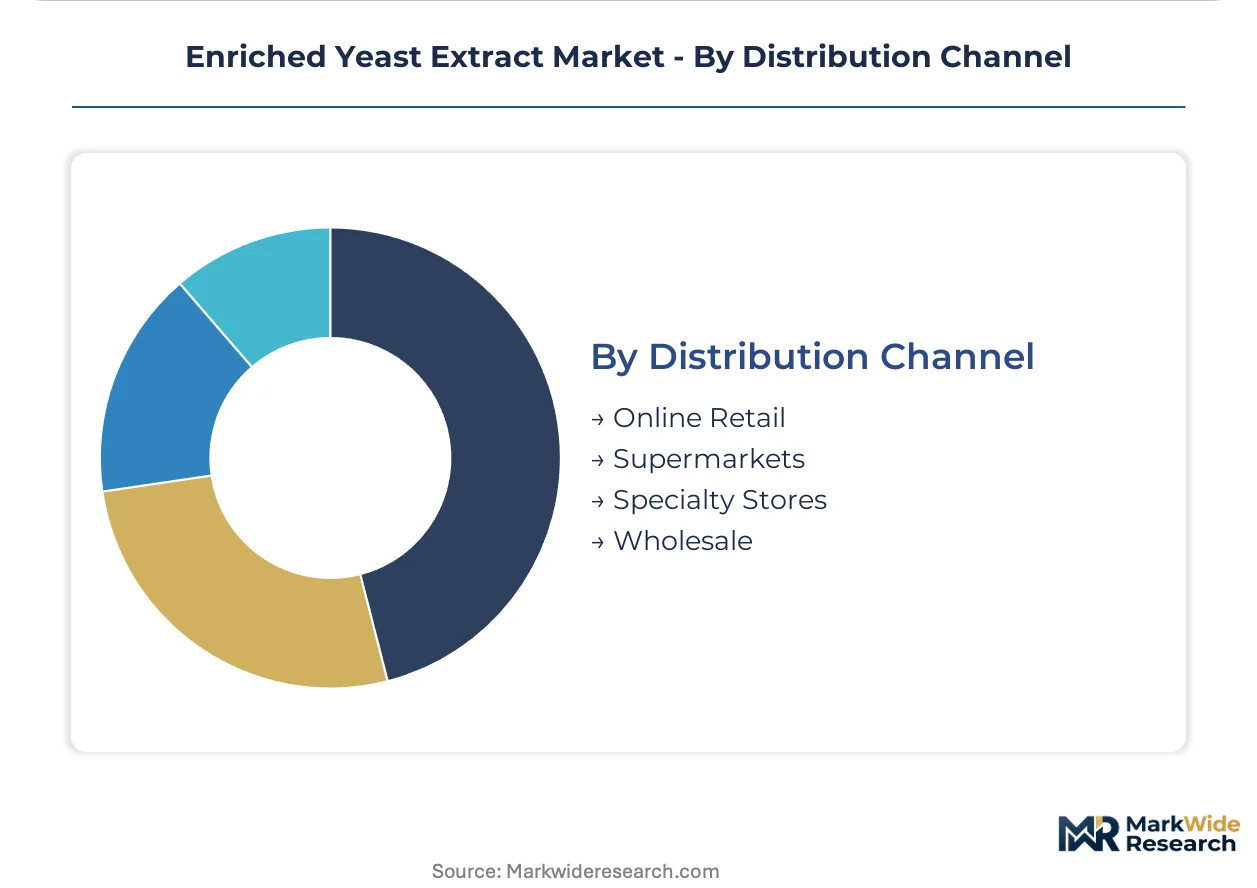
Volume scale separates wholesale bulk procurement from specialty store premium positioning, with online retail capturing share in small-batch supplement brands.
- Online Retail:Supplement brands with niche positioning leverage direct-to-manufacturer relationships to bypass traditional ingredient trading houses.
- Supermarkets:Consumer-facing powder formats for home cooking applications occupy shelf-stable convenience positioning.
- Specialty Stores:High-specification liquid extract for beverage formulators and artisanal savory base producers.
- Wholesale:Dry extract and powder bulk movement to integrated food manufacturers with multi-facility procurement operations.
Wholesale channels move the highest tonnage. Online Retail is gaining share fastest among emerging supplement brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in substrate procurement varies sharply across consuming regions. Buyers in molasses-importing markets face volatile feedstock costs, while integrated fermentation clusters in major beet and cane producing zones absorb supply shocks more smoothly.
Germany
Central European savory product manufacturers drive concentrated demand for REACH-compliant yeast extracts. The EU F-Gas Regulation tightens specifications for food-grade biotech inputs, accelerating substitution of petrochemical flavor precursors. Ingredient processors in Hamburg and Lower Saxony consolidate supplier lists to ECHA-registered dossier holders.
United States
Plant-based meat startups in California source liquid extract directly from fermentation facilities, bypassing traditional distributor channels. FDA GRAS self-determination frameworks govern novel extract variants, with qualification timelines compressing as venture-funded buyers consolidate procurement. The Pacific Northwest hosts emerging toll manufacturing capacity for nucleotide-standardized products.
China
Integrated molasses-to-extract operations in Hubei province stabilize nucleotide yields for domestic and export markets. SAMR food production licensing and GB standards impose compositional testing requirements on both local and imported extracts. Yangtze River Delta processors serve pharmaceutical-grade specifications for regional biopharmaceutical serum-free media demand.
Netherlands
Pet food palatant manufacturers in the Netherlands source pharmaceutical-grade autolyzed yeast for natural-positioned premium formulations. EFSA novel food evaluation requirements shape cross-border documentation for yeast-derived ingredients entering EU-wide distribution. Rotterdam-area logistics infrastructure supports bulk dry extract movement to German and Belgian compound feed operations.
India
Sugar beet and cane supply fluctuations transmit directly to substrate costs for non-integrated extract processors. FSSAI food safety standards and import licensing requirements create documentation friction for foreign yeast extract suppliers. Maharashtra-based fermentation facilities face margin compression from molasses price volatility during monsoon-disrupted harvest cycles.
Enriched Yeast Extract Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in the enriched yeast extract sector. Captive fermentation capacity and specialized extraction infrastructure define the top tier, while toll-dependent processors compete on formulation flexibility and regional service. Three archetypes dominate: integrated bioprocessors with substrate control, pharmaceutical-grade specialists with ECHA dossier depth, and regional toll manufacturers serving mid-tier savory applications. Competitive moves concentrate on backward integration into molasses supply and dual-certification capacity for simultaneous FDA and EFSA compliance.
Among the integrated bioprocessor archetype, Lallemand Inc., Angel Yeast Co., Ltd., and Kerry Group Plc exemplify contrasting geographic and structural positioning. Lallemand represents North American captive fermentation capacity with standardized beta-glucan yield control. Angel Yeast anchors Asian volume through integrated upstream substrate operations. Kerry Group occupies European supply security through specialized extraction infrastructure in the United Kingdom and Ireland. Each exemplifies how substrate integration or downstream specialization shapes competitive position without overlapping core geographic strongholds.
| Leading Market Players |
|---|
| Lallemand Inc. |
| Associated British Foods plc |
| Lesaffre Group |
| Biorigin |
| Chr. Hansen A/S |
| Angel Yeast Co., Ltd. |
| Kerry Group Plc |
| Titan Biotech Ltd. |
| Koninklijke DSM N.V. |
| Others |
Value Network & Pricing Analysis
Captive fermentation capacity utilization in Hubei province and Hamburg establishes price floors that non-integrated processors cannot match, compressing margin structures across the value chain while concentrating procurement power among substrate-controlled producers. Molasses-to-extract integration stabilizes nucleotide yield consistency but raises capital barriers, forcing mid-tier competitors toward toll manufacturing arrangements that sacrifice pricing autonomy.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure by mandating REACH compliance documentation that separates ECHA-registered dossier holders from uncertified competitors. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels reflects divergent documentation burdens and beta-glucan standardization requirements. Cost compression in feed-grade segments is intensifying because enzymatic hydrolysis substitutes from Aspergillus oryzae fermentation capture mid-tier savory share. Food manufacturers with dual-certification tolerance show least price sensitivity, while regional toll processors serving unbranded seasonings face acute margin pressure.
Supply Chain Analysis
Inventory lead times stretch 8-12 weeks for liquid extract shipped from Yangtze River Delta facilities to California plant-based meat startups, compressing formulation windows for venture-funded buyers. Supply concentrates in China, Germany, and the United States, with Hubei province anchoring Asian substrate integration and Hamburg serving Central European savory manufacturing. Raw material dependencies center on sugar beet molasses, cane molasses, and specialized protease enzymes for plasmolysis control. Single-source vulnerability runs through Indian monsoon-disrupted harvest cycles that transmit directly to substrate costs. Distribution runs through direct procurement relationships displacing traditional ingredient trading houses in high-specification umami sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as clean-label reformulation mandates splinter demand across pharmaceutical-grade, food-grade, and pet food palatant specifications, creating defendable niches for specialized processors.
For Market Incumbents: Compound defensive positioning by deepening captive molasses supply chains in beet-producing regions and accelerating dual-certification capacity for simultaneous FDA GRAS and EFSA compliance. Threat from enzymatic hydrolysis substitutes demands nucleotide specificity investments that fungal protease systems cannot replicate. Channel control through direct procurement relationships with plant-based meat startups secures volume previously flowing through distributors. For New Entrants and Emerging Players: FDA GRAS self-determination fast-tracks offer entry into nutraceutical beta-glucan segments where immune health positioning commands specification premiums. White-space targets include pet food palatant manufacturing in the Netherlands and serum-free cell culture media for biopharmaceutical applications. Go-to-market angle should leverage carbon accounting integration under EU Green Deal sustainability reporting requirements to displace petrochemical flavor precursors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated bioprocessors with substrate control over toll-dependent competitors facing margin compression. Long-term viability hinges on backward integration into molasses supply and continuous fermentation platform adoption. Acquisition target archetype: regional processors with established ECHA registration dossiers and specialized extraction infrastructure. Signal to watch: consolidation of supplier lists by German savory base formulators as REACH compliance documentation requirements tighten.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molasses Supply | Captive substrate chains in Hubei and Maharashtra stabilize nucleotide yields against harvest volatility. |
| Dual-Certification Capacity Investment | Simultaneous FDA GRAS and EFSA novel food evaluation opens cross-border access for pharmaceutical-grade extracts. |
| Continuous Fermentation Platform Adoption | Real-time metabolite monitoring compresses capital recovery timelines for nucleotide-standardized production. |
| Direct Procurement Relationship Development | California and Netherlands plant-based meat startups bypass distributor intermediaries for high-specification umami. |
| Carbon Accounting Integration Program | Verified lifecycle assessments under EU Green Deal requirements favor fermentation-derived over petrochemical inputs. |
Research Methodology
Initial hypotheses were tested against primary input from fermentation facility operations directors, savory product formulators, regulatory affairs specialists at ingredient processors, and procurement leads at plant-based meat manufacturers, then refined through secondary validation. Secondary sources included SAMR food production licensing databases, ECHA registration dossiers, FDA GRAS notification filings, and EU F-Gas Regulation implementation guidance. Bottom-up volume estimates from molasses-to-extract operations triangulated against top-down market sizing from trade flow analysis.
Variance-decomposition framing separated volume drivers from price-level effects across the projection horizon. Segmentation dimensions modeled include product format hierarchy, application-grade certification tier, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from fitted growth curves anchored to disclosed capacity expansions and qualification timeline compression. Industry-specific forecast inputs incorporated REACH compliance documentation burden trajectories and plant-based meat venture funding velocity as demand proxies.
The analysis sits within stated boundaries; outcomes outside sustained EU F-Gas Regulation enforcement or abrupt molasses supply disruption would require recalibration. Forecasts reflect documented assumptions about regulatory harmonization progress and clean-label reformulation penetration rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Europe Water Enhancer Market
Food Enhancers and Additives
Fortifying Agent Market
Food Enhancers and Additives
Japan Water Enhancer Market
Food Enhancers and Additives
Flour Conditioner Market
Food Enhancers and Additives
Trans-Resveratrol Market
Food Enhancers and Additives
Gut Modifiers Market
Food Enhancers and Additives
Food Raising Agents Market
Food Enhancers and Additives
Crumb Softener Market
Food Enhancers and Additives
Anti-Sagging Agents Market
Food Enhancers and Additives
India Food Flavor and Enhancer Market
Food Enhancers and Additives
Europe Feed Palatability Enhancers Market
Food Enhancers and Additives
North America Feed Palatability Enhancers Market
Food Enhancers and Additives
Used Cooking Oil Market
Food Enhancers and Additives
Asia-Pacific Food Flavor and Enhancer Market
Food Enhancers and Additives
Cake Softener Market
Food Enhancers and Additives
Natural Taste Enhancers and Modifiers Market