
 North America Feed Palatability Enhancers Market | 2026-2036
North America Feed Palatability Enhancers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Feed Palatability Enhancers Market Analytics
Subscription-based palatability testing services is decoupling product development from traditional capital-intensive flavor houses. Kemin Industries leverages its Iowa-based manufacturing footprint to anchor supply relationships with Midwestern feed compounders. DuPont competes through microbial fermentation platforms that reduce batch-to-batch variability in sweetener potency. Symrise AG extends its botanical extraction expertise into species-specific flavor profiles for premium pet food channels.
Feed palatability enhancers comprise flavoring agents, sweeteners, texturizers, and nutritional additives formulated to stimulate voluntary feed intake across livestock, aquaculture, and companion animal species. These compounds typically incorporate volatile organic compounds, amino acid derivatives, or lipid-based carriers applied at inclusion rates between 0.01% and 2.0% by weight during pelleting or extrusion. Flavoring agents occupy the largest value pool due to their direct impact on first-pass consumption metrics in commercial feed trials. Sweeteners represent the fastest-growing product class as dairy nutrition and pet food formulators seek alternatives to molasses and sucrose with lower hygroscopicity and improved flow characteristics.
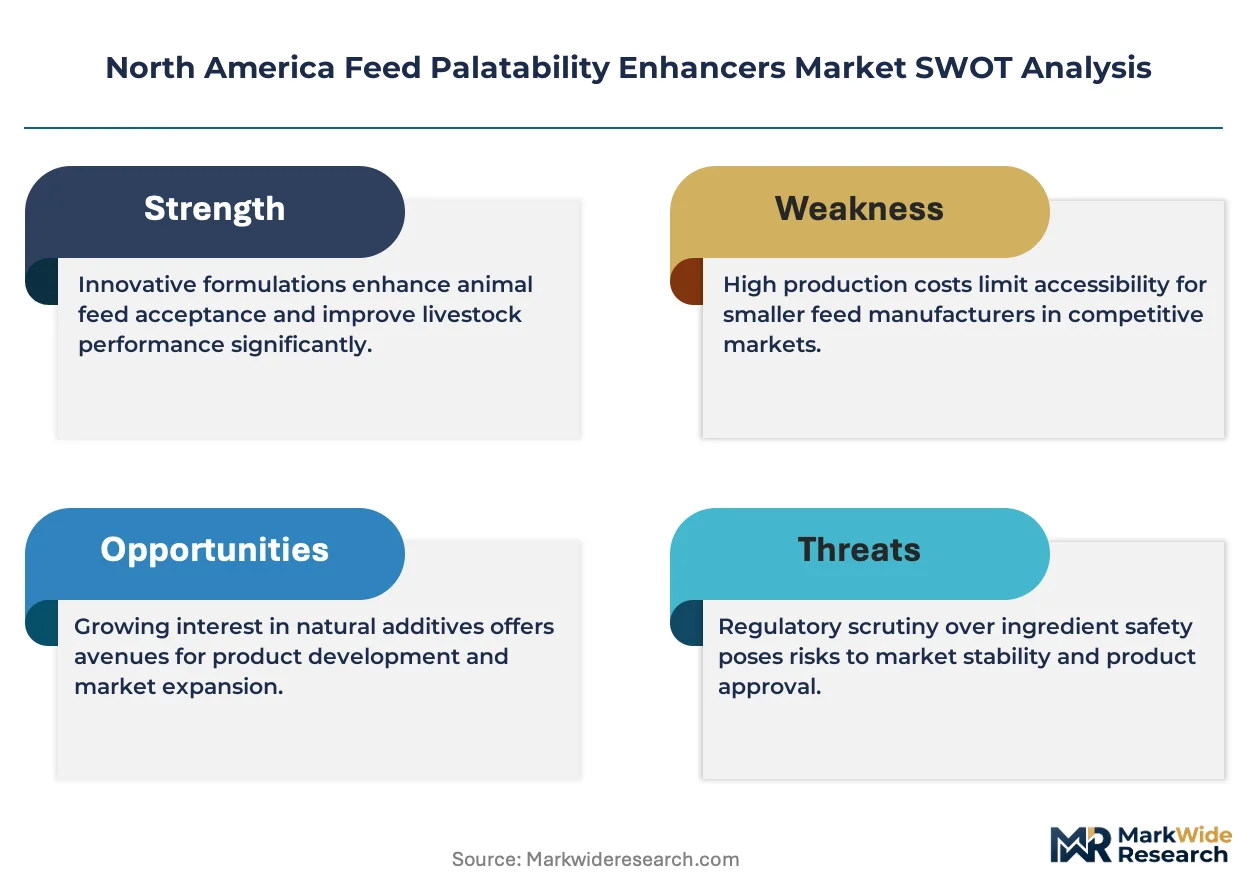
The U.S. Food and Drug Administration, the Canadian Food Inspection Agency, and the Association of American Feed Control Officials collectively govern ingredient safety assessments, labeling requirements, and Good Manufacturing Practice standards across the North American supply chain. These frameworks mandate pre-market notification for novel flavor compounds and restrict certain synthetic palatants in ruminant feeds, compelling manufacturers to maintain dual formulation portfolios. Stakeholders must monitor pending state-level feed additive legislation in California and New York that could diverge from federal tolerances and fragment compliance obligations.
Market Dynamics
Subscription-based palatability testing services are decoupling product development from traditional capital-intensive flavor houses, compressing R&D cycles and lowering barriers to entry for mid-tier feed compounders across the United States and Canada.
Growth Catalysts
- AAFCO ingredient definitions:Standardized nomenclature for novel flavor compounds accelerates cross-state product registration and reduces reformulation costs for multi-territory feed manufacturers.
- Dairy nutrition formulators:Widespread substitution of molasses with non-hygroscopic sweeteners in total mixed rations drives volume demand for low-moisture palatability systems.
- Midwest protein production corridors:Concentrated livestock operations in Iowa, Illinois, and Nebraska generate procurement scale that justifies dedicated palatability additive manufacturing footprints.
Market Restraints
- Novel compound notification requirements:FDA pre-market review timelines for new flavor molecules extend commercialization cycles by 18-24 months.
- Botanical extract supply:Weather-dependent harvests of vanilla and citrus derivatives in Mexico and Central America create input cost volatility.
- Dual formulation portfolios:Restrictions on synthetic palatants in ruminant feeds force manufacturers to maintain separate product lines, inflating inventory carrying costs.
Strategic Opportunities
- California state-level legislation:Pending feed additive disclosure requirements could create first-mover advantage for transparent ingredient labeling systems.
- Microbial fermentation sweeteners:Convergence of precision fermentation and enzymatic modification enables consistent glycoside potency without agricultural extraction.
- Premium pet food channels:Species-specific flavor profiles for feline and canine segments command formulation premiums in direct-to-consumer subscription models.
Industry Challenges
- Flavor chemist talent scarcity:Specialized expertise in volatile organic compound stability across pelleting temperatures remains concentrated among legacy flavor houses.
- Extrusion equipment retrofitting:Heat-sensitive palatant application requires capital investment in post-pelleting liquid coating systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Feed Palatability Enhancers Market |
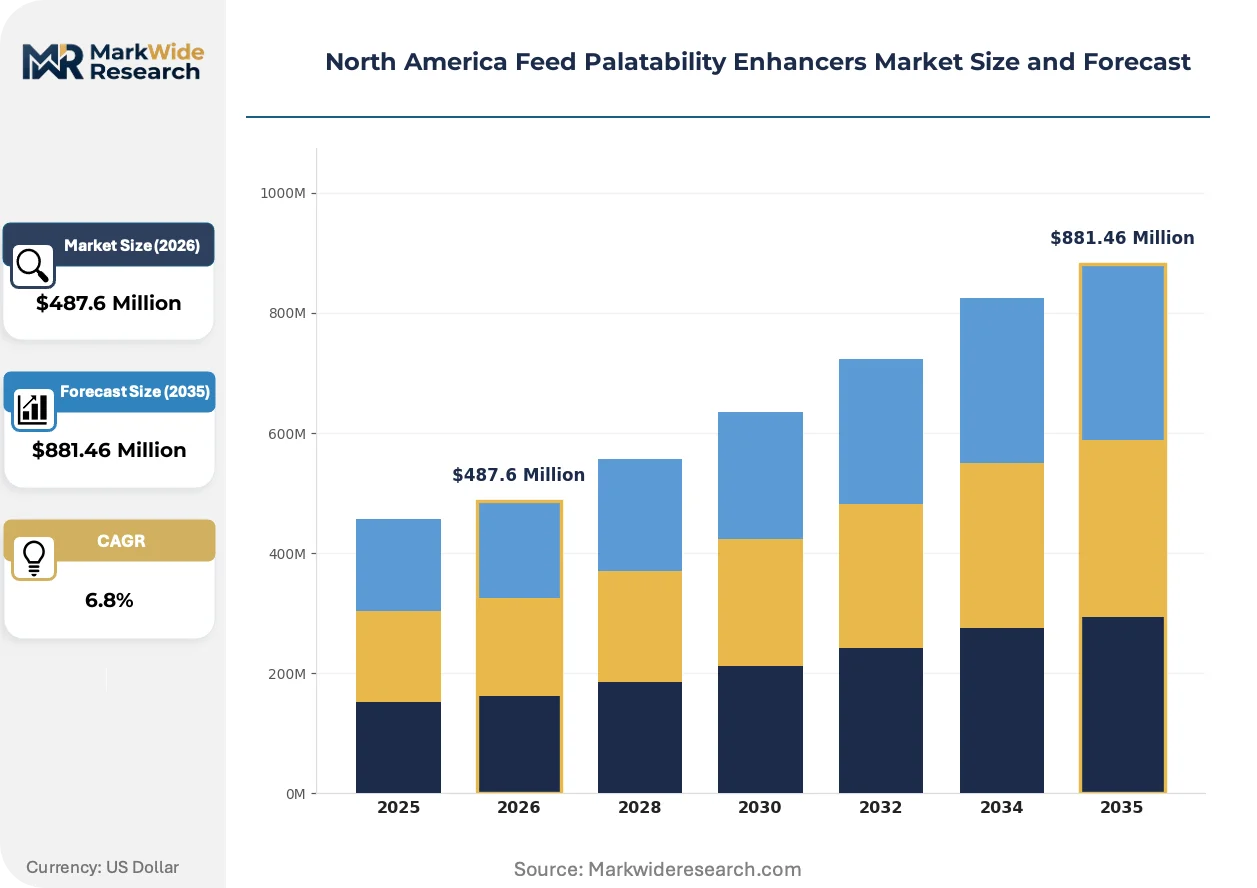
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavoring Agents, Sweeteners, Texturizers, Nutritional Additives Application: Pet Food, Livestock Feed, Aquaculture, Dairy Nutrition End User: Farmers, Pet Owners, Feed Manufacturers, Aquaculture Producers Distribution Channel: Online Retail, Distributors, Specialty Stores, Direct Sales |
| Companies Covered | Symrise AG, Kemin Industries, Associated British Foods PLC, DuPont, Adisseo, Cargill, ADM Animal Nutrition, Kerry Group, Elanco Animal Health, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Feed Palatability Enhancers Market Evolving Landscape
Digital palatability testing platforms and precision fermentation are converging to compress product development timelines while expanding the addressable ingredient universe beyond traditional botanical and synthetic sources.
Encapsulation technology using lipid-based carriers is expanding into high-temperature extrusion applications previously dominated by surface-sprayed liquid flavors. Large-scale pet food manufacturers in the United States are adopting microencapsulated palatants at inclusion rates below 0.5% by weight to preserve volatile compounds through processing. This shift is expanding into species-specific formulations where thermal degradation previously limited flavor complexity.
The FDA's evolving guidelines on feed-grade additives are compelling manufacturers to submit expanded safety dossiers for novel flavor compounds, particularly those derived from microbial fermentation. This regulatory tightening is elevating compliance costs for smaller ingredient suppliers while consolidating approval expertise among firms with dedicated regulatory affairs functions. Dairy nutrition and aquaculture feed segments are most affected, with several pending notifications stalled in pre-market review queues.
Buyer concentration among integrated protein producers is compressing supplier negotiation cycles and demanding real-time consumption data from commercial feed trials. Large Midwestern livestock operations now require palatability vendors to provide on-farm testing protocols rather than laboratory-based preference studies. This behavioral shift is most visible in Nebraska and Iowa, where procurement teams are unbundling flavor supply from full-nutrition premix contracts to optimize unit economics.
North America Feed Palatability Enhancers Market Segmentation
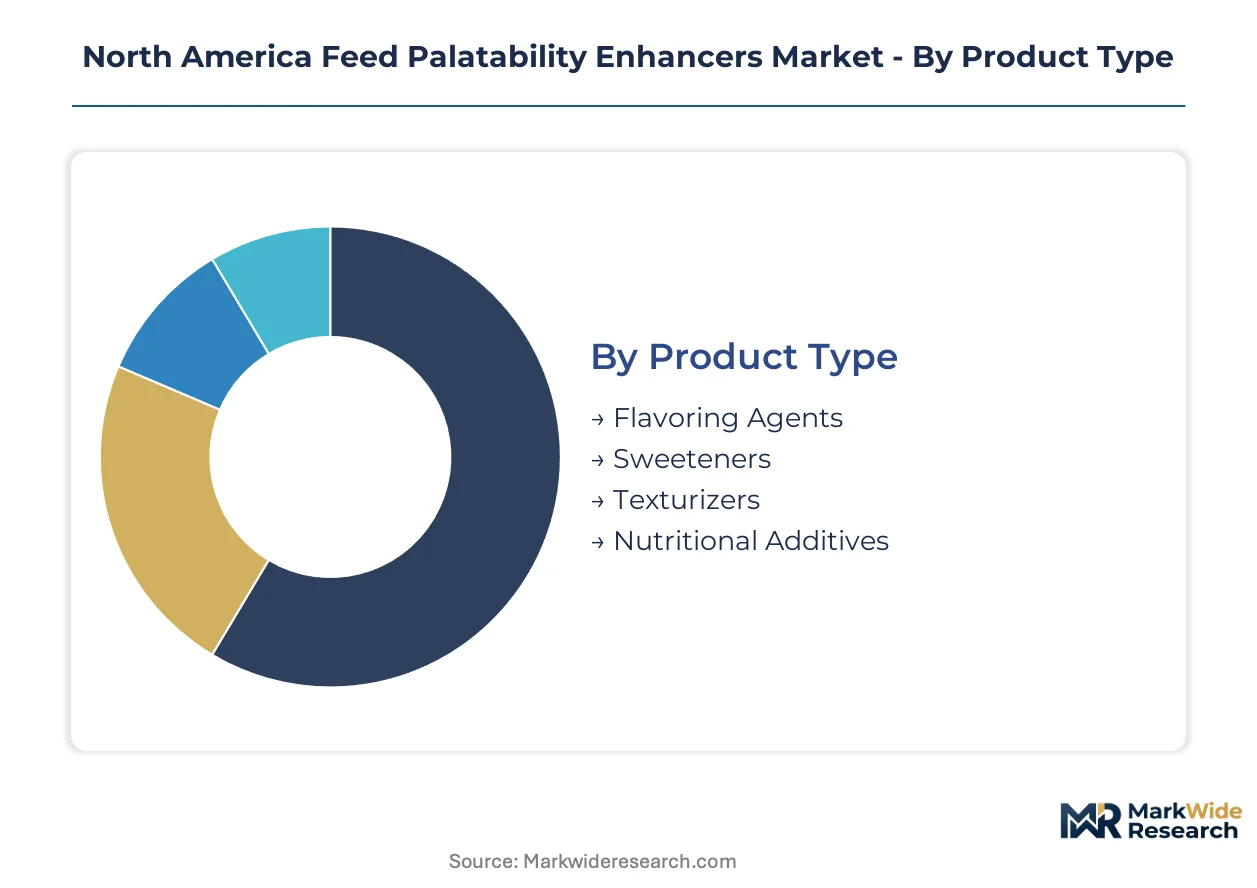
Feed palatability enhancers exhibit distinct performance profiles across product chemistry, species application, and procurement channels. Manufacturers optimize formulation strategies differently depending on whether additives serve standalone flavor systems or embed within complete nutritional premixes.
Product Type:
Flavoring agents and sweeteners dominate standalone additive sales, while texturizers and nutritional additives embed more deeply into integrated feed systems.
- Flavoring Agents:Volatile organic compounds and amino acid derivatives applied at 0.01-0.5% inclusion rates. Demand concentrates in premium pet food channels across California and New York, where first-pass consumption metrics determine procurement decisions. FDA pre-market notification requirements for novel molecules extend commercialization timelines.
- Sweeteners:Non-hygroscopic glycosides and fermentation-derived compounds replacing molasses in dairy total mixed rations. Procurement scale in Iowa and Nebraska livestock corridors justifies dedicated manufacturing footprints for low-moisture palatability systems.
- Texturizers:Lipid-based carriers and hydrocolloids modifying mouthfeel in extruded pet foods. Midwestern feed compounders integrate these during pelleting operations.
- Nutritional Additives:Vitamin and mineral complexes with dual palatability-nutrition functionality. Aquaculture feed manufacturers in the Pacific Northwest specify these for species-specific acceptance profiles.
Flavoring agents lead volumes today; sweeteners are gaining share fastest.
Application:
Cost tier segmentation separates premium-positioned pet food from commodity livestock nutrition, with aquaculture and dairy occupying intermediate value bands.
- Pet Food:Species-specific flavor profiles for feline and canine segments commanding formulation premiums. Direct-to-consumer subscription models in metropolitan markets drive demand for microencapsulated palatants below 0.5% inclusion.
- Livestock Feed:Large-scale Midwestern operations in Illinois and Nebraska unbundle flavor supply from full-nutrition premix contracts. AAFCO standardized nomenclature accelerates cross-state registration for multi-territory manufacturers.
- Aquaculture:Species-specific acceptance studies for salmon and shrimp feeds. Pacific Northwest producers require on-farm testing protocols rather than laboratory preference studies.
- Dairy Nutrition:Widespread molasses substitution with non-hygroscopic alternatives in total mixed rations. Heat-sensitive palatant application demands capital investment in post-pelleting liquid coating systems.
Livestock feed anchors volume; pet food shows the steepest expansion trajectory.
End User:
Customer type determines technical service intensity, with feed manufacturers demanding formulation support and farmers prioritizing unit economics.
- Farmers:Midwestern protein producers in Iowa and Nebraska requiring real-time consumption data from commercial feed trials. Procurement teams specify on-farm testing protocols.
- Pet Owners:Subscription-based direct purchasing in premium channels, decoupling product evaluation from traditional retail.
- Feed Manufacturers:Integrated compounders in the Midwest maintaining dual formulation portfolios for ruminant and monogastric species. Inventory carrying costs inflate due to synthetic palatant restrictions in cattle feeds.
- Aquaculture Producers:Pacific Northwest operations demanding species-specific flavor complexity previously limited by thermal degradation.
Feed manufacturers dominate procurement volumes; pet owners are expanding most quickly.
Distribution Channel:
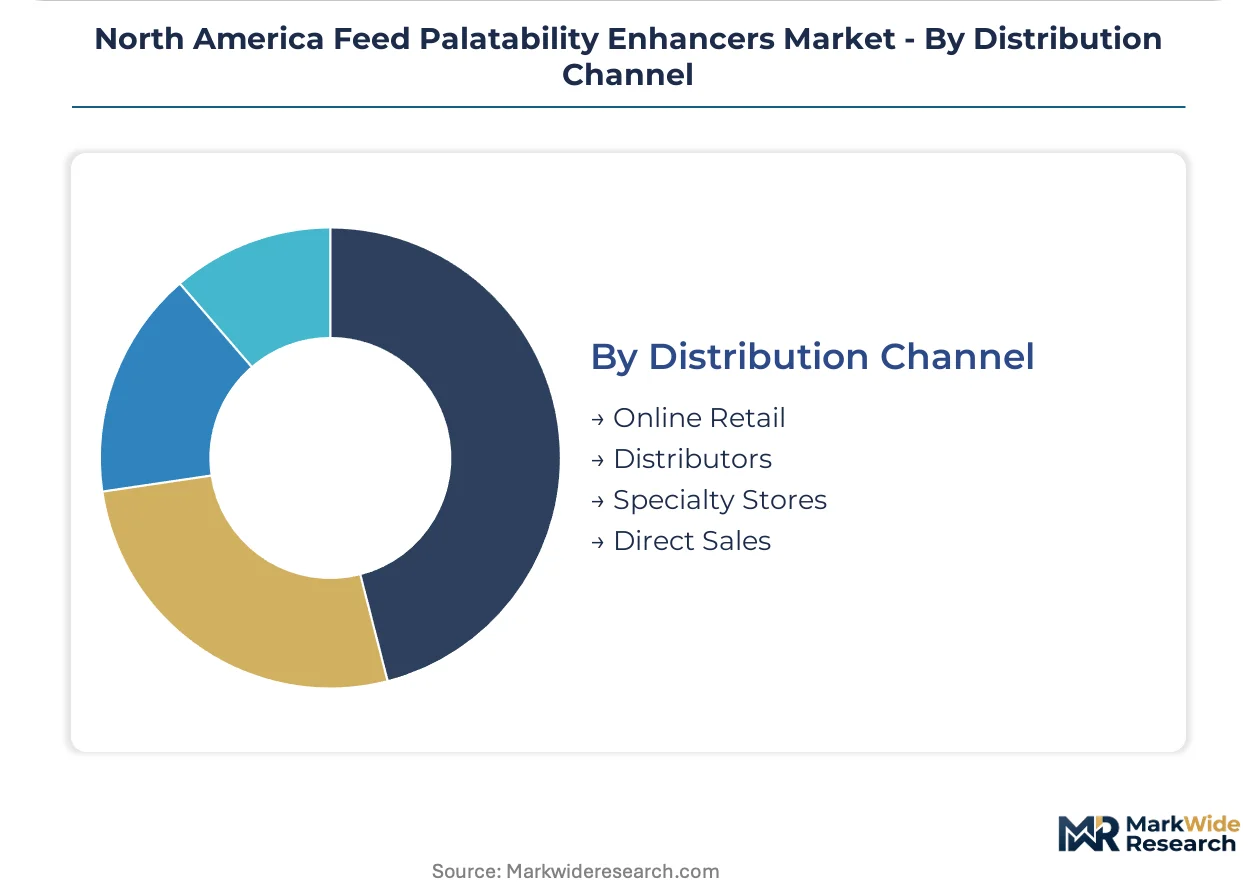
Supply concentration favors distributor networks for commodity livestock applications, while specialty and direct channels capture premium pet nutrition.
- Online Retail:Direct-to-consumer subscription models in premium pet food segments, compressing traditional distributor margins.
- Distributors:Full-nutrition premix bundling in Midwestern livestock corridors, though unbundling trends accelerate.
- Specialty Stores:Independent pet retailers in metropolitan markets emphasizing transparent ingredient labeling systems.
- Direct Sales:Technical service relationships between palatability vendors and integrated protein producers, particularly in Nebraska and Iowa.
Distributors maintain volume leadership; online retail climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's regulatory trajectory diverges from the United States as provincial feed additive disclosure requirements advance faster than federal harmonization. Mexico's agricultural export corridors are driving adoption of palatability systems that meet dual U.S.-Canadian compliance standards.
United States
Midwestern protein production corridors in Iowa, Illinois, and Nebraska concentrate procurement scale for large livestock operations. The FDA's evolving guidelines on feed-grade additives compel manufacturers to submit expanded safety dossiers for novel flavor compounds. Integrated feed mills around Omaha and Des Moines are unbundling flavor supply from full-nutrition premix contracts to optimize unit economics.
Canada
Dairy nutrition formulators in Ontario and Quebec are substituting molasses with non-hygroscopic sweeteners in total mixed rations. The Canadian Food Inspection Agency governs ingredient safety assessments alongside provincial feed boards. Manufacturing footprints in Alberta serve Prairie livestock operations with dedicated low-moisture palatability systems.
Mexico
Botanical extract supply chains from Veracruz and Oaxaca face weather-dependent harvest volatility for vanilla and citrus derivatives. The country's national agricultural regulator coordinates with FDA-equivalent standards for export-oriented feed producers. Poultry and swine operations in Jalisco and Nuevo León are adopting species-specific flavor profiles for premium protein export channels.
North America Feed Palatability Enhancers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated nutrition companies capturing livestock feed volumes while flavor houses dominate premium pet food channels. The vendor base concentrates among three tiers: global diversified nutrition conglomerates, regional fermentation and extraction specialists, and subscription-based testing service platforms. Strategic archetypes include backward-integrated compounders controlling captive flavor supply, precision fermentation platforms reducing batch variability, and botanical extraction houses extending expertise into species-specific profiles. Capacity expansion in Midwestern manufacturing corridors and technology licensing for microbial-derived sweeteners represent the dominant competitive moves.
Within the fermentation-technology tier, DuPont exemplifies platforms reducing sweetener potency variability through microbial processes. Kemin Industries anchors supply relationships through Iowa-based manufacturing proximity to Midwestern feed compounders. Symrise AG occupies a position translating botanical extraction expertise into premium pet food flavor complexity. These three entities represent distinct strategic archetypes: industrial biotechnology, geographic supply anchoring, and natural ingredient premiumization.
| Leading Market Players |
|---|
| Symrise AG |
| Kemin Industries |
| Associated British Foods PLC |
| DuPont |
| Adisseo |
| Cargill |
| ADM Animal Nutrition |
| Kerry Group |
| Elanco Animal Health |
| Others |
Value Network & Pricing Analysis
Microbial fermentation platforms for sweetener production are compressing unit economics while redrawing supplier concentration maps across the North American feed additive landscape. This biotechnology shift simultaneously erodes traditional agricultural extraction margins and rewards capital-intensive manufacturing footprints with batch-to-batch consistency guarantees.
Pricing Analysis
Capacity additions in Iowa and Nebraska are reshaping price floors for low-moisture palatability systems as regional compounders achieve procurement scale. Three-tier pricing structure across premium, standard, and economy levels separates microencapsulated pet food palatants from commodity livestock flavoring agents. Cost compression in standard-tier sweeteners is intensifying because fermentation-derived glycosides displace molasses with superior flow characteristics. Livestock feed manufacturers exhibit highest price sensitivity due to unbundling trends, while premium pet food channels absorb formulation premiums for species-specific profiles.
Supply Chain Analysis
Dual-sourcing requirements from integrated protein producers in the Midwest mandate multi-supplier qualification for heat-sensitive palatant coatings. Manufacturing concentrates in the United States, Canada, and Mexico with Veracruz supplying weather-dependent vanilla and citrus derivatives. Raw material dependencies include fermentation feedstocks, lipid-based carriers, and botanical extracts. Single-source vulnerability persists for specialized flavor chemist expertise concentrated among legacy houses. Distribution runs through technical service relationships between vendors and large livestock operations, with unbundling trends accelerating direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Feed Palatability Enhancers Market represents a late-cycle quality story as pet food formulators shift demand toward microencapsulated, species-specific flavor systems that command sustained formulation premiums.
For Market Incumbents: Extend regulatory affairs capabilities to navigate FDA pre-market notification timelines that stall smaller competitors. Build captive fermentation capacity to defend margin position against biotechnology entrants displacing traditional extraction methods. Channel control through Iowa-based manufacturing proximity remains essential as Midwestern compounders consolidate supplier relationships. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for premium pet food palatants below 0.5% inclusion rates. Target California metropolitan markets where transparent ingredient labeling requirements create first-mover positioning. White-space exists in precision fermentation sweeteners for dairy nutrition formulators seeking non-hygroscopic alternatives to molasses. For Investors and Strategic Acquirers: Roll-up economics work for regional fermentation specialists because batch-to-batch variability reduction commands persistent technology premiums. Five-to-ten year viability hinges on microbial platform consolidation as synthetic biology scales. Acquisition targets should demonstrate dedicated regulatory affairs functions with queued FDA notifications. Watch stalled pre-market review queues as inflection indicator for approval expertise scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | DuPont's microbial platforms reduce sweetener potency variability for dairy nutrition formulators. |
| Post-Pelleting Coating Investment | Capital deployment in liquid application systems preserves volatile compounds through high-temperature extrusion. |
| Regulatory Affairs Expansion | Dedicated FDA notification expertise accelerates novel compound commercialization timelines. |
| Midwest Manufacturing Footprint | Iowa-based proximity anchors supply relationships with concentrated livestock operations. |
| Subscription Testing Platform Launch | Digital palatability services compress R&D cycles for mid-tier feed compounders. |
Research Methodology
Direct dialogue with feed formulation scientists, regulatory affairs directors at flavor houses, procurement managers at integrated protein producers, and technical service leads at palatability vendors grounded qualitative findings. Secondary validation drew from FDA pre-market notification databases, AAFCO ingredient definition proceedings, USDA livestock production statistics, and SEC filings from publicly traded nutrition conglomerates. Bottom-up demand modeling triangulated against top-down supply capacity assessments across fermentation and extraction platforms.
Segmented outputs across the projection horizon reflect product chemistry tiers, species application categories, and procurement channel structures. CAGRs emerged from iterative reconciliation of historical consumption patterns with disclosed capacity expansion timelines. Key inputs included dairy nutrition molasses substitution rates, pet food microencapsulation adoption curves, and FDA review queue velocity assumptions.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation sweeteners would alter the outlook if batch consistency fails to achieve cost parity with agricultural extraction. Forecasts incorporate assumptions about regulatory harmonization between federal and state-level feed additive standards. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Raising Agents Market
Food Enhancers and Additives
Asia-Pacific Flavor Enhancer Market
Food Enhancers and Additives
Resveratrol Market
Food Enhancers and Additives
Emulsifier Enhancers Market
Food Enhancers and Additives
United Kingdom Interesterified Fats Market
Food Enhancers and Additives
Browning Enhancers Market
Food Enhancers and Additives
North America Food Thickeners Market
Food Enhancers and Additives
Global Citrus Aurantium Extract Market
Food Enhancers and Additives
Frying Shortening Market
Food Enhancers and Additives
Food Raising Agents Market
Food Enhancers and Additives
Liquid Water Enhancers Market
Food Enhancers and Additives
Asia-Pacific Feed Palatability Enhancers Market
Food Enhancers and Additives
Dysphagia Diet Thickening Market
Food Enhancers and Additives
Isomalt Market
Food Enhancers and Additives
North America Water Enhancer Market
Food Enhancers and Additives
Isoprenol Market