
 United States Surveillance Camera Market | 2026-2036
United States Surveillance Camera Market Size, Share, and Industry Trends Forecast 2026-2036
United States Surveillance Camera Market Insights
Municipal governments is rotating toward cloud-managed video platforms as the fastest-growing buyer archetype in the United States surveillance camera landscape. Hanwha Vision America leverages its American manufacturing footprint to satisfy federal sourcing requirements. Bosch Sicherheitssysteme GmbH anchors its position through deep integration with building management systems. Motorola Solutions dominates the public safety vertical through its command-center software ecosystem.
United States surveillance cameras are electro-optical devices capturing continuous visual data for security, operational monitoring, and evidentiary purposes, typically operating across infrared and visible spectrums with resolutions from 2MP to 4K and frame rates between 15fps and 60fps depending on application criticality. Their primary commercial purpose centers on loss prevention, perimeter protection, and real-time situational awareness across critical infrastructure and commercial facilities. Dome cameras lead the product type category due to vandal-resistant housings and discreet positioning in retail and hospitality settings, while thermal technology within the technology segment captures expanding share in perimeter defense and low-visibility environments where conventional imaging fails. IP-based systems command the technology margin pool through recurring software licensing and cloud storage attach rates that analog infrastructure cannot replicate.
FCC equipment authorization requirements govern radio-frequency transmission in wireless surveillance deployments, while NDAA Section 889 procurement prohibitions restrict federal and federally funded installations to approved component supply chains. NHTSA guidelines increasingly influence traffic monitoring camera specifications at state department of transportation levels. Stakeholders must monitor evolving Commerce Department entity list designations and state-level procurement mandates that progressively constrain vendor eligibility for public sector contracts.
Market Dynamics
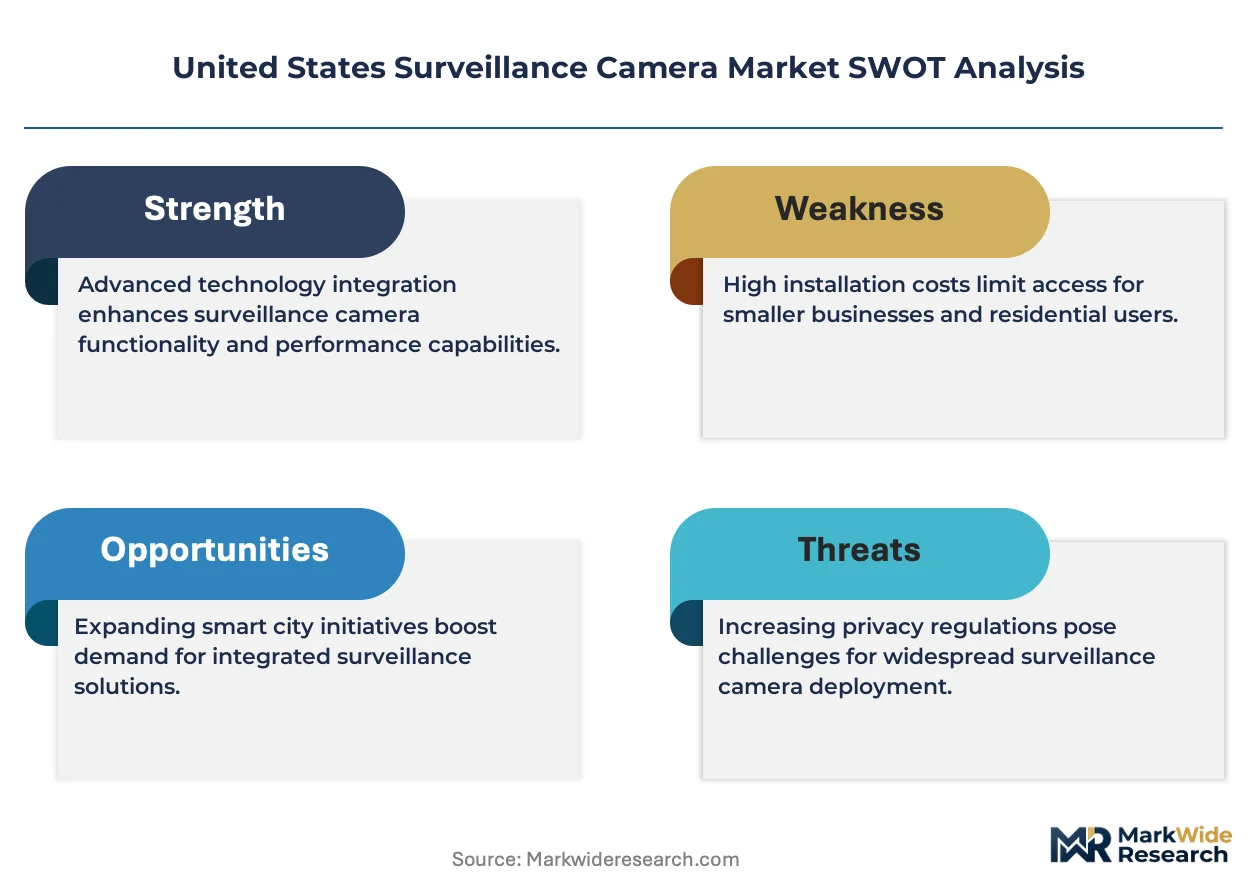
NDAA Section 889 procurement prohibitions are restructuring vendor eligibility for federal and federally funded surveillance camera deployments, forcing rapid supply chain reconfiguration toward compliant component sources.
Growth Catalysts
- Federal infrastructure mandates:The Infrastructure Investment and Jobs Act channels funding toward critical facility hardening, with state transportation departments upgrading traffic monitoring networks.
- Smart city acceleration:Municipal governments across Texas and California corridors are deploying integrated video-analytics platforms for public safety and operational efficiency.
- Cloud-managed platforms:IP-based video surveillance with remote management capabilities is capturing expanding share from analog infrastructure in retail and hospitality verticals.
Market Restraints
- Semiconductor supply concentration:Image sensor fabrication capacity concentrates in East Asian foundries, creating vulnerability for NDAA-compliant sourcing requirements.
- FCC equipment authorization friction:Radio-frequency certification timelines for wireless surveillance devices extend deployment schedules for municipal buyers.
- Technical performance ceilings:Thermal imaging resolution limitations below 640x512 pixels constrain evidentiary utility in perimeter defense applications.
Strategic Opportunities
- Edge AI convergence:On-camera analytics combining computer vision with low-latency processing is opening new service revenue streams for integrators.
- Critical infrastructure underpenetration:Energy sector facilities across the Gulf Coast and Midwest remain below 40% video coverage density versus commercial benchmarks.
- State procurement mandate expansion:Florida and Arizona are extending NDAA-aligned vendor restrictions to state-funded projects beyond federal requirements.
Industry Challenges
- Cybersecurity certification complexity:NIST SP 800-53 compliance for federal deployments demands specialized engineering resources scarce among regional integrators.
- Legacy analog integration friction:Hybrid system architectures combining existing coaxial infrastructure with IP backbones inflate commissioning timelines and total cost of ownership.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Surveillance Camera Market |
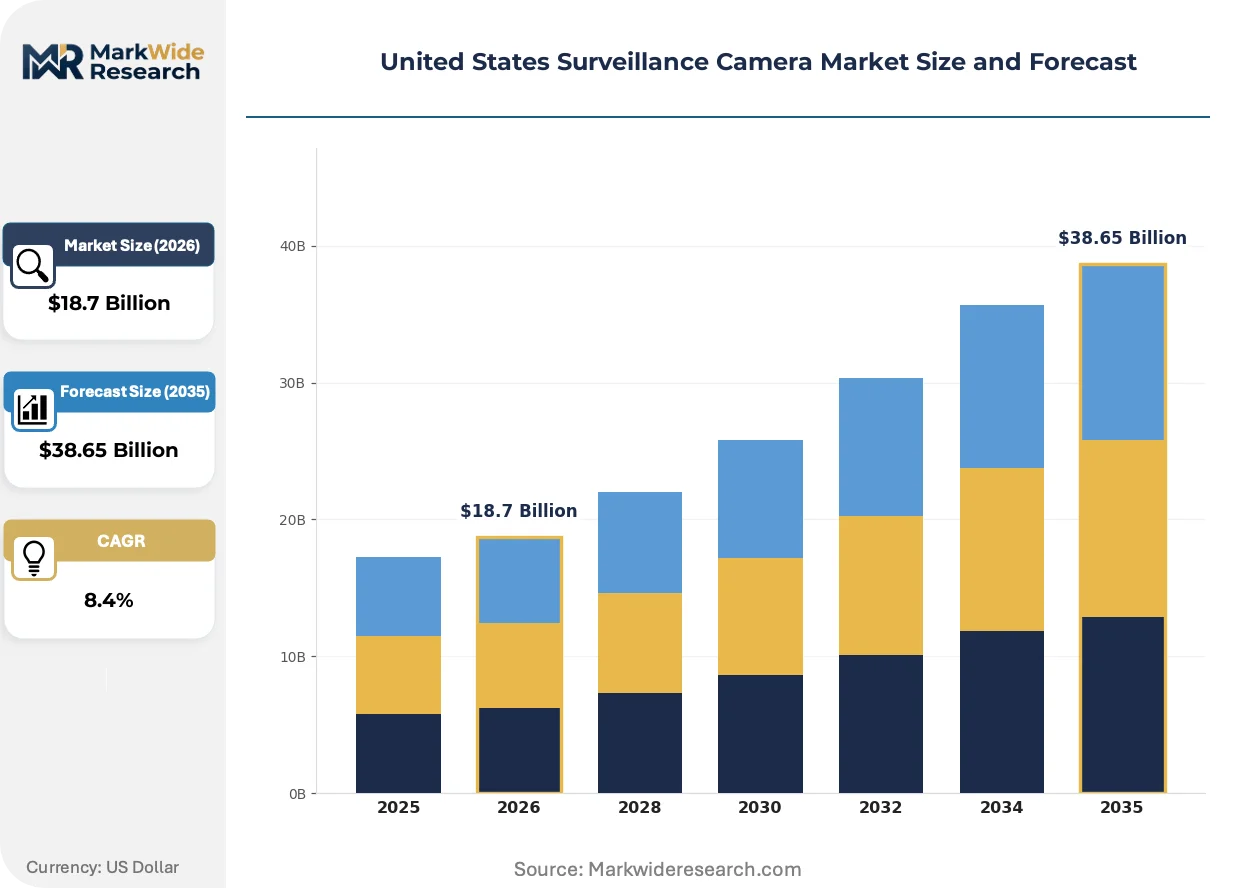
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome, Bullet, PTZ, C-Mount Technology: Analog, IP, Thermal, HD-SDI Installation Type: Indoor, Outdoor, Covert, Fixed End User: Retail, Transportation, Government, Healthcare |
| Companies Covered | Axis Communications AB, Hanwha Vision America, Bosch Sicherheitssysteme GmbH, Avigilon Corporation, Pelco, Motorola Solutions, Teledyne FLIR, Vivotek Inc., Honeywell International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Surveillance Camera Market Trends and Innovations
Video surveillance architecture is splitting between centralized cloud platforms and distributed edge processing, with procurement patterns diverging sharply across federal, municipal, and commercial buyer segments.
Multi-sensor cameras is bifurcating the hardware landscape by combining visible-light and thermal channels in unified housings. Critical infrastructure operators are deploying these units at perimeter checkpoints previously requiring separate devices. The technology is bifurcating vendor R&D budgets between single-sensor commoditization and integrated-platform premium positioning.
FCC equipment authorization requirements for wireless transmission are tightening field-deployment protocols for municipal video networks. The industrial consequence is extended pre-procurement testing cycles and third-party laboratory certification costs. State departments of transportation in California and Texas are responding by consolidating wireless camera purchases under master service agreements with pre-certified vendors.
Subscription-based video-analytics licensing is displacing perpetual software ownership in municipal and enterprise accounts. Systems integrators are unbundling hardware from recurring analytics services, compressing upfront capital requirements while extending customer lifetime value. This shift is most visible among K-12 school districts and mid-market retail chains seeking operational expenditure predictability.
United States Surveillance Camera Market Segmentation
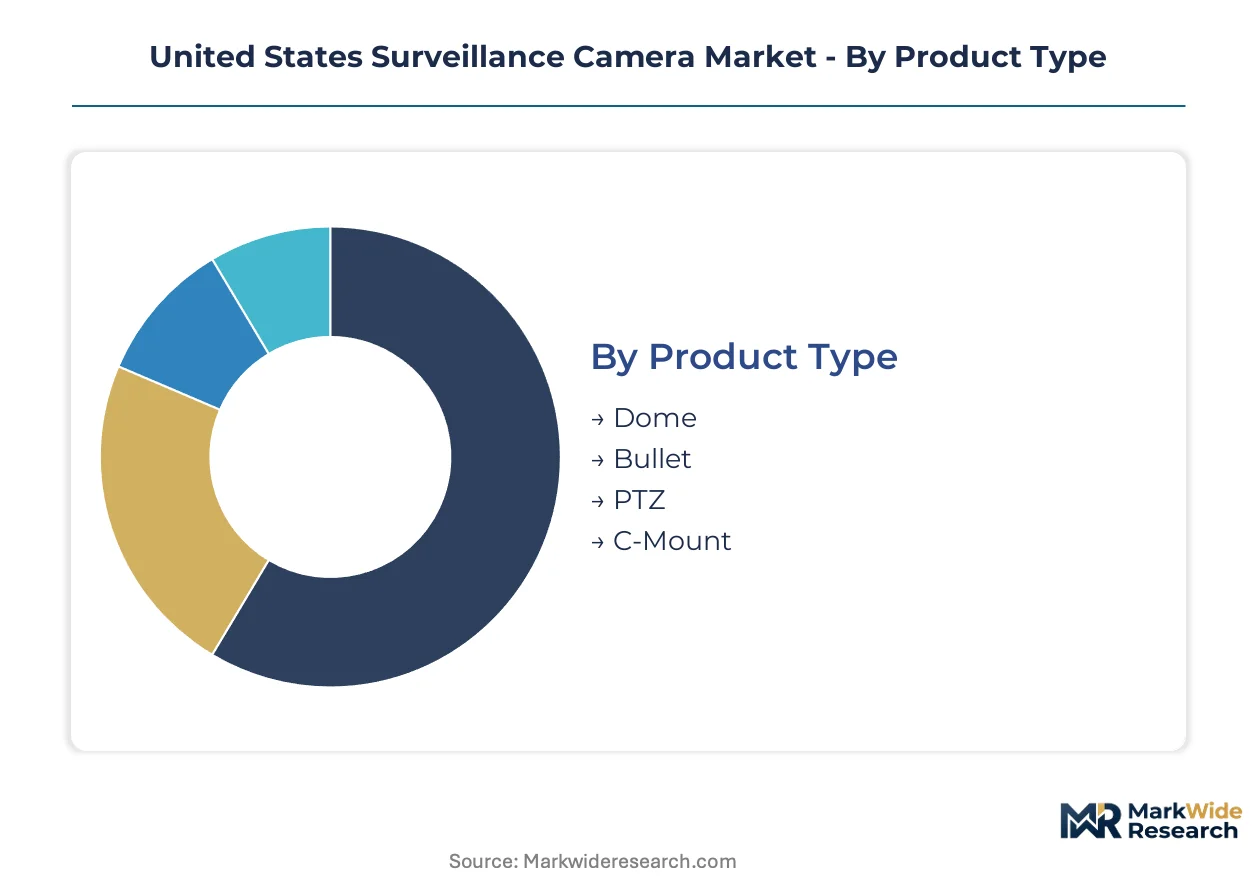
Surveillance camera procurement patterns diverge sharply across federal, municipal, and commercial channels in the United States. Understanding these segment boundaries clarifies where NDAA compliance requirements apply and where cloud-managed platforms are displacing legacy infrastructure.
Product Type:
Domestic manufacturing concentration varies by housing design, with vandal-resistant enclosures commanding premium positioning in federally funded deployments.
- Dome:Vandal-resistant housings with discreet positioning dominate retail and hospitality settings. Demand concentrates across California and Texas municipal corridors where smart city budgets prioritize unobtrusive public space coverage.
- Bullet:Weather-sealed cylindrical housings with exposed lens positioning excel in perimeter defense applications. Gulf Coast energy facilities and Midwest critical infrastructure operators favor these units for long-range visible-light capture in harsh environments.
- PTZ:Motorized pan-tilt-zoom mechanisms enable operator-directed surveillance across wide areas.
- C-Mount:Interchangeable lens systems serve specialized industrial inspection and scientific imaging applications.
Dome cameras hold the largest share; momentum sits with PTZ units in transportation verticals.
Technology:
Cost tier separation between legacy infrastructure and connected platforms determines procurement eligibility for federal versus commercial buyers.
- IP:Network-based transmission with Power-over-Ethernet connectivity enables cloud-managed analytics and remote firmware updates. State transportation departments in Texas and California are consolidating purchases under master service agreements with pre-certified vendors.
- Thermal:Uncooled microbolometer sensors detect infrared radiation for perimeter defense in zero-visibility conditions. Border security installations and Gulf Coast petrochemical facilities drive demand where conventional imaging fails.
- Analog:Coaxial-based CVBS transmission persists in legacy retail and small commercial retrofits.
- HD-SDI:High-definition serial digital interface bridges coaxial infrastructure with uncompressed video quality.
IP systems command the value pool; thermal technology is gaining share fastest in critical infrastructure.
Installation Type:
Application environment dictates environmental sealing ratings, mounting hardware specifications, and FCC authorization requirements for wireless variants.
- Outdoor:IP66/IP67-rated enclosures with integrated heaters and sun shields withstand temperature extremes and precipitation. Federal infrastructure projects and state DOT traffic monitoring networks specify these units exclusively.
- Indoor:Lightweight housings optimized for climate-controlled environments dominate commercial and healthcare settings. K-12 school districts and mid-market retail chains favor these for operational expenditure predictability in subscription-based models.
- Covert:Disguised or miniature form factors serve law enforcement and sensitive facility applications.
- Fixed:Static-position units without motorized adjustment serve cost-constrained deployments.
Outdoor installations generate the highest unit values; indoor deployments are expanding most quickly through cloud-managed platform adoption.
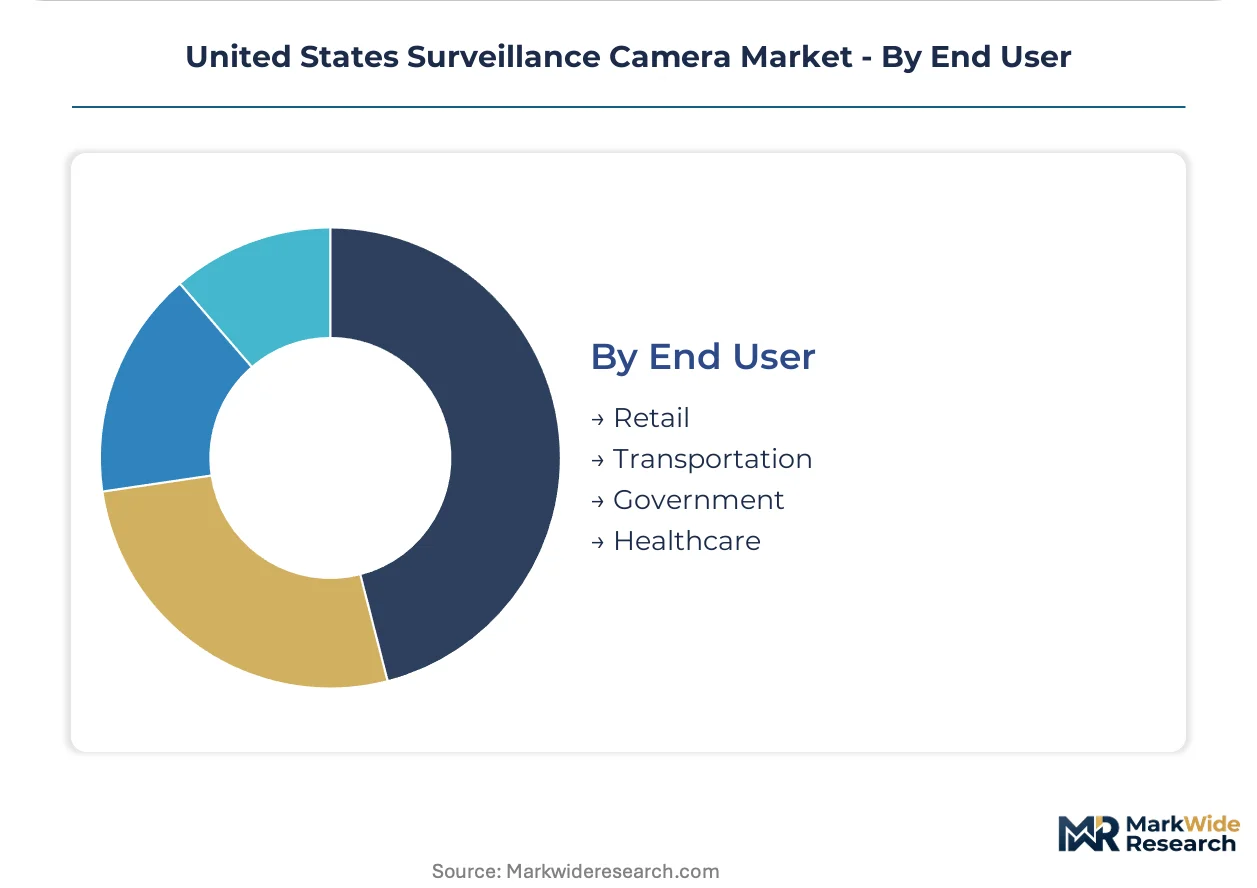
End User:
Customer type determines procurement protocol complexity, with federal and state mandates creating vendor eligibility tiers unavailable to commercial buyers.
- Government:Federal agencies and state entities operate under NDAA Section 889 prohibitions restricting component sourcing to approved supply chains. The Infrastructure Investment and Jobs Act channels funding toward critical facility hardening with compliant hardware mandates.
- Transportation:State departments of transportation specify NHTSA-influenced guidelines for traffic monitoring camera networks. California and Texas DOTs are upgrading video analytics capabilities for incident detection and congestion management.
- Retail:Loss prevention and operational monitoring drive deployment across brick-and-mortar chains.
- Healthcare:HIPAA-compliant video systems serve patient safety and facility security applications.
Government verticals enforce the strictest compliance standards; transportation represents the steepest expansion trajectory through federal infrastructure funding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surveillance camera trade flows from South Korean and Taiwanese component fabricators into United States federal procurement channels. California and Texas municipal corridors absorb the highest installation volumes. NDAA compliance requirements reshape sourcing geography across domestic assembly operations.
California
Smart city budgets in Los Angeles and San Francisco prioritize cloud-managed video analytics for public safety. State transportation departments specify NHTSA-influenced guidelines for traffic monitoring networks. The Silicon Valley corridor concentrates edge-AI camera development laboratories serving municipal pilot programs.
Texas
Gulf Coast energy facilities drive thermal imaging demand for perimeter defense in petrochemical zones. State DOT contracts consolidate under master service agreements with pre-certified vendors. The Dallas-Fort Worth metroplex anchors regional distribution for NDAA-compliant hardware serving federal infrastructure projects.
Florida
K-12 school districts adopt subscription-based analytics licensing for operational expenditure predictability. State procurement mandates extend NDAA-aligned vendor restrictions to state-funded projects. The Miami-Dade corridor concentrates hospitality-sector dome camera deployments for loss prevention.
Arizona
Border security installations require thermal technology where conventional imaging fails in desert conditions. State-level critical facility upgrades channel Infrastructure Investment and Jobs Act funding toward compliant hardware. The Phoenix metro serves as a logistics hub for Southwest regional integrators.
New York
Healthcare facilities deploy HIPAA-compliant video systems for patient safety applications. Metropolitan transportation authorities upgrade legacy analog infrastructure with IP-based platforms. The New York City metro absorbs high volumes of indoor installations through cloud-managed service contracts.
United States Surveillance Camera Market Competitive Landscape
Player mix skews toward diversified security conglomerates with command-center software ecosystems. Market structure concentrates around vendors with federal procurement eligibility and domestic manufacturing footprints. Three archetypes dominate: American-assembled hardware specialists, European building-system integrators, and diversified public-safety technology conglomerates. Competitive moves center on supply chain reconfiguration for NDAA compliance and cloud platform unbundling to capture recurring revenue.
Within the American manufacturing tier, Hanwha Vision America and Motorola Solutions exemplify divergent positioning strategies. Hanwha Vision America leverages its domestic assembly footprint to satisfy federal sourcing requirements under Section 889 prohibitions. Motorola Solutions anchors the public safety vertical through command-center software integration rather than hardware differentiation alone. Bosch Sicherheitssysteme GmbH occupies a position bridging European engineering heritage with building management system integration. These three represent how vendor eligibility tiers separate federal-contract winners from commercial-market competitors.
| Leading Market Players |
|---|
| Axis Communications AB |
| Hanwha Vision America |
| Bosch Sicherheitssysteme GmbH |
| Avigilon Corporation |
| Pelco |
| Motorola Solutions |
| Teledyne FLIR |
| Vivotek Inc. |
| Honeywell International |
| Others |
Pricing and Supply Chain Analysis
Ninety-day lead times for NDAA-compliant image sensors concentrate pricing power with domestic assemblers serving federal procurement channels. Component scarcity at compliant foundries compresses margins for mid-tier vendors while premium-positioned players capture attach-rate gains through bundled analytics licensing.
Pricing Analysis
IP-to-analog pricing gaps of three-to-one separate connected platforms from legacy coaxial infrastructure, with thermal-visible multi-sensor units commanding additional premiums above single-channel alternatives. Three-tier pricing structure across federal-certified, enterprise-grade, and commercial-economy levels tracks certification depth and software attach rates. Cost compression in the commercial tier intensifies because cloud-managed platforms displace capital-heavy perpetual licenses. State transportation departments exhibit lowest price sensitivity due to master service agreement consolidation, while K-12 districts face acute budget constraints favoring subscription predictability.
Supply Chain Analysis
Strategic stockpiling of uncooled microbolometer sensors characterizes thermal camera vendors responding to Taiwan and South Korea fabrication bottlenecks. Image sensor supply draws from Taiwanese foundries, South Korean memory fabricators, and domestic packaging operations for NDAA-eligible final assembly. Single-source vulnerability concentrates in advanced CMOS fabrication below 28 nanometers. Distribution runs through regional integrators serving municipal corridors in Texas and California, with direct OEM relationships dominating federal infrastructure awards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering talent scarcity for NIST SP 800-53 cybersecurity compliance separates contract winners from disqualification in federal surveillance deployments. This capability gap widens as state-level mandates proliferate beyond federal minimums.
For Market Incumbents: Compound federal eligibility advantages by deepening domestic assembly footprints and pre-certifying wireless variants under streamlined FCC equipment authorization. Threat substitution from emerging edge-AI chip vendors demands captive silicon sourcing or strategic foundry partnerships. Certification investment in state-level procurement mandates beyond Section 889 minimums anchors channel control against mid-tier challengers. For New Entrants and Emerging Players: Differentiate on thermal-analytics bundling for Gulf Coast energy facilities where perimeter defense specifications outrun incumbent software roadmaps. White-space concentrates in Midwest critical infrastructure below forty percent video coverage density. Channel partnership with regional integrators holding existing state DOT master service agreements accelerates procurement access without direct certification burden. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-premium play because regulatory layering creates durable vendor eligibility moats with recurring software attach rates. Acquisition targets cluster around edge-AI software specialists with federal deployment experience and thermal imaging engineering teams. Signal to watch: Florida and Arizona state mandate expansion velocity as predictor of national procurement standard convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Footprint Expansion | NDAA Section 889 compliance unlocks federal infrastructure funding pools. |
| Cloud Platform Integration | Recurring analytics licensing displaces perpetual ownership in municipal accounts. |
| Edge AI Chip Partnership | On-camera processing capability differentiates against centralized alternatives. |
| Master Service Agreement Consolidation | Pre-certified vendor status accelerates state transportation department procurement cycles. |
| Thermal-Visible Multi-Sensor Development | Unified perimeter devices capture premium positioning in critical infrastructure verticals. |
Research Methodology
Desk research of FCC equipment authorization databases, NDAA compliance certification registries, and state procurement records preceded structured interviews with municipal IT directors, critical infrastructure security officers, and systems integration firm executives. Secondary validation drew from Infrastructure Investment and Jobs Act funding disclosures, NHTSA traffic monitoring specifications, and Commerce Department entity list designations. Bottom-up installation volume estimates triangulated against top-down federal budget appropriation analysis.
Variance decomposition across technology generation, end-user compliance tier, and regional procurement maturity shaped projection outputs over the analysis window. Segmentation dimensions modeled include product housing type, transmission architecture, environmental sealing rating, and customer procurement protocol complexity. CAGRs derived from segment-level growth rate reconciliation against aggregate market boundary conditions. Forecast inputs incorporated federal infrastructure appropriation trajectories and state-level mandate adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained federal funding authorization or accelerated state mandate harmonization would require recalibration. Forecasts reflect documented assumptions regarding compliant component supply elasticity and municipal cloud platform adoption velocity. Revision becomes warranted when semiconductor fabrication capacity reallocation crosses thresholds enabling non-compliant vendor re-entry.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Mini Security Camera Market
Video Surveillance Systems
Homeland Security Surveillance Camera Market
Video Surveillance Systems
United Kingdom Surveillance Camera Market
Video Surveillance Systems
Japan Surveillance Analog Camera Market
Video Surveillance Systems
AI Surveillance System Market
Video Surveillance Systems
Smart Home Security Camera Market
Video Surveillance Systems
Global Mobile Video Surveillance Market
Video Surveillance Systems
Home Security Camera Market
Video Surveillance Systems
United States Surveillance Storage Market
Video Surveillance Systems
India Video Surveillance Market
Video Surveillance Systems
US Video Surveillance Market
Video Surveillance Systems
Japan Surveillance Camera Market
Video Surveillance Systems
Security Camera Software Market
Video Surveillance Systems
Canada Video Surveillance Market
Video Surveillance Systems
Smart Outdoor Cameras Market
Video Surveillance Systems
United Arab Emirates Surveillance Camera Market