
 India Used Car Market | 2026-2036
India Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
India Used Car Market Outlook
The premium certified pre-owned segment is repositioning away from unorganized roadside dealers through 150-plus point inspection protocols and warranty-backed sales. Cars24 leverages its proprietary auction-to-retail pipeline to control vehicle sourcing costs across 200 Indian cities. Spinny sustains a capital-intensive inventory-owning model that removes seller-buyer friction but demands heavy warehousing. CarDekho anchors its used car vertical within a broader automotive content ecosystem, capturing intent upstream of purchase decisions.
India used cars comprise pre-owned passenger vehicles that have completed at least one registration cycle, typically evaluated through odometer readings, service history verification, and structural damage assessment before resale. These vehicles serve cost-conscious consumers seeking depreciation-optimized mobility without factory-new price premiums. SUVs and hatchbacks dominate transaction volumes, with SUVs commanding stronger residual values due to India's deteriorating urban road conditions and rural buyer preference for ground clearance. Electric used cars remain nascent but represent an emerging structural pocket as early EV adopters cycle into second-generation models. First-time buyers absorb the largest share of organized channel growth, drawn by standardized financing from NBFCs allied with platforms.
BIS emission norms and state-level RTO documentation requirements under the Motor Vehicles Act shape vehicle eligibility for interstate resale and financing access. The RBI's regulatory oversight of NBFC lending practices directly determines down-payment thresholds and interest rate spreads for used car loans. Stakeholders must monitor how FASTag integration and pending vehicle scrappage policy implementation alter fleet turnover velocity and supply-side inventory quality.
Market Dynamics
Digital auction-to-retail pipelines are compressing vehicle sourcing cycles from weeks to days, forcing traditional dealer networks to adopt platform-mediated inventory acquisition or face margin erosion from price-transparent transactions.
Growth Catalysts
- NBFC financing standardization:RBI-regulated non-banking financial companies have reduced down-payment thresholds for organized channel buyers, expanding credit access to first-time purchasers in Tier-2 cities.
- VAHAN database digitization:The centralized RTO platform under India's Motor Vehicles Act enables real-time ownership verification and interstate transfer clearance, reducing transaction friction.
- SUV residual value premiums:Deteriorating urban road infrastructure and rural ground-clearance requirements sustain stronger resale pricing for utility vehicles versus sedans.
Market Restraints
- Input cost volatility:Spare parts pricing for imported components fluctuates with rupee-dollar exchange rates, compressing refurbishment margins for organized dealers.
- Supply concentration risk:Maharashtra, Karnataka and Gujarat account for disproportionate organized inventory flows, leaving other states dependent on fragmented roadside sourcing.
- BIS emission norm friction:Interstate resale eligibility varies by state-level pollution under control certificate validity, creating documentation bottlenecks for cross-border transactions.
Strategic Opportunities
- Electric vehicle secondary market:Early EV adopters cycling into second-generation models will release certified battery health data, enabling platform-guaranteed resale pricing.
- PLI scheme alignment:India's production-linked incentive framework for automotive components reduces domestic refurbishment input costs versus imported alternatives.
- FASTag integration:Toll-transponder data streams enable odometer fraud detection and actual usage verification, strengthening buyer trust metrics.
Industry Challenges
- Certified inspection talent scarcity:150-point mechanical assessment protocols require trained technicians capable of structural damage detection, a skill pool concentrated in metro service centers.
- Warehousing capex intensity:Inventory-owning models demand capital deployment for vehicle holding facilities, creating working capital pressure during demand troughs.
- Legacy RTO interface fragmentation:State-level motor vehicle department software varies in API compatibility, forcing platforms to maintain multiple integration stacks for document processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Used Car Market |
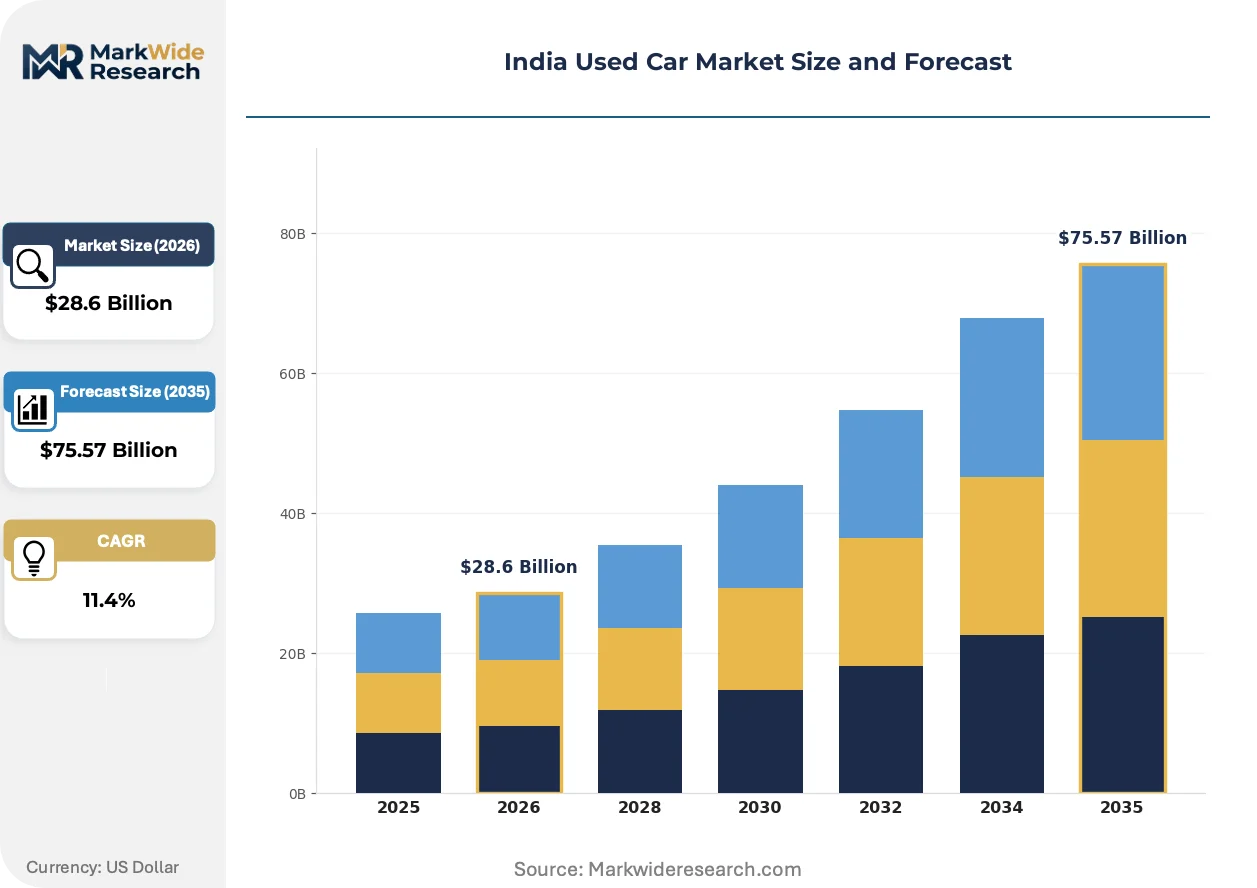
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Coupe Fuel Type: Petrol, Diesel, CNG, Electric Customer Segment: First-Time Buyers, Families, Commuters, Enthusiasts Age Group: 18-25, 26-35, 36-50, 51+ |
| Companies Covered | Cars24, Droom, CarDekho, CarTrade, CredR, CarWale, Spinny, Maruti Suzuki True Value, OLX India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Used Car Market Strategic Shifts
Artificial intelligence-driven pricing engines are compressing valuation spreads between buyer bids and seller asks, eliminating information asymmetry that historically sustained dealer arbitrage margins.
Computer vision damage assessment is overtaking manual inspection protocols at platform intake centers. The technology captures panel-level defects through standardized imaging bays, enabling algorithmic repair cost estimation. Tier-2 city first-time buyers adopt these machine-certified vehicles at accelerating rates, compressing trust-building timelines from weeks to hours.
India's pending vehicle scrappage policy under the Ministry of Road Transport and Highways will mandate fitness certification renewal cycles. Commercial fleet operators face accelerated replacement timelines, flooding organized channels with younger, lower-mileage inventory. Financing penetration deepens fastest in Gujarat and Tamil Nadu where state RTOs have pre-integrated fitness data with NBFC underwriting systems.
Subscription-to-ownership conversion models are fragmenting traditional purchase pathways. Urban millennials in Bengaluru and Hyderabad lease certified pre-owned vehicles through platform-managed monthly plans before exercising buyout options. This behavior compresses the average holding period per unit, increasing inventory velocity for warehouse-operating dealers.
India Used Car Market Segmentation
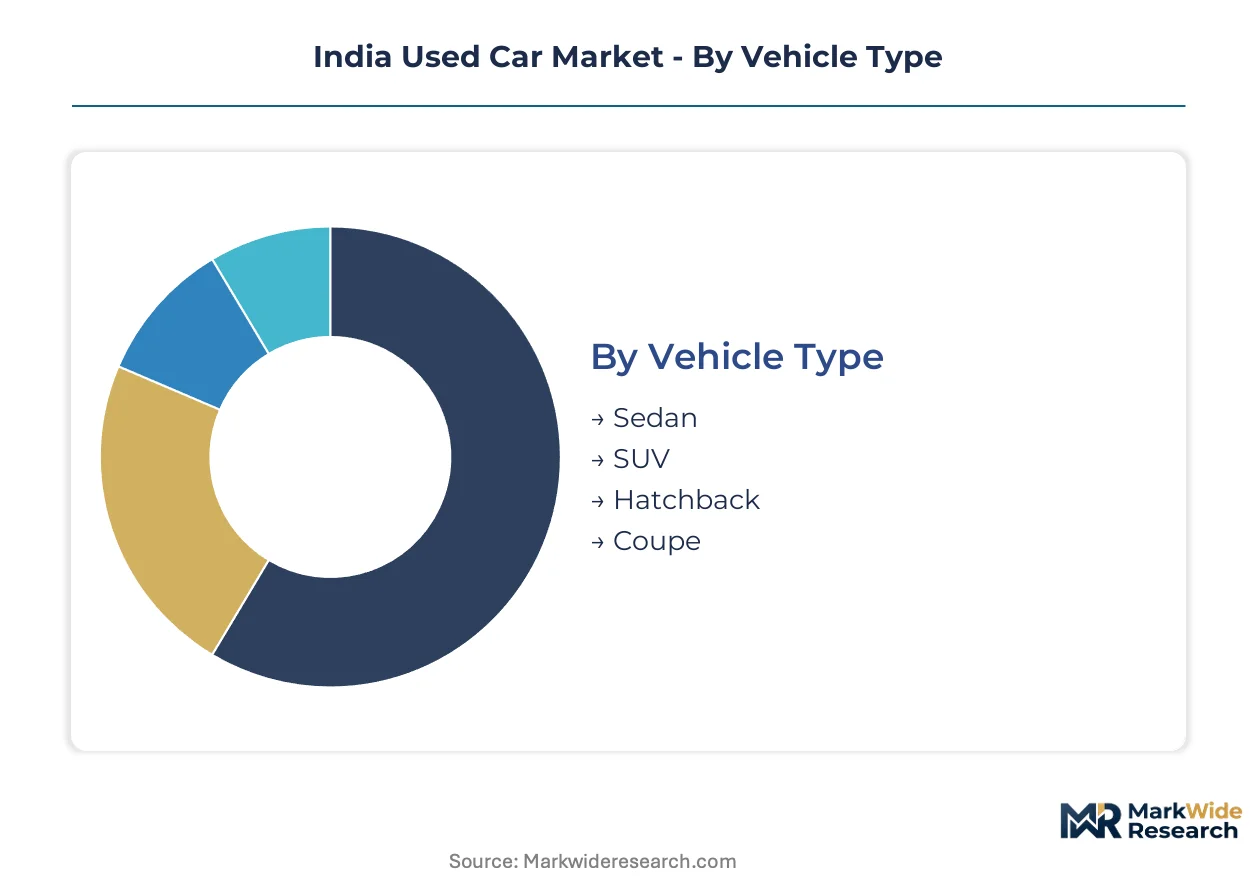
Segmentation in India's used car market reveals how supply-side inventory concentration shapes platform strategies and buyer targeting. Organized dealers calibrate procurement and refurbishment investments around vehicle type and fuel category preferences that vary sharply across Maharashtra, Karnataka, and Gujarat.
Vehicle Type:
Supply concentration in organized dealer networks favors utility vehicles and compact formats that command faster inventory turns and stronger residual values.
- SUV:High ground clearance specifications address deteriorating urban road infrastructure across Bengaluru, Mumbai, and Pune. Rural buyers in Gujarat and Maharashtra absorb the largest volume, driving platforms to prioritize SUV sourcing at auction pipelines.
- Hatchback:Compact dimensions and fuel efficiency specifications dominate Tier-2 city first-time buyer demand. Karnataka and Tamil Nadu organized channels concentrate hatchback refurbishment capacity due to lower per-unit capex requirements and faster turnover velocity.
- Sedan:Three-box configurations retain preference among commuter segments seeking cabin comfort for highway usage. Organized inventory flows concentrate in metro corporate resale channels.
- Coupe:Two-door sport formats represent a niche enthusiast segment with limited organized channel penetration. Supply depends heavily on individual owner listings rather than fleet or corporate releases.
SUV absorbs the bulk of installed refurbishment capacity; Hatchback is expanding most quickly among Tier-2 first-time buyers.
Fuel Type:
Cost tier differentiation separates petrol dominance from emerging electric infrastructure dependencies that reshape platform warranty and certification protocols.
- Petrol:Widest service network coverage and lower maintenance complexity sustain petrol's position across all customer segments. Organized dealers in Maharashtra and Gujarat maintain deepest petrol inventory due to RTO documentation standardization under VAHAN.
- Diesel:Torque specifications and highway efficiency attract commercial fleet replacement supply entering organized channels. Karnataka's logistics corridor concentration generates disproportionate diesel inventory flows.
- CNG:Factory-fitted CNG kits command price premiums in Delhi-NCR and Mumbai metropolitan regions where pump infrastructure density supports daily operational economics.
- Electric:Battery health certification protocols remain under development as early adopter supply enters secondary markets. Gujarat's charging infrastructure lead positions Ahmedabad and Surat as initial electric used car liquidity centers.
Petrol commands the largest share of transaction volume; Electric is climbing the fastest as battery data standardization enables platform-guaranteed pricing.
Customer Segment:
Application-driven segmentation aligns financing product design with distinct purchase journey friction points across buyer maturity levels.
- First-Time Buyers:RBI-regulated NBFC partnerships reduce down-payment thresholds for this credit-thin segment. Tier-2 city expansion in Rajasthan and Madhya Pradesh concentrates first-time buyer growth.
- Families:Multi-generational usage requirements prioritize safety feature verification and spacious cabin configurations. Organized 150-point inspection protocols address family segment trust barriers most directly.
- Commuters:High-mileage durability requirements and fuel cost sensitivity define this segment's platform engagement patterns. Subscription-to-ownership conversion models gain traction among urban commuter cohorts.
- Enthusiasts:Performance specification verification and modification history documentation require specialized assessment talent concentrated in metro service centers.
First-Time Buyers absorb the bulk of organized channel marketing investment; Families are gaining share fastest as certified pre-owned trust metrics mature.
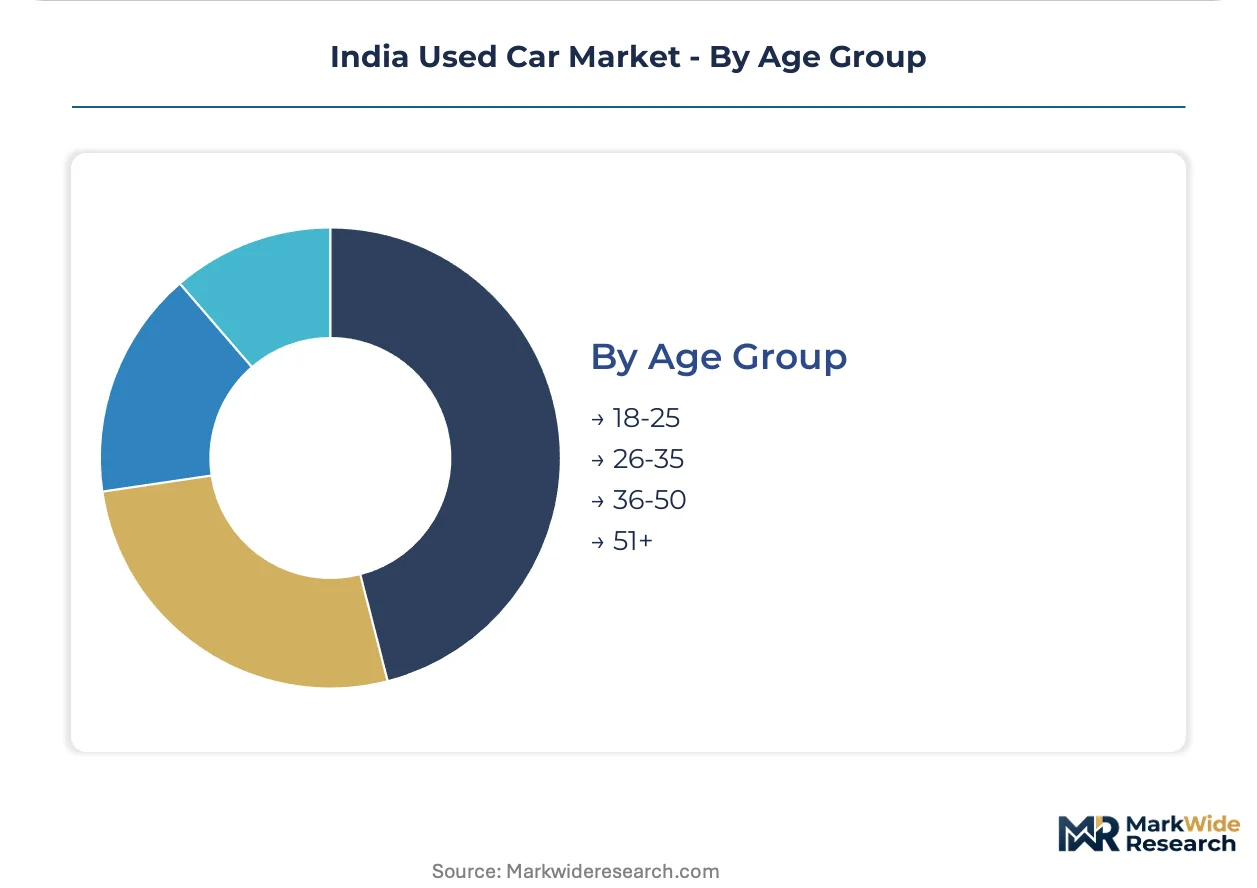
Age Group:
Customer maturity correlates with financing access, digital platform comfort, and willingness to absorb information asymmetry in unorganized sourcing.
- 26-35:Digital-native behavior and stable employment documentation optimize this cohort for platform-mediated transactions with standardized NBFC underwriting. Bengaluru and Hyderabad millennial concentration drives organized channel adoption.
- 36-50:Family formation stage elevates vehicle size requirements and safety feature prioritization. This segment displays highest subscription-to-ownership conversion rates in platform-managed programs.
- 18-25:Credit history limitations and budget constraints push this cohort toward older inventory segments with higher unorganized channel dependency.
- 51+:Brand loyalty persistence and service relationship continuity sustain preference for authorized dealer networks over pure-play digital platforms.
26-35 represents the deepest organized channel penetration; 36-50 is expanding most quickly as family-stage buyers migrate from new car to certified pre-owned consideration sets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai anchors India's organized used car infrastructure through its dense network of certified refurbishment centers and NBFC financing partnerships that funnel inventory into Maharashtra's consumer base.
Maharashtra
Mumbai and Pune concentrate the deepest organized dealer penetration, with SUV demand driven by deteriorating urban road conditions. The state's RTO digitization under the VAHAN database enables real-time ownership verification, reducing interstate transfer friction. Organized platforms operate auction-to-retail pipelines across the Mumbai-Pune industrial corridor, compressing vehicle sourcing cycles from weeks to days.
Gujarat
Ahmedabad and Surat generate disproportionate financing penetration due to pre-integrated fitness data sharing between state RTOs and NBFC underwriting systems. The RBI's regulatory oversight of non-banking financial companies has reduced down-payment thresholds here faster than national averages. Surat's logistics hub concentration releases commercial fleet inventory into organized channels at accelerated rates.
Karnataka
Bengaluru's millennial concentration drives subscription-to-ownership conversion models, with platform-managed monthly plans compressing average holding periods per unit. The state's logistics corridor generates diesel-heavy inventory flows from commercial fleet replacements. Karnataka's organized channels concentrate hatchback refurbishment capacity due to lower per-unit capex requirements and faster turnover velocity.
Tamil Nadu
Chennai's manufacturing ecosystem feeds organized channels with corporate resale inventory from automotive sector employees. State-level RTO pre-integration with NBFC systems deepens financing penetration comparable to Gujarat. The Chennai-Bengaluru highway corridor sustains commuter segment demand for sedan configurations with verified highway durability.
Delhi-NCR
The National Capital Region absorbs factory-fitted CNG kit premiums due to pump infrastructure density supporting daily operational economics. BIS emission norms create documentation bottlenecks for cross-border transactions into neighboring states. Gurugram's corporate resale channels release younger, lower-mileage inventory from technology sector fleet operators.
India Used Car Market Competitive Environment
Capital-heavy inventory owners compete with asset-light marketplace operators for transaction volume and customer acquisition efficiency. The vendor base clusters around three strategic archetypes: full-stack platforms controlling sourcing-to-delivery pipelines, pure-play aggregators monetizing lead generation, and OEM-backed certified programs leveraging brand trust. Consolidation pressure intensifies as digital price transparency erodes traditional dealer arbitrage margins. Dominant competitive moves include backward integration into auction sourcing and strategic partnerships with NBFCs for embedded financing.
Within the full-stack platform tier, Cars24 exemplifies the auction-to-retail pipeline archetype through its proprietary sourcing infrastructure spanning 200 Indian cities. Spinny occupies a position representing the capital-intensive inventory-owning model that removes seller-buyer friction but demands heavy warehousing deployment. CarDekho anchors the automotive content ecosystem archetype, capturing purchase intent upstream of transaction decisions through its integrated media-to-marketplace funnel.
| Leading Market Players |
|---|
| Cars24 |
| Droom |
| CarDekho |
| CarTrade |
| CredR |
| CarWale |
| Spinny |
| Maruti Suzuki True Value |
| OLX India |
| Others |
Value Chain & Pricing Dynamics
Certified inspection technician concentration in Maharashtra and Karnataka creates labor-cost differentials that widen pricing-tier spreads between metro-organized and Tier-2 unorganized channels. RBI-regulated NBFC financing standardization compresses these spreads for credit-qualified buyers, while roadside dealers absorb residual price-sensitive demand through unverified inventory.
Pricing Analysis
Residual value-based pricing anchors organized channel transactions, with SUV ground-clearance premiums and hatchback fuel-efficiency metrics determining tier placement. Certification grade from 150-point inspection protocols and VAHAN-verified ownership history drive price differentiation between warranty-backed and as-is inventory. Pricing pressure intensifies in the unorganized tier as digital auction transparency erodes traditional dealer arbitrage. First-time buyers in Tier-2 cities exhibit highest price sensitivity, while family segments absorb certified pre-owned premiums for safety-verified configurations.
Supply Chain Analysis
Reverse-logistics flows from commercial fleet operators and corporate resale channels feed organized refurbishment pipelines with younger, lower-mileage inventory. Supply concentrates in Maharashtra, Karnataka, and Gujarat where RTO digitization under VAHAN enables interstate transfer clearance. The pipeline draws from auction sourcing, OEM trade-ins, and lease returns, with imported component dependencies for spare parts creating rupee-dollar exposure. Single-source vulnerability in certified inspection talent pools threatens refurbishment throughput. Distribution runs through platform-managed warehousing for inventory-owning models and marketplace-mediated handoffs for asset-light operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
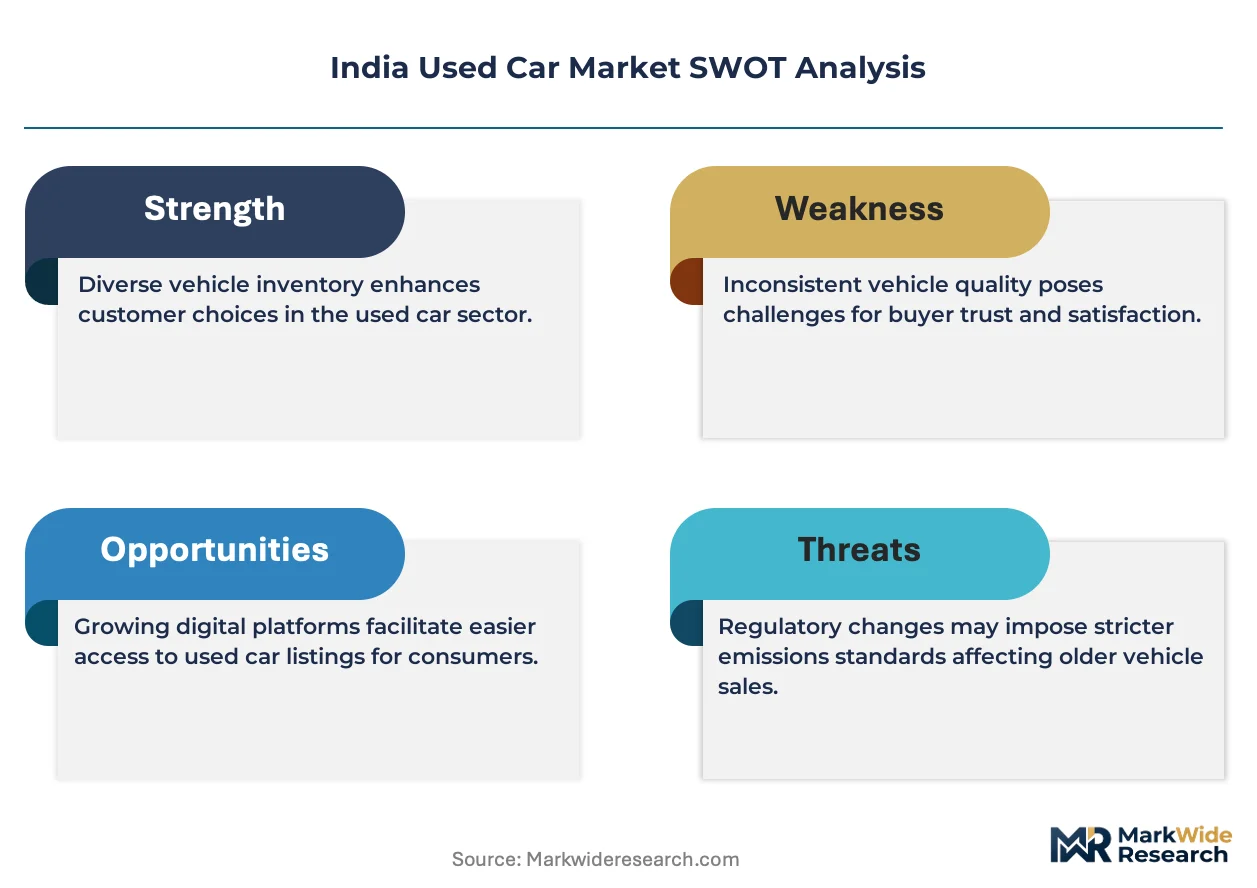
BIS emission norm compliance and VAHAN database integration under the Motor Vehicles Act create a cost-of-compliance moat that favors organized platforms with dedicated regulatory affairs capacity over fragmented roadside operators.
For Market Incumbents: Deepen backward integration into auction sourcing infrastructure to control vehicle acquisition costs against emerging pure-play aggregators. Expand certified inspection training programs in Tier-2 cities to address technician scarcity threatening refurbishment throughput. Prioritize API development for state-level RTO software fragmentation to accelerate document processing velocity. For New Entrants and Emerging Players: The mid-tier price-point gap between Spinny's capital-intensive certified inventory and OLX's unmediated peer-to-peer listings offers white-space entry for hybrid marketplace models. Rajasthan and Madhya Pradesh present penetrable geographies with rising first-time buyer demand and limited organized dealer presence. A subscription-to-ownership conversion angle targeting urban millennials in Hyderabad and Bengaluru enables asset-light customer acquisition. For Investors and Strategic Acquirers: The window for entry favors platforms with proprietary battery health certification capabilities as electric used car liquidity emerges. Long-term viability hinges on RTO digitization pre-integration and NBFC underwriting partnerships. Monitor Gujarat and Tamil Nadu's fitness data sharing protocols as inflection indicators for financing penetration scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Auction Pipeline Development | Cars24's sourcing infrastructure across 200 cities compresses acquisition cycles from weeks to days. |
| NBFC Embedded Financing Partnership | RBI-regulated partnerships reduce down-payment thresholds for Tier-2 first-time buyer expansion. |
| Computer Vision Inspection Deployment | Algorithmic damage assessment at platform intake centers eliminates manual inspection bottlenecks. |
| State RTO API Pre-Integration | VAHAN database connectivity enables real-time ownership verification and interstate transfer clearance. |
| Electric Vehicle Certification Protocol | Battery health data standardization positions platforms for early adopter secondary market liquidity. |
Study Parameters
Company filings, RTO digitization progress reports, and NBFC lending disclosures formed the secondary backbone, cross-referenced with primary interviews spanning platform operations executives, certified refurbishment center managers, NBFC underwriting leads, and state motor vehicle department officials. Bottom-up vehicle transaction volume estimates triangulated against top-down organized channel revenue assessments derived from financing penetration data.
Bottom-up modeling aggregated segment-level transaction flows across vehicle type, fuel category, and customer archetype dimensions, while top-down analysis calibrated aggregate market expansion against macroeconomic mobility demand indicators. CAGRs were derived from regression-weighted historical velocity patterns applied across the projection horizon. Forecast inputs incorporated PLI scheme automotive component incentives and pending vehicle scrappage policy implementation timelines.
Inputs from platform transaction databases and RTO VAHAN integration status reports were available through the study window; gaps in real-time Tier-2 unorganized channel activity introduce uncertainty bands around first-time buyer penetration estimates. Forecasts reflect documented assumptions regarding NBFC regulatory stability and state-level digitization rollout velocity. Practitioners should monitor FASTag odometer verification deployment and battery health data standardization protocols for early signals of trust metric evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Oman Used Car Market
Used Vehicles
Russia Used Car Market
Used Vehicles
United States Used Car Market
Used Vehicles
South Korea Used Car Market
Used Vehicles
GCC Used Car Market
Used Vehicles
Philippines Used Car Market
Used Vehicles
China Used Car Market
Used Vehicles
Kenya Used Car Market
Used Vehicles
Saudi Arabia Used Car Market
Used Vehicles
Indonesia Used Car Financing Market
Used Vehicles
Australia Used Car Market
Used Vehicles
France Used Car Market
Used Vehicles
Malaysia Used Car Market
Used Vehicles
Qatar Used Car Market
Used Vehicles
Global Online Second-Hand Car Trading Service Market
Used Vehicles
Thailand Used Car Market