
 Used E-Scooter Market | 2026-2036
Used E-Scooter Market Size, Share, and Industry Trends Forecast 2026-2036
Used E-Scooter Market Analytics
Buyer concentration is realigning as urban delivery fleets and university procurement offices consolidate purchasing power away from individual consumers. Xiaomi Corporation leverages its original equipment ecosystem to dominate refurbishment quality benchmarks. Apollo Scooters differentiates through high-performance component recovery for premium resale tiers. Voro Motors controls regional distribution density in North American secondary channels.
A used e-scooter is a previously operated personal electric mobility device with a rechargeable battery system, typically retaining 60-80% of original lithium-ion capacity after initial commercial deployment, repurposed for cost-sensitive urban transit applications. Folding e-scooters and commuter e-scooters anchor volume flows from decommissioned shared fleets into individual ownership channels. Off-road e-scooters occupy a thinner but higher-margin resale niche driven by aftermarket modification demand. Lead-acid battery variants face structural decline as lithium-ion replacement economics improve across all usage scenarios.
The EPA governs battery disposal and recycling standards that constrain refurbishment economics, while the FCC regulates integrated connectivity modules in connected fleet units, and California Air Resources Board zero-emission incentives shape regional resale premiums through subsidy transferability rules. Stakeholders must monitor how evolving state-level right-to-repair legislation affects access to proprietary diagnostic tools and spare parts networks.
Market Dynamics
Shared fleet decommissioning pipelines from Bird and Lime are flooding secondary channels with lithium-ion units, compressing refurbishment margins while expanding affordable access for individual buyers and small fleet operators.
Growth Catalysts
- California CARB Incentives:Zero-emission vehicle subsidy transferability rules create resale premiums for certified refurbished units, accelerating individual adoption in Los Angeles and San Francisco metro corridors.
- Fleet Circular Economy Mandates:European corporate sustainability reporting obligations under CSRD pressure shared-mobility operators to document end-of-life asset recovery, guaranteeing supply flow into refurbishment networks.
- Lithium-Ion Battery Diagnostics:Portable capacity testing equipment enables street-level verification of remaining charge cycles, reducing information asymmetry between sellers and buyers in peer-to-peer transactions.
Market Restraints
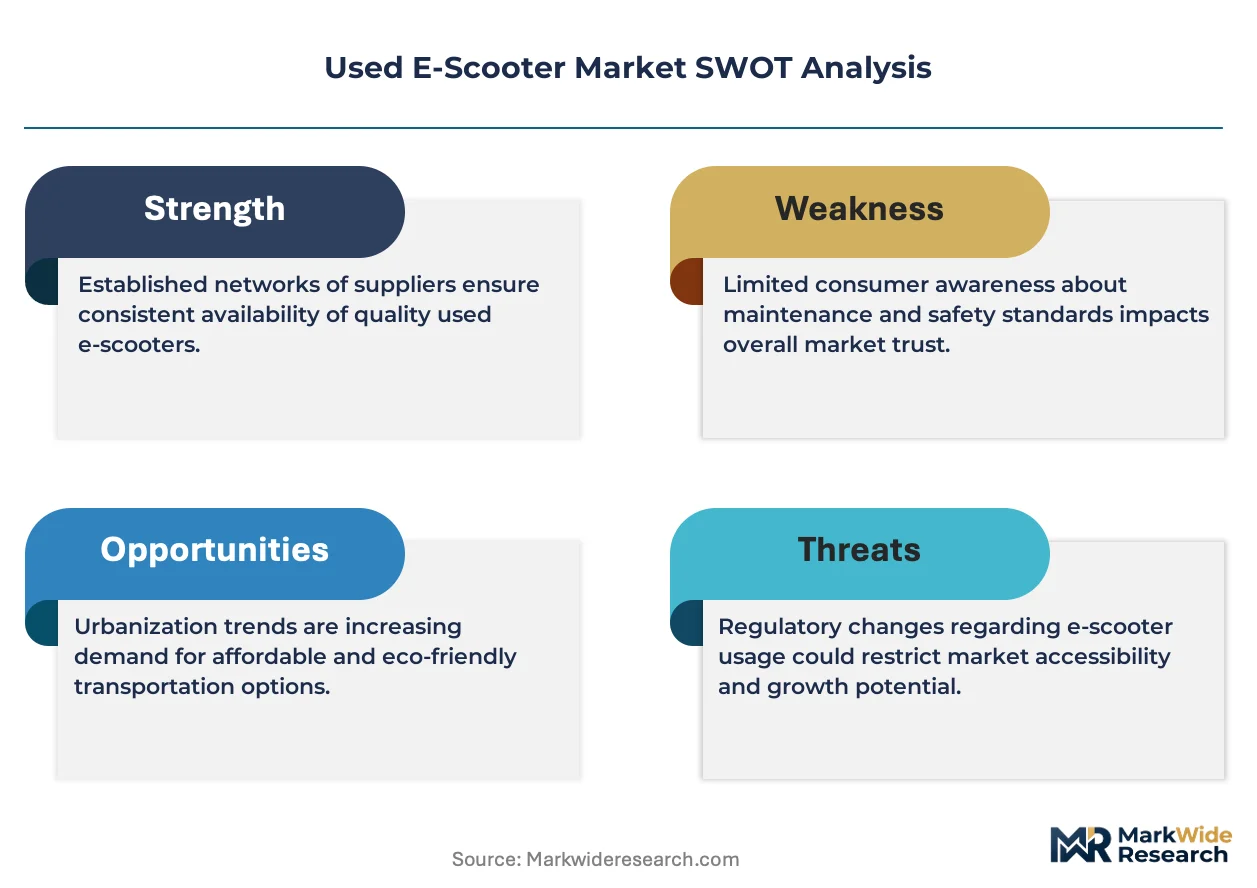
- EPA Hazardous Waste Classification:Damaged or degraded battery packs trigger costly disposal protocols under RCRA subtitle C, eroding economics for units below 50% residual capacity thresholds.
- Controller Firmware Lockouts:Manufacturer-specific encryption on motor control boards restricts third-party refurbishment, concentrating repair capability within authorized service networks.
- Lead-Acid Stranded Assets:Early-generation rental fleets with sealed lead-acid batteries face accelerated obsolescence as lithium replacement costs fall below refurbishment viability.
Strategic Opportunities
- German Municipal Tender Residuals:Berlin and Hamburg shared-scooter contract expirations generate predictable decommissioning waves, enabling forward procurement agreements with Tier-1 refurbishers.
- University Fleet-as-a-Service:Campus mobility offices in Texas and Florida are piloting semester-length subscriptions for certified pre-owned units, replacing capital purchases with operating leases.
- Right-to-Repair Legislation:Pending state bills in New York and Minnesota mandate diagnostic tool access, opening proprietary repair ecosystems to independent refurbishment shops.
Industry Challenges
- Battery Certification Backlogs:UL 2272 recertification queues stretch 8-12 weeks at accredited labs, delaying inventory turnover and freezing working capital in warehoused units.
- Cross-Border Compliance Fragmentation:Divergent state-level e-mobility equipment standards create SKU proliferation, forcing refurbishers to maintain jurisdiction-specific component inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Used E-Scooter Market |
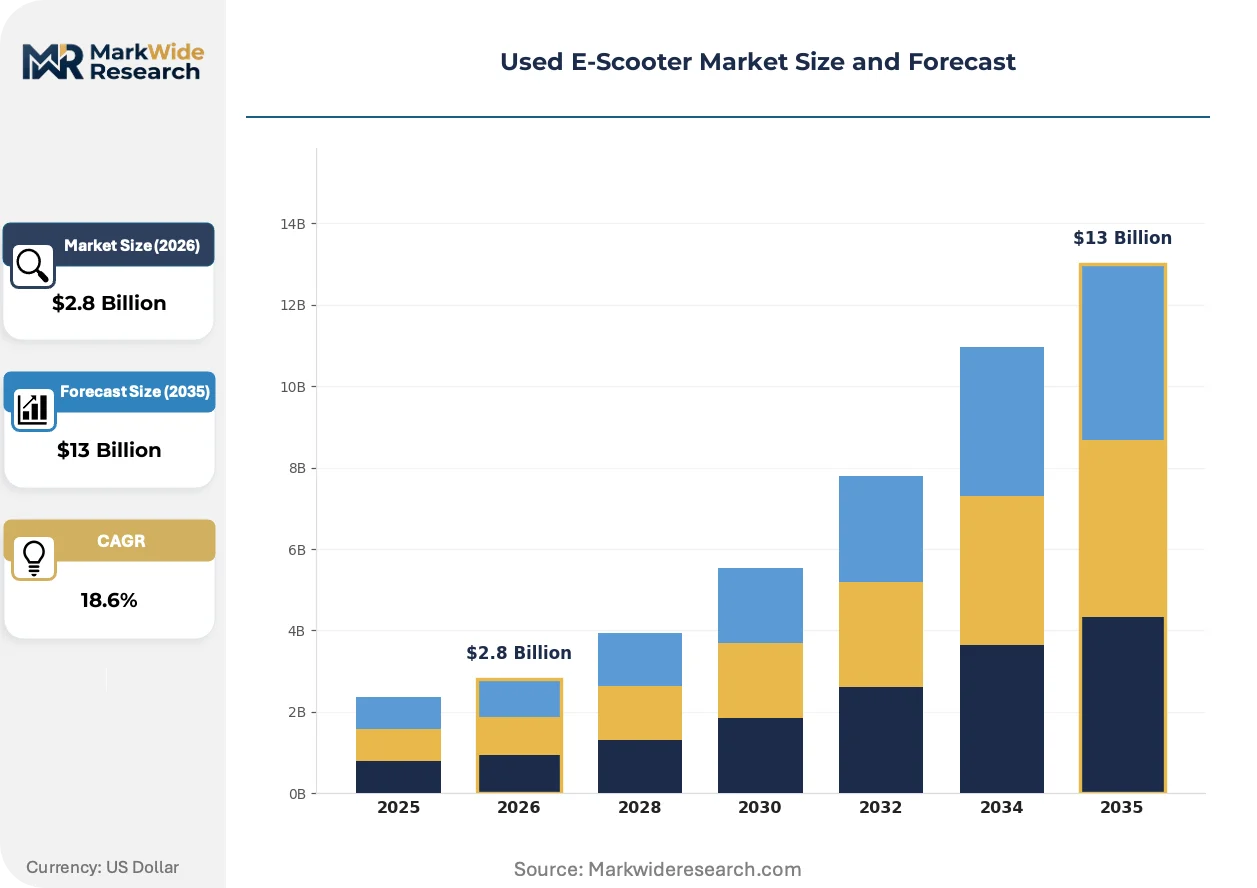
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding E-Scooter, Stand-Up E-Scooter, Off-Road E-Scooter, Commuter E-Scooter Battery Type: Lithium-Ion, Lead-Acid, Nickel-Metal Hydride, Polymer Weight Capacity: 100 kg, 120 kg, 150 kg, 200 kg Usage Scenario: Urban Commuting, Leisure Activities, Delivery Services, College Transport |
| Companies Covered | Razor, Apollo Scooters, Xiaomi Corporation, Bird, GOTRAX, INOKIM, Voro Motors, Hover, KAABO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Used E-Scooter Market Evolving Landscape
Modular battery architecture and open-source diagnostic platforms are dismantling manufacturer-controlled repair monopolies, enabling independent operators to compete on refurbishment quality and warranty terms.
Swappable battery systems originally deployed in Gogoro and Niu fleets are expanding into the used channel, allowing buyers to lease power packs separately from chassis acquisition and decouple range anxiety from vehicle depreciation curves. Food delivery cooperatives in Taipei and Mexico City are adopting this split-asset model fastest, converting capex-light scooter purchases into opex-flexible fleet operations. The technology is expanding into North American and European secondary markets through grey-import networks and licensed refurbishment partnerships.
REACH substance restrictions on nickel-manganese-cobalt cathode chemistries are forcing European refurbishers to document supply chain provenance and battery composition down to the cell level, triggering investments in X-ray fluorescence testing equipment. Compliance costs are compressing margins for small operators while creating accreditation barriers that favor scaled players with laboratory partnerships. German and Dutch resale platforms now display battery chemistry certificates as primary filtering criteria, reshaping buyer search behavior and price discovery mechanisms.
Subscription-based ownership models are displacing outright purchase in urban consumer segments, with refurbished units bundled into monthly mobility packages alongside maintenance and insurance. Paris and Madrid operators pioneered this structure for shared fleets, and the approach is migrating into individual ownership through fintech-integrated resale platforms. California buyers under thirty show highest receptivity, treating scooters as utility subscriptions rather than depreciating assets.
Used E-Scooter Market Segmentation
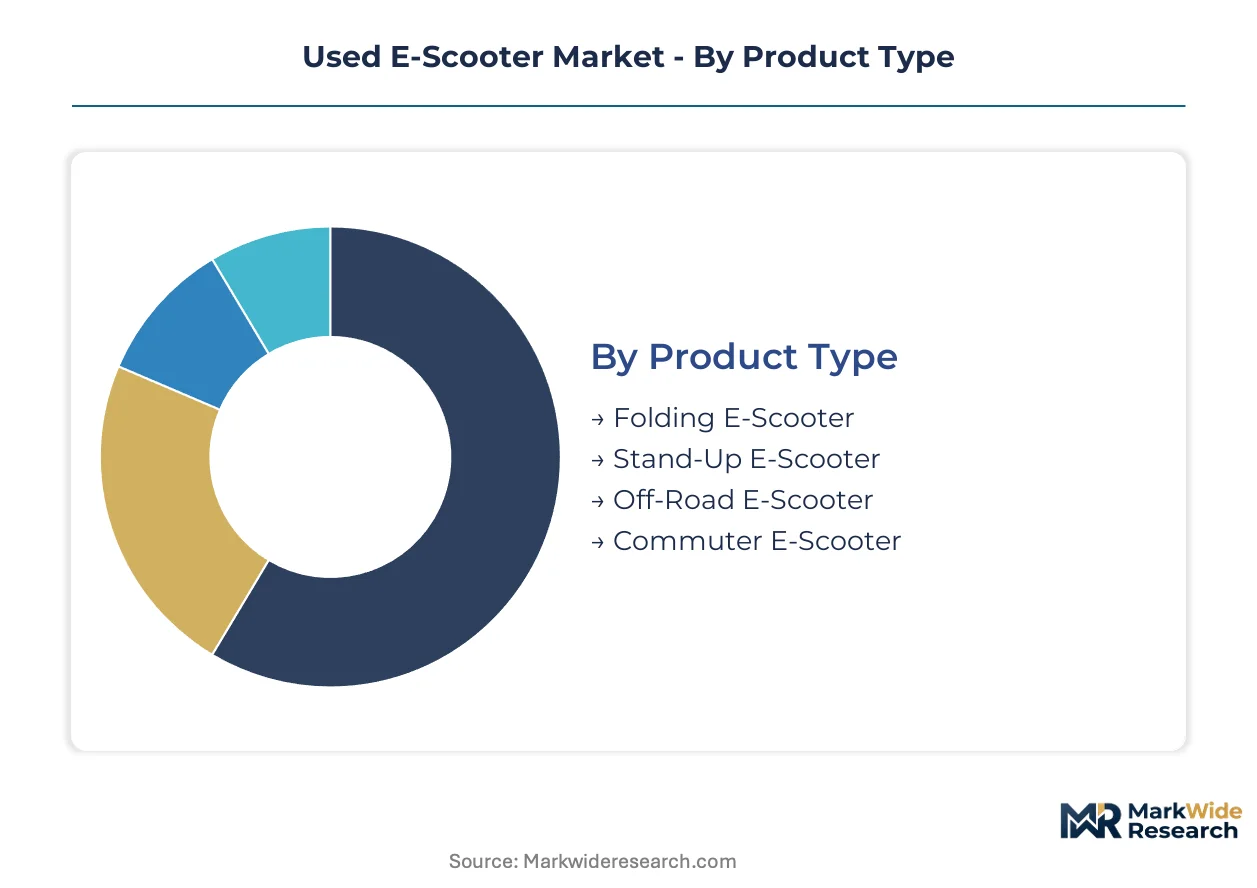
Segmentation in the used e-scooter market determines refurbishment economics, warranty viability, and resale channel selection. Battery chemistry and frame architecture create divergent value retention curves that reshape procurement strategies across fleet operators and individual buyers.
Product Type:
Standardization dominates folding and commuter variants, while off-road models command customization premiums through aftermarket component swaps.
- Folding E-Scooter:Collapsible frame designs with hinge-lock mechanisms enable compact storage in multi-modal transit environments. Demand concentrates in Berlin and Hamburg where decommissioned shared fleet units feed dense secondary networks constrained by apartment storage limits.
- Commuter E-Scooter:Rigid-frame builds prioritize battery range and deck stability over portability, typically retaining 70-80% of original capacity post-fleet deployment. University procurement offices in Texas and Florida are consolidating purchasing power toward certified pre-owned commuter units with semester-length lease structures.
- Stand-Up E-Scooter:Minimalist platforms without folding hardware reduce mechanical failure points and simplify refurbishment workflows.
- Off-Road E-Scooter:Reinforced suspension and pneumatic tire systems support terrain versatility, attracting aftermarket modification demand in higher-margin resale niches.
Leading the category by volume: Commuter E-Scooter. Expanding most quickly: Off-Road E-Scooter.
Battery Type:
Cost tiers separate lithium-ion dominance from stranded lead-acid assets facing accelerated obsolescence.
- Lithium-Ion:Nickel-manganese-cobalt and lithium-iron-phosphate chemistries deliver 500-1000 charge cycles with 60-80% residual capacity in decommissioned fleet units. REACH substance restrictions force European refurbishers to document cell-level provenance through X-ray fluorescence testing, compressing margins for small operators while favoring scaled players with laboratory partnerships.
- Lead-Acid:Sealed lead-acid packs in early-generation rental fleets face structural decline as lithium replacement costs fall below refurbishment viability thresholds, triggering costly EPA hazardous waste disposal protocols under RCRA subtitle C.
- Nickel-Metal Hydride:Transitional chemistry retains niche presence in legacy Asian import units with moderate cycle life degradation.
- Polymer:Lithium-polymer variants enable flexible form factors in compact folding designs with higher energy density trade-offs.
Dominating procurement economics: Lithium-Ion. Facing steepest volume contraction: Lead-Acid.
Weight Capacity:
Application requirements drive specification clustering around rider demographics and cargo loads.
- 100 kg:Entry-tier frames target individual urban commuters with minimal payload requirements, anchoring volume flows from decommissioned shared fleets into individual ownership channels.
- 120 kg:Mid-range reinforcement supports average adult riders with occasional cargo, forming the procurement sweet spot for university fleet-as-a-service pilots.
- 150 kg:Heavy-duty construction accommodates food delivery cooperatives in Taipei and Mexico City adopting swappable battery split-asset models.
- 200 kg:Commercial-grade platforms enable dual-rider configurations and substantial cargo hauling in last-mile logistics applications.
Procurement concentrates at: 120 kg. Gaining share fastest: 150 kg.
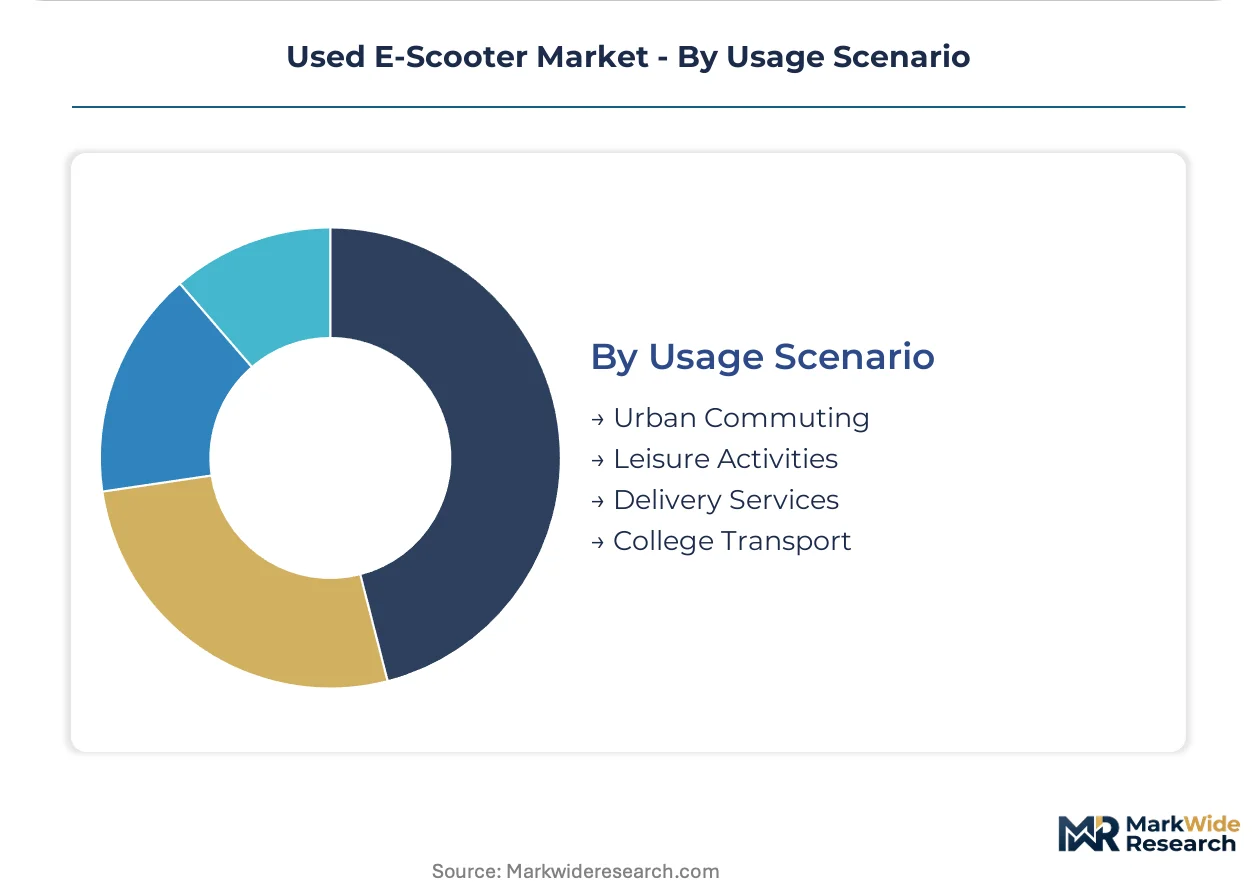
Usage Scenario:
Customer type separates institutional fleet demand from individual mobility subscriptions.
- Urban Commuting:Daily transit replacement applications prioritize reliability certifications and warranty transferability, with California CARB zero-emission incentives creating resale premiums for certified refurbished units in Los Angeles and San Francisco metro corridors.
- Delivery Services:High-utilization fleet operations demand modular battery architectures and open-source diagnostic platforms to dismantle manufacturer-controlled repair monopolies, enabling independent operators to compete on refurbishment quality.
- College Transport:Campus mobility offices pilot semester-length subscriptions converting capital purchases into operating leases with maintenance bundling.
- Leisure Activities:Recreational usage tolerates higher aesthetic wear and shorter remaining cycle life, supporting lower price-point market tiers.
Volume leadership: Urban Commuting. Steepest expansion trajectory: Delivery Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Used e-scooter demand concentrates in Germany, the United States, and Taiwan, where municipal fleet turnover, state-level subsidy programs, and delivery cooperative adoption create distinct procurement environments across three continents.
Germany
Berlin and Hamburg municipal shared-scooter decommissioning feeds dense secondary networks with predictable supply waves. The KBA enforces battery certification standards that tighten resale quality thresholds, forcing refurbishers to maintain laboratory partnerships. Bavaria-based refurbishment clusters now display REACH-compliant battery chemistry certificates as primary filtering criteria on resale platforms.
United States
California CARB zero-emission incentives create resale premiums for certified refurbished units in Los Angeles and San Francisco metro corridors. The EPA governs hazardous waste classification under RCRA subtitle C, triggering costly disposal protocols for degraded battery packs. Texas and Florida university procurement offices pilot semester-length subscriptions converting capital purchases into operating leases.
Taiwan
Food delivery cooperatives in Taipei adopt swappable battery split-asset models fastest, converting capex-light scooter purchases into opex-flexible fleet operations. The national standards bureau regulates integrated connectivity modules in connected fleet units. Kaohsiung refurbishment hubs now license Gogoro-compatible diagnostic platforms to independent operators.
France
Paris subscription-based ownership models displace outright purchase in urban consumer segments, with refurbished units bundled into monthly mobility packages. ANSM monitors aftermarket modification safety for off-road variants. Lyon and Marseille resale platforms integrate fintech-integrated payment structures for buyers under thirty treating scooters as utility subscriptions.
Netherlands
Amsterdam and Rotterdam circular economy mandates under CSRD pressure shared-mobility operators to document end-of-life asset recovery. ECHA REACH substance restrictions force refurbishers to document supply chain provenance down to the cell level. Eindhoven-based testing equipment suppliers now serve scaled players with X-ray fluorescence partnerships.
Used E-Scooter Market Competitive Landscape
Chinese producers anchor one tier; North American specialists hold refurbishment quality differentiation in another. The vendor base fragments across original equipment ecosystems, regional distribution networks, and independent service channels. Three strategic archetypes dominate: OEM-integrated refurbishers, third-party quality certifiers, and fleet-decommissioning aggregators. Competitive moves concentrate on strategic partnerships with municipal tender residuals and technology licensing for diagnostic platform access.
Within the OEM-integrated tier, Xiaomi Corporation and Bird exemplify contrasting approaches to secondary market positioning. Apollo Scooters occupies a position among performance-focused specialists. Voro Motors anchors regional distribution density in North American secondary channels. These three represent how geographic origin and founding business model shape competitive archetype selection.
| Leading Market Players |
|---|
| Razor |
| Apollo Scooters |
| Xiaomi Corporation |
| Bird |
| GOTRAX |
| INOKIM |
| Voro Motors |
| Hover |
| KAABO |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up refurbishment specialists in North America and Europe are consolidating decommissioned fleet pipelines, converting fragmented municipal tender residuals into scaled inventory pools that discipline pricing through volume certainty. This ownership pattern tightens working capital cycles while compressing margins for independent operators lacking forward procurement agreements with Bird or Lime.
Pricing Analysis
Volume flows concentrate in economy-tier folding units from shared fleet decommissioning, while margin capture clusters in premium commuter segments with UL 2272 recertification and warranty transferability. Three-tier pricing structure across premium, standard, and economy levels separates certified pre-owned units with diagnostic reports from as-is peer-to-peer sales. Cost compression in economy tiers is intensifying because lithium-ion battery replacement economics now fall below refurbishment viability for lead-acid stranded assets. University procurement offices show lowest price sensitivity due to semester-length subscription bundling, whereas individual urban commuters exhibit highest sensitivity to upfront chassis acquisition costs.
Supply Chain Analysis
Technician shortages in Shenzhen, Dongguan, and Hamburg refurbishment hubs are extending UL 2272 recertification queues and freezing working capital in warehoused inventory. Geographic supply concentration centers on China for lithium-ion cell sourcing, Germany for diagnostic equipment manufacturing, and Taiwan for Gogoro-compatible controller modules. Raw material dependencies draw from nickel-manganese-cobalt cathode chemistries, aluminum frame extrusions, and semiconductor motor control boards. Single-source vulnerability in proprietary firmware encryption creates repair capability concentration within authorized service networks. Distribution runs through regional refurbishment clusters in California, Texas, and Florida feeding university fleet-as-a-service pilots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified refurbishment capacity is the binding constraint propping pricing premiums, as UL 2272 recertification backlogs stretch 8-12 weeks and accredited laboratory partnerships remain scarce outside scaled players.
For Market Incumbents: Deploy forward procurement agreements with municipal tender residuals to lock decommissioning supply waves from Berlin and Hamburg. Secure exclusive diagnostic platform licensing from Gogoro or Niu before right-to-repair legislation opens proprietary ecosystems to independent shops. Battery certification backlogs threaten inventory turnover velocity for operators lacking laboratory partnerships. For New Entrants and Emerging Players: Food delivery cooperatives in Taipei and Mexico City represent the most penetrable buyer archetype, with swappable battery split-asset models converting capex-light purchases into opex-flexible subscriptions. Target grey-import licensing partnerships for Gogoro-compatible refurbishment hubs in North American secondary channels. White-space exists in off-road aftermarket modification services where customization premiums exceed standard refurbishment margins. For Investors and Strategic Acquirers: Distressed-cycle entries favor scaled refurbishers with laboratory partnerships in Germany and California, where REACH compliance costs and CARB incentive transferability rules create accreditation barriers. Long-term viability hinges on subscription-based ownership model adoption among buyers under thirty treating mobility as utility rather than asset ownership. Watch for right-to-repair bill passage in New York and Minnesota as inflection signal opening proprietary repair ecosystems.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic Platform Licensing | Gogoro-compatible tool access dismantles manufacturer-controlled repair monopolies for independent operators. |
| Battery Chemistry Certification | REACH-compliant X-ray fluorescence testing creates accreditation barriers favoring scaled European refurbishers. |
| Forward Procurement Agreements | Municipal tender residual contracts with Berlin and Hamburg guarantee predictable decommissioning supply waves. |
| Subscription Model Development | Fintech-integrated semester-length leases convert university capital purchases into operating expenditure structures. |
| Swappable Battery Integration | Split-asset deployment in Taipei food delivery cooperatives decouples range anxiety from vehicle depreciation curves. |
Research Methodology
Document review covered EPA RCRA subtitle C guidance, California CARB zero-emission incentive regulations, and ECHA REACH substance restriction filings, complemented by interviews with fleet decommissioning managers at shared-mobility operators, refurbishment shop owners in Hamburg and Los Angeles, university procurement officers in Texas and Florida, and diagnostic equipment suppliers in Eindhoven. Secondary validation drew from customs trade data on lithium-ion cell imports, SEC filings of listed micromobility operators, and municipal tender documentation from Berlin and Hamburg. Bottom-up unit economics modeling triangulated against top-down market sizing across battery chemistry and frame architecture segments.
Installed base projections and residual value curves were generated across the analysis window through segmented cohort modeling of fleet deployment cycles, battery degradation curves, and refurbishment cost structures. Segmentation dimensions included product type, battery chemistry, weight capacity, and usage scenario with regional regulatory cluster overlays. CAGRs were derived from logistic diffusion modeling of subscription adoption rates and replacement cost parity thresholds. Industry-specific inputs incorporated UL 2272 recertification queue durations and CARB subsidy transferability rule changes.
Revisions become necessary when EPA hazardous waste classification thresholds shift, right-to-repair legislation mandates diagnostic tool access, or lithium-ion replacement cost curves fall below remaining lead-acid refurbishment economics. Forecasts reflect assumptions on municipal fleet contract renewal rates and university procurement office subscription receptivity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Canada Used Car Market
Used Vehicles
Philippines Used Car Market
Used Vehicles
Switzerland Used Car Market
Used Vehicles
United Arab Emirates Used Car Market
Used Vehicles
Used Semi Truck Market
Used Vehicles
Kuwait Used Car Market
Used Vehicles
Myanmar Used Car Market
Used Vehicles
China Used Car Market
Used Vehicles
United States Used Car Market
Used Vehicles
France Used Car Market
Used Vehicles
Russia Used Car Market
Used Vehicles
Used Cars Market
Used Vehicles
Bangladesh Used Car Market
Used Vehicles
Oman Used Car Market
Used Vehicles
Belgium Used Car Market
Used Vehicles
Kenya Used Car Market