
 Middle East and Africa Used Car Market | 2026-2036
Middle East and Africa Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Used Car Market Foresight
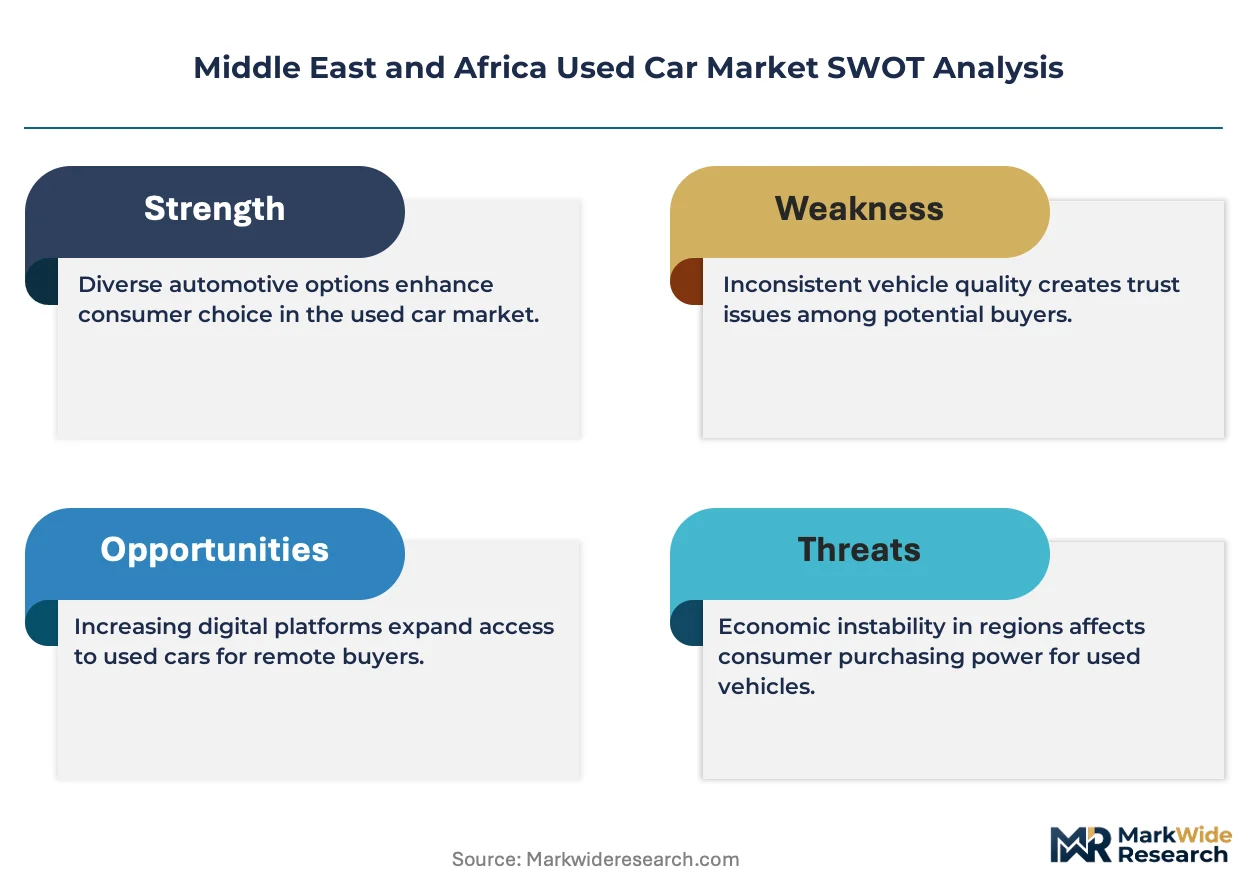
The Middle East and Africa used car trade is recalibrating around a widening split between certified pre-owned vehicles with warranty backing and unverified imports sold through informal channels. Al-Futtaim Automotive leverages its multi-brand dealership network to anchor certified programs across the UAE and Saudi Arabia. Kayishha competes through AI-driven pricing engines that reduce valuation variance for sellers in Riyadh and Jeddah. Dubizzle Motors controls classified liquidity by dominating digital listing volumes in Dubai and Abu Dhabi.
A used car denotes a previously registered automobile transferred through resale, typically evaluated by odometer reading, service history, and structural integrity prior to retransaction. Condition grading determines pricing tiers, with certified pre-owned units commanding premiums due to manufacturer-backed inspections and limited warranty coverage. SUV and sedan segments dominate transaction volumes across the Middle East and Africa, reflecting family-size requirements and fuel accessibility patterns. The 1-3 year age bracket captures the fastest turnover as off-lease vehicles from corporate fleets enter secondary markets with lower depreciation curves.
Saudi Arabia's Ministry of Commerce and SAMR enforce disclosure standards on imported used vehicles, while South Africa's National Consumer Commission applies warranty obligations to dealer sales under the Consumer Protection Act. The UAE's MOHAP-aligned vehicle inspection protocols in Dubai and Abu Dhabi restrict accident-damaged imports from entering certified channels. Stakeholders must monitor how fuel-type regulations and electrification timelines reshape import eligibility criteria for hybrid and battery-electric used units.
Market Dynamics
The Middle East and Africa used car market is restructuring around digital verification infrastructure that separates certified inventory from informal trade. Platform-based pricing algorithms and government-mandated disclosure systems are compressing information asymmetries between sellers and buyers.
Growth Catalysts
- Ride-hailing fleet procurement:Platform operators in Nigeria and Kenya are accelerating second-hand vehicle acquisition to meet driver onboarding targets. Fleet managers prioritize 1-3 year old sedans with documented service histories.
- SAMR disclosure mandates:Saudi Arabia's Ministry of Commerce now requires odometer and accident history documentation for all imported used vehicles. This transparency framework is pulling transactions into formal channels.
- AI-driven valuation engines:Machine learning pricing models are reducing bid-ask spreads in Riyadh and Jeddah auction markets. Sellers receive instant quotes based on condition grading and comparable sales data.
Market Restraints
- Currency volatility in Sub-Saharan markets:Nigerian naira and Kenyan shilling fluctuations are compressing import purchasing power. Fleet operators face working capital strain when sourcing from dollar-denominated GCC suppliers.
- Accident-damaged import concentration:Unverified vehicles from Asian export markets continue entering informal channels in East Africa. Dubai and Abu Dhabi inspection protocols restrict these units from certified pre-owned programs.
- Limited warranty infrastructure:Most transactions lack manufacturer-backed coverage outside UAE and Saudi Arabia dealership networks. Buyer hesitation slows premium segment penetration.
Strategic Opportunities
- Ethiopia's underpenetrated formal market:Addis Ababa's rising middle class lacks organized used car distribution. Digital marketplace entry could capture first-mover advantage before regulatory frameworks mature.
- Hybrid and electric vehicle import eligibility:GCC fuel-type regulations are creating new certification categories for battery-electric and plug-in hybrid used units. Early movers in Dubai can establish inspection expertise.
- Embedded finance integration:Sharia-compliant vehicle financing products are penetrating Saudi Arabia's secondary market. Lenders partnering with digital platforms can expand addressable buyer pools.
Industry Challenges
- Condition assessment standardization:No unified grading protocol exists across Middle East and Africa markets. Cross-border traders face reconciliation costs when moving inventory between Dubai, Lagos, and Nairobi.
- Legacy paper-based title systems:Kenya and Nigeria lack centralized vehicle history databases. Title verification delays create fraud exposure for financiers and fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Used Car Market |
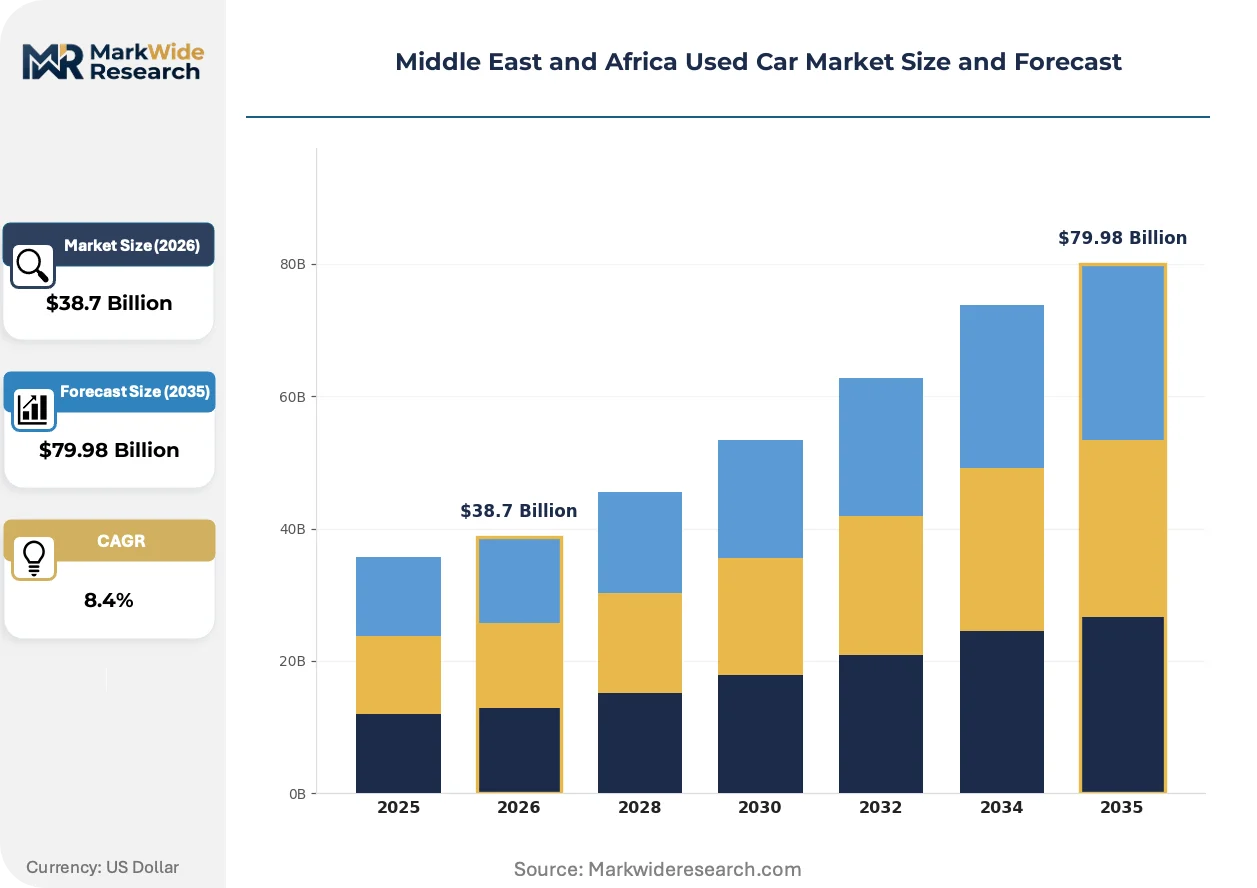
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Coupe Age of Vehicle: 1-3 Years, 4-6 Years, 7-10 Years, Over 10 Years Condition: Certified Pre-Owned, Good, Fair, Poor Fuel Type: Petrol, Diesel, Electric, Hybrid |
| Companies Covered | Al Jomaih Automotive, Kayishha, Al-Futtaim Automotive, Cars45, Syarah, Abdul Latif Jameel Motors, Dubizzle Motors, WeBuyCars, Abu Dhabi Motors, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Used Car Market Shifts & Advancements
Digital infrastructure is compressing transaction friction across the Middle East and Africa used car value chain. Verification technologies and platform-based liquidity are displacing traditional dealer intermediation in high-volume markets.
Blockchain-based title verification is unifying fragmented ownership records across UAE, Saudi Arabia, and South Africa. Dubai's Roads and Transport Authority is piloting distributed ledger systems for cross-emirate vehicle transfers. This technology is unifying previously siloed registration databases, reducing title fraud exposure for lenders and certified pre-owned programs.
South Africa's National Consumer Commission is extending warranty obligations to dealer sales under the Consumer Protection Act. The regulation now mandates minimum coverage periods for vehicles below specified age thresholds. Independent dealers in Johannesburg and Cape Town are responding by partnering with third-party warranty providers to maintain transaction flow.
Subscription-based vehicle access models are fragmenting traditional ownership patterns among urban professionals in Riyadh and Dubai. Younger buyers are deferring purchase decisions in favor of flexible monthly mobility commitments. This behavioral shift is most visible in Saudi Arabia's expatriate professional segment, where tenure uncertainty reduces appetite for depreciating asset exposure.
Middle East and Africa Used Car Market Segmentation
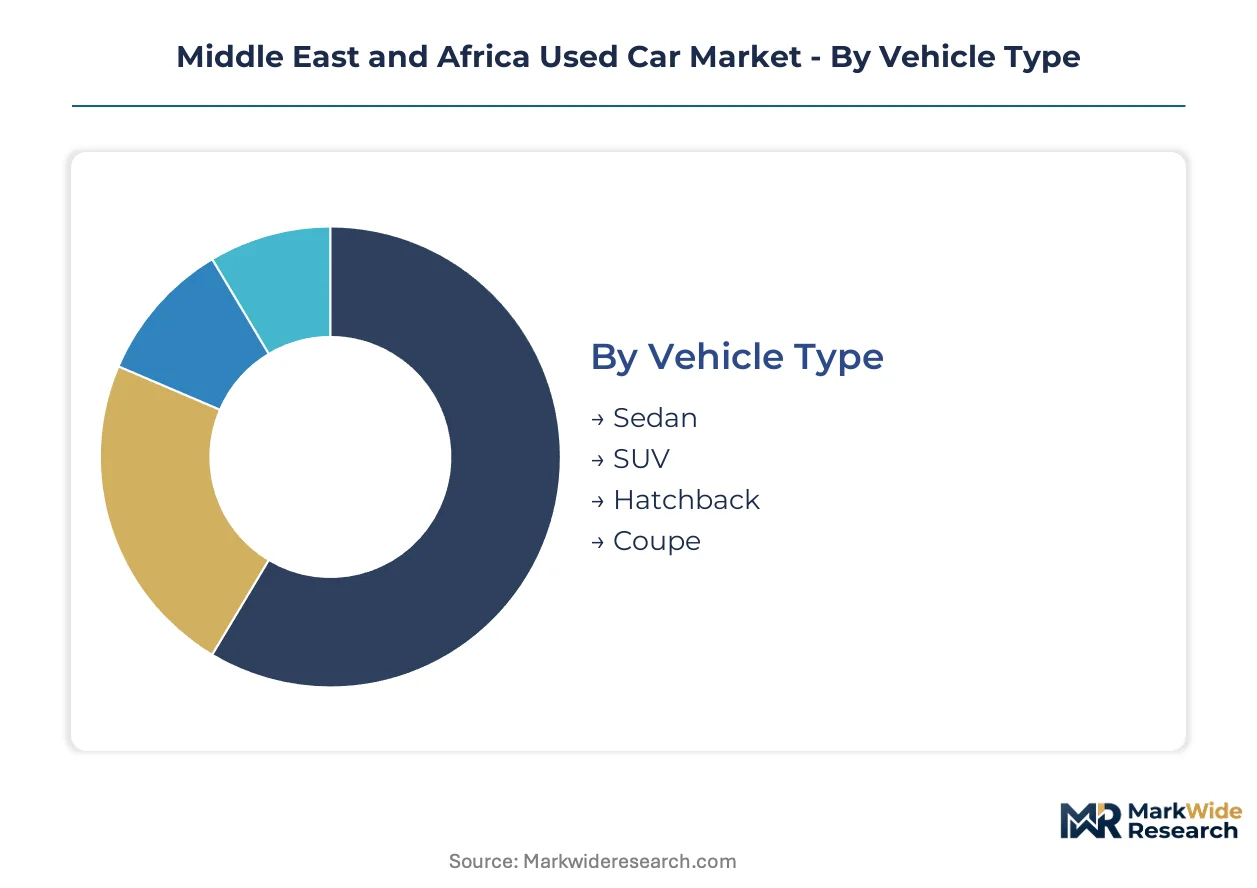
Vehicle replacement cycles across the Middle East and Africa vary sharply by income bracket and import channel, creating distinct demand pockets that reward precise segmentation. Fleet operators, private buyers, and certified program participants each prioritize different age-condition-fuel combinations, fragmenting procurement strategies across the value chain.
Vehicle Type:
Upgrade preferences diverge between family-oriented buyers seeking cabin space and urban professionals prioritizing maneuverability in congested city centers.
- Sedan:Three-box configurations with dedicated trunk compartments dominate corporate fleet procurement in Nigeria and Kenya. Ride-hailing platforms favor 1-3 year old units with documented service histories for driver onboarding programs.
- SUV:Higher ground clearance and multi-row seating align with Saudi Arabian and UAE family requirements where fuel accessibility reduces operating cost sensitivity. Body-on-frame and unibody variants both circulate through certified pre-owned channels.
- Hatchback:Compact footprints suit narrow street networks in Addis Ababa and Nairobi where parking constraints limit vehicle length. Lower price points attract first-time buyers entering formal ownership.
- Coupe:Two-door configurations with sport-tuned suspensions appeal to younger professionals in Dubai and Riyadh. Limited rear accessibility restricts family adoption, concentrating transactions in premium urban segments.
Volume placements concentrate in Sedan; the faster expansion belongs to SUV.
Age of Vehicle:
Depreciation curves and warranty availability reshape buyer calculus across each age bracket, with off-lease corporate units commanding distinct pricing premiums.
- 1-3 Years:Minimal mechanical wear and remaining manufacturer warranty coverage position these units as certified program anchors. Corporate fleet turnover in the UAE and Saudi Arabia feeds this bracket with low-mileage inventory.
- 4-6 Years:Moderate depreciation has occurred while major components remain serviceable without overhaul. Kenyan and Nigerian importers target this bracket for cost-conscious fleet expansion.
- 7-10 Years:Higher maintenance exposure and expired warranty coverage shift transactions toward informal channels. Price-sensitive buyers in Ethiopia and Tanzania dominate this segment.
- Over 10 Years:Salvage-grade condition and parts availability constraints limit formal market participation. Spare parts harvesting and amateur restoration projects absorb most volume.
Transaction liquidity peaks at 1-3 Years; steepest expansion trajectory runs through 4-6 Years as fleet sourcing broadens.
Condition:
Inspection standardization and disclosure mandates are bifurcating the market between verified inventory and undocumented trade.
- Certified Pre-Owned:Manufacturer-backed multi-point inspections and limited warranty coverage command pricing premiums. SAMR disclosure requirements in Saudi Arabia and MOHAP-aligned protocols in Dubai restrict this designation to qualifying units.
- Good:Minor cosmetic wear with no structural damage or major mechanical defects. Independent dealers in Johannesburg and Cape Town apply this grade to auction-sourced inventory with verifiable maintenance records.
- Fair:Visible wear, possible minor accident history, and approaching major service intervals. Nigerian and Kenyan informal channels absorb most volume at negotiated discounts.
- Poor:Significant mechanical deficiencies, unverified accident damage, or odometer discrepancies. Parts recovery and export to neighboring markets represents primary exit pathway.
Certified Pre-Owned captures margin concentration; Good condition inventory is climbing fastest as inspection infrastructure spreads.
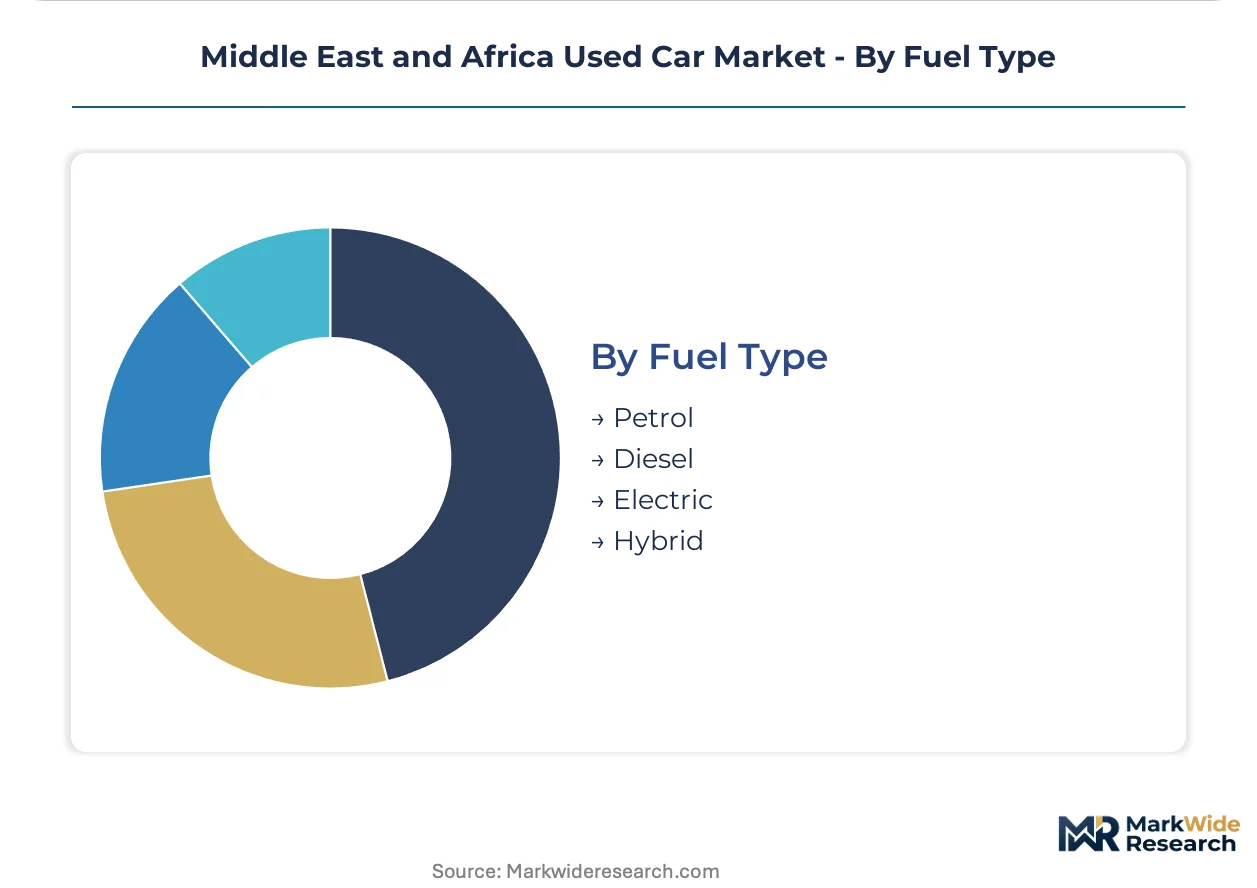
Fuel Type:
Regulatory timelines for electrification and subsidy structures are reordering import eligibility and resale value retention.
- Petrol:Widest service network coverage and lowest upfront acquisition cost sustain dominance across Sub-Saharan markets. Refining infrastructure and retail distribution maturity support continued circulation.
- Diesel:Torque characteristics suit commercial hauling and long-distance fleet operations in South Africa. Emission scrutiny in GCC markets is compressing future import eligibility.
- Electric:Battery-electric units with zero tailpipe emissions face charging infrastructure gaps outside Dubai and Riyadh urban cores. Early adopters in UAE certified programs test resale viability.
- Hybrid:Dual-powertrain configurations offering fuel consumption reduction without range anxiety. Saudi Arabian and UAE regulators are developing certification categories for used hybrid imports.
Petrol retains volume leadership; hybrid and electric categories are gaining share fastest as GCC fuel-type regulations mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's automotive corridor anchors the Middle East and Africa used car trade, with digital auction platforms and certified pre-owned programs concentrating transaction liquidity in the UAE's commercial hub.
Saudi Arabia
Ride-hailing fleet operators in Riyadh and Jeddah are accelerating procurement of 1-3 year old sedans with documented service histories. SAMR disclosure mandates now require odometer and accident history documentation for all imported used vehicles. AI-driven valuation engines in Riyadh auction markets are compressing bid-ask spreads through machine learning pricing models.
United Arab Emirates
Middle-income buyers in Dubai and Abu Dhabi are migrating toward certified pre-owned programs as alternatives to new vehicle tariffs. MOHAP-aligned vehicle inspection protocols restrict accident-damaged imports from entering certified channels. Al-Futtaim Automotive leverages its multi-brand dealership network to anchor warranty-backed programs across the emirates.
Nigeria
Fleet operators in Lagos are expanding second-hand vehicle acquisition to meet ride-hailing platform driver onboarding targets. Currency volatility in the naira is compressing import purchasing power for dollar-denominated GCC suppliers. Informal channels in Lagos absorb unverified vehicles from Asian export markets despite condition uncertainties.
Kenya
Nairobi-based fleet managers prioritize 4-6 year old units for cost-conscious expansion of driver networks. The country's lack of centralized vehicle history databases creates title verification delays and fraud exposure for financiers. Mombasa port serves as the primary entry corridor for used vehicle imports targeting East African markets.
South Africa
Independent dealers in Johannesburg and Cape Town are partnering with third-party warranty providers to comply with extended coverage obligations. The National Consumer Commission applies warranty mandates to dealer sales under the Consumer Protection Act. Subscription-based vehicle access models are fragmenting traditional ownership patterns among urban professionals in Gauteng province.
Middle East and Africa Used Car Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification and warranty backing dimensions. The vendor base separates into three tiers: multi-brand dealership networks with manufacturer authorization, digital-native platforms with AI pricing engines, and informal importers operating through unverified channels. Two dominant competitive moves are reshaping positioning: vertical integration into inspection and financing services, and geographic expansion through digital marketplace entry.
Within the certified pre-owned tier, Al-Futtaim Automotive and Abdul Latif Jameel Motors occupy positions anchored by multi-brand dealership networks. Kayishha exemplifies the digital-native archetype through its AI-driven pricing engine deployment in Saudi Arabian markets. Dubizzle Motors represents the classified liquidity controller segment, dominating digital listing volumes in Dubai and Abu Dhabi.
| Leading Market Players |
|---|
| Al Jomaih Automotive |
| Kayishha |
| Al-Futtaim Automotive |
| Cars45 |
| Syarah |
| Abdul Latif Jameel Motors |
| Dubizzle Motors |
| WeBuyCars |
| Abu Dhabi Motors |
| Others |
Supply & Pricing Matrix
Ride-hailing fleet operators in Nigeria and Kenya anchor demand concentration, locking procurement around transaction-based pricing per vehicle unit rather than subscription or lease structures. Their dollar-denominated sourcing from GCC suppliers creates currency-exposure pricing tiers that separate formal certified channels from informal import arbitrage.
Pricing Analysis
Certified pre-owned warranty coverage serves as the value-based pricing anchor, with manufacturer-backed inspections commanding premiums tied to residual reliability outcomes. Price differentiation rests on condition grading rigor and SAMR disclosure compliance, separating verified inventory from undocumented trade. Cost compression in Sub-Saharan informal channels is intensifying because naira and shilling depreciation erodes import purchasing power. Fleet operators exhibit highest price sensitivity, while UAE middle-income buyers seeking tariff alternatives show lowest sensitivity to certified premiums.
Supply Chain Analysis
Refurbishment flows from Dubai's inspection hubs redirect accident-damaged units away from certified channels toward East African informal markets. Supply concentrates in the UAE, Japan, and South Korea as primary export origination points. Component dependencies include replacement powertrain assemblies, electronic control modules, and crash-structure replacement parts. Single-source vulnerability runs through Mombasa and Lagos port chokepoints for landlocked hinterland distribution. Distribution runs through digital auction platforms in Riyadh and Dubai, layered over traditional dealer networks in Johannesburg and Cape Town.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-based title verification is displacing legacy paper-based ownership records across the Middle East and Africa used car trade, compressing fraud exposure and transaction friction simultaneously.
For Market Incumbents: Acquire digital inspection technology assets to defend certified pre-owned positioning against AI-native pricing platforms. SAMR disclosure mandate expansion threatens margin capture in Saudi Arabia's formal channels. Backward integration into captive warranty underwriting preserves pricing power as third-party coverage proliferates. For New Entrants and Emerging Players: Begin with Ethiopia's Addis Ababa corridor, where organized distribution gaps meet rising middle-class vehicle demand. Hybrid and electric vehicle certification categories in Dubai offer the most penetrable regulatory white-space. Partner with Sharia-compliant financiers in Saudi Arabia to embed lending at point of digital transaction. For Investors and Strategic Acquirers: The window for entry favors inspection-technology specialists with cross-border data interoperability. Long-term viability hinges on platform consolidation across fragmented national registries. Monitor SAMR disclosure enforcement intensity as the inflection signal for formal channel acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Title Verification Deployment | Dubai's Roads and Transport Authority pilots distributed ledger systems to unify cross-emirate ownership records. |
| AI-Driven Pricing Engine Integration | Kayishha's machine learning models reduce bid-ask spreads in Riyadh and Jeddah auction markets. |
| Sharia-Compliant Finance Embedding | Lenders partnering with digital platforms expand addressable buyer pools in Saudi Arabia's secondary market. |
| Hybrid-Electric Certification Category Development | GCC regulators create new inspection protocols for battery-electric and plug-in hybrid used imports. |
| Multi-Brand Dealership Network Expansion | Al-Futtaim Automotive anchors warranty-backed programs across UAE and Saudi Arabia certified channels. |
Research Methodology
Trade databases, vehicle registration filings, and customs import records formed the secondary backbone, supplemented by SAMR regulatory bulletins and MOHAP inspection protocol documentation. Primary interviews with fleet procurement managers, certified pre-owned program directors, digital platform operators, and independent dealer principals validated demand-side assumptions. Bottom-up transaction volume modeling and top-down macroeconomic triangulation converged on segment-level estimates across the analysis window.
Historical trendline analysis of off-lease corporate fleet turnover, ride-hailing platform vehicle acquisition patterns, and certified program penetration rates informed the analytical framework. Segmentation dimensions modeled include vehicle age bracket, condition grade, fuel type, and regional regulatory cluster. CAGRs were derived from regression-adjusted growth trajectory fitting. Forecast inputs incorporated currency volatility indices for Nigerian naira and Kenyan shilling, plus electrification timeline assumptions from GCC regulator announcements.
Currency devaluation shocks, abrupt fuel-type import bans, and blockchain title system rollout delays are the dominant revision risks to modeled projections. Forecasts reflect documented assumptions about inspection infrastructure buildout pace and disclosure mandate enforcement consistency. Practitioners should monitor SAMR audit intensity, naira-shilling exchange rate volatility, and Dubai RTA distributed ledger pilot outcomes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Kenya Used Car Market
Used Vehicles
Thailand Used Car Market
Used Vehicles
Global Online Second-Hand Car Trading Service Market
Used Vehicles
Indonesia Used Car Market
Used Vehicles
Australia Used Car Market
Used Vehicles
North America Used Truck Market
Used Vehicles
Spain Used Car Market
Used Vehicles
Philippines Used Car Market
Used Vehicles
Used Cars in Russia Market
Used Vehicles
Portugal Used Car Market
Used Vehicles
Used E-Scooter Market
Used Vehicles
Used Semi Truck Market
Used Vehicles
Japan Used Car Market
Used Vehicles
France Used Car Market
Used Vehicles
Ethiopia Used Car Market
Used Vehicles
Oman Used Car Market