
 Netherlands Used Car Market | 2026-2036
Netherlands Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Used Car Market Insights
Digital auction infrastructure and AI-powered vehicle condition scoring is reconfiguring how used cars are sourced, priced, and distributed across Dutch wholesale channels. Van Mossel Automotive Group leverages its integrated dealership network to control upstream supply and downstream retail placement. Hedin Automotive anchors its position through Scandinavian-brand specialization and centralized refurbishment operations. Gaspedaal.nl competes as a pure-play aggregator, capturing price-sensitive consumers through transparent cross-platform comparison tools.
A used car denotes a previously registered vehicle sold through secondary transactions, typically evaluated by odometer reading, service history completeness, and structural integrity assessments before remarketing. The primary commercial purpose centers on value recovery from depreciated automotive assets while extending vehicle lifecycles through certified refurbishment protocols. SUVs and hatchbacks dominate transaction volumes in the Netherlands, reflecting Dutch parking constraints and family mobility patterns that favor compact utility. Electric and hybrid segments within fuel type classification are expanding fastest, driven by BiK tax advantages and municipality-level emission zone enforcement that renders older diesel inventory less liquid. Certified pre-owned condition grades command margin premiums due to dealer-backed warranties and standardized inspection protocols that reduce buyer uncertainty.
The Netherlands Vehicle Authority (RDW) enforces registration transparency and odometer verification, while the Authority for Consumers and Markets (ACM) monitors platform pricing fairness and anti-competitive listing practices. WLTP emission testing standards and provincial zero-emission zone timelines are compressing the resale value of non-compliant internal combustion vehicles. Stakeholders must monitor RDW data-sharing mandates and ACM platform regulation evolution to anticipate inventory obsolescence risks and remarketing channel restructuring.
Market Dynamics
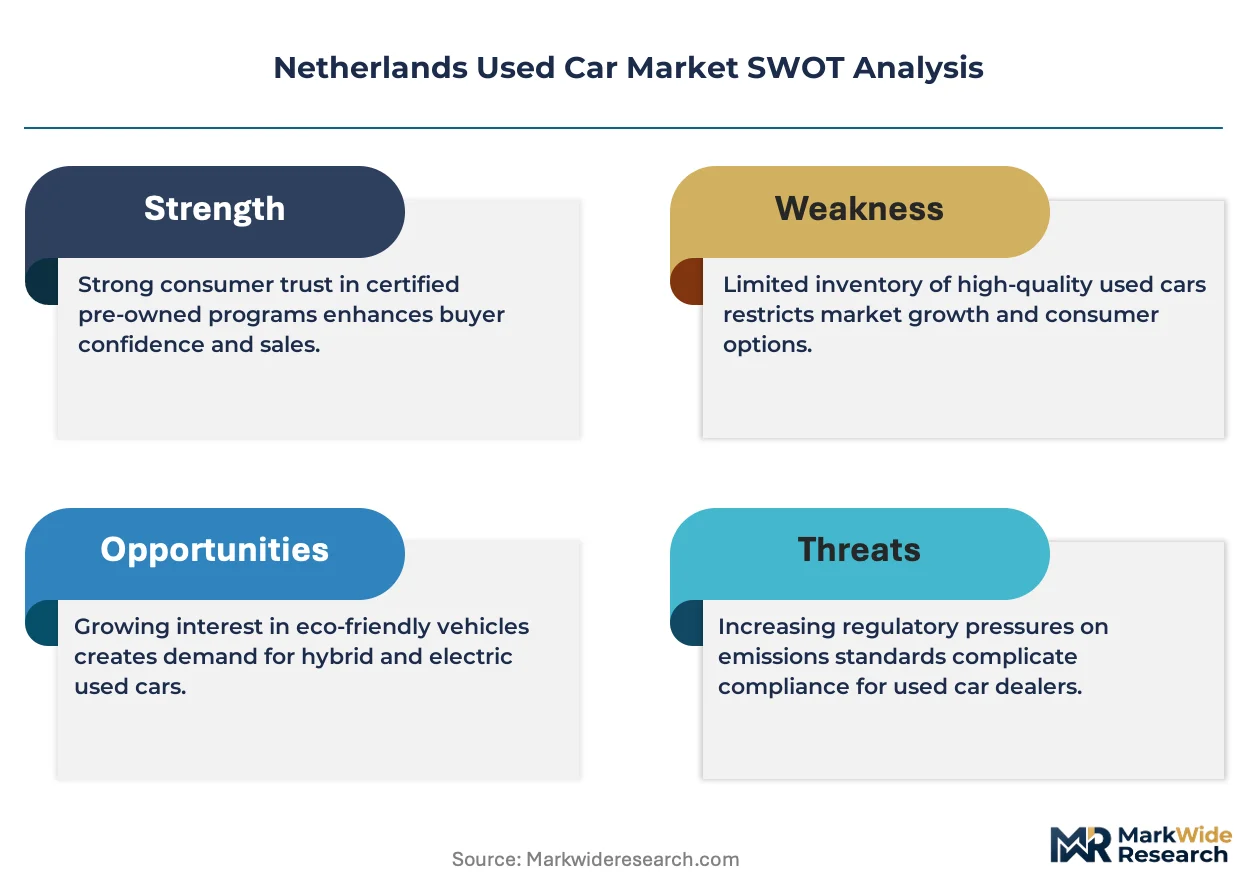
WLTP-based taxation adjustments and zero-emission zone mandates in Amsterdam, Rotterdam, and Utrecht are compressing resale values of older diesel inventory while accelerating turnover toward younger, lower-emission certified pre-owned vehicles.
Growth Catalysts
- BiK Tax Advantages:Dutch Benefit-in-Kind tax structures for electric and plug-in hybrid vehicles reduce total cost of ownership for corporate fleet buyers, expanding procurement of certified pre-owned electrified models.
- RDW Registration Transparency:The Netherlands Vehicle Authority's mandatory odometer verification and blockchain-linked title history reduce information asymmetry, accelerating transaction velocity in wholesale channels.
- Randstad Urban Congestion Pricing:Parking restrictions and emission-based access controls in Amsterdam, Rotterdam, and Utrecht concentrate demand for compact hatchbacks and plug-in hybrids with documented service histories.
Market Restraints
- WLTP Compliance Compression:Stricter emission testing standards render non-compliant internal combustion vehicles illiquid, trapping dealer inventory in depreciating asset categories with compressed remarketing windows.
- Refurbishment Cost Volatility:Battery diagnostic equipment and technician certification for electrified drivetrains elevate fixed costs for independent dealers without captive refurbishment operations.
- Platform Concentration Risk:Digital auction infrastructure consolidates price discovery through a limited set of aggregator platforms, squeezing margin capture for fragmented independent retailers.
Strategic Opportunities
- AI-Powered Condition Scoring:Machine vision systems for automated damage assessment and predictive maintenance forecasting enable standardized grading across decentralized inspection networks.
- Provincial Zero-Emission Zone Expansion:Municipality-level enforcement timelines in Groningen, Eindhoven, and Maastricht create geographic arbitrage for early compliance inventory positioning.
- Battery Health Certification:Standardized state-of-health reporting for used electric vehicles addresses buyer uncertainty in secondary battery transactions, unlocking premium pricing for documented performance.
Industry Challenges
- Electrified Drivetrain Technician Scarcity:High-voltage certification requirements and specialized diagnostic training constrain refurbishment throughput at scale.
- ACM Platform Pricing Scrutiny:The Authority for Consumers and Markets monitors anti-competitive listing practices, requiring compliance investment from aggregator-dependent retailers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Used Car Market |
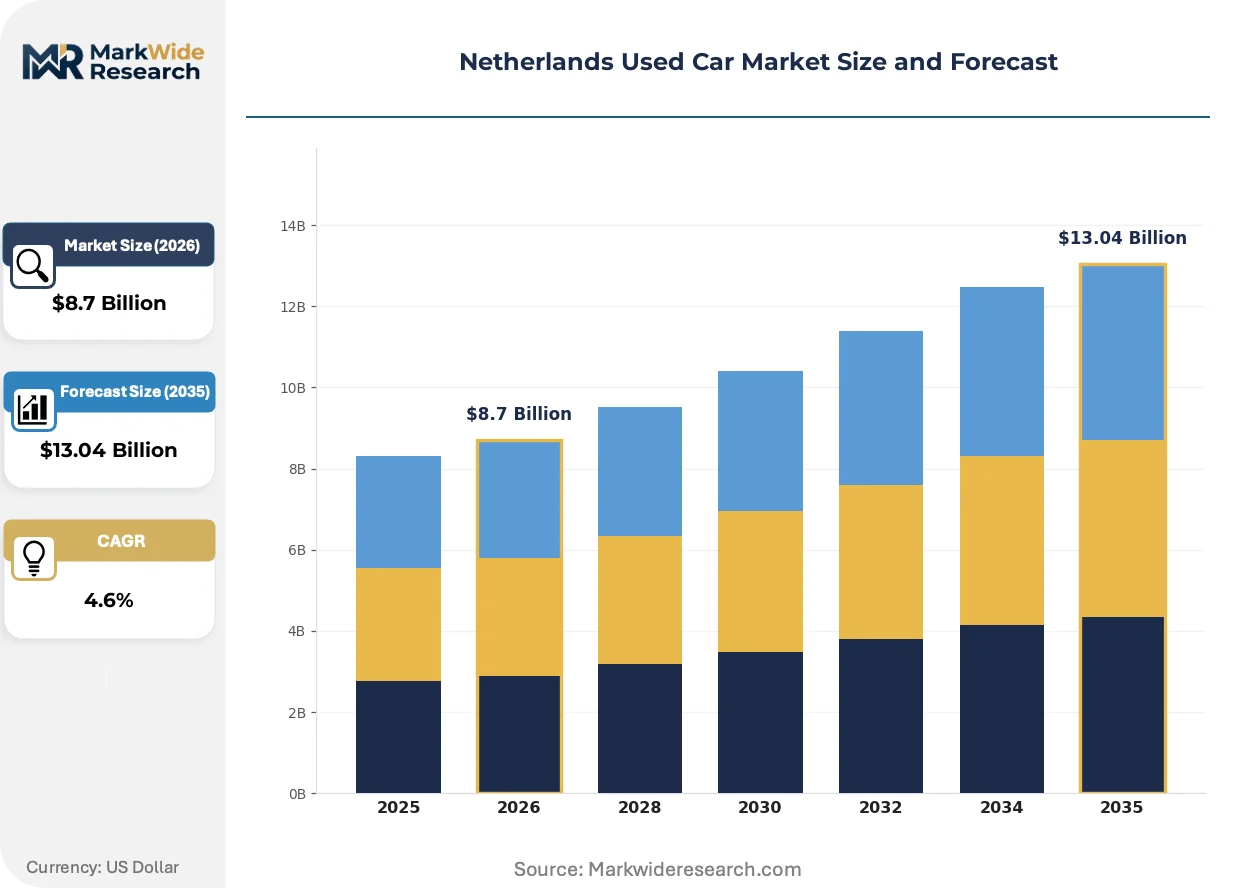
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Coupe Fuel Type: Petrol, Diesel, Hybrid, Electric Transmission: Automatic, Manual, Semi-Automatic, CVT Condition: Certified Pre-Owned, As-Is, Damaged, Repaired |
| Companies Covered | Van Mossel Automotive Group, Hedin Automotive, Emil Frey Netherlands, Ayvens Carmarket, Arval Trading, Gaspedaal.nl, Autoscout24.nl, Marktplaats.nl, AutoUncle, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Used Car Market Trends and Innovations
Digital infrastructure is reconfiguring vehicle sourcing, condition assessment, and price discovery across Dutch wholesale and retail channels, compressing transaction cycles while elevating transparency requirements.
Automated vehicle inspection systems deploying machine vision and acoustic analysis is digitizing condition reporting across auction platforms and dealership networks. Fleet operators and leasing companies are adopting these tools at scale for inbound remarketing decisions. The technology is digitizing upstream supply capture by enabling remote grading that reduces physical logistics costs and accelerates inventory turnover velocity.
The Netherlands Vehicle Authority's enhanced data-sharing mandates and odometer verification protocols tighten registration transparency requirements. ACM oversight of platform pricing fairness creates compliance friction for digital marketplaces aggregating cross-dealer inventory. Certified pre-owned segments with standardized inspection documentation command buyer preference as regulatory scrutiny elevates trust requirements in secondary transactions.
Corporate procurement patterns favor subscription-based mobility solutions and flexible fleet leasing over fixed asset ownership. Leasing companies and fleet management providers are consolidating vehicle sourcing through centralized digital auctions, displacing traditional dealer relationships. This concentration is most visible in Randstad corridors where congestion pricing and parking restrictions elevate total cost of ownership calculations for employer-provided vehicles.
Netherlands Used Car Market Segmentation
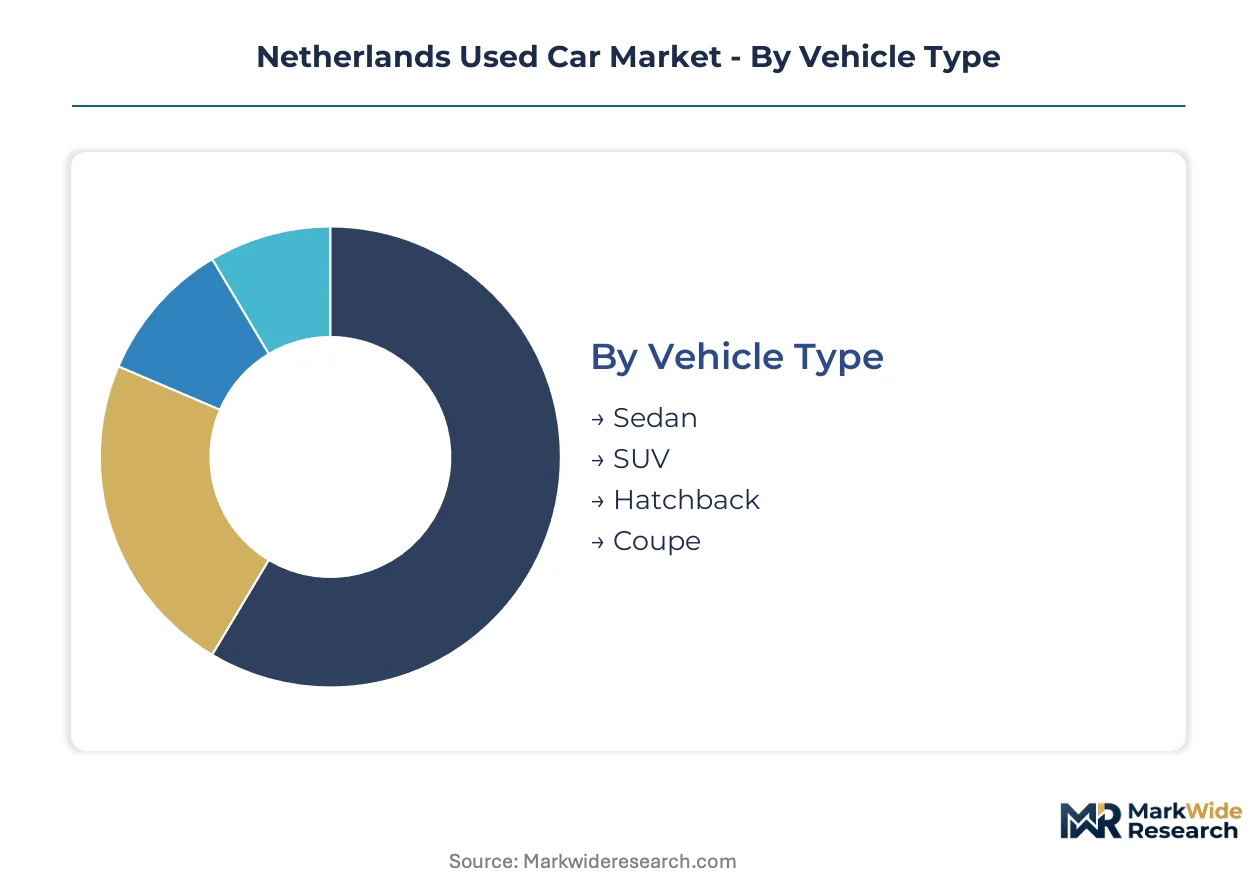
Dutch used car segmentation reflects Randstad urban constraints, WLTP compliance pressures, and corporate fleet procurement patterns. Dealers and auction platforms calibrate inventory mix across vehicle dimensions, drivetrain technologies, and certification grades to match municipality-level emission enforcement and parking economics.
Vehicle Type:
The use-case spectrum spans family mobility, corporate fleet duty, and urban commuter applications across Dutch population corridors.
- SUV:Compact and mid-size utility vehicles dominate suburban household transactions outside Amsterdam and Rotterdam congestion zones. Noord-Brabant and Gelderland provinces concentrate demand where parking constraints ease and family cargo needs persist.
- Hatchback:Three-door and five-door compact configurations command premium liquidity in Amsterdam, Utrecht, and The Hague where street parking dimensions and emission access rules filter larger vehicles. BiK tax advantages for plug-in hybrid variants accelerate corporate procurement of certified pre-owned units.
- Sedan:Traditional three-box configurations serve executive fleet segments and long-distance commuters traversing interprovincial corridors.
- Coupe:Two-door performance and luxury variants occupy niche positioning among enthusiast buyers and secondary household vehicles.
The dominant share belongs to Hatchback, while SUV is closing the gap fastest.
Fuel Type:
Cost tier stratification separates compliance-ready electrified inventory from depreciating combustion assets facing municipal access restrictions.
- Electric:Battery-electric vehicles with documented state-of-health certification capture margin premiums in corporate remarketing channels. Randstad fleet operators prioritize used EV procurement where zero-emission zone mandates in Amsterdam, Rotterdam, and Utrecht eliminate diesel alternatives.
- Hybrid:Plug-in and full-hybrid drivetrains bridge taxation advantages with range flexibility, concentrating demand among benefit-in-kind-optimizing employers and urban commuters.
- Petrol:Internal combustion gasoline engines retain liquidity in rural provinces and price-sensitive private buyer segments outside emission enforcement zones.
- Diesel:Compression-ignition inventory faces accelerating value compression as provincial zero-emission timelines expand beyond core Randstad cities into Groningen and Eindhoven.
Electric holds the steepest expansion trajectory as battery health standardization unlocks secondary transaction confidence.
Transmission:
Application-driven selection patterns separate automated convenience for fleet and urban use from manual cost control in private transactions.
- Automatic:Torque-converter and dual-clutch configurations dominate corporate procurement and premium retail segments where driver fatigue reduction justifies acquisition premiums.
- Manual:Clutch-operated transmissions retain cost-sensitive private buyer preference in rural provinces and entry-price segments.
- Semi-Automatic:Automated manual systems occupy intermediate positioning in compact urban vehicles and budget fleet rotations.
- CVT:Continuously variable transmissions concentrate in hybrid-integrated drivetrains where efficiency optimization aligns with electrified powertrain architectures.
Automatic transmission inventory commands dealer margin premiums, while CVT integration expands fastest through hybrid drivetrain penetration.
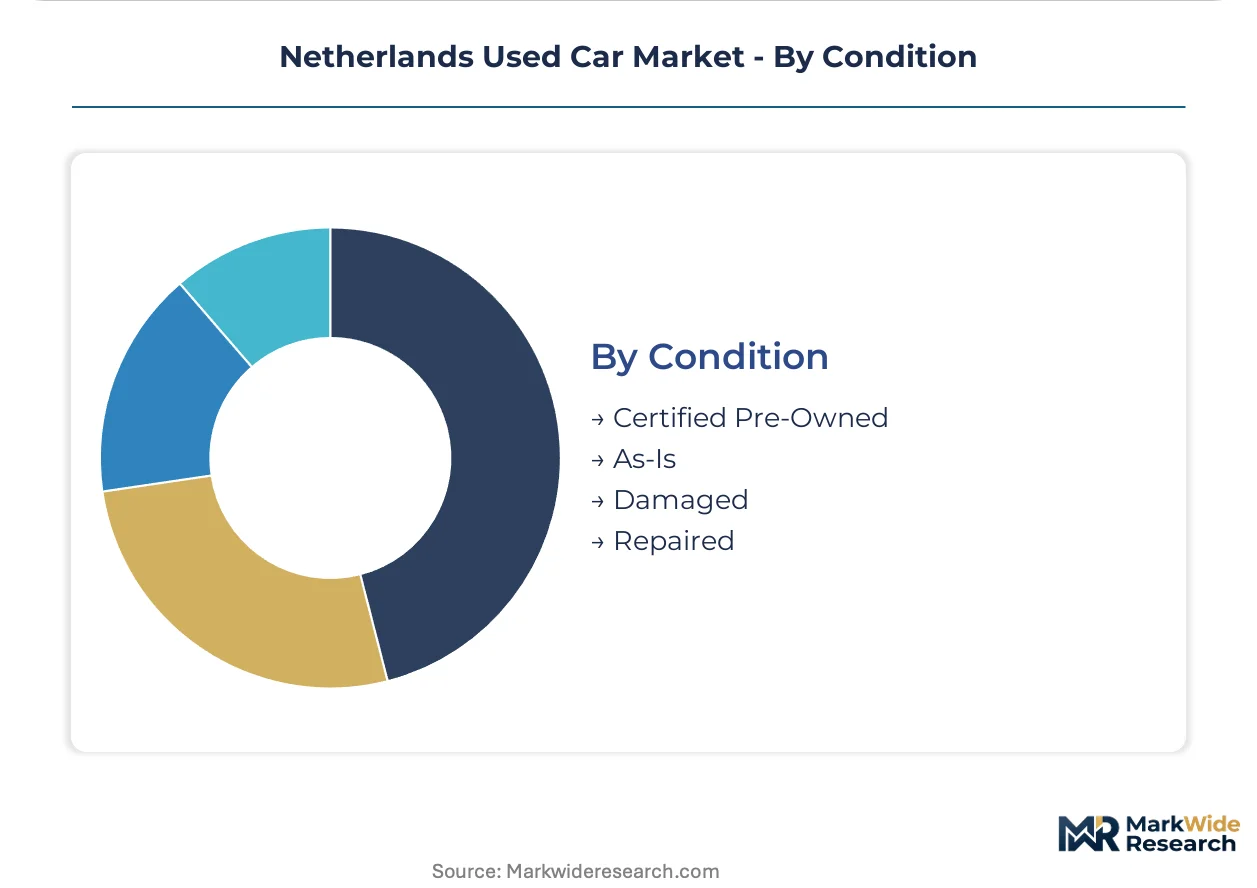
Condition:
Margin concentration stratifies across certification-backed warranty coverage versus as-is transactional velocity in wholesale channels.
- Certified Pre-Owned:Dealer-backed inspection protocols and standardized warranty terms reduce buyer uncertainty, enabling pricing premiums in Amsterdam and Rotterdam retail networks. RDW registration transparency and blockchain-linked title history reinforce trust requirements for this segment.
- As-Is:Unwarranted inventory moves through digital auction platforms to price-sensitive buyers and independent refurbishment operators.
- Damaged:Insurance-totaled and structurally compromised units flow to salvage networks and export channels.
- Repaired:Previously damaged vehicles with documented restoration history serve budget segments where disclosure compliance satisfies RDW structural integrity verification.
Certified Pre-Owned captures the dominant transaction value, while Repaired inventory is gaining liquidity fastest through enhanced documentation standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and corporate buyers concentrate procurement in Randstad urban corridors where congestion pricing and emission access rules filter vehicle eligibility. Private transactions dominate rural provinces where parking constraints ease and diesel inventory retains residual liquidity. Sub-regional variation reflects municipality-level enforcement timelines and provincial refurbishment infrastructure density.
Randstad
Amsterdam, Rotterdam, and Utrecht enforce zero-emission zone mandates that accelerate turnover toward younger, lower-emission certified pre-owned vehicles. The Netherlands Vehicle Authority's RDW registration transparency requirements compress transaction cycles in these dense urban markets. Parking restrictions and street dimension constraints favor compact hatchbacks and plug-in hybrid models with documented service histories.
Brabant
Noord-Brabant province concentrates SUV and mid-size utility demand where suburban household parking constraints ease relative to Randstad cores. Provincial refurbishment infrastructure supports certified pre-owned throughput for corporate fleet rotations. Eindhoven's automotive technology cluster generates secondary supply from leasing company remarketing channels.
Eindhoven Region
Brainport Eindhoven's high-tech employment base expands corporate mobility procurement through centralized digital auction platforms. Municipality-level zero-emission zone preparation is compressing diesel inventory values ahead of formal enforcement. Regional dealers leverage proximity to leasing company headquarters for upstream supply capture.
Northern Netherlands
Groningen and Friesland provinces retain manual transmission and petrol vehicle liquidity where emission enforcement remains less stringent than Randstad corridors. Price-sensitive private buyers dominate transaction volumes in these lower-density markets. Independent refurbishment operators serve dispersed rural demand without captive auction platform access.
Netherlands Used Car Market Competitive Landscape
Channel-controlling players compete with product-specialist players and pure-play aggregators across Dutch wholesale and retail channels. The market structure fragments across integrated dealership networks, Scandinavian-brand specialists, and digital comparison platforms. Three archetypes dominate: vertically integrated automotive groups with refurbishment capabilities, brand-specialized distributors with centralized operations, and algorithm-driven price aggregators with transparent cross-platform tools. Competitive moves concentrate on digital auction infrastructure control and AI-powered condition scoring standardization.
Among integrated dealership networks, Van Mossel Automotive Group and Hedin Automotive occupy positions representing channel-control archetypes. Van Mossel exemplifies upstream supply capture through network density, while Hedin anchors brand-specialist positioning through Scandinavian marque concentration. Gaspedaal.nl sits within the pure-play aggregator tier, exemplifying price-transparent comparison infrastructure that compresses margin capture for fragmented independent retailers.
| Leading Market Players |
|---|
| Van Mossel Automotive Group |
| Hedin Automotive |
| Emil Frey Netherlands |
| Ayvens Carmarket |
| Arval Trading |
| Gaspedaal.nl |
| Autoscout24.nl |
| Marktplaats.nl |
| AutoUncle |
| Others |
Pricing and Supply Chain Analysis
WLTP compliance chokepoints determine pricing tier spreads and supply chain shape in the Dutch used car market. The Netherlands Vehicle Authority's emission verification protocols compress remarketing windows for non-compliant inventory while elevating certified pre-owned premiums.
Pricing Analysis
Cost-plus refurbishment contracts with battery diagnostic equipment indexation dominate dealer-to-fleet transactions. Three-tier pricing structure across certified pre-owned, standard retail, and auction-as-is levels separates warranty-backed inventory from depreciated diesel assets. Pricing pressure stems from platform concentration risk as digital aggregators compress margin capture for independent retailers. Corporate fleet buyers exhibit lowest price sensitivity due to BiK tax optimization, while rural private buyers in Northern Netherlands drive hardest bargain on manual petrol vehicles.
Supply Chain Analysis
Upstream feedstock of lease-return and corporate fleet vehicles concentrates supply from Germany, Belgium, and domestic Dutch lessors. Battery-electric and plug-in hybrid inventory draws from automotive OEM captive finance arms and pan-European fleet operators. Single-source vulnerability sits with centralized digital auction platforms controlling price discovery for fragmented independent dealers. Distribution runs through integrated dealership networks, brand-specialist distributors, and pure-play aggregators to Randstad retail corridors and provincial independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Dutch used car market rewards players who control high-voltage technician pipelines and blockchain-verified title infrastructure. Scarcity of certified battery assessors and WLTP-compliant refurbishment capacity constrains scalable entry.
For Market Incumbents: Entrench position by acquiring captive battery diagnostic capabilities and securing exclusive digital auction platform partnerships. Van Mossel Automotive Group's integrated network density demonstrates how upstream supply control neutralizes platform concentration risk. Prioritize technician certification pipelines to maintain refurbishment throughput as electrified drivetrain volume accelerates. For New Entrants and Emerging Players: Rural Northern Netherlands provinces with manual transmission and petrol vehicle liquidity represent the most penetrable entry point for independent refurbishment operators lacking aggregator platform access. Battery health certification services for secondary EV transactions offer specialized white-space positioning. Partner with regional leasing company headquarters for upstream supply capture rather than competing for Randstad retail density. For Investors and Strategic Acquirers: The Authority for Consumers and Markets' platform pricing scrutiny reshapes the acquisition landscape toward compliance-capable operators. Long-term viability centers on players with demonstrated RDW data-sharing integration and standardized inspection documentation. Target vertically integrated dealership groups with captive refurbishment operations. Watch Eindhoven and Groningen zero-emission zone enforcement timelines as geographic arbitrage inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Health Certification Program | Standardized state-of-health reporting unlocks premium pricing for documented EV performance in corporate remarketing channels. |
| Digital Auction Platform Integration | Centralized procurement access displaces traditional dealer relationships and compresses transaction cycles for fleet operators. |
| High-Voltage Technician Pipeline Development | Certification capacity constraints refurbishment throughput at scale across electrified drivetrain inventory. |
| Provincial Zero-Emission Zone Pre-Positioning | Early compliance inventory placement in Groningen and Eindhoven captures geographic arbitrage ahead of formal enforcement. |
| Blockchain-Linked Title Infrastructure | RDW-mandated transparency reduces information asymmetry and accelerates transaction velocity in wholesale channels. |
Research Methodology
Operator-level perspectives from fleet procurement managers, dealership operations directors, digital auction platform engineers, and RDW compliance officers anchored the qualitative base. Primary interviews combined with secondary validation against RDW registration databases, ACM platform oversight filings, and leasing company remarketing disclosures. Bottom-up vehicle transaction modeling and top-down market sizing triangulation produced volume and value estimates.
Scenario-bracketing across WLTP compliance timelines and provincial zero-emission zone enforcement patterns structured the analytical framework across the analysis window. Segmentation dimensions modeled include vehicle type, fuel architecture, transmission configuration, condition grade, and regional enforcement cluster. CAGRs derived from historical transaction velocity patterns and projected fleet rotation schedules incorporate battery technology depreciation curves and BiK tax structure evolution.
Stress conditions across battery replacement cost trajectories, technician certification throughput limits, and platform pricing regulation intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about RDW data-sharing mandate adherence and municipal enforcement consistency. Cross-checking against European leasing industry remarketing volume benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Middle East and Africa Used Car Market
Used Vehicles
Spain Used Car Market
Used Vehicles
Germany Used Car Market
Used Vehicles
Oman Used Car Market
Used Vehicles
Malaysia Used Car Market
Used Vehicles
Indonesia Used Car Financing Market
Used Vehicles
Online Car Buying Market
Used Vehicles
Belgium Used Car Market
Used Vehicles
France Used Car Market
Used Vehicles
Saudi Arabia Used Car Market
Used Vehicles
Japan Used Car Market
Used Vehicles
Brazil Used Car Market
Used Vehicles
Philippines Used Car Market
Used Vehicles
Russia Used Car Market
Used Vehicles
Singapore Used Car Market
Used Vehicles
Italy Used Car Market