
 Indonesia Used Car Market | 2026-2036
Indonesia Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Used Car Market Outlook
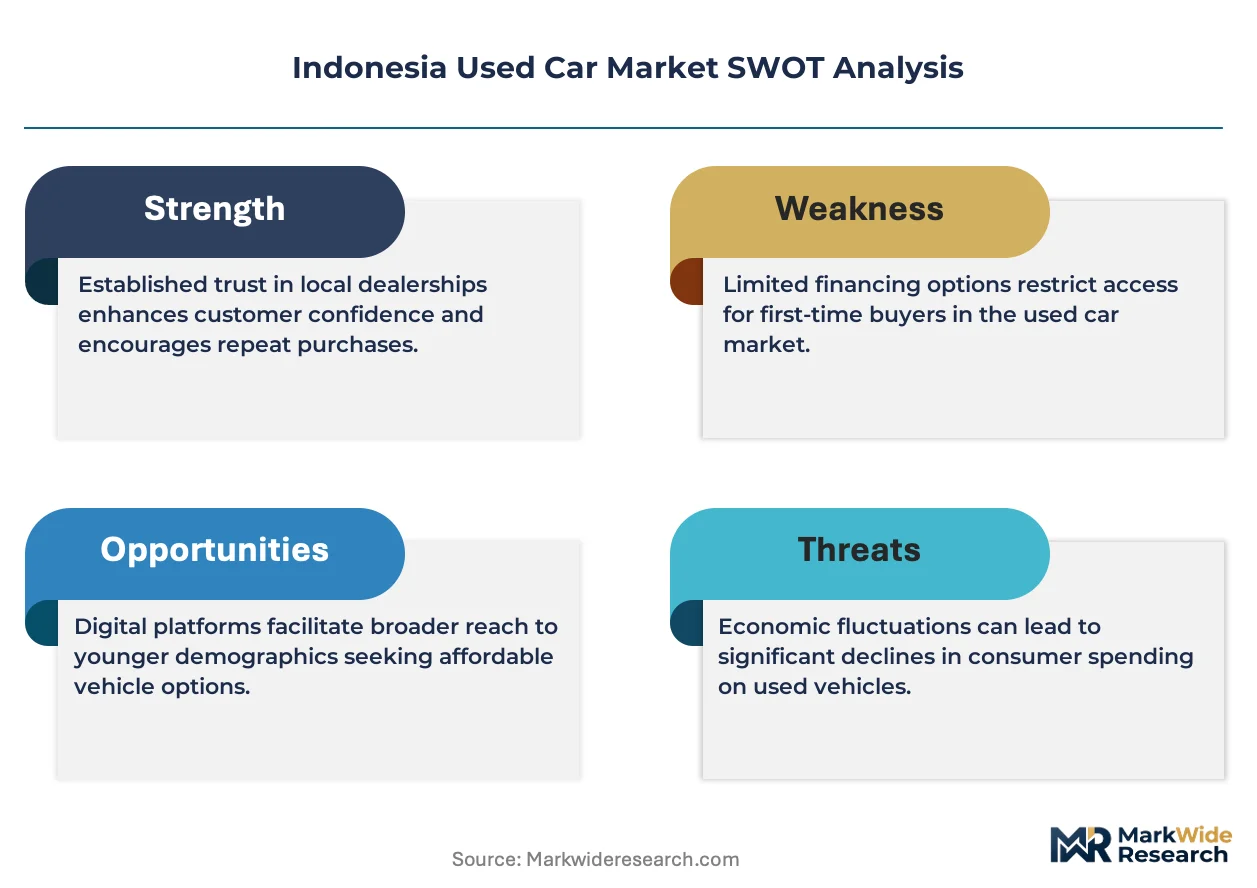
Embedded leasing and pay-per-use asset-light models is narrowing the capital barrier for multi-unit fleet buyers and suburban dealership networks. Carsome Indonesia leverages its end-to-end inspection and refurbishment infrastructure to sustain pricing power across Java and Sumatra. PT Tunas Ridean Tbk anchors its position through captive financing arms tied to Astra International's distribution network. Moladin competes by embedding inventory financing directly into dealer management systems, reducing working capital gaps for small lot operators.
A used car denotes a previously registered motor vehicle resold through secondary channels, typically subjected to condition grading based on odometer reading, frame integrity, and powertrain function before re-entry into commercial circulation. Its primary purpose is to satisfy mobility demand at lower depreciation-adjusted cost points while extending vehicle economic life across multiple ownership cycles. The certified pre-owned condition segment commands premium pricing due to standardized multi-point inspection protocols and limited warranty coverage that reduce buyer uncertainty. Online marketplaces represent the fastest-expanding sales channel as smartphone penetration and digital payment rails compress search and transaction friction for dispersed archipelago buyers.
Indonesia's Financial Services Authority (OJK) governs consumer credit provisioning and leasing disclosure standards, while the Ministry of Industry sets local content thresholds that affect spare parts availability and reconditioning economics. The National Standardization Agency (BSN) maintains vehicle safety and emissions benchmarks that determine roadworthiness certification for resale eligibility. Stakeholders must monitor evolving electric vehicle conversion guidelines and battery health verification protocols as hybrid and full-electric units enter secondary circulation in greater volumes.
Market Dynamics
Digital auction platforms and peer-to-peer lending apps are collapsing transaction friction for first-time buyers across Java and Sumatra, while OJK consumer finance regulations steer demand toward certified pre-owned units with verified service histories.
Growth Catalysts
- Embedded Leasing Models:Asset-light pay-per-use structures narrow capital barriers for multi-unit fleet buyers and suburban dealership networks. Fleet operators in Jakarta refresh vehicles more frequently as residual value guarantees improve.
- Local Content Requirements:Indonesia's Ministry of Industry mandates on spare parts availability strengthen reconditioning economics for certified pre-owned channels. Verified service histories command measurable price premiums.
- Smartphone Penetration:Mobile-first search and digital payment rails compress discovery-to-purchase cycles for dispersed archipelago buyers. First-time purchasers in secondary cities access inventory previously limited to major metros.
Market Restraints
- Import Dependency:Critical reconditioning components concentrate in ASEAN supply corridors, exposing refurbishment economics to cross-border logistics volatility.
- Battery Health Verification:Absence of standardized protocols for hybrid and full-electric secondary units creates information asymmetry that suppresses resale liquidity.
- OJK Disclosure Standards:Stringent leasing documentation requirements extend approval timelines for thin-file borrowers, constraining volume at the market's entry tier.
Strategic Opportunities
- Sulawesi and Kalimantan Penetration:Underdeveloped dealer infrastructure outside Java creates first-mover terrain for mobile inspection units and regional logistics hubs.
- Electric Vehicle Conversion Guidelines:Anticipated BSN protocols for battery health certification will unlock certified pre-owned segments for hybrid inventory.
- Dealer Management System Integration:Inventory financing embedded directly into small lot operator workflows reduces working capital gaps and accelerates inventory turns.
Industry Challenges
- Certified Inspector Shortage:Multi-point assessment protocols require technicians trained in frame integrity and powertrain diagnostics, creating recruitment bottlenecks for scaling operations.
- Legacy System Integration:Rural dealerships operate on paper-based recordkeeping that complicates service history verification for digital marketplace listings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Used Car Market |
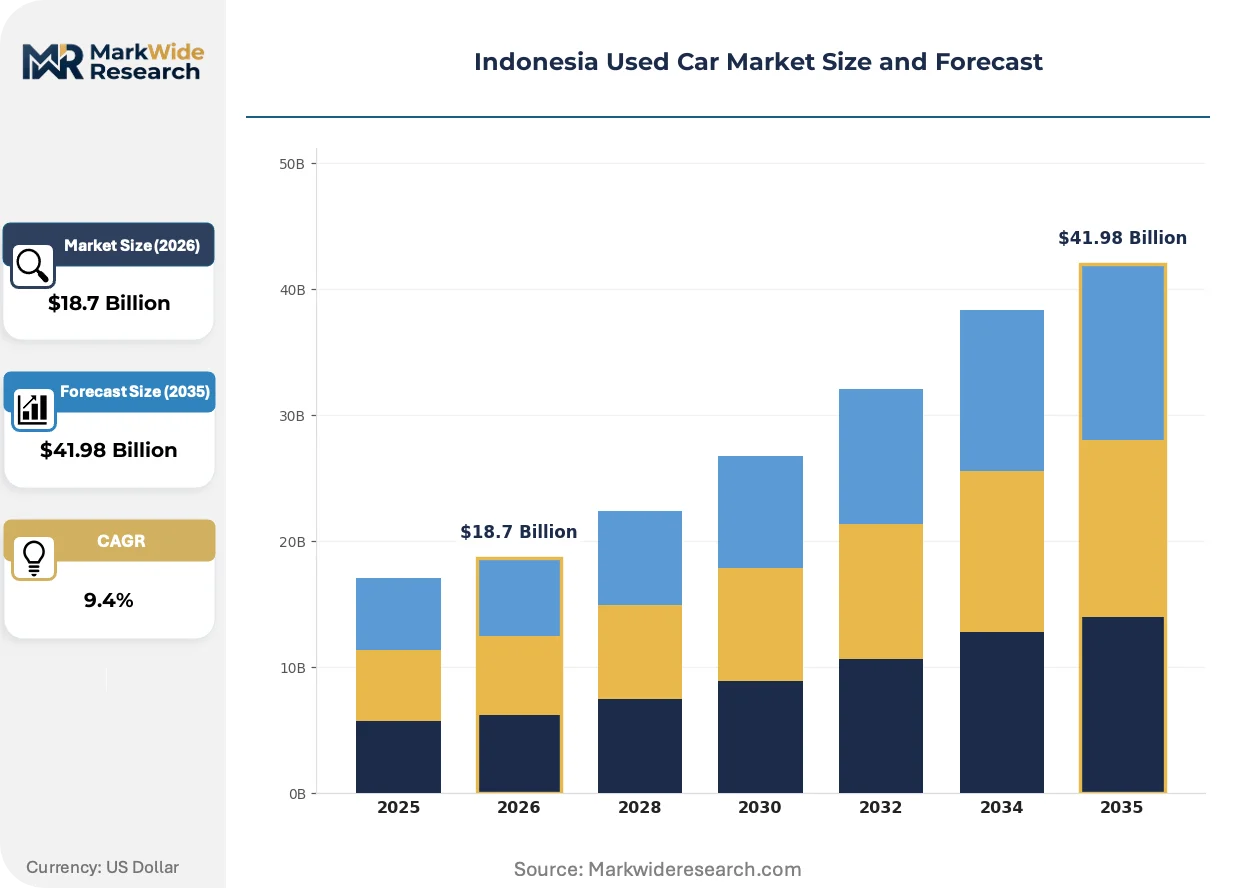
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Sedan, Hatchback, Pickup Condition: Certified Pre-Owned, As-Is, Minor Damage, Major Damage Fuel Type: Petrol, Diesel, Electric, Hybrid Sales Channel: Dealerships, Online Marketplaces, Auctions, Private Sellers |
| Companies Covered | Carsome Indonesia, PT Tunas Ridean Tbk, OLX Indonesia, Carmudi Indonesia, Broom.id, Mobil88, Toyota Astra Motor, Moladin, Carro Indonesia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Used Car Market Strategic Shifts
Condition-grading algorithms and real-time pricing engines are displacing static valuation methods, while regulatory pressure on emissions verification and buyer protection reshapes certification protocols across the archipelago.
AI-powered image recognition for odometer and frame damage assessment is collapsing the cost structure of remote vehicle inspection. Multi-platform marketplace operators deploy computer vision tools to standardize condition reports without physical site visits. Fleet disposal volumes in Surabaya and Bandung now clear through fully digital channels, compressing days-to-sale from weeks to hours.
OJK's consumer finance disclosure mandates tighten leasing contract transparency, forcing captive financing arms to restructure fee presentations. Small lot operators face compliance overhead that favors consolidated dealership networks with dedicated legal functions. The certified pre-owned segment absorbs disproportionate compliance investment, widening the documentation gap against informal secondary channels.
Subscription-based mobility packages are fragmenting traditional ownership cycles, with corporate fleet managers piloting flexible tenure models. Young professionals in Greater Jakarta prioritize access over asset accumulation, redirecting demand from conventional installment purchase toward short-term lease-to-own structures. Digital-native buyers expect seamless handoffs between online discovery and physical delivery, pressuring logistics networks to integrate last-mile transport with title transfer services.
Indonesia Used Car Market Segmentation
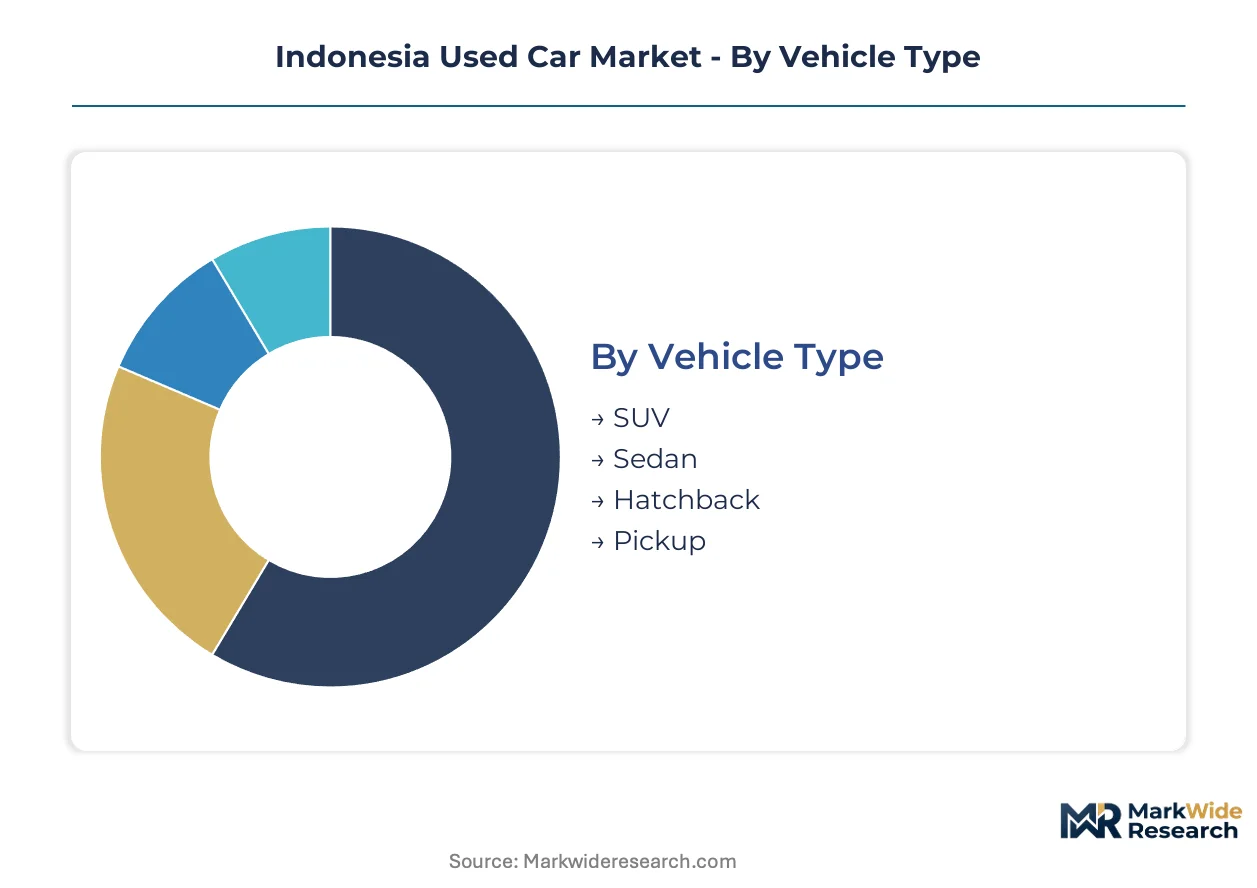
Segmentation in Indonesia's used car market reflects divergent buyer risk tolerances, financing access tiers, and infrastructure maturity across the archipelago. Condition grading and channel selection determine pricing power and transaction velocity for fleet operators and individual sellers alike.
Vehicle Type:
Vehicle classification captures body architecture and utility profile, separating family-oriented configurations from commercial applications.
- SUV:Higher ground clearance and third-row seating configurations dominate suburban Jakarta and Surabaya demand. Fleet refresh cycles in ride-hailing services concentrate on compact SUV platforms for passenger capacity optimization.
- Sedan:Three-box body style with dedicated trunk compartment retains preference among corporate fleet managers for executive transport. Residual value stability in Java's secondary cities supports financing accessibility for salaried borrowers.
- Hatchback:Two-box compact architecture suits narrow urban corridors in Bandung and Yogyakarta with parking space constraints.
- Pickup:Open-bed utility configuration serves Kalimantan plantation operators and Sulawesi construction contractors with cargo flexibility requirements.
SUV commands the established base. The steepest expansion runs through hatchback segments in emerging middle-class suburbs.
Condition:
Condition tiers stratify buyer protection levels and documentation completeness, directly correlating with OJK financing eligibility and warranty coverage.
- Certified Pre-Owned:Standardized multi-point inspection protocols with limited warranty coverage reduce information asymmetry for first-time buyers. OJK disclosure mandates steer regulated lenders toward documented service histories, compressing approval timelines.
- As-Is:No warranty transfer or inspection verification creates price discounts that attract cash buyers in informal secondary channels. Rural dealership networks in Sumatra move significant volume through direct owner-to-owner transfer without platform intermediation.
- Minor Damage:Cosmetic panel repairs or non-structural collision history recorded in vehicle documentation.
- Major Damage:Frame integrity compromise or powertrain replacement requiring specialized reconditioning investment.
Certified Pre-Owned absorbs disproportionate compliance investment. The steepest expansion trajectory belongs to As-Is transactions outside formal financing networks.
Fuel Type:
Powertrain segmentation tracks energy source diversification and regulatory pressure on emissions verification across BSN roadworthiness protocols.
- Petrol:Spark-ignition internal combustion engines dominate refurbishment economics with established spare parts supply chains through Ministry of Industry local content networks. Java's dense service infrastructure supports rapid reconditioning turnaround.
- Diesel:Compression-ignition configurations retain torque advantages for commercial pickup and SUV applications in Kalimantan mining corridors.
- Electric:Battery-electric powertrains face resale liquidity constraints pending standardized health verification protocols from BSN.
- Hybrid:Dual-mode petrol-electric systems accumulate in Greater Jakarta fleet retirements with battery degradation uncertainty suppressing secondary pricing.
Petrol retains volume leadership. Hybrid inventory climbs fastest as early fleet adoptions complete depreciation cycles.
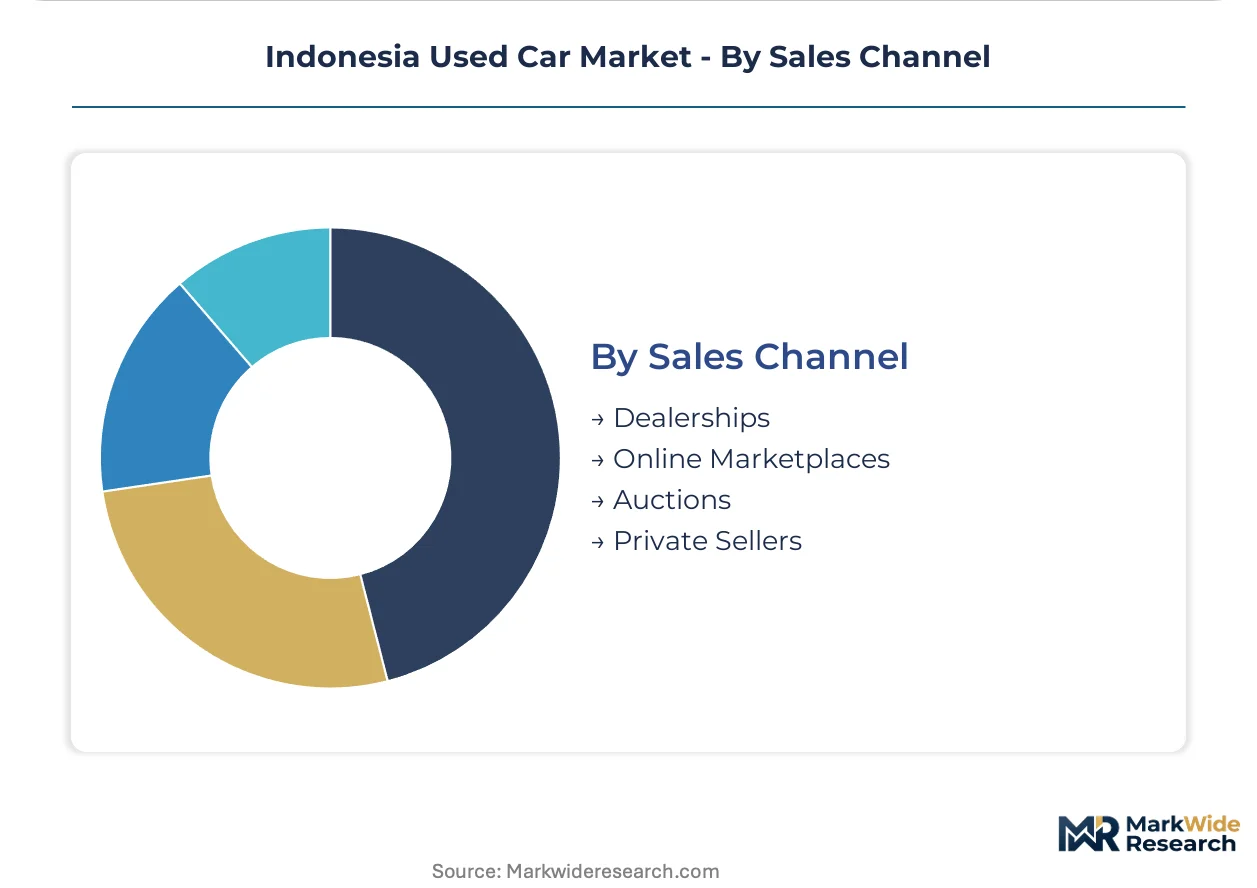
Sales Channel:
Channel structure determines search friction, price transparency, and working capital requirements for inventory holders.
- Dealerships:Physical lot operations with captive financing integration provide test drive access and immediate title transfer in major metros. PT Tunas Ridean Tbk and consolidated Astra-affiliated networks leverage scale for compliance overhead absorption.
- Online Marketplaces:Smartphone-native discovery platforms collapse geographic search boundaries for dispersed archipelago buyers. Carsome Indonesia deploys inspection infrastructure to standardize remote condition reporting without physical site visits.
- Auctions:Time-bound competitive bidding concentrates fleet disposal volumes from Surabaya and Bandung corporate operators.
- Private Sellers:Direct owner-to-buyer negotiation eliminates intermediary margins but complicates service history verification.
Dealerships anchor transaction value. Online marketplaces gain share fastest through mobile payment rail integration and logistics network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's archipelago geography creates distinct used car supply-demand imbalances. Java dominates transaction volume while outer islands face inventory shortages and logistics bottlenecks. The Ministry of Industry's local content mandates shape spare parts availability across regional refurbishment networks.
Greater Jakarta
Ride-hailing fleet operators drive vehicle refresh cycles at scale. OJK consumer finance regulations concentrate certified pre-owned demand in this metro. Depok and Tangerang satellite cities host emerging digital auction infrastructure.
East Java
Surabaya anchors secondary market liquidity for eastern Indonesia. Surabaya's port connectivity enables cross-archipelago vehicle redistribution. Gresik industrial zones support reconditioning parts manufacturing under local content rules.
West Java
Bandung's narrow urban corridors favor compact hatchback transactions. Suburban dealership networks expand into Cimahi and Sumedang regencies. Bandung's tech workforce accelerates mobile-first marketplace adoption.
North Sumatra
Medan serves as Sumatra's primary used car redistribution hub. Plantation and logistics fleets create commercial pickup demand. Medan's dealer infrastructure lags Java, creating working capital gaps for inventory financing.
South Sulawesi
Makassar represents underdeveloped terrain with first-mover potential. Mobile inspection units address dispersed buyer populations across Sulawesi. Regional logistics hubs remain sparse, compressing price discovery efficiency.
Indonesia Used Car Market Competitive Environment
On the supply side, the industry is bifurcated between integrated platform operators and fragmented dealership networks. Consolidated players capture premium pricing through captive financing and inspection standardization. Two strategic archetypes dominate: vertically integrated marketplace platforms and manufacturer-affiliated dealer networks. Competitive moves center on logistics network expansion and embedded inventory financing integration.
Within the platform archetype, Carsome Indonesia and Moladin exemplify asset-light models that collapse transaction friction through digital infrastructure. PT Tunas Ridean Tbk anchors the captive financing tier through its Astra International distribution affiliation. These three occupy distinct competitive positions: Carsome Indonesia represents inspection-standardized marketplace scale, Moladin exemplifies dealer management system integration, and PT Tunas Ridean Tbk embodies manufacturer-tied financing depth.
| Leading Market Players |
|---|
| Carsome Indonesia |
| PT Tunas Ridean Tbk |
| OLX Indonesia |
| Carmudi Indonesia |
| Broom.id |
| Mobil88 |
| Toyota Astra Motor |
| Moladin |
| Carro Indonesia |
| Others |
Value Chain & Pricing Dynamics
ASEAN spare parts corridors concentrate reconditioning component supply for Indonesia's refurbishment networks, anchoring margin pools in certified pre-owned channels with verified service histories and OJK-compliant documentation. Fleet operators in Jakarta and Surabaya capture residual value premiums through standardized inspection protocols, while informal as-is channels absorb price compression from logistics volatility and thin-file borrower constraints.
Pricing Analysis
First-time buyers anchor Indonesia's used car pricing structure around condition-graded tiers. Three-tier pricing structure across certified pre-owned, documented minor damage, and as-is transactions reflects OJK financing eligibility and warranty coverage differentiation. Price pressure intensifies in the entry tier as stringent disclosure standards extend approval timelines for unbanked borrowers. Cash buyers in Sumatra's informal channels exhibit highest price sensitivity, while fleet operators in Greater Jakarta prioritize residual value guarantees over unit cost.
Supply Chain Analysis
Reconditioning feedstock flows from Thailand, Malaysia, and Singapore into Java's refurbishment hubs. Critical components including engine management systems, transmission assemblies, and collision repair parts draw from ASEAN manufacturing networks. Single-source vulnerability concentrates in specialized diagnostic equipment for hybrid battery assessment. Distribution runs through consolidated dealership networks with captive financing arms and digital marketplace platforms with embedded logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's used car market represents high-growth disruption as OJK regulatory pressure and AI-powered inspection technology simultaneously compress transaction friction and elevate compliance barriers. The intersection of smartphone-native buyer behavior and certified pre-owned standardization creates asymmetric expansion opportunities across the archipelago.
For Market Incumbents: Insulate certified pre-owned positioning through captive technician training pipelines addressing the multi-point inspector shortage threatening scale. Deepen backward integration into refurbishment parts warehousing under Ministry of Industry local content mandates. Lock in fleet disposal volumes from ride-hailing operators through residual value guarantee products that emerging platform competitors cannot replicate.
For New Entrants and Emerging Players: Build out mobile inspection infrastructure targeting Sulawesi and Kalimantan dealer infrastructure gaps before consolidated platforms establish logistics density. Capture working capital-constrained small lot operators through dealer management system-embedded inventory financing. Lead with battery health verification capabilities as BSN protocols for hybrid and electric secondary units unlock first-mover certification premiums.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated marketplace platforms with inspection standardization technology and archipelago logistics networks. Long-term viability over a five-to-ten year horizon hinges on regulatory compliance automation and electric vehicle conversion guideline anticipation. Monitor BSN battery certification protocol announcements as the critical inflection signal for hybrid inventory liquidity unlocking.
| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Inspection Infrastructure Deployment | Addresses certified inspector scarcity across Sulawesi and Kalimantan while collapsing remote assessment costs. |
| Dealer Management System Integration | Embeds inventory financing directly into small lot operator workflows, reducing working capital gaps. |
| Captive Technician Training Pipeline | Secures multi-point assessment capacity for frame integrity and powertrain diagnostics at scale. |
| Battery Health Verification Capability Buildout | Positions for BSN protocol announcements unlocking hybrid and electric certified pre-owned segments. |
| Residual Value Guarantee Product Development | Captures fleet refresh volumes from Jakarta and Surabaya ride-hailing operators through asset-light structures. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with used car marketplace executives, fleet operations managers at ride-hailing platforms, dealership network heads, OJK regulatory affairs specialists, and refurbishment facility operators; and secondary validation through OJK consumer finance disclosure filings, Ministry of Industry local content compliance records, BSN vehicle safety standards documentation, and ASEAN automotive trade flow databases. Bottom-up transaction volume modeling triangulated against top-down macroeconomic consumption projections.
Forecast inputs considered vehicle type segmentation across SUV, sedan, hatchback, and pickup configurations; condition tiers spanning certified pre-owned through as-is transactions; fuel type evolution from petrol dominance toward hybrid accumulation; and sales channel migration from physical dealerships to smartphone-native marketplaces. CAGRs derived from regression analysis against vehicle ownership penetration, financing accessibility indices, and digital payment rail expansion across the projection horizon. Hybrid inventory depreciation cycles and battery health verification protocol timelines served as industry-specific demand shifters.
Sensitivities concentrate around BSN electric vehicle conversion guideline timing, OJK disclosure standard enforcement intensity, and ASEAN spare parts corridor logistics stability. Cross-checking against OJK consumer credit provisioning statistics and Ministry of Industry local content compliance audits is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Finland Used Car Market
Used Vehicles
Malaysia Used Car Market
Used Vehicles
Myanmar Used Car Market
Used Vehicles
Oman Used Car Market
Used Vehicles
Japan Used Car Market
Used Vehicles
Middle East and Africa Used Car Market
Used Vehicles
Online Car Buying Market
Used Vehicles
Europe Used Car Market
Used Vehicles
North America Used Truck Market
Used Vehicles
Russia Used Car Market
Used Vehicles
India Used Car Market
Used Vehicles
Kenya Used Car Market
Used Vehicles
Global Online Second-Hand Car Trading Service Market
Used Vehicles
Vintage Car Market
Used Vehicles
Portugal Used Car Market
Used Vehicles
Vietnam Used Car Market