
 Global Wireless Doorbells Market | 2026-2036
Global Wireless Doorbells Market Size, Share, and Industry Trends Forecast 2026-2036
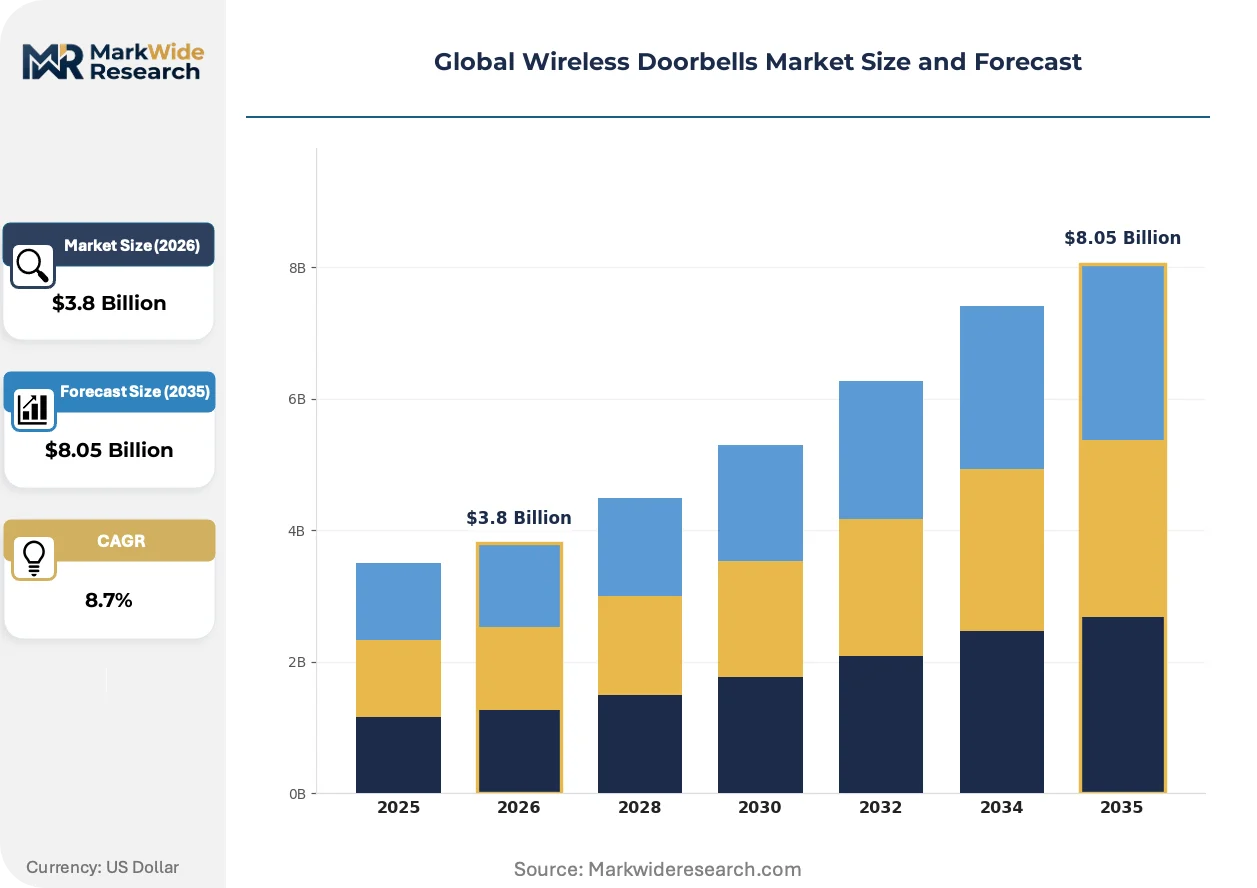
Global Wireless Doorbells Market Outlook
Asset-light leasing models for smart home infrastructure is fragmenting competitive barriers in the wireless doorbells sector. Ring leverages its cloud-connected ecosystem to sustain recurring revenue streams beyond hardware sales. Honeywell International anchors its position through backward integration into security system protocols. Panasonic competes on manufacturing scale across RF and Wi-Fi enabled product lines.
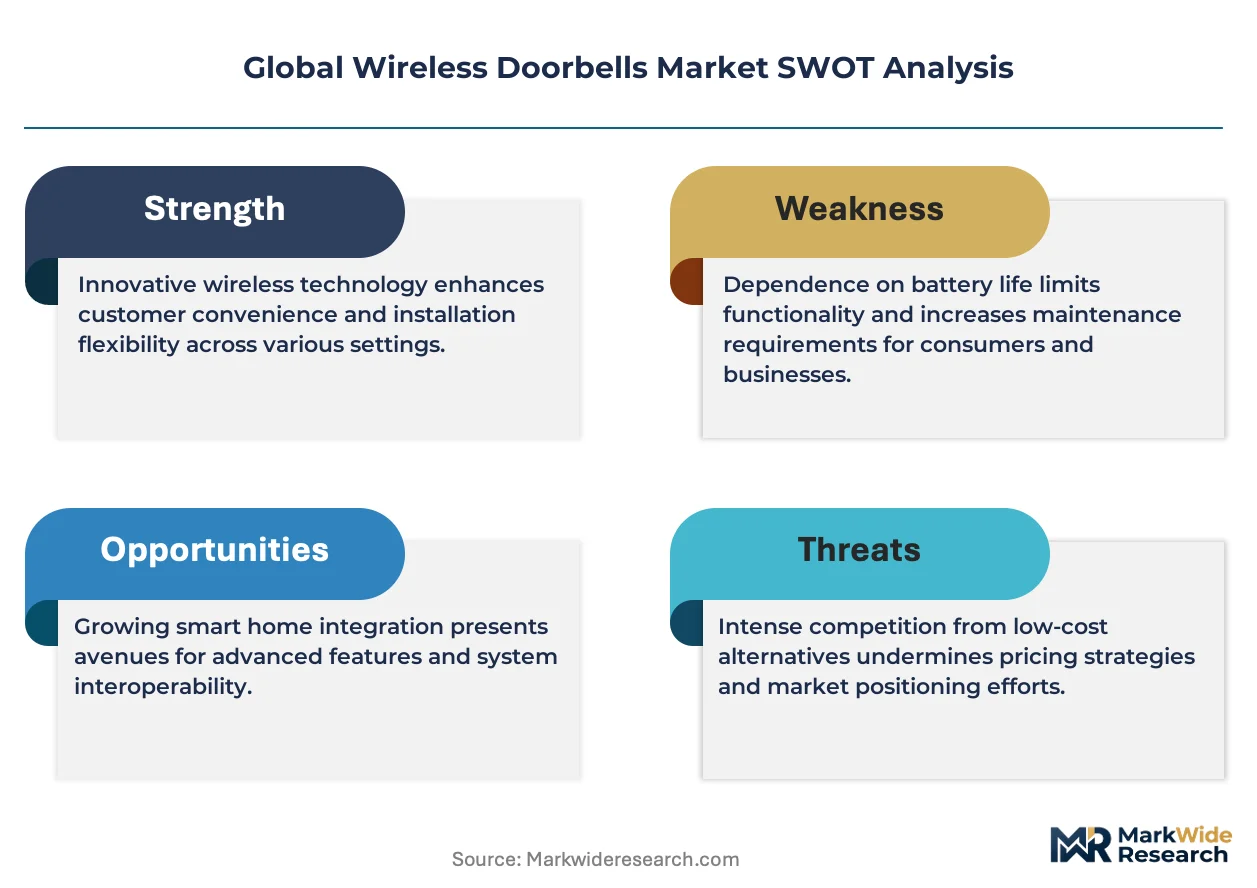
Wireless doorbells are battery-operated or mains-powered signaling devices that transmit audio and video alerts via radio frequency, Wi-Fi, or Bluetooth protocols to indoor receivers or mobile applications, typically operating on 2.4 GHz bands with motion detection ranges of 15-30 feet. Video doorbells dominate value capture due to subscription-backed cloud storage margins, while battery-powered units lead volume growth in retrofit residential installations across North America and Asia-Pacific. Smart doorbells integrating AI-powered person detection command premium positioning, whereas RF technology segments serve price-sensitive markets with simpler relay architectures.
FCC Part 15 rules in the United States, CE marking under the EU Radio Equipment Directive, and China's SRRC certification collectively shape transmission power limits, encryption mandates, and market access protocols for cross-border manufacturers. Ecodesign requirements from the EU Green Deal are pressing battery-powered suppliers toward rechargeable lithium-ion architectures and reduced standby consumption. Stakeholders must monitor evolving cybersecurity labeling schemes and interoperability standards as smart home platforms consolidate around Matter protocol adoption.
Market Dynamics
Smart home platform consolidation is collapsing standalone product architectures as Matter protocol adoption forces interoperability mandates across previously siloed ecosystems.
Growth Catalysts
- FCC Part 15 Certification:Streamlined radio frequency equipment approval in the United States accelerates time-to-market for Wi-Fi enabled doorbell manufacturers seeking retail distribution.
- Residential Property Development:Pre-installation of wireless doorbell infrastructure in new construction across suburban clusters in China and Germany locks in hardware specifications before consumer purchase decisions.
- Cloud Storage Subscription Models:Recurring revenue from video archival services shifts unit economics toward lifetime value calculations rather than one-time hardware margins.
Market Restraints
- Lithium-Ion Battery Supply Concentration:Dependence on cylindrical cell production concentrated in East Asian manufacturing clusters creates input cost volatility for battery-powered unit suppliers.
- EU Ecodesign Standby Limits:The EU Green Deal's power consumption thresholds for networked standby mode force hardware redesign cycles that compress margin structures.
- RF Interference Limitations:2.4 GHz spectrum congestion in dense urban environments degrades signal reliability, limiting deployment effectiveness in multi-dwelling residential complexes.
Strategic Opportunities
- India Smart City Infrastructure:Government-backed urban modernization programs create procurement channels for integrated security hardware in municipal residential developments.
- AI-Edge Processing Convergence:On-device person detection algorithms eliminate cloud latency and reduce subscription dependency for privacy-sensitive consumer segments.
- Insurance Premium Incentives:Homeowner policy discounts for verified video doorbell installation in the United States create pull-through demand from underpenetrated rural markets.
Industry Challenges
- Cybersecurity Certification Timelines:UL 2900 and IEC 62443 evaluation periods extend product launch schedules by 4-6 months for manufacturers seeking enterprise channel access.
- Legacy Protocol Integration:Backward compatibility requirements with proprietary RF ecosystems from established security system installers complicate firmware architecture decisions.
- Field Installation Skill Gaps:Shortage of technicians trained in low-voltage wiring and Wi-Fi mesh optimization limits service coverage expansion in secondary metropolitan areas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wireless Doorbells Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Doorbells, Smart Doorbells, Battery-Powered Doorbells, Wired Doorbells Technology: Wi-Fi, Bluetooth, Wired, RF End User: Residential, Commercial, Retail, Industrial Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesale |
| Companies Covered | Ring, Honeywell International, Aiphone, Panasonic, COMMAX, SkyBell Technologies, 1byone, Legrand, Arlo Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wireless Doorbells Market Strategic Shifts
Three forces are actively restructuring competitive positioning: edge computing migration, regulatory pressure on electromagnetic emissions, and the unbundling of hardware from service monetization.
On-device neural processing units are collapsing the distinction between cloud-dependent and standalone video doorbell categories. Residential consumers in Germany and the United States are adopting edge-AI units at rates that outpace traditional Wi-Fi connected models. This compression eliminates subscription revenue dependence for privacy-focused buyers while raising hardware bill-of-materials costs.
CE marking under the EU Radio Equipment Directive is tightening encryption minimums and transmission power ceilings for products entering European distribution. Manufacturers must redesign RF front-end modules to satisfy updated electromagnetic compatibility testing protocols. Battery-powered segments face the steepest compliance costs as reduced standby consumption mandates conflict with motion detection sensitivity requirements.
Direct-to-consumer channel expansion is fragmenting traditional retail and installer-dominated distribution patterns. Amazon and brand-owned storefronts now capture volume previously routed through electrical wholesalers and security integrators in North America and Western Europe. This disintermediation compresses margin stacking but forces manufacturers to absorb customer support and installation guidance costs previously borne by channel intermediaries.
Global Wireless Doorbells Market Segmentation
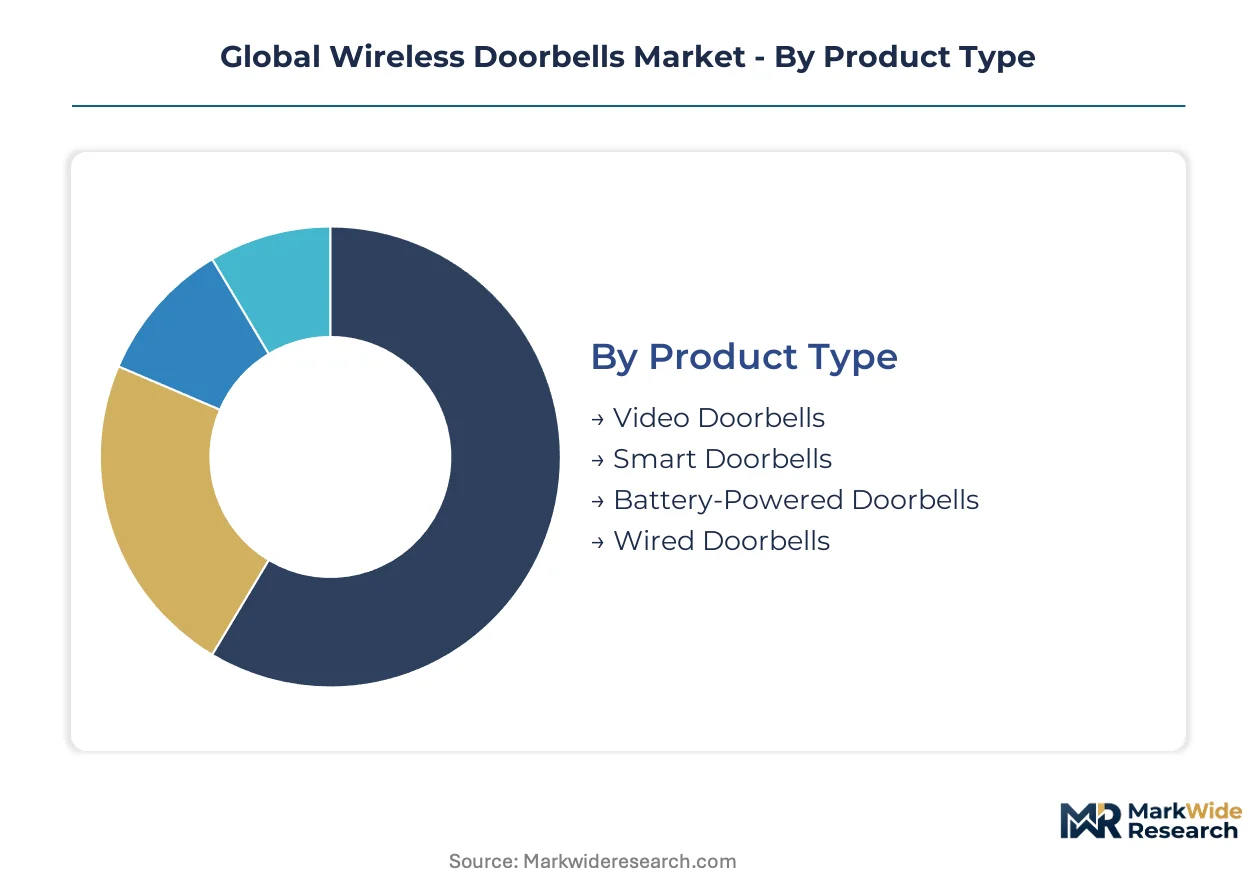
Wireless doorbell segmentation reveals divergent service intensity requirements across product architectures. Battery-powered units demand higher field support density than mains-connected alternatives, while video-enabled systems carry recurring cloud infrastructure obligations that reshape vendor cost structures.
Product Type:
After-sales service intensity varies sharply across product architectures, with cloud-connected systems requiring ongoing subscription management and battery-powered units needing periodic replacement logistics.
- Video Doorbells:Camera-equipped units transmit encrypted footage via Wi-Fi to mobile applications and indoor displays, typically incorporating two-way audio and night vision capabilities. Demand concentrates in suburban United States and Germany where homeowner insurance incentives offset hardware premiums. Cloud storage subscriptions generate recurring service obligations that extend vendor-customer relationships beyond point-of-sale.
- Smart Doorbells:AI-enabled devices process person detection algorithms locally or via edge-cloud hybrid architectures, integrating with broader home automation ecosystems. Residential developers in China pre-install these units in new construction clusters to differentiate property offerings and lock in platform ecosystems before consumer purchase decisions.
- Battery-Powered Doorbells:Self-contained units eliminate low-voltage wiring requirements, enabling rapid retrofit installation in existing structures.
- Wired Doorbells:Mains-powered devices leverage existing doorbell transformer infrastructure for continuous operation without battery maintenance.
Video doorbells hold the largest share; momentum sits with smart doorbells integrating on-device neural processing.
Technology:
Protocol selection determines regulatory compliance burden and interoperability scope, with Wi-Fi architectures facing stricter electromagnetic emissions testing than simpler RF alternatives.
- Wi-Fi:IEEE 802.11-based connectivity enables high-bandwidth video streaming and cloud integration, typically operating on 2.4 GHz bands with 5 GHz support in premium tiers. FCC Part 15 certification timelines in the United States and CE marking under the EU Radio Equipment Directive impose 4-6 month approval cycles that gate retail distribution.
- Bluetooth:Low-energy protocols support proximity-based pairing with limited range, serving as secondary connectivity for initial device configuration.
- Wired:Physical electrical connections bypass radio frequency regulatory requirements entirely, simplifying certification for traditional chime replacement.
- RF:Proprietary radio frequency protocols operate in unlicensed spectrum bands with simpler relay architectures, dominating price-sensitive retrofit markets.
Wi-Fi dominates value capture; Bluetooth is expanding most quickly as a configuration bridge for multi-protocol ecosystems.
End User:
Application context shapes specification requirements, with commercial deployments demanding centralized management platforms absent in residential single-unit purchases.
- Residential:Individual homeowners and renters prioritize mobile application integration and aesthetic discretion. Battery-powered Wi-Fi units lead volume in North American retrofit installations where landlord restrictions prohibit wiring modifications.
- Commercial:Multi-tenant office buildings and hospitality properties require centralized access logging and integration with building management systems.
- Retail:Storefront applications emphasize theft deterrence through visible camera placement and real-time alert capabilities.
- Industrial:Manufacturing facilities and warehouses utilize ruggedized units with extended temperature tolerance and vandal-resistant housings.
Residential commands absolute volume; commercial applications show steepest expansion trajectory as facility managers consolidate security infrastructure.
Distribution Channel:
Channel selection determines margin stacking depth and customer support burden, with direct sales capturing lifetime value at the cost of acquisition efficiency.
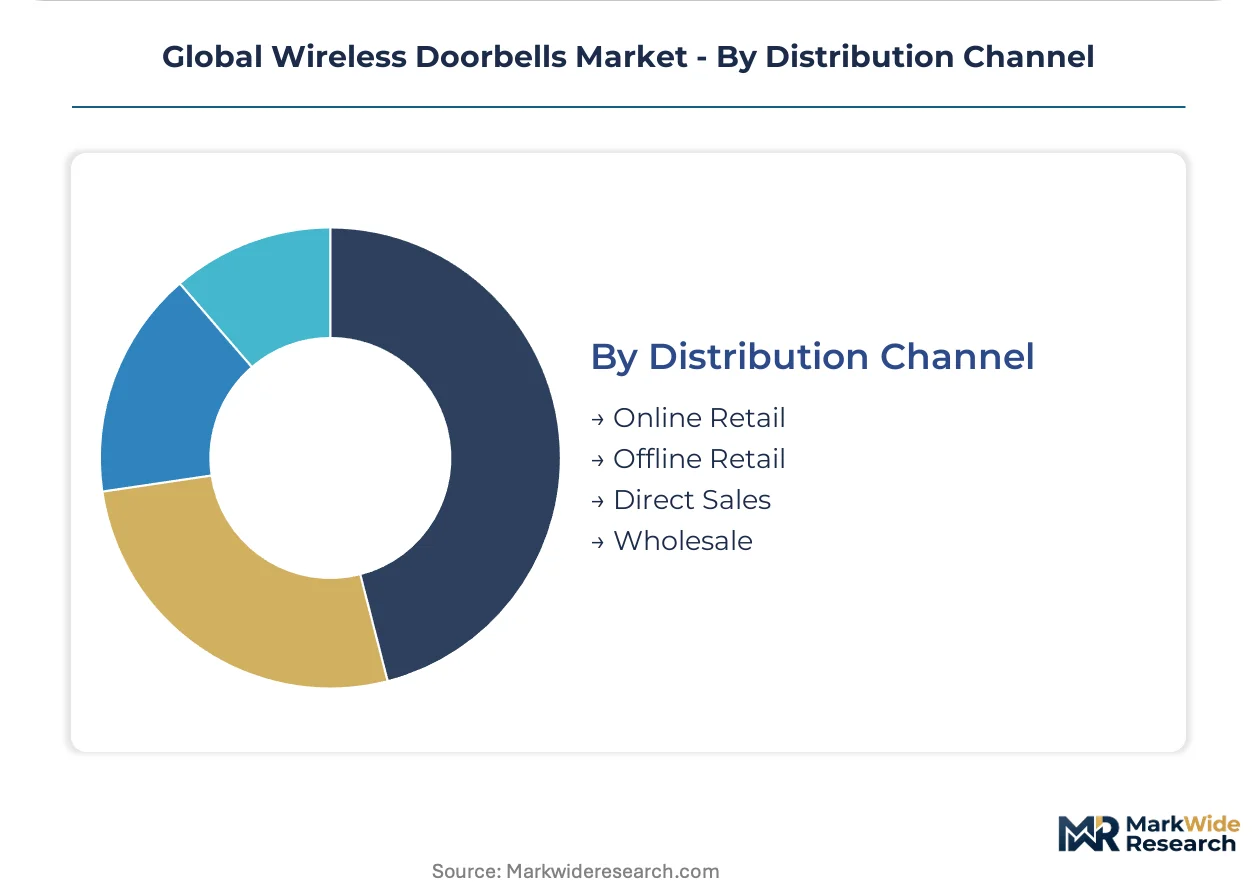
- Online Retail:Amazon and brand-owned storefronts aggregate consumer research behavior and enable subscription attachment at point-of-sale. Direct-to-consumer expansion fragments traditional electrical wholesaler dominance in North America and Western Europe.
- Offline Retail:Big-box home improvement chains and electrical supply houses provide tactile evaluation and immediate availability for time-sensitive replacements.
- Direct Sales:Manufacturer-owned channels absorb customer support and installation guidance costs previously borne by intermediaries.
- Wholesale:Bulk procurement routes serve property developers and security integrators with volume pricing and specification standardization.
Online retail holds the largest share; wholesale is gaining share fastest through pre-installation contracts with residential developers in China and Germany.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor manufacturers with FCC-certified production for North American distribution, while European demand pulls compliant hardware through Rotterdam and Hamburg logistics hubs. China retains component supply dominance, though finished goods trade faces escalating electromagnetic compatibility testing requirements at destination markets.
United States
Homeowner insurance premium discounts for verified video doorbell installation drive retrofit demand across suburban Texas and Florida markets. FCC Part 15 certification timelines average 4-6 months for Wi-Fi enabled units entering retail distribution. Installation technician shortages in secondary metropolitan areas constrain service coverage expansion beyond major coastal corridors.
Germany
Residential property developers in Bavaria and Baden-Württemberg pre-install smart doorbell infrastructure to differentiate new construction offerings. CE marking under the EU Radio Equipment Directive imposes updated encryption minimums and transmission power ceilings. The Rhine-Ruhr industrial cluster hosts component manufacturing for RF front-end modules serving continental distribution.
China
Government-backed smart city programs in Shenzhen and Hangzhou create procurement channels for integrated security hardware in municipal residential developments. SRRC certification mandates shape transmission power limits and market access protocols for domestic manufacturers. The Pearl River Delta concentration supplies cylindrical lithium-ion cells to battery-powered unit assemblers across Asia-Pacific.
India
Rising middle-class homeownership in Maharashtra and Karnataka accelerates demand for battery-powered retrofit units avoiding landlord wiring restrictions. BIS certification requirements for radio equipment tighten quality thresholds for imported hardware. The Delhi-NCR corridor concentrates e-commerce fulfillment infrastructure supporting direct-to-consumer channel expansion.
United Kingdom
Post-rental renovation activity in Greater London and the Southeast drives replacement of traditional wired chimes with wireless alternatives. GDPR compliance obligations shape cloud storage subscription terms for video doorbell service providers. The Midlands manufacturing base produces RF relay components for price-sensitive European export markets.
Global Wireless Doorbells Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying RF modules and imaging sensors to branded assemblers. Market structure fragments across three tiers: cloud-connected ecosystem providers, security system incumbents with installer relationships, and contract manufacturers serving private-label retailers. Strategic archetypes include subscription-dependent platform builders, backward-integrated security conglomerates, and scale-driven electronics fabricators. Dominant competitive moves encompass direct-to-consumer channel expansion and pre-installation contracting with residential developers.
Within the platform-integrator tier, Ring and Arlo Technologies exemplify cloud-connected ecosystem approaches with recurring revenue architectures. Honeywell International occupies a position bridging security system heritage with smart home convergence. Panasonic sits within the scale-driven manufacturing archetype, leveraging production breadth across RF and Wi-Fi enabled product lines.
| Leading Market Players |
|---|
| Ring |
| Honeywell International |
| Aiphone |
| Panasonic |
| COMMAX |
| SkyBell Technologies |
| 1byone |
| Legrand |
| Arlo Technologies |
| Others |
Value Chain & Pricing Dynamics
Lithium-ion battery supply concentration in East Asian manufacturing clusters determines both tiered hardware margins and procurement geography for wireless doorbell assemblers. FCC certification timelines and EU Ecodesign standby limits compound input cost volatility with compliance-driven redesign cycles that compress pricing flexibility across battery-powered and mains-connected product lines.
Pricing Analysis
Residential property developers anchor pricing stratification across premium, standard, and economy tiers based on pre-installation contract scale and after-sales service bundling. Wi-Fi enabled video doorbells with cloud subscription attachments command hardware premiums over RF-only alternatives, while battery-powered retrofit units face cost compression from cylindrical cell price volatility. Price differentiation rests on CE marking tier and FCC Part 15 certification status, with enterprise channel buyers exhibiting lowest price sensitivity due to insurance premium incentive offsets. Margins are tightening in entry-level segments as direct-to-consumer channel expansion forces manufacturers to absorb customer support costs previously borne by electrical wholesalers.
Supply Chain Analysis
Tariff exposure between China and destination markets in North America and Europe dominates supply chain risk calculus for finished wireless doorbell assembly. Component sourcing draws from the Pearl River Delta for imaging sensors and RF front-end modules, South Korea for advanced semiconductor content, and domestic US facilities for FCC-certified final configuration. Distribution runs through Rotterdam and Hamburg logistics hubs for European CE-marked inventory, with Shenzhen and Hong Kong anchoring Asia-Pacific fulfillment. Single-source vulnerability concentrates in cylindrical lithium-ion cell supply, while 2.4 GHz spectrum component shortages present secondary chokepoints for Wi-Fi enabled unit production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud storage subscription attachment is expanding faster than hardware unit sales, transforming vendor economics from transactional margins toward recurring lifetime value calculations. This service-layer acceleration favors stakeholders who integrate subscription management infrastructure ahead of pure hardware scale.
For Market Incumbents: Pre-empt platform disintermediation by deepening backward integration into AI-edge processing chipsets and Matter protocol certification stacks. Incumbents must consolidate installer channel relationships before direct-to-consumer brands capture pre-installation contracts with residential developers in China and Germany. Certification investment in UL 2900 and IEC 62443 cybersecurity standards represents the critical defensive lever for enterprise channel access. For New Entrants and Emerging Players: Establish a beachhead in India's battery-powered retrofit segment where BIS certification barriers remain lower than FCC or CE marking requirements. New entrants should target Maharashtra and Karnataka residential clusters where landlord wiring restrictions create organic demand for self-contained units. A direct-to-consumer go-to-market angle through Delhi-NCR e-commerce infrastructure bypasses traditional electrical wholesaler gatekeepers. For Investors and Strategic Acquirers: RF module specialists with captive imaging sensor partnerships represent the priority acquisition archetype for platform integrators seeking hardware cost control. Long-term viability in this market hinges on subscription attach rates rather than unit shipment growth, making service infrastructure multiples more durable than hardware revenue streams. Watch for Matter protocol adoption inflection as the signal indicating which ecosystem bets will consolidate smart home platform share.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Edge Processing Integration | On-device neural processing eliminates cloud latency for privacy-sensitive German and US residential buyers. |
| Matter Protocol Certification | Interoperability mandates collapse standalone product architectures into consolidated smart home ecosystems. |
| Pre-Installation Developer Contracts | Hardware specification lock-in with Bavaria and Shenzhen property developers captures volume before consumer purchase decisions. |
| Cybersecurity Certification Investment | UL 2900 and IEC 62443 compliance gates enterprise channel access and extends product launch timelines by months. |
| Direct-to-Consumer Channel Expansion | Amazon and brand-owned storefronts fragment electrical wholesaler dominance while forcing customer support cost absorption. |
Study Parameters
Initial hypotheses were tested against primary input from smart home platform engineers, residential property development procurement leads, low-voltage installation technicians, and security system integrators and refined through secondary validation against FCC equipment authorization databases, EU Radio Equipment Directive compliance registries, SRRC certification filings, and customs trade data for RF module and imaging sensor flows. Bottom-up unit economics modeling triangulated with top-down market sizing across product type, technology protocol, end-use application, and distribution channel segmentation dimensions.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning video versus audio-only architectures, Wi-Fi versus RF versus Bluetooth connectivity, residential versus commercial end-use, and online versus offline channel routes. CAGRs were derived from installed base growth rates, replacement cycle assumptions, and new construction penetration curves, with lithium-ion cell supply constraints and cybersecurity certification timelines incorporated as industry-specific forecast inputs.
Stress conditions across cylindrical battery input costs, FCC and CE marking approval duration variability, and 2.4 GHz spectrum congestion thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding Matter protocol adoption velocity and insurance premium incentive expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Home Security Market
Security and Surveillance
North America Wireless Monitoring and Surveillance Market
Security and Surveillance
North America People Screening Market
Security and Surveillance
Electronic Alarms Market
Security and Surveillance
Global X-Ray Security Scanner Market
Security and Surveillance
Europe Security Services Market
Security and Surveillance
Global Security Advisory Services Market
Security and Surveillance
5G-Enhanced Surveillance Market
Security and Surveillance
Latin America Security Services Market
Security and Surveillance
Night Vision Scopes Market
Security and Surveillance
Cargo and Vehicle Screening Market
Security and Surveillance
Stadium Security Market
Security and Surveillance
Global Threat Intelligence Management Market
Security and Surveillance
Home Security Solution Market
Security and Surveillance
Lawful Interception Market
Security and Surveillance
Airport Baggage Screening Systems Market