
 Afterburner Market | 2026-2036
Afterburner Market Size, Share, and Industry Trends Forecast 2026-2036
Afterburner Market Analysis
Military aviation is repositioning the afterburner market toward next-generation combat aircraft requirements. Pratt & Whitney leverages its vertical integration across turbine blade casting and final assembly to sustain dominance in fighter engine supply chains. Rolls-Royce Holdings anchors European sovereign capability through its UK-based military propulsion division, while SE Ivchenko-Progress competes on cost-engineered architectures for Eastern European and Asian air forces.
An afterburner is a secondary combustion chamber installed aft of a gas turbine engine's turbine section, injecting additional fuel into the exhaust stream to raise exhaust gas temperatures beyond 1,700°C and generate supplemental thrust for supersonic flight regimes. The device operates by re-igniting oxygen-rich exhaust gases through flameholder arrays, enabling combat aircraft to achieve Mach 2+ dash speeds without enlarging core engine dimensions. Turbofan afterburner configurations command the largest value share given their integration into modern fighter propulsion systems where bypass ratio optimization demands sophisticated exhaust mixing. Scramjet afterburning technology represents the fastest-expanding segment, though from a minimal base, as hypersonic weapons programs in the United States, Russia, and Australia drive investment in airframe-integrated supersonic combustion architectures where traditional turbomachinery gives way to ram-accelerated flow paths.
The FAA and EPA jointly shape commercial afterburner development through Stage 5 noise standards and CO2 emissions benchmarks that constrain civilian supersonic applications, while military procurement operates under DoD MIL-STD-810 environmental qualification and ITAR export control frameworks. China's MIIT and SAMR enforce domestic content requirements on afterburner alloys and coatings, fragmenting supplier access for Western component producers. Stakeholders must monitor scramjet transition timelines and sovereign content mandates to calibrate technology licensing and joint venture exposure across divergent regulatory blocs.
Market Dynamics
Hypersonic weapons programs are compressing scramjet afterburner development timelines, forcing traditional turbofan suppliers to retool for airframe-integrated supersonic combustion architectures that bypass conventional turbomachinery entirely.
Growth Catalysts
- EU Green Deal emissions benchmarks:The framework is accelerating combustion efficiency investments as European defense contractors retrofit existing fighter fleets with lower-NOx afterburner injectors to maintain operational clearance.
- China's domestic fighter production:Shenyang Aircraft Corporation and Chengdu Aircraft Corporation are expanding captive engine foundry capacity, creating sustained demand for high-temperature alloy flameholder assemblies.
- Scramjet propulsion maturation:Ram-accelerated flow path architectures are displacing traditional turbofan afterburners in hypersonic cruise missile applications across United States, Russia, and Australian defense programs.
Market Restraints
- Superalloy supply concentration:Single-crystal turbine blade casting capacity clusters in United States, United Kingdom, and Russia, creating chokepoints for niobium-rhenium alloy procurement.
- ITAR export controls:United States Department of State restrictions fragment component sourcing for non-NATO customers, forcing parallel supply chain development.
- Technical ceiling on turbofan architectures:Turbine inlet temperature limits near 1,700°C constrain thrust augmentation without transitioning to scramjet or combined-cycle systems.
Strategic Opportunities
- India's indigenous engine programs:The DRDO-HAL Kaveri derivative and AMCA powerplant initiatives create openings for joint ventures in ceramic matrix composite afterburner liners.
- Directed energy weapon integration:Laser-equipped fighter platforms require modified exhaust nozzle geometries, generating retrofit demand for variable-geometry afterburner assemblies.
- Australian hypersonic test infrastructure:The Woomera Range Complex and Queensland Hypersonics Precinct offer flight-test partnerships for scramjet qualification outside United States regulatory umbrellas.
Industry Challenges
- Computational fluid dynamics talent scarcity:Supersonic combustion modeling expertise concentrates in national laboratories and select university programs, constraining private-sector simulation capacity.
- Flight-test certification timelines:Full-scale afterburner qualification demands hundreds of hours in altitude test facilities, compressing program schedules for next-generation combat aircraft.
- Legacy platform sustainment:Fourth-generation fighter operators require obsolescence-managed spare sourcing as original equipment manufacturers prioritize sixth-generation development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Afterburner Market |
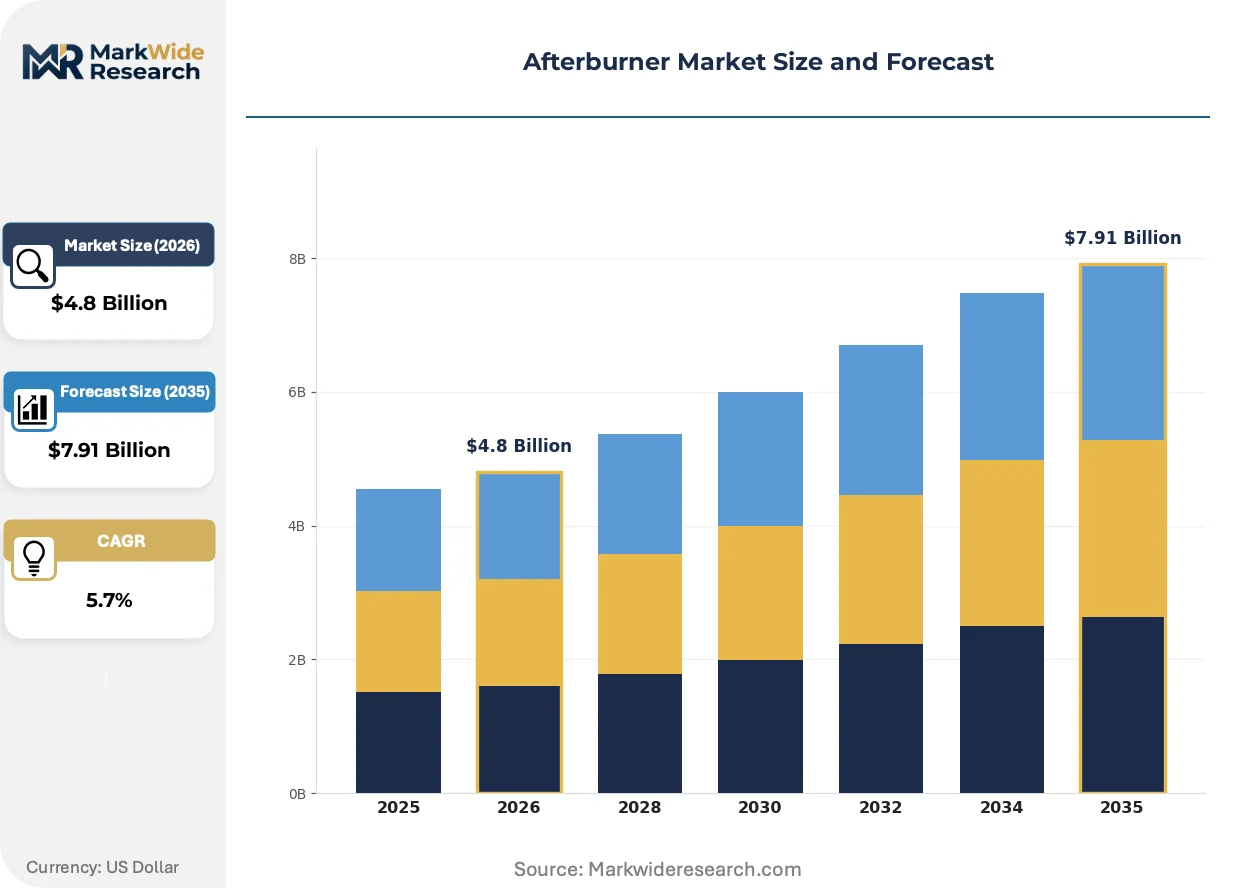
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turbojet, Turbofan, Pulse Detonation, Scramjet End User: Military Aviation, Commercial Aviation, Research Institutions, Aero-Engine Manufacturers Application: Aircraft Propulsion, Space Launch, Hybrid Engines, Test Facilities Technology: Advanced Propulsion, Exhaust Management, Combustion Efficiency, Noise Reduction |
| Companies Covered | General Electric, Pratt & Whitney, Rolls-Royce Holdings, Honeywell International, Safran, Raytheon Technologies, GE Aviation, SE Ivchenko-Progress, Aviadvigatel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Afterburner Market Emerging Trajectories
Additive manufacturing is rewriting afterburner component economics, enabling topology-optimized flameholder geometries that were previously unmachinable through conventional five-axis milling processes.
Directed energy deposition of Inconel 718 is automating the production of complex internal cooling channels in afterburner liners. United States Air Force Research Laboratory and select tier-one suppliers are adopting this process for low-rate initial production of next-generation adaptive cycle engine components. The technology is automating lead time compression from eighteen months to under ninety days for prototype iterations.
REACH restrictions on hexavalent chromium coatings are forcing conversion to aluminum-rich diffusion coatings and ceramic thermal barrier systems across European supply chains. The regulation is accelerating qualification programs for plasma-sprayed yttria-stabilized zirconia in afterburner hot-section applications. French and German engine houses are responding fastest, with production transitions scheduled ahead of 2026 sunset clauses.
Performance-based logistics contracts are displacing traditional spares procurement for military afterburner fleets. United States Naval Air Systems Command and United Kingdom Defence Equipment and Support are unbundling hardware ownership from availability guarantees, transferring operational risk to propulsion system integrators. This model is concentrating most visibly in F-35 Lightning II global sustainment networks, where Pratt & Whitney assumes responsibility for engine module readiness rather than discrete part delivery.
Afterburner Market Segmentation
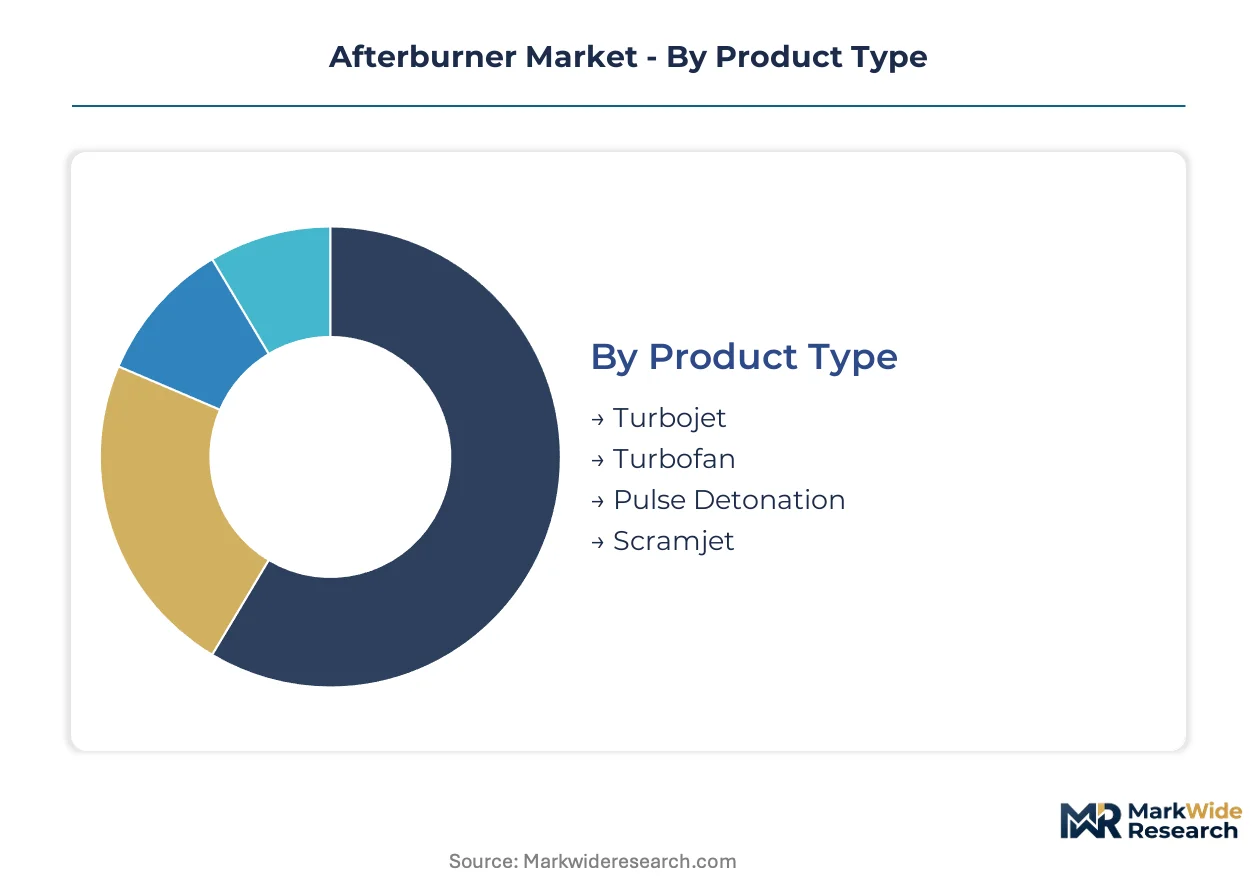
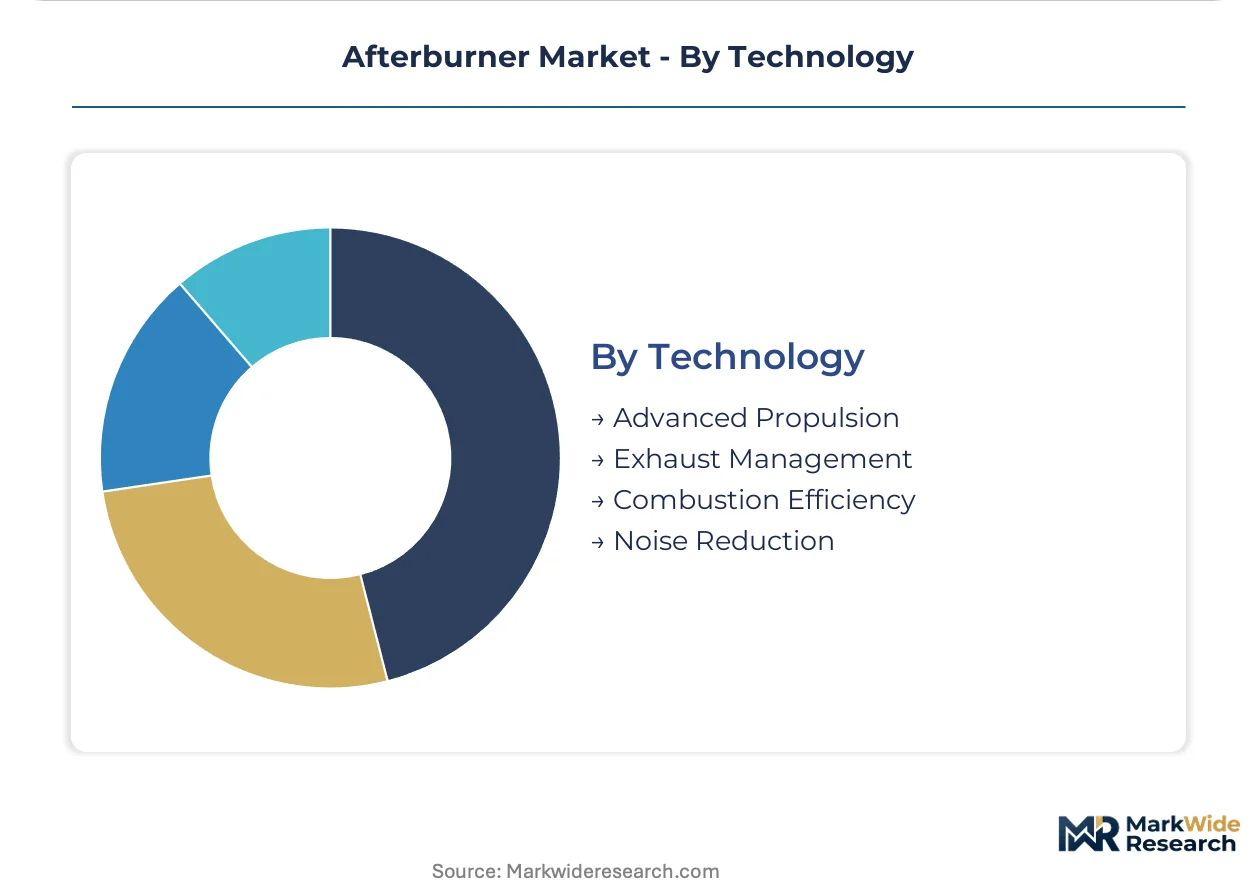
Afterburner architectures fragment across propulsion physics, end-use mission profiles, and thermal management technologies. Each segment carries distinct qualification timelines, alloy specifications, and regulatory exposure that reshape supplier economics and procurement patterns.
Product Type:
Turbofan configurations command the largest installed base while scramjet systems claim the steepest expansion trajectory.
- Turbofan:Integrates bypass airflow mixing with core exhaust reheat, enabling Mach 2+ dash speeds without core enlargement. Demand concentrates in China's Shenyang and Chengdu fighter production lines where captive foundry capacity is scaling for high-temperature flameholder assemblies.
- Scramjet:Bypasses rotating turbomachinery entirely through ram-accelerated supersonic combustion above Mach 5. United States, Russian, and Australian hypersonic weapons programs are compressing development timelines, forcing traditional suppliers to retool for airframe-integrated architectures.
- Turbojet:Legacy supersonic interceptor propulsion with lower bypass ratios, now limited to sustainment fleets and unmanned target drone applications.
- Pulse Detonation:Cyclic detonation wave combustion promising 15-20% fuel efficiency gains over deflagration-based systems, still in subscale demonstrator phase with no production engine integration.
Today's leader: Turbofan. Tomorrow's challenger: Scramjet.
End User:
Military procurement dominates volume while research institutions drive technology maturation.
- Military Aviation:Fighter engine programs across United States, Europe, and China account for the majority of flameholder and variable-geometry nozzle demand. India's DRDO-HAL Kaveri derivative and AMCA initiatives are opening joint venture opportunities for ceramic matrix composite liner suppliers.
- Research Institutions:National laboratories and university programs concentrate supersonic combustion CFD expertise, constraining private-sector simulation capacity for scramjet qualification. Australian Woomera Range Complex and Queensland Hypersonics Precinct offer flight-test partnerships outside United States ITAR umbrellas.
- Aero-Engine Manufacturers:Pratt & Whitney and Rolls-Royce anchor vertical integration across turbine blade casting and final assembly, though REACH restrictions on hexavalent chromium coatings are forcing European transitions to aluminum-rich diffusion systems.
- Commercial Aviation:FAA Stage 5 noise standards and EPA CO2 benchmarks constrain civilian supersonic applications, limiting afterburner deployment to experimental and heritage aircraft operations.
Military procurement sets the technical baseline. Research partnerships unlock next-generation architectures.
Application:
Aircraft propulsion generates recurring revenue while space launch demands disposable hardware economics.
- Aircraft Propulsion:Reusable fighter engine cycles require obsolescence-managed spare sourcing as OEMs prioritize sixth-generation development over fourth-generation sustainment. Performance-based logistics contracts are transferring operational risk to integrators.
- Space Launch:Expendable booster applications tolerate lower cycle life specifications, opening cost-engineered supply from Eastern European and Asian producers.
- Hybrid Engines:Combined-cycle architectures merging turbofan and scramjet modes for reusable hypersonic platforms, still in ground-test phase with no flight-qualified examples.
- Test Facilities:Altitude test cell demand surges with full-scale afterburner qualification requiring hundreds of hours in simulated flight conditions.
Reusable aircraft applications concentrate margin. Expendable launch applications concentrate volume.
Technology:
Combustion efficiency investments are accelerating under emissions mandates while noise reduction lags in military priority.
- Combustion Efficiency:Lower-NOx afterburner injectors are retrofitting European fighter fleets to maintain EU Green Deal operational clearance. Additive manufacturing of topology-optimized flameholder geometries is compressing prototype lead times from eighteen months to under ninety days.
- Advanced Propulsion:Adaptive cycle engines with variable bypass ratios demand sophisticated exhaust mixing architectures, requiring new qualification protocols.
- Exhaust Management:Laser-equipped fighter platforms require modified nozzle geometries, generating retrofit demand for variable-geometry assemblies.
- Noise Reduction:Civilian supersonic constraints limit investment; military applications prioritize thermal signature suppression over acoustic metrics.
Emissions compliance is concentrating combustion investment. Signature management is redirecting exhaust R&D.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting afterburner component sourcing toward jurisdictions with lower compliance burdens on superalloy processing and thermal barrier coating applications.
United States
DoD hypersonic weapons programs and sixth-generation fighter engine development drive demand for scramjet qualification infrastructure. FAA and EPA jointly enforce Stage 5 noise standards and CO2 emissions benchmarks that constrain civilian supersonic applications. Edwards Air Force Base and Arnold Engineering Development Complex anchor flight-test and altitude-test cell capacity for full-scale afterburner certification.
China
Shenyang Aircraft Corporation and Chengdu Aircraft Corporation are expanding captive engine foundry capacity for domestic fighter production lines. MIIT and SAMR enforce domestic content requirements on afterburner alloys and coatings, fragmenting supplier access for Western component producers. Xi'an and Chengdu industrial clusters concentrate high-temperature flameholder assembly manufacturing for the J-20 and J-35 programs.
United Kingdom
Rolls-Royce Holdings anchors European sovereign capability through its UK-based military propulsion division, serving Typhoon and Tempest engine requirements. REACH restrictions on hexavalent chromium coatings are forcing conversion to aluminum-rich diffusion coatings ahead of 2026 sunset clauses. Bristol and Derby manufacturing sites concentrate single-crystal turbine blade casting capacity for NATO fighter engine supply chains.
India
DRDO-HAL Kaveri derivative and AMCA powerplant initiatives create demand for ceramic matrix composite afterburner liner joint ventures. BIS and CEA regulate domestic content thresholds on strategic alloy procurement under defense indigenization mandates. Bangalore and Hyderabad clusters house Gas Turbine Research Establishment facilities and HAL engine divisions developing indigenous fighter propulsion systems.
Australia
Hypersonic weapons research partnerships with the United States and United Kingdom are compressing scramjet development timelines outside ITAR regulatory umbrellas. TGA and national defense procurement frameworks govern technology transfer protocols for dual-use propulsion components. Woomera Range Complex and Queensland Hypersonics Precinct offer flight-test partnerships for scramjet qualification at southern hemisphere latitudes.
Afterburner Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated propulsion system houses commanding fighter engine supply chains while tier-two fabricators serve sustainment and upgrade markets. The vendor base concentrates around three strategic archetypes: vertically integrated engine OEMs with captive casting capacity, national champion suppliers serving sovereign defense requirements, and specialized coating houses qualifying thermal barrier systems under REACH and ITAR frameworks. Dominant competitive moves include backward integration into superalloy recycling streams and strategic partnerships for scramjet ground-test infrastructure access.
Among integrated engine OEMs, General Electric and Pratt & Whitney exemplify the vertically integrated archetype with in-house turbine blade casting and final assembly control. Rolls-Royce Holdings occupies a position representing European sovereign capability through UK-based military propulsion operations. SE Ivchenko-Progress sits within the cost-engineered supplier tier, anchoring Eastern European and Asian air force procurement with architectures optimized for non-NATO operational requirements.
| Leading Market Players |
|---|
| General Electric |
| Pratt & Whitney |
| Rolls-Royce Holdings |
| Honeywell International |
| Safran |
| Raytheon Technologies |
| GE Aviation |
| SE Ivchenko-Progress |
| Aviadvigatel |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed engine foundries in China and Russia anchor supply-side ownership patterns, compressing margin capture for Western component specialists while reinforcing pricing discipline through captive alloy sourcing and ITAR-constrained alternative supplier development.
Pricing Analysis
Distributor margins on aftermarket flameholder assemblies run 12-18 points above direct-to-OEM contract pricing for equivalent superalloy grades. Three-tier pricing structure across flight-qualified, depot-repair, and test-cell tiers separates certified military-grade components from commercial-aerospace equivalents and expendable space-launch hardware. Pricing pressure stems from China's expanding captive foundry capacity, which is displacing Western sourcing for non-NATO air forces. Fourth-generation fighter operators exhibit highest price sensitivity as sustainment budgets compete with sixth-generation procurement programs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Pratt & Whitney and Rolls-Royce final assembly lines, while tier-two fabricators serve obsolescence-managed sustainment markets through distributor networks. Single-crystal turbine blade casting concentrates in the United States, United Kingdom, and Russia, with niobium-rhenium superalloy feedstock drawing from Brazilian and Canadian mining operations. Supply chain risk centers on REACH-mandated coating transitions, which are forcing parallel qualification of aluminum-rich diffusion systems ahead of hexavalent chromium sunset clauses. Distribution runs through defense-procurement frameworks with ITAR-controlled shipping lanes and national-security-cleared logistics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
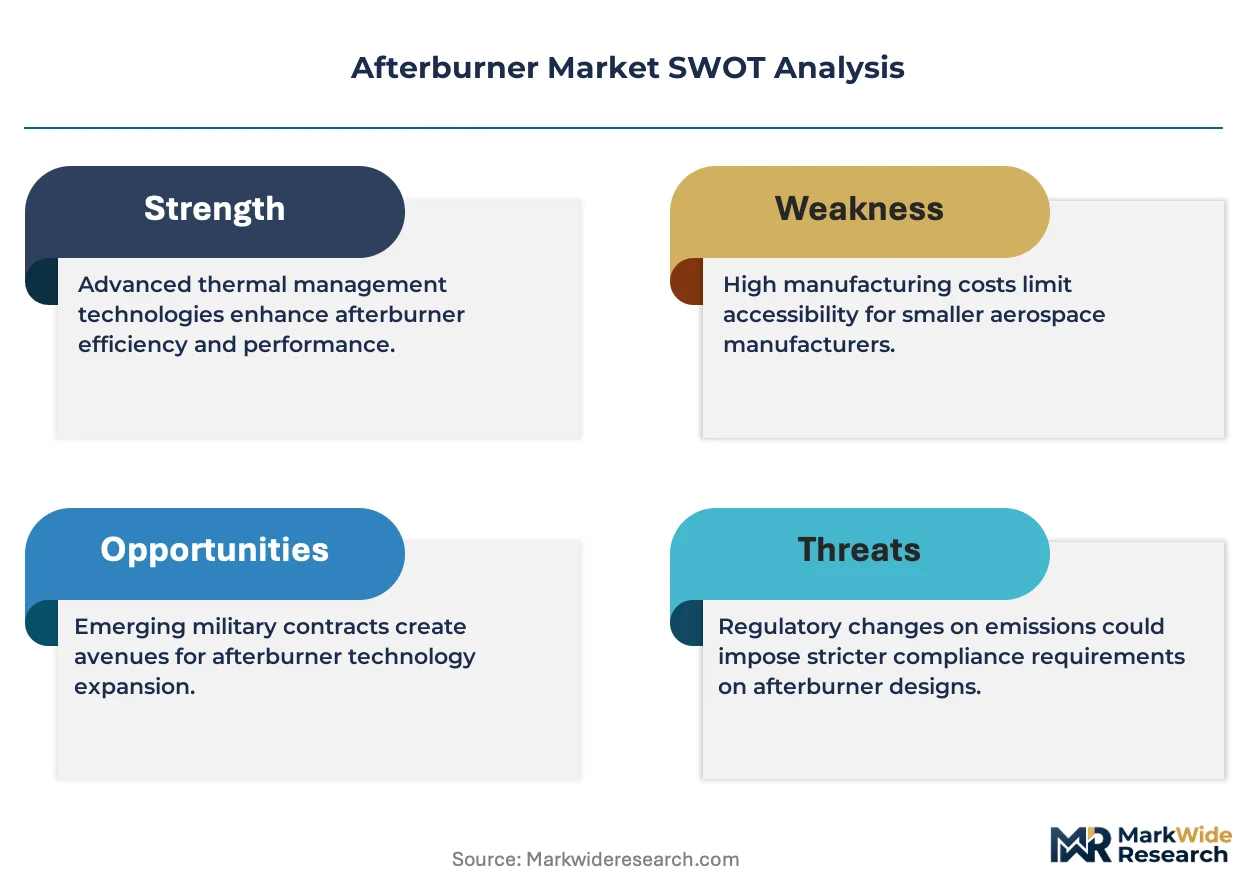
Afterburner market margins are expanding through additive manufacturing lead-time compression and scramjet qualification premiums, even as turbofan commoditization pressures legacy product lines.
For Market Incumbents: Acquire scramjet ground-test infrastructure access to anchor hypersonic weapons program participation against emerging national-laboratory spinouts. Consolidate ceramic matrix composite liner supply through backward integration into precursor fiber production, insulating against REACH-driven coating transition costs and single-source superalloy chokepoints. For New Entrants and Emerging Players: The premium-to-economy tier gap in expendable space-launch afterburner hardware offers entry points for cost-engineered architectures from Eastern European supply bases. Target Australian hypersonic test partnerships outside ITAR umbrellas to build flight-qualification credentials without State Department licensing exposure. Lead with directed energy weapon integration retrofits for F-35 and Typhoon fleets requiring modified exhaust nozzle geometries. For Investors and Strategic Acquirers: Valuations sit cheapest among tier-two coating houses qualifying thermal barrier systems under REACH and ITAR frameworks simultaneously. Five-to-ten-year viability hinges on scramjet transition timelines and sovereign content mandate enforcement intensity. Watch for ITAR waiver expansions or contractions as the primary inflection signal for cross-border joint venture accessibility.| Strategic Initiative | Industry Significance |
|---|---|
| Additive Manufacturing Scale-Up | Topology-optimized flameholder geometries cut prototype lead times from eighteen months to under ninety days at Air Force Research Laboratory facilities. |
| Scramjet Ground-Test Partnership | Woomera Range Complex access enables qualification outside United States ITAR regulatory umbrellas for Australian-United Kingdom-United States hypersonic programs. |
| Ceramic Matrix Composite Integration | DRDO-HAL Kaveri derivative and AMCA initiatives create joint venture demand for afterburner liner suppliers meeting Indian defense indigenization mandates. |
| REACH Compliance Transition | French and German engine houses are accelerating aluminum-rich diffusion coating production transitions ahead of 2026 hexavalent chromium sunset clauses. |
| Performance-Based Logistics Contracting | United States Naval Air Systems Command and United Kingdom Defence Equipment and Support are transferring operational risk to Pratt & Whitney through availability guarantees. |
Methodological Framework
Bottom-up fighter engine program modeling reconciled against top-down superalloy casting capacity tracking forms the analytical core of this study. Primary interviews with propulsion system integrators, defense procurement officers at NAVAIR and DE&S, foundry operations directors, and scramjet qualification engineers were validated against secondary sources including DoD budget justification documents, EU Green Deal implementation timelines, MIIT domestic content circulars, and REACH regulatory filings. Triangulation across these inputs ensures supply-side capacity claims align with disclosed program funding and production rate assumptions.
Historical trendline analysis of turbofan and scramjet development cycles informed projection frameworks across the analysis window. Segmentation modeling incorporated propulsion architecture type, end-use mission profile, thermal management technology tier, and sovereign procurement framework. CAGRs were derived from program-level production rate disclosures and alloy demand coefficients per engine variant. Industry-specific forecast inputs included hypersonic weapons program funding trajectories and adaptive cycle engine transition timelines.
Caveats apply where scramjet technology maturation delays, REACH enforcement intensity variations, or ITAR regime shifts could materially shift the outlook. Forecasts reflect documented program commitments and regulatory phase-in schedules rather than speculative technology adoption curves. Periodic stress-testing of base assumptions against defense budget authorization volatility and superalloy supply disruption scenarios is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Europe Business Jet Market
Aircraft
Turboprop Aircraft Market
Aircraft
Cargo Compartment Latches Market
Aircraft
Wing Inspection and Taxi Lighting Upgrade Kits Market
Aircraft
Anti Rolling Gyro (ARG) Market
Aircraft
Aircraft Jack Market
Aircraft
Airplane Brackets Market
Aircraft
Asia-Pacific Light and Very Light Jets Market
Aircraft
Aircraft Leasing and Rental Market
Aircraft
Commercial Aircraft Overhead Stowage Bins Market
Aircraft
Firefighting Aircraft Market
Aircraft
Global Business Jets Market
Aircraft
Commercial Helicopter Market
Aircraft
Aircraft Mounts Market
Aircraft
Regional Jet Market
Aircraft
Military Aircraft Market