
 Washbasin Market | 2026-2036
Washbasin Market Size, Share, and Industry Trends Forecast 2026-2036
Washbasin Market Analysis
The EU Green Deal is pivoting ceramic basin specifications toward lower-flow compatibility across European residential and hospitality channels. Kohler Co. leverages its captive glaze technology to sustain margin pools in premium wall-mounted lines. TOTO Ltd. anchors its competitive stance through sensor-integrated basin systems for commercial washrooms. Duravit AG differentiates via mineral-cast formulations that compete on weight reduction and thermal retention.
A washbasin constitutes a fixed sanitary fixture engineered for personal hygiene, typically fabricated from vitreous china ceramic with glazed surfaces meeting ISO 9994 water-resistance thresholds, and serves as the central washing station in residential bathrooms, commercial restrooms, and hospitality suites. Wall-mounted basins occupy the dominant share in dense urban residential retrofits where floor-area optimization governs specification. Vessel basins represent the fastest-expanding product type in hospitality and luxury residential segments where above-counter installation creates visual distinction. Ceramic materials command the largest volume position due to cost scalability and regulatory acceptance, while stone and glass alternatives concentrate margin pools in boutique hotel and high-end residential channels.
REACH compliance governs glaze chemistry and surface coating emissions across European manufacturing, while CE marking mandates structural load testing for wall-mounted installations. China's GB standards and MIIT circular-economy directives enforce water-consumption limits and recycled-content thresholds in domestic production. India's BIS certification requires ceramic durability testing for institutional procurement eligibility. Stakeholders must monitor evolving water-efficiency thresholds and material disclosure requirements as procurement specifications harden across regulatory jurisdictions.
Market Dynamics
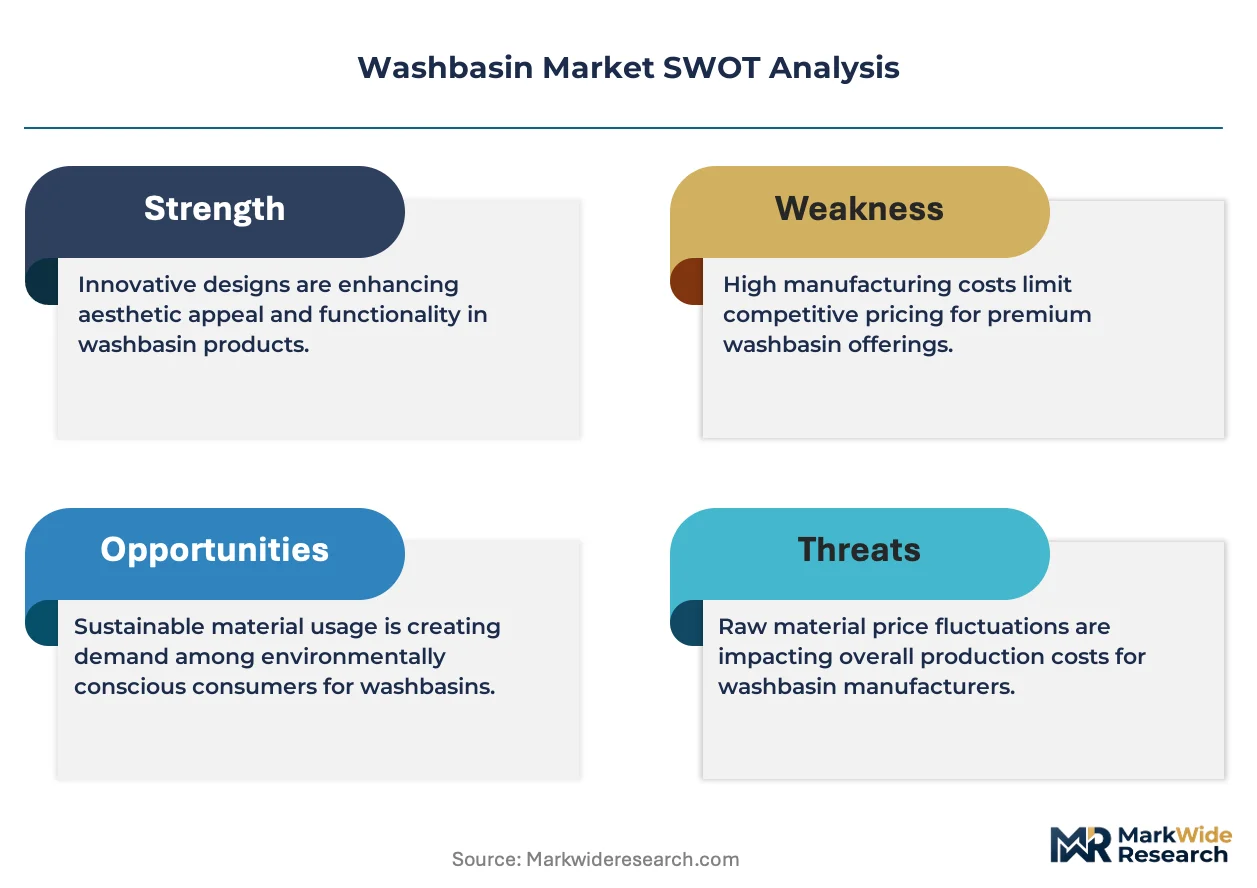
Water-efficiency mandates under the EU Green Deal are compressing ceramic basin specifications toward lower-flow compatibility, forcing manufacturers to reengineer glaze chemistry and fixture geometry while residential renovation activity in Germany, France, and Italy sustains replacement demand.
Growth Catalysts
- EU Green Deal water mandates:The directive forces fixture redesign across European residential and hospitality channels, creating specification pull for compatible basin systems.
- Urban renewal in China:Tier-one city redevelopment projects specify premium vessel and integrated installations, concentrating demand in Shanghai, Beijing, and Shenzhen.
- Mineral-cast material substitution:Weight reduction and thermal retention properties drive adoption in boutique hotel fit-outs seeking installation efficiency.
Market Restraints
- REACH glaze compliance costs:ECHA surface-coating emission thresholds raise formulation expenses for European manufacturers.
- Feldspar supply concentration:Ceramic feedstock dependence on specific mining regions creates input cost volatility.
- Wall-mounted structural limitations:CE marking load-testing requirements restrict design freedom for large-format residential basins.
Strategic Opportunities
- Sensor-integrated commercial systems:Touchless basin technology converges with building management systems in airport and stadium washrooms.
- India institutional procurement:BIS certification requirements create a certified-supplier moat for compliant ceramic producers.
- China MIIT circular-economy directives:Recycled-content thresholds favor domestic manufacturers with captive waste-stream processing.
Industry Challenges
- Glaze chemistry talent scarcity:Formulation expertise for water-resistant vitreous china surfaces concentrates among aging European specialists.
- ISO 9994 testing backlog:Certification queue delays for water-resistance validation extend product launch timelines.
- Legacy plumbing rough-in incompatibility:Vessel basin above-counter installation requires drain relocation in renovation projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Washbasin Market |
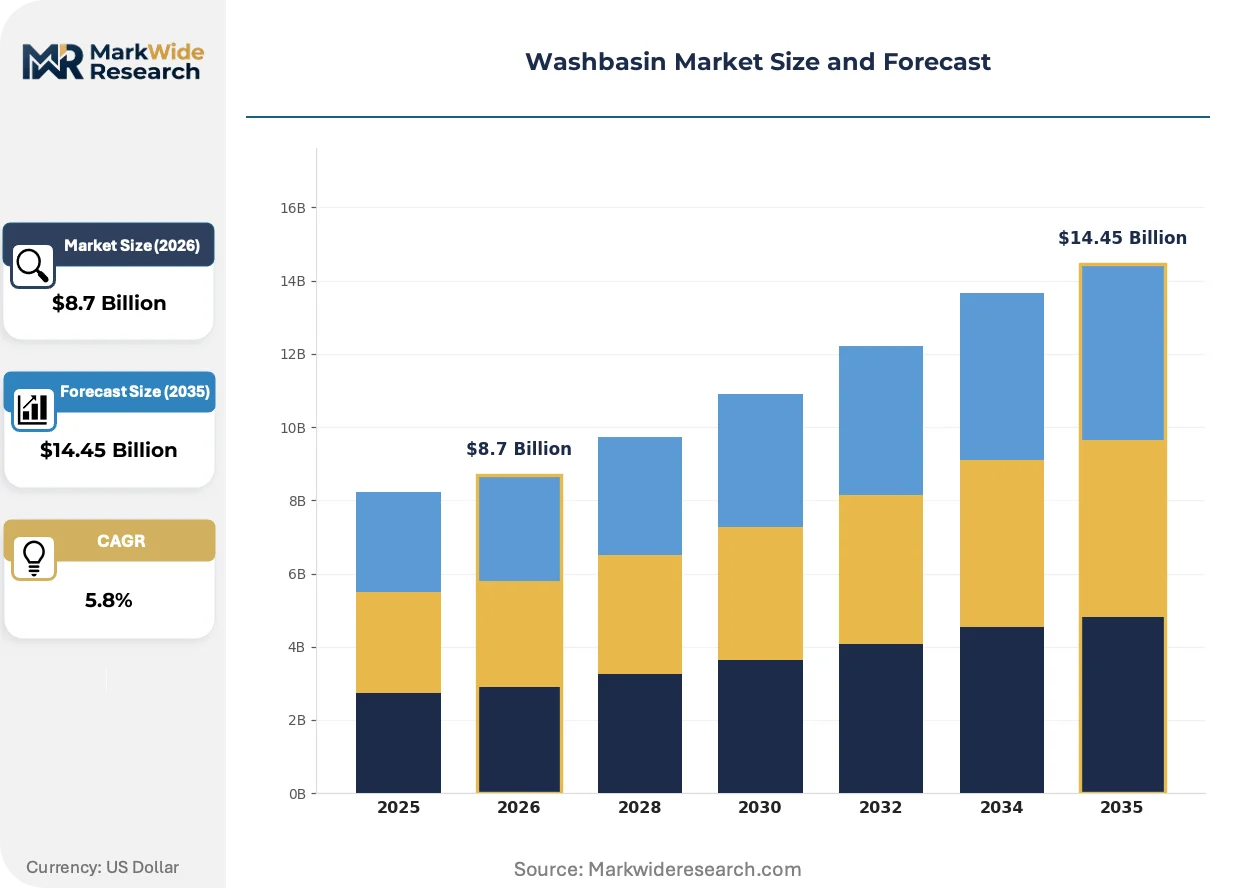
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Countertop, Pedestal, Vessel Material: Ceramic, Glass, Stone, Acrylic Installation Type: Drop-In, Undermount, Above Counter, Integrated End User: Residential, Commercial, Hospitality, Institutional |
| Companies Covered | Kohler Co., TOTO Ltd., Duravit AG, Roca Sanitario S.A., Villeroy & Boch AG, LIXIL Corporation, American Standard Brands, Jaquar Group, Hansgrohe SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Washbasin Market Emerging Trajectories
Digital specification tools and modular installation systems are compressing project timelines while regulatory chemistry constraints force material science investment. Three developments dominate competitive positioning.
Additive manufacturing for basin molds is decentralizing production economics for short-run custom geometries. Boutique hotel chains and luxury residential developers are adopting 3D-printed mold capabilities for project-specific vessel designs. This technology is decentralizing volume concentration away from mass-ceramic producers toward regional fabrication hubs serving localized aesthetic preferences.
REACH compliance deadlines are hardening glaze chemistry disclosure requirements across European manufacturing. ECHA mandates now force full material transparency for surface coatings used in residential installations. German and Italian producers are responding by consolidating captive glaze formulation in-house rather than sourcing from third-party chemical suppliers.
Builder procurement teams are consolidating vendor relationships around full-bathroom system suppliers rather than discrete fixture sourcing. Mid-market residential developers in China's tier-two cities now specify integrated basin-vanity-faucet packages from single manufacturers. This pattern is most visible in Hangzhou and Chengdu where project scale rewards simplified supply chain management.
Washbasin Market Segmentation
Washbasin procurement patterns diverge sharply across installation constraints, material durability requirements, and end-user specification rigor. Understanding these segment boundaries clarifies where manufacturers must align product development with distinct buyer priorities and regulatory exposure.
Product Type:
Buyer differentiation hinges on floor-area constraints versus aesthetic priority in residential and commercial fit-outs.
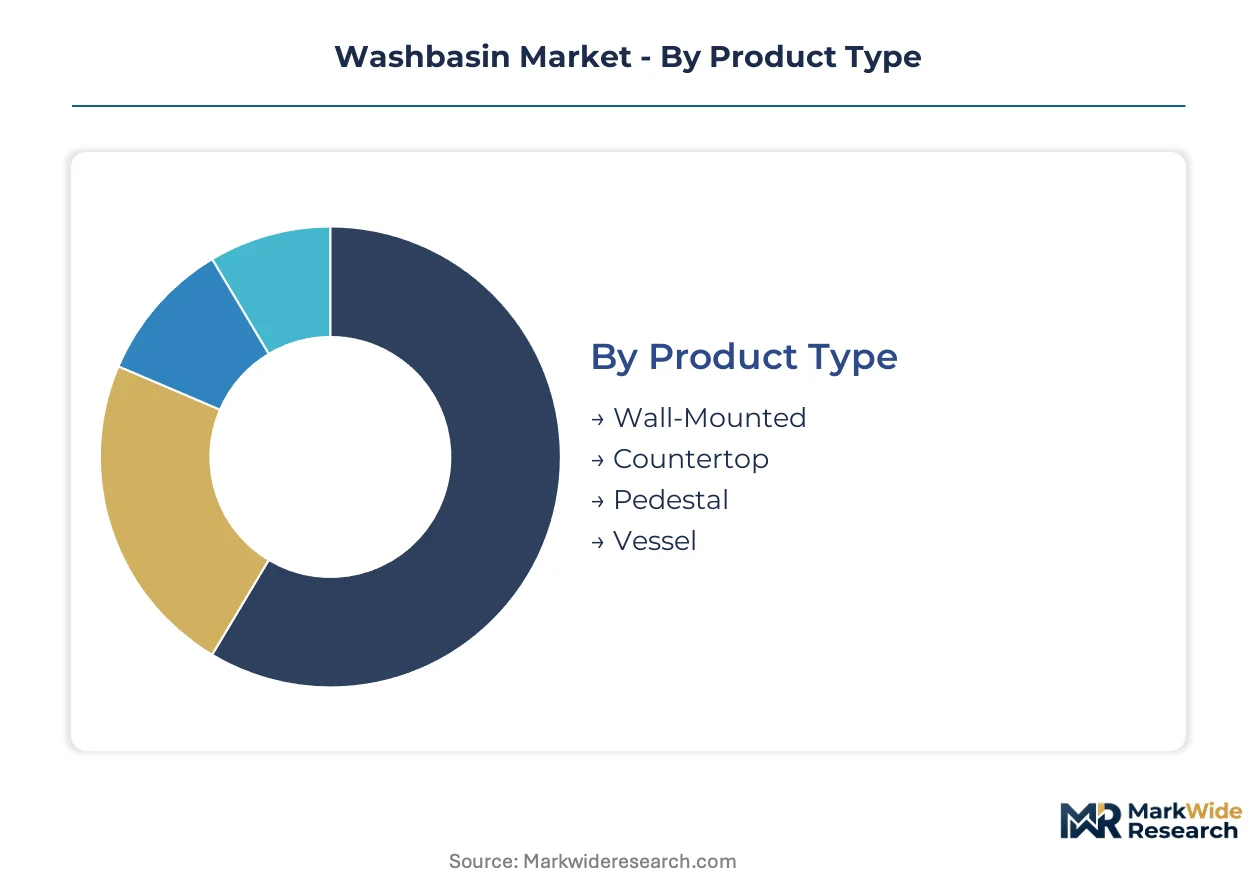
- Wall-Mounted:Ceramic or mineral-cast basins affixed directly to vertical surfaces eliminate pedestal footprint. Demand concentrates in German, French, and Italian urban residential retrofits where CE marking load-testing governs specification for space-constrained bathrooms.
- Vessel:Above-counter bowl forms create visual distinction through exposed profiles. Boutique hotel chains in Shanghai, Beijing, and Shenzhen specify these for lobby washroom installations where guest experience justifies premium positioning.
- Countertop:Recessed or surface-mounted designs integrate with vanity furniture across mid-market residential developments.
- Pedestal:Freestanding column-supported forms persist in institutional and heritage property renovations requiring traditional aesthetics.
Volume sits with wall-mounted basins; growth tilts toward vessel installations in premium hospitality channels.
Material:
Cost tier and thermal performance separate buyers seeking regulatory compliance from those prioritizing weight reduction or visual distinction.
- Ceramic:Vitreous china with ISO 9994-compliant glazed surfaces dominates due to cost scalability and REACH regulatory acceptance across European residential channels.
- Stone:Natural or engineered solid surfaces command margin pools in luxury residential and boutique hotel segments where thermal retention and tactile quality justify installation complexity.
- Glass:Tempered or cast glass alternatives serve design-forward hospitality installations seeking translucency effects.
- Acrylic:Lightweight polymer formulations penetrate budget residential and quick-turn commercial projects where freight economics matter.
Volume concentrates in ceramic; expansion accelerates fastest in stone as mineral-cast formulations displace traditional ceramic in weight-sensitive fit-outs.
Installation Type:
Plumbing rough-in compatibility and renovation complexity shape procurement decisions between new construction and retrofit applications.
- Drop-In:Self-rimming basins seat into pre-cut countertop openings with minimal substructure modification. Residential renovation contractors in Germany and France favor these for bathroom refresh projects avoiding drain relocation costs.
- Integrated:Monolithic basin-countertop systems from single-source manufacturers streamline procurement for China's tier-two city developers in Hangzhou and Chengdu seeking simplified supply chain management.
- Undermount:Below-counter mounting creates seamless countertop surfaces for premium residential and hospitality vanity installations.
- Above Counter:Vessel-style exposed mounting demands precise faucet height coordination and drain rough-in adjustment.
Drop-in variants retain volume leadership; integrated systems gain share fastest as builder procurement consolidates around full-bathroom package suppliers.
End User:
Specification rigor and compliance exposure separate institutional buyers with certification mandates from residential consumers prioritizing cost and aesthetics.
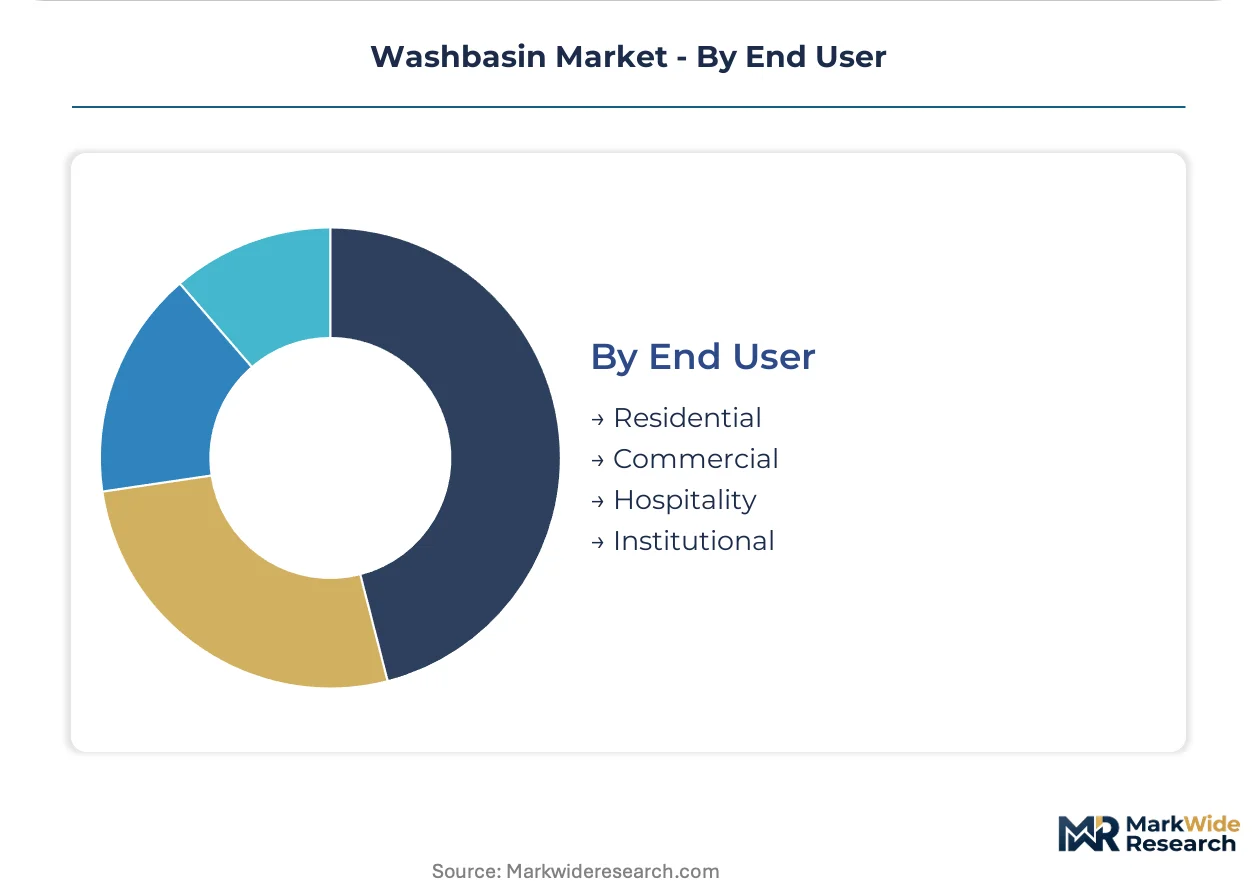
- Residential:Individual homeowners and developers drive volume through renovation cycles and new construction, with EU Green Deal water-efficiency mandates reshaping fixture selection across Germany, France, and Italy.
- Hospitality:Hotel operators and design firms specify vessel and integrated basins for guest experience differentiation, concentrating demand in China's tier-one urban renewal corridors.
- Commercial:Office building and retail washroom procurement emphasizes durability and maintenance efficiency over design distinction.
- Institutional:Government, healthcare, and education facilities require BIS certification in India and CE marking compliance in Europe, creating certified-supplier moats for compliant ceramic producers.
Residential channels anchor volume; hospitality applications expand most quickly as boutique hotel development accelerates across Chinese and European urban centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the most intensive specification activity for premium vessel and integrated basin installations, with tier-one urban renewal corridors across China, Germany, France, and Italy concentrating replacement demand and regulatory-driven product redesign.
Germany
Residential renovation cycles in Berlin, Munich, and Hamburg sustain ceramic basin replacement volumes, particularly for wall-mounted formats in space-constrained urban apartments. The EU Green Deal water-efficiency mandates under ECHA oversight force glaze chemistry reformulation for lower-flow compatibility. The Rhine-Ruhr industrial corridor hosts mineral-cast production facilities serving boutique hotel fit-outs across Western Europe.
China
Urban renewal projects in Beijing, Shenzhen, and Guangzhou specify premium vessel basins for luxury residential and hospitality installations. MIIT circular-economy directives enforce recycled-content thresholds and water-consumption limits in domestic manufacturing. The Yangtze River Delta manufacturing cluster concentrates ceramic production capacity serving both domestic specification and export procurement.
France
Paris and Lyon metropolitan retrofits drive demand for wall-mounted and integrated basin systems in heritage property renovations. REACH compliance deadlines harden disclosure requirements for glaze surface coatings across residential channels. The Auvergne-Rhône-Alpes region hosts specialized ceramic formulation facilities supplying hospitality-focused mineral-cast alternatives.
Italy
Milan and Rome residential refresh cycles expand uptake of ceramic and stone basin formats across mid-market and luxury segments. CE marking mandates structural load testing for wall-mounted installations, constraining large-format residential designs. The Emilia-Romagna ceramic district maintains captive glaze formulation capabilities responding to ECHA emission thresholds.
India
Institutional procurement in Delhi-NCR, Mumbai, and Bangalore creates certified-supplier demand for BIS-compliant ceramic durability. The national building code and state-level urban development authorities specify water-efficiency standards for government, healthcare, and education facilities. The Gujarat ceramic belt scales production to meet institutional certification requirements while serving residential renovation demand in western metropolitan corridors.
Washbasin Market Vendor Landscape
Premium-margin players sit above commodity-margin players across material technology and regulatory certification dimensions, with consolidated European and Japanese manufacturers commanding specification influence in hospitality and institutional channels while fragmented regional fabricators compete on cost in residential retrofits. Three archetypes dominate: integrated bathroom system suppliers consolidating full-fixture procurement, mineral-cast specialists competing on weight reduction and thermal retention, and ceramic volume producers leveraging captive glaze technology for regulatory compliance. Dominant competitive moves include backward integration into raw material processing and strategic partnerships with urban development consortia for project-specific specification.
Among Germany-based sanitary ware specialists, Duravit AG and Villeroy & Boch AG exemplify the premium-tier mineral-cast and ceramic formulation archetype, while Wisconsin-headquartered Kohler Co. anchors the integrated system supplier position across North American and Asian hospitality channels. These three entities represent distinct competitive vectors: European mineral-cast innovation, heritage ceramic manufacturing scale, and transcontinental bathroom system integration.
| Leading Market Players |
|---|
| Kohler Co. |
| TOTO Ltd. |
| Duravit AG |
| Roca Sanitario S.A. |
| Villeroy & Boch AG |
| LIXIL Corporation |
| American Standard Brands |
| Jaquar Group |
| Hansgrohe SE |
| Others |
Supply Flow & Price Mechanics
Family-owned ceramic specialists across Italy's Emilia-Romagna district and Germany's Rhine-Ruhr corridor maintain pricing discipline through captive glaze formulation, insulating margin pools from commodity feedstock volatility while channeling investment toward REACH compliance rather than price competition.
Pricing Analysis
Value-based pricing anchored to water-efficiency certification tiers governs European procurement, with CE-marked wall-mounted basins commanding premiums over uncertified alternatives. Price differentiation separates ISO 9994-compliant ceramic from REACH-tier mineral-cast formulations, while feldspar cost volatility compresses margins in economy-grade production. Pricing pressure intensifies in China's tier-two cities as integrated vanity-package suppliers consolidate procurement volume. Institutional buyers in India exhibit highest price sensitivity due to BIS certification barriers, whereas boutique hotel operators in Shanghai absorb premium positioning for vessel installations.
Supply Chain Analysis
Dual-sourcing requirements from European hospitality procurement teams mandate qualified suppliers across both China and Germany, mitigating single-source exposure to Yangtze River Delta disruptions. Ceramic feedstock draws from feldspar mining corridors in Turkey and India, while mineral-cast resin formulations hinge on petrochemical supply from Rotterdam and Singapore. Tariff exposure on Chinese ceramic exports to Europe elevates landed cost unpredictability. Distribution runs through builder-merchant networks in Germany and France, direct-project specification in China's tier-one cities, and institutional tender channels in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance deadlines and ECHA glaze disclosure mandates are accelerating exit pressure on formulation-dependent mid-caps lacking captive chemistry capabilities.
For Market Incumbents: Anticipate consolidation among mineral-cast specialists by securing backward integration into feldspar processing or resin formulation. Duravit AG and Villeroy & Boch AG demonstrate defensive positioning through captive glaze technology that substitutes for third-party chemical supply. Channel control via direct specification relationships with Shanghai and Beijing urban development consortia provides moat against integrated-package competitors. For New Entrants and Emerging Players: The mid-tier pricing gap between premium vessel basins and economy ceramic drop-ins offers white-space entry for mineral-cast regional fabricators serving boutique hotel chains. India's BIS certification bottleneck creates penetrable institutional demand for compliant domestic producers. A go-to-market angle through 3D-printed mold capabilities for project-specific geometries bypasses mass-ceramic scale disadvantages. For Investors and Strategic Acquirers: MIIT circular-economy directive enforcement is the leading indicator that recycled-content processing capabilities will separate viable targets from stranded assets. Long-term viability favors manufacturers with waste-stream integration rather than pure-play ceramic volume. Acquisition target archetype: mid-cap European specialists with REACH-compliant formulation and underutilized capacity in Germany or Italy. Watch for ECHA emission threshold tightening as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Glaze Formulation Investment | ECHA disclosure mandates force in-house chemistry control, eliminating third-party supplier dependency. |
| Mineral-Cast Capacity Expansion | Weight reduction properties address boutique hotel installation efficiency requirements across Western Europe. |
| Sensor-Integrated System Development | TOTO Ltd. anchors competitive stance through touchless basin convergence with building management platforms. |
| Urban Development Consortium Partnerships | Direct specification access in Shanghai and Beijing urban renewal corridors secures premium vessel volume. |
| Recycled-Content Processing Integration | MIIT circular-economy thresholds favor domestic Chinese manufacturers with captive waste-stream capabilities. |
Methodological Framework
Document review covered customs trade databases, ECHA regulatory filings, and MIIT circular-economy directives, complemented by interviews with ceramic plant managers, hospitality procurement directors, and urban development specification leads across Germany, China, and India. Secondary validation drew from BIS certification records, CE marking compliance registries, and ISO 9994 testing documentation. Bottom-up volume triangulation against top-down macroeconomic indicators ensured cross-verification of replacement cycle assumptions.
Output modeling generated segment-level value and volume trajectories across the projection horizon, with analytical frameworks incorporating installation type, material durability tier, and end-user compliance exposure. CAGRs were derived from regression against historical replacement patterns and regulatory mandate timelines. Industry-specific forecast inputs included EU Green Deal water-efficiency implementation schedules and China tier-one urban renewal project pipelines.
Inputs from ECHA disclosure registries and MIIT producer compliance reports were available through the study window; gaps in real-time feldspar spot pricing and boutique hotel project cancellation rates introduce uncertainty bands around mineral-cast adoption assumptions. Deviation in REACH enforcement intensity or China property sector liquidity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
India Bath Fittings Market
Bathroom Fixtures and Accessories
India Shower Cubicle Market
Bathroom Fixtures and Accessories
Europe Bath Fitting Market
Bathroom Fixtures and Accessories
Shower Curtain Market
Bathroom Fixtures and Accessories
Automatic Toilet Seat Market
Bathroom Fixtures and Accessories
Global Shower Enclosure and Cubicles Market
Bathroom Fixtures and Accessories
Toilet Partition Market
Bathroom Fixtures and Accessories
Asia Pacific Bath Fitting Market
Bathroom Fixtures and Accessories
Artificial Stone Bathtubs Market
Bathroom Fixtures and Accessories
Bathroom Worktops Market
Bathroom Fixtures and Accessories
Baby Changing Tables and Stations Market
Bathroom Fixtures and Accessories
Europe Bath and Shower Products Market
Bathroom Fixtures and Accessories
Global Shower Cubicles Market
Bathroom Fixtures and Accessories
Sanitary Ware and Bathroom Accessories Market
Bathroom Fixtures and Accessories
Water Sink Market
Bathroom Fixtures and Accessories
Pullout Faucets Market