
 United States Bath Fitting Market | 2026-2036
United States Bath Fitting Market Size, Share, and Industry Trends Forecast 2026-2036
United States Bath Fitting Market Analytics
WaterSense certification is reorganizing competitive access in the United States bath fitting sector, filtering out manufacturers unable to meet EPA-mandated flow-rate thresholds. Masco Corporation leverages extensive retail channel partnerships to sustain volume leadership across big-box and pro-contractor networks. Kohler Co. anchors its position through in-house foundry operations and design-forward product lines that command premium positioning. TOTO USA differentiates via advanced ceramic engineering and bidet-integrated toilet systems that occupy a growing niche in upscale residential and hospitality specification.
United States bath fittings encompass plumbed fixtures and their mounting hardware, typically fabricated from brass castings, stainless steel tubing, or engineered polymer composites, with surface finishes applied through physical vapor deposition or electroplating to achieve corrosion resistance and aesthetic consistency. These products regulate water delivery and drainage in hygiene and bathing applications across residential, commercial, and institutional environments. Faucets and showerheads represent the largest product volume pools, while wall-mounted installations dominate new construction specifications due to labor efficiency and space optimization. Brass material grades command the strongest margin profile among metal options, though stainless steel gains specification in coastal markets where salinity accelerates corrosion. The hospitality end-user segment shows the fastest trajectory as hotel renovation cycles compress and wellness-oriented bathroom concepts expand.
The EPA WaterSense program and DOE appliance efficiency standards govern maximum flow rates for lavatory faucets and showerheads, directly constraining product design parameters and manufacturing test protocols. California Title 20 and CEC regulations enforce stricter thresholds than federal baselines, creating a dual-compliance burden for national distribution strategies. OSHA and state-level plumbing codes further shape installation specifications and contractor certification requirements. Stakeholders must monitor pending federal rulemakings on showerhead multiplexing definitions and state-level water scarcity responses that could trigger step-function changes in allowable product performance envelopes.
Market Dynamics
WaterSense certification requirements are compressing fixture performance envelopes while accelerating replacement cycles among residential renovators across Sun Belt states.
Growth Catalysts
- EPA WaterSense Program:Federal flow-rate mandates for lavatory faucets and showerheads are forcing fixture upgrades in older housing stock, creating replacement demand independent of aesthetic renovation cycles.
- Residential Renovation Spending:Homeowners in Florida, Texas, and Arizona are outpacing national averages for bathroom remodel activity, concentrating volume in states with favorable construction climates.
- Wellness-Oriented Hospitality Concepts:Hotel renovation cycles are compressing as chains integrate spa-inspired bathing environments, expanding specification opportunities for premium shower systems.
Market Restraints
- Brass Input Cost Volatility:Copper and zinc price swings directly compress margin profiles for manufacturers dependent on brass castings for valve bodies and decorative components.
- California Title 20 Compliance Burden:The California Energy Commission enforces stricter flow-rate thresholds than federal EPA baselines, forcing dual-SKU strategies that fragment production runs.
- Physical Vapor Deposition Capacity Constraints:Premium finish application requires specialized vacuum chamber equipment concentrated among a limited supplier base in the Midwest.
Strategic Opportunities
- Bidet-Integrated Toilet Systems:Underpenetrated residential adoption in the Southeast and Midwest creates expansion runway for washlet technology proven in upscale hospitality specification.
- Pro-Contractor Direct Channels:Bypassing big-box retail through dedicated contractor supply houses captures higher-margin specification decisions at the point of installation.
- Infrastructure Investment and Jobs Act Water Efficiency Grants:Federal funding for municipal water conservation programs subsidizes consumer fixture upgrades in drought-stressed Western states.
Industry Challenges
- Cross-State Plumbing Code Harmonization:Variation in state-level installation specifications and contractor certification requirements complicates national distribution logistics.
- Multiplexing Definition Uncertainty:Pending EPA rulemakings on showerhead flow-rate testing protocols for multi-jet systems create product development timeline risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Bath Fitting Market |
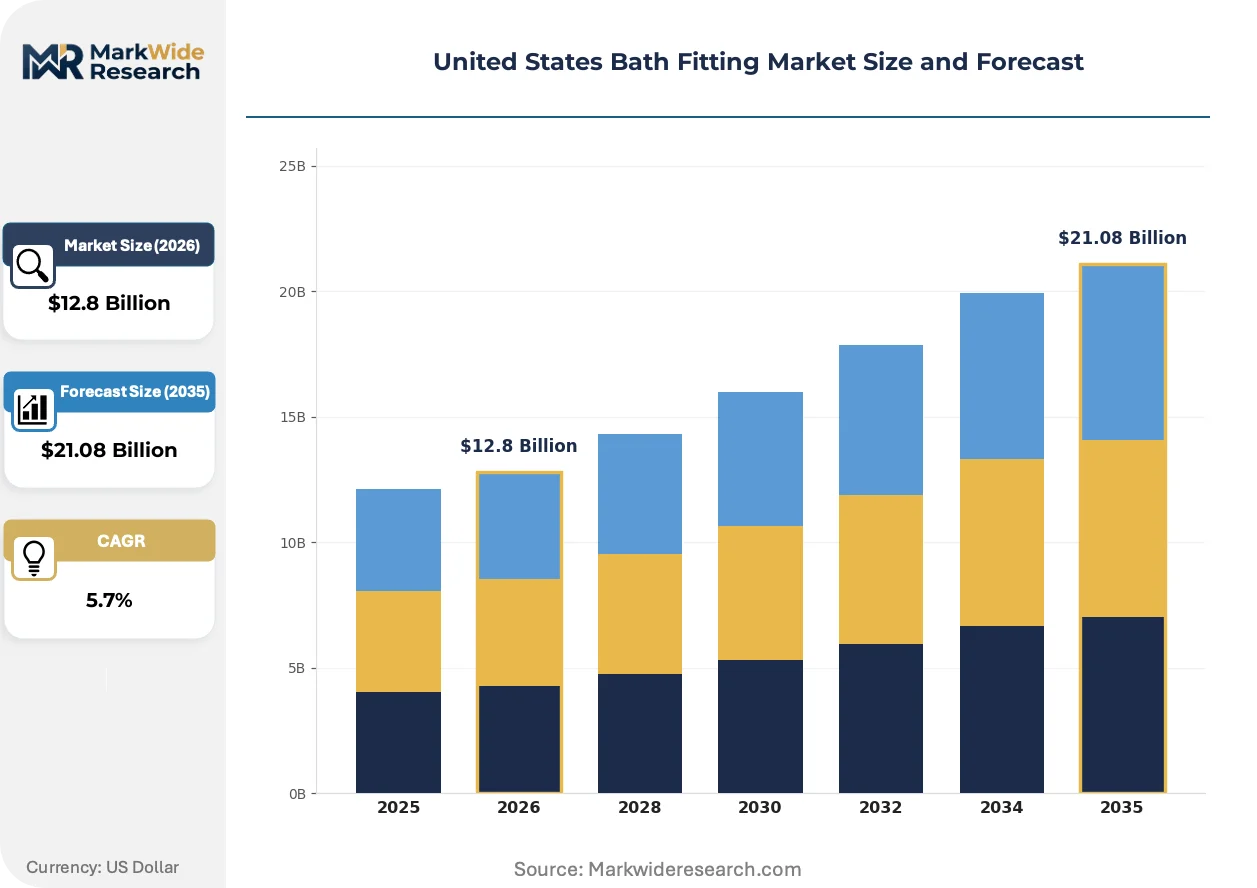
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Showerheads, Faucets, Tubs, Toilets Material: Brass, Stainless Steel, Plastic, Ceramic Installation Type: Wall-Mounted, Freestanding, Floor-Mounted, Integrated End User: Residential, Commercial, Hospitality, Healthcare |
| Companies Covered | Fortune Brands Innovations, Masco Corporation, Kohler Co., LIXIL, ASSA ABLOY, TOTO USA, Hansgrohe SE, Jacuzzi Brands, Elkay Manufacturing, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Bath Fitting Market Evolving Landscape
Fixture engineering is converging around water conservation mandates, digital control interfaces, and wellness-oriented bathing experiences that redefine user interaction with plumbed environments.
Touchless sensor activation is supplanting manual lever handles in commercial and high-end residential specification. Office building owners and hospitality operators are adopting infrared-triggered faucets to reduce water waste and improve hygiene protocols. This technology is compressing maintenance intervals while commanding 15-25% price premiums over conventional mechanical controls.
California Title 20 and CEC regulations are tightening maximum flow-rate thresholds for showerheads below federal WaterSense baselines. Manufacturers serving national distribution must maintain dual compliance SKUs or default to the stricter standard, raising per-unit test and certification costs. The Western United States bears the heaviest compliance burden, with Arizona and Nevada adopting California-aligned standards.
Wellness-oriented bathing is redirecting consumer preference toward multi-jet shower systems and thermostatic mixing valves. Homeowners in Sun Belt states are prioritizing spa-inspired renovation elements over traditional tub-shower combinations. This shift concentrates specification volume with plumbing contractors capable of complex rough-in configurations.
United States Bath Fitting Market Segmentation
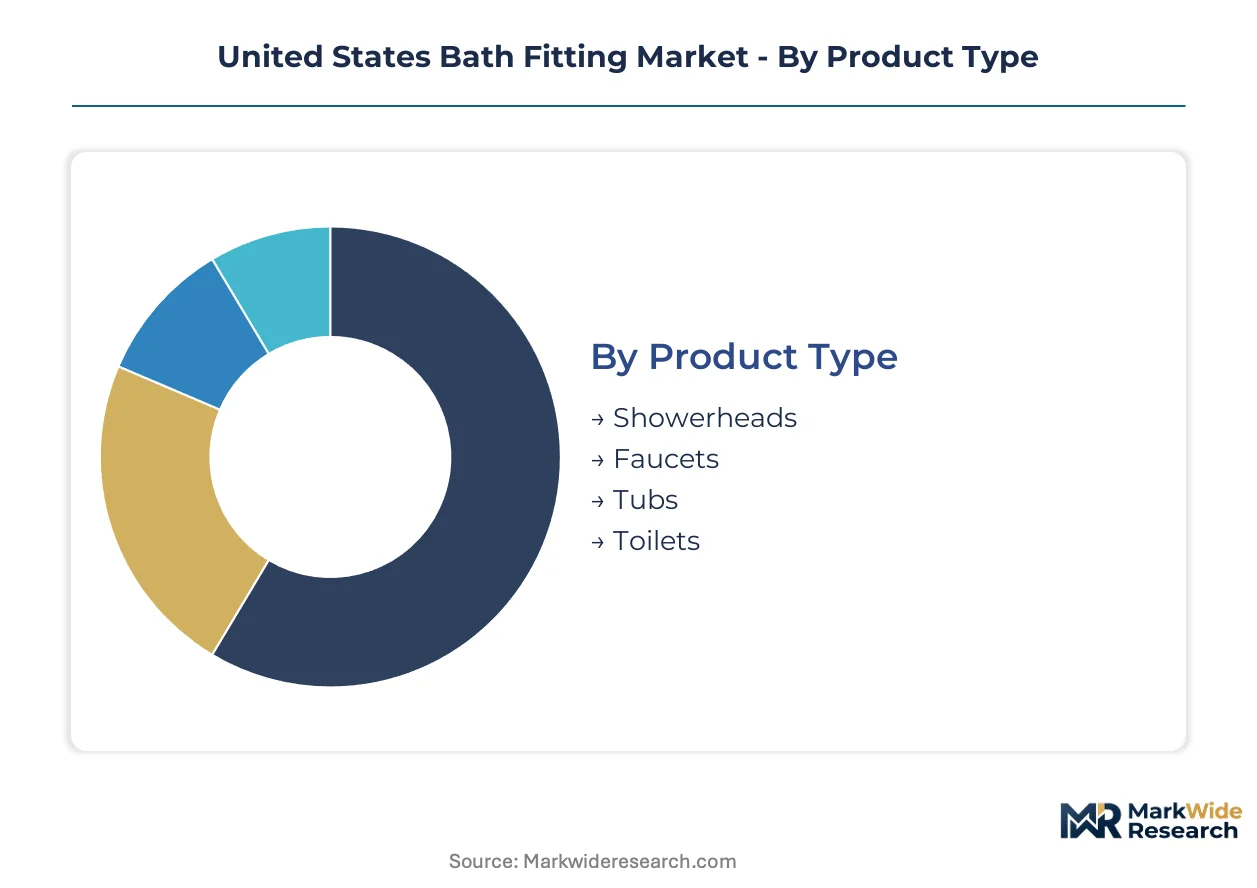
Segmentation in the United States bath fitting market reveals distinct procurement patterns across material grades, installation methods, and end-use environments. Understanding these divides helps manufacturers align production capacity with geographic demand clusters and regulatory compliance burdens.
Product Type:
Showerheads and faucets concentrate in domestic renovation channels, while tubs and toilets see stronger export-linked production from coastal manufacturing zones.
- Showerheads:Multi-jet configurations with thermostatic mixing dominate upscale residential specification in Florida and Arizona. California Title 20 flow-rate mandates are compressing allowable performance envelopes and accelerating replacement cycles in drought-stressed Western states.
- Faucets:Lavatory and kitchen variants fabricated from brass castings command premium positioning through physical vapor deposition finishes. Touchless sensor activation is gaining specification in commercial office buildings and hospitality properties seeking hygiene protocol upgrades.
- Tubs:Freestanding acrylic and cast-iron units serve renovation-driven demand in Sun Belt master bathroom expansions.
- Toilets:Bidet-integrated systems remain underpenetrated in Southeast residential markets despite proven hospitality adoption.
Faucets hold the largest share; momentum sits with showerheads.
Material:
Cost tier stratification separates premium metal specifications from volume polymer alternatives, with coastal corrosion concerns reshaping regional preference.
- Brass:Copper-zinc castings for valve bodies and decorative components deliver superior machinability and finish adhesion. Input cost volatility from LME copper pricing directly compresses margin profiles for manufacturers lacking backward integration into foundry operations.
- Stainless Steel:Austenitic grades gain specification in Florida and Gulf Coast markets where atmospheric salinity accelerates brass corrosion. Tubing-based construction suits minimalist aesthetic trends in urban residential renovation.
- Plastic:Engineered polymer composites serve economy-tier new construction and multi-family housing where initial cost dominates specification.
- Ceramic:Advanced vitreous china formulations anchor toilet and bidet manufacturing, with TOTO USA's engineering standards influencing industry quality benchmarks.
Brass holds the largest share; stainless steel is climbing the fastest.
Installation Type:
Volume concentration favors rough-in-efficient methods that reduce skilled labor hours on job sites facing contractor availability constraints.
- Wall-Mounted:Concealed valve bodies and floating vanities dominate new construction specifications for space optimization and cleaning access. Rough-in standardization across Sun Belt production housing accelerates installation velocity.
- Freestanding:Tub and vanity units command premium positioning in renovation markets where spatial reconfiguration permits statement-piece placement.
- Floor-Mounted:Traditional closet and pedestal configurations persist in replacement markets and institutional healthcare environments.
- Integrated:Modular shower-wall systems with pre-formed pans reduce tile-trade dependency and warranty exposure for production builders.
Wall-mounted holds the largest share; integrated is gaining share fastest.
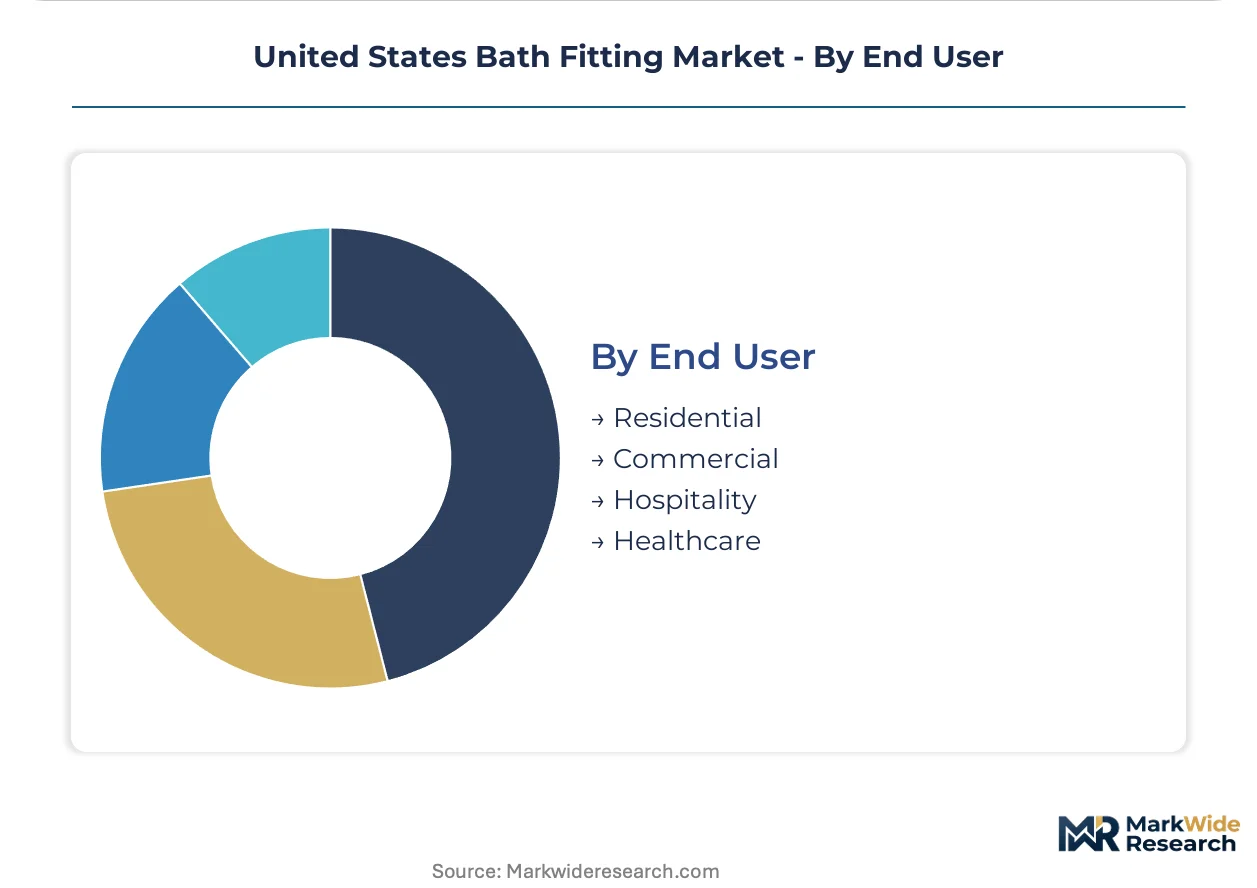
End User:
Customer type determines specification authority, with pro-contractor channels capturing renovation decisions and developer procurement controlling new construction volume.
- Residential:Single-family and multi-family homeowners drive replacement cycles through EPA WaterSense rebate programs and aesthetic renovation. Sun Belt states concentrate volume where favorable construction climates extend remodeling seasons.
- Commercial:Office building owners specify touchless fixtures to reduce water waste and maintenance intervals. Infrared-activated faucets command price premiums over mechanical controls in Class A properties.
- Hospitality:Hotel renovation cycles are compressing as chains integrate spa-inspired bathing environments. Wellness-oriented bathroom concepts expand specification opportunities for premium shower systems and thermostatic controls.
- Healthcare:Hospitals and long-term care facilities prioritize infection control through sensor-activated fixtures and antimicrobial surface treatments.
Residential holds the largest share; hospitality shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pro-contractor supply houses and big-box retail chains concentrate specification authority across distinct state-level regulatory environments. Demand clusters in Sun Belt markets where construction climates extend remodeling seasons and water scarcity triggers accelerated fixture replacement cycles.
California
California Title 20 mandates flow-rate thresholds below federal EPA WaterSense baselines, forcing dual-SKU compliance strategies for national distributors. The California Energy Commission enforces stricter showerhead and faucet specifications than any other state, elevating test and certification costs for manufacturers serving Western markets. Los Angeles and San Diego metro areas anchor specification volume for premium multi-jet shower systems in upscale residential renovation.
Texas
Houston and Dallas-Fort Worth production housing markets drive wall-mounted installation specifications for labor-efficient new construction. The Texas Commission on Environmental Quality coordinates drought-response programs that subsidize WaterSense-certified fixture upgrades in municipal water districts. Austin and San Antonio renovation activity concentrates demand for bidet-integrated toilet systems among tech-sector homeowners.
Florida
Atmospheric salinity in Miami and Tampa coastal zones accelerates stainless steel specification over traditional brass castings for corrosion resistance. Florida building codes mandate hurricane-resistant installation methods that favor floor-mounted fixtures in replacement markets. Orlando hospitality renovation cycles compress as hotel chains integrate spa-inspired wellness bathrooms, expanding premium shower system procurement.
Arizona
Phoenix and Tucson adoption of California-aligned flow-rate standards creates compliance burden for distributors serving Southwest markets. The Arizona Department of Water Resources administers municipal conservation rebates that accelerate residential fixture replacement independent of aesthetic renovation cycles. Scottsdale and Paradise Valley master bathroom expansions concentrate specification for freestanding tub and thermostatic mixing valve combinations.
Northeast Corridor
Greater Boston and New York Metro commercial office buildings specify touchless sensor faucets to reduce water waste and maintenance intervals in Class A properties. State-level plumbing code variation across Massachusetts, Connecticut, and New Jersey complicates contractor certification requirements for national service networks. Philadelphia and Baltimore institutional healthcare facilities prioritize infection-control fixtures with antimicrobial surface treatments.
United States Bath Fitting Market Competitive Landscape
Player mix skews toward diversified building-products conglomerates with captive foundry operations and dedicated retail channel partnerships. The vendor base separates into three functional tiers: vertically integrated manufacturers controlling brass casting and finish application, specialist fabricators focused on premium design-forward positioning, and volume-oriented suppliers serving production housing markets. Consolidation pressure operates through strategic acquisitions of regional distributors and technology licensing agreements for sensor-activated control systems.
Within the integrated-manufacturer tier, Masco Corporation and Kohler Co. exemplify archetypes combining in-house foundry capacity with extensive retail and pro-contractor channel presence. TOTO USA occupies a position representing advanced ceramic engineering specialization and bidet-integrated system expertise proven in hospitality specification. Among diversified building-products groups, Fortune Brands Innovations and LIXIL sit within portfolios leveraging cross-category bathroom and kitchen fixture synergies.
| Leading Market Players |
|---|
| Fortune Brands Innovations |
| Masco Corporation |
| Kohler Co. |
| LIXIL |
| ASSA ABLOY |
| TOTO USA |
| Hansgrohe SE |
| Jacuzzi Brands |
| Elkay Manufacturing |
| Others |
Value Network & Pricing Analysis
EPA WaterSense certification gates both supplier qualification and price differentiation in the United States bath fitting sector, compressing margin structures for uncertified producers while enabling certified manufacturers to command specification premiums in Western states. Compliance burden stratifies the vendor base between dual-SKU national distributors and California-default producers, with input cost volatility from LME copper pricing feeding directly into brass casting economics.
Pricing Analysis
Cost-plus contracts with LME copper indexation dominate brass casting supply agreements, exposing manufacturers to margin compression when zinc and copper prices spike. Three-tier pricing structure across premium, standard, and economy levels separates physical vapor deposition finished fixtures from electroplated alternatives and polymer composites. Price differentiation hinges on WaterSense certification tier and geographic delivery cost to Sun Belt construction clusters. Margins are tightening due to California Title 20 compliance overhead, with multi-family housing developers exhibiting highest price sensitivity and hospitality specifiers showing lowest.
Supply Chain Analysis
Midwest vacuum chamber capacity for physical vapor deposition finishing creates a chokepoint that constrains premium fixture output and extends lead times for specialty finishes. Brass casting concentrates in Ohio, Michigan, and Indiana foundry clusters, while ceramic toilet manufacturing anchors in Georgia and Alabama. Raw material dependencies span LME copper and zinc for valve bodies, engineered polymers for economy tiers, and austenitic stainless steel for coastal corrosion resistance. Tariff exposure on Chinese ceramic components threatens bidet-integrated system cost structures. Distribution runs through big-box retail chains and pro-contractor supply houses, with direct specification authority increasingly captured at installation points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity scarcity and certified finish application bottlenecks constrain supply elasticity, rewarding manufacturers with backward integration into brass casting and captive physical vapor deposition operations.
For Market Incumbents: Compound channel control through dedicated pro-contractor supply house partnerships that capture specification decisions at rough-in stage, while investing in dual-SKU production flexibility to serve California Title 20 markets without fragmenting national runs. Brass input cost volatility threatens margin stability; securing long-term copper offtake agreements or captive foundry capacity anchors cost predictability. For New Entrants and Emerging Players: Anchor in Southeast residential bidet adoption gaps where hospitality-proven washlet technology remains underpenetrated despite proven specification in hotel renovation cycles. Target Florida and Gulf Coast stainless steel corrosion-resistant specifications where atmospheric salinity displaces traditional brass. Bypass big-box retail saturation through direct plumbing contractor relationships and municipal rebate program participation. For Investors and Strategic Acquirers: Pending EPA rulemakings on showerhead multiplexing definitions reshape the acquisition landscape by elevating product development timeline risk for multi-jet system specialists. Long-term viability favors vertically integrated manufacturers with captive foundry operations and WaterSense certification infrastructure already deployed. Monitor EPA final rule publication as inflection signal for stranded asset risk in non-compliant product portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brass Foundry Operations | Masco Corporation's captive casting capacity insulates margin profiles from LME copper volatility. |
| Dual-SKU Compliance Strategy | California Title 20 alignment enables unified Western distribution without federal baseline fragmentation. |
| Pro-Contractor Direct Channel Expansion | Bypassing big-box retail captures higher-margin specification authority at installation points. |
| Physical Vapor Deposition Capacity Addition | Midwest vacuum chamber scarcity constrains premium finish output for design-forward positioning. |
| Bidet-Integrated System Market Development | Southeast residential penetration gaps replicate TOTO USA's hospitality-proven specification model. |
Research Methodology
The analysis maps showerhead, faucet, tub, and toilet sub-sectors, each validated through plumbing contractor interviews, big-box retail category managers, pro-contractor supply house procurement leads, and hospitality specification directors. Secondary validation draws from EPA WaterSense certification databases, California Energy Commission Title 20 filings, LME metals pricing records, and municipal water conservation rebate program disclosures. Bottom-up channel volume estimates triangulate against top-down construction spending allocations across Sun Belt states.
Consistency checks against Census Bureau residential improvement expenditure benchmarks and hospitality renovation cycle surveys validate projection outputs across the modeling period. Segmentation dimensions span product type, material grade, installation method, and end-user environment with regulatory compliance tier overlay. CAGRs derive from fitted growth curves applied to renovation cycle acceleration patterns and new construction permit trajectories, with WaterSense mandate enforcement timelines and copper price scenario inputs informing sensitivity bounds.
Decision-makers should treat outputs as directional under sustained Sun Belt construction climate advantage and EPA rulemaking finalization; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as California-aligned state adoption patterns and brass input cost volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Toilet Seat Market
Bathroom Fixtures and Accessories
Bath Fittings and Accessories Market
Bathroom Fixtures and Accessories
Toilet Partition Market
Bathroom Fixtures and Accessories
Germany Bathroom Furniture Market
Bathroom Fixtures and Accessories
Luxury Plumbing Fixtures Market
Bathroom Fixtures and Accessories
Asia Pacific Bath Fitting Market
Bathroom Fixtures and Accessories
Baby Changing Tables and Stations Market
Bathroom Fixtures and Accessories
United Kingdom Bath Fitting Market
Bathroom Fixtures and Accessories
Faucet Market
Bathroom Fixtures and Accessories
Bathroom Pods Market
Bathroom Fixtures and Accessories
Plumbing Fixtures and Fittings Market
Bathroom Fixtures and Accessories
Bathroom Accessories Market
Bathroom Fixtures and Accessories
India Shower Cubicle Market
Bathroom Fixtures and Accessories
Bathtub Market
Bathroom Fixtures and Accessories
Water Sink Market
Bathroom Fixtures and Accessories
Shower Tray Market