
 Australia Bathroom Products Market | 2026-2036
Australia Bathroom Products Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Bathroom Products Market Insights
Modular vanity and storage bundling is restructuring how Australian consumers configure bathroom renovations, shifting purchase decisions from standalone items to coordinated systems. GWA Group Limited anchors the national supply chain through extensive distribution networks and owned manufacturing facilities. Kohler Co. differentiates through design-forward collections that command positioning in architect-specified projects. Sussex Taps specializes in locally machined brassware that competes on craftsmanship credentials against imported alternatives.
Australia bathroom products encompass sanitary ware, water delivery fixtures, and surface materials engineered for wet-environment durability, corrosion resistance, and hydraulic efficiency under mains pressure conditions. Ceramic vitrification and PVD metal coating processes determine longevity in hard-water regions across the country. Faucets and showers dominate volume throughput in the market, while freestanding bathtubs capture disproportionate margin pools in the premium residential channel. Metal and glass material segments are expanding fastest as consumers prioritize tactile quality and visual lightness over conventional plastic and basic ceramic options.
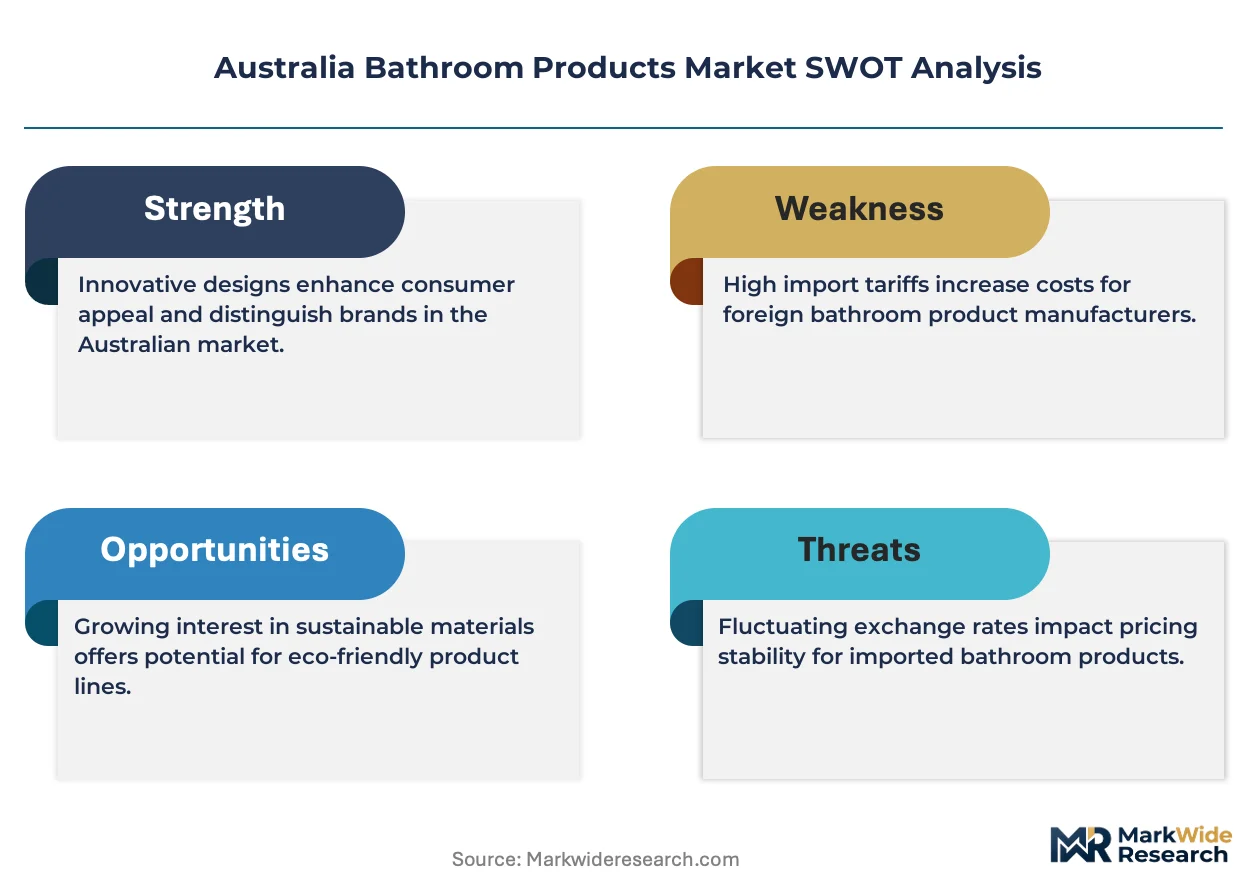
The Water Efficiency Labelling and Standards scheme administered by the Australian government shapes product eligibility and retail access by mandating flow-rate disclosures on all registered fittings. State-level plumbing codes enforced by bodies such as Plumbing Code Australia and the Victorian Building Authority create jurisdictional variation in installation compliance requirements. Building sustainability ratings including NABERS and Green Star influence commercial and hospitality procurement specifications toward WELS-certified and low-carbon material selections. Stakeholders must monitor pending revisions to the National Construction Code and state-level embodied carbon policies that will redefine compliance thresholds for bathroom product specifications in new builds and major renovations.
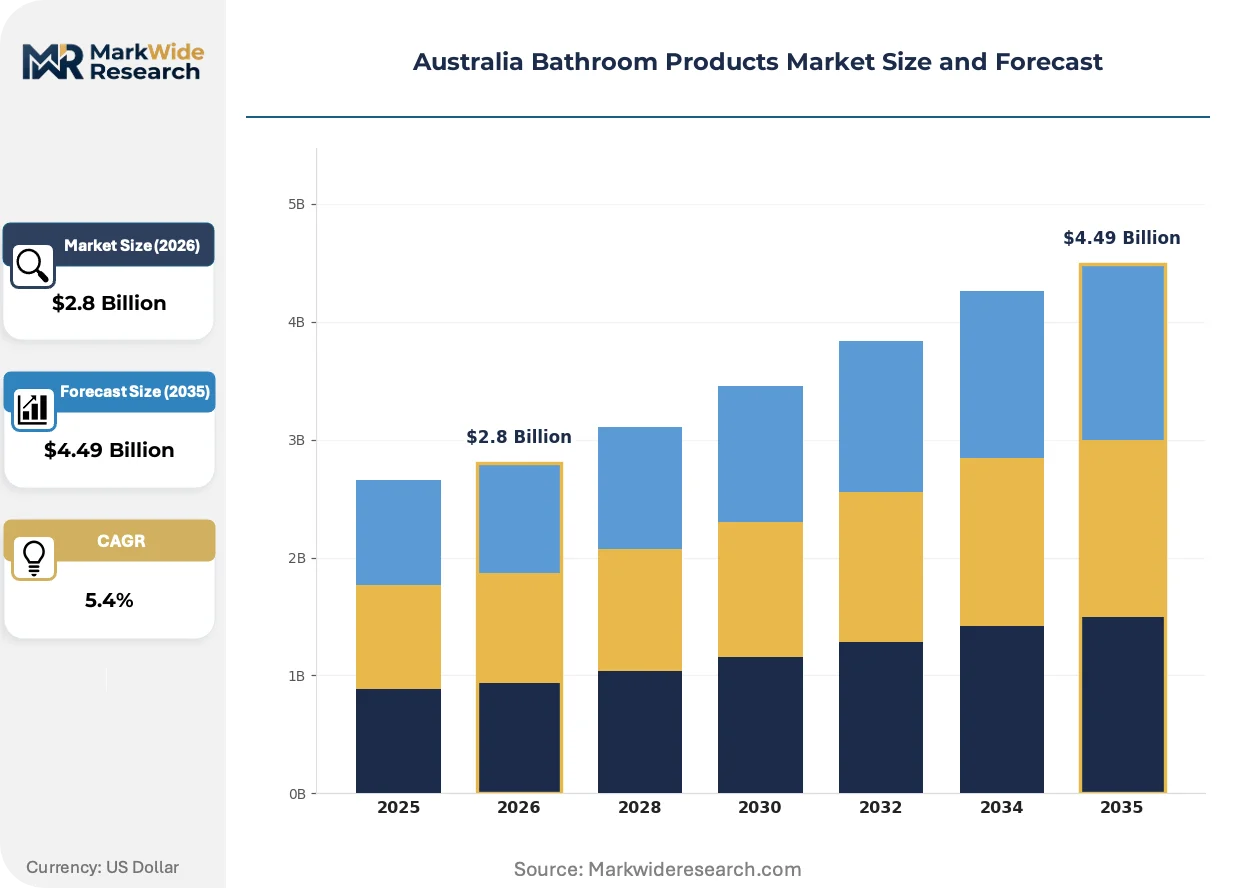
Market Dynamics
The WELS scheme is compressing replacement cycles for non-compliant fixtures while redirecting procurement toward certified low-flow alternatives, creating a bifurcated market where hydraulic efficiency credentials determine retail access.
Growth Catalysts
- Water Efficiency Labelling and Standards (WELS) scheme:Mandatory flow-rate disclosures on all registered fittings are accelerating fixture replacement in renovation channels as consumers and specifiers prioritize compliant products.
- Smart touchless technology:Sensor-activated faucets and flush systems are penetrating premium residential and commercial hospitality segments, driven by hygiene protocols and water conservation targets.
- Melbourne and Sydney renovation activity:Residential property upgrading in these metropolitan clusters is lifting demand for coordinated bathroom systems and accelerating fixture replacement timelines.
Market Restraints
- Brass and copper input cost volatility:Machined brassware manufacturers face margin compression from fluctuating base metal prices, particularly affecting locally fabricated tapware against imported alternatives.
- Hard-water corrosion:Ceramic vitrification and PVD coating durability requirements limit product lifespan in regional areas with high mineral content, constraining warranty terms and brand positioning.
- State-level plumbing code fragmentation:Jurisdictional variation between Plumbing Code Australia and Victorian Building Authority compliance requirements creates inventory complexity for national distributors.
Strategic Opportunities
- Green Star and NABERS procurement specifications:Building sustainability ratings are opening specification pathways for WELS-certified and low-carbon material selections in commercial and hospitality verticals.
- Freestanding bathtub margin pools:Premium residential channels present underexploited positioning for sculptural fixtures that command disproportionate margin relative to volume throughput.
- Metal and glass material substitution:Consumer preference for tactile quality and visual lightness over plastic and basic ceramic options is expanding addressable premium segments.
Industry Challenges
- Pending National Construction Code revisions:Anticipated changes to embodied carbon thresholds will force rapid product requalification and supply chain recertification for new build specifications.
- Coordinated system integration complexity:Modular vanity and storage bundling requires installers to manage multi-component fit-out sequencing, straining trade coordination and project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Bathroom Products Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Faucets, Showers, Bathtubs, Toilets Material: Ceramic, Metal, Glass, Plastic Form: Wall-mounted, Freestanding, Integrated, Vessel End User: Residential, Commercial, Hospitality, Institutional |
| Companies Covered | Masco Corporation, Sussex Taps, Decina Bathroomware, Robertson Bathware, Felton Industries Ltd, GWA Group Limited, Gessi SPA, The Procter and Gamble Company, Kohler Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Bathroom Products Market Trends and Innovations
Touchless sensor systems and low-flow hydraulic engineering are converging to redefine fixture specifications, while material preferences shift toward premium tactile surfaces that signal durability and design intent.
Smart sensor integration is consolidating control over water delivery systems in both residential and commercial installations. Specifiers in architect-driven projects are mandating touchless activation for hygiene and efficiency compliance. This technology is consolidating multiple functions—temperature control, flow modulation, and usage monitoring—into single fixture platforms, compressing demand for standalone mechanical alternatives.
The WELS scheme administered by the Australian government is tightening eligibility thresholds for retail distribution. Manufacturers must now maintain continuous compliance documentation to retain product registration, increasing administrative overhead. Victorian and New South Wales procurement officers are prioritizing WELS-certified fittings in public infrastructure tenders, accelerating specification migration toward labeled products.
Renovation procurement is fragmenting from standalone item selection toward coordinated system purchasing. Consumers in premium segments are engaging design consultants to specify matched vanity, storage, and fixture ensembles. This pattern is most visible in Sydney and Melbourne metropolitan renovations where project value thresholds justify bundled professional services.
Australia Bathroom Products Market Segmentation
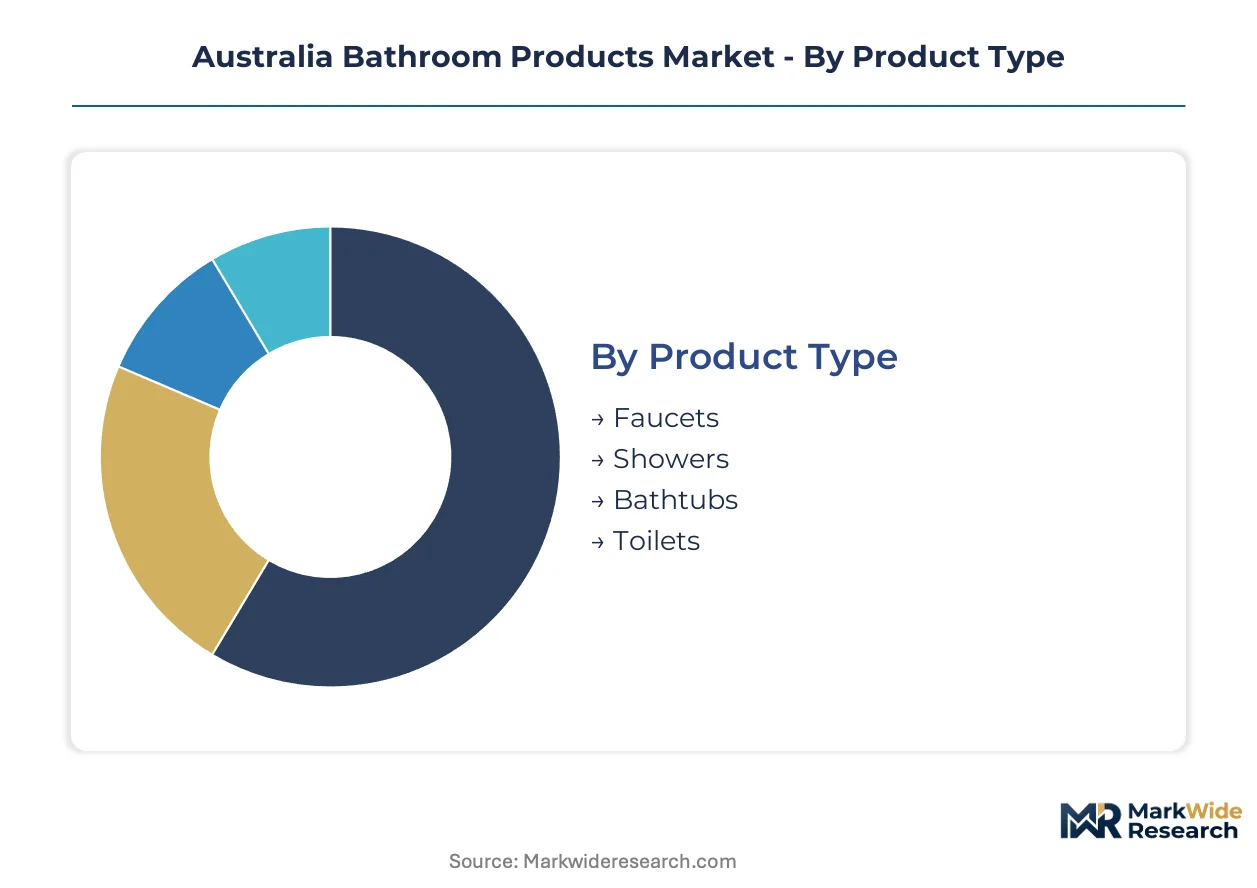
Australian bathroom procurement splits across four structural axes that determine specification pathways, compliance obligations, and margin capture. Each segmentation layer interacts with WELS certification requirements, state plumbing codes, and renovation versus new-build project economics.
Product Type:
Specification intensity varies by hydraulic complexity and replacement frequency, with water delivery fixtures commanding disproportionate engineering attention.
- Faucets:Machined brassware with ceramic disc cartridges dominates volume throughput. Melbourne and Sydney renovation channels prioritize WELS-certified low-flow models as mandatory replacements for non-compliant legacy installations.
- Showers:Multi-function rail systems and overhead rainheads concentrate demand in premium residential upgrades. Water efficiency mandates under the WELS scheme are compressing replacement cycles for high-flow legacy units.
- Bathtubs:Freestanding sculptural forms capture disproportionate margin pools in architect-specified projects.
- Toilets:Wall-hung and rimless designs are gaining specification share in space-constrained urban renovations.
Mature deployment sits with faucets and showers in renovation channels. Newer deployment is concentrated in freestanding bathtubs for premium new-build specifications.
Material:
Cost tier stratification separates commodity substrates from premium tactile surfaces that signal durability and design intent.
- Ceramic:Vitrified sanitary ware remains the baseline for toilets and basins. Hard-water corrosion resistance determines warranty positioning in regional Queensland and Western Australia.
- Metal:Solid brass and PVD-coated tapware command specification in high-end residential and commercial hospitality. Fluctuating copper and zinc input costs compress margins for locally machined alternatives against imported competition.
- Glass:Tempered vessel basins and shower enclosures are expanding fastest as consumers prioritize visual lightness.
- Plastic:Polymer cisterns and budget tapware serve cost-sensitive renovation segments and rental property maintenance.
Volume concentration remains with ceramic across all price tiers. Metal and glass are climbing the fastest as premium renovation budgets expand.
Form:
Installation geometry dictates trade coordination complexity and project timeline sequencing for modular bathroom systems.
- Wall-mounted:Concealed cisterns and floating vanities maximize floor space in compact urban bathrooms. Victorian Building Authority compliance requirements for in-wall plumbing create installer certification barriers.
- Freestanding:Sculptural bathtubs and pedestal basins serve as focal points in premium residential specifications. These forms demand precise floor waste positioning and structural load assessment.
- Integrated:Pre-fabricated vanity and basin combinations streamline procurement for mid-market renovation projects.
- Vessel:Above-counter basins require heightened tapware clearance specifications and coordinated countertop material selection.
Integrated forms dominate mid-market volume. Vessel and freestanding configurations are expanding most quickly in design-consultant-led renovations.
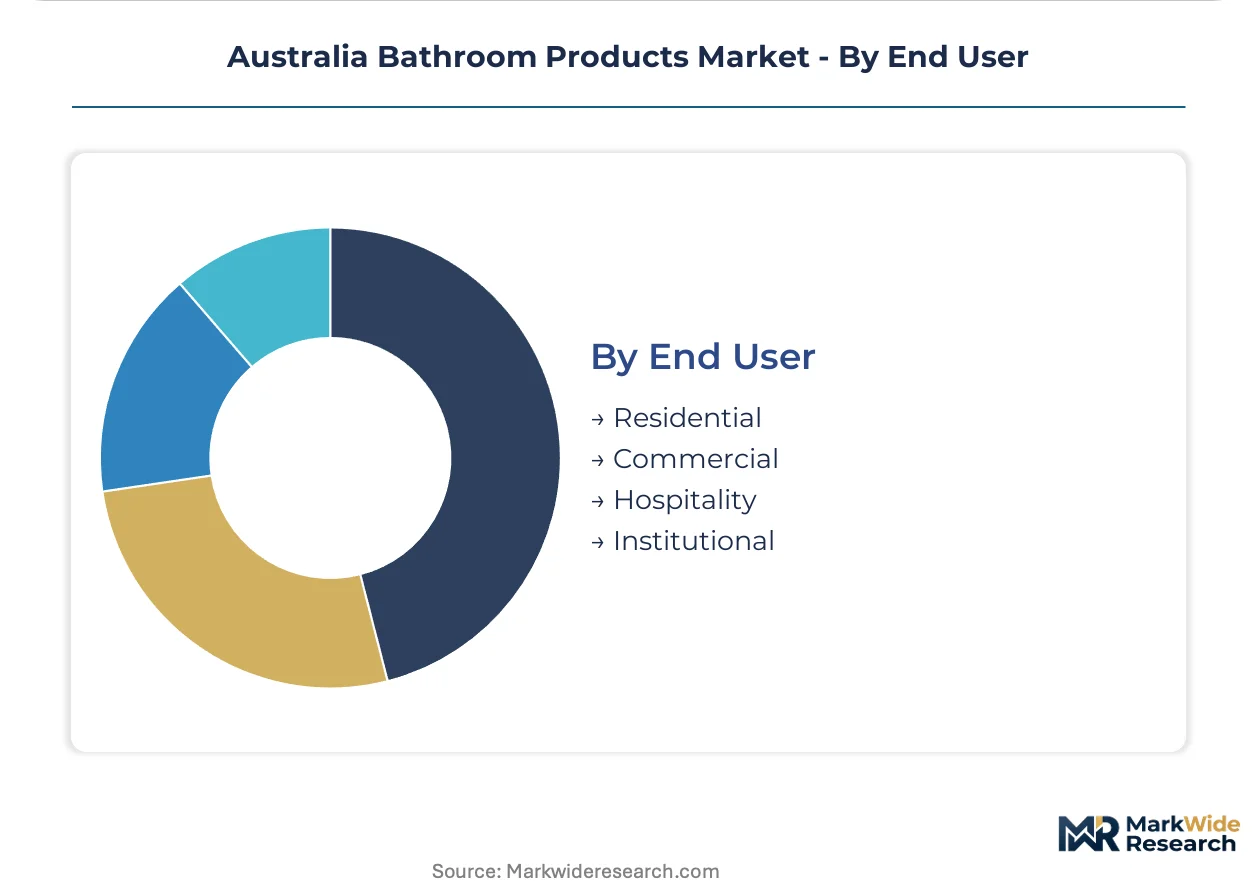
End User:
Application context determines procurement authority, specification standards, and compliance documentation requirements.
- Residential:Owner-occupier renovations in New South Wales and Victoria drive coordinated system purchasing through design consultants. Project value thresholds above $50,000 justify bundled professional services.
- Commercial:Office and retail fit-outs prioritize WELS-certified fixtures to meet NABERS water efficiency targets. Procurement runs through facilities managers with sustainability mandates.
- Hospitality:Hotels and resorts specify touchless sensor systems for hygiene protocols and operational water conservation. Green Star ratings influence material selection toward low-carbon alternatives.
- Institutional:Healthcare and education projects face stringent Plumbing Code Australia compliance for accessibility and infection control.
Residential channels anchor volume throughput. Hospitality and institutional segments are gaining share fastest as sustainability ratings tighten specification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturing capacity concentrates in southeastern states while consumption spreads across metropolitan renovation corridors. Import dependency shapes competitive dynamics in premium segments.
New South Wales
Sydney metropolitan renovation activity drives coordinated system purchasing through design consultants. The WELS scheme administered by the Australian government mandates flow-rate disclosures that compress replacement cycles for non-compliant fixtures. Newcastle and Wollongong industrial zones host distribution hubs serving regional trade channels.
Victoria
Melbourne residential property upgrading accelerates fixture replacement timelines in premium bathroom renovations. Victorian Building Authority compliance requirements for in-wall plumbing create installer certification barriers for wall-mounted configurations. Geelong manufacturing facilities anchor brassware production for national distribution networks.
Queensland
Hard-water corrosion challenges in regional areas constrain warranty positioning for ceramic vitrification and PVD coating durability. State-level procurement officers prioritize WELS-certified fittings in public infrastructure tenders. Brisbane and Gold Coast hospitality developments specify touchless sensor systems for operational water conservation.
Western Australia
Mining sector employment stability underpins renovation demand in Perth metropolitan clusters. High mineral content in regional water supplies limits product lifespan for standard coating processes. Fremantle port facilities handle import throughput for premium European fixture collections.
South Australia
Adelaide's mid-market renovation segment favors integrated vanity and basin combinations for streamlined procurement. Green Star ratings influence commercial specifications toward low-carbon material selections. Local fabrication capacity focuses on polymer cisterns and budget tapware for rental property maintenance channels.
Australia Bathroom Products Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price positioning. The vendor base stratifies between scale-driven manufacturers with captive distribution and craftsmanship-oriented fabricators serving architect-specified channels. Three archetypes dominate: integrated manufacturers with owned retail networks, design-forward specialists commanding premium positioning, and import-dependent distributors competing on cost. Competitive moves center on portfolio diversification into smart touchless technology and strategic partnerships with sustainability certification bodies.
Among Australian-based fabricators, GWA Group Limited and Sussex Taps occupy distinct positioning within the national supply chain. GWA Group Limited exemplifies the integrated manufacturer archetype through extensive distribution networks and owned production facilities. Sussex Taps represents craftsmanship-specialist positioning with locally machined brassware competing on quality credentials. Masco Corporation and Kohler Co. anchor the multinational presence, with the former exemplifying diversified conglomerate scale and the latter representing design-forward collection strategies in architect-driven projects.
| Leading Market Players |
|---|
| Masco Corporation |
| Sussex Taps |
| Decina Bathroomware |
| Robertson Bathware |
| Felton Industries Ltd |
| GWA Group Limited |
| Gessi SPA |
| The Procter and Gamble Company |
| Kohler Co. |
| Others |
Pricing and Supply Chain Analysis
The WELS scheme administered by the Australian government gates both qualified supply and premium-tier pricing access, compressing replacement cycles for non-compliant fixtures while redirecting procurement toward certified low-flow alternatives that command higher price points in renovation channels.
Pricing Analysis
Margin tightening in machined brassware reflects fluctuating copper and zinc input costs that compress locally fabricated tapware against imported competition. Three-tier pricing structure across premium, standard, and economy levels separates WELS-certified sensor-activated fixtures from basic mechanical alternatives and budget polymer options. Cost-down pressure on premium sculptural bathtubs accelerates because design-consultant-led renovations prioritize tactile quality over volume throughput. Owner-occupiers in New South Wales and Victoria show lowest price sensitivity for coordinated system bundles, while rental property maintenance channels in South Australia remain most cost-conscious.
Supply Chain Analysis
Refurbishment flows for legacy non-compliant fixtures create secondary market circulation that competes with new certified product sales in cost-sensitive segments. Manufacturing concentration draws from Geelong brassware facilities, Chinese ceramic vitrification plants, and Italian design-forward collections distributed through Fremantle port facilities. Raw material dependencies rest on copper and zinc concentrates for machined tapware, vitrified clay for sanitary ware, and tempered glass for vessel basins. Single-source vulnerability sits with PVD coating chemicals subject to export licensing restrictions. Distribution runs through GWA Group Limited's owned retail networks and independent trade channels serving Melbourne and Sydney metropolitan renovation corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia bathroom products market represents a consolidation play as pending National Construction Code revisions force rapid product requalification that weaker fabricators cannot fund, accelerating exits among import-dependent distributors lacking captive manufacturing.
For Market Incumbents: Extend WELS certification coverage across full product portfolios before revised National Construction Code thresholds take effect, locking out competitors with incomplete compliance documentation. Deepen upstream control over brass machining capacity in Geelong to offset copper price volatility against Chinese import alternatives. Sensor-activated fixture lines represent the priority R&D area for defending specification share in architect-driven projects.
For New Entrants and Emerging Players: Regional Queensland hard-water corrosion challenges present an underserved buyer archetype for warranty-differentiated ceramic vitrification and enhanced PVD coating durability. The most penetrable segment is mid-market integrated vanity systems for Adelaide's streamlined procurement preference. A direct-to-trade digital platform bypassing incumbent distributor markups offers the strongest go-to-market angle.
For Investors and Strategic Acquirers: Accelerating Victorian Building Authority enforcement actions against non-compliant in-wall plumbing installations is the leading indicator that installer certification barriers will consolidate demand among qualified fabricators with proven compliance track records. Long-term viability over the analysis window favors vertically integrated manufacturers with owned distribution and captive brassware production. Practitioners should monitor state-level embodied carbon policy announcements for early signals of supply chain recertification burden shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| WELS Certification Expansion | Full portfolio registration under the Australian government scheme locks out non-compliant competitors from retail distribution channels. |
| Sensor Technology Integration | Touchless activation systems consolidate temperature control and flow modulation functions that displace standalone mechanical alternatives. |
| Brassware Capacity Expansion | Geelong manufacturing footprint deepens upstream control over copper and zinc input cost exposure against import competition. |
| Design Consultant Partnership Program | Sydney and Melbourne specification relationships capture coordinated system bundling in premium renovation projects above value thresholds. |
| Hard-Water Durability Repositioning | Enhanced ceramic vitrification and PVD coating warranties address Queensland and Western Australia regional corrosion constraints. |
Research Methodology
Independent corroboration across plumbing merchant procurement directors, Victorian Building Authority compliance officers, and design consultant specifications underwrites the qualitative findings in this study. Primary interviews with brassware manufacturing plant managers, bathroom renovation trade contractors, and hospitality facilities managers combined with secondary validation from WELS registration databases, Plumbing Code Australia technical standards, and state-level building authority enforcement records. Bottom-up project pipeline analysis across Melbourne and Sydney metropolitan renovation channels triangulates with top-down consumption estimates derived from import customs data and distribution network throughput.
Rate-of-change decomposition across the analysis window isolates fixture replacement cycle compression from new-build specification growth. Segmentation dimensions modeled include product type, material substrate, installation form, and end-user application context alongside regional regulatory cluster variation between Plumbing Code Australia and Victorian Building Authority jurisdictions. CAGRs were derived from trend extrapolation of renovation activity indices and WELS compliance migration patterns, with water efficiency mandate tightening and smart sensor penetration rates serving as primary forecast inputs.
Revisions become necessary when National Construction Code embodied carbon thresholds materialize ahead of schedule or when state-level plumbing code fragmentation intensifies inventory complexity beyond current distributor adaptation capacity. Practitioners should monitor brass and copper futures price volatility and pending Green Star rating revisions for early signals of margin compression or specification pathway shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Pullout Faucets Market
Bathroom Fixtures and Accessories
US Smart Kitchen and Bathroom Products Market
Bathroom Fixtures and Accessories
Washbasin Market
Bathroom Fixtures and Accessories
Shower Curtain Market
Bathroom Fixtures and Accessories
Bathroom Accessories Market
Bathroom Fixtures and Accessories
North America Toilet Seat Market
Bathroom Fixtures and Accessories
Baby Changing Tables and Stations Market
Bathroom Fixtures and Accessories
North America Traditional Toilet Seat Market
Bathroom Fixtures and Accessories
Bathroom Cabinets Market
Bathroom Fixtures and Accessories
US Faucet Market
Bathroom Fixtures and Accessories
US Toilet Partition Market
Bathroom Fixtures and Accessories
Faucet Market
Bathroom Fixtures and Accessories
Vietnam Sanitary Ware & Bathroom Accessories Market
Bathroom Fixtures and Accessories
Bidet Market
Bathroom Fixtures and Accessories
Automatic Toilet Seat Market
Bathroom Fixtures and Accessories
Shower Tray Market