
 Europe Steam Room Market | 2026-2036
Europe Steam Room Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Steam Room Market Foresight
Aftermarket service revenue is rewriting value capture across the Europe Steam Room Market, pulling margin pools from one-time equipment sales toward recurring maintenance contracts and component lifecycle management. KLAFS Group leverages its German manufacturing footprint to dominate premium commercial installations across Western Europe. Harvia PLC anchors its competitive position through deep vertical integration into heater and control system production. TyloHelo Oy specializes in modular steam generation technology that reduces on-site installation complexity for hotel and spa operators.
Europe steam rooms are enclosed thermal chambers that generate humid heat typically between 40°C and 50°C using electric steam generators, with primary construction from moisture-resistant materials such as thermo-treated wood, tempered safety glass, and corrosion-protected steel framing. Their commercial purpose centers on wellness therapy, muscle recovery, and respiratory health applications across hospitality, fitness, and residential settings. Traditional steam rooms lead the product type category due to established installation protocols and lower capital barriers, while infrared variants are gaining fastest in residential retrofits where energy efficiency and compact footprints matter. Glass and wood materials command the highest margin pools because customization complexity and moisture-resistant treatment requirements limit commoditization.
CE marking under the EU Construction Products Regulation governs structural safety and electrical compliance for steam room installations across member states, while the EU Green Deal's building renovation targets are tightening energy efficiency standards for wet leisure equipment. Germany's KBA-influenced product liability frameworks and Finland's national building code both mandate specific ventilation and electrical isolation protocols that shape manufacturer design priorities. Stakeholders must monitor how the EU F-Gas Regulation's phase-down of fluorinated greenhouse gases will constrain refrigerant-based steam generation technologies and redirect R&D toward resistive heating and heat pump alternatives.
Market Dynamics
Post-pandemic wellness infrastructure investment across Northern Europe is compressing installation timelines and forcing manufacturers to pre-fabricate modular steam generation systems. CE marking compliance under the EU Construction Products Regulation now governs structural safety protocols for every commercial installation.
Growth Catalysts
- EU Green Deal building renovation targets:Energy efficiency mandates for wet leisure equipment are accelerating replacement cycles in German and Finnish hospitality properties. Member states must retrofit existing building stock by mid-century deadlines.
- Modular steam generation technology:Pre-fabricated generator units reduce on-site labor hours and permit hotel operators to minimize operational downtime during installation. This engineering approach compresses project delivery windows.
- Finland:National sauna and steam bathing traditions sustain premium residential investment even during construction cost inflation. Cultural attachment to thermal wellness insulates demand from discretionary spending volatility.
Market Restraints
- Copper and electrical component input costs:Resistive heating element manufacturing faces raw material price volatility that manufacturers struggle to pass through in fixed-price commercial contracts.
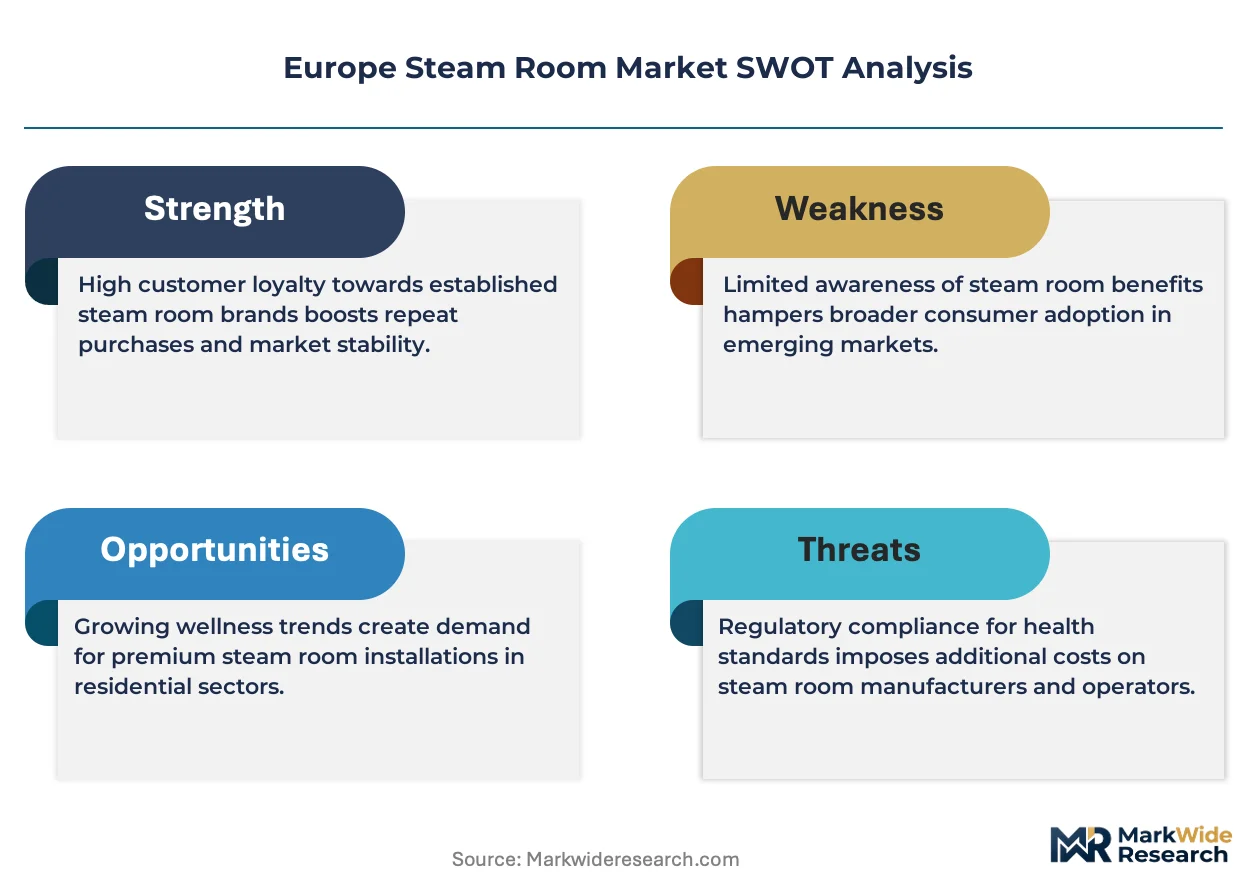
- EU F-Gas Regulation phase-down:Fluorinated greenhouse gas restrictions constrain refrigerant-based steam generation technologies and force R&D redirection toward alternative heating methods.
- Steam inhalation therapy substitutes:Portable nebulizers and home respiratory devices capture segments of the wellness-therapy market that steam rooms previously monopolized in clinical-adjacent settings.
Strategic Opportunities
- Swedish residential retrofits:Urban apartment renovations present underpenetrated demand for compact steam room installations where space constraints previously excluded full-size units.
- Heat pump steam generation convergence:Integration of heat pump efficiency with resistive heating backup creates hybrid systems qualifying for national green building incentives.
- Direct-to-developer digital channels:Hotel construction consortia increasingly procure wellness equipment through centralized procurement platforms that bypass traditional distributor networks.
Industry Challenges
- Moisture-resistant carpentry specialization:Thermo-treated wood installation requires certified craftsmen whose training pipelines have not expanded to match installation demand growth.
- CE marking certification timelines:Third-party conformity assessment for electrical isolation protocols extends product launch schedules by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Steam Room Market |
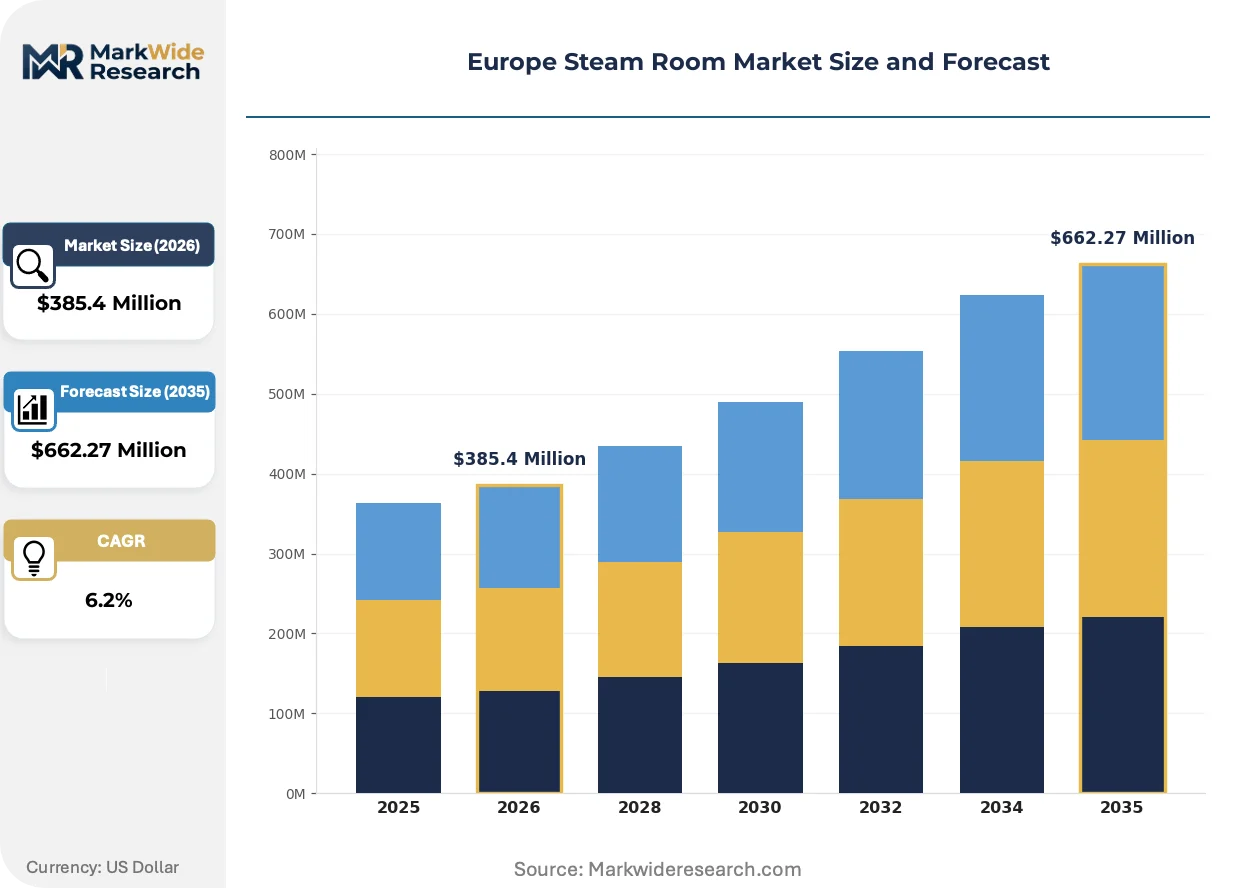
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Infrared, Portable, Customized Material: Glass, Wood, Concrete, Steel Installation Type: Indoor, Outdoor, Mobile, Permanent End User: Residential, Commercial, Wellness Centers, Hotels |
| Companies Covered | KLAFS Group, Harvia PLC, TyloHelo Oy, Duravit, Physiotherm, Oceanic, SAWO Inc., Thermalux, Finnleo, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Steam Room Market Shifts & Advancements
Digital control interfaces and predictive maintenance algorithms are redefining how steam room operators manage energy consumption and equipment lifecycle costs. Three distinct developments are compressing competitive differentiation timelines.
Smart building integration platforms are virtualizing the steam room as a networked thermal appliance rather than standalone equipment. Hotel chains across Germany and Austria are deploying these systems to synchronize steam generation with occupancy sensors and HVAC load balancing. This connectivity is virtualizing traditional equipment procurement into integrated building management contracts.
The EU F-Gas Regulation's refrigerant phase-down timeline is forcing manufacturers to abandon compression-based steam generation before alternative technologies achieve cost parity. Industrial consequences include accelerated patent filing in resistive heating and heat pump hybrid architectures. Nordic manufacturers are responding fastest due to earlier national building code alignment with Brussels efficiency standards.
Wellness center procurement teams now unbundle after-sales service from equipment purchase, selecting maintenance providers through competitive tender separate from capital acquisition. This behavior shift disrupts traditional manufacturer-captive service revenue models. The pattern is most visible in Netherlands and Belgium where facility management outsourcing concentrates buying power among specialized property services firms.
Europe Steam Room Market Segmentation
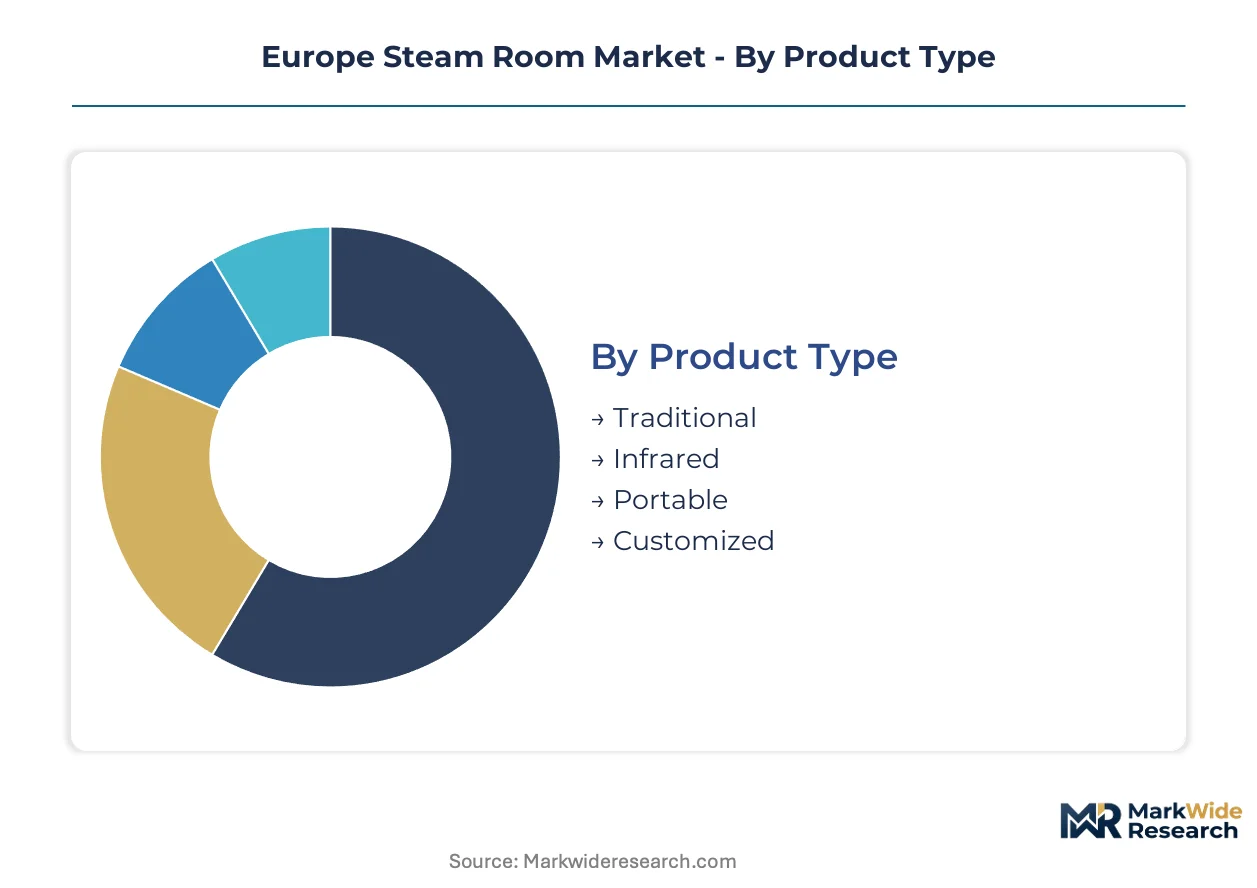
Steam room market segmentation reveals how thermal wellness infrastructure fragments across construction methods, thermal technologies, and procurement contexts. Understanding these divisions exposes where margin pools concentrate and which specification pathways dominate capital allocation decisions across European hospitality and residential development.
Product Type:
Mature thermal generation technologies coexist with emerging efficiency-focused alternatives across the maturity spectrum.
- Traditional:Electric steam generators produce humid heat between 40°C and 50°C through resistive elements, dominating German and Finnish wellness center installations where established maintenance protocols and technician familiarity reduce operational risk. CE marking compliance under the EU Construction Products Regulation reinforces specification inertia in commercial retrofit projects.
- Infrared:Ceramic and carbon fiber panels deliver dry radiant heat at lower ambient temperatures, penetrating Swedish and Norwegian residential retrofits where energy efficiency certifications and compact footprints override steam humidity preferences. National green building incentives in Nordic markets accelerate specification shifts away from conventional generation.
- Portable:Modular tent-style units with integrated generators target temporary wellness programming and event hospitality.
- Customized:Bespoke architectural installations accommodate irregular spatial constraints in heritage building renovations.
Traditional retains volume leadership; infrared holds the steepest expansion curve.
Material:
Cost tier stratification separates specification pathways between premium architectural finishes and functional economy alternatives.
- Glass:Tempered safety glass panels with specialized sealing systems command premium positioning in Dutch and Belgian hotel spas where visual transparency and design minimalism drive procurement decisions. Customization complexity and moisture-resistant hardware requirements limit supplier commoditization.
- Wood:Thermo-treated aspen, cedar, and abachi lumber deliver natural antimicrobial properties and tactile warmth, anchoring Finnish and Estonian residential installations where cultural attachment to organic materials sustains price inelasticity. Certified craftsmen scarcity constrains installation capacity expansion.
- Concrete:Cast or sprayed cementitious surfaces enable seamless curved geometries in contemporary wellness architecture.
- Steel:Corrosion-protected framing and panel systems support high-traffic commercial durability requirements.
Wood dominates residential volume; glass captures the highest margin concentration.
Installation Type:
Application context determines structural integration depth and regulatory compliance burden.
- Indoor:Fixed building-integrated chambers governed by national electrical isolation and ventilation codes, concentrating in German urban wellness centers where basement and rooftop mechanical spaces accommodate generator infrastructure.
- Outdoor:Weather-resistant enclosures with enhanced thermal insulation, penetrating Swedish lakehouse and mountain lodge developments where landscape integration overrides climate exposure concerns.
- Mobile:Trailer or container-mounted units for festival and corporate event deployment.
- Permanent:Foundation-anchored structures with dedicated utility connections in hospitality new-build projects.
Indoor commands the largest installed base; outdoor gains share in premium leisure residential.
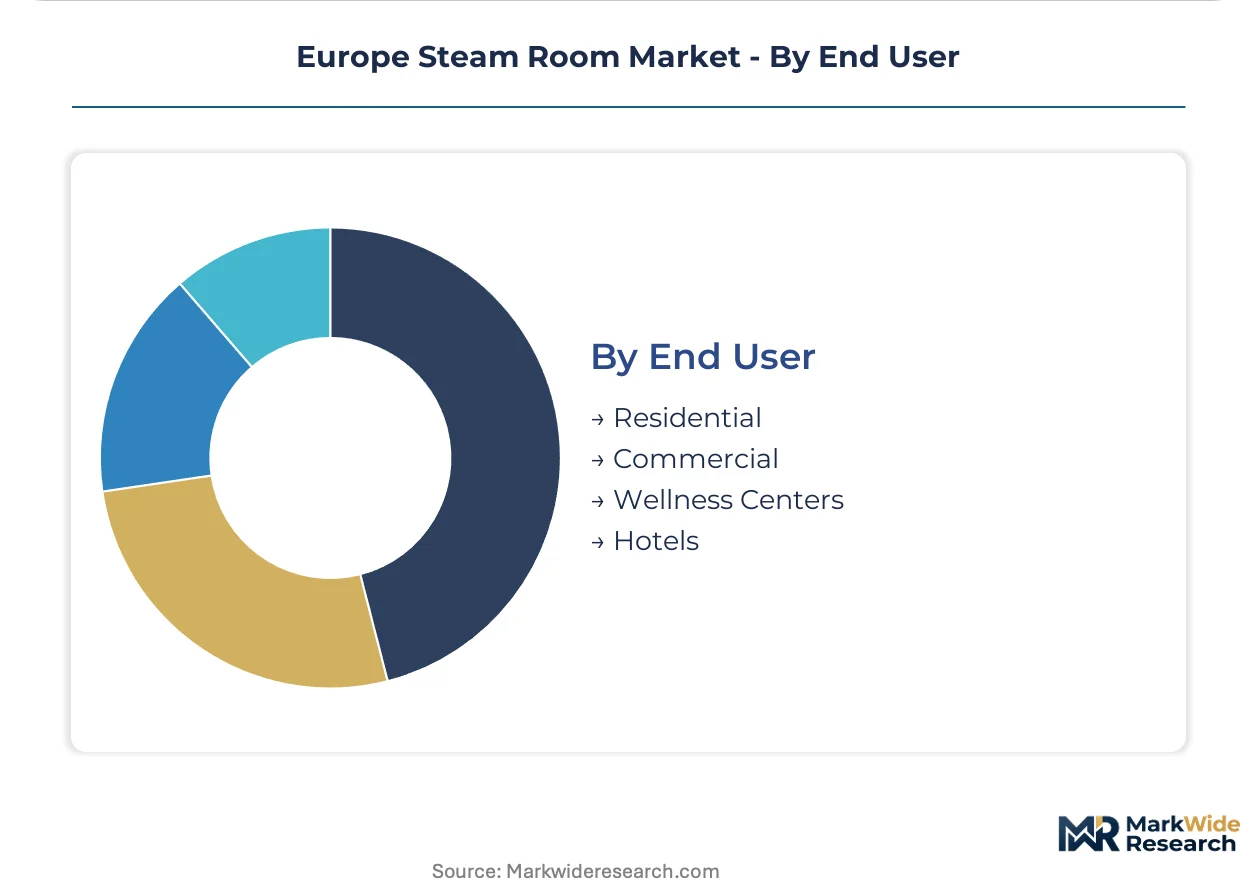
End User:
Customer type segmentation maps divergent procurement authority structures and lifecycle value expectations.
- Residential:Single-family and apartment installations where owner-occupier decision-making prioritizes energy operating costs and space efficiency, expanding fastest in Swedish urban retrofit markets constrained by floorplate dimensions.
- Commercial:Fitness chains and corporate wellness facilities procuring through centralized capital budgets with standardized specifications.
- Wellness Centers:Dedicated spa and thermal therapy operations in Germany and Austria where treatment protocol integration drives generator redundancy requirements.
- Hotels:Hospitality groups deploying wellness amenities as competitive differentiation, increasingly unbundling equipment purchase from facility management contracts in Netherlands and Belgium.
Commercial anchors aggregate volume; residential climbs the fastest in unit expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German wellness centers favor traditional electric steam generators while Swedish residential developers increasingly specify infrared panels for energy certification compliance. This consumption-mix differential reflects divergent building stock ages and national efficiency incentive structures.
Germany
Urban wellness centers in Berlin and Munich drive commercial installations with basement mechanical infrastructure accommodating generator redundancy. KBA-influenced product liability frameworks mandate electrical isolation protocols that extend manufacturer design cycles. The Rhine-Ruhr industrial corridor hosts fabrication clusters supplying thermo-treated wood components across Western European hospitality projects.
Sweden
Stockholm apartment retrofits generate demand for compact infrared systems where floorplate constraints previously excluded full-size units. National green building incentives accelerate specification shifts away from conventional steam generation. Lakehouse developments in the Stockholm archipelago anchor outdoor installation growth despite climate exposure concerns.
Finland
Cultural attachment to thermal bathing sustains premium residential investment even through construction cost inflation. National building codes mandate specific ventilation requirements that shape generator placement in new-build wellness facilities. The Helsinki-Tampere corridor concentrates thermo-treated aspen and cedar sourcing for domestic and export markets.
Netherlands
Hotel construction consortia increasingly procure wellness equipment through centralized digital platforms bypassing traditional distributor networks. Facility management outsourcing concentrates buying power among specialized property services firms in Amsterdam and Rotterdam. Glass-intensive spa designs dominate premium hospitality specifications where visual transparency drives procurement decisions.
Belgium
Wellness center procurement teams unbundle after-sales service from equipment purchase through competitive tender processes. CE marking compliance timelines for electrical isolation protocols extend product launch schedules for manufacturers serving the Brussels-Antwerp-Ghent triangle. Heritage building renovations generate bespoke architectural installation demand requiring irregular spatial accommodations.
Europe Steam Room Market Competitive Landscape
Capability concentration sits with premium-tier specialists commanding customization complexity; scale advantage sits with integrated manufacturers controlling heater and control system production. The vendor base separates into three strategic archetypes: vertically integrated thermal equipment producers, modular system specialists reducing on-site labor, and component fabricators supplying moisture-resistant materials. Dominant competitive moves include backward integration into resistive heating element production and pre-fabrication investments compressing hotel installation timelines.
Among German-based manufacturers, KLAFS Group exemplifies premium commercial installation capability across Western European hospitality markets. Harvia PLC anchors the integrated production archetype through captive supply of heater and control systems. TyloHelo Oy occupies the modular specialization position, with Finnish engineering heritage informing steam generation technology that reduces operational downtime for spa operators.
| Leading Market Players |
|---|
| KLAFS Group |
| Harvia PLC |
| TyloHelo Oy |
| Duravit |
| Physiotherm |
| Oceanic |
| SAWO Inc. |
| Thermalux |
| Finnleo |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's container cost dynamics compress margin pools for German steam room manufacturers while amplifying price differentiation between premium glass-intensive installations and economy steel-framed alternatives. Supply concentration in Finnish thermo-treated lumber and Baltic electrical component sourcing shapes how procurement teams negotiate fixed-price commercial contracts across Northern European hospitality development.
Pricing Analysis
Long-term offtake agreements dominate procurement between hotel chains and modular steam generation specialists, insulating manufacturers from copper price volatility while locking in service revenue streams. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked architectural glass installations from basic steel-framed units, with customization depth and certified craftsman availability driving spread expansion. Pricing pressure stems from fixed-price commercial contracts that manufacturers cannot renegotiate when resistive heating element input costs spike. Wellness center operators demonstrate highest price sensitivity due to unbundled procurement practices, while Finnish residential buyers exhibit inelastic demand rooted in cultural thermal bathing traditions.
Supply Chain Analysis
Upstream feedstock concentration in Finnish thermo-treated aspen, German corrosion-protected steel framing, and Chinese electrical control components creates multi-tier dependency structures for European assembly operations. Copper for resistive heating elements and specialized moisture-resistant glass hardware anchor cost volatility exposure. Single-source vulnerability concentrates in certified thermo-treated wood craftsmen whose training pipelines lag installation demand growth across German wellness center expansion. Distribution runs through hospitality-focused distributor networks in Western Europe and direct-to-developer digital platforms penetrating Dutch and Belgian hotel construction consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against portable nebulizers and home respiratory devices capturing clinical-adjacent wellness therapy segments that steam rooms previously monopolized. Incumbents must fortify around irreplaceable experiential value while new entrants exploit modular installation white space.
For Market Incumbents: Insulate recurring revenue streams by captive supply of resistive heating elements and predictive maintenance algorithm deployment that portable substitutes cannot replicate. Deepen backward integration into thermo-treated lumber certification programs to constrain competitor access to scarce craftsman networks. Prioritize CE marking compliance investment as a barrier against low-cost entrants seeking rapid market entry through regulatory shortcuts. For New Entrants and Emerging Players: Build out compact infrared system penetration in Swedish urban apartment retrofits where floorplate constraints exclude established traditional steam room specifications. Target direct-to-developer digital procurement channels in Netherlands hospitality construction that bypass incumbent distributor relationships. Position around heat pump hybrid architectures qualifying for national green building incentives ahead of EU F-Gas Regulation phase-down deadlines. For Investors and Strategic Acquirers: Modular system specialists with pre-fabricated generator capabilities and established hotel operator relationships represent the most defensible acquisition archetype for portfolio exposure. Long-term viability hinges on substitution resilience against home wellness device proliferation and regulatory alignment with Brussels efficiency standards. Monitor CE marking certification timeline compression as an inflection signal for competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Element Production | Captive supply of resistive components insulates margin pools from copper price volatility in German manufacturing. |
| Pre-Fabricated Modular System Expansion | Compressed installation timelines align with Dutch hotel operator demands for minimized operational downtime. |
| Heat Pump Hybrid R&D Investment | Alternative heating architectures qualify for Nordic national green building incentives ahead of F-Gas restrictions. |
| Direct-to-Developer Digital Channel Buildout | Bypassing traditional distributor networks captures procurement authority shifts in Belgian hospitality consortia. |
| Certified Craftsman Training Pipeline Development | Scarcity of thermo-treated wood installation specialists constrains competitor capacity expansion across Finnish residential markets. |
Research Methodology
The analysis maps traditional electric generators, infrared panels, portable units, and customized architectural installations, each validated through wellness center procurement directors, hotel facility managers, thermo-treated lumber suppliers, and electrical component distributors. Primary interview intelligence triangulates against EU Construction Products Regulation filings, national building code databases, customs trade records for copper and wood inputs, and hospitality construction permit registries. Bottom-up unit economics from generator manufacturer cost structures reconcile with top-down expenditure flows from European wellness infrastructure investment tracking.
Assumption sets held EU Green Deal building renovation targets and F-Gas Regulation phase-down timelines as fixed regulatory boundary conditions while varying copper price trajectories and certified craftsman availability as sensitivity inputs. Segmentation modeling spans product type, material specification, installation context, and end-user procurement authority across the projection horizon. CAGRs derive from installed base replacement cycle analysis and new-build penetration rate calibration against national efficiency incentive structures. Heat pump technology cost curves and modular system adoption elasticities inform scenario-weighted outputs.
Stress conditions across raw material price spikes, CE marking certification delays, and substitute technology performance improvements were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation pacing and cultural demand persistence in Nordic thermal bathing markets. Cross-checking against national building renovation expenditure surveys and hospitality CAPEX disclosure trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Toilet Partition Market
Bathroom Fixtures and Accessories
United Kingdom Bath Fitting Market
Bathroom Fixtures and Accessories
Luxury Plumbing Fixtures Market
Bathroom Fixtures and Accessories
Bathroom Vanities Market
Bathroom Fixtures and Accessories
Ceramic Wash Basin Market
Bathroom Fixtures and Accessories
United States Bath Fitting Market
Bathroom Fixtures and Accessories
Europe Bath and Shower Products Market
Bathroom Fixtures and Accessories
Bathroom Furniture Market
Bathroom Fixtures and Accessories
Bath Fittings and Accessories Market
Bathroom Fixtures and Accessories
US Toilet Partition Market
Bathroom Fixtures and Accessories
Baby Changing Tables and Stations Market
Bathroom Fixtures and Accessories
Vietnam Sanitary Ware & Bathroom Accessories Market
Bathroom Fixtures and Accessories
North America Toilet Seat Market
Bathroom Fixtures and Accessories
Bathroom Sink Market
Bathroom Fixtures and Accessories
Toilet Seat Market
Bathroom Fixtures and Accessories
India Steam Rooms Market