
 Global Shower Enclosure and Cubicles Market | 2026-2036
Global Shower Enclosure and Cubicles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Shower Enclosure and Cubicles Market Outlook
After-sales maintenance contracts and digital configuration tools is shifting how shower enclosure vendors capture lifetime value. Kohler leverages its North American service network to lock in recurring revenue from commercial hospitality clients. Jaquar anchors its position across South Asia through localized manufacturing and installer training academies. LIXIL Group differentiates through water-efficiency software integrated into its smart shower systems.
Shower enclosures and cubicles are self-contained bathing compartments fabricated from tempered glass, acrylic, or fiberglass, typically featuring aluminum or stainless steel framing, with specifications including 8-12mm glass thickness and watertight sealing rated to IPX4 or higher, designed to contain water spray and steam within defined bathroom footprints. Frameless and semi-frameless glass configurations dominate premium residential and hospitality specifications, while sliding mechanisms lead in compact urban apartments where space optimization dictates product selection. Acrylic and fiberglass materials sustain demand in healthcare and budget residential segments where cost efficiency and impact resistance outweigh aesthetic priorities.
CE marking under the EU Construction Products Regulation, REACH chemical compliance for sealants and coatings, and EPA WaterSense standards in the United States collectively elevate barrier-to-entry requirements for cross-border suppliers. China's GB standards for bathroom products and India's BIS certification for glass safety add further national compliance layers that shape regional competitive dynamics. Stakeholders must monitor evolving water-efficiency mandates and circular-economy material-recovery rules as these frameworks increasingly determine product eligibility for public procurement and green-building certification programs.
Market Dynamics
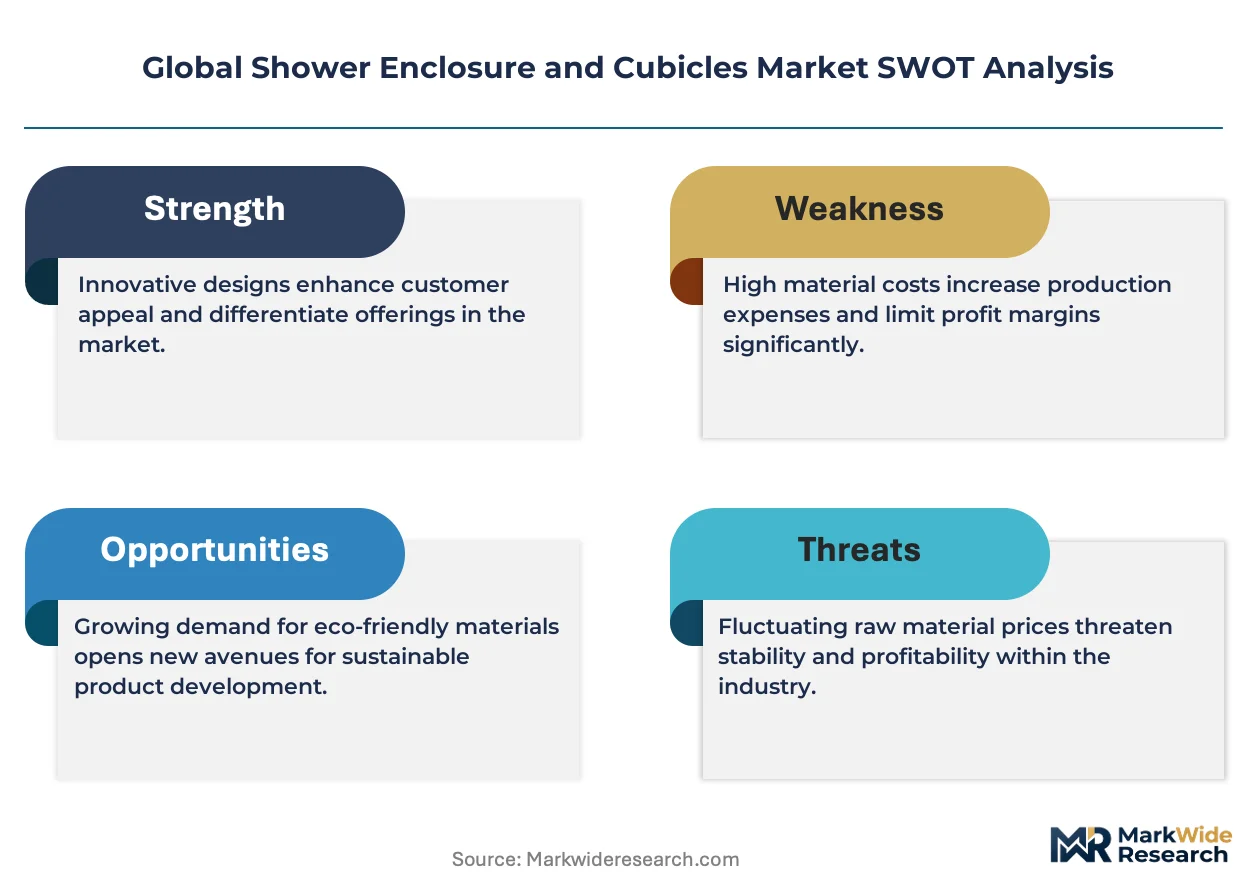
Water-efficiency mandates and circular-economy material-recovery rules are reconfiguring product eligibility for public procurement and green-building certification programs, forcing manufacturers to redesign supply chains and certification strategies.
Growth Catalysts
- EU Green Deal compliance:CE marking under the Construction Products Regulation and REACH chemical standards for sealants are creating preferential procurement pathways for compliant suppliers across German and French hospitality renovation pipelines.
- Urban density patterns:Sliding-door mechanisms optimized for sub-5-square-meter bathrooms are capturing specification share in Tokyo, Shanghai, and Mumbai residential towers where floorplate efficiency dictates design.
- Tempered glass safety codes:China's GB standards and India's BIS certification for 8-12mm glass thickness are accelerating replacement cycles in aging commercial stock across South and East Asian hotel portfolios.
Market Restraints
- Aluminum framing cost volatility:Primary aluminum price swings tied to energy-intensive smelting operations in China and Russia are compressing margin stability for mid-tier frame fabricators.
- Silicone sealant supply concentration:Specialty polymer feedstock production clusters in Germany and Japan create single-source vulnerability for watertight IPX4-rated gasket systems.
- Acrylic substitution ceiling:Impact-resistant fiberglass-reinforced polymer panels face aesthetic disqualification in premium residential segments where frameless glass maintains specification lock-in.
Strategic Opportunities
- Saudi hospitality construction:Giga-project hotel pipelines under MOHAP facility standards are creating demand for large-format custom enclosures with integrated steam-generation compatibility.
- Digital configuration platforms:BIM-integrated specification tools are displacing traditional distributor showrooms in North American commercial contractor procurement workflows.
- WaterSense retrofit incentives:EPA-certified low-flow shower systems bundled with enclosure replacements are unlocking municipal rebate programs in California and Texas multi-family housing authorities.
Industry Challenges
- Installer certification bottlenecks:Frameless glass precision mounting requires specialized glazing trade skills that training academies in India and Indonesia have not yet scaled to match project velocity.
- Multi-standard compliance timelines:Simultaneous GB, BIS, and CE certification processes for a single product variant extend time-to-revenue by 8-14 months for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Shower Enclosure and Cubicles Market |
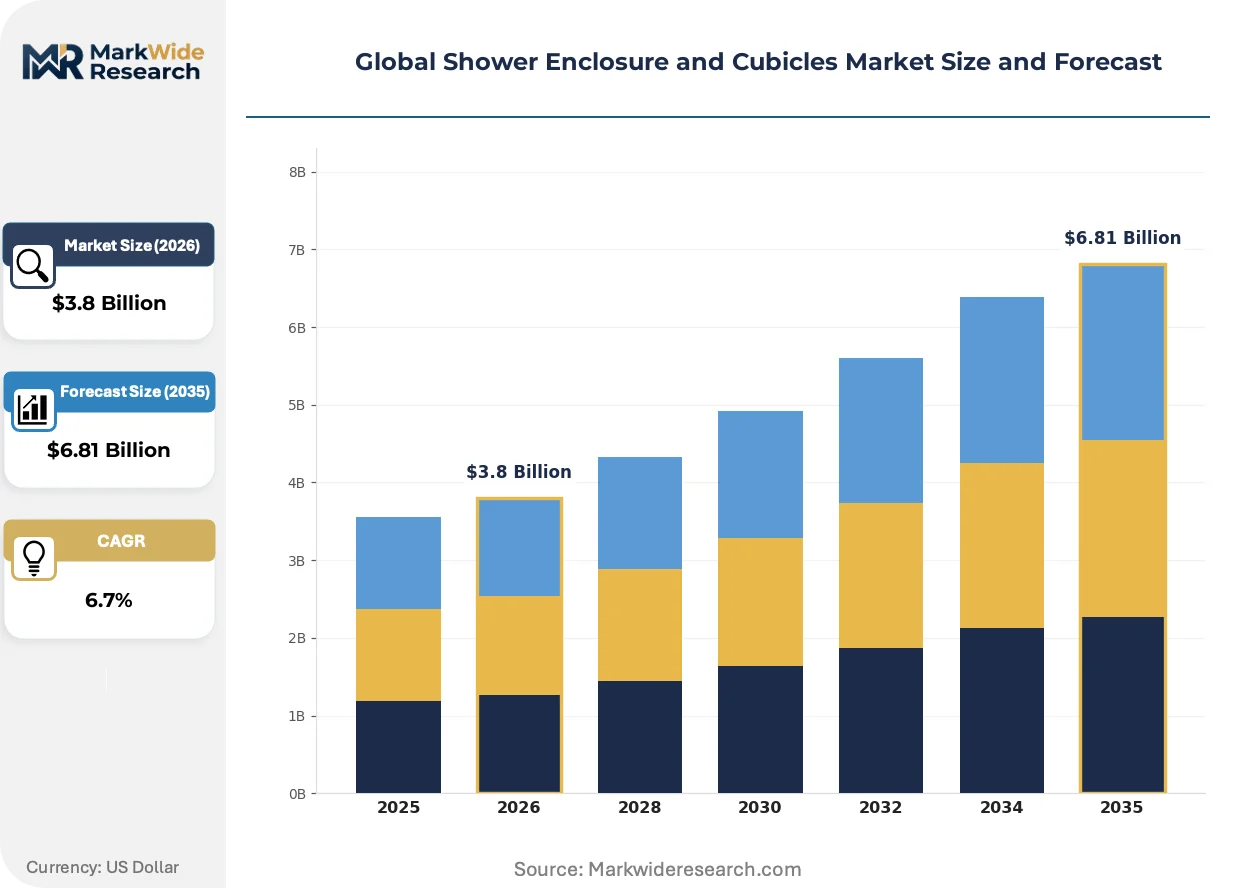
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frameless, Semi-Frameless, Bi-Fold, Sliding Material: Glass, Acrylic, Fiberglass, Stainless Steel Installation Type: Wall-Mounted, Corner, Freestanding, Custom End User: Residential, Commercial, Hospitality, Healthcare |
| Companies Covered | Jaquar, Kohler, LIXIL Group, Duravit, Masco, Huppe, Porcelanosa, American Shower Door Corporation, Hindware Homes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Shower Enclosure and Cubicles Market Strategic Shifts
Smart water-management systems and predictive maintenance architectures are embedding intelligence into previously passive bathroom fixtures, transforming how building operators manage lifecycle costs.
Electrochromic privacy glass is absorbing specification share from traditional frosted and textured alternatives in luxury hospitality and healthcare segments. Marriott and Hyatt design standards now prioritize instant opacity switching for multi-user bathroom flexibility. This technology is absorbing the premium that mechanical blinds and curtains previously commanded in executive suite configurations.
REACH chemical compliance deadlines for per- and polyfluoroalkyl substances in sealant formulations are forcing reformulation investments across European supply chains. Manufacturers serving German and French markets must certify replacement chemistries by 2025 cutoff dates. Healthcare and senior living facilities face the steepest transition costs due to infection-control performance requirements.
Direct-to-contractor digital specification platforms are compressing traditional distributor margins in North American commercial construction. Kohler's proprietary configuration software and Jaquar's installer academy portals are capturing decision-making authority previously held by regional bathroom fixture wholesalers. California and Texas multi-family developers show the fastest platform adoption rates, driven by compressed project timelines and reduced site-visit requirements.
Global Shower Enclosure and Cubicles Market Segmentation
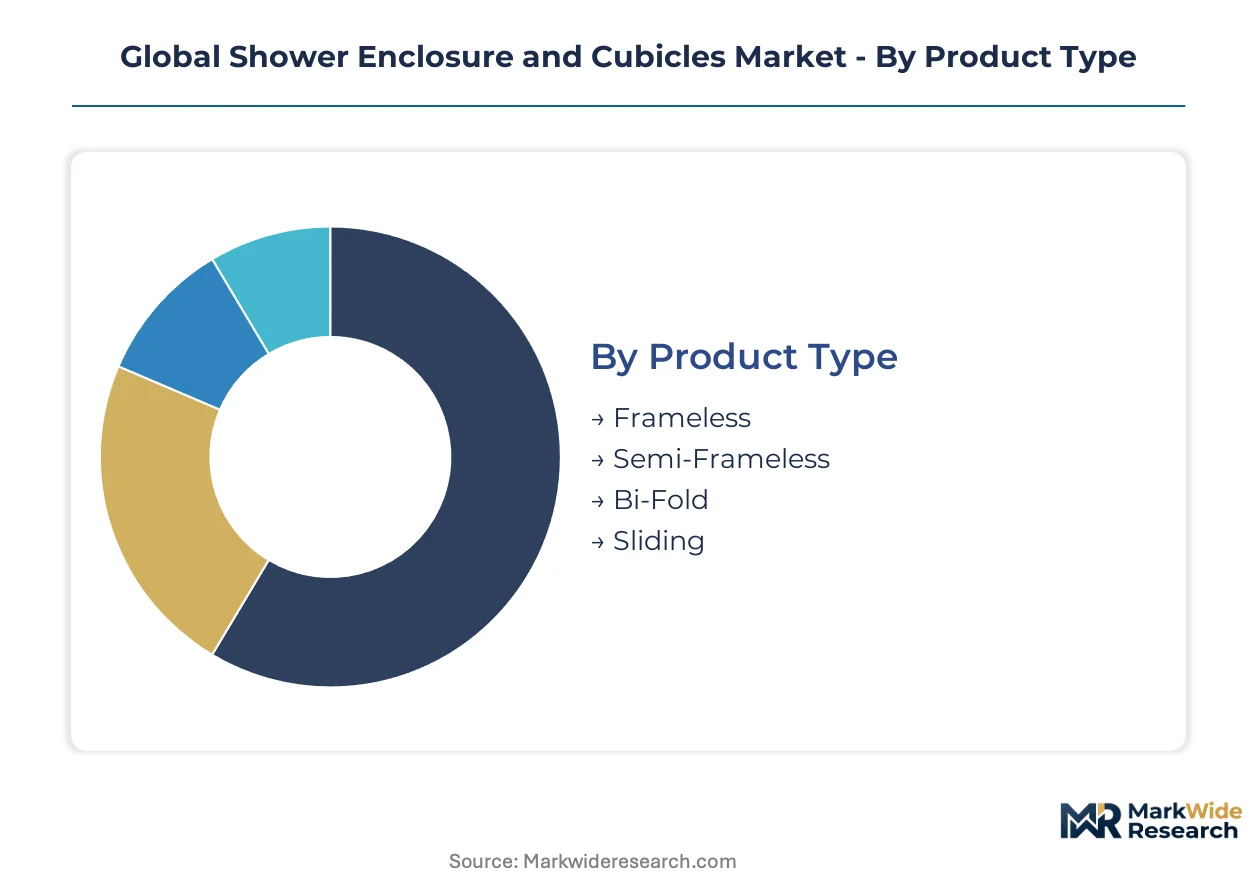
Product configuration and material certification requirements fragment procurement pathways across residential, hospitality, and healthcare verticals. Specification authority concentrates with architects and facilities managers who weight compliance documentation alongside unit economics.
Product Type:
CE marking and REACH sealant compliance create divergent approval timelines across frameless versus framed configurations, with German and French procurement pipelines enforcing the strictest documentation standards.
- Frameless:8-12mm tempered glass panels rely on precision-engineered hardware and specialized glazing trade skills. Premium residential towers in Shanghai and luxury hotel renovations across Southeast Asia specify these for spatial transparency and aesthetic minimalism.
- Semi-Frameless:Aluminum or stainless steel framing on select edges reduces hardware complexity while maintaining visual openness. Mid-tier hospitality projects in Mumbai and budget-conscious residential developments favor this configuration for cost-optimized compliance with BIS glass safety standards.
- Bi-Fold:Hinged folding mechanisms suit ultra-compact bathrooms under 4 square meters. Tokyo micro-apartments and London retrofit projects specify these for space efficiency.
- Sliding:Roller-track door systems dominate sub-5-square-meter bathrooms where swing clearance is unavailable. Chinese GB standards and Indian BIS certification requirements apply to track hardware and glass thickness specifications.
Sliding enclosures sit at the top of the volume ranking, with frameless configurations climbing the fastest.
Material:
Raw material cost tiers and circular-economy recovery rules stratify supplier margins, with glass commanding premium pricing and acrylic sustaining volume in price-sensitive segments.
- Glass:Tempered safety glass rated to GB, BIS, or CE standards dominates premium specifications. Electrochromic privacy variants are absorbing specification share from frosted alternatives in Marriott and Hyatt design standards.
- Acrylic:Impact-resistant polymer panels serve healthcare and senior living facilities where infection control and shatter resistance outweigh aesthetic priorities. REACH chemical compliance deadlines for sealant formulations force reformulation investments across European supply chains.
- Fiberglass:Fiberglass-reinforced polymer composites offer durability in high-traffic commercial environments. Budget residential segments in India and Indonesia specify these for cost efficiency.
- Stainless Steel:Corrosion-resistant framing and hardware components meet IPX4 watertight sealing requirements. Saudi giga-project hotel pipelines under MOHAP facility standards specify these for steam-generation compatibility.
Glass commands the highest value share, with electrochromic variants gaining specification momentum fastest.
Installation Type:
Installer certification bottlenecks and BIM integration readiness differentiate procurement channels, with custom configurations requiring extended lead times and specialized trade coordination.
- Wall-Mounted:Standard alcove installations anchored to structural walls represent the most common specification. Multi-family housing authorities in California and Texas bundle these with WaterSense-certified low-flow systems for municipal rebate eligibility.
- Corner:Two-wall configurations maximize floorplate efficiency in compact urban apartments. Mumbai and Tokyo residential towers specify these for space optimization.
- Freestanding:Self-supporting structures require reinforced subflooring and precise leveling. Luxury hospitality suites and high-end residential bathrooms favor these for design flexibility.
- Custom:Bespoke dimensions and integrated steam-generation systems serve Saudi hospitality giga-projects and specialized healthcare facilities. Digital configuration platforms compress specification timelines for these complex orders.
Wall-mounted installations sustain volume leadership, with custom configurations expanding most quickly in hospitality pipelines.
End User:
Procurement authority and lifecycle cost calculations vary sharply across end-use segments, with commercial and hospitality buyers prioritizing after-sales maintenance contracts over upfront unit costs.
- Residential:Individual homeowners and developers drive demand for frameless and semi-frameless configurations. North American service networks and localized manufacturing anchor competitive positioning in this segment.
- Commercial:Office building facilities managers prioritize durability and standardized replacement parts. Multi-standard compliance timelines extend supplier onboarding by 8-14 months for cross-border vendors.
- Hospitality:Luxury hotel chains across Southeast Asia are expanding bathroom renovation budgets. Electrochromic privacy glass and smart water-management systems embed intelligence into previously passive fixtures.
- Healthcare:Hospitals and senior living facilities face the steepest REACH reformulation transition costs due to infection-control performance requirements. Acrylic and fiberglass materials sustain demand where impact resistance is paramount.
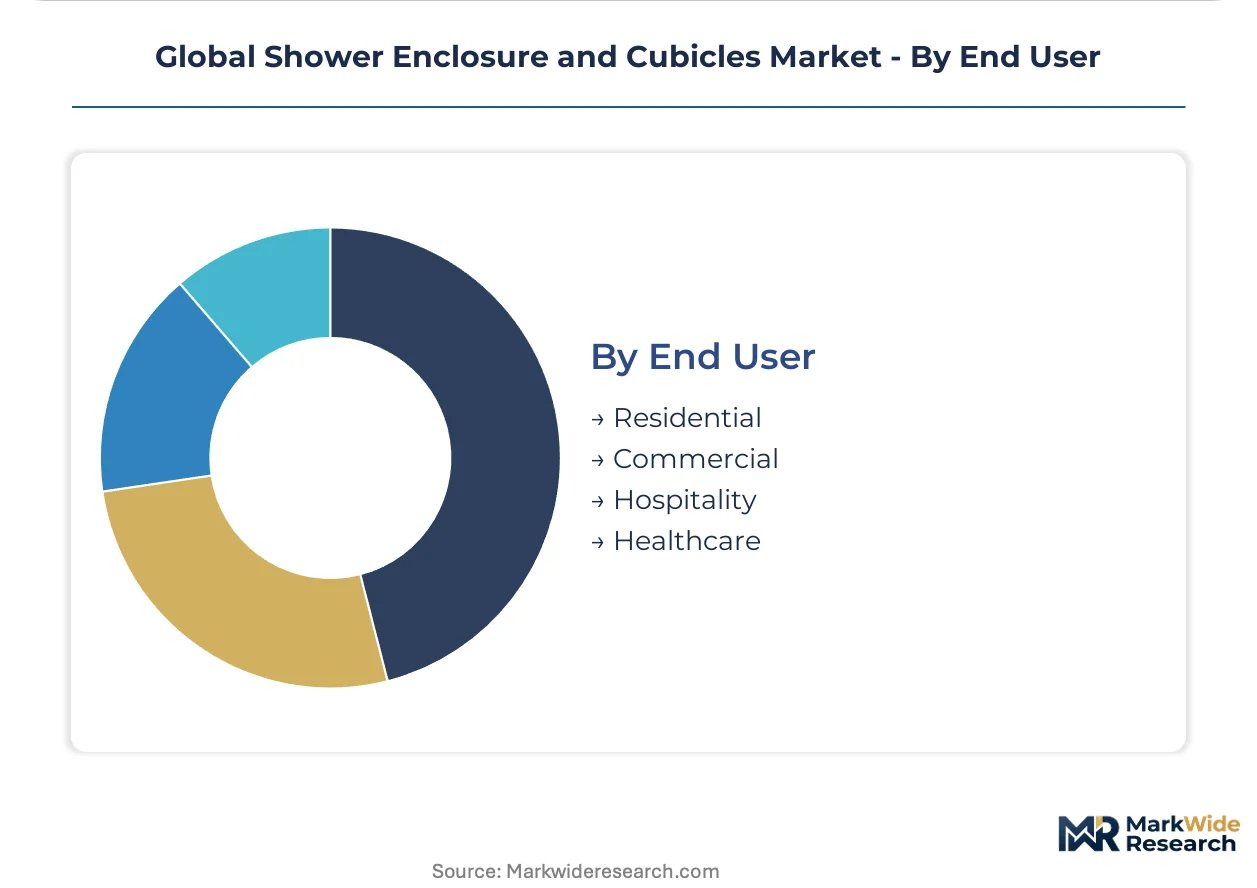
Residential applications hold volume primacy, with hospitality end-use showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China generates substantially higher installation volumes than Germany, yet German procurement pipelines enforce stricter documentation standards that compress supplier margins. Demand concentrates where urban density, hospitality construction, and regulatory tightening intersect.
China
GB standards for bathroom products and tempered glass safety codes drive replacement cycles in aging commercial hotel stock. MIIT industrial policy incentivizes domestic production of high-performance glazing systems. Manufacturing clusters in the Yangtze River Delta supply frameless configurations to Southeast Asian hospitality chains.
Germany
CE marking under the Construction Products Regulation and REACH chemical compliance for sealants create preferential procurement pathways for certified suppliers. KBA-adjacent testing protocols influence hardware durability specifications. Fabricators in North Rhine-Westphalia anchor supply to French and Benelux renovation pipelines.
United States
EPA WaterSense retrofit incentives unlock municipal rebate programs for low-flow shower systems bundled with enclosure replacements. Multi-family housing authorities in California and Texas show fastest adoption of digital specification platforms. Regional service networks lock in recurring commercial hospitality revenue.
India
BIS certification for 8-12mm glass thickness accelerates safety-driven replacement in budget residential and mid-tier hospitality segments. CDSCO-aligned material standards shape healthcare facility procurement. Installer training academies in Maharashtra and Gujarat struggle to scale specialized glazing trade skills to match project velocity.
Saudi Arabia
MOHAP facility standards for giga-project hotel pipelines create demand for large-format custom enclosures with steam-generation compatibility. SFDA-aligned material safety protocols apply to sealant formulations in healthcare-adjacent hospitality configurations. Fabrication clusters in Riyadh and the Eastern Province serve NEOM Northwest construction timelines.
Global Shower Enclosure and Cubicles Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium hospitality specifications favoring integrated service networks while budget residential channels reward scale fabrication. The vendor base organizes around three archetypes: full-service bathroom solution providers, regional glazing specialists with installer training infrastructure, and OEM fabricators serving private-label distributor channels. Consolidation pressure concentrates among mid-tier frame fabricators facing aluminum cost volatility. Strategic moves center on backward integration into tempered glass supply and geographic expansion through digital specification platforms.
Among Asia-Pacific specialists, Jaquar anchors the regional glazing archetype through localized manufacturing and installer academy infrastructure. Kohler occupies a position exemplifying the full-service bathroom solution provider, leveraging North American service networks for commercial hospitality recurring revenue. LIXIL Group sits within the smart-systems tier, representing water-efficiency software integration as a differentiation vector.
| Leading Market Players |
|---|
| Jaquar |
| Kohler |
| LIXIL Group |
| Duravit |
| Masco |
| Huppe |
| Porcelanosa |
| American Shower Door Corporation |
| Hindware Homes |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between CE-marked frameless systems and uncertified acrylic alternatives manifests in divergent margin architectures and procurement channel structures across German hospitality and Indian budget residential verticals. Premium configurations command hardware-intensive supply chains anchored in Yangtze River Delta glass fabrication clusters, while commodity tiers draw from dispersed fiberglass molding operations in Gujarat and Indonesia with minimal documentation overhead.
Pricing Analysis
Capacity additions in China's tempered glass sector are reshaping price floors for 8-12mm safety-rated panels across Southeast Asian hospitality pipelines. Three-tier pricing structure across premium, standard, and economy levels separates electrochromic privacy systems from semi-frameless aluminum-framed units and fiberglass-reinforced polymer alternatives. Cost compression in mid-tier framed configurations is intensifying because primary aluminum price volatility tied to energy-intensive smelting erodes fabricator margins. Commercial hospitality buyers exhibit lowest price sensitivity due to lifecycle cost calculations and maintenance contract bundling, while Indian budget residential developers prioritize unit economics over certification tier.
Supply Chain Analysis
Freight cost differentials between containerized glass shipments and bulk polymer feedstock movements favor regionalized sourcing strategies for frameless versus acrylic product lines. Manufacturing gravity centers on China, Germany, and India, with specialized sealant production tethered to German and Japanese polymer chemistry clusters. Raw material dependencies span tempered glass from Yangtze River Delta foundries, aluminum extrusions from Russian and Chinese smelters, and silicone formulations from Rhine-Ruhr chemical corridors. Single-source vulnerability in specialty gasket systems creates procurement risk for IPX4-rated watertight assemblies. Distribution runs through architect-specified channels in commercial verticals and distributor showrooms in residential retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where REACH chemical compliance deadlines for per- and polyfluoroalkyl substances in sealant formulations are accelerating replacement demand across European healthcare and hospitality facilities.
For Market Incumbents: Acquire installer training academy infrastructure to lock in specification authority as frameless glass precision mounting skills become the binding constraint across Indian and Indonesian project pipelines. Consolidate backward integration into tempered glass supply to neutralize primary aluminum cost volatility compressing mid-tier frame fabricator margins. Certification investment in simultaneous GB, BIS, and CE marking processes defends position against cross-border suppliers facing 8-14 month time-to-revenue penalties. For New Entrants and Emerging Players: Digital specification platforms represent the most penetrable channel for displacing traditional distributor margins in North American commercial contractor procurement workflows. White-space opportunity concentrates in Saudi giga-project hospitality pipelines requiring large-format custom enclosures with steam-generation compatibility under MOHAP facility standards. Go-to-market execution should anchor on BIM-integrated configuration tools that compress specification timelines for complex custom orders. For Investors and Strategic Acquirers: Asymmetric upside sits with regional glazing specialists possessing captive installer academy networks and localized manufacturing footprints across South Asia. Long-term viability over the projection horizon favors archetypes integrating water-efficiency software into hardware systems, mirroring LIXIL Group's smart-systems positioning. The signal to watch is EPA WaterSense retrofit incentive expansion across California and Texas multi-family housing authorities as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tempered Glass Supply | Yangtze River Delta captive production neutralizes aluminum cost volatility for frame fabricators. |
| Installer Academy Network Expansion | Maharashtra and Gujarat training infrastructure addresses glazing trade skill bottlenecks in Indian project pipelines. |
| Digital Configuration Platform Deployment | BIM-integrated tools displace traditional distributor showrooms in California and Texas commercial procurement. |
| Multi-Standard Certification Investment | Simultaneous GB, BIS, and CE marking processes unlock cross-border revenue without 8-14 month delays. |
| Water-Efficiency Software Integration | Smart shower system bundling captures EPA WaterSense municipal rebate eligibility in multi-family housing. |
Study Parameters
Direct dialogue with shower enclosure procurement managers at luxury hospitality chains, facilities directors at healthcare systems, glazing trade contractors, aluminum extrusion procurement leads, and sealant formulation chemists grounded qualitative findings in operational reality. Secondary validation drew from EU Construction Products Regulation documentation, EPA WaterSense certification databases, BIS glass safety standards filings, and trade flow records for tempered glass and aluminum framing components. Bottom-up unit economics triangulated against top-down sector spending patterns across residential, commercial, hospitality, and healthcare verticals.
Segment-level projections across product type, material grade, installation configuration, and end-use vertical populated the analytical framework across the modeling period. CAGRs derived from regression analysis against urban density indices, hospitality construction pipelines, and regulatory compliance deadline schedules. Industry-specific forecast inputs included replacement cycle acceleration from China's GB safety code enforcement and electrochromic privacy glass specification momentum in Marriott and Hyatt design standards.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aluminum price volatility, REACH chemical compliance deadline shifts, and installer certification scaling velocity in emerging markets. Forecasts reflect assumptions around regulatory enforcement consistency and hospitality construction timeline execution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Artificial Stone Bathtubs Market
Bathroom Fixtures and Accessories
Bathroom Cabinets Market
Bathroom Fixtures and Accessories
Europe Steam Room Market
Bathroom Fixtures and Accessories
Smart Toilet Seat Market
Bathroom Fixtures and Accessories
Shower Curtain Market
Bathroom Fixtures and Accessories
Luxury Plumbing Fixtures Market
Bathroom Fixtures and Accessories
Germany Bathroom Furniture Market
Bathroom Fixtures and Accessories
Malaysia Sanitaryware Market
Bathroom Fixtures and Accessories
Europe Bath Fitting Market
Bathroom Fixtures and Accessories
Bathroom Pods Market
Bathroom Fixtures and Accessories
Bath Fittings and Accessories Market
Bathroom Fixtures and Accessories
Ceramic Wash Basin Market
Bathroom Fixtures and Accessories
United Kingdom Bath Fitting Market
Bathroom Fixtures and Accessories
Pullout Faucets Market
Bathroom Fixtures and Accessories
US Smart Kitchen and Bathroom Products Market
Bathroom Fixtures and Accessories
North America Toilet Seat Market