
 Bathroom Furniture Market | 2026-2036
Bathroom Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Bathroom Furniture Market Analysis
European ceramic basin producers is rebalancing capacity toward integrated vanity systems after years of component-only supply. Villeroy & Boch leverages its long-standing kiln expertise to dominate premium glazed-finish segments. JOMOO sustains cost-competitive stainless-steel framing through automated welding lines in Guangdong. Kohler anchors North American distribution through exclusive builder partnerships and dedicated showroom networks.
Bathroom furniture encompasses fixed and movable storage, grooming surfaces, and reflective installations engineered from moisture-resistant substrates with sealed edge banding, typically rated for IPX4 splash-zone exposure. Its commercial purpose centers on organizing hygiene rituals while protecting structural walls from water vapor and chemical cleaners. Vanities and cabinets together command the largest value share, though mirrors with embedded LED demisting and touch controls are expanding fastest as hotels and luxury residential buyers prioritize wellness aesthetics. Wood and MDF remain the dominant material pairing, with MDF gaining in mid-market flat-pack distribution where precision CNC routing enables complex basin cutouts at scale.
EPA WaterSense specifications in the United States and EU Ecodesign requirements under the F-Gas Regulation and broader Green Deal framework constrain faucet-integrated vanity designs, pushing manufacturers toward lower-flow compatibility. CE marking and REACH chemical compliance create non-tariff barriers for Asian exporters seeking European retail placement. Stakeholders must monitor evolving national building codes that increasingly mandate accessibility clearances and recycled-content thresholds in public procurement tenders.
Market Dynamics
EU Green Deal building-efficiency mandates are compressing renovation timelines across residential construction, forcing bathroom furniture procurement toward water-integrated vanity systems and certified sustainable materials.
Growth Catalysts
- EU Ecodesign requirements:The F-Gas Regulation and broader Green Deal framework mandate lower-flow fixture compatibility, pulling demand toward integrated vanity-basin systems in German and French residential developments.
- Urban housing cluster formation:Middle-class household expansion in China, India, and Brazil accelerates bathroom upgrade cycles in high-density metropolitan zones.
- FSC-certified wood sourcing:Procurement specifications across European retail channels now require chain-of-custody documentation, favoring suppliers with captive forestry assets.
Market Restraints
- CE marking and REACH compliance:Chemical substance restrictions create non-tariff barriers for Asian exporters seeking European retail placement, extending certification timelines.
- MDF substrate cost volatility:Resin and fiber input prices fluctuate with energy markets, compressing margins in mid-market flat-pack distribution.
- IPX4 splash-zone rating requirements:Moisture-resistance testing protocols limit material substitutions and raise engineering costs for vanity edge-banding systems.
Strategic Opportunities
- LED demisting mirror convergence:Wellness aesthetics in luxury residential and hospitality segments create white space for touch-control reflective installations with embedded heating elements.
- Accessibility clearance mandates:Evolving national building codes in public procurement tenders specify universal design requirements, opening specification channels for adjustable-height vanity systems.
- Automated welding scale:Guangdong-based stainless-steel framing production demonstrates cost-competitive pathways for robotic assembly integration in emerging manufacturing bases.
Industry Challenges
- CNC programming talent scarcity:Precision routing for complex basin cutouts requires specialized operators, creating bottlenecks in mid-market flat-pack scaling.
- Recycled-content threshold verification:Public procurement documentation demands third-party chain-of-custody audits, extending bid preparation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bathroom Furniture Market |
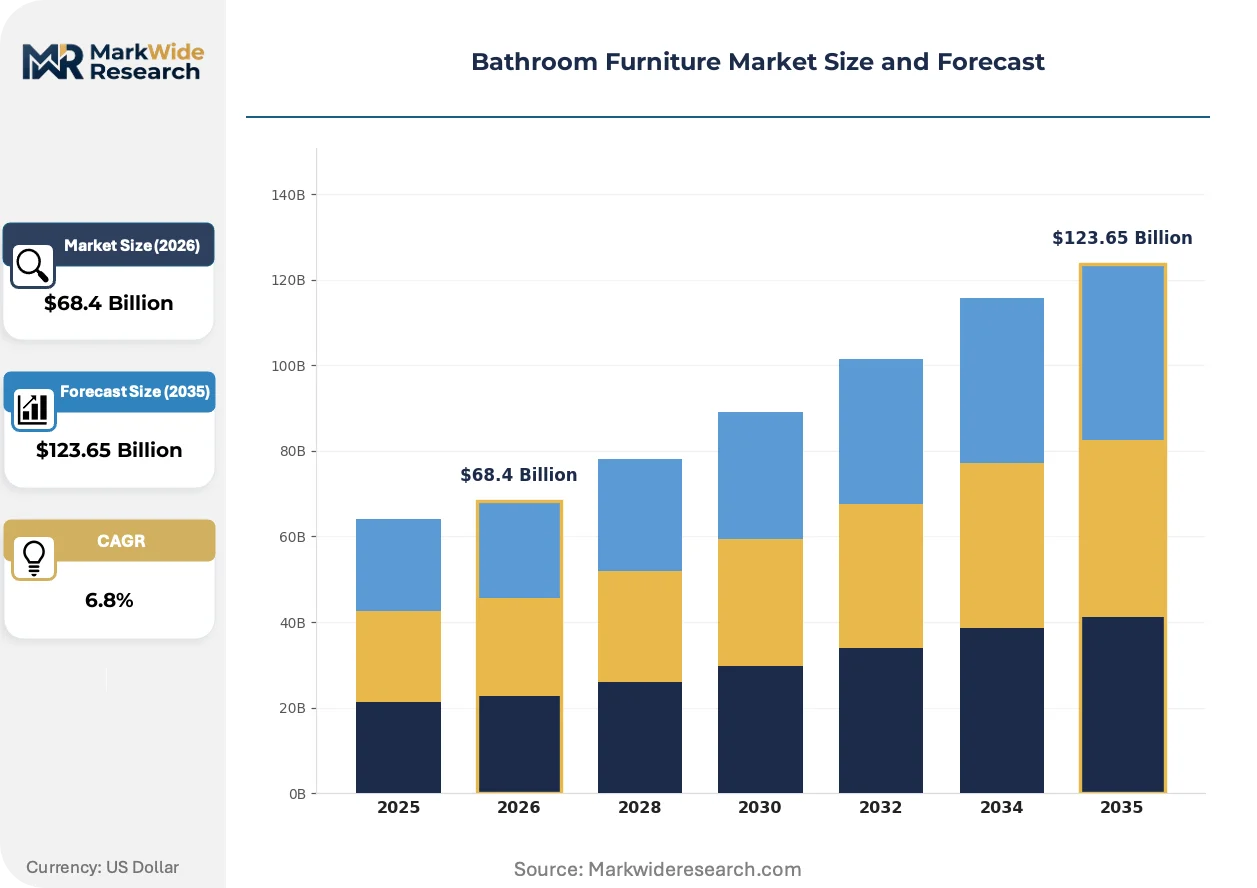
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vanities, Cabinets, Shelves, Mirrors Material: Wood, MDF, Glass, Metal Style: Modern, Traditional, Rustic, Contemporary End User: Residential, Commercial, Hospitality, Healthcare |
| Companies Covered | Villeroy & Boch, JOMOO, Kohler, Virtu USA, James Martin Furniture, Roca, Geberit, LAUFEN, Duravit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bathroom Furniture Market Emerging Trajectories
Digital fabrication and regulatory chemistry constraints are simultaneously elevating manufacturing precision and material compliance requirements across bathroom furniture supply chains.
Automated welding lines are automating stainless-steel frame production for vanity support structures. Guangdong-based manufacturers deploy robotic seam welding to achieve IPX4-rated joints at throughput rates manual operations cannot match. This automation is compressing cost structures in mid-market segments and displacing traditional spot-weld assembly across export-oriented production bases.
REACH chemical compliance is redefining substrate specifications for European market entry. The ECHA restriction list now governs formaldehyde emissions in MDF edge-banding adhesives, forcing reformulation of moisture-resistant sealants. Vanity manufacturers serving German and French retail channels have shifted procurement toward low-emission PUR adhesives certified under updated emission class standards.
Builder partnership exclusivity is consolidating specification influence in North American distribution. Kohler's dedicated showroom networks and direct-to-developer contracting have compressed traditional distributor margins in multi-family residential projects. This channel concentration is most visible in Texas and Florida metropolitan construction corridors where volume builders centralize bathroom package decisions.
Bathroom Furniture Market Segmentation
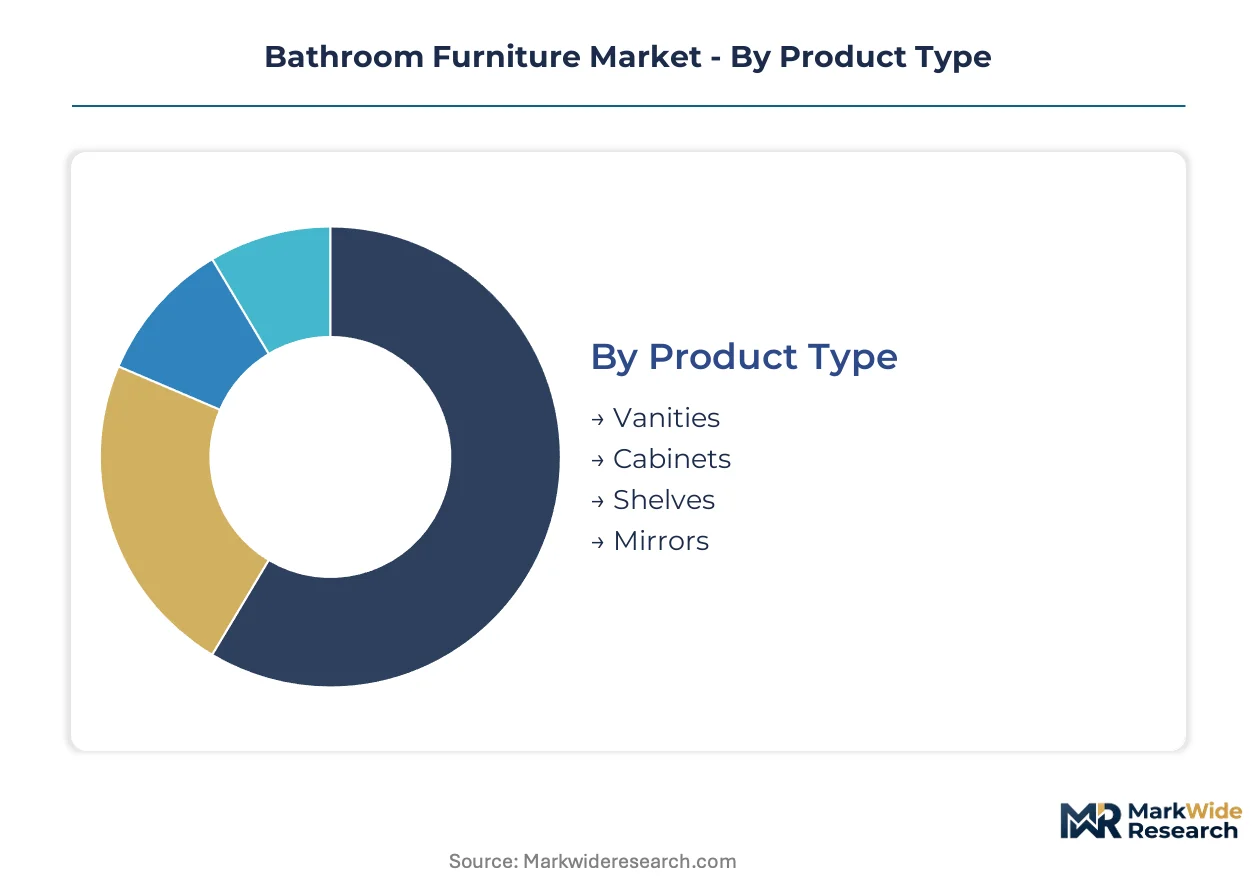
Bathroom furniture procurement divides sharply between moisture-resistance certifications for splash-zone applications and aesthetic specifications for dry-storage installations. Material compliance with REACH and FSC chain-of-custody requirements creates divergent cost structures across segment tiers.
Product Type:
CE marking and IPX4 splash-zone ratings concentrate certification burdens on integrated basin-vanity combinations rather than standalone storage units.
- Vanities:Engineered with sealed edge-banding and moisture-resistant substrates to withstand IPX4 splash-zone exposure. German and French residential developers specify these for water-integrated systems under EU Ecodesign mandates. MDF construction with PUR adhesive sealing dominates mid-market flat-pack distribution.
- Mirrors:Embedded LED demisting and touch-control interfaces require electrical safety certifications alongside moisture ratings. Hospitality buyers in urban China and India prioritize wellness aesthetics with heated reflective surfaces, driving specification volume in luxury segments.
- Cabinets:Wall-mounted and floor-standing storage units face lower certification thresholds, concentrating demand in retrofit renovation cycles.
- Shelves:Open storage formats compete on material sourcing transparency rather than technical compliance, favoring FSC-certified wood suppliers.
Vanities sit at the top of the volume ranking, with mirrors climbing the fastest.
Material:
Cost tier stratification separates premium solid-wood sourcing from economy MDF flat-pack production, with resin price volatility compressing mid-market margins.
- MDF:Precision CNC routing enables complex basin cutouts at scale for flat-pack distribution. Energy-linked resin and fiber input costs create margin pressure in mid-market segments serving Brazilian and Indian urban housing clusters.
- Wood:FSC-certified chain-of-custody documentation now gates European retail placement, favoring suppliers with captive forestry assets. German and French procurement specifications mandate verified sustainable sourcing for residential developments.
- Metal:Stainless-steel framing achieves IPX4-rated joints through automated robotic welding in Guangdong production bases.
- Glass:Tempered and laminated formats serve decorative mirror backing and shelving applications with lower regulatory burden than structural substrates.
MDF commands the largest production volume, while certified wood sourcing gains specification share fastest.
Style:
Application context determines style selection, with hospitality and healthcare segments imposing distinct aesthetic requirements on procurement.
- Modern:Clean lines and handle-less surfaces align with LED-integrated mirror specifications in luxury residential and hotel segments across China and India.
- Contemporary:Transitional aesthetics bridge traditional and modern formats, capturing renovation demand in mature European housing stock.
- Traditional:Ornate detailing and classic hardware specifications persist in heritage property renovations and upscale residential developments.
- Rustic:Distressed finishes and reclaimed wood aesthetics target boutique hospitality and vacation rental segments with lower certification requirements.
Modern styling leads specification volume, with contemporary formats expanding most quickly across retrofit markets.
End User:
Customer type dictates accessibility clearance mandates and recycled-content thresholds in public procurement tenders versus private residential flexibility.
- Residential:Middle-class household formation in China, India, and Brazil accelerates bathroom upgrade cycles in high-density metropolitan zones. Volume builders in Texas and Florida centralize package decisions through exclusive supplier partnerships.
- Hospitality:Wellness aesthetics drive LED demisting mirror adoption and premium glazed-finish specifications in luxury hotel developments.
- Healthcare:Evolving national building codes mandate accessibility clearances and infection-control surfaces in public procurement tenders.
- Commercial:Office and retail fit-outs prioritize durability and standardized maintenance protocols over design differentiation.
Residential demand dominates volume, with hospitality segments showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as Asian producers exploit compliance-cost gaps to serve European and North American demand. Production clusters in Guangdong and Zhejiang provinces leverage automated welding scale to offset REACH certification burdens for EU-bound exports.
United States
Multi-family residential construction in Texas and Florida metropolitan corridors centralizes bathroom package decisions through exclusive builder partnerships. EPA WaterSense specifications constrain faucet-integrated vanity designs, pulling procurement toward lower-flow compatibility. Volume builders in Houston and Miami-Dade counties consolidate specification influence through dedicated showroom networks.
Germany
Residential developers in Bavaria and North Rhine-Westphalia expand renovation budgets under tightening EU Green Deal building-efficiency mandates. The F-Gas Regulation and Ecodesign requirements enforce chain-of-custody documentation for FSC-certified wood sourcing. Ceramic basin producers in the Rhineland rebalancing capacity toward integrated vanity systems after years of component-only supply.
China
Middle-class household formation in Shanghai and Shenzhen accelerates bathroom upgrade cycles in high-density metropolitan zones. MIIT industrial standards and GB certification requirements govern domestic moisture-resistance testing protocols. Guangdong-based manufacturers deploy robotic seam welding to achieve IPX4-rated joints at throughput rates manual operations cannot match.
India
Urban housing cluster formation in Mumbai and Bangalore drives specification volume for cost-competitive flat-pack distribution. BIS certification requirements and DGFT import regulations create compliance thresholds for European and Asian suppliers. Precision CNC routing operations in Gujarat and Tamil Nadu enable complex basin cutouts at scale for mid-market segments.
Brazil
Middle-class residential development in São Paulo and Rio de Janeiro concentrates demand for MDF-construction vanities with moisture-resistant edge-banding. ANVISA chemical substance regulations and national building code accessibility mandates shape procurement specifications. Local distributors in the Southeast region prioritize FSC-certified wood transparency to capture European export alignment.
Bathroom Furniture Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue wellness-integrated and accessibility-specialized segments. The vendor base stratifies across premium glazed-finish specialists, cost-competitive stainless-steel framers, and mid-market flat-pack distributors. Three archetypes dominate: kiln-heritage ceramic producers, automated-scale metal fabricators, and exclusive-channel plumbing integrators. Competitive moves concentrate on builder partnership exclusivity and robotic welding capacity expansion.
Among European kiln-heritage specialists, Villeroy & Boch and Duravit occupy positions exemplifying premium glazed-finish expertise. Guangdong-based JOMOO represents the automated-scale archetype through cost-competitive stainless-steel framing production. Kohler anchors the exclusive-channel vector through North American builder partnership networks. These three entities collectively illustrate the geographic and strategic segmentation defining competitive positioning across the analysis window.
| Leading Market Players |
|---|
| Villeroy & Boch |
| JOMOO |
| Kohler |
| Virtu USA |
| James Martin Furniture |
| Roca |
| Geberit |
| LAUFEN |
| Duravit |
| Others |
Supply Flow & Price Mechanics
EU Ecodesign requirements and FSC-certified wood sourcing mandates gate qualified supply access and premium-tier pricing power, compressing margins for uncertified producers while rewarding chain-of-custody documentation with specification placement in German and French residential developments. The interaction between regulatory compliance costs and buyer willingness to pay for verified sustainability credentials stratifies the market into certified-premium and uncertified-economy tiers with limited middle-ground viability.
Pricing Analysis
Distributor margins in European retail channels absorb REACH compliance certification costs before products reach specification buyers, while direct-to-developer contracting in Texas and Florida metropolitan corridors compresses traditional markup layers through exclusive builder partnerships. Three-tier pricing structure across premium glazed-finish, standard MDF flat-pack, and economy unframed component levels separates Villeroy & Boch kiln-heritage positioning from Guangdong automated-scale competition. Pricing pressure stems from resin and fiber input cost volatility in energy-linked MDF substrate markets, squeezing mid-market flat-pack producers serving Brazilian and Indian urban housing clusters. Volume builders in North American multi-family residential construction exhibit highest price sensitivity, while luxury hospitality buyers in Shanghai and Shenzhen prioritize wellness-aesthetic specifications over unit cost.
Supply Chain Analysis
CNC programming talent scarcity in Gujarat and Tamil Nadu precision routing operations constrains throughput scaling for complex basin cutouts, while robotic welding technician availability in Guangdong province enables IPX4-rated stainless-steel frame production at manual-operation-defying rates. Manufacturing concentration centers on China, India, and Germany, with raw material dependencies spanning FSC-certified timber from Baltic and Nordic forestry assets, resin and fiber inputs for MDF substrates tied to petrochemical feedstock pricing, and ceramic glaze formulations requiring specific mineral compositions. Supply chain risk manifests in single-source vulnerability for automated welding equipment and precision CNC spindle components, where replacement timelines extend procurement cycles. Distribution runs through exclusive builder partnership networks in North America, specialized bathroom retailers in Germany and France, and direct-to-contractor channels in Brazilian and Indian urban construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bathroom furniture market reads as a late-cycle quality story where specification buyers in hospitality and luxury residential segments prioritize FSC-certified sourcing and LED-integrated wellness aesthetics over economy-tier alternatives, compressing volume for undifferentiated producers.
For Market Incumbents: Extend kiln-heritage expertise into integrated vanity-basin systems rather than component-only supply, capturing specification influence as EU Ecodesign mandates pull demand toward water-integrated solutions. Invest in captive FSC-certified forestry assets or long-term chain-of-custody partnerships to defend margin position against resin-cost volatility in MDF-dependent mid-market tiers. Automated welding capacity expansion in Guangdong-style production bases offers cost-competitive positioning against emerging stainless-steel framers threatening European ceramic producers. For New Entrants and Emerging Players: LED demisting mirror technology with embedded heating elements and touch-control interfaces offers specification entry into wellness-aesthetic-driven hospitality segments in urban China and India where incumbent ceramic producers lack electrical safety certification expertise. Target accessibility-clearance adjustable-height vanity systems for healthcare and public procurement tenders where evolving national building codes create specification white space. Go-to-market execution should emphasize direct contracting with volume builders in Texas and Florida metropolitan corridors, bypassing distributor margin layers entirely. For Investors and Strategic Acquirers: Roll-up economics work for automated-scale metal fabricators with robotic welding capacity because fragmented mid-market flat-pack distribution in Brazil and India rewards consolidated procurement leverage over resin and fiber inputs. Five-to-ten year viability hinges on positioning for EU Green Deal building-efficiency mandate acceleration and accessibility requirement expansion in public procurement. Acquisition targets should demonstrate either captive FSC-certified forestry assets or precision CNC routing scale with IPX4 certification pathways. Watch for inflection in German and French renovation budget expansion rates as the signal for premium-tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Welding Capacity Expansion | Guangdong-based robotic seam welding achieves IPX4-rated joints at throughput rates manual operations cannot match. |
| FSC-Certified Forestry Backward Integration | Captive chain-of-custody documentation gates European retail placement under tightening EU Green Deal procurement specifications. |
| LED Demisting Mirror Technology Launch | Embedded heating elements and touch-control interfaces capture wellness-aesthetic specification in luxury hospitality segments. |
| Exclusive Builder Partnership Networks | Kohler-style direct-to-developer contracting in Texas and Florida corridors compresses traditional distributor margins. |
| Accessibility-Clearance Product Development | Adjustable-height vanity systems open specification channels for evolving national building code mandates in public procurement. |
Methodological Framework
Coverage spans Germany, France, China, India, Brazil, and the United States, with primary inputs from each market's stakeholder ecosystem combining interviews with residential development procurement directors, hospitality FF&E specification managers, bathroom furniture manufacturing plant managers, and ceramic basin kiln operations leads with secondary validation. Trade data from customs records, EU Ecodesign regulatory filings, EPA WaterSense certification databases, and SEC 10-K disclosures of publicly traded building products companies anchored supply-side assessment. Bottom-up unit economics triangulated against top-down construction spending and renovation cycle data.
Granularity-level modeling disaggregated volume and value outputs across product type (vanities, mirrors, cabinets, shelves), material substrate (MDF, FSC-certified wood, stainless steel, glass), and end-user segment (residential, hospitality, healthcare, commercial) throughout the forecast period. CAGRs derived from regression analysis against macro construction indicators and regulatory mandate implementation timelines. Industry-specific forecast inputs included EU Green Deal building-efficiency mandate compliance cost curves and middle-class household formation rates in Chinese, Indian, and Brazilian urban housing clusters.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to resin and fiber input cost volatility, REACH chemical restriction list updates, and accessibility clearance mandate expansion timing in public procurement tenders. Forecasts reflect documented assumptions regarding regulatory implementation schedules and renovation budget elasticity in German and French residential construction. Material deviation in EU Ecodesign enforcement intensity or FSC certification audit capacity constraints warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Asia Pacific Bath Fitting Market
Bathroom Fixtures and Accessories
Plumbing Fixtures and Fittings Market
Bathroom Fixtures and Accessories
Australia Bathroom Products Market
Bathroom Fixtures and Accessories
Water Sink Market
Bathroom Fixtures and Accessories
Bathtub Market
Bathroom Fixtures and Accessories
India Bath Fittings Market
Bathroom Fixtures and Accessories
Shower Tray Market
Bathroom Fixtures and Accessories
Bathroom Worktops Market
Bathroom Fixtures and Accessories
US Toilet Partition Market
Bathroom Fixtures and Accessories
United States Bath Fitting Market
Bathroom Fixtures and Accessories
Sanitary Ware and Bathroom Accessories Market
Bathroom Fixtures and Accessories
New Zealand Bathroom Products Market
Bathroom Fixtures and Accessories
Bathroom Cabinets Market
Bathroom Fixtures and Accessories
Bathroom Accessories Market
Bathroom Fixtures and Accessories
Bathroom Vanities Market
Bathroom Fixtures and Accessories
Smart Toilet Seat Market