
 Bathroom Worktops Market | 2026-2036
Bathroom Worktops Market Size, Share, and Industry Trends Forecast 2026-2036
Bathroom Worktops Market Outlook
Specialist bathroom retailers and direct-to-builder channels is reconfiguring how fabricated surfaces reach end users. Cosentino leverages its quartz manufacturing scale to dominate specification-driven commercial projects. Kohler sustains brand strength through captive distribution and integrated fixture-worktop bundling. DuPont anchors the premium solid-surface segment with Corian's recognized performance credentials in moisture-intensive environments.
Bathroom worktops are engineered horizontal surfaces installed above vanities or storage units, typically fabricated from stone, engineered composites, or synthetic laminates with thicknesses ranging from 20mm to 40mm and moisture-resistant edge sealing to prevent substrate degradation in humid conditions. Their primary purpose is to provide durable, hygienic workspace for grooming activities while supporting integrated sink and fixture installations. Quartz surfaces command the widest specification penetration among material types due to non-porous performance and color consistency. Custom sizing generates premium margin pools as fabrication shifts from mass stock to templated, site-specific production. Modern design styling leads volume in new residential construction, while traditional styling sustains replacement demand in heritage property renovations.
FDA guidelines on surface sanitization compatibility influence material selection in healthcare-adjacent hospitality bathrooms, while EPA VOC emissions standards constrain adhesive and sealant formulations used in fabrication and installation. WaterSense specifications in the United States restrict eligible product pairings, affecting how worktop suppliers qualify for federal procurement and rebate programs. ISO 4586 laminate performance standards govern European export compliance, creating certification barriers for non-compliant Asian manufacturers. Stakeholders must monitor evolving chemical disclosure requirements under REACH and state-level restricted substance lists to preserve market access across major demand centers.
Market Dynamics
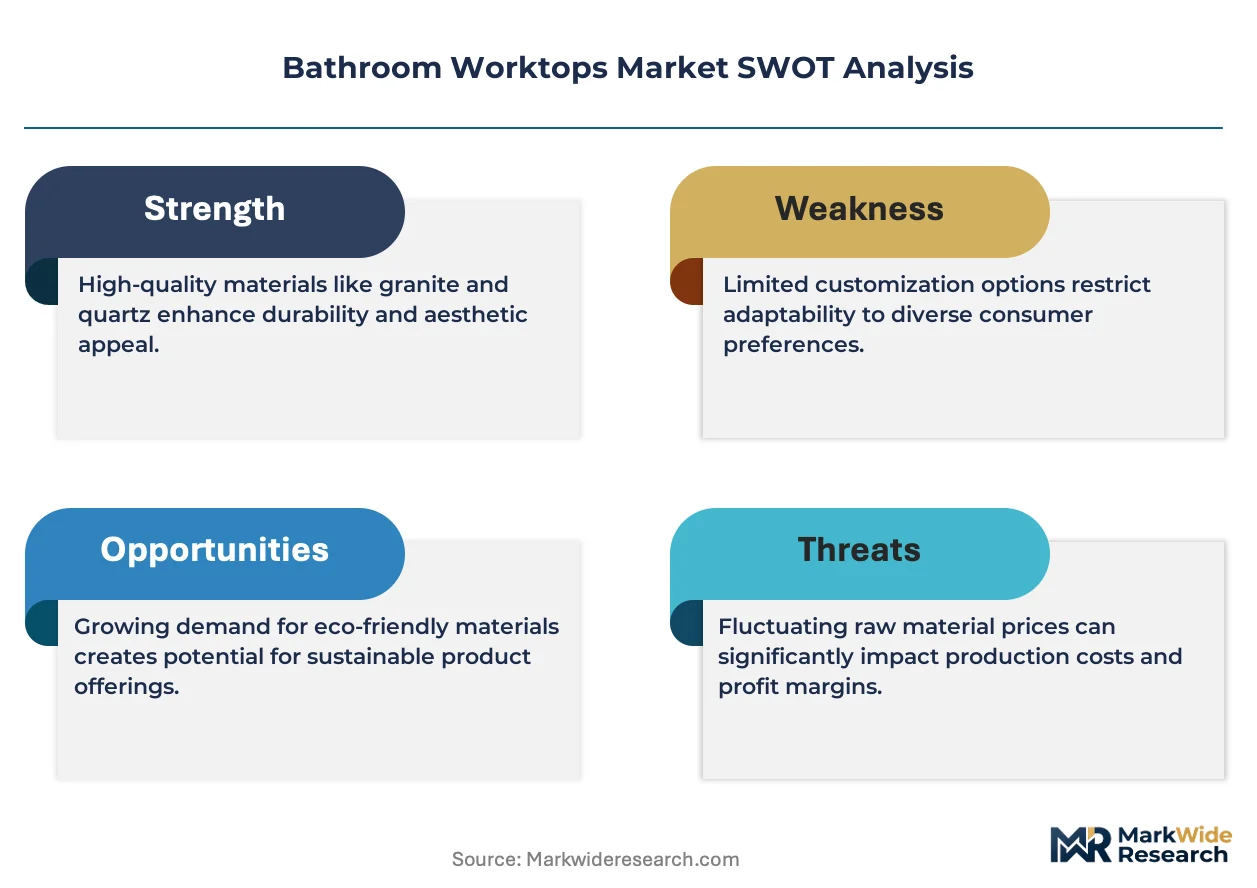
WaterSense certification requirements in the United States are tightening surface-material compatibility standards, forcing fabricators to requalify product pairings and reshaping procurement eligibility for federal rebate programs.
Growth Catalysts
- Luxury hospitality renovations:Premium hotel chains are expanding specification-grade quartz installations across bathroom portfolios, creating sustained demand for high-performance engineered surfaces with color consistency guarantees.
- REACH chemical disclosure evolution:Expanding substance restrictions under the European framework are accelerating substitution toward compliant resin formulations in laminate and solid-surface production.
- Germany's Saarland manufacturing cluster:Concentrated premium bathroom fixture production around this regional hub generates localized pull for templated, site-specific worktop fabrication with integrated sink compatibility.
Market Restraints
- Petrochemical resin cost volatility:Engineered quartz and solid-surface substrates depend on petroleum-derived binders, exposing margins to crude price swings without long-term supply contracts.
- Asian laminate manufacturer concentration:Non-compliant producers face ISO 4586 certification barriers for European export, creating supply bottlenecks when regional demand spikes exceed qualified capacity.
- Granite substitution threat:Natural stone fabricators compete on price for heritage renovation projects where traditional styling preferences override performance specifications.
Strategic Opportunities
- Healthcare-adjacent hospitality bathrooms:FDA surface sanitization guidelines create specification openings for materials with verified antimicrobial performance credentials in clinic-hotel hybrid properties.
- Direct-to-builder digital channels:Specialist bathroom retailers are reconfiguring distribution, enabling fabricators to bypass wholesale markup and capture template-to-install margin pools.
- Custom sizing premium migration:Templated production replacing mass stock generates margin expansion as fabrication shifts toward site-specific measurement and CNC cutting workflows.
Industry Challenges
- Moisture-resistant edge sealing skill gaps:Fabrication shops struggle to train technicians on 20mm to 40mm substrate sealing protocols that prevent humidity degradation in steam-intensive bathroom environments.
- WaterSense pairing certification timelines:EPA qualification procedures for fixture-worktop combinations extend product development cycles, delaying eligibility for federal procurement programs.
- VOC emissions compliance complexity:Adhesive and sealant formulations must simultaneously satisfy EPA standards and evolving state-level restricted substance lists, multiplying formulation testing requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bathroom Worktops Market |
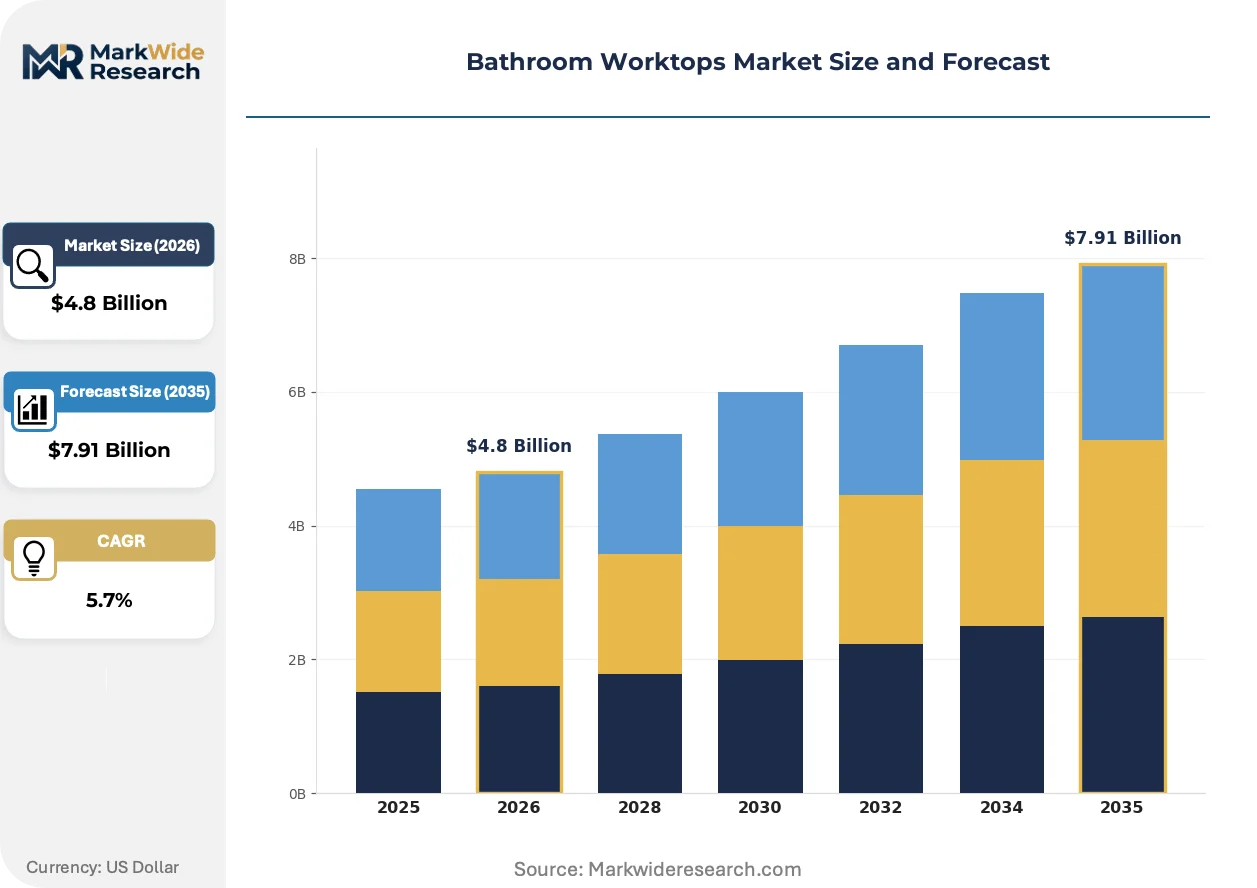
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Granite, Quartz, Marble, Laminate Design Style: Modern, Traditional, Rustic, Minimalist Size: Standard, Custom, Small, Large Installation Method: Top-Mount, Under-Mount, Wall-Mounted, Integrated |
| Companies Covered | DuPont, Cosentino, Caesarstone, Cambria, Kohler, Duravit, Villeroy & Boch, American Standard, TOTO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bathroom Worktops Market Strategic Shifts
Digital templating and CNC fabrication are compressing lead times while enabling mass customization, reshaping how fabricated surfaces move from quarry or resin plant to finished installation.
Laser measurement and CAD-driven cutting is digitizing the templating workflow for quartz and solid-surface materials. High-end residential developers and commercial hospitality specifiers are adopting these systems at accelerating rates. The technology is digitizing what was previously a manual, error-prone process, compressing fabrication lead times from weeks to days.
EPA VOC emissions standards are constraining adhesive and sealant chemistries used in fabrication and installation. Manufacturers must reformulate bonding agents to maintain structural performance while meeting tightening thresholds. Solid-surface and laminate segments face the steepest compliance costs, with European exporters additionally navigating REACH substance restrictions.
Builder-direct procurement is displacing traditional wholesale distribution for specification-grade materials. Large residential developers and hospitality renovation contractors now source templated worktops through dedicated account programs, bypassing retailer markup. This pattern concentrates most visibly in Germany's premium bathroom manufacturing cluster and comparable North American metro construction corridors.
Bathroom Worktops Market Segmentation
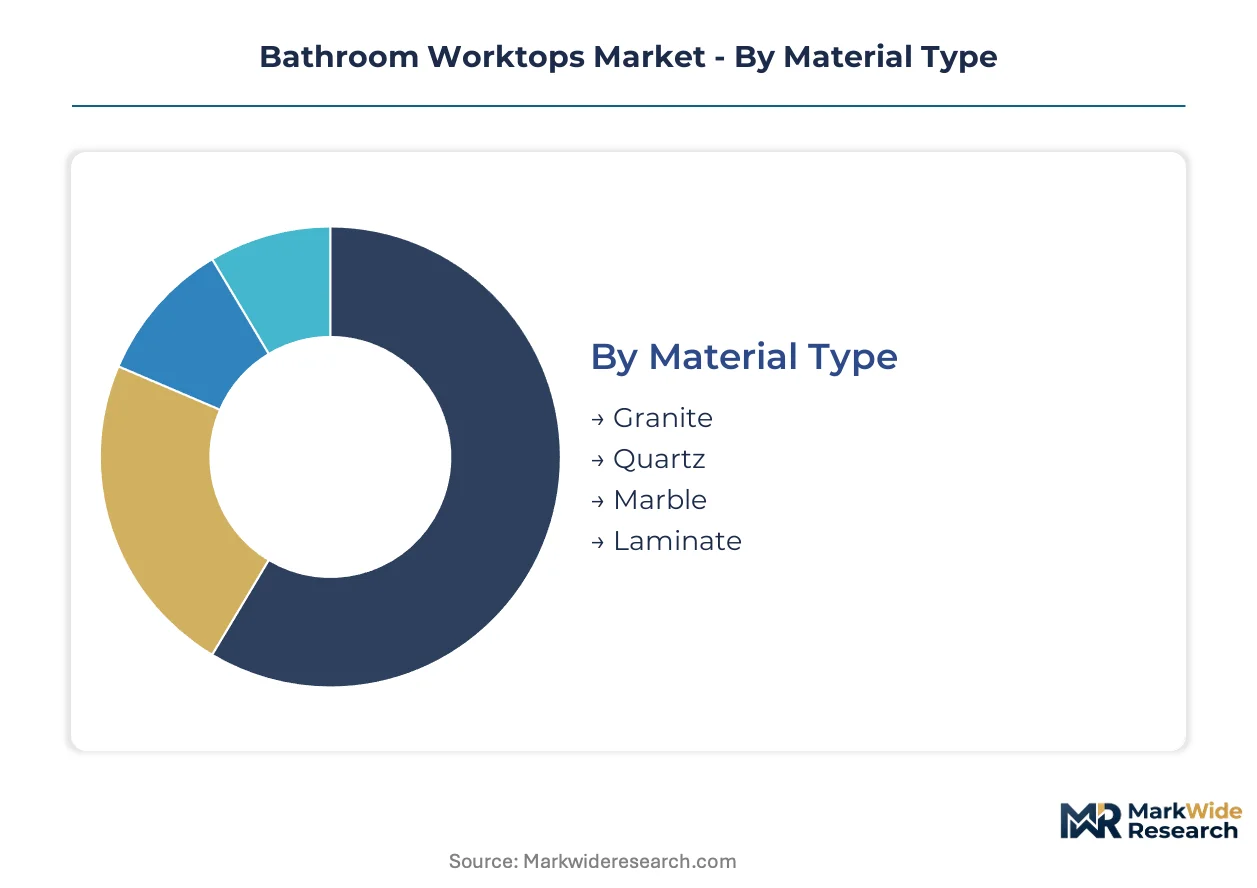
Segmentation in bathroom worktops reveals how fabrication complexity, specification requirements, and installation protocols create distinct margin pools. Material selection dictates moisture-resistance performance and after-sales service intensity. Design styling, sizing flexibility, and mounting methods further stratify procurement channels and customer relationships.
Material Type:
After-sales service intensity varies sharply across material categories, with engineered surfaces requiring warranty support for seam integrity and natural stone demanding periodic resealing protocols.
- Quartz:Engineered stone combines ground quartz with polymer resins to create non-porous, color-consistent slabs. Demand concentrates in luxury hospitality renovations across Germany's Saarland manufacturing cluster, where specification-grade installations require certified fabricator networks for warranty validation.
- Granite:Igneous rock slabs offer natural pattern variation and heat resistance but require periodic sealing maintenance. Heritage property renovations in traditional styling segments sustain demand where authentic material credentials override performance specifications.
- Marble:Metamorphic limestone prized for veining aesthetics and thermal conductivity. Premium residential developers specify marble for spa-adjacent bathrooms despite etching susceptibility from acidic cleaning agents.
- Laminate:Kraft paper and resin composite layers bonded under heat and pressure. Budget-conscious multi-family housing projects in North America specify laminate for volume installations where replacement cycles exceed durability concerns.
Quartz holds the largest share; momentum sits with engineered surfaces gaining specification penetration.
Design Style:
Cost tier stratification separates premium styling from mass-market alternatives, with fabrication complexity and material waste rates driving margin differentiation.
- Modern:Clean lines, waterfall edges, and integrated sink basins characterize this specification-driven category. New residential construction in urban corridors specifies modern styling for developer-standard bathroom packages.
- Traditional:Ornate edge profiles, decorative backsplashes, and warm color palettes define this heritage-oriented segment. Renovation contractors in established metropolitan districts source traditional worktops for period-property restoration.
- Rustic:Textured surfaces, live edges, and organic material variation appeal to boutique hospitality properties. Mountain resort developments in Colorado and Alpine regions specify rustic styling for experiential differentiation.
- Minimalist:Ultra-thin profiles, hidden seams, and monochromatic palettes dominate high-end residential specifications. Scandinavian-influenced architects in Copenhagen and Stockholm specify minimalist worktops for compact urban bathrooms.
Modern styling commands volume leadership; minimalist designs are climbing the fastest in premium segments.
Size:
Volume concentration in standard sizing contrasts with margin expansion in templated production, where digital measurement workflows enable site-specific fabrication.
- Custom:CNC-cut dimensions from laser-measured templates maximize material yield and seam placement. Large residential developers in Texas and Florida metro corridors source custom sizing through direct-to-builder procurement channels.
- Standard:Pre-cut dimensions from manufacturer stock enable rapid fulfillment for replacement and repair markets. Big-box retailers in suburban markets stock standard sizes for contractor walk-in purchases.
- Small:Compact vanity dimensions for powder rooms and guest bathrooms. Urban condominium conversions in London and New York specify small-format worktops where spatial constraints dominate design decisions.
- Large:Extended spans for double vanities and spa-style wet rooms. Estate developments in Dubai and Miami specify large-format surfaces where visual impact drives specification decisions.
Standard sizing maintains volume dominance; custom fabrication shows the steepest expansion trajectory as digital templating compresses lead times.
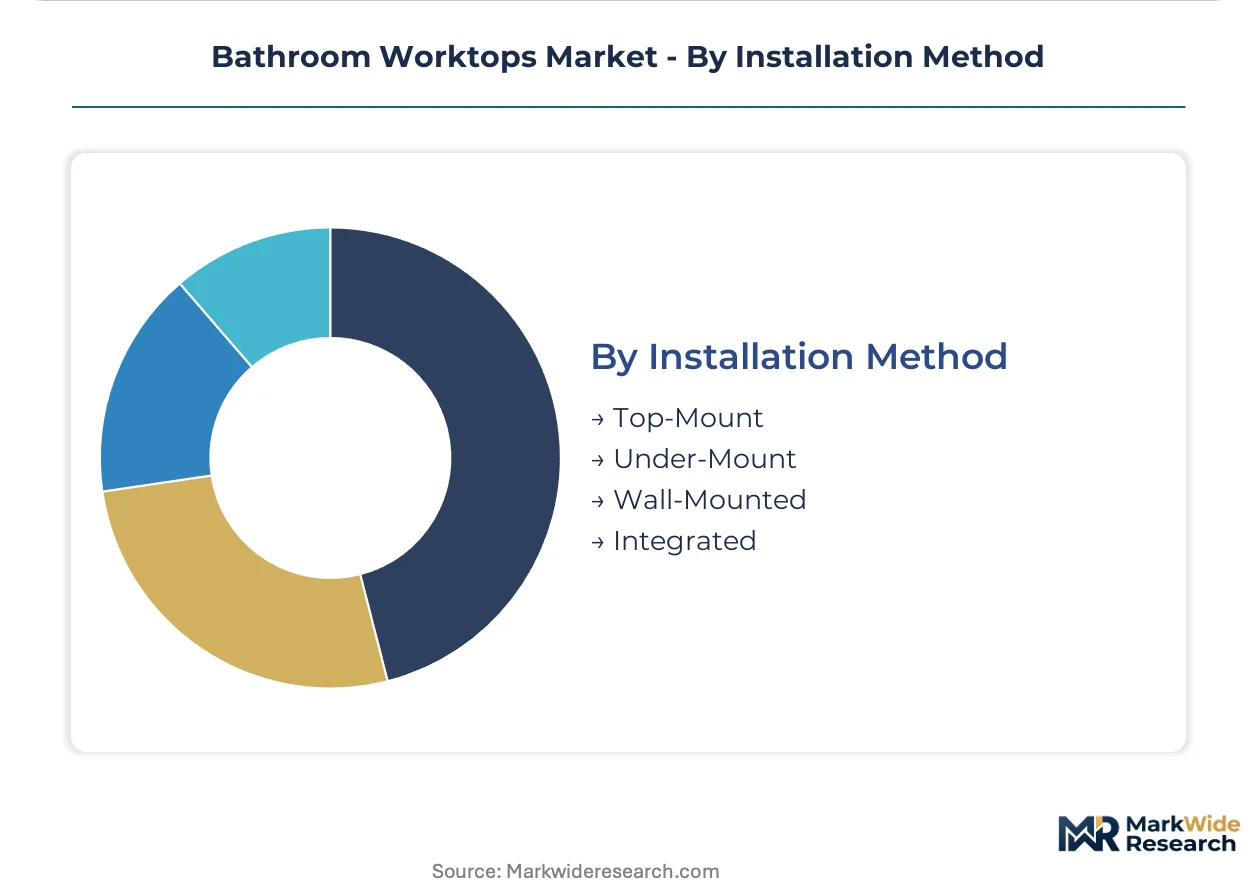
Installation Method:
Supply concentration among certified fabricators shapes competitive positioning, with integrated and under-mount methods requiring specialized skill sets that limit qualified installer pools.
- Integrated:Sink basin formed from the same material slab eliminates seams and crevices. Healthcare-adjacent hospitality bathrooms specify integrated installations where FDA surface sanitization guidelines drive material selection.
- Under-Mount:Basin installed beneath the worktop surface creates a seamless transition for cleaning. Premium hotel chains in the United States specify under-mount methods for guest bathroom durability.
- Top-Mount:Self-rimming basin rests on the worktop surface for straightforward replacement. Multi-family housing maintenance teams prefer top-mount installations for repair accessibility.
- Wall-Mounted:Floating worktop with concealed brackets maximizes floor space and cleaning access. Compact urban bathrooms in Tokyo and Singapore specify wall-mounted methods where square footage commands premium pricing.
Under-mount methods hold the largest installed base; integrated installations are gaining share fastest in commercial specification channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal rebate programs through EPA WaterSense certification are reshaping procurement eligibility for surface-material pairings in the United States. Germany's Saarland manufacturing cluster generates concentrated demand for specification-grade quartz installations. Japan's metropolitan bathroom renovation market responds to METI efficiency guidelines for residential building materials.
United States
Luxury hospitality chains across Florida and Texas are expanding specification-grade quartz portfolios for bathroom renovations. EPA WaterSense certification requirements tighten surface-material compatibility standards, forcing fabricators to requalify product pairings for federal procurement eligibility. The Dallas-Fort Worth metro corridor concentrates direct-to-builder procurement channels where templated fabrication workflows compress lead times from weeks to days.
Germany
Premium bathroom fixture manufacturers around Saarland drive localized demand for integrated sink-worktop compatibility. ECHA REACH chemical disclosure evolution accelerates substitution toward compliant resin formulations in laminate production. The Stuttgart region anchors CNC fabrication capacity for site-specific templating serving heritage property renovations requiring traditional styling specifications.
Japan
Compact urban bathroom conversions in Tokyo and Osaka specify wall-mounted worktop methods where spatial constraints dominate design decisions. METI building material efficiency standards influence surface selection for residential renovation subsidies. The Nagoya manufacturing belt concentrates solid-surface production serving clinic-hotel hybrid properties requiring FDA-aligned sanitization performance.
United Arab Emirates
Estate developments in Dubai specify large-format surfaces for spa-style wet rooms where visual impact drives specification decisions. MOHAP building material safety protocols constrain adhesive formulations used in high-humidity installation environments. The Abu Dhabi luxury hospitality sector imports specification-grade quartz through dedicated account programs bypassing traditional wholesale distribution.
United Kingdom
Heritage property renovations in London and Edinburgh sustain demand for traditional styling worktops with ornate edge profiles. ISO 4586 laminate performance standards govern export compliance for European market access, creating certification barriers for non-compliant suppliers. The Manchester fabrication hub specializes in templated custom sizing for multi-family housing developers optimizing material yield through digital measurement workflows.
Bathroom Worktops Market Competitive Environment
On the supply side, the industry is consolidating around specification-grade quartz manufacturers with certified fabricator networks and captive distribution channels. Three strategic archetypes dominate: scale-driven engineered stone producers with international quarrying operations, integrated fixture-worktop bundlers leveraging brand strength in hospitality procurement, and regional templating specialists capturing margin pools through digital fabrication workflows. Competitive moves concentrate on direct-to-builder channel expansion and backward integration into resin formulation to secure petrochemical supply stability.
Among scale-driven engineered surface producers, Cosentino anchors specification-driven commercial project penetration through quartz manufacturing scale. Kohler exemplifies the integrated bundling archetype, occupying a position where captive distribution and fixture-worktop pairing sustain brand strength in renovation procurement. DuPont represents the premium solid-surface segment, sitting within moisture-intensive environment specifications where recognized performance credentials command specification loyalty.
| Leading Market Players |
|---|
| DuPont |
| Cosentino |
| Caesarstone |
| Cambria |
| Kohler |
| Duravit |
| Villeroy & Boch |
| American Standard |
| TOTO |
| Others |
Value Chain & Pricing Dynamics
Germany's Saarland manufacturing cluster concentrates premium bathroom fixture production, translating localized quartz fabrication capacity into downstream pricing leverage for specification-grade installations across European hospitality procurement channels.
Pricing Analysis
Certification level (WaterSense/FDA-grade) creates the primary spread between procurement tiers, with EPA-qualified fixture-worktop pairings commanding premium positioning against uncertified alternatives. Project-based contract pricing dominates specification channels, while standard stock sizes flow through per-unit transactional models. Cost compression in economy laminate segments is intensifying because Asian manufacturers face ISO 4586 compliance barriers. Multi-family housing developers exhibit highest price sensitivity; luxury hospitality chains demonstrate lowest.
Supply Chain Analysis
Petrochemical resin feedstock anchors engineered quartz and solid-surface production, drawing from petroleum-derived binder supplies concentrated in Germany, China, and the United States. Ground quartz aggregate and kraft paper substrates constitute secondary material inputs. Single-source vulnerability sits with specialized polymer resin formulations facing REACH disclosure evolution. Distribution runs through certified fabricator networks for specification-grade materials, bypassing traditional wholesale channels in builder-direct procurement corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across templating specialists, resin formulators, and fixture integrators creates niche expansion opportunities as digital fabrication compresses lead times and enables mass customization workflows.
For Market Incumbents: Pre-empt granite substitution threats in heritage renovation segments by certifying traditional-styling quartz alternatives with authentic material credentials. Backward integration into compliant resin formulation secures petrochemical supply stability against crude price volatility. Channel control through captive distribution networks defends margin pools from direct-to-builder disintermediation.
For New Entrants and Emerging Players: Japan's compact urban bathroom renovation market offers underpenetrated white-space for wall-mounted worktop specialists addressing METI efficiency guidelines. Clinic-hotel hybrid properties in Nagoya's manufacturing belt present the most penetrable application segment for FDA-aligned sanitization performance. A templated-fabrication go-to-market angle bypasses wholesale markup capture.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specification-grade quartz manufacturing scale advantages are concentrating among certified fabricator networks with international quarrying operations. Target regional templating specialists with digital measurement workflows and CNC cutting capabilities. Watch WaterSense certification timeline acceleration as the inflection signal for procurement eligibility shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Secures petrochemical supply stability against REACH disclosure evolution and crude price volatility. |
| Digital Templating Workflow Expansion | Compresses fabrication lead times from weeks to days for Dallas-Fort Worth metro corridor developers. |
| WaterSense Certification Investment | Unlocks federal procurement eligibility and rebate program access for specification-grade pairings. |
| Direct-to-Builder Channel Development | Bypasses wholesale markup concentration in Germany's Saarland manufacturing cluster procurement. |
| Healthcare-Adjacent Hospitality Positioning | Captures FDA surface sanitization specification openings in clinic-hotel hybrid properties. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with quartz fabrication plant managers, hospitality procurement directors, certified installer network heads, and resin formulation R&D leads; combined with secondary validation against EPA WaterSense product databases, ECHA REACH substance registrations, customs trade records for quartz slab imports, and ISO 4586 compliance certifications. Bottom-up templating workflow analysis and top-down material consumption estimates were triangulated.
Forecast inputs considered material type penetration rates, design styling preference shifts across residential construction and renovation cycles, sizing flexibility adoption curves, and installation method specification trends. CAGRs were derived from segment-level growth rate reconciliation across the projection horizon. Modeled dimensions included material performance tier, end-use application, geographic regulatory cluster, and fabrication complexity tier.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by petrochemical-integrated Asian manufacturers would shift outcomes. Cross-checking against hospitality renovation pipeline databases and federal procurement eligibility registries is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Vietnam Sanitary Ware & Bathroom Accessories Market
Bathroom Fixtures and Accessories
Shower Chairs Market
Bathroom Fixtures and Accessories
Bath Fittings and Accessories Market
Bathroom Fixtures and Accessories
Australia Bathroom Products Market
Bathroom Fixtures and Accessories
Asia Pacific Bath Fitting Market
Bathroom Fixtures and Accessories
Bathtub Market
Bathroom Fixtures and Accessories
Toilet Partition Market
Bathroom Fixtures and Accessories
Germany Bathroom Furniture Market
Bathroom Fixtures and Accessories
US Toilet Partition Market
Bathroom Fixtures and Accessories
Baby Changing Tables and Stations Market
Bathroom Fixtures and Accessories
Sanitary Ware and Bathroom Accessories Market
Bathroom Fixtures and Accessories
Bathroom Vanities Market
Bathroom Fixtures and Accessories
US Smart Kitchen and Bathroom Products Market
Bathroom Fixtures and Accessories
United States Bath Fitting Market
Bathroom Fixtures and Accessories
Bathroom Cabinets Market
Bathroom Fixtures and Accessories
Global Shower Enclosure and Cubicles Market