
 Solar Combiner Boxes Market | 2026-2036
Solar Combiner Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Combiner Boxes Market Insights
UL 1741 certification for grid-interactive inverters and associated balance-of-system components is collapsing from a multi-year barrier into a twelve-month gate for new entrants. Eaton Corporation leverages its pre-certified platform architecture to sustain rapid utility-scale deployment cycles. ABB Ltd. anchors European project pipelines with IEC-compliant string combiner systems. Schneider Electric dominates North American utility procurement through integrated power distribution portfolios.
A solar combiner box aggregates multiple photovoltaic string inputs into a single DC output, typically housing fuses, surge protection devices, and monitoring hardware within NEMA 3R or IP65 enclosures rated for outdoor endurance. Its primary purpose centers on reducing cabling complexity while enabling fault isolation and string-level performance diagnostics across commercial and utility-scale arrays. DC combiner variants occupy the dominant volume position due to their ubiquity in large ground-mounted installations, while hybrid combiner configurations are capturing disproportionate interest from developers seeking streamlined AC-DC integration in building-integrated photovoltaics. Utility-scale end users concentrate the highest-margin procurement pools, driven by long-term performance warranties and remote monitoring requirements.
FERC Order 2023 interconnection reforms in the United States compress study timelines for solar-plus-storage projects, directly tightening combiner box delivery schedules. India's CEA technical standards for grid-connected solar plants mandate specific surge protection and arc fault detection capabilities, reshaping product specifications for suppliers targeting national solar mission tenders. IEC 61439-1 and IEC 61643-31 standards in Europe enforce thermal cycling and electromagnetic compatibility testing that filters out lower-tier manufacturers. Stakeholders must monitor evolving grid code harmonization between regions, as divergent certification timelines threaten to fragment supplier qualification investments across major deployment markets.
Market Dynamics
Utility-scale solar developers are compressing combiner box procurement cycles from 18-month planning horizons to sub-90-day deployment windows, forcing manufacturers to pre-certify modular platforms rather than engineer custom configurations per project.
Growth Catalysts
- FERC Order 2023:Interconnection study timeline compression in the United States accelerates balance-of-system procurement, pulling combiner box orders forward into earlier project phases.
- India CEA technical standards:Mandatory arc fault detection and surge protection requirements for grid-connected solar plants reshape product specifications, creating specification lock-in for compliant suppliers.
- String-level monitoring hardware:Embedded IoT sensors in DC combiner variants enable predictive maintenance contracts, extending supplier revenue streams beyond hardware sales.
Market Restraints
- Copper and aluminum price volatility:Busbar material costs comprise 35-40% of combiner box manufacturing inputs, exposing margins to commodity swings without effective hedging mechanisms.
- East Asian enclosure supply concentration:NEMA 3R and IP65-rated steel housings depend on concentrated sheet metal stamping capacity in China and Vietnam, creating single-source vulnerability.
- IEC 61439-1 thermal cycling requirements:European low-voltage switchgear standards demand accelerated aging tests that filter out regional fabricators lacking climatic chamber access.
Strategic Opportunities
- Building-integrated photovoltaics:Hybrid AC-DC combiner configurations address rooftop space constraints in commercial retrofits across Germany and the Netherlands.
- Saudi Arabia renewable tenders:Gigawatt-scale solar park announcements under Vision 2030 create demand for desert-rated enclosures with enhanced dust ingress protection.
- UL 1741-SA certification:Grid support function requirements for smart inverters extend to associated combiner hardware, enabling premium pricing for ride-through capable designs.
Industry Challenges
- Power electronics engineering talent scarcity:String-level optimization and arc detection algorithm development require specialized firmware capabilities concentrated among semiconductor designers.
- Multi-standard certification overlap:Simultaneous UL, IEC, and CEA qualification demands duplicate testing budgets that strain mid-tier manufacturer R&D allocations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Combiner Boxes Market |
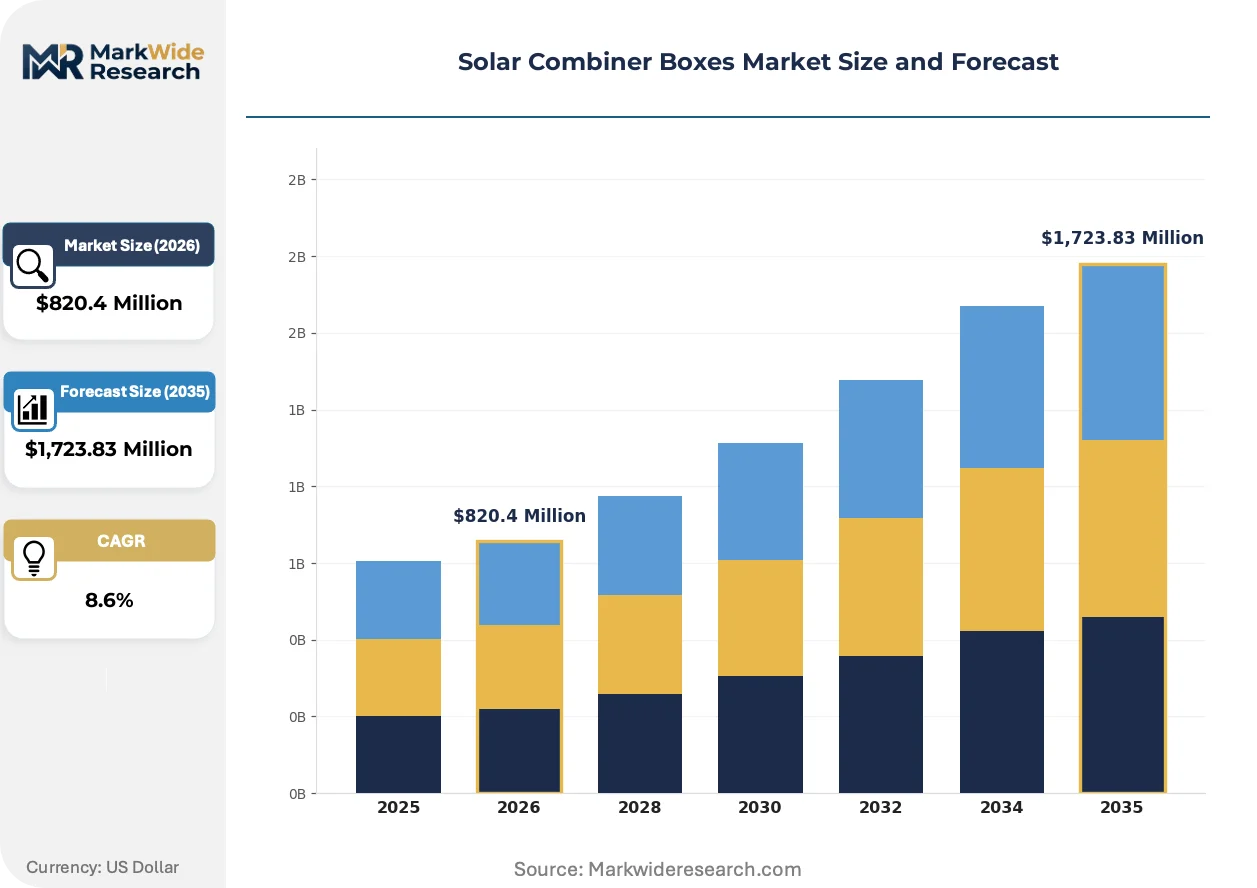
| Market Size in 2026 | $820.4 Million |
| Market Size in 2035 | $1,723.83 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: DC Combiner, AC Combiner, Hybrid Combiner, Others Installation Type: Roof-mounted, Ground-mounted, Pole-mounted, Building-integrated End User: Residential, Commercial, Industrial, Utility-scale Power Rating: Up to 10 kW, 10 kW - 50 kW, 50 kW - 100 kW, Above 100 kW |
| Companies Covered | Eaton Corporation, ABB Ltd., Yueqing VIOX Electric Co., Ltd., Weidmüller, SMA Solar Technology, Zhejiang Sandi Electric Co., Ltd., Schneider Electric, CNKUANGYA, SolarCtrl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Combiner Boxes Market Trends and Innovations
Smart monitoring integration and modular platform architectures are collapsing the traditional separation between passive electrical hardware and active grid management systems in solar deployment.
Intelligent combiner boxes with embedded string-level monitoring and remote fault isolation are supplanting passive fuse-based configurations in utility-scale procurement. Developers in Texas and California specify these units to reduce O&M truck rolls and accelerate downtime response. The technology is compressing warranty negotiations toward performance-guaranteed service contracts rather than hardware-only sales.
REACH substance restrictions and RoHS recast directives in Europe are phasing out cadmium-plated hardware and certain flame retardants in enclosure manufacturing. Combiner box suppliers must reformulate gasket materials and coating chemistries to maintain CE marking eligibility. German and Spanish project financiers now require full material disclosure documentation as a loan condition precedent.
Long-term service agreements are displacing transactional hardware purchases among independent power producers seeking to outsource balance-of-system asset management. Third-party O&M providers in Arizona and Nevada bundle combiner box monitoring into portfolio-wide contracts, stripping original equipment manufacturers of direct customer relationships. This pattern concentrates most acutely in merchant solar projects without utility offtake security.
Solar Combiner Boxes Market Segmentation
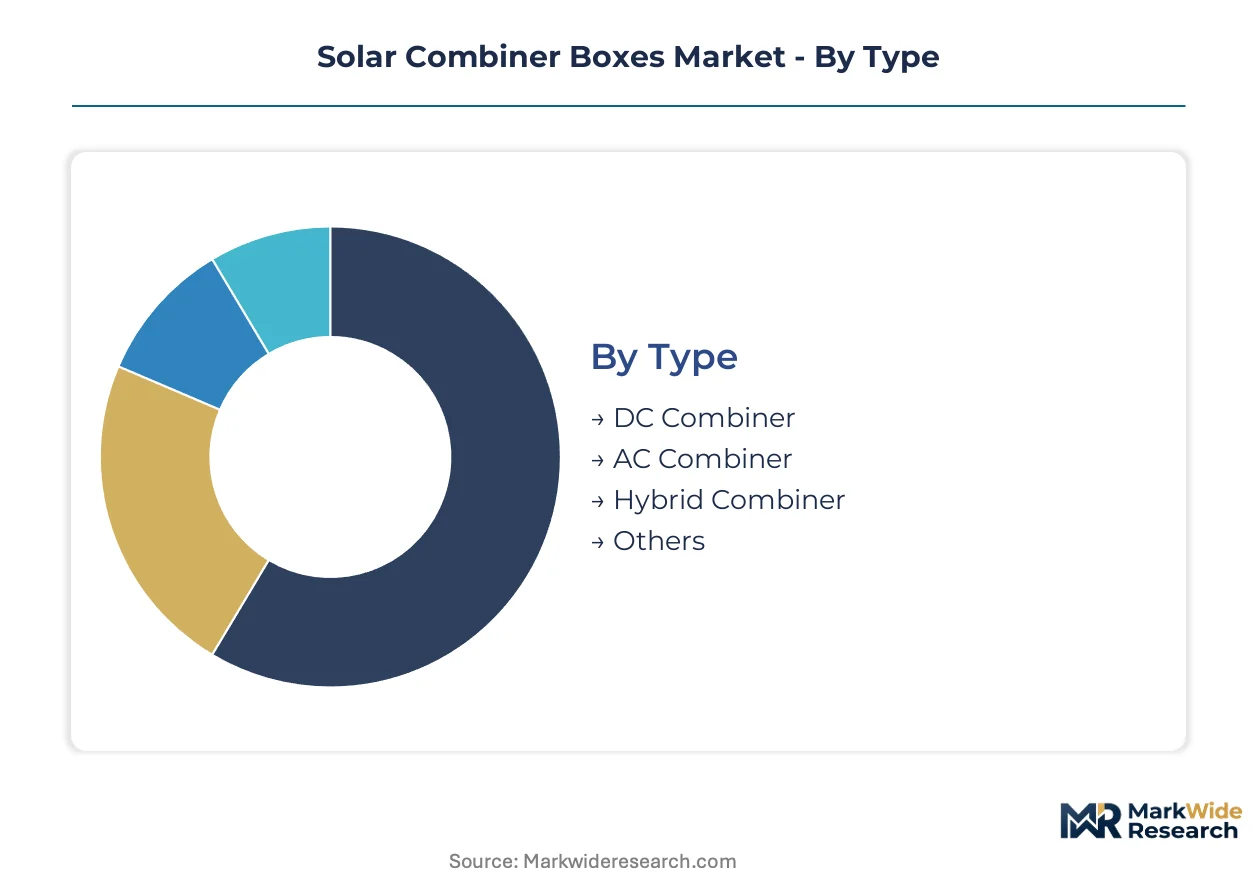
Combiner box procurement patterns diverge sharply across deployment contexts. String-level monitoring capabilities and enclosure durability ratings command premium positioning in utility-scale tenders, while compact footprints dominate residential rooftop specifications.
Type:
Margin pools concentrate in configurations enabling grid-interactive functionality and predictive maintenance revenue streams.
- DC Combiner:Aggregates multiple photovoltaic string inputs into unified DC output circuits, housing fuses, surge protection, and monitoring hardware within NEMA 3R or IP65 enclosures. Utility-scale solar farms in India and the United States specify these units for ground-mounted installations, driven by FERC Order 2023 interconnection timeline compression that rewards pre-certified modular platforms.
- Hybrid Combiner:Integrates AC and DC pathways within single enclosure architectures, reducing balance-of-system footprint for space-constrained deployments. Building-integrated photovoltaic projects across Germany and the Netherlands specify hybrid configurations, where rooftop structural limitations and dual electrical pathways create specification premiums.
- AC Combiner:Consolidates inverter AC outputs into collection circuits for medium-voltage step-up transformers.
- Others:Encompasses specialized configurations including string-level rapid shutdown boxes and custom junction assemblies.
The dominant share belongs to DC Combiner, while Hybrid Combiner is closing the gap fastest.
Installation Type:
Cost tier stratification follows environmental exposure severity and structural mounting complexity rather than electrical sophistication.
- Ground-mounted:Deploys on racking systems across utility-scale solar parks, requiring enhanced dust ingress protection and thermal cycling endurance. Saudi Arabia's Vision 2030 gigawatt-scale tenders specify desert-rated ground-mounted enclosures with sealed gasket architectures.
- Roof-mounted:Attaches to commercial and industrial building structures, demanding lightweight enclosures with integrated fall protection anchor points. California Title 24 compliance mandates rapid shutdown functionality that reshapes rooftop combiner specifications.
- Pole-mounted:Elevates hardware above flood-prone or snow-accumulation zones in agricultural and remote installations.
- Building-integrated:Embeds within facade or canopy structures where aesthetic constraints override standard enclosure geometries.
Ground-mounted installations capture the largest procurement volume, though Building-integrated applications show the steepest expansion trajectory.
End User:
Customer type determines warranty structure, with long-term performance guarantees concentrating among independent power producers.
- Utility-scale:Concentrates the highest-margin procurement pools, driven by 25-year performance warranties and remote monitoring requirements. Developers in Texas and Arizona specify intelligent combiner boxes with embedded IoT sensors to reduce O&M truck rolls.
- Commercial:Encompasses retail, warehouse, and office rooftop installations where third-party O&M providers bundle monitoring into portfolio-wide contracts.
- Industrial:Serves manufacturing facilities with high behind-the-meter consumption and demand charge mitigation objectives.
- Residential:Captures single-family and small multi-family rooftop deployments with standardized string configurations.
Utility-scale end users command the dominant revenue share, while Commercial applications are gaining share fastest.
Power Rating:
Volume distribution skews toward higher-capacity units where busbar material efficiency improves per-watt manufacturing economics.
- Above 100 kW:Serves central inverter architectures in utility-scale solar parks, consolidating 20+ string inputs through high-current busbar assemblies. India's national solar mission tenders specify arc fault detection and surge protection capabilities that filter supplier pools.
- 50 kW - 100 kW:Addresses commercial and small utility installations with string inverter clusters, balancing modularity against installation labor efficiency.
- 10 kW - 50 kW:Targets commercial rooftop segments with distributed string configurations.
- Up to 10 kW:Matches residential scale deployments with 2-8 string aggregation requirements.
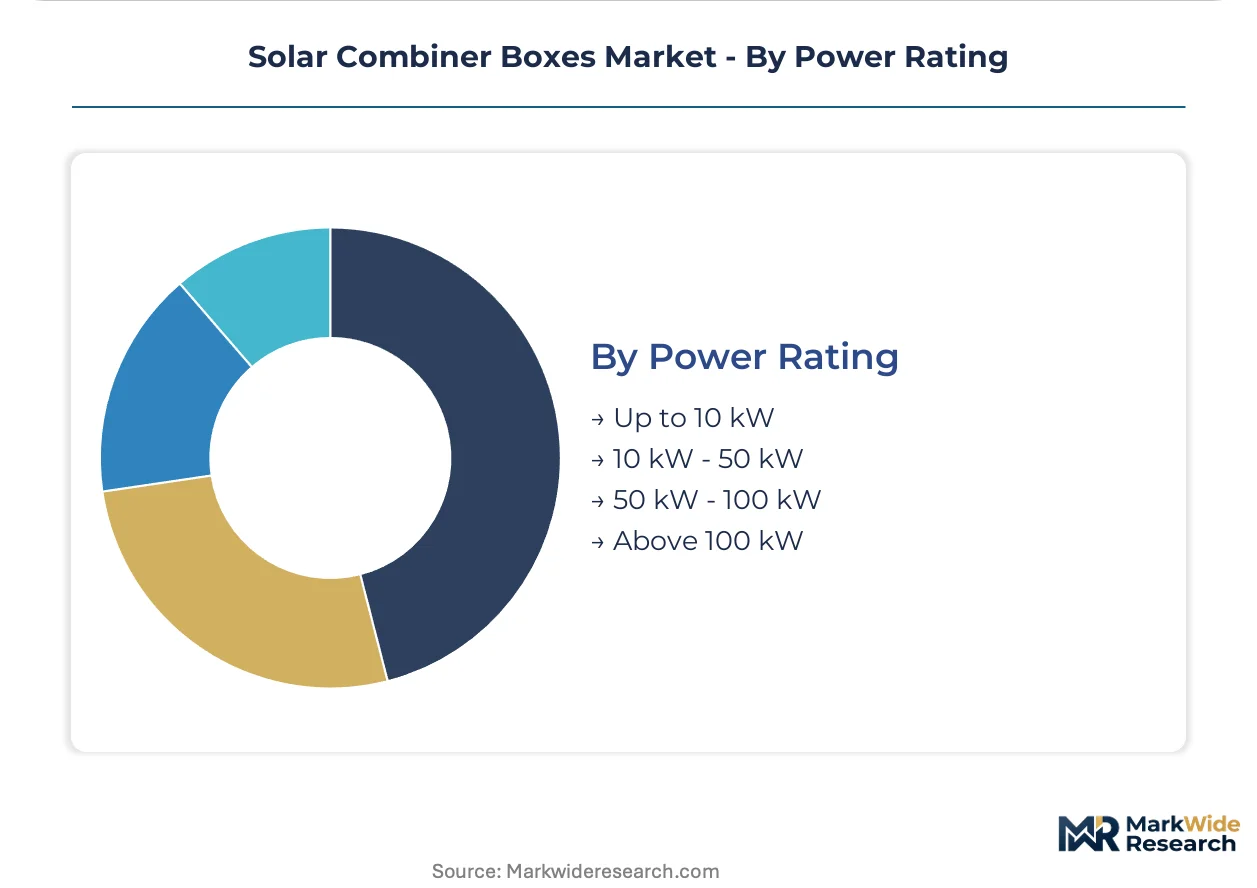
Above 100 kW ratings hold the dominant position, while 50 kW - 100 kW segments are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC Order 2023 interconnection reforms in the United States compress procurement timelines for solar-plus-storage projects, tightening combiner box delivery schedules and rewarding pre-certified modular platforms. India's CEA technical standards mandate arc fault detection and surge protection capabilities, reshaping supplier qualification for national solar mission tenders. European IEC 61439-1 and IEC 61643-31 standards enforce thermal cycling and electromagnetic compatibility testing that filters lower-tier manufacturers.
United States
Utility-scale developers in Texas and Arizona specify intelligent combiner boxes with embedded IoT sensors to reduce O&M truck rolls. FERC Order 2023 interconnection study timeline compression accelerates balance-of-system procurement into earlier project phases. California Title 24 compliance mandates rapid shutdown functionality that reshapes rooftop combiner specifications across the state's commercial solar market.
India
National solar park tenders under the Ministry of New and Renewable Energy accelerate combiner box procurement cycles to sub-90-day deployment windows. CEA technical standards for grid-connected solar plants mandate specific surge protection and arc fault detection capabilities, creating specification lock-in for compliant suppliers. Rajasthan and Gujarat host the densest concentrations of utility-scale solar parks driving high-current busbar assembly demand.
Germany
Building-integrated photovoltaic projects across commercial rooftops specify hybrid AC-DC combiner configurations to address space constraints. REACH substance restrictions and RoHS recast directives phase out cadmium-plated hardware and certain flame retardants in enclosure manufacturing. The Eindhoven-to-Dortmund corridor hosts project financiers requiring full material disclosure documentation as loan condition precedent.
Saudi Arabia
Gigawatt-scale solar park announcements under Vision 2030 create demand for desert-rated enclosures with enhanced dust ingress protection. The national renewable energy program tenders specify ground-mounted installations requiring sealed gasket architectures for extreme thermal cycling. The Eastern Province and Riyadh region concentrate developer activity for utility-scale procurement pools.
China
Domestic solar installation targets drive volume demand for DC combiner variants in ground-mounted utility-scale deployments. GB standards and dual carbon goals enforce product efficiency benchmarks that filter supplier pools for national pipeline projects. The Yangtze River Delta and Pearl River Delta regions host concentrated sheet metal stamping capacity for NEMA 3R and IP65-rated steel housings.
Solar Combiner Boxes Market Competitive Landscape
Listed leaders compete with private specialists across certification platform breadth, with public companies leveraging pre-certified architectures to sustain rapid deployment cycles while private fabricators compete on regional customization speed. The market structure tilts toward tiered consolidation, where multinational electrical conglomerates anchor premium utility procurement against mid-tier specialists capturing commercial retrofit volume. Three archetypes dominate: integrated power distribution portfolios, string combiner system specialists, and regional enclosure fabricators. Competitive moves concentrate on modular platform pre-certification and strategic partnerships with inverter manufacturers.
Among diversified electrical conglomerates, Eaton Corporation and ABB Ltd. occupy positions representing integrated platform strategies, while Schneider Electric anchors North American utility procurement through power distribution portfolio breadth. Yueqing VIOX Electric Co., Ltd. and Zhejiang Sandi Electric Co., Ltd. exemplify Chinese specialists competing on enclosure manufacturing scale and regional customization velocity. SMA Solar Technology represents inverter-aligned combiner system integration. Weidmüller sits within the European industrial connectivity tier serving commercial and industrial rooftop segments.
| Leading Market Players |
|---|
| Eaton Corporation |
| ABB Ltd. |
| Yueqing VIOX Electric Co., Ltd. |
| Weidmüller |
| SMA Solar Technology |
| Zhejiang Sandi Electric Co., Ltd. |
| Schneider Electric |
| CNKUANGYA |
| SolarCtrl |
| Others |
Pricing and Supply Chain Analysis
UL 1741-SA certification gates both supplier qualification and price differentiation simultaneously, compressing multi-year approval timelines into twelve-month windows that separate pre-certified platform providers from commodity fabricators unable to absorb accelerated testing budgets.
Pricing Analysis
Certification level creates the primary spread between premium intelligent combiner boxes and standard passive configurations. Three-tier pricing structure across intelligent monitoring, pre-certified modular, and basic fuse-based units reflects embedded IoT sensor costs and arc fault detection capabilities. Cost compression in standard DC combiner tiers intensifies because copper and aluminum busbar volatility exposes margins without effective hedging mechanisms. Commercial rooftop developers exhibit highest price sensitivity due to third-party O&M provider bundling, while utility-scale IPPs prioritize 25-year performance warranties over unit economics.
Supply Chain Analysis
Container availability fluctuations on Asia-North America and Asia-Europe trade lanes disrupt enclosure delivery schedules for NEMA 3R and IP65-rated steel housings. Manufacturing gravity centers on China, Vietnam, and India for sheet metal stamping capacity, while semiconductor components for monitoring hardware draw from Taiwan and South Korea. Single-source vulnerability concentrates in East Asian enclosure supply, with tariff exposure on steel imports amplifying cost uncertainty. Distribution runs through EPC contractors and inverter OEMs rather than direct developer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where pre-certified platform architectures create switching costs that lock utility-scale developers into established supplier relationships through compressed interconnection timelines.
For Market Incumbents: Compound certification platform breadth by accelerating IEC 61439-1 and UL 1741-SA qualification for emerging grid support functions before margin pressure from Chinese enclosure fabricators intensifies. Deepen backward integration into copper busbar processing to offset commodity volatility exposure. Prioritize firmware development for arc detection algorithms where semiconductor engineering talent scarcity limits competitor replication speed. For New Entrants and Emerging Players: Predictive maintenance service gaps in merchant solar projects without utility offtake security offer white-space entry where incumbents cede direct customer relationships to third-party O&M providers. Saudi Arabia desert-rated enclosure specifications under Vision 2030 tenders present the most penetrable geography given limited incumbent pre-certification for extreme thermal cycling. Pursue strategic partnerships with regional EPC contractors as the primary go-to-market angle rather than direct utility engagement. For Investors and Strategic Acquirers: FERC Order 2023 interconnection timeline compression reshapes the acquisition landscape toward pre-certified modular platform providers capable of sub-90-day deployment cycles. Target acquisition archetypes include intelligent combiner specialists with embedded IoT sensor capabilities and firmware differentiation. Watch for CEA technical standard harmonization with IEC frameworks as the signal indicating qualification investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Pre-Certification | UL 1741-SA and IEC 61439-1 compliance compresses utility procurement cycles to sub-90-day windows. |
| Embedded IoT Sensor Integration | String-level monitoring hardware enables predictive maintenance contracts extending beyond hardware sales. |
| Desert-Rated Enclosure Development | Saudi Arabia Vision 2030 tenders demand sealed gasket architectures for extreme dust ingress protection. |
| Copper Busbar Backward Integration | In-house processing of 35-40% cost inputs mitigates commodity volatility exposure. |
| Third-Party O&M Partnership | Arizona and Nevada portfolio-wide contracts strip OEMs of direct customer relationships. |
Research Methodology
Initial hypotheses were tested against primary input from utility-scale project developers, EPC procurement officers, inverter OEM platform engineers, and balance-of-system asset managers and refined through secondary validation against FERC interconnection filings, CEA technical standard documentation, IEC certification registries, and utility-scale solar project development databases. Bottom-up installation volume estimates across type, installation, end user, and power rating segments were triangulated against top-down market value reconstruction.
Variance decomposition across the projection horizon isolates volume, pricing, and mix effects within each segmentation dimension including DC versus hybrid versus AC combiner configurations, ground-mounted versus building-integrated installation types, utility-scale versus commercial end user categories, and above 100 kW versus sub-100 kW power ratings. CAGRs were derived from segment-level trajectory modeling incorporating FERC Order 2023 implementation pace, India national solar mission tender acceleration, and REACH substance restriction compliance timelines.
Underlying assumptions cover sustained utility-scale solar deployment velocity, continued copper and aluminum price volatility, and stable regulatory certification harmonization, with deviation risk concentrated in interconnection queue reform implementation delays and East Asian enclosure supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Composite Line Post Insulators Market
Electrical Power Equipment
India Instrument Transformer Market
Electrical Power Equipment
Battery Charger Market
Electrical Power Equipment
Asia Pacific Gas Insulated Switchgear Market
Electrical Power Equipment
Composite Insulators Market
Electrical Power Equipment
Magnet Bearings Market
Electrical Power Equipment
GCC Induction Motor Market
Electrical Power Equipment
High Voltage Ionising Air Gun Market
Electrical Power Equipment
Europe Alternating Current (AC) Drive Market
Electrical Power Equipment
Power Over Ethernet Lighting Market
Electrical Power Equipment
North America Air-Insulated Switchgear Market
Electrical Power Equipment
North America Oil Filled Electric Heaters Market
Electrical Power Equipment
Alternators Market
Electrical Power Equipment
North America Surge Arresters Market
Electrical Power Equipment
Transformer Oil Testers Market
Electrical Power Equipment
Offshore Cables Market