
 United States Weight Management Market | 2026-2036
United States Weight Management Market Size, Share, and Industry Trends Forecast 2026-2036
United States Weight Management Market Intelligence
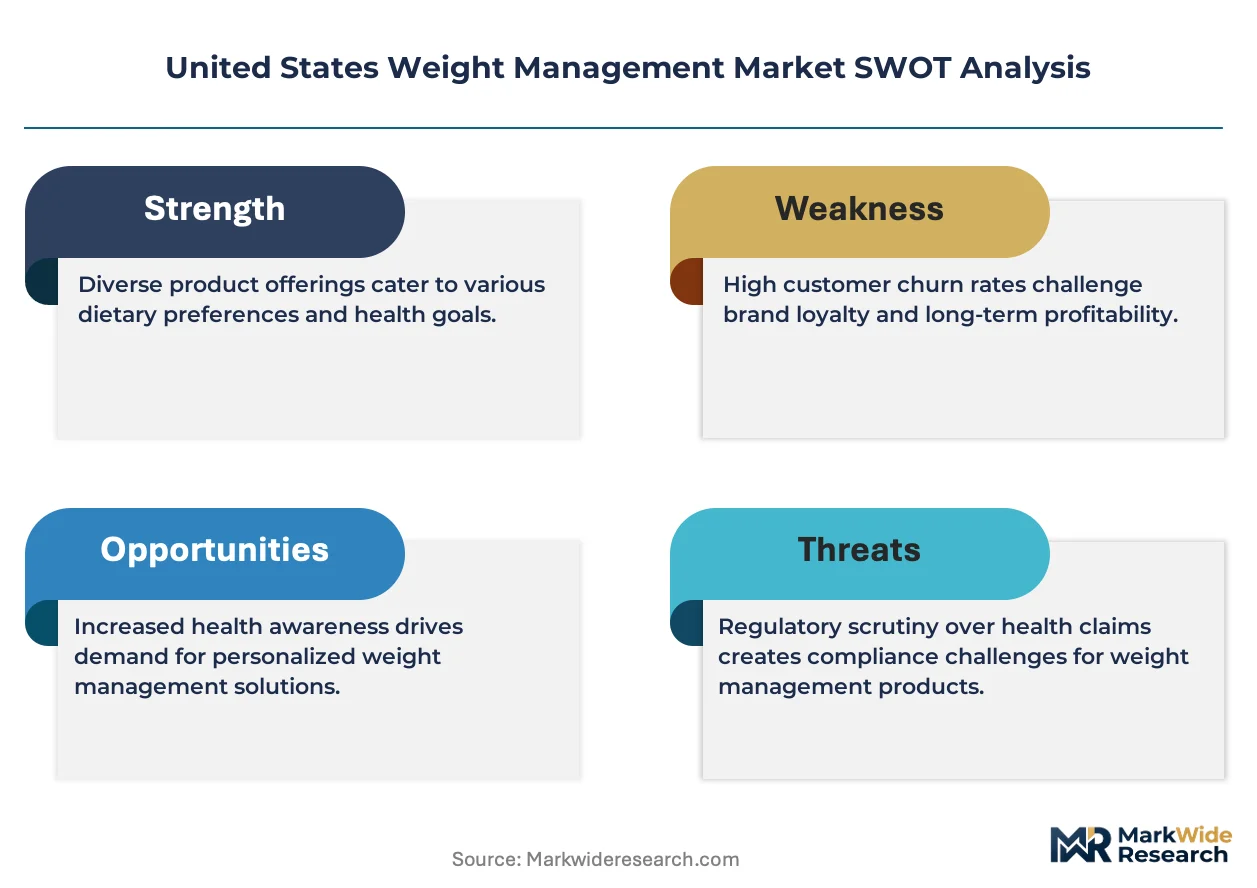
Subscription bundling of digital coaching with meal replacements and pharmacy fulfillment is shifting how consumers evaluate total program cost. Novo Nordisk leverages its GLP-1 manufacturing scale to anchor clinical weight management channels. WW International differentiates through behavioral coaching infrastructure that extends beyond pharmaceutical intervention. Herbalife Nutrition Ltd competes via direct-to-consumer distribution networks that occupy nutrition club density in suburban markets.
United States weight management encompasses products, services, and interventions designed to reduce, control, or maintain body mass through caloric modulation, metabolic enhancement, or behavioral modification. The category spans formulated meal replacements with defined macronutrient profiles, prescription and over-the-counter appetite suppressants, and supervised dietary protocols administered through clinical or commercial channels. Meal replacements capture substantial volume as shelf-stable, portion-controlled formats penetrate employer wellness and retail pharmacy segments. Appetite suppressants, particularly GLP-1 agonist prescriptions, represent the fastest-expanding margin pool as endocrinology and primary care prescribing broadens. Dietary supplements face mature growth trajectories amid FDA scrutiny of structure-function claims and variable bioequivalence across formulations.
FDA, FTC, and USDA frameworks collectively govern product safety, advertising substantiation, and nutritional labeling across the weight management value chain. FDA oversight of prescription anti-obesity drugs and compounded GLP-1 products shapes clinical access and pharmacy reimbursement dynamics. FTC enforcement against unsubstantiated fat-loss claims constrains dietary supplement marketing and directs investment toward evidence generation. Stakeholders must monitor evolving DEA scheduling discussions for stimulant-based appetite suppressants and state-level Medicaid coverage determinations for pharmacotherapy to anticipate demand inflections and channel migration.
Market Dynamics
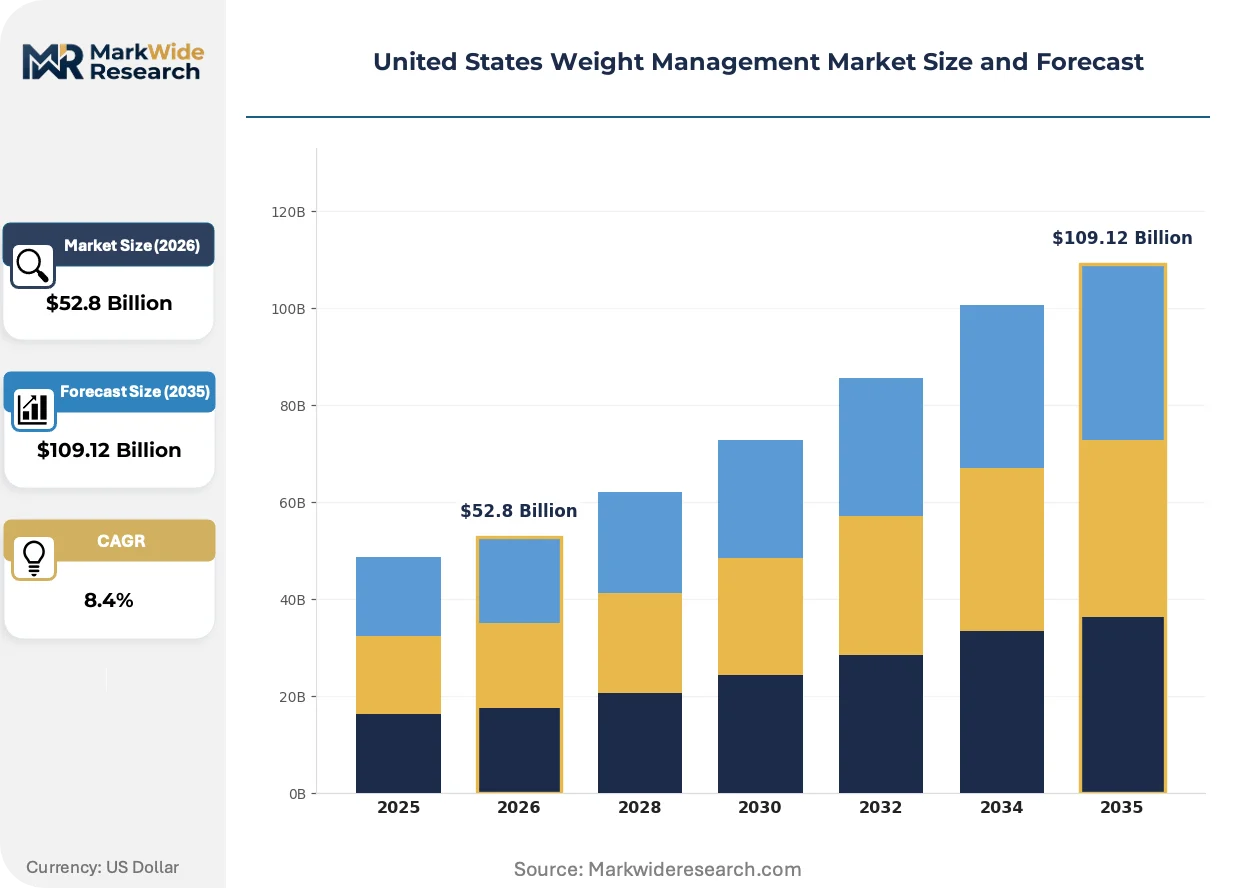
GLP-1 receptor agonist prescribing expansion is restructuring the United States weight management market by shifting volume from commercial diet programs toward clinical pharmacy channels and employer-covered medical benefit structures.
Growth Catalysts
- Employer wellness procurement:Large self-insured employers in Texas and California are adding pharmacotherapy riders to health plans, creating covered access pathways for adult workforces with metabolic risk profiles.
- FDA regulatory clarity:The agency's compounding enforcement actions against unapproved semaglutide variants are consolidating demand into verified manufacturer supply chains and legitimate clinical settings.
- Retail pharmacy density:CVS Health and Walgreens are expanding in-store weight management clinics in Florida, creating physical access points that bridge prescription fulfillment with counseling services.
Market Restraints
- Supply concentration risk:Novo Nordisk and Eli Lilly control virtually all FDA-approved GLP-1 manufacturing capacity for obesity indications, creating vulnerability to production disruptions or allocation decisions.
- Medicaid coverage gaps:State-level formulary exclusions for anti-obesity medications limit access for low-income populations in jurisdictions without expanded pharmacotherapy benefits.
- Substitution pressure from bariatric surgery:Improved laparoscopic techniques and durable metabolic outcomes are pulling eligible candidates away from pharmaceutical-only intervention pathways.
Strategic Opportunities
- Telehealth platform integration:Virtual prescriber networks can capture rural and suburban demand in Ohio and Pennsylvania where endocrinology specialist density remains below metropolitan benchmarks.
- Medicare Part D inclusion:Legislative pressure to add obesity pharmacotherapy to federal formularies would unlock demand among adults aged sixty-five and older currently excluded from coverage.
- Digital therapeutics bundling:Pairing prescription fulfillment with app-based behavioral coaching creates stickier patient relationships and improves payer-relevant outcome metrics.
Industry Challenges
- Prior authorization complexity:Insurers require extensive documentation of failed lifestyle intervention before approving GLP-1 coverage, creating administrative burden on prescribing physicians and patient abandonment.
- Reimbursement rate compression:Pharmacy benefit managers are tightening formulary placement terms for anti-obesity drugs, squeezing margin on what had been premium-priced therapeutic categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Weight Management Market |
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $109.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meal Replacements, Dietary Supplements, Appetite Suppressants, Fat Burners End User: Adults, Adolescents, Seniors, Children Distribution Channel: Online Stores, Supermarkets, Drugstores, Health Food Stores Dietary Approach: Keto, Paleo, Mediterranean, Vegan |
| Companies Covered | Nestle S.A, The Simply Good Foods Company, Novo Nordisk, WW International, Glanbia PLC, Eli Lilly, Herbalife Nutrition Ltd, Noom, Abbott Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Weight Management Market Strategic Shifts & Innovations
Continuous glucose monitoring integration and AI-driven meal planning are converging with pharmaceutical intervention, creating hybrid care models that extend beyond traditional diet program structures.
Continuous glucose monitors designed for non-diabetic metabolic tracking are overtaking food journaling apps as the preferred self-monitoring tool among employer wellness enrollees. Large corporations in the technology and financial services sectors are subsidizing CGM hardware for prediabetic employees. This sensor-driven feedback loop is compressing reliance on manual calorie counting and enabling real-time dietary adjustment protocols.
FDA's Risk Evaluation and Mitigation Strategy for stimulant-based appetite suppressants is tightening prescribing controls on phentermine-topiramate combinations. The agency's enhanced cardiovascular safety monitoring requirements are extending time-to-market for novel sympathomimetic compounds. Primary care networks in California and New York are responding by shifting prescribing preference toward GLP-1 agonists with established cardiac outcome data.
Subscription bundling of medication delivery with nutrition coaching is displacing standalone pharmacy fulfillment as the preferred commercial model. Direct-to-consumer platforms are capturing patients who bypass traditional clinic channels entirely. This channel migration is most visible in metropolitan Texas markets where employer-sponsored health savings accounts cover qualified wellness subscriptions.
United States Weight Management Market Segmentation
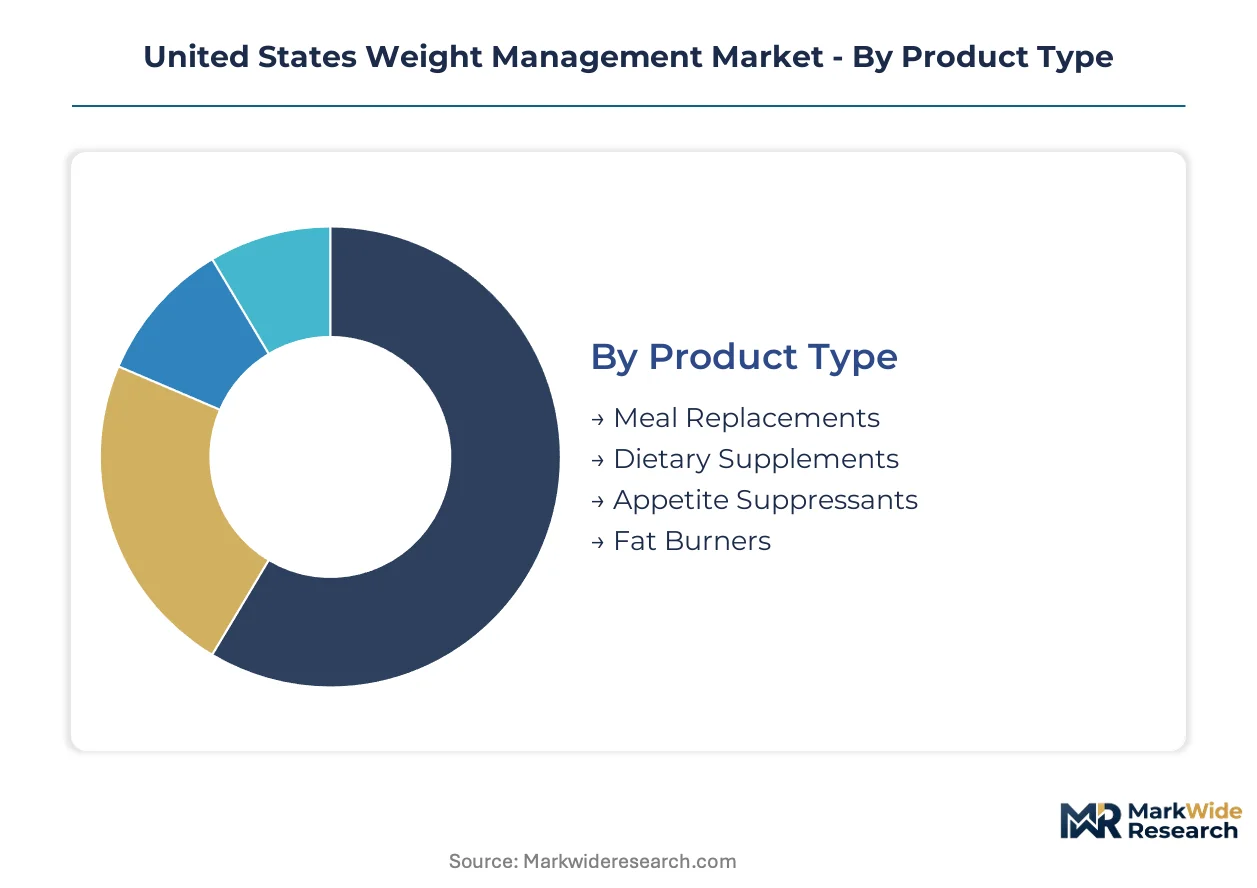
GLP-1 pharmacotherapy is compressing traditional segment boundaries as prescription fulfillment displaces over-the-counter categories. Manufacturers now allocate R&D across four distinct taxonomies—product chemistry, patient life stage, channel infrastructure, and macronutrient philosophy—each requiring differentiated regulatory and go-to-market strategies.
Product Type:
Capital intensity varies sharply across formulation complexity, with biologic manufacturing demanding tenfold higher upfront investment than powder-based nutritionals.
- Meal Replacements:Shelf-stable formulations with defined protein-carbohydrate-fat ratios, often fortified with micronutrients. Demand clusters in employer wellness programs across Texas and California where portion-controlled formats simplify cafeteria procurement. Portion standardization reduces foodservice labor costs.
- Appetite Suppressants:Prescription GLP-1 receptor agonists and legacy sympathomimetic compounds. Florida's retail pharmacy clinics are expanding in-store prescribing capacity to capture patients seeking clinical intervention beyond commercial diet programs. FDA REMS requirements constrain new stimulant entry.
- Dietary Supplements:Powder, capsule, and gummy formats with structure-function claims.
- Fat Burners:Thermogenic and lipolytic formulations, predominantly caffeine-based.
Meal replacements absorb the bulk of installed capacity; appetite suppressants are expanding most quickly.
End User:
Reimbursement eligibility and metabolic risk profiles create divergent margin structures across life-stage segments.
- Adults:Working-age populations with employer-sponsored coverage. Self-insured corporations in technology and financial services sectors are adding pharmacotherapy riders to health plans, creating covered access pathways for metabolic risk management.
- Seniors:Medicare-excluded population currently paying out-of-pocket for anti-obesity interventions. Legislative pressure to add obesity pharmacotherapy to Part D formularies would unlock substantial latent demand among adults aged sixty-five and older.
- Adolescents:Pediatric endocrinology referral pathways.
- Children:Family-based behavioral modification programs.
Adults command the dominant share of commercial investment; seniors present the steepest expansion trajectory pending coverage reform.
Distribution Channel:
Channel selection determines regulatory exposure and patient acquisition economics.
- Drugstores:CVS Health and Walgreens are expanding in-store weight management clinics, bridging prescription fulfillment with counseling services. Physical access points in Florida and Texas capture patients seeking integrated care models.
- Online Stores:Direct-to-consumer platforms bypass traditional clinic channels entirely. Telehealth-integrated fulfillment captures rural and suburban demand in Ohio and Pennsylvania where specialist density remains below metropolitan benchmarks.
- Supermarkets:Mass-market meal replacement placement.
- Health Food Stores:Premium supplement positioning.
Drugstores retain the deepest infrastructure investment; online channels are gaining share fastest through telehealth integration.
Dietary Approach:
Macronutrient philosophy shapes ingredient sourcing requirements and formulation R&D priorities.
- Keto:Very-low-carbohydrate formulations emphasizing ketone body metabolism. Continuous glucose monitor integration enables real-time dietary adjustment protocols among employer wellness enrollees in technology sector programs.
- Mediterranean:Olive oil and omega-3 fatty acid emphasis with cardiac outcome alignment. Primary care networks in California and New York are shifting preference toward approaches with established cardiovascular safety data.
- Paleo:Grain-free, dairy-free ancestral nutrition frameworks.
- Vegan:Plant-protein formulations addressing complete amino acid profiles.
Keto commands the largest dedicated manufacturing footprint; Mediterranean is climbing the fastest on cardiac outcome validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas, California, and Florida consume the majority of structured weight management services while manufacturing concentrates in the Northeast and Midwest corridors. State-level Medicaid coverage decisions create sharp access boundaries that reshape patient migration patterns.
Texas
Employer wellness procurement from Dallas-Fort Worth technology and energy corporations drives demand for pharmacotherapy riders. State Medicaid excludes anti-obesity medications from formulary coverage, forcing low-income patients toward commercial diet programs. Houston's medical center corridor hosts the densest concentration of bariatric surgery capacity competing directly with pharmaceutical intervention.
California
Primary care networks in Los Angeles and San Francisco Bay Area favor GLP-1 agonists with established cardiac outcome data over legacy stimulant prescriptions. FDA REMS enforcement against phentermine-topiramate combinations tightens prescribing controls statewide. Silicon Valley employers subsidize continuous glucose monitoring hardware for prediabetic workforces, creating sensor-driven demand clusters.
Florida
Retiree migration from Medicare-excluded obesity pharmacotherapy populations sustains out-of-pocket demand for concierge weight management clinics. CVS Health and Walgreens expand in-store weight management clinics across Miami-Dade and Orange County corridors. State-level telehealth regulations enable virtual prescriber networks to capture rural Panhandle demand.
Illinois
Chicago's employer base in financial services and manufacturing adds metabolic risk management to self-insured health plans. Illinois Medicaid covers anti-obesity medications for adults with diagnosed diabetes, creating narrower eligibility than commercial formularies. Rockford and Peoria manufacturing clusters drive occupational health program procurement of portion-controlled meal replacements.
Ohio
Rural and suburban counties below metropolitan endocrinology density benchmarks generate telehealth-integrated pharmacy fulfillment demand. Cleveland Clinic's integrated delivery network anchors clinical weight management capacity competing with direct-to-consumer platforms. State pharmacy benefit manager contracts tighten formulary placement terms for anti-obesity drugs.
United States Weight Management Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the United States weight management market. Pharmaceutical manufacturers with metabolic disease portfolios anchor clinical channels while nutrition companies occupy commercial diet program segments. Three archetypes dominate: GLP-1 manufacturing scale players, behavioral coaching infrastructure operators, and direct-to-consumer distribution network owners. Consolidation pressure favors M&A between telehealth platforms and pharmacy fulfillment networks; vertical integration into compounding pharmacy capacity represents a secondary competitive move.
Within the pharmaceutical manufacturing tier, Novo Nordisk and Eli Lilly exemplify scale-driven supply concentration that controls virtually all FDA-approved GLP-1 capacity for obesity indications. Among behavioral coaching specialists, WW International occupies a position emphasizing infrastructure that extends beyond pharmaceutical intervention. Herbalife Nutrition Ltd represents the direct-to-consumer archetype through nutrition club density in suburban markets.
| Leading Market Players |
|---|
| Nestle S.A |
| The Simply Good Foods Company |
| Novo Nordisk |
| WW International |
| Glanbia PLC |
| Eli Lilly |
| Herbalife Nutrition Ltd |
| Noom |
| Abbott Laboratories |
| Others |
Cost & Logistics Intelligence
Self-insured employer procurement from Texas and California technology corporations anchors the dominant subscription-bundling pricing model across clinical and commercial weight management channels.
Pricing Analysis
Price erosion across employer-sponsored pharmacotherapy tiers traces to pharmacy benefit manager formulary tightening and Medicaid coverage exclusions in major states. Three-tier pricing structure across premium concierge, standard telehealth, and economy retail pharmacy levels separates patients by insurance density and metabolic risk stratification. Cost-down pressure on meal replacement formulations accelerates because portion-controlled procurement contracts favor volume scale over brand premium. Price differentiation hinges on FDA approval status versus compounded alternatives, with Medicare-excluded seniors showing highest sensitivity and employer-covered adults demonstrating lowest elasticity.
Supply Chain Analysis
Biologic manufacturing workforce availability in Denmark and Indianapolis production corridors constrains GLP-1 capacity expansion against demand acceleration. Active pharmaceutical ingredient synthesis draws from Irish and Puerto Rican fermentation facilities, while fill-finish operations concentrate in North Carolina and Belgium. Single-source vulnerability around Novo Nordisk and Eli Lilly manufacturing allocation decisions threatens supply continuity for obesity indications. Distribution runs through cold-chain pharmacy networks bridging specialty distributor hubs with retail clinic fulfillment points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GLP-1 manufacturing capacity scarcity props pricing power across prescription channels, creating supply-constrained conditions that favor incumbent scale players and complicate new entrant access.
For Market Incumbents: Deploy formulary placement leverage to secure preferred pharmacy benefit manager positioning ahead of Medicare Part D inclusion debates. Consolidate backward integration into compounding pharmacy capacity to capture demand displaced by FDA enforcement actions against unapproved semaglutide variants. Threat substitution from bariatric surgery durability demands clinical outcome data investments that reinforce medical benefit justification. For New Entrants and Emerging Players: Direct-to-consumer telehealth platforms offer the most penetrable route around incumbent pharmacy channel control, particularly in Ohio and Pennsylvania counties below endocrinology specialist density benchmarks. White-space concentration in Medicare-excluded senior populations and rural Medicaid gaps creates addressable demand outside employer-sponsored structures. Behavioral coaching app bundling with prescription fulfillment provides differentiated go-to-market positioning against standalone pharmacy competitors. For Investors and Strategic Acquirers: The window for entry favors telehealth-integrated pharmacy networks with established prescriber relationships and cold-chain logistics infrastructure. Long-term viability rests on legislative momentum for federal formulary inclusion and employer wellness program expansion durability. Watch state-level Medicaid coverage determinations as the inflection signal for demand migration between clinical and commercial channels.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Integration | Virtual prescriber networks capture rural demand in specialist-scarce Ohio and Pennsylvania markets. |
| CGM Hardware Subsidization | Silicon Valley employers fund continuous glucose monitoring for prediabetic workforce metabolic tracking. |
| In-Store Clinic Expansion | CVS Health and Walgreens bridge prescription fulfillment with counseling across Florida retail corridors. |
| Compounding Pharmacy Backward Integration | Captures demand displaced by FDA enforcement against unapproved semaglutide supply chains. |
| Digital Therapeutics Bundling | App-based behavioral coaching paired with medication delivery improves payer-relevant outcome metrics. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this United States weight management market analysis. Primary interviews with formulary directors at pharmacy benefit managers, endocrinology prescribing physicians, employer benefits consultants, and retail pharmacy clinic operators combined with FDA adverse event databases, CMS Medicare claims extracts, and state Medicaid formulary publications. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation validated segment-level estimates across the analysis window.
Granularity-level modeling captured product type chemistry distinctions, patient life-stage reimbursement eligibility, channel infrastructure regulatory exposure, and macronutrient philosophy ingredient sourcing requirements. CAGRs derived from employer wellness program adoption curves, GLP-1 prescribing expansion trajectories, and continuous glucose monitor penetration rates across technology sector workforces. Forecast inputs incorporated FDA compounding enforcement intensity and state-level Medicaid coverage probability assessments.
The model holds under sustained FDA regulatory clarity and employer-sponsored benefit expansion; deviation in Medicare Part D legislative timing or GLP-1 manufacturing disruption would shift volume and value projections. Forecasts reflect assumptions around pharmacotherapy access pathway durability and behavioral coaching platform retention rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Middle East and Africa Sports Nutrition Market
Sports Nutrition
Arginine Supplement Market
Sports Nutrition
Caloric Supplements Market
Sports Nutrition
Brazil Sports Nutrition Market
Sports Nutrition
Caloric Test Market
Sports Nutrition
Europe Protein Based Sports Drinks Market
Sports Nutrition
United States Sports Drink Market
Sports Nutrition
Sports Supplement Market
Sports Nutrition
North America Protein Based Sports Drinks Market
Sports Nutrition
Creatine Supplements Market
Sports Nutrition
Cricket Protein Powder Market
Sports Nutrition
Branched Chain Amino Acid Supplements Market
Sports Nutrition
Androstenedione Market
Sports Nutrition
North America Sports Drink Market
Sports Nutrition
Asia-Pacific Sports Drink Market
Sports Nutrition
South America Sports Nutrition Market