
 United States Sports Nutrition Market | 2026-2036
United States Sports Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
United States Sports Nutrition Market Outlook
Contract manufacturing is rebalancing toward hybrid sourcing as brands blend in-house flavor development with third-party protein toll processing. Glanbia PLC leverages its vertically integrated whey supply chain to dominate bulk ingredient contracts. Abbott Laboratories sustains hospital and clinical channel access that competitors cannot replicate. PepsiCo Inc. competes through beverage-scale distribution that extends into convenience retail.
United States sports nutrition encompasses formulated consumables designed to enhance athletic performance, recovery, or body composition, typically containing protein isolates, carbohydrate matrices, caffeine, creatine monohydrate, or branched-chain amino acids at specified dosages. These products serve competitive athletes, recreational exercisers, and lifestyle consumers seeking measurable physiological outcomes from training regimens. Protein powders occupy the deepest margin pools due to ingredient commoditization at the base and premiumization at the branded finish. Online retail channels represent the fastest-expanding distribution vector, though supermarkets retain volume leadership through impulse placement near pharmacy and produce zones.
FDA New Dietary Ingredient notifications, FTC substantiation requirements for performance claims, and state-level Prop 65 labeling mandates in California collectively elevate compliance costs and barrier thresholds for new entrants. The USDA Organic seal and NSF Certified for Sport programs function as de facto market access credentials for collegiate and professional athletic procurement. Stakeholders must monitor evolving enforcement patterns around cannabidiol and selective androgen receptor modulator adulteration that threaten category credibility and invite federal preemption debates.
Market Dynamics
NCAA athletic programs are expanding mandatory nutrition staff positions, creating institutional procurement channels that bypass traditional retail and reshape how performance products reach competitive athletes.
Growth Catalysts
- Collegiate athletic procurement mandates:NCAA Division I programs now employ full-time sports dietitians, generating institutional purchase orders for NSF Certified for Sport products that retail channels cannot replicate.
- FDA enforcement clarity:New Dietary Ingredient notification pathways for caffeine analogs and novel botanicals are stabilizing, reducing regulatory uncertainty that previously stalled pre-workout innovation cycles.
- California fitness corridor density:Los Angeles and San Francisco metropolitan areas concentrate boutique gym chains and CrossFit affiliates driving premium protein consumption at per-capita rates unmatched elsewhere in the United States.
Market Restraints
- Whey protein concentrate volatility:Dairy commodity price swings tied to Midwest feed grain costs compress margin predictability for mid-sized brands lacking forward purchase contracts.
- Prop 65 litigation exposure:California's Safe Drinking Water and Toxic Enforcement Act generates private plaintiff lawsuits over heavy metal content in plant proteins, elevating insurance and testing burdens nationwide.
- Third-party manufacturing concentration:Toll processing for flavored protein powders clusters with a handful of Wisconsin and Utah contract manufacturers, creating bottleneck risk during seasonal demand spikes.
Strategic Opportunities
- Texas and Florida metropolitan expansion:Dallas-Fort Worth and Miami fitness club penetration remains below California benchmarks, offering whitespace for premium brand entry before local competitors consolidate shelf space.
- USDA Organic certification tailwinds:Federal procurement guidelines for military and federal employee wellness programs increasingly preference organic-labeled products, opening institutional segments previously closed to conventional formulations.
- Telehealth integration:Registered dietitian networks delivering remote coaching protocols are embedding supplement recommendations into patient management software, creating prescription-like adherence channels.
Industry Challenges
- NSF Certified for Sport backlog:Third-party testing capacity constraints extend certification timelines to 14-18 weeks, delaying collegiate and professional team contract executions.
- Flavor stability capex requirements:Natural masking technologies for plant proteins demand extrusion and microencapsulation equipment investments that strain sub-$50 million revenue manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Sports Nutrition Market |
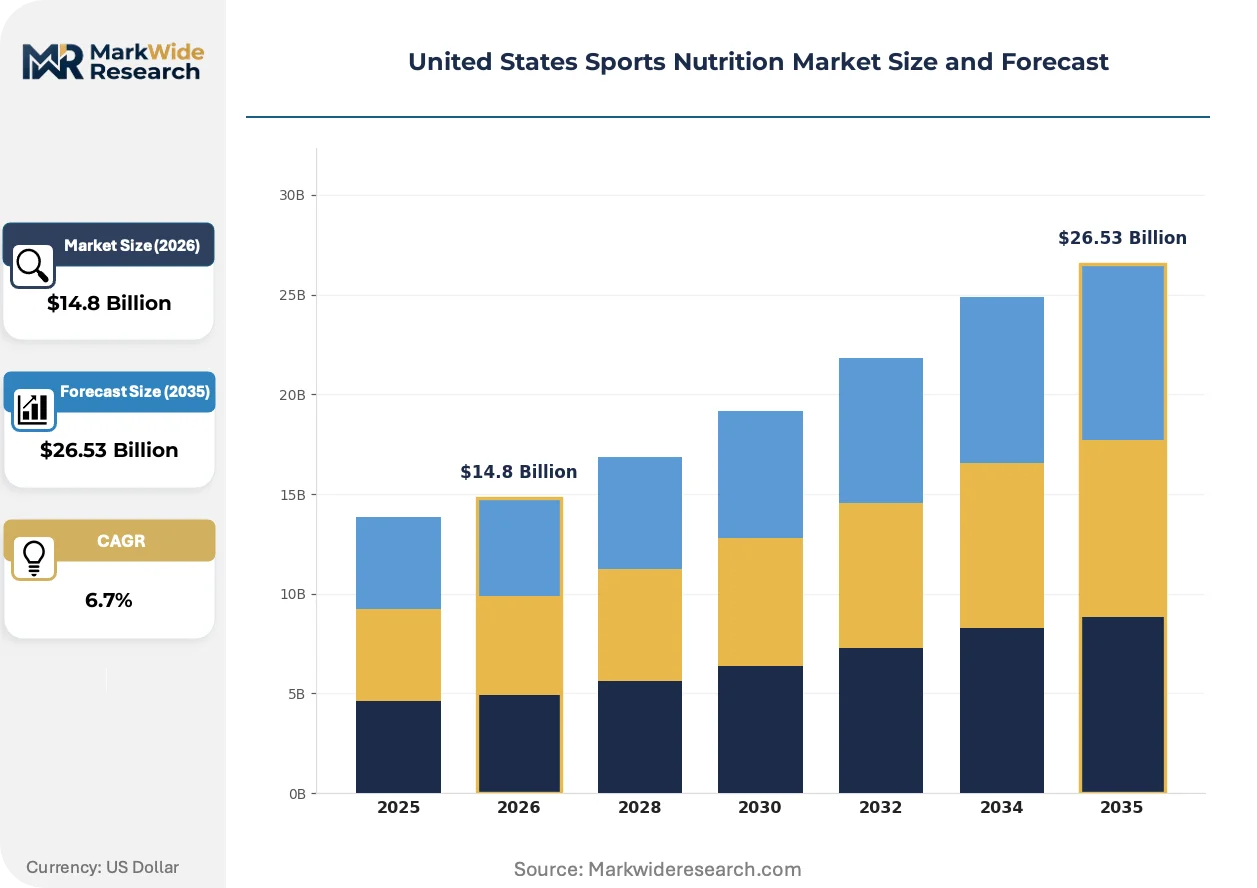
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Powders, Energy Bars, Sports Drinks, Meal Replacements Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales End User: Athletes, Fitness Enthusiasts, Bodybuilders, Casual Users Ingredient Type: Plant-Based, Whey, Casein, Creatine |
| Companies Covered | Glanbia PLC, Abbott Laboratories, PepsiCo Inc., The Coca-Cola Company, GNC Holdings, Quest Nutrition, Clif Bar & Company, NOW Foods, Hormel Foods Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Sports Nutrition Market Strategic Shifts
Precision fermentation and cellular agriculture are migrating from alt-protein headlines into sports nutrition ingredient supply, while regulatory scrutiny on novel stimulants intensifies and direct-to-consumer subscription models displace conventional replenishment habits.
Precision fermentation-derived whey proteins are expanding into the ingredient supply base of major sports nutrition brands. Biotech suppliers in California and Illinois now offer whey-identical proteins without dairy supply chain exposure. This technology is expanding into price-competitive positioning against conventional isolate products by 2026.
The FDA's evolving enforcement stance on NDI notifications for pre-workout stimulants is compressing formulation freedom. DMHA and similar synthetic alkaloids face accelerated warning letter campaigns. Pre-workout manufacturers are responding with botanical caffeine matrices and theacrine-based alternatives that require no novel ingredient filings.
Subscription-based replenishment is displacing retail repurchase cycles among millennial and Gen-Z consumers. Brands offering personalized flavor rotation and flexible delivery intervals capture higher lifetime value than supermarket-dependent competitors. This behavioral shift concentrates in coastal metropolitan markets where gym attendance patterns are most predictable.
United States Sports Nutrition Market Segmentation
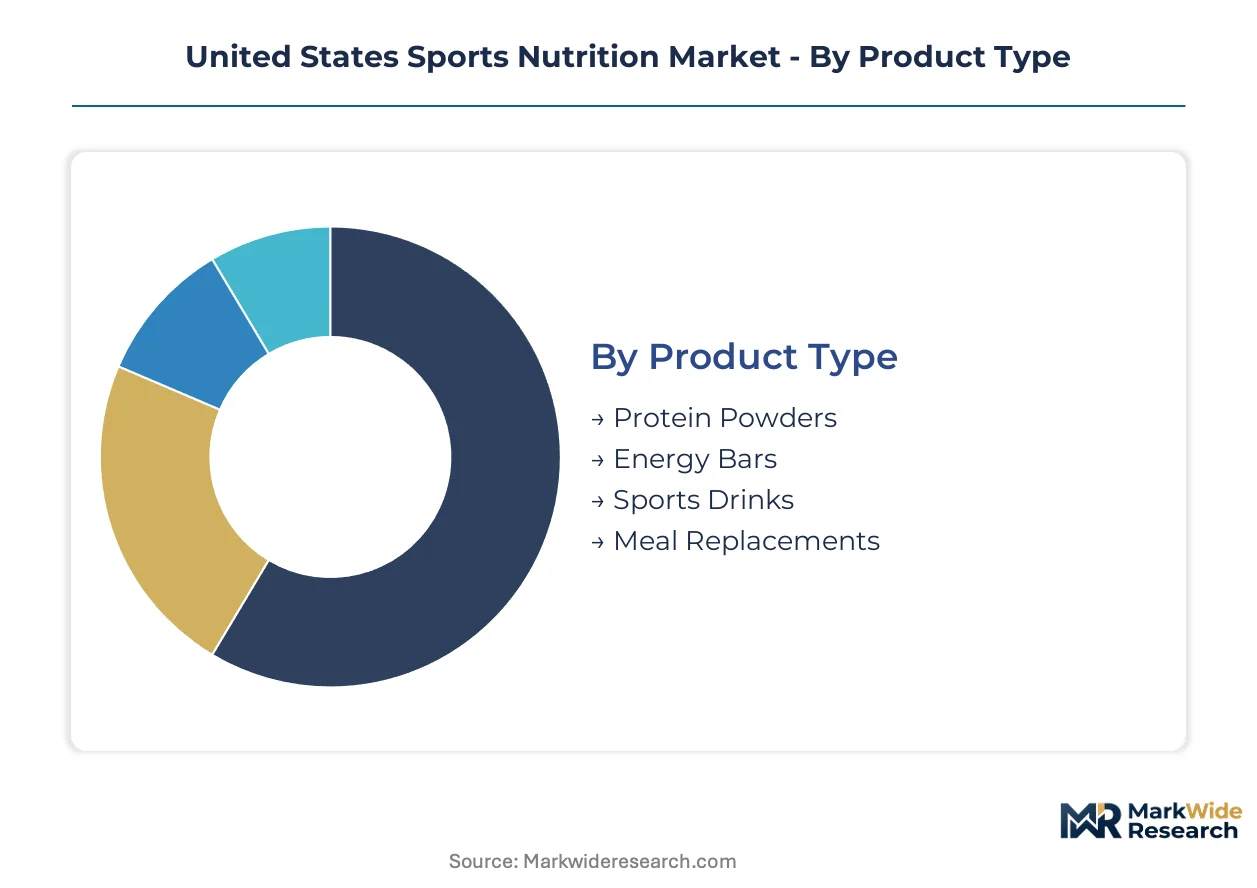
Sports nutrition segmentation reveals how formulation choices, channel strategies, and user psychographics create distinct margin profiles. Understanding these divisions exposes where premium pricing holds and where commodity pressure erodes returns.
Product Type:
Volume concentrates in mass-market formats while premium extraction defines profitability at the specialty tier.
- Protein Powders:Whey isolates and concentrates dominate institutional procurement through NSF Certified for Sport accreditation. California's boutique gym chains and CrossFit affiliates drive per-capita consumption unmatched elsewhere, though whey protein concentrate volatility tied to Midwest feed grain costs compresses margin predictability for mid-sized brands lacking forward contracts.
- Energy Bars:Formulated with carbohydrate matrices and branched-chain amino acids at specified dosages, these products serve time-constrained athletes seeking portable nutrition. Demand clusters in metropolitan fitness corridors where impulse placement near pharmacy zones in supermarkets retains volume leadership despite online expansion.
- Sports Drinks:Electrolyte and carbohydrate formulations competing through beverage-scale distribution into convenience retail.
- Meal Replacements:Complete macronutrient profiles targeting body composition goals with subscription-based replenishment models gaining traction.
Today's leader: Protein Powders. Tomorrow's challenger: Meal Replacements.
Distribution Channel:
Channel selection determines compliance burden and customer acquisition economics simultaneously.
- Online Retail:Direct-to-consumer subscription models displace conventional replenishment cycles among millennial and Gen-Z consumers. Personalized flavor rotation and flexible delivery intervals capture higher lifetime value than supermarket-dependent competitors, concentrating in coastal metropolitan markets where gym attendance patterns are most predictable.
- Supermarkets:Impulse placement near pharmacy and produce zones retains volume leadership despite faster-expanding online alternatives.
- Health Stores:Specialty retailers carrying NSF Certified for Sport and USDA Organic products for collegiate procurement channels.
- Direct Sales:Institutional purchase orders from NCAA Division I programs bypassing traditional retail entirely.
Online Retail captures the steepest expansion trajectory as subscription mechanics reshape repurchase behavior.
End User:
User sophistication creates tiered pricing tolerance from clinical precision to lifestyle aspiration.
- Athletes:Competitive performers requiring NSF Certified for Sport accreditation for collegiate and professional team contracts. NCAA athletic programs expanding mandatory nutrition staff positions generate institutional procurement channels that retail cannot replicate.
- Fitness Enthusiasts:Recreational exercisers seeking measurable physiological outcomes from training regimens, driving premium protein consumption in Los Angeles and San Francisco metropolitan areas.
- Bodybuilders:Users prioritizing body composition outcomes with specific dosage requirements for creatine monohydrate and branched-chain amino acids.
- Casual Users:Lifestyle consumers purchasing through convenience retail with lower formulation specificity tolerance.
Athletes command premium positioning through certification requirements. Fitness Enthusiasts represent the volume expansion opportunity.
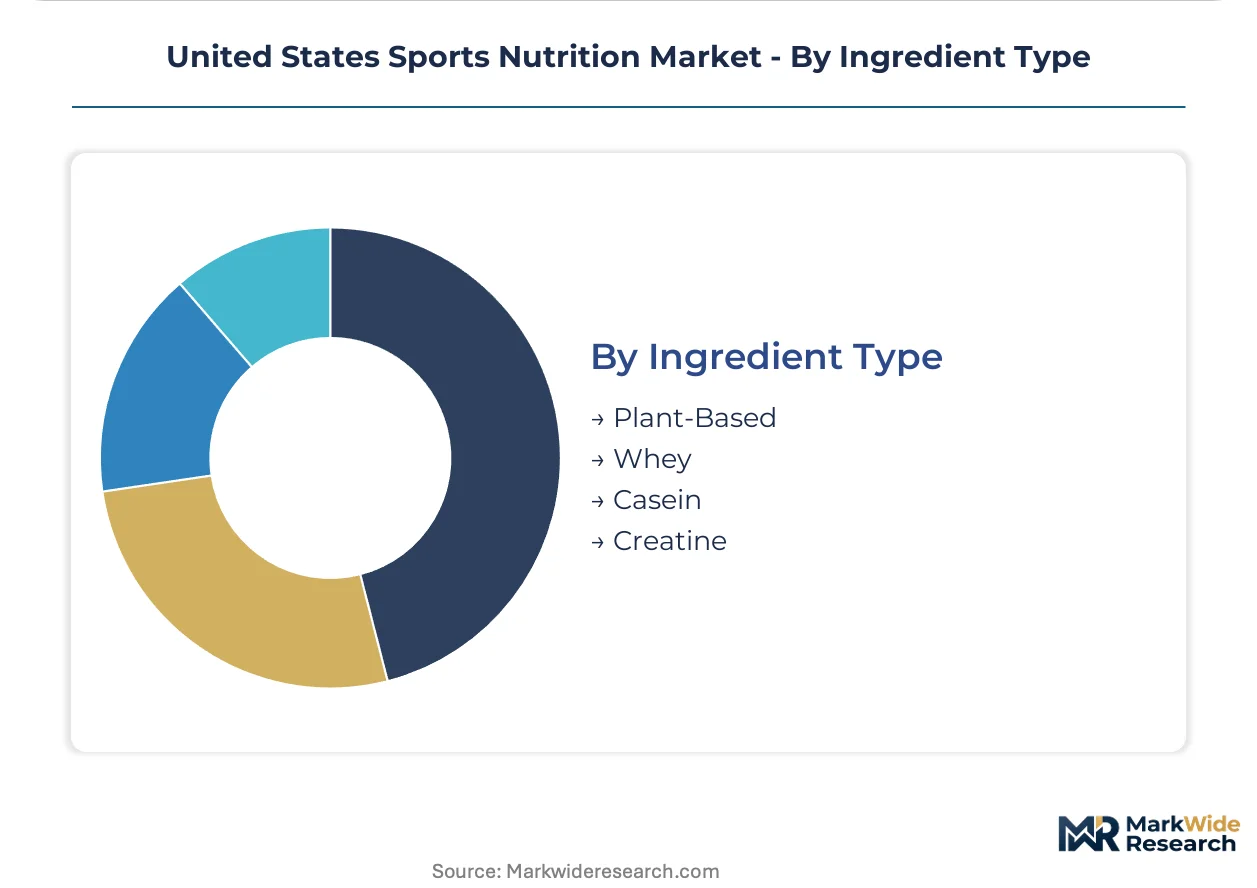
Ingredient Type:
Input sourcing separates commodity-exposed formulations from supply-chain-resilient alternatives.
- Plant-Based:Pea, rice, and hemp protein isolates facing Prop 65 litigation exposure over heavy metal content, elevating insurance and testing burdens nationwide for California compliance.
- Whey:Dairy-derived proteins dominating bulk ingredient contracts through vertically integrated supply chains, though price swings tied to Midwest feed grain costs create margin volatility.
- Casein:Slow-digesting dairy protein targeting overnight recovery applications with specialized manufacturing requirements.
- Creatine:Monohydrate formulations with established FDA enforcement pathways avoiding New Dietary Ingredient notification complexity.
Whey retains volume dominance. Plant-Based ingredients gain share fastest as precision fermentation expands price-competitive positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's fitness-dense metropolitan corridors concentrate the highest per-capita consumption of premium sports nutrition products in the United States, with Los Angeles and San Francisco driving demand through boutique gym chains and CrossFit affiliates.
California
Boutique gym chains and CrossFit affiliates in Los Angeles and San Francisco metropolitan areas generate unmatched per-capita premium protein consumption. The state's Safe Drinking Water and Toxic Enforcement Act (Prop 65) mandates heavy metal labeling for plant proteins, elevating compliance costs nationwide for brands distributing into California. San Diego and Orange County host precision fermentation biotech suppliers offering dairy-identical proteins without commodity dairy exposure.
Texas
Dallas-Fort Worth fitness club penetration remains below California benchmarks, creating whitespace for premium brand entry before local competitors consolidate shelf space. The Texas Department of State Health Services enforces food and dietary supplement manufacturing standards that align with FDA cGMP requirements. Houston's institutional procurement channels serve NCAA Division I athletic programs expanding mandatory sports dietitian positions.
Florida
Miami's metropolitan fitness market shows underpenetration relative to coastal benchmarks, offering expansion opportunity for subscription-based replenishment models. The Florida Department of Agriculture and Consumer Services regulates dietary supplement distribution through state-level food safety protocols. Orlando and Tampa Bay clusters concentrate contract manufacturing capacity for flavored protein powders serving seasonal demand spikes.
Wisconsin
Midwest dairy processing infrastructure anchors whey protein concentrate production with vertically integrated supply chain advantages. The Wisconsin Department of Agriculture, Trade and Consumer Protection oversees dairy-derived ingredient manufacturing standards. Madison and Milwaukee metropolitan areas host toll processing facilities that create bottleneck risk for mid-sized brands lacking forward purchase contracts during peak demand periods.
Utah
Mountain West contract manufacturing clusters specialize in natural masking technologies and microencapsulation equipment for plant protein formulations. The Utah Department of Agriculture and Food regulates dietary supplement production facilities under state food safety frameworks. Salt Lake City and Provo-Orem metropolitan areas concentrate third-party manufacturing capacity that serves national brands seeking flavor stability investments.
United States Sports Nutrition Market Competitive Environment
Global majors compete with regional champions across distribution channel access and institutional procurement relationships. The vendor base stratifies into three tiers: multinational conglomerates with beverage-scale distribution networks, vertically integrated ingredient suppliers with captive dairy processing, and specialty brands competing through subscription mechanics and certification premiums. Dominant competitive moves include strategic partnerships with NCAA athletic programs and portfolio diversification into precision fermentation-derived ingredients.
Among Ireland-based multinational suppliers, Glanbia PLC exemplifies the vertically integrated archetype through whey supply chain control. Abbott Laboratories represents the clinical channel specialist position with hospital and institutional access. PepsiCo Inc. anchors the beverage-scale distribution tier extending into convenience retail networks. These three companies occupy distinct competitive positions based on structural advantages in supply chain configuration, regulatory compliance infrastructure, and channel relationships rather than overlapping direct competition.
| Leading Market Players |
|---|
| Glanbia PLC |
| Abbott Laboratories |
| PepsiCo Inc. |
| The Coca-Cola Company |
| GNC Holdings |
| Quest Nutrition |
| Clif Bar & Company |
| NOW Foods |
| Hormel Foods Corporation |
| Others |
Value Chain & Pricing Dynamics
USDA Organic certification gates qualified supply and premium-tier pricing access, as federal procurement guidelines for military and federal employee wellness programs increasingly preference organic-labeled products. This mandate creates a bifurcated market where certified suppliers command institutional premiums while conventional formulations face margin compression in competing channels.
Pricing Analysis
Input-cost pass-through from whey protein concentrate volatility tied to Midwest feed grain costs compresses margin predictability for mid-sized brands lacking forward purchase contracts. Three-tier pricing structure across premium, standard, and economy levels separates NSF Certified for Sport products from conventional formulations from private-label alternatives. Price differentiation hinges on certification grade and volume scale. Cost compression in the standard tier is intensifying because dairy commodity price swings compress operating leverage. Casual users purchasing through convenience retail exhibit highest price sensitivity, while NCAA athletic programs demonstrate lowest sensitivity due to mandatory compliance requirements.
Supply Chain Analysis
Warehouse-distribution layer concentration in Wisconsin and Utah contract manufacturers creates seasonal bottleneck risk during peak demand periods. Supply draws from Midwest dairy processing infrastructure, California precision fermentation biotech clusters, and Mountain West toll processing facilities. Raw material dependencies include whey isolates, pea protein isolates, and natural masking technologies. Single-source vulnerability concentrates in flavored protein powder toll processing. Distribution runs through hybrid models blending direct-to-consumer subscription fulfillment with beverage-scale convenience retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States sports nutrition market functions as a geographic-arbitrage play, with Prop 65 compliance costs in California elevating pricing floors relative to Texas and Florida metropolitan corridors where regulatory burdens remain lighter.
For Market Incumbents: To counter precision fermentation-derived whey proteins from California and Illinois biotech suppliers, incumbents must deepen backward integration into captive dairy processing infrastructure and accelerate NSF Certified for Sport certification investments to defend institutional procurement relationships with NCAA Division I programs.
For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable entry vector, targeting Dallas-Fort Worth and Miami metropolitan fitness markets where boutique gym penetration remains below California benchmarks and local competitors have yet to consolidate shelf space.
For Investors and Strategic Acquirers: Roll-up economics work for specialty brands with subscription mechanics and certification premiums because customer lifetime value concentration in coastal metropolitan markets creates scalable acquisition multiples. Acquisition target archetypes include precision fermentation ingredient suppliers and telehealth-integrated registered dietitian networks. The signal to watch is FDA enforcement clarity on novel stimulant pathways, which would accelerate formulation innovation cycles and expand addressable product margins.
| Strategic Initiative | Industry Significance |
|---|---|
| NSF Certified for Sport Portfolio Expansion | Unlocks NCAA Division I institutional procurement channels that retail competitors cannot replicate. |
| Precision Fermentation Ingredient Sourcing | Eliminates dairy commodity price exposure while meeting federal organic procurement preferences. |
| Direct-to-Consumer Subscription Launch | Captures higher lifetime value through personalized flavor rotation in coastal metropolitan markets. |
| Telehealth Platform Integration | Embeds supplement recommendations into registered dietitian patient management software protocols. |
| Texas and Florida Distribution Expansion | Secures shelf space in underpenetrated metropolitan corridors before local competitors consolidate positions. |
Study Parameters
Direct dialogue with sports nutrition brand managers, NCAA athletic program nutrition directors, contract manufacturing procurement leads, and retail category buyers anchored qualitative findings, combined with secondary validation from FDA warning letter databases, NSF certification registries, USDA organic compliance records, and Nielsen retail audit data. Bottom-up and top-down triangulation cross-checked volume estimates against channel shipment data and consumer panel expenditure patterns.
Bottom-up modeling built category forecasts from individual segment trajectories across product type, distribution channel, end user, and ingredient type dimensions, while top-down approaches anchored aggregate market sizing to macroeconomic fitness participation trends and protein consumption per capita benchmarks. CAGRs were derived from regression analysis of historical growth patterns applied to projected demand drivers. Industry-specific forecast inputs included NCAA athletic program nutrition staff expansion timelines and precision fermentation capacity buildout announcements.
The model assumes a particular technology adoption path for precision fermentation-derived proteins; alternative pathways for cellular agriculture scale-up would alter the outlook for dairy-dependent supply chains. Forecasts reflect documented assumptions around regulatory enforcement continuity and commodity price stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Energy and Protein Bars Market
Sports Nutrition
Caloric Supplements Market
Sports Nutrition
GLA Supplements Market
Sports Nutrition
Medicated Fitness Supplements Market
Sports Nutrition
Brazil Sports Drinks Market
Sports Nutrition
Global Gummy Supplements Market
Sports Nutrition
Cricket Protein Powder Market
Sports Nutrition
Global Ketone Supplements Market
Sports Nutrition
Brazil Sports Nutrition Market
Sports Nutrition
Germany Sports Nutrition Market
Sports Nutrition
Caloric Test Market
Sports Nutrition
Europe Weight Management Supplement Market
Sports Nutrition
Global Sexual Enhancement Supplements Market
Sports Nutrition
Europe Protein Based Sports Drinks Market
Sports Nutrition
Middle East Sports Drinks Market
Sports Nutrition
Asia-Pacific Weight Management Supplement Market