
 Global Sexual Enhancement Supplements Market | 2026-2036
Global Sexual Enhancement Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sexual Enhancement Supplements Market Foresight
Microencapsulation and sustained-release delivery technology is reshaping bioavailability profiles in sexual enhancement formulations, enabling precise dosing windows and improved ingredient stability. Dabur India Ltd. leverages its Ayurvedic R&D heritage to anchor herbal extract portfolios across South Asian and diaspora markets. GNC Holdings competes through retail footprint density and private-label manufacturing scale in North American health stores. Reckitt Benckiser Group plc differentiates via pharmacy channel control and clinician endorsement programs in European markets.
Sexual enhancement supplements comprise orally administered formulations containing bioactive compounds—typically L-arginine, ginsenosides, or yohimbine alkaloids at standardized concentrations—designed to modulate vascular function, hormonal pathways, or neurotransmitter activity related to sexual response. These products are manufactured through extraction, granulation, and tableting or encapsulation processes, then distributed for consumer self-medication or adjunctive wellness use. Pills and capsules dominate volume due to manufacturing economies and consumer familiarity, though gummies are gaining fastest among younger demographics seeking palatable, discreet consumption formats. Online retail captures expanding margin pools as subscription models reduce customer acquisition costs and enable personalized bundling across the men and women end-user segments.
The FDA regulates dietary supplement claims under DSHEA while the EMA and national EU bodies enforce novel food and borderline product classifications that determine market access pathways. REACH compliance for synthetic compound sourcing and EFSA health claim substantiation requirements are elevating formulation costs and favoring suppliers with in-house toxicology capabilities. Stakeholders must monitor regulatory divergence between permissive self-regulation regimes and emerging pre-market notification requirements that could reshape competitive barriers.
Market Dynamics
Microencapsulation technology is compressing formulation timelines while FDA's evolving DSHEA enforcement is elevating clinical substantiation costs for market access. These twin pressures are redistributing margin pools toward suppliers with in-house R&D and toxicology capabilities.
Growth Catalysts
- Telehealth platform normalization:Direct-to-consumer subscription models in the United States reduce customer acquisition costs and enable personalized bundling across demographic segments. Middle-aged adults drive volume expansion as stigma around sexual wellness declines.
- REACH compliance elevation:ECHA's tightening requirements for synthetic compound sourcing favor manufacturers with captive toxicology capabilities and in-house extraction facilities.
- Ayurvedic heritage commercialization:Standardized herbal extract portfolios anchored in traditional medicine R&D unlock diaspora market penetration across South Asian consumer bases.
Market Restraints
- Novel food classification friction:EMA and national EU borderline product determinations create unpredictable market access timelines for innovative bioactive formulations.
- Raw material concentration risk:Ginsenoside and yohimbine alkaloid supply chains concentrate in specific cultivation zones, exposing formulators to harvest volatility and quality inconsistency.
- Clinical substantiation cost inflation:EFSA health claim requirements demand placebo-controlled trials that mid-tier manufacturers cannot fund without dilution or partnership.
Strategic Opportunities
- Gummy format adoption white space:Palatable, discreet consumption formats capture younger demographics underserved by pill and capsule incumbents.
- Preventive health attitude convergence:Wellness positioning adjacent to cardiovascular and hormonal health categories expands addressable consumer base beyond symptomatic users.
- Pharmacy channel reclamation:Clinician endorsement programs in European markets restore professional legitimacy that e-commerce commoditization eroded.
Industry Challenges
- Formulation scientist scarcity:Cross-disciplinary expertise spanning phytochemistry, pharmacokinetics, and food-grade manufacturing commands premium compensation and retention difficulty.
- Legacy system integration friction:ERP and quality management systems designed for pharmaceutical GMP struggle to accommodate dietary supplement batch variability and botanical raw material heterogeneity.
- IP landscape complexity:Traditional knowledge patent disputes and extract standardization method claims create licensing uncertainty for herbal-derived portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sexual Enhancement Supplements Market |
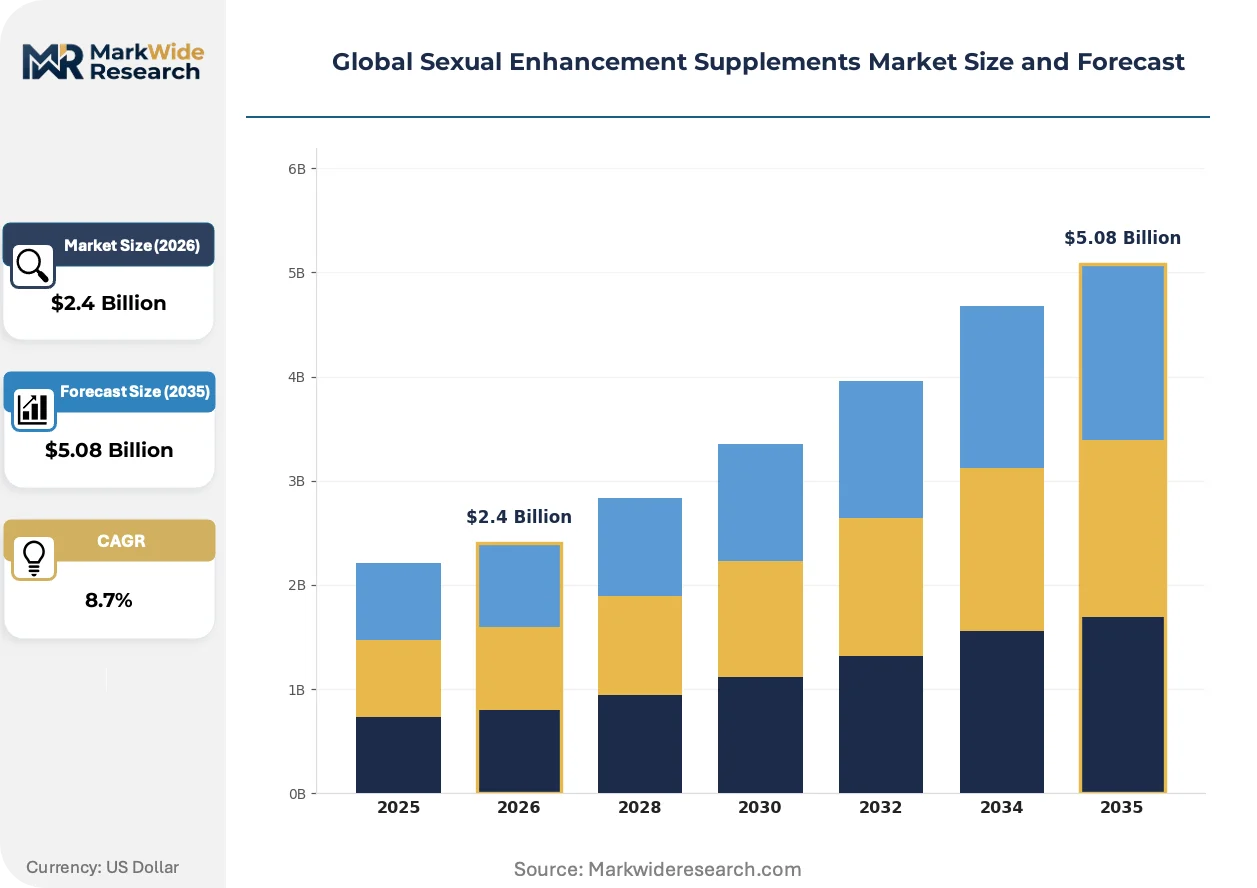
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pills, Capsules, Liquid Extracts, Powders, Gummies Distribution Channel: Online Retail, Pharmacies, Health Stores, Direct Selling, Supermarkets End User: Men, Women, Couples, Middle-aged Adults, Seniors Ingredient Source: Herbal Extracts, Synthetic Compounds, Vitamins, Amino Acids, Enzymes |
| Companies Covered | Herbalife Nutrition Ltd., GNC Holdings, Dabur India Ltd., Himalaya Global Holdings Ltd., Leading Edge Health, Church & Dwight Co., Inc., Reckitt Benckiser Group plc, Nature's Way Products, Irwin Naturals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sexual Enhancement Supplements Market Shifts & Advancements
Sustained-release delivery systems are redefining competitive differentiation while regulatory divergence between permissive and pre-market notification regimes reshapes geographic prioritization. These forces concentrate investment in bioavailability enhancement and jurisdiction-specific compliance infrastructure.
Liposomal encapsulation technology improves ingredient stability and enables precise dosing windows for vascular-modulating compounds. Premium formulation houses adopt these systems to justify price positioning against commodity generic alternatives. Manufacturing is migrating from conventional granulation toward nano-dispersion methods that compress dissolution variability.
FDA's evolving oversight of structure-function claims under DSHEA is tightening labeling substantiation requirements and pushing manufacturers toward clinical trial investment. The industrial consequence is margin compression for private-label assemblers without captive research capabilities. Subscription-based direct-to-consumer brands in the United States respond by building in-house medical advisory boards and commissioning peer-reviewed studies.
Younger demographics reject traditional pill formats in favor of gummy and functional food delivery systems that align with wellness lifestyle positioning. Pharmacy and health store channels lose share to specialized e-commerce platforms that offer discreet packaging and algorithmic personalization. This behavioral rotation is most visible in metropolitan United States markets where telehealth integration enables seamless prescription-to-supplement continuity.
Global Sexual Enhancement Supplements Market Segmentation
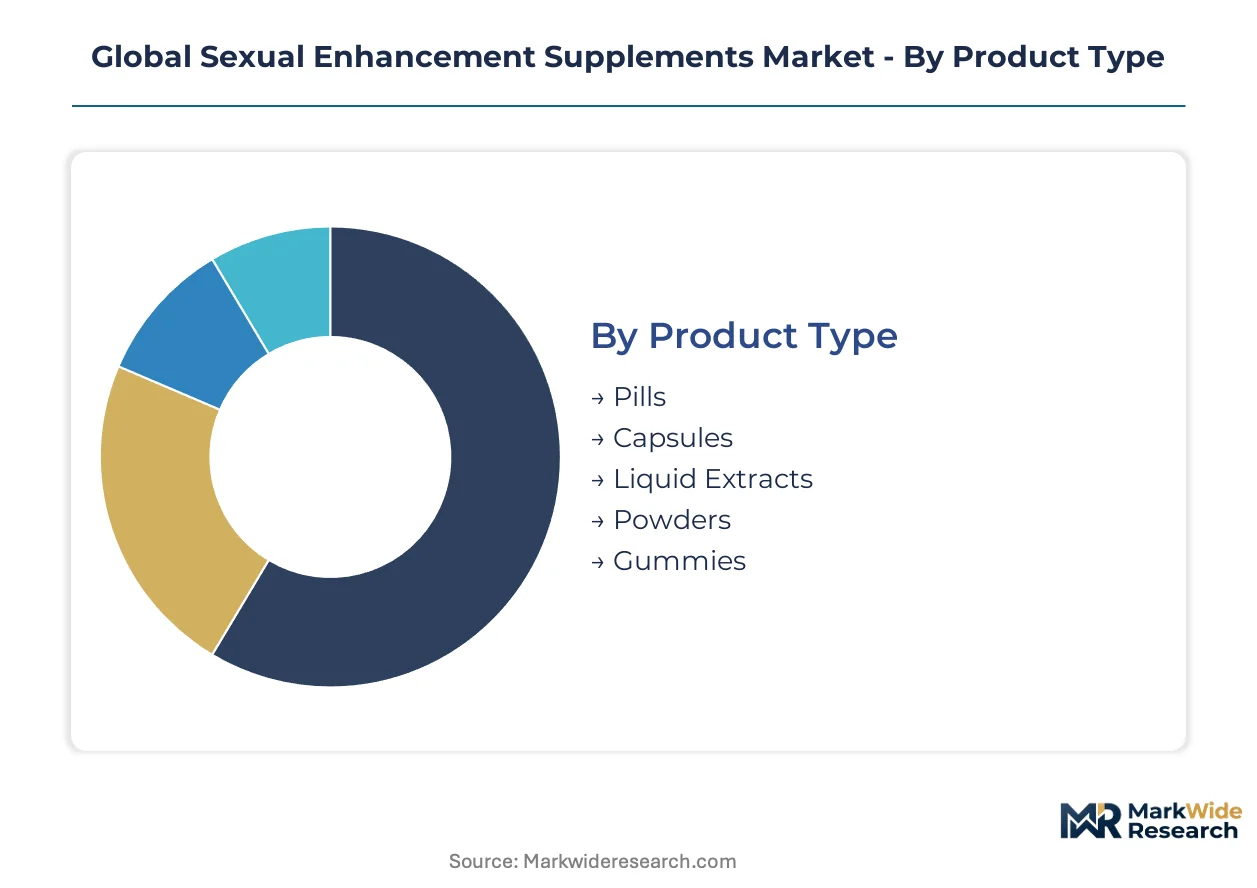
Segmentation in sexual enhancement supplements determines formulation priorities, channel investment, and regulatory pathway selection. Manufacturers must align R&D spend with format-specific bioavailability requirements and demographic-specific consumption patterns.
Product Type:
Format selection drives manufacturing infrastructure requirements and margin profiles across the value chain.
- Pills:Compressed tablets containing standardized herbal extracts or synthetic actives deliver precise dosing through conventional granulation and tableting equipment. United States health store chains and pharmacy channels concentrate demand here due to consumer familiarity and shelf stability requirements.
- Gummies:Palatable gelatin or pectin matrices mask bitter alkaloid tastes while enabling discreet consumption. Younger demographics in metropolitan United States markets are rotating toward this format fastest as wellness lifestyle positioning displaces clinical aesthetics.
- Capsules:Hard-shell gelatin or HPMC enclosures protect moisture-sensitive compounds and enable combination formulations.
- Liquid Extracts:Tincture-based delivery systems offer rapid absorption for vascular-modulating compounds.
- Powders:Bulk active blends allow customizable dosing and functional food integration.
Pills hold installed capacity. Gummies are rotating up the share rankings.
Distribution Channel:
Channel configuration determines customer acquisition economics and brand positioning latitude.
- Online Retail:Subscription-based direct-to-consumer platforms capture expanding margin pools through algorithmic personalization and discreet packaging. United States telehealth integration enables seamless prescription-to-supplement continuity for middle-aged adult segments.
- Pharmacies:Professional endorsement programs restore legitimacy that e-commerce commoditization eroded. European markets concentrate demand here as EMA borderline product classifications favor clinician-mediated distribution.
- Health Stores:Specialized retail footprints target wellness-oriented consumers seeking adjunctive cardiovascular support positioning.
- Direct Selling:Multi-level marketing networks penetrate diaspora communities with Ayurvedic heritage products.
- Supermarkets:Mass-market placement captures impulse purchasing for vitamin-adjacent positioning.
Online Retail commands the steepest expansion trajectory. Pharmacies defend professional legitimacy positioning.
End User:
Demographic targeting shapes messaging architecture and clinical substantiation requirements.
- Middle-aged Adults:Preventive health attitudes and declining stigma around sexual wellness drive volume expansion fastest. United States subscription platforms concentrate acquisition investment here through personalized bundling with hormonal and cardiovascular wellness categories.
- Men:Vascular function modulation represents the historical core demand segment with established ingredient pathways around L-arginine and ginsenosides.
- Women:Neurotransmitter and hormonal pathway targeting requires distinct formulation R&D and clinical trial investment.
- Couples:Dual-user positioning expands addressable base through shared subscription models.
- Seniors:Drug-interaction safety profiles and clinician consultation requirements elevate regulatory scrutiny.
Men hold established demand base. Middle-aged Adults are climbing the fastest.
Ingredient Source:
Raw material provenance determines regulatory pathway, supply security, and substantiation burden.
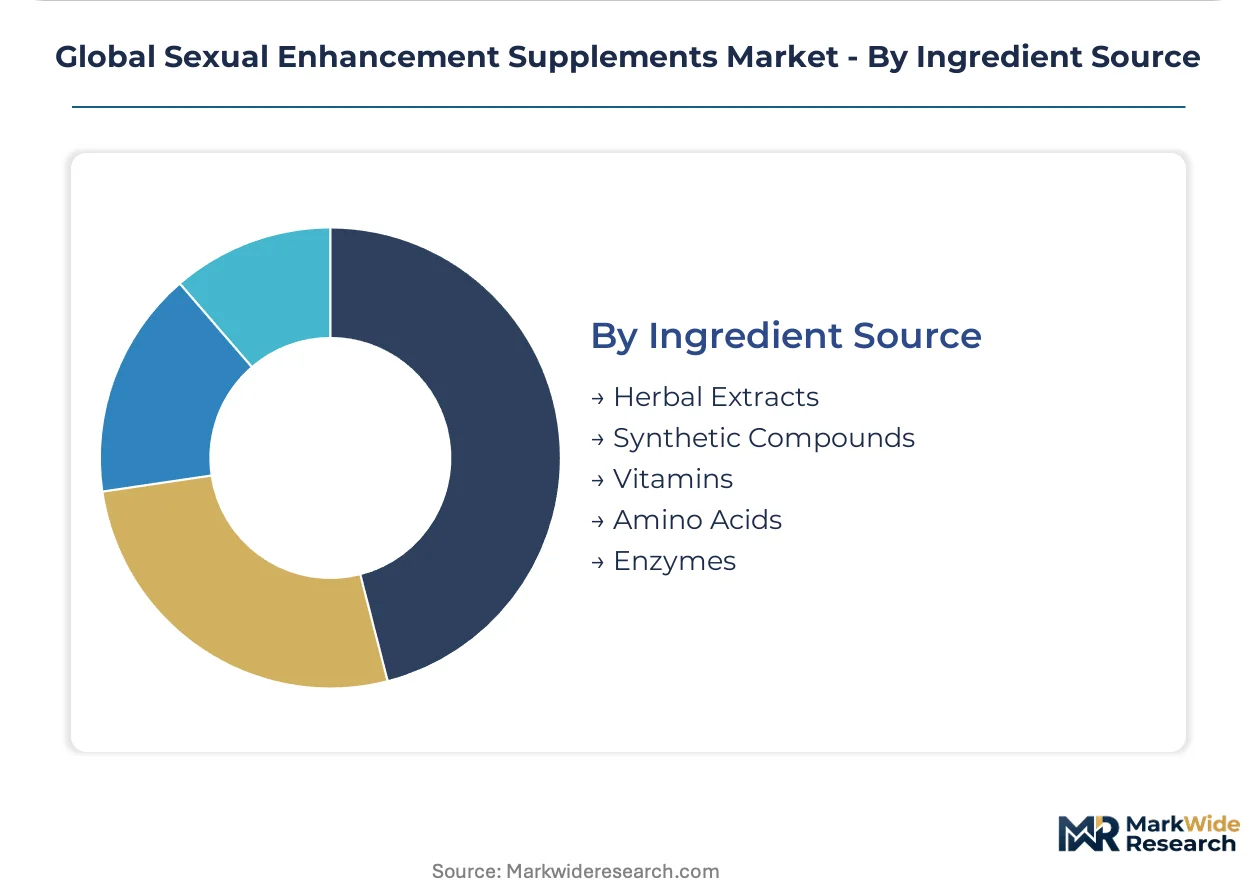
- Herbal Extracts:Standardized ginsenoside, yohimbine alkaloid, and traditional medicine portfolios anchor Ayurvedic heritage suppliers. REACH compliance for cultivation-zone sourcing favors manufacturers with captive extraction facilities in India and Southeast Asian supply bases.
- Synthetic Compounds:Precise molecular control enables patent protection and batch consistency for vascular-modulating actives.
- Vitamins:Micronutrient cofactors for hormonal synthesis pathways occupy mass-market price tiers.
- Amino Acids:L-arginine and L-citrulline substrates for nitric oxide production dominate functional positioning.
- Enzymes:Bioavailability enhancement and digestive support applications represent emerging formulation territory.
Herbal Extracts anchor diaspora market penetration. Synthetic Compounds are gaining share in pharmacy-channel premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports standardized herbal extracts to United States and European formulators, anchoring a trade corridor that supplies ginsenoside and alkaloid raw materials for finished supplement manufacturing.
United States
Telehealth platform normalization and subscription-based direct-to-consumer models drive demand concentration. FDA's evolving DSHEA enforcement tightens structure-function claim substantiation requirements. The San Francisco Bay Area and New York Metro host venture-backed wellness brands building in-house medical advisory boards.
Germany
Pharmacy channel preference and clinician endorsement programs sustain professional legitimacy positioning. EMA borderline product classifications and BfArM oversight create complex market access pathways. The Cologne-Düsseldorf corridor concentrates contract manufacturing for EU-compliant herbal formulations.
India
Ayurvedic heritage commercialization and diaspora market penetration accelerate standardized extract demand. FSSAI labeling requirements and CDSCO quality standards elevate manufacturing compliance costs. The Mumbai-Pune belt anchors captive extraction facilities serving North American and European contract formulators.
United Kingdom
Wellness lifestyle positioning and discreet e-commerce consumption patterns expand addressable demographics. MHRA borderline product determinations and Trading Standards enforcement create regulatory uncertainty for novel bioactives. London's health-tech cluster incubates subscription brands targeting middle-aged professional segments.
China
Domestic TCM modernization and export-oriented contract manufacturing reshape supply-side capabilities. NMPA dietary supplement registration requirements and SAMR advertising enforcement elevate market entry barriers. The Yangtze River Delta concentrates extraction and encapsulation capacity serving global private-label assemblers.
Global Sexual Enhancement Supplements Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base spans multinational consumer health conglomerates, Ayurvedic heritage houses, and venture-backed direct-to-consumer brands. Three archetypes dominate: pharmacy-channel incumbents with clinician endorsement networks, telehealth-integrated subscription platforms, and raw material-integrated extract suppliers. Competitive moves concentrate on M&A for regulatory capabilities and strategic partnerships for geographic licensing.
Within the heritage-pharmaceutical tier, Dabur India Ltd. and Himalaya Global Holdings Ltd. occupy positions anchored in traditional medicine R&D and standardized extract portfolios. GNC Holdings exemplifies the retail-density archetype with private-label manufacturing scale. Reckitt Benckiser Group plc sits within the pharmacy-channel control segment, leveraging clinician programs across European markets.
| Leading Market Players |
|---|
| Herbalife Nutrition Ltd. |
| GNC Holdings |
| Dabur India Ltd. |
| Himalaya Global Holdings Ltd. |
| Leading Edge Health |
| Church & Dwight Co., Inc. |
| Reckitt Benckiser Group plc |
| Nature's Way Products |
| Irwin Naturals |
| Others |
Supply & Pricing Matrix
Overcapacity in China's Yangtze River Delta encapsulation facilities is compressing contract manufacturing margins while simultaneously elevating pricing power for Indian captive extractors serving North American subscription brands. This utilization asymmetry rewards backward-integrated suppliers with raw material security while forcing toll manufacturers toward commodity positioning.
Pricing Analysis
Cost-plus contracts with ginsenoside and yohimbine alkaloid indexation dominate raw material procurement between Indian extractors and United States formulators. Three-tier pricing structure across premium liposomal formulations, standard encapsulated products, and economy-grade tablets separates clinical substantiation tiers. Pricing pressure stems from EFSA health claim requirements that force placebo-controlled trial investment. Mass-market vitamin-adjacent segments exhibit highest price sensitivity; pharmacy-channel premium tiers show lowest.
Supply Chain Analysis
Upstream feedstock for standardized herbal extracts concentrates in India's Mumbai-Pune belt, China's Yunnan cultivation zones, and Vietnam's emerging alkaloid operations. Finished formulation draws from gelatin capsule shell producers in the United States and Germany, plus pectin gummy matrix suppliers in Italy. Single-source vulnerability runs through concentrated ginsenoside harvest zones exposed to climate volatility. Distribution runs through direct-to-consumer subscription platforms, pharmacy wholesale networks, and health store retail footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: DSHEA structure-function claim pathways and EMA borderline product classifications create asymmetric compliance burdens that favor incumbent scale.
For Market Incumbents: Harden clinical substantiation moats through captive toxicology capabilities and in-house placebo-controlled trial infrastructure. Expand backward integration into Indian extraction facilities to secure ginsenoside supply chains against harvest volatility. Defend against venture-backed subscription entrants by locking pharmacy channel exclusivity in European markets. For New Entrants and Emerging Players: Pursue gummy format white space in metropolitan United States markets where wellness lifestyle positioning displaces clinical aesthetics. Target middle-aged adult preventive health segments through telehealth-integrated subscription bundling. Leverage Ayurvedic heritage narratives for diaspora community penetration via direct-selling networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telehealth-integrated subscription platforms with algorithmic personalization capabilities. Long-term viability favors extract suppliers with captive cultivation and REACH-compliant toxicology infrastructure. Monitor FDA DSHEA enforcement intensity as inflection signal for clinical substantiation cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Investment | Placebo-controlled studies satisfy EFSA health claim requirements and defend premium positioning. |
| Backward Integration into Extraction | Captive ginsenoside and alkaloid facilities in India mitigate raw material concentration risk. |
| Telehealth Platform Partnership | Seamless prescription-to-supplement continuity captures United States middle-aged adult volume. |
| Gummy Format Manufacturing Scale-Up | Palatable delivery systems penetrate younger demographics underserved by pill incumbents. |
| Pharmacy Channel Reclamation | Clinician endorsement programs restore professional legitimacy eroded by e-commerce commoditization. |
Research Methodology
Cross-validation between formulation scientist interviews and regulatory filing databases anchors the qualitative findings. Primary fieldwork engaged R&D directors at Ayurvedic heritage houses, regulatory affairs leads at United States direct-to-consumer brands, pharmacy channel managers in Germany, and toxicology consultants advising on REACH compliance. Secondary sources included FDA warning letters and structure-function claim determinations, EMA borderline product classification registers, EFSA health claim opinions, FSSAI labeling advisories, and customs trade data for ginsenoside and alkaloid raw material flows. Bottom-up segment sizing triangulated against top-down macro health expenditure trends.
Calibration against historical subscription platform customer acquisition cost trajectories and pharmacy channel margin evolution informed the analytical framework. Segmentation dimensions modeled encompass product format, distribution channel, end-user demographic, and ingredient source provenance across the projection horizon. CAGRs derived from fitted growth curves incorporating telehealth penetration rates, preventive health attitude diffusion indices, and regulatory enforcement intensity proxies. Industry-specific inputs included gummy format adoption velocity and diaspora market expansion coefficients.
Macroeconomic conditions sit as an overlay; deviation in discretionary wellness spending elasticity or raw material harvest yields would shift the trajectory. Forecasts embed assumptions regarding DSHEA enforcement continuity and EMA borderline product classification stability. Cross-checking against Nielsen retail audit data for health store channel performance is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Creatine Market
Sports Nutrition
Middle East and Africa Sports Nutrition Market
Sports Nutrition
China Sports Drink Market
Sports Nutrition
Middle East Sports Drinks Market
Sports Nutrition
Sports Supplement Market
Sports Nutrition
United States Sports Drink Market
Sports Nutrition
Brazil Sports Drinks Market
Sports Nutrition
Asia-Pacific Sports Nutrition Market
Sports Nutrition
Brazil Sports Nutrition Market
Sports Nutrition
Medicated Fitness Supplements Market
Sports Nutrition
South America Sports Nutrition Market
Sports Nutrition
North America Protein Based Sports Drinks Market
Sports Nutrition
Branched Chain Amino Acid Supplements Market
Sports Nutrition
Pre-Workout Supplements Market
Sports Nutrition
Sports Nutrition Market
Sports Nutrition
Sports Hydration Market