
 Weight Management Supplements Market | 2026-2036
Weight Management Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Weight Management Supplements Market Insights
China is narrowing its capacity gap in botanical extract processing for weight management actives, with domestic suppliers now serving regional contract manufacturers. Herbalife Nutrition leverages its direct-selling infrastructure across Latin America to sustain recurring revenue from meal replacement programs. Glanbia PLC anchors the premium protein powders segment through specialized whey isolate formulations. Abbott Laboratories competes in the clinical nutrition channel with physician-recommended portfolios.
Weight management supplements comprise formulated ingestible products containing macronutrients, thermogenic compounds, fiber matrices, or micronutrient blends designed to modulate energy balance, satiety signaling, or substrate metabolism, typically manufactured through spray-drying, microencapsulation, or cold-press tableting to preserve bioactive stability. Their primary commercial purpose spans discretionary fitness optimization to medically supervised obesity intervention protocols. Protein powders occupy the largest revenue pool due to cross-over appeal among athletes and aging consumers seeking lean mass retention, while gummies represent the fastest-growing form segment as flavor technology and gelatin-alternative formulations expand adult compliance. Online retail channels capture disproportionate margin expansion through subscription algorithms and influencer-affiliate economics.
The FDA enforces Current Good Manufacturing Practice regulations and adverse event reporting mandates for domestic supplement production, while the EMA and national EU competent authorities coordinate border inspections under the Food Supplements Directive to limit non-compliant slimming product circulation. China's SAMR now requires functional food registration certificates for weight-loss claims, extending approval timelines for imported brands. Stakeholders must monitor evolving substantiation standards for structure-function claims as litigation risk from plaintiff attorneys general escalates across multiple jurisdictions.
Market Dynamics
FDA's New Dietary Ingredient notification requirements are forcing reformulation cycles and compliance investments across the supply base, compressing margins for entrants lacking regulatory infrastructure.
Growth Catalysts
- Protein powder crossover demand:Aging consumers seeking lean mass retention alongside fitness enthusiasts are expanding addressable demand beyond traditional bodybuilding segments.
- SAMR functional food registration:China's tightening certification requirements for weight-loss claims are legitimizing premium imported formulations for compliant brands.
- Direct-to-consumer subscription algorithms:Recurring revenue models powered by predictive replenishment are capturing lifetime value from digitally native supplement buyers.
Market Restraints
- Whey protein concentrate price volatility:Dairy commodity swings tied to New Zealand and EU milk production cycles destabilize input cost forecasting for powder manufacturers.
- Botanical extract supply concentration:Green tea catechin and forskolin raw material processing clusters in China's Zhejiang and Yunnan provinces create single-source vulnerability.
- Bioactive stability limitations:Thermogenic compounds degrade under standard spray-drying temperatures, forcing expensive microencapsulation or cold-press alternatives.
Strategic Opportunities
- Underpenetrated Southeast Asia:Indonesia, Vietnam, and Philippines present whitespace for meal replacement programs as urbanization accelerates and disposable incomes rise.
- Personalized nutrition convergence:Integration of microbiome testing with AI-driven supplement stacking protocols opens subscription stickiness beyond generic formulations.
- EMA border inspection harmonization:Coordinated EU enforcement against non-compliant slimming products creates shelf space for certified entrants meeting Food Supplements Directive standards.
Industry Challenges
- Structure-function claim substantiation expertise:Plaintiff attorneys general escalation across multiple US state jurisdictions demands specialized legal and clinical trial capabilities few mid-tier brands possess.
- Adverse event reporting infrastructure:FDA-mandated Serious Adverse Event reporting systems require pharmacovigilance investments that strain emerging brand operational budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weight Management Supplements Market |
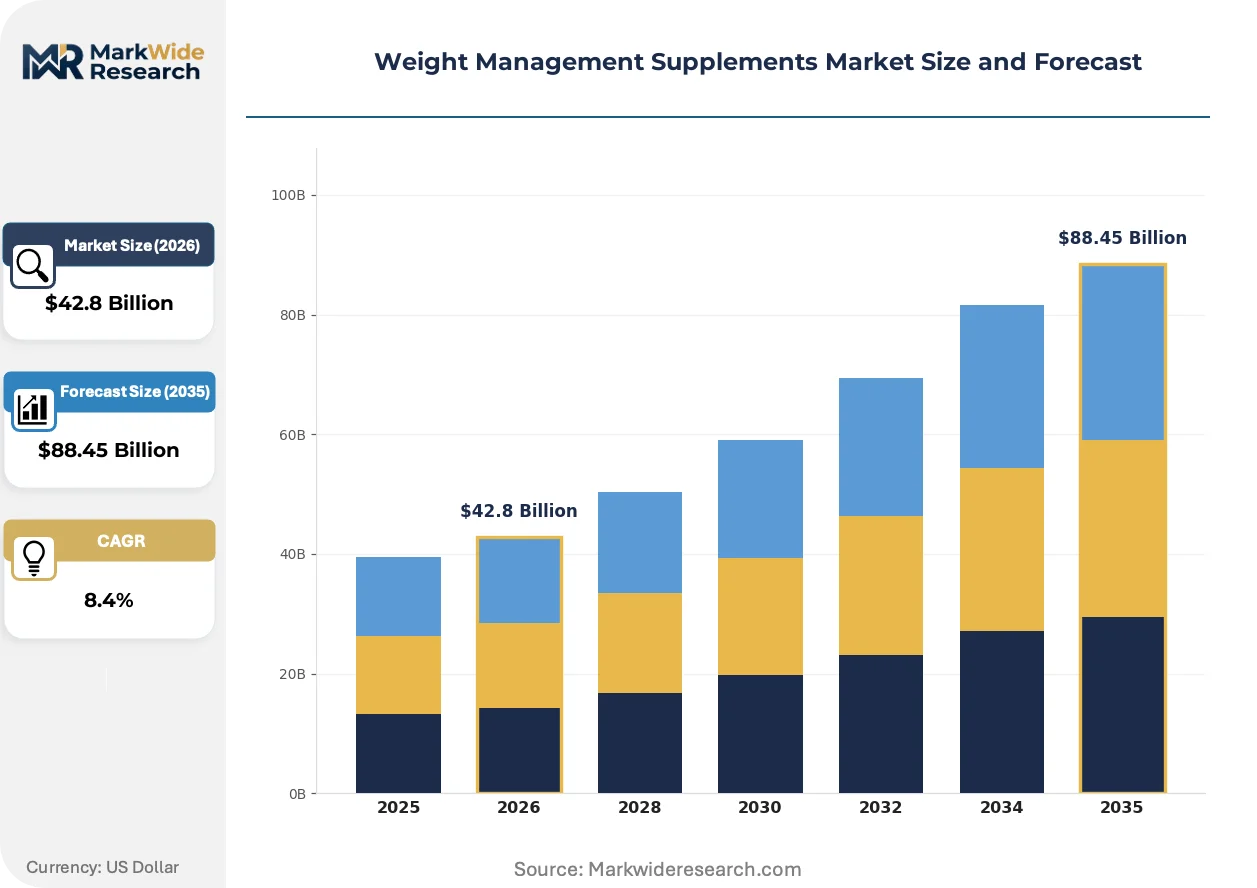
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $88.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Powders, Fat Burners, Meal Replacements, Appetizers Form: Pills, Powders, Gummies, Liquids End User: Fitness Enthusiasts, Health-Conscious Consumers, Athletes, Dieters Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Herbalife Nutrition, Glanbia PLC, Abbott Laboratories, Amway Corporation, Nestle Health Science, GNC Holdings, GlaxoSmithKline PLC, Ajinomoto Co. Inc., Nutrisystem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weight Management Supplements Market Trends and Innovations
Formulation science and distribution architecture are undergoing parallel compression, with bioactive delivery technologies and algorithmic commerce rewriting competitive thresholds.
Microencapsulation via lipid-shell and complex-carbohydrate matrices is collapsing the stability gap between thermogenic actives and conventional powder processing. Contract manufacturers serving sports nutrition brands are retrofitting spray-dry lines with fluid-bed coating systems at accelerating rates. This capability expansion is collapsing premium pricing for shelf-stable green tea extract and capsaicin formulations previously requiring refrigerated logistics.
REACH registration requirements for novel botanical isolates are tightening substance dossier standards for European market entry. ECHA's cumulative assessment protocols now demand toxicological profiles that extend approval timelines for imported actives. Powder and gummy manufacturers targeting Germany and France are responding by pre-subscribing consortium registrations for shared botanical safety data.
Healthcare practitioner channels are unbundling from traditional pharmacy distribution as telehealth platforms integrate supplement recommendations into obesity management protocols. Physician-recommended portfolios are displacing discretionary retail purchases in clinically supervised weight loss verticals. This channel migration is most visible in United States Medicare Advantage networks and United Kingdom NHS pilot programs for metabolic syndrome intervention.
Weight Management Supplements Market Segmentation
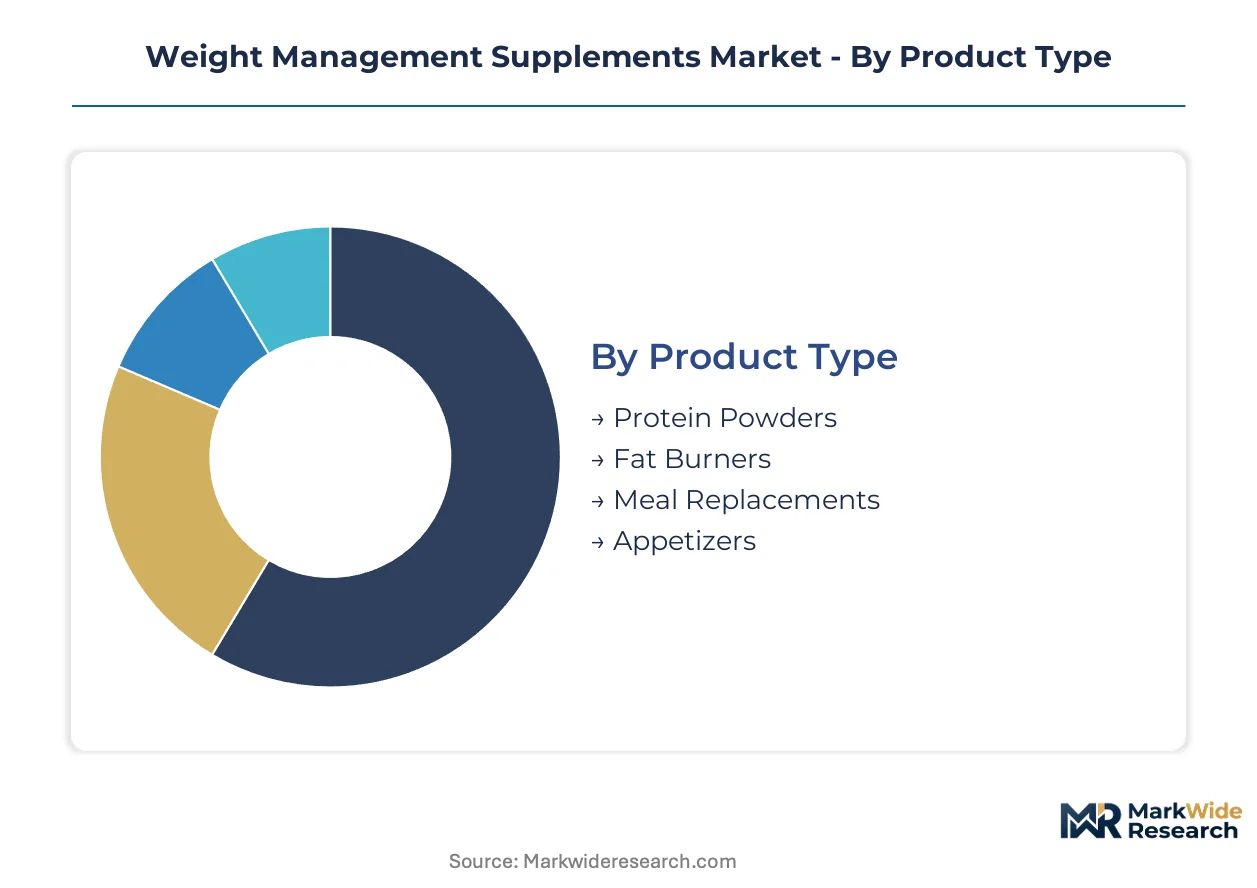
Segmentation in weight management supplements reveals divergent margin profiles and loyalty mechanics across consumption contexts. Product form and channel selection determine replenishment frequency, while end-user motivation shapes price elasticity and brand switching costs.
Product Type:
After-sales service intensity varies sharply across product categories, with meal replacement programs requiring nutritional counseling infrastructure and subscription management capabilities that powder brands rarely maintain.
- Protein Powders:Formulated from whey isolate, casein, or plant-based matrices with standardized amino acid profiles. Demand concentrates among aging consumers in the United States seeking lean mass retention alongside fitness enthusiasts, with crossover appeal stabilizing volume against seasonal gym enrollment cycles. Protein powders hold the largest share; momentum sits with meal replacements.
- Meal Replacements:Complete macronutrient formulations delivering controlled caloric density with vitamin and mineral fortification. Direct-to-consumer subscription models in the United States capture recurring revenue through predictive replenishment algorithms, though compliance rates depend on flavor technology investment and coaching support.
- Fat Burners:Thermogenic and lipolytic actives including green tea catechins, capsaicinoids, and forskolin requiring microencapsulation for stability.
- Appetizers:Satiety-inducing fiber matrices and gastric bulking agents positioned as pre-meal consumption rituals.
Protein powders command the largest revenue pool due to cross-demographic penetration; meal replacements are expanding most quickly through subscription economics.
Form:
Manufacturing capital requirements and shelf-life engineering create distinct competitive moats across delivery formats, with gummy production demanding specialized starch molding and pectin chemistry expertise.
- Powders:Spray-dried or agglomerated formulations permitting high active loading and flavor masking flexibility. Bulk packaging in the United States serves price-sensitive fitness enthusiasts, while single-serve sachets target travel and workplace consumption.
- Gummies:Gelatin or pectin-based matrices with flavor technology overcoming botanical bitterness and thermogenic pungency. Adult compliance in the United States and United Kingdom climbs as gelatin alternatives expand vegan addressability, though moisture sensitivity constrains distribution geography.
- Pills:Compressed tablets and two-piece capsules offering precise dosing and extended-release engineering through polymer coatings.
- Liquids:Ready-to-drink emulsions and concentrates requiring aseptic filling and cold-chain logistics for probiotic or unstable actives.
Powders retain volume leadership through manufacturing scale; gummies post the steepest expansion trajectory as flavor technology matures.
End User:
Customer lifetime value calculations diverge fundamentally across motivation profiles, with clinically supervised dieters exhibiting higher retention but lower discretionary spending than self-directed fitness enthusiasts.
- Fitness Enthusiasts:Gym-affiliated consumers pursuing body recomposition and performance optimization. Protein powder stacking with pre-workout and recovery formulations in the United States creates basket expansion opportunities, though brand loyalty fragments across influencer recommendations.
- Health-Conscious Consumers:Preventive wellness seekers prioritizing clean label attributes and third-party certification. United States demand clusters around organic and non-GMO positioning, with willingness-to-pay premiums for transparent supply chain documentation.
- Athletes:Competitive and recreational performers requiring batch-tested formulations with banned substance certification.
- Dieters:Weight-loss motivated consumers spanning discretionary self-management to physician-supervised protocols.
Fitness enthusiasts anchor volume through stacking behavior; health-conscious consumers are gaining share fastest as clean label expectations mainstream.
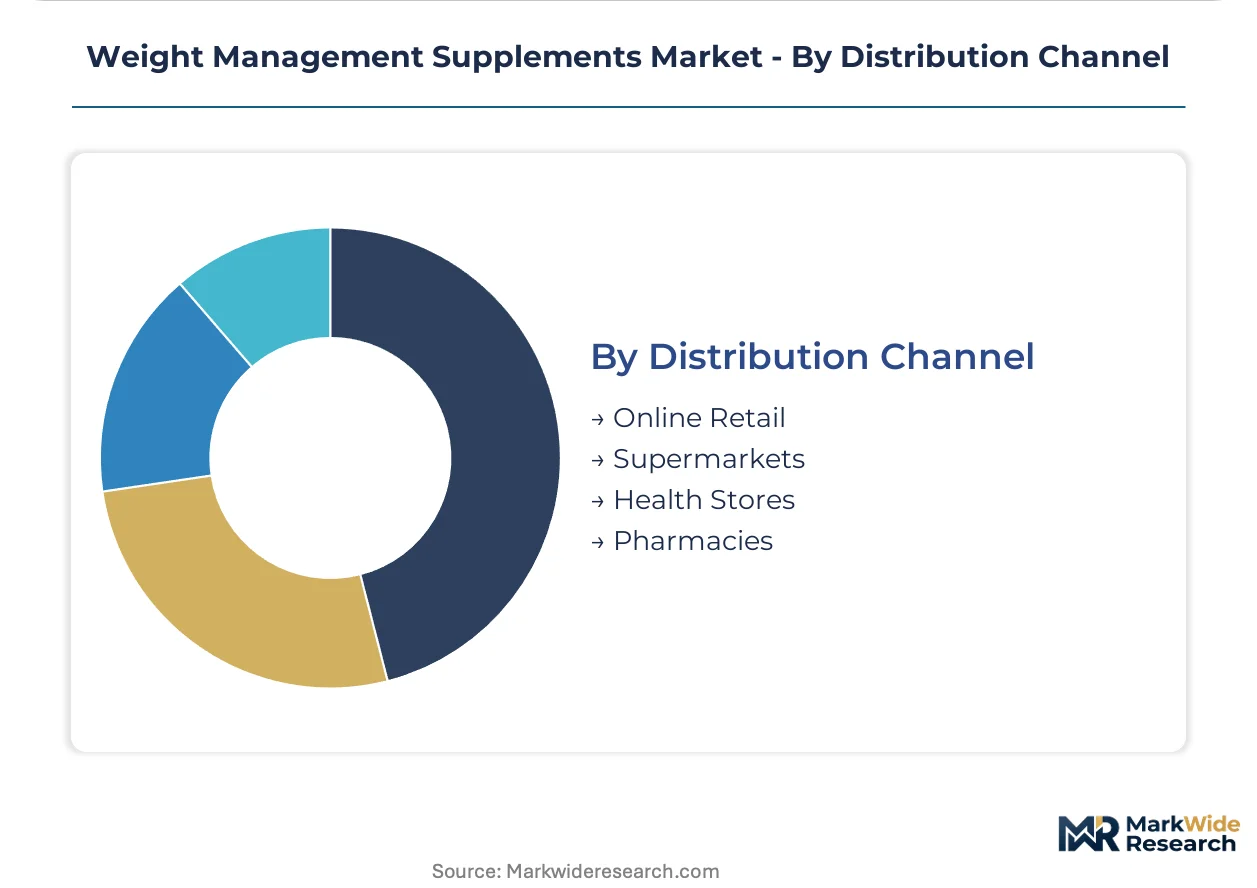
Distribution Channel:
Channel selection determines margin capture and data asset accumulation, with online platforms extracting predictive value from purchase patterns that physical retail cannot replicate.
- Online Retail:Direct-to-consumer and marketplace platforms leveraging subscription algorithms and influencer-affiliate economics. United States operators capture disproportionate lifetime value through predictive replenishment, though customer acquisition costs escalate on saturated social channels.
- Health Stores:Specialized retailers offering educated staff consultation and curated premium assortments. United States and United Kingdom footprints concentrate in urban centers, with staff training investments differentiating against mass-market alternatives.
- Supermarkets:Mass-market shelf space demanding slotting fees and promotional velocity thresholds.
- Pharmacies:Clinically positioned channels with pharmacist recommendation leverage and insurance-adjacent credibility.
Online retail commands the fastest expansion trajectory; health stores retain premium positioning through consultation services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: United States buyers favor subscription-based meal replacements with coaching support, while Asian markets prioritize botanical extracts and functional food positioning under stricter registration regimes.
United States
Direct-to-consumer subscription models dominate channel strategy, with predictive replenishment algorithms capturing lifetime value from digitally native buyers. FDA's New Dietary Ingredient notification requirements reshape product compliance pathways for entrants lacking regulatory infrastructure. Utah and California clusters concentrate contract manufacturing capacity for spray-dried protein formulations.
China
Domestic suppliers narrow the capacity gap in botanical extract processing for weight management actives, serving regional contract manufacturers with green tea catechin and forskolin outputs. SAMR functional food registration certificates now govern weight-loss claims, extending approval timelines for imported brands. Zhejiang and Yunnan provinces anchor raw material processing clusters for thermogenic compound extraction.
Germany
Healthcare practitioner channels unbundle from traditional pharmacy distribution as telehealth platforms integrate supplement recommendations into obesity management protocols. EMA border inspection harmonization under the Food Supplements Directive limits non-compliant slimming product circulation. REACH registration requirements for novel botanical isolates tighten substance dossier standards for market entry.
Brazil
Direct-selling infrastructure sustains recurring revenue from meal replacement programs across Latin American expansion networks. ANVISA governs supplement registration with functional claim substantiation requirements that favor established multinationals. São Paulo state concentrates distribution logistics for regional market penetration.
United Kingdom
NHS pilot programs for metabolic syndrome intervention drive physician-recommended portfolio displacement of discretionary retail purchases. MHRA coordinates with EMA on border enforcement against non-compliant products. London and Southeast England clusters host telehealth platform headquarters integrating supplement recommendations into clinical protocols.
Weight Management Supplements Market Competitive Landscape
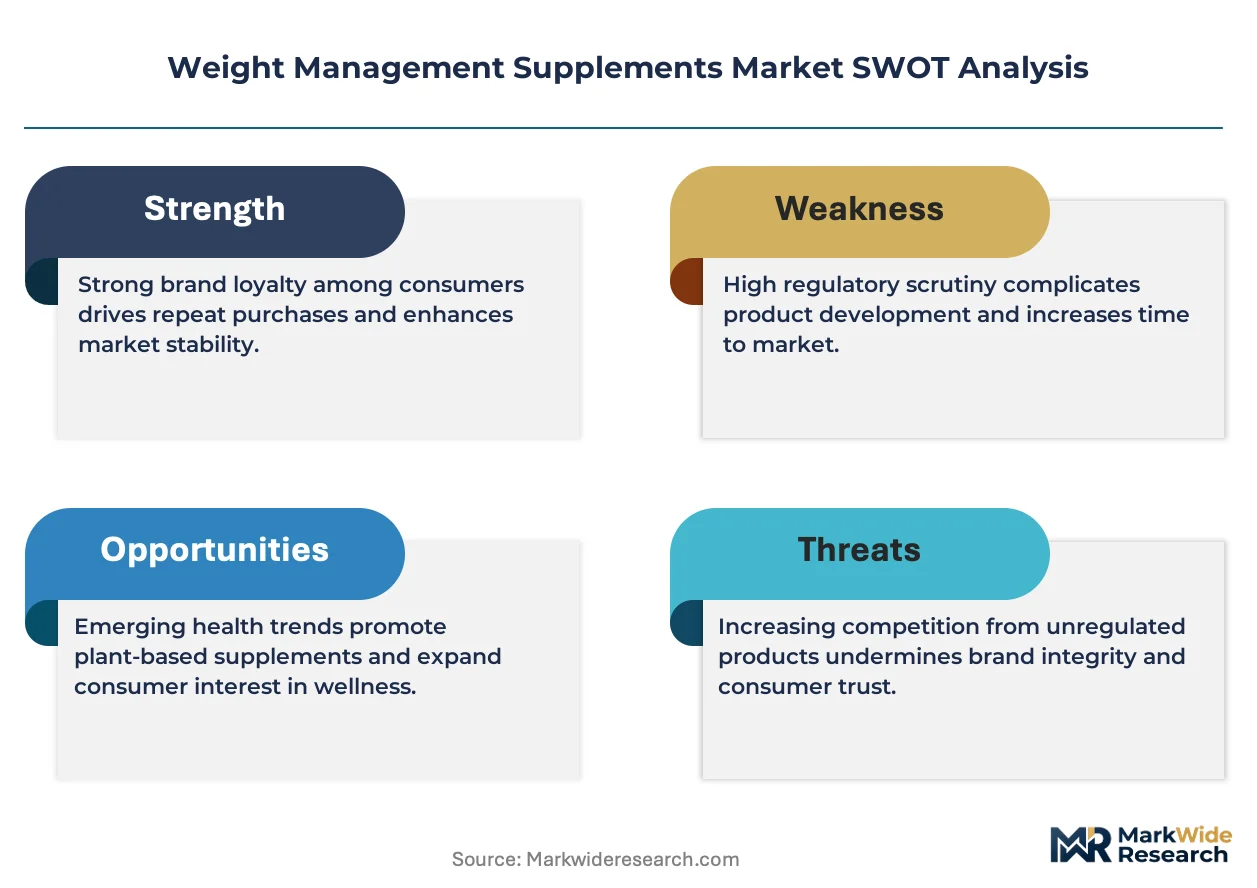
Capability concentration sits with specialized botanical extract processors and microencapsulation technology holders; scale advantage sits with diversified nutrition conglomerates with existing distribution infrastructure. The market structures around three tiers: global nutrition giants with clinical nutrition credentials, direct-selling specialists with recurring revenue engines, and contract manufacturing platforms serving private-label brands. Dominant competitive moves include strategic partnerships with telehealth platforms and geographic licensing arrangements for regulatory-constrained markets.
Within the direct-selling infrastructure tier, Herbalife Nutrition exemplifies recurring revenue capture through meal replacement program adherence. Glanbia PLC anchors the premium protein powders segment through specialized whey isolate formulations. Abbott Laboratories occupies a position bridging clinical nutrition and consumer wellness through physician-recommended portfolio development.
| Leading Market Players |
|---|
| Herbalife Nutrition |
| Glanbia PLC |
| Abbott Laboratories |
| Amway Corporation |
| Nestle Health Science |
| GNC Holdings |
| GlaxoSmithKline PLC |
| Ajinomoto Co. Inc. |
| Nutrisystem |
| Others |
Pricing and Supply Chain Analysis
Pacific container freight corridors from Shanghai to Long Beach transmit cost volatility directly into landed pricing for whey protein concentrates and botanical extracts, compressing margins for brands lacking backward integration into New Zealand dairy cooperatives or Yunnan processing clusters while amplifying price spreads between premium microencapsulated formulations and commodity powder tiers.
Pricing Analysis
Geographic price spreads between United States direct-to-consumer subscriptions and European pharmacy channels exceed forty percent for equivalent whey isolate formulations. Three-tier pricing structure across premium, standard, and economy levels separates physician-recommended portfolios with pharmacovigilance documentation from mass-market powders and private-label alternatives. Pricing pressure stems from whey protein concentrate commodity swings tied to Oceania milk production cycles. Fitness enthusiasts exhibit highest price sensitivity, while clinically supervised dieters accept premium positioning for adherence support.
Supply Chain Analysis
Extended payment terms from sixty to ninety days now dominate contract manufacturer relationships with emerging brands, straining working capital for microencapsulation technology holders. Supply concentrates in China for green tea catechin and forskolin extraction, New Zealand for whey protein isolate, and the United States for spray-drying infrastructure. Raw material dependencies span dairy commodities, gelatin and pectin alternatives, and lipid-shell encapsulation agents. Single-source vulnerability in Zhejiang and Yunnan provinces threatens thermogenic active availability. Distribution runs through direct-to-consumer subscription platforms, health store consultation networks, and pharmacy recommendation channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market structures around regulatory entrenchment as the primary defensive moat, with FDA New Dietary Ingredient notification requirements and SAMR functional food registration certificates creating compliance barriers that incumbent scale advantages reinforce against emerging competitors lacking specialized legal infrastructure.
For Market Incumbents: Build regulatory dossier depth as the core moat by pre-subscribing REACH consortium registrations for novel botanical isolates and securing SAMR certificates ahead of import competitor entry. Capacity addition in Utah and California spray-drying clusters secures powder manufacturing leverage against contract manufacturer pricing power. FDA adverse event reporting infrastructure investments raise operational barriers for mid-tier challengers. For New Entrants and Emerging Players: Establish a beachhead in Southeast Asian meal replacement whitespace, specifically Indonesia and Vietnam where urbanization accelerates and direct-selling infrastructure remains underdeveloped. Indonesia's rising disposable income and limited incumbent penetration offers the most penetrable geography. Telehealth platform partnerships provide go-to-market acceleration without competing for saturated United States social channel acquisition. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified nutrition conglomerates seeking to divest non-core supplement portfolios lacking clinical nutrition credentials. Long-term viability centers on subscription algorithm capabilities and microencapsulation technology ownership rather than brand equity alone. Watch FDA enforcement escalation against structure-function claim litigation as the inflection signal for regulatory compliance premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Acquisition | Cold-press and fluid-bed coating capabilities collapse stability premiums for thermogenic actives in United States formulations. |
| SAMR Registration Pre-Investment | Early functional food certificate pursuit in China locks shelf space before competitor approval timelines conclude. |
| Telehealth Platform Partnership | Physician recommendation integration into Medicare Advantage networks displaces discretionary retail channel dependence. |
| Southeast Asian Distribution Licensing | Local regulatory expertise in Indonesia and Vietnam accelerates market entry without direct infrastructure buildout. |
| Subscription Algorithm Development | Predictive replenishment models capture lifetime value metrics that traditional retail cannot replicate for meal replacement programs. |
Research Methodology
Operator-level perspectives from brand managers at direct-to-consumer platforms, contract manufacturing executives at spray-drying facilities, regulatory affairs leads navigating FDA and SAMR submissions, and procurement directors at whey protein suppliers anchored the qualitative base. Secondary validation drew from FDA warning letters and New Dietary Ingredient notifications, SAMR functional food registration databases, EMA border inspection reports, and customs trade data for whey concentrate and botanical extract flows. Bottom-up demand modeling across product type, form, end user, and distribution channel segments triangulated against top-down macroeconomic indicators.
Scenario-bracketing around whey protein commodity volatility, regulatory enforcement intensity, and subscription churn dynamics framed the projection horizon. Segmentation dimensions spanned protein powders versus meal replacements versus fat burners, delivery format mechanics, fitness enthusiast versus clinically supervised dieter motivation profiles, and channel economics from algorithmic commerce to pharmacy recommendation. CAGRs derived from segment-level volume buildups adjusted for pricing elasticity and regulatory approval timeline risk across the analysis window. Forecast inputs incorporated spray-drying capacity utilization rates and microencapsulation technology adoption curves.
Sensitivities concentrate around FDA enforcement escalation against structure-function claims, SAMR registration timeline extensions for imported brands, and Oceania dairy production disruptions. Forecasts reflect documented assumptions regarding regulatory pathway stability and commodity input cost trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Brazil Sports Nutrition Market
Sports Nutrition
Middle East Sports Drinks Market
Sports Nutrition
Branched Chain Amino Acid Supplements Market
Sports Nutrition
Sports Supplement Market
Sports Nutrition
Europe Protein Based Sports Drinks Market
Sports Nutrition
Global Ketone Supplements Market
Sports Nutrition
South America Sports Nutrition Market
Sports Nutrition
Asia-Pacific Sports Drink Market
Sports Nutrition
Japan Sports Drink Market
Sports Nutrition
Germany Sports Nutrition Market
Sports Nutrition
Caloric Supplements Market
Sports Nutrition
Energy and Protein Bars Market
Sports Nutrition
Creatine Monohydrate Market
Sports Nutrition
Creatine Market
Sports Nutrition
Sports Nutrition Market
Sports Nutrition
Hydroxymethylbutyrate Supplement Market