
 Middle East Sports Drinks Market | 2026-2036
Middle East Sports Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Sports Drinks Market Insights
SFDA sugar-reduction mandates are recalibrating formulation costs across the Middle East. PepsiCo Inc leverages its regional bottling infrastructure to navigate reformulation requirements efficiently. The Coca-Cola Company sustains distribution dominance through its controlled retail network in Saudi Arabia and the UAE. Gatorade anchors premium positioning via deep health club partnerships across Gulf Cooperation Council markets.
Sports drinks are electrolyte-enhanced beverages containing sodium, potassium, and carbohydrates formulated to replenish fluids and energy during or after physical exertion, typically with osmolality ranging between 270-330 mOsm/kg for isotonic variants. Isotonic formulations dominate volume due to balanced absorption rates suited to average perspiration loss, while organic variants command expanding shelf space as clean-label preferences penetrate Gulf retail. Fitness enthusiasts and athletes represent the deepest end-user margin pools, though online platforms are capturing the fastest volume growth through subscription replenishment models.
SFDA standards, UAE Ministry of Economy labeling requirements, and Saudi Food and Drug Authority excise tax classifications collectively determine product eligibility and cost structures across the region. These frameworks incentivize reformulation toward reduced-sugar profiles while tightening import documentation for functional beverage claims. Stakeholders must monitor evolving Gulf Cooperation Council harmonization talks that could unify standards and reshape competitive access across member states.
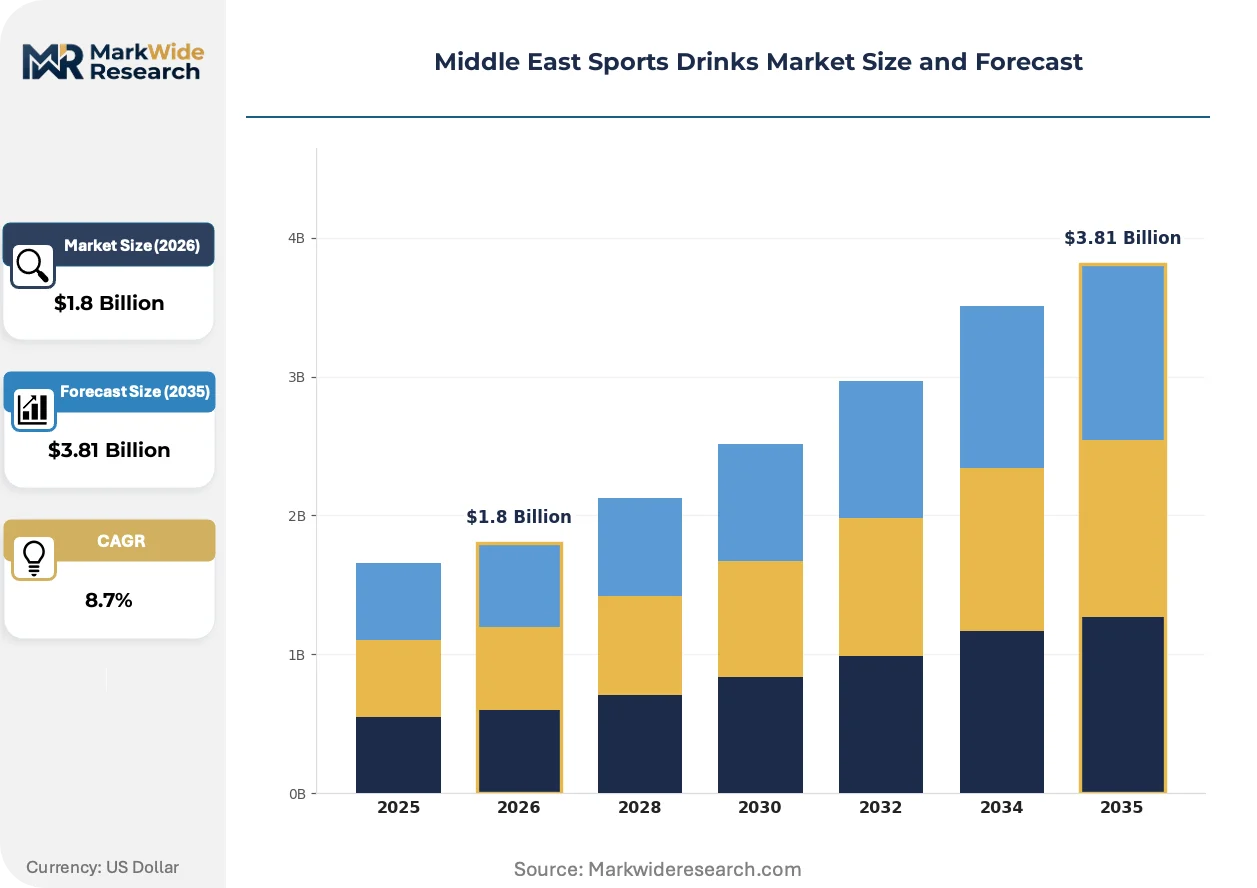
Market Dynamics
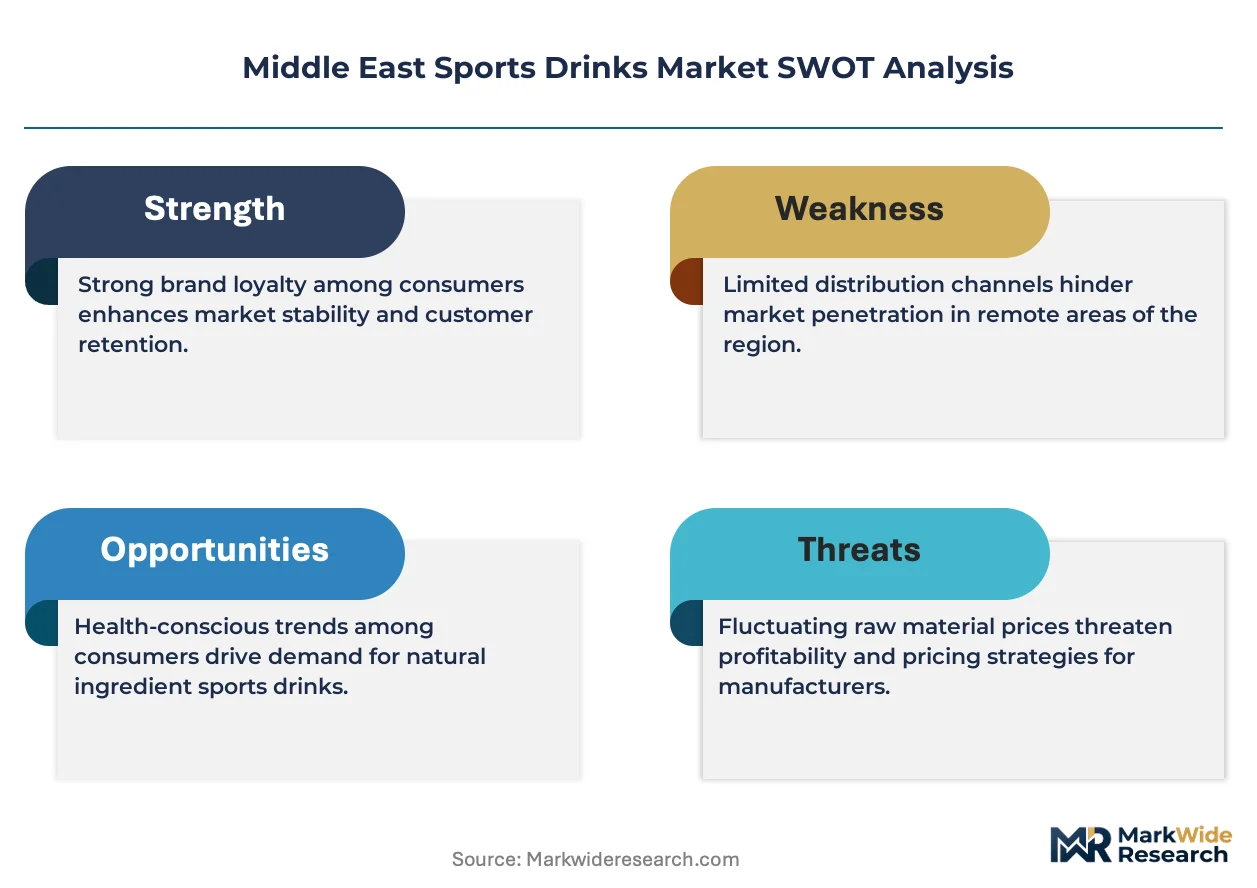
Saudi Arabia's excise tax regime is compressing formulation margins across the Middle East, forcing manufacturers to absorb sugar-tax costs or accelerate low-calorie portfolio transitions while maintaining electrolyte efficacy standards.
Growth Catalysts
- Fitness tourism infrastructure:Dubai's year-round athletic events and health club density sustain premium isotonic consumption volumes unmatched elsewhere in the Gulf Cooperation Council.
- SFDA sugar-reduction mandates:Saudi reformulation requirements are accelerating clean-label innovation cycles as manufacturers compete for shelf space with reduced-sugar functional claims.
- Subscription replenishment models:Online platforms are capturing recurring volume through automated delivery systems targeting gym members and amateur athletes in UAE metropolitan zones.
Market Restraints
- Input cost volatility:Natural flavoring and stevia extract prices fluctuate with agricultural yields, squeezing margin on reformulated low-calorie variants.
- Regulatory friction:Divergent UAE Ministry of Economy labeling requirements and SFDA excise classifications complicate cross-border product standardization.
- Substitution threat:Coconut water and enhanced bottled water variants are displacing volume in price-sensitive convenience channels.
Strategic Opportunities
- Kuwait and Bahrain underpenetration:These markets exhibit lower sports drinks per-capita consumption than UAE or Saudi Arabia, offering whitespace for premium isotonic positioning.
- Clean-label regulatory tailwind:Gulf Cooperation Council harmonization talks could unify organic certification standards, reducing multi-country compliance overhead.
- Direct-to-athlete channel innovation:Team sponsorship and event hydration partnerships bypass traditional retail markup structures.
Industry Challenges
- Reformulation talent scarcity:Food scientists capable of balancing electrolyte osmolality with sugar reduction command premium compensation in Riyadh and Dubai.
- Legacy system integration:Bottling infrastructure designed for high-sugar formulations requires capital retrofitting to handle alternative sweetener viscosity profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Sports Drinks Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isotonic, Hypotonic, Hypertonic, Organic End User: Athletes, Fitness Enthusiasts, Recreational Users, Teams Distribution Channel: Retail Stores, Online Platforms, Health Clubs, Supermarkets Packaging Type: Bottles, Cans, Pouches, Tetra Packs |
| Companies Covered | PepsiCo Inc, The Coca-Cola Company, Otsuka Holdings Co Ltd, Suntory Holdings Limited, Sapporo Holdings Limited, BodyArmor, Powerade, Gatorade, Pokka, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Sports Drinks Market Trends and Innovations
Formulation science and distribution architecture are undergoing parallel transformation across Gulf markets, with regulatory pressure and athlete-centric purchasing patterns as the twin engines of change.
Precision electrolyte dosing technology is decentralizing production planning for regional bottlers. Isotonic customization systems now allow facility-level adjustment of sodium and potassium concentrations to match local climate-induced perspiration profiles. UAE health clubs are piloting on-demand blending stations, compressing the traditional centralized manufacturing-to-shelf cycle.
SFDA sugar taxation is accelerating low-calorie portfolio transitions across Saudi manufacturing facilities. The industrial consequence is a 15-20% reformulation cost inflation absorbed through packaging simplification and volume scale. Reduced-sugar isotonic variants are capturing disproportionate shelf space in Jeddah and Riyadh hypermarkets as retailers preempt compliance deadlines.
Amateur athlete subscription purchasing is displacing impulse convenience-store buying among dedicated fitness participants. Online replenishment platforms are capturing recurring volume through mobile-integrated reordering systems linked to training app usage data. This behavioral shift concentrates most visibly in Dubai's Marina and Downtown districts, where gym density supports same-day delivery economics.
Middle East Sports Drinks Market Segmentation
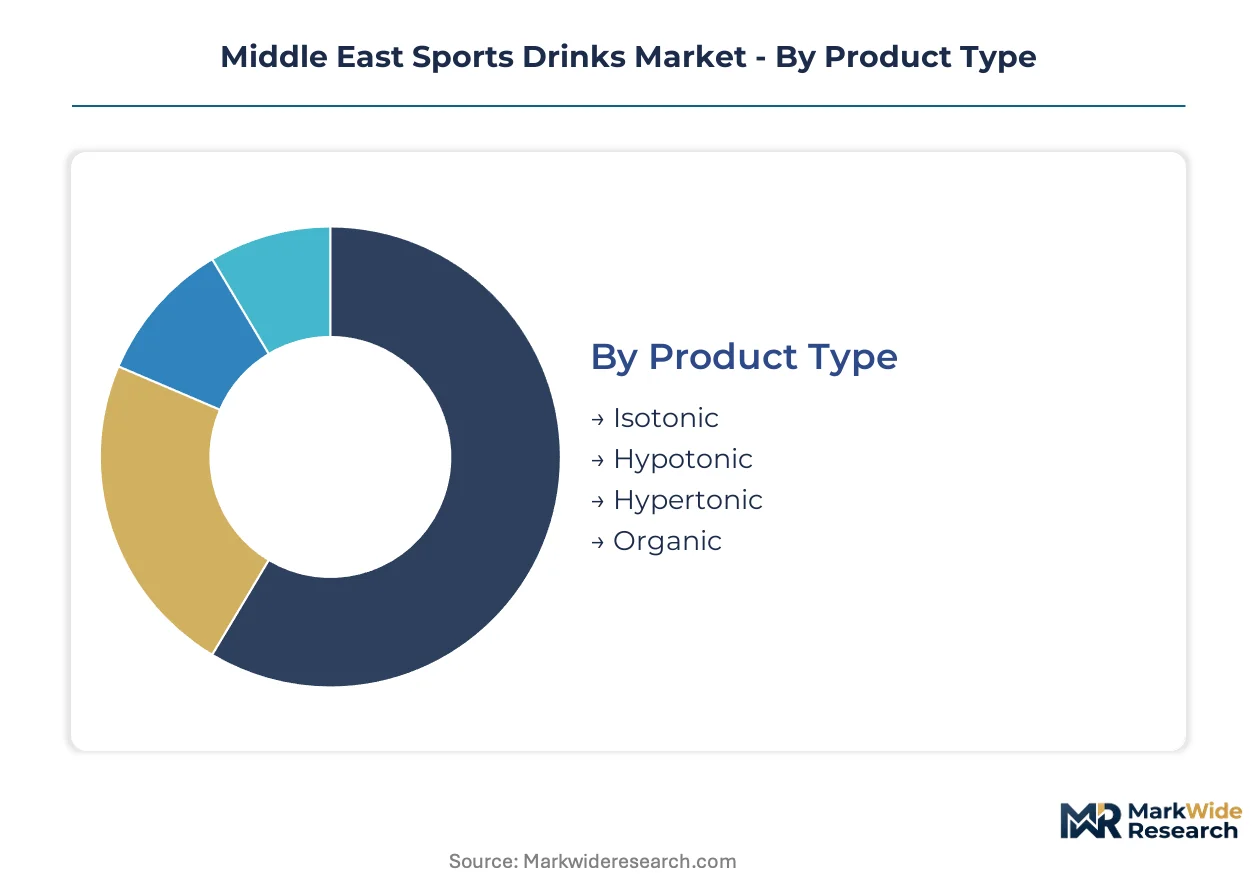
Segmentation in the Middle East sports drinks market reveals how formulation science, channel economics, and regulatory pressure intersect. Each dimension exposes distinct margin structures and compliance burdens that reshape competitive positioning across Gulf Cooperation Council states.
Product Type:
Supply concentration in isotonic manufacturing dominates Saudi bottling corridors, where electrolyte standardization amortizes across the highest volume runs.
- Isotonic:Osmolality balanced between 270-330 mOsm/kg mirrors human plasma for rapid gastric emptying. Dubai health clubs and Jeddah hypermarkets absorb the bulk of regional volume as fitness tourism infrastructure expands.
- Hypotonic:Lower solute concentration accelerates fluid absorption for low-intensity exertion. Recreational users in Bahrain and Kuwait favor these variants where heat stress is moderate and sugar taxation pressures are lighter.
- Hypertonic:High carbohydrate density targets glycogen replenishment post-exertion. Team sports programs in Riyadh and Abu Dhabi represent concentrated demand pockets.
- Organic:Clean-label formulations using natural sweeteners and certified ingredients. UAE Ministry of Economy labeling requirements and MOHAP standards are tightening certification pathways.
Today's leader: Isotonic. Tomorrow's challenger: Organic.
End User:
Margin capture varies sharply by user sophistication, with subscription economics favoring committed participants over casual purchasers.
- Athletes:Competitive performers require precise electrolyte dosing for training blocks. Saudi sports federations and UAE national team programs drive institutional procurement in Riyadh and Abu Dhabi.
- Fitness Enthusiasts:Dedicated gym members with recurring consumption patterns. Dubai Marina and Downtown districts exhibit the densest subscription platform penetration.
- Recreational Users:Occasional consumers responding to impulse availability. Convenience channels in Jeddah and Dammam capture this fragmented demand.
- Teams:Organized sports units purchasing in bulk for training and competition. Kuwaiti football clubs and Omani rugby programs represent expanding institutional accounts.
The deepest margin pools sit with Fitness Enthusiasts. The steepest expansion trajectory belongs to Teams.
Distribution Channel:
Channel fragmentation reflects divergent shopper missions, from immediate thirst relief to planned replenishment cycles.
- Retail Stores:Convenience outlets and petrol station forecourts serving impulse demand. Saudi Arabia's controlled retail network maintains shelf discipline through exclusive bottler arrangements.
- Online Platforms:Subscription replenishment models linked to training app data. Dubai's same-day delivery infrastructure supports automated reordering for gym members.
- Health Clubs:On-premise consumption and post-workout retail. Premium isotonic positioning concentrates in Abu Dhabi and Doha facilities with high member lifetime value.
- Supermarkets:Family-scale purchasing and promotional exposure. Hypermarket chains in Riyadh and Jeddah are reallocating shelf space toward reduced-sugar variants ahead of SFDA compliance deadlines.
Volume gravity centers on Supermarkets. Growth velocity concentrates in Online Platforms.
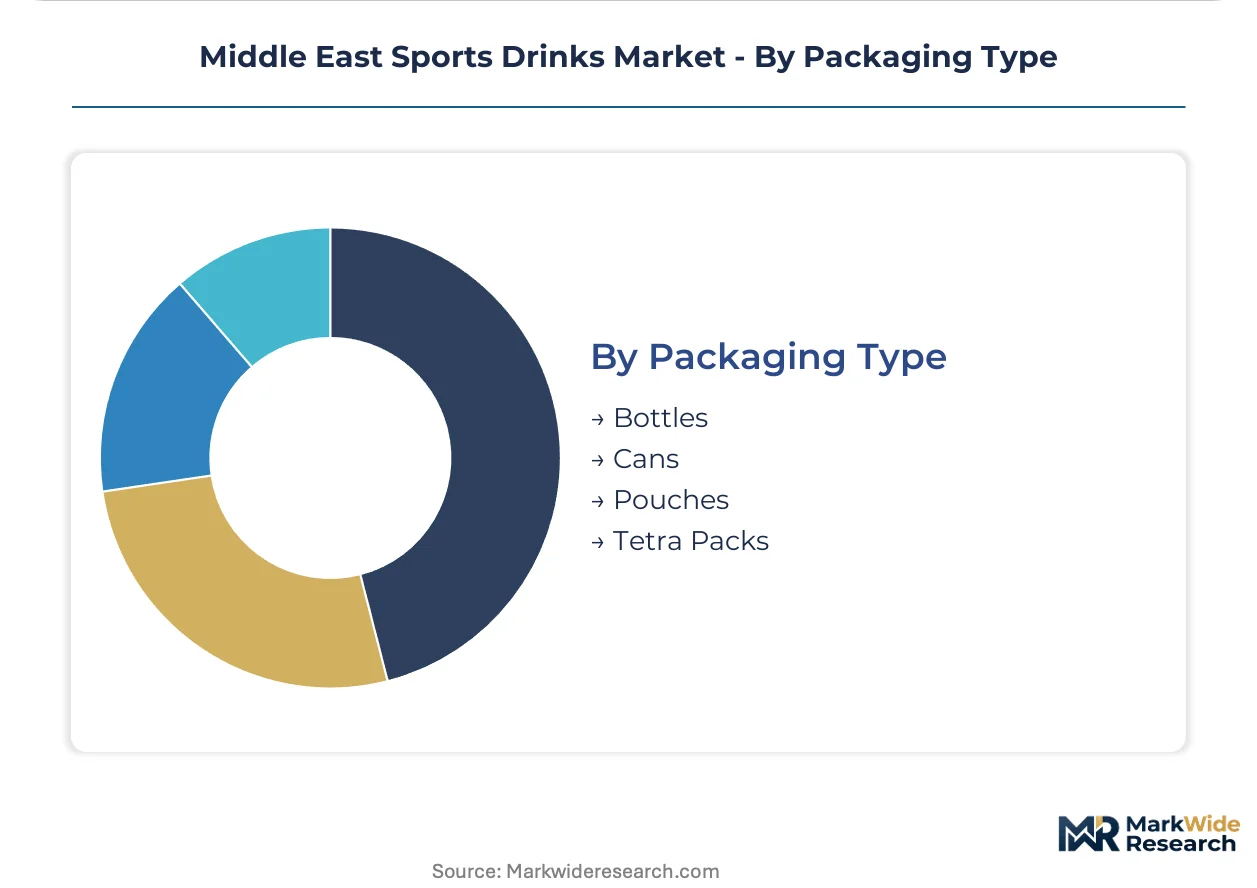
Packaging Type:
Packaging economics trace the tension between portability requirements and sustainability pressures reshaping Gulf retail.
- Bottles:PET and rPET formats dominating single-serve consumption. UAE recycling infrastructure and Saudi sustainability mandates are accelerating lightweighting investments.
- Cans:Aluminum formats favored for outdoor events and stadium environments. Bahrain and Qatar sporting venues drive seasonal demand spikes.
- Pouches:Flexible packaging for youth sports and school channels. MOHAP guidelines on child-targeted beverage marketing constrain placement in Dubai educational settings.
- Tetra Packs:Aseptic cartons for ambient distribution in underserved retail. Omani and Jordanian peripheral markets exhibit modest adoption.
Bottles command current volume. Cans are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sports drinks formulation talent clusters in Riyadh and Dubai, where food scientists command premium compensation to balance electrolyte osmolality with sugar-reduction mandates. This workforce concentration shapes manufacturing investment patterns across Gulf Cooperation Council states.
United Arab Emirates
Dubai's fitness tourism infrastructure and year-round athletic events sustain premium isotonic consumption volumes unmatched elsewhere in the region. MOHAP labeling requirements and UAE Ministry of Economy standards tighten certification pathways for organic variants. Abu Dhabi's health club density supports same-day delivery economics for subscription replenishment platforms.
Saudi Arabia
SFDA sugar-reduction mandates and excise tax classifications are accelerating low-calorie portfolio transitions across domestic manufacturing facilities. The controlled retail network maintains shelf discipline through exclusive bottler arrangements concentrated in Riyadh and Jeddah. Jeddah hypermarkets are reallocating space toward reduced-sugar variants ahead of compliance deadlines.
Qatar
Stadium sporting venues and outdoor event infrastructure drive seasonal demand spikes for aluminum can formats. The country's national food safety regulator enforces labeling requirements aligned with broader Gulf harmonization talks. Doha health clubs with high member lifetime value anchor premium isotonic positioning.
Kuwait
Football clubs and organized sports programs represent expanding institutional accounts for team-scale purchasing. Lower per-capita sports drinks consumption than UAE or Saudi Arabia offers whitespace for market development. Kuwaiti retail channels exhibit lighter sugar taxation pressures supporting recreational user segments.
Bahrain
Moderate heat stress and lighter regulatory burdens favor hypotonic variants among recreational consumers. The island's sporting venues and youth sports channels drive flexible packaging demand constrained by child-targeted beverage marketing guidelines. Manama retail corridors capture impulse convenience-store buying patterns.
Middle East Sports Drinks Market Competitive Landscape
The competitive structure tilts toward multinational beverage conglomerates with regional bottling infrastructure. Two dominant archetypes occupy the landscape: global soft drink majors leveraging controlled distribution networks, and specialized sports nutrition brands building health club partnerships. Competitive moves concentrate on portfolio reformulation for sugar compliance and direct-to-athlete channel innovation bypassing traditional retail markups.
Within the multinational tier, PepsiCo Inc and The Coca-Cola Company exemplify scale-driven market presence through established Gulf bottling operations. Otsuka Holdings Co Ltd occupies a position representing specialized electrolyte formulation expertise. These three anchors demonstrate how regulatory navigation capabilities and distribution infrastructure determine competitive access across Saudi Arabia and UAE markets.
| Leading Market Players |
|---|
| PepsiCo Inc |
| The Coca-Cola Company |
| Otsuka Holdings Co Ltd |
| Suntory Holdings Limited |
| Sapporo Holdings Limited |
| BodyArmor |
| Powerade |
| Gatorade |
| Pokka |
| Others |
Pricing and Supply Chain Analysis
Precision electrolyte dosing technology is compressing production planning cycles while simultaneously fragmenting cost structures across Gulf bottling corridors. This decentralization allows facility-level customization but inflates per-unit formulation expenses as manufacturers balance osmolality standards with sugar-reduction mandates.
Pricing Analysis
Bundled subscription services targeting fitness enthusiasts command premium positioning against unbundled retail impulse purchases. Three-tier pricing structure across premium isotonic, standard hypotonic, and economy private-label levels stratifies by electrolyte precision and certification grade. Pricing pressure stems from SFDA sugar taxation absorbing 15-20% reformulation cost inflation. Recreational users in convenience channels exhibit highest price sensitivity; institutional team buyers show lowest sensitivity due to bulk procurement economics.
Supply Chain Analysis
Direct-to-health-club channels handle premium isotonic demand in Dubai and Abu Dhabi, while controlled retail networks manage volume distribution across Saudi Arabia. Manufacturing concentrates in Saudi Arabia, UAE, and Jordan, with raw material dependencies on stevia extracts from agricultural suppliers, electrolyte compounds from specialty chemical producers, and rPET packaging from regional recyclers. Single-source vulnerability in natural sweetener supply chains threatens margin stability. Distribution runs through exclusive bottler arrangements anchored by multinational beverage conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East sports drinks market functions as a regulatory compounder where SFDA sugar-reduction mandates continuously reshape competitive access and formulation economics.
For Market Incumbents: Lock in health club partnerships and direct-to-athlete channels before subscription platforms consolidate gym member relationships. Defend margin position by accelerating captive supply of stevia-based sweetener alternatives and securing exclusive bottling rights in Saudi Arabia's controlled retail network against emerging clean-label entrants. For New Entrants and Emerging Players: MOHAP organic certification requirements in UAE open a window for premium clean-label positioning in Dubai's fitness tourism corridor. Target underpenetrated team sports procurement in Kuwaiti football clubs and Bahraini youth leagues. Launch through event hydration partnerships bypassing traditional retail markup structures. For Investors and Strategic Acquirers: Roll-up economics work for regional bottlers with SFDA compliance infrastructure because regulatory fragmentation prevents easy cross-border expansion. Five-to-ten year viability hinges on Gulf Cooperation Council harmonization progress. Watch for organic certification standard unification as the inflection signal for scalable acquisition deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Calorie Portfolio Transition | SFDA sugar taxation accelerates reformulation investment to maintain shelf access in Saudi hypermarkets. |
| Subscription Platform Integration | Mobile-linked replenishment systems capture recurring revenue from Dubai Marina fitness enthusiasts. |
| Health Club Partnership Expansion | On-premise positioning in Abu Dhabi facilities secures premium isotonic volume with minimal retail competition. |
| Organic Certification Investment | MOHAP compliance pathways differentiate clean-label variants in UAE's tightening regulatory environment. |
| Team Sports Procurement Targeting | Institutional accounts in Kuwait and Qatar offer whitespace beyond saturated retail channels. |
Research Methodology
Bottom-up fitness enthusiast and athlete consumption modeling reconciled against top-down bottling capacity and retail audit tracking forms the analytical core of this study. Primary interviews with beverage formulation scientists, health club procurement managers, retail category buyers, and SFDA regulatory affairs specialists were cross-validated against secondary sources including SFDA excise tax classifications, UAE Ministry of Economy labeling filings, MOHAP organic certification databases, and Gulf Cooperation Council trade flow records.
Historical consumption trendlines across isotonic, hypotonic, and organic product categories informed projection frameworks segmented by end-user sophistication, distribution channel economics, and packaging format sustainability profiles. CAGRs were derived from electrolyte demand elasticity tied to gym membership growth and climate-induced perspiration patterns throughout the forecast period. Reformulation cost trajectories and subscription platform penetration rates served as industry-specific forecast inputs.
Revisions become necessary when Gulf Cooperation Council harmonization talks accelerate or stall, when stevia supply shocks disrupt natural sweetener availability, or when fitness tourism infrastructure investments in Dubai plateau. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Hydration Products Market
Sports Nutrition
Taurine Supplements Market
Sports Nutrition
United States Weight Management Market
Sports Nutrition
Global Gummy Supplements Market
Sports Nutrition
Asia-Pacific Weight Management Supplement Market
Sports Nutrition
Creatine Monohydrate Market
Sports Nutrition
Europe Weight Management Supplement Market
Sports Nutrition
Caloric Supplements Market
Sports Nutrition
Creatine Supplements Market
Sports Nutrition
B2B Sports Nutrition Market
Sports Nutrition
GLA Supplements Market
Sports Nutrition
North America Sports Nutrition Market
Sports Nutrition
Asia-Pacific Sports Nutrition Market
Sports Nutrition
Middle East and Africa Sports Nutrition Market
Sports Nutrition
Medicated Fitness Supplements Market
Sports Nutrition
Global Sexual Enhancement Supplements Market