
 Marine Collagen Powder Market | 2026-2036
Marine Collagen Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Collagen Powder Market Analytics
The marine collagen powder category is pivoting on a widening split between pharmaceutical-grade hydrolysates and bulk commodity gelatin. Rousselot leverages captive fisheries partnerships in France to secure Atlantic cod skin supply chains. Gelita AG anchors its position through backward integration into sustainable North Sea fishing operations. Vital Proteins LLC differentiates via direct-to-consumer branding that commands premium pricing in specialty retail channels.
Marine collagen powder comprises protein extracted from fish skin, scales, and bones through enzymatic hydrolysis, yielding peptides with molecular weights typically below 10 kDa for enhanced bioavailability. The material serves primarily as a functional ingredient in nutraceutical and cosmeceutical formulations targeting connective tissue support. Hydrolyzed collagen dominates current volume flows due to its neutral flavor profile and rapid dissolution properties, while collagen peptides capture expanding margin pools in clinical nutrition applications. The dietary supplements channel exhibits the steepest trajectory as athletes and beauty enthusiasts shift protein sourcing away from bovine and porcine origins.
Regulatory oversight spans FDA GRAS determinations for food-grade marine collagen, EFSA novel food assessments for non-traditional species sources, and ISO 17025 testing protocols for heavy metal contamination in ocean-derived inputs. These frameworks elevate compliance costs for new entrants while rewarding established operators with certified quality management systems. Stakeholders must monitor evolving marine stewardship certifications and traceability mandates as retail buyers increasingly predicate procurement decisions on verifiable sustainability credentials.
Market Dynamics
Marine collagen powder supply chains face acute pressure from the EU's Novel Food regulation, which reclassifies non-traditional fish species sources and forces reformulators to rebuild dossiers for clinical-grade peptide approvals.
Growth Catalysts
- EFSA Novel Food Pathway:Streamlined safety assessments for enzymatic hydrolysates accelerate ingredient approvals across German and French nutraceutical markets.
- Sports Nutrition Pivot:Athletes in Japan and the United States actively substitute marine peptides for bovine isolates due to religious dietary restrictions and digestibility claims.
- Cosmeceutical Formulation:Korean beauty manufacturers integrate low-molecular-weight collagen into topical serums, creating dual-use demand for powder inputs.
Market Restraints
- Raw Material Volatility:Atlantic cod skin prices fluctuate with Norwegian fishing quotas, compressing margin predictability for hydrolysate producers.
- Species Concentration Risk:Over 60% of pharmaceutical-grade supply depends on North Sea wild-catch operations vulnerable to warming-induced stock migration.
- Religious Substitution:Halal-certified bovine collagen from Brazilian operations competes aggressively in Middle Eastern personal care markets.
Strategic Opportunities
- Indian Dietary Supplement Channel:FSSAI's streamlined protein import classifications open direct-to-consumer positioning for marine peptide brands.
- Regenerative Medicine Convergence:3D bioprinting scaffold applications pair marine collagen with synthetic polymer matrices in tissue engineering trials.
- Australian Aquaculture Partnerships:Farmed barramundi operations in Queensland offer traceable, certified-sustainable alternatives to wild-catch dependency.
Industry Challenges
- Peptide Characterization Expertise:Mass spectrometry analysts capable of validating sub-3 kDa molecular weight distributions command premium salaries in Hamburg and Singapore hiring markets.
- ISO 17025 Accreditation Timelines:Heavy metal testing protocol certification for new ocean-derived inputs requires 18-24 month validation cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Collagen Powder Market |
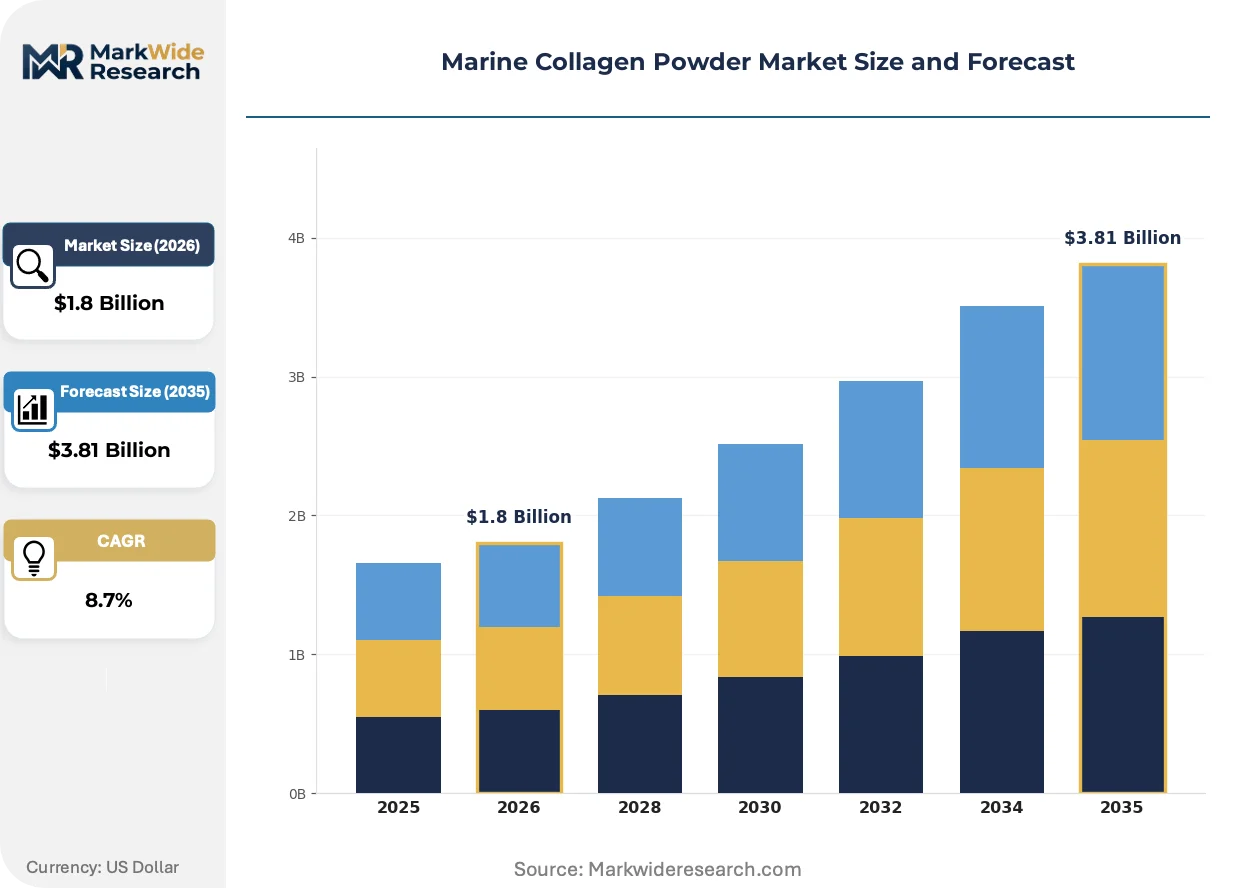
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Gelatin, Collagen Peptides, Collagen Bars Application: Food & Beverages, Nutraceuticals, Cosmetics, Dietary Supplements End User: Athletes, Health-conscious Individuals, Aging Population, Beauty Enthusiasts Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies |
| Companies Covered | Nitta Gelatin Inc., Rousselot, Gelita AG, Ashland Inc., Vital Proteins LLC, Croda International Plc., Collagen Solutions Plc., Weishardt Holding SA, Titan Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Collagen Powder Market Evolving Landscape
Enzymatic hydrolysis protocols and traceability infrastructure are compressing production timelines while elevating quality verification standards across marine collagen value chains.
Continuous-flow enzymatic reactors are automating peptide cleavage processes that previously required batch-wise pH monitoring and manual temperature adjustment. Mid-sized German and Japanese ingredient houses deploy these systems to reduce hydrolysis cycle times from 12 hours to under 4 hours. The capital efficiency gains are automating smaller producers into pharmaceutical-grade supply tiers previously dominated by integrated multinationals.
REACH Annex XVII restrictions on heavy metal thresholds in cosmetic raw materials force reformulators to source exclusively from fisheries with documented catch-location GPS tagging. The compliance burden falls heaviest on bulk commodity gelatin traders lacking vessel-level traceability systems. French and Spanish operators now require Marine Stewardship Council chain-of-custody certification as a baseline procurement filter.
Beauty enthusiasts in Seoul and Los Angeles now verify collagen provenance via QR-coded batch records before purchase, displacing blind brand loyalty. Specialty retailers respond by unbundling bulk powder into single-origin, species-specific SKUs with premium positioning. This pattern concentrates margin capture with vertically integrated producers capable of farm-to-package storytelling.
Marine Collagen Powder Market Segmentation
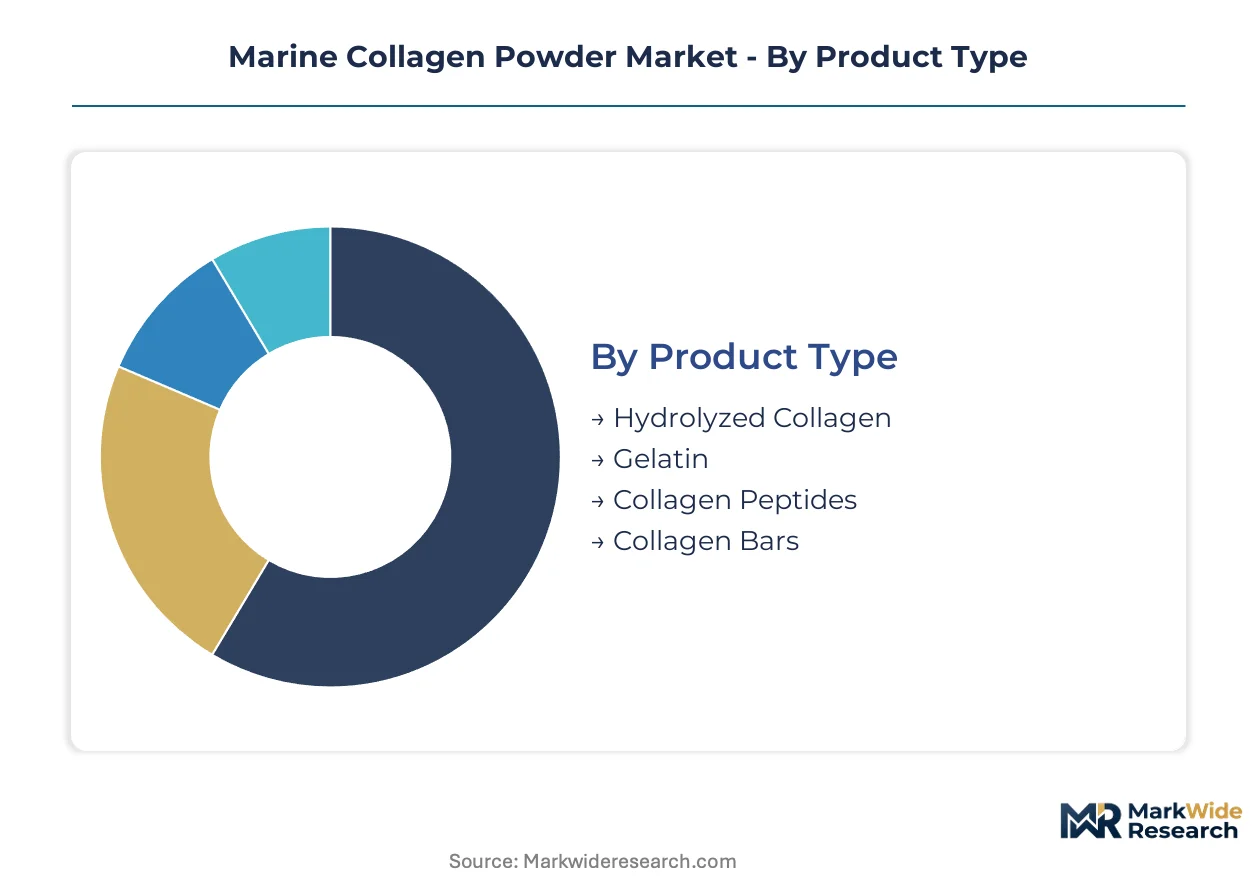
Marine collagen powder segmentation reveals how formulation chemistry and channel access determine margin capture. Product type and application hierarchies stratify value chains from commodity gelatin through clinical-grade peptides.
Product Type:
Customization intensity varies from standardized bulk hydrolysates to precision-engineered peptide fractions with molecular weight specifications.
- Hydrolyzed Collagen:Enzymatically cleaved protein fractions with molecular weights below 10 kDa deliver rapid dissolution and neutral flavor profiles. German and Japanese nutraceutical manufacturers dominate procurement for sports nutrition powders. Neutral taste and instant solubility drive adoption in ready-to-drink formulations where sensory masking costs erode margins.
- Collagen Peptides:Sub-3 kDa bioactive fractions undergo additional filtration and chromatographic separation to concentrate specific amino acid motifs. Korean cosmeceutical houses and clinical nutrition specialists in Switzerland source these for dermal matrix and wound-healing applications. Premium pricing reflects mass spectrometry validation costs and pharmaceutical-grade facility overhead.
- Gelatin:Partial hydrolysis yields gelling agents for confectionery and capsule shells.
- Collagen Bars:Pre-formulated delivery systems combine marine protein with flavor masking and binding agents.
Most installed capacity flows through Hydrolyzed Collagen. Expansion is steepest in Collagen Peptides.
Application:
Cost tiers separate commodity food inputs from premium clinical and beauty applications with certification requirements.
- Dietary Supplements:Powder and capsule formats target protein supplementation with connective tissue claims. Athletes in the United States and beauty enthusiasts in Japan drive volume through direct-to-consumer subscription models. EFSA health claim dossiers and FDA GRAS notifications create regulatory moats against unvalidated competitors.
- Cosmetics:Topical serums and ingestible beauty powders integrate low-molecular-weight fractions for dermal elasticity positioning. Seoul-based manufacturers and Los Angeles indie brands command premium shelf space with species-specific provenance stories. REACH Annex XVII heavy metal thresholds force supply chain restructuring toward GPS-tagged catch documentation.
- Nutraceuticals:Clinical nutrition and functional food positioning requires pharmaceutical-grade manufacturing standards.
- Food & Beverages:Beverage fortification and gummy confectionery utilize cost-optimized hydrolysates with flavor masking.
Volume concentrates in Dietary Supplements. Value per kilogram climbs fastest in Cosmetics.
End User:
Customer maturity spans mass-market protein seekers to sophisticated buyers demanding batch-level traceability verification.
- Athletes:Competitive and recreational sports participants substitute marine peptides for bovine isolates due to digestibility claims and religious dietary accommodation. United States collegiate sports nutrition programs and Japanese endurance communities represent concentrated demand nodes with recurring purchase patterns.
- Aging Population:Joint mobility and skin elasticity positioning targets consumers over 55 in Germany and Japan with disposable income for preventive health spending. Clinical trial citations and physician recommendations outweigh price sensitivity in this segment.
- Health-conscious Individuals:General wellness positioning competes with plant-based alternatives in mass retail.
- Beauty Enthusiasts:Social media-influenced purchasers prioritize aesthetic outcomes and brand storytelling over cost-per-gram metrics.
Recurring subscription revenue concentrates with Athletes. New customer acquisition costs are lowest for Aging Population segments.
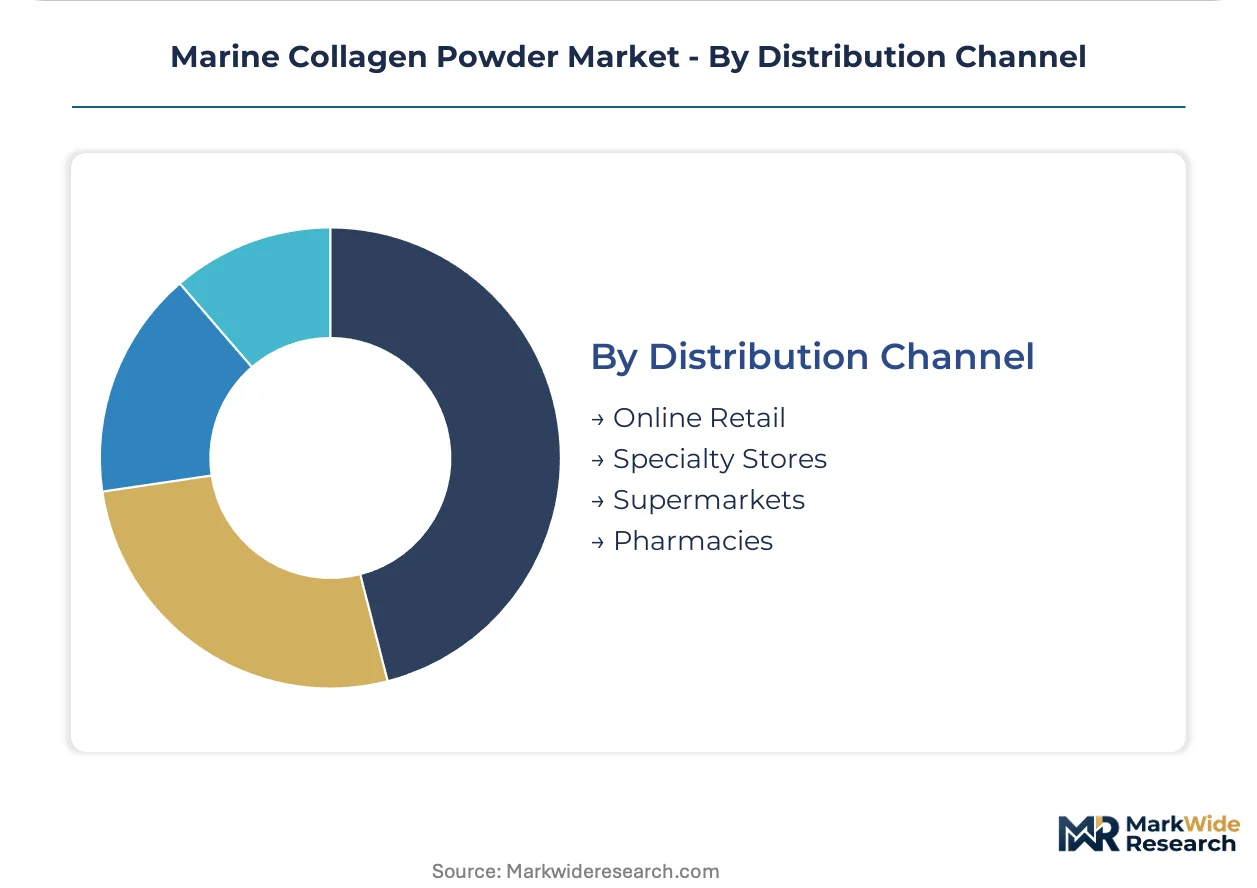
Distribution Channel:
Channel configuration determines margin retention and brand control intensity across the value chain.
- Online Retail:Direct-to-consumer platforms capture first-party data and enable subscription economics. Specialty brands bypass wholesale markups while investing in content marketing and influencer partnerships. German and United States markets show highest digital penetration for marine collagen powders.
- Specialty Stores:Health food and beauty boutiques provide curated discovery environments with educated staff recommendations. Premium positioning justifies species-specific SKUs with QR-coded provenance verification.
- Supermarkets:Mass retail placement requires price competitiveness and broad demographic appeal.
- Pharmacies:Clinical credibility and healthcare professional endorsement drive trust-based purchasing.
Customer lifetime value peaks in Online Retail. Physical channel expansion is accelerating fastest in Specialty Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peptide characterization specialists in Hamburg and Singapore command premium salaries, anchoring quality verification capacity for pharmaceutical-grade supply chains. These talent clusters concentrate near mass spectrometry laboratories serving EFSA novel food dossier preparation and ISO 17025 accreditation workflows.
United States
Collegiate sports nutrition programs and endurance athlete communities drive recurring subscription demand for marine peptide powders. FDA GRAS determinations for food-grade hydrolysates create regulatory moats against unvalidated competitors. Greater Boston hosts contract research organizations validating sub-3 kDa molecular weight distributions for clinical nutrition applications.
Germany
Aging consumers over 55 prioritize joint mobility formulations with physician-backed clinical trial citations. EFSA novel food assessments for enzymatic hydrolysates streamline ingredient approvals across nutraceutical markets. Hamburg anchors mass spectrometry analyst hiring for peptide characterization expertise serving pharmaceutical-grade facility networks.
Japan
Endurance sports communities and beauty enthusiasts converge on direct-to-consumer marine collagen platforms. METI standards for functional food positioning elevate manufacturing overhead for imported hydrolysates. Osaka-based ingredient houses deploy continuous-flow enzymatic reactors to compress hydrolysis cycle times below four hours.
France
Atlantic cod skin supply chains depend on Norwegian fishing quota negotiations for margin predictability. ANSM oversight of cosmetic raw materials enforces REACH Annex XVII heavy metal thresholds with GPS-tagged catch documentation requirements. Rousselot leverages captive fisheries partnerships in coastal processing clusters to secure species-specific inputs.
Australia
Farmed barramundi operations in Queensland offer traceable alternatives to wild-catch dependency for sustainability-conscious buyers. TGA novel ingredient assessments parallel EFSA timelines for clinical-grade peptide approvals. Sydney and Melbourne specialty retailers unbundle bulk powder into single-origin SKUs with QR-coded batch verification.
Marine Collagen Powder Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the marine collagen value chain. Integrated multinationals with captive fisheries partnerships and in-house hydrolysis capacity dominate pharmaceutical-grade supply tiers, while specialty brands outsource production to contract manufacturers and invest in direct-to-consumer content marketing. Three archetypes define competitive positioning: backward-integrated fishing conglomerates with species-specific supply control, asset-light digital-native brands commanding premium pricing through provenance storytelling, and mid-sized enzymatic technology licensors automating smaller producers into higher certification tiers. Dominant competitive moves include strategic partnerships with Marine Stewardship Council-certified fisheries and portfolio diversification into collagen peptide fractions for clinical nutrition applications.
Within the backward-integrated tier, Rousselot and Gelita AG exemplify archetypes of supply chain control through captive fisheries relationships and North Sea fishing operations respectively. Vital Proteins LLC occupies a position as the asset-light digital-native archetype, anchoring premium positioning in specialty retail channels through direct-to-consumer branding rather than manufacturing ownership. These three companies represent the structural split between production gravity and margin capture in the category.
| Leading Market Players |
|---|
| Nitta Gelatin Inc. |
| Rousselot |
| Gelita AG |
| Ashland Inc. |
| Vital Proteins LLC |
| Croda International Plc. |
| Collagen Solutions Plc. |
| Weishardt Holding SA |
| Titan Biotech |
| Others |
Value Network & Pricing Analysis
Mass spectrometry analysts capable of validating sub-3 kDa molecular weight distributions command premium salaries in Hamburg and Singapore, widening spreads between pharmaceutical-grade peptide pricing and commodity hydrolysate tiers. Labor-cost differentials between these specialized talent clusters and standard manufacturing geographies compress margins for mid-tier producers while rewarding integrated operators with in-house peptide characterization laboratories.
Pricing Analysis
Bundled certification-plus-traceability packages separate premium marine collagen positioning from unbundled bulk commodity sales. Three-tier pricing structure across pharmaceutical-grade peptides, food-grade hydrolysates, and industrial gelatin reflects molecular weight thresholds and ISO 17025 accreditation status. Price differentiation hinges on mass spectrometry validation costs and Marine Stewardship Council chain-of-custody documentation. Cost compression in standard hydrolysate tiers intensifies because Brazilian halal-certified bovine collagen competes aggressively for Middle Eastern personal care contracts. Athletes and beauty enthusiasts show lowest price sensitivity, while food and beverage formulators exhibit highest cost-per-gram elasticity.
Supply Chain Analysis
Workforce availability constraints in peptide characterization constrain expansion timelines for German and Japanese enzymatic technology licensors. Supply concentrates in France, Norway, and Japan, where Atlantic cod skin processors and continuous-flow reactor operators anchor pharmaceutical-grade capacity. Raw material flows draw from Norwegian fishing quotas, North Sea wild-catch operations, and Queensland farmed barramundi partnerships. Single-source vulnerability runs through Norwegian quota negotiations that govern Atlantic cod skin availability. Distribution runs through direct-to-consumer platforms, specialty retailers with QR-coded provenance verification, and mass-market wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marine collagen powder market operates as a regulatory compounder, where EFSA novel food assessments and REACH Annex XVII heavy metal thresholds continuously elevate compliance barriers that filter out unvalidated competitors.
For Market Incumbents: Hedge species concentration risk by diversifying into Queensland farmed barramundi partnerships that reduce wild-catch dependency. Secure backward integration into Marine Stewardship Council-certified fisheries before GPS-tagged catch documentation becomes mandatory for cosmetic raw material procurement. Incumbent positioning rests on accelerating ISO 17025 accreditation timelines that delay challenger product launches by 18-24 months. For New Entrants and Emerging Players: FSSAI's streamlined protein import classifications in India open a window for direct-to-consumer marine peptide brands seeking white-space positioning outside saturated North American and European channels. Target beauty enthusiasts in Seoul and Los Angeles with single-origin, species-specific SKUs unbundled from bulk commodity supply. Pursue cosmeceutical formulation partnerships with Korean beauty manufacturers as the most penetrable application segment. For Investors and Strategic Acquirers: Nutraceutical formulators with captive fisheries partnerships are the most active acquirer in this space, seeking enzymatic technology licensors that automate smaller producers into pharmaceutical-grade certification tiers. Long-term viability hinges on traceability infrastructure investments that satisfy evolving retail buyer procurement filters. Watch for Marine Stewardship Council chain-of-custody certification mandates as the inflection indicator that separates investable operators from stranded commodity traders.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Fisheries Partnership | Rousselot's Atlantic cod skin supply control in France secures species-specific inputs against quota volatility. |
| Continuous-Flow Enzymatic Reactor Deployment | Osaka-based ingredient houses compress hydrolysis cycles below four hours, automating into pharmaceutical-grade tiers. |
| Marine Stewardship Council Certification | French and Spanish operators now require chain-of-custody documentation as baseline procurement filter for cosmetic raw materials. |
| Direct-to-Consumer Platform Launch | Vital Proteins LLC captures first-party data and subscription economics through specialty retail channel bypass. |
| Peptide Characterization Laboratory Investment | Hamburg and Singapore talent clusters anchor quality verification capacity for EFSA novel food dossier preparation. |
Research Methodology
Direct dialogue with peptide characterization specialists, enzymatic technology licensors, nutraceutical formulators, and Marine Stewardship Council certification auditors grounded qualitative assessments in operational reality. Secondary validation drew from EFSA novel food submission databases, FDA GRAS determination filings, ISO 17025 accreditation registries, and customs trade data for fish-derived protein imports. Bottom-up capacity assessments and top-down demand modeling triangulated volume and value estimates across the analysis window.
Bottom-up modeling aggregated installed enzymatic hydrolysis capacity by facility certification tier, while top-down approaches tracked dietary supplement channel growth and cosmeceutical formulation demand. Segmentation dimensions included molecular weight classification, application vertical, end-user archetype, and distribution channel configuration. CAGRs derived from regression analysis against protein substitution trends and regulatory approval timelines. Forecast inputs incorporated Norwegian fishing quota negotiations and METI functional food positioning standards.
Revisions become necessary when EFSA novel food pathway streamlining accelerates, REACH Annex XVII thresholds tighten, or marine stewardship certification mandates expand beyond voluntary retail procurement filters. Forecasts reflect documented assumptions about peptide characterization analyst hiring availability and continuous-flow reactor adoption curves. Material deviation in regulatory approval timelines or quota-driven raw material cost spikes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
North America Beta-Glucan Market
Nutritional Supplements
South America Nutraceuticals Market
Nutritional Supplements
Brazil Whey Protein Market
Nutritional Supplements
Nicotine Gum Market
Nutritional Supplements
Austria Protein Supplements Market
Nutritional Supplements
Hangover Cure Products Market
Nutritional Supplements
Eggshell Membrane Powder Market
Nutritional Supplements
Flax Protein Powder Market
Nutritional Supplements
Microencapsulated Fish Oil Market
Nutritional Supplements
Hydroxymethylbutyrate (HMB) Market
Nutritional Supplements
DHA Oil Supplement Market
Nutritional Supplements
Medium-Chain Triglycerides Market
Nutritional Supplements
Asia Pacific Collagen Supplements Market
Nutritional Supplements
Asia Pacific Nutraceuticals Market
Nutritional Supplements
Vegan Collagen Protein Market
Nutritional Supplements
Camu Camu Extract Market