
 Stress Relief Supplements Market | 2026-2036
Stress Relief Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Stress Relief Supplements Market Analytics
Premium clinical-grade certification is bifurcating the stress relief supplements landscape into pharmacy-legitimate and general wellness tiers. Life Extension leverages its physician-education infrastructure to sustain credibility in the clinical channel. NOW Foods anchors the mass-market tier through vertical control over raw material sourcing and manufacturing scale. Herbalife International competes via its direct-sales network, which dominates emerging-market penetration.
Stress relief supplements comprise bioactive formulations targeting cortisol modulation, GABAergic activity, and HPA-axis regulation, typically standardized to marker compounds such as withanolides in ashwagandha or kavalactones in kava extracts. Their primary commercial purpose centers on non-prescription anxiety mitigation and sleep-quality improvement for chronically stressed populations. Herbal extracts occupy the dominant value pool due to consumer preference for plant-derived actives, while gummies represent the fastest-growing formulation segment as taste-masked delivery expands beyond traditional pill-averse demographics. Online retail channels capture disproportionate margin expansion through subscription-based replenishment models.
The FDA's NDI notification requirements and the FTC's substantiation standards for stress claims create a dual compliance threshold that filters smaller entrants from premium positioning. EFSA's health claims regulation in Europe imposes additional evidentiary burdens on adaptogenic marketing, while Australia's TGA maintains a separate complementary medicines framework that permits certain stress indications with lower evidence tiers. Stakeholders must monitor regulatory divergence between jurisdictions to optimize portfolio allocation and label claims strategy.
Market Dynamics
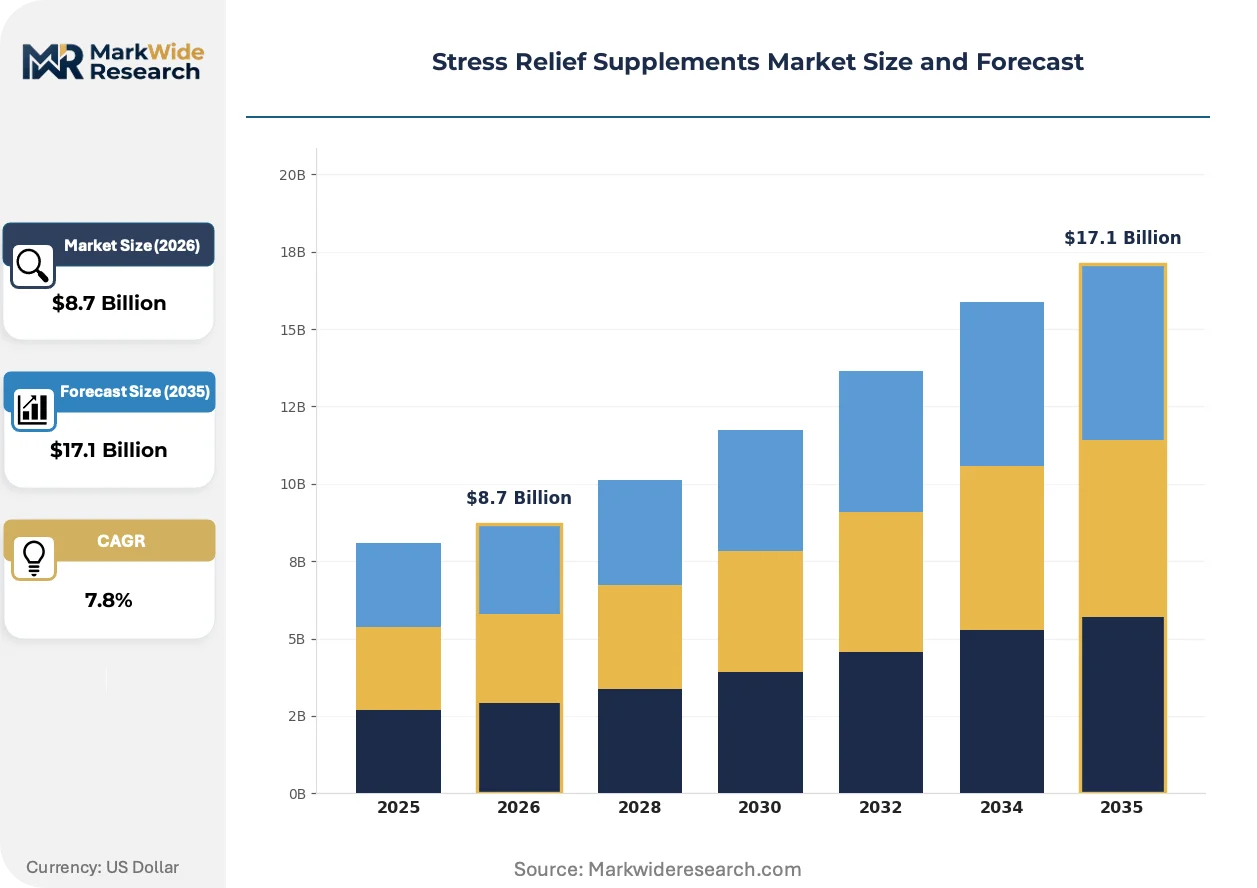
Corporate wellness programs are driving a structural demand surge for adaptogenic and nootropic formulations, while FDA NDI notification requirements are simultaneously raising compliance barriers for new entrants seeking premium positioning.
Growth Catalysts
- Corporate wellness mandates:Large employers across the United States are integrating stress relief supplements into employee benefit packages, creating institutional procurement channels that bypass traditional retail markups.
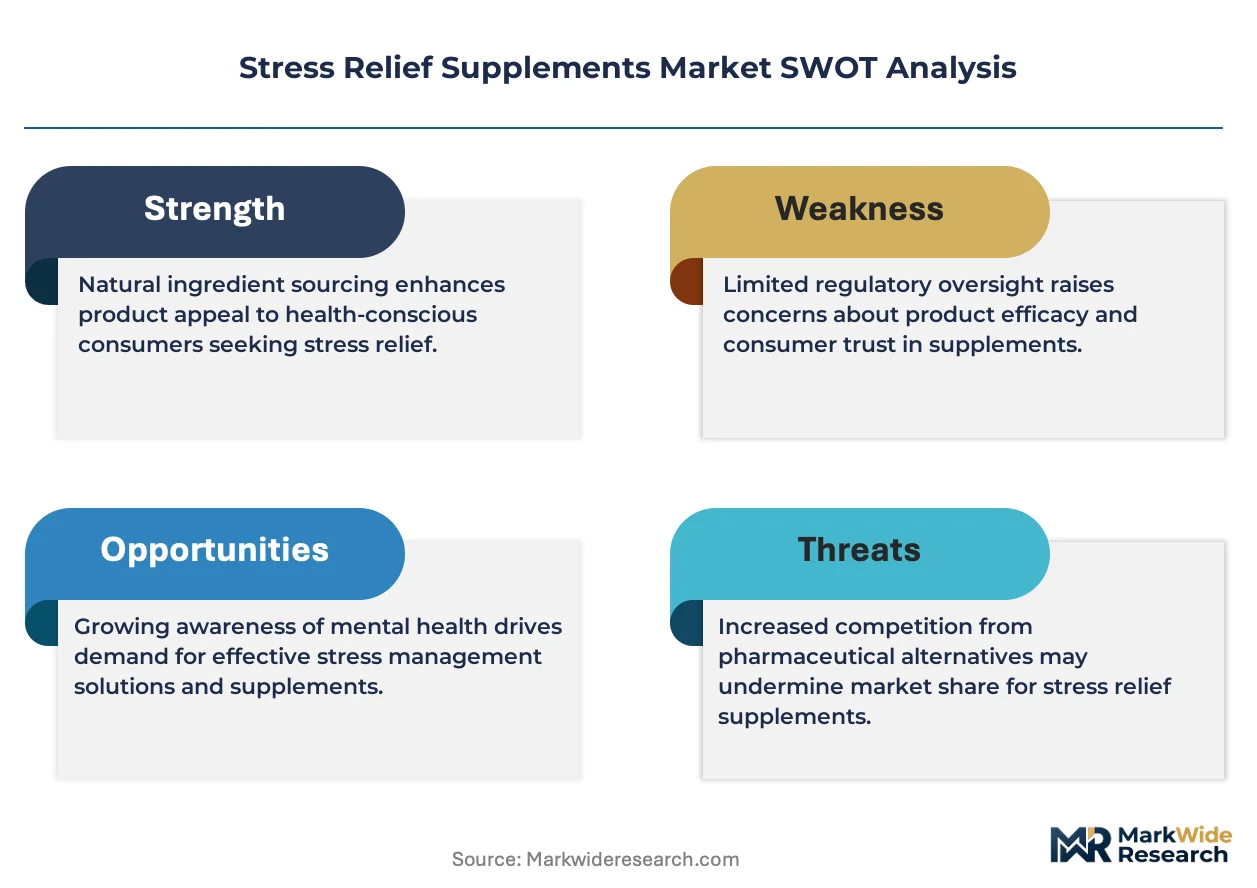
- NDI notification pathways:The FDA's evolving guidance on New Dietary Ingredient safety documentation is clarifying compliance routes for novel botanical extracts, reducing regulatory uncertainty for compliant formulators.
- Ashwagandha cultivation expansion:Indian agricultural cooperatives are scaling KSM-66 and Sensoril raw material output, securing supply continuity for withanolide-standardized extracts.
Market Restraints
- Kava supply concentration:Pacific Island sourcing of noble kava cultivars remains concentrated in Vanuatu and Fiji, exposing processors to climate disruption and export quota volatility.
- EFSA health claims barriers:The European Food Safety Authority's stringent substantiation requirements for adaptogenic marketing block stress-reduction label claims across EU member states.
- Pharmaceutical substitution threat:Prescription anxiolytics and sedative-hypnotics retain reimbursement advantages in employer-sponsored health plans, limiting supplement penetration in severe anxiety segments.
Strategic Opportunities
- Direct-to-consumer subscription models:US-based platforms are capturing recurring revenue through personalized formulation algorithms and automated replenishment logistics.
- TGA complementary medicines pathway:Australia's Therapeutic Goods Administration permits specific stress indications with lower evidence tiers, enabling faster market entry than FDA or EFSA routes.
- Gummy format expansion:Taste-masked delivery systems are converting pill-averse demographics in younger consumer cohorts, opening incremental volume pools beyond traditional capsule users.
Industry Challenges
- Standardized extract verification:Laboratories struggle to validate withanolide and kavalactone content consistency across heterogeneous botanical raw material batches.
- Cross-jurisdictional label compliance:Formulators must maintain parallel claim sets for FDA, EFSA, and TGA requirements, multiplying packaging complexity and inventory segmentation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stress Relief Supplements Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Extracts, Vitamins, Amino Acids, Minerals Formulation: Capsules, Powders, Gummies, Liquid End User: Adults, Elderly, Athletes, Students Distribution Channel: Online Retail, Supermarkets, Pharmacies, Health Stores |
| Companies Covered | Life Extension, ZeinPharma Germany GmbH, Amway Corp., NOW Foods, Vitalife Ltd, Herbalife International, Inc., InnateVitality, Natrol, LLC., HUM Nutrition Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stress Relief Supplements Market Evolving Landscape
Microbiome-targeted delivery systems and synthetic biology-derived actives are disrupting traditional extraction-based manufacturing, while regulatory divergence between FDA, EFSA, and TGA frameworks is forcing portfolio regionalization.
Liposomal encapsulation technology is fragmenting bioavailability benchmarks across the stress relief category. Wellness-focused consumers in direct-to-consumer channels are adopting phospholipid-bound formulations at accelerating rates. This delivery innovation is compressing margins for standard powder-in-capsule products while enabling premium pricing for enhanced-absorption positioning.
The FDA's 2022 NDI guidance update on enzymatically modified botanicals is tightening safety documentation requirements for fermented adaptogen extracts. Contract manufacturers in the United States are investing in expanded toxicology testing capacity to maintain compliance. Smaller formulators lacking in-house regulatory affairs functions are retreating from novel ingredient development toward established GRAS compounds.
Subscription-based replenishment is displacing pharmacy and mass retail as the dominant acquisition channel for chronic stress supplement users. Millennial and Gen-Z cohorts in the United States prefer algorithm-driven personalization over static shelf assortments. This behavioral pivot is concentrating margin capture with vertically integrated platforms that control formulation, fulfillment, and customer data analytics.
Stress Relief Supplements Market Segmentation
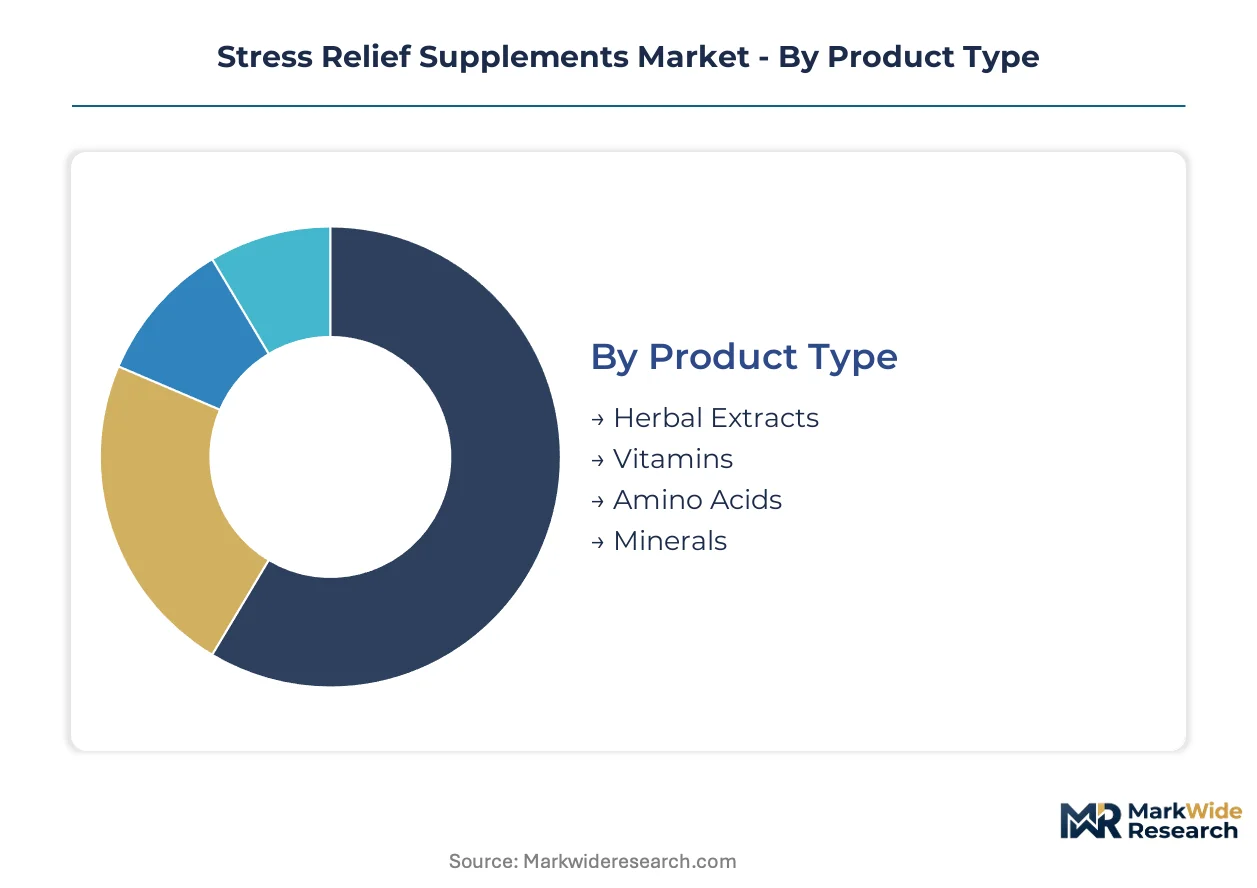
Segmentation in stress relief supplements reflects divergent regulatory tolerances for efficacy claims and delivery format preferences. FDA substantiation standards, EFSA health claim restrictions, and TGA complementary medicines pathways each favor different product architectures and channel strategies.
Product Type:
FDA NDI notifications apply most stringently to novel botanical isolates, while GRAS-designated vitamins and minerals face lower evidentiary barriers for market entry.
- Herbal Extracts:Standardized formulations containing withanolides from ashwagandha or kavalactones from noble kava cultivars dominate pharmacy-legitimate positioning. Demand concentrates in United States direct-to-consumer channels where subscription algorithms match adaptogenic profiles to cortisol biomarker data.
- Vitamins:B-complex and D3 formulations targeting HPA-axis support occupy mass-market shelf space with lower per-unit margins but higher purchase frequency. Corporate wellness programs in United States employer benefit packages drive institutional procurement of vitamin-based stress protocols.
- Amino Acids:L-theanine and GABA precursors serve nootropic-adjacent positioning in performance-oriented demographics.
- Minerals:Magnesium glycinate and zinc formulations target sleep-quality improvement in chronically stressed populations.
Herbal extracts handle the majority of throughput; gummies are expanding most quickly in younger consumer cohorts.
Formulation:
Cost tier differentiation separates premium bioavailability-enhanced delivery from commodity powder formats.
- Gummies:Taste-masked delivery systems convert pill-averse demographics through palatability engineering. United States millennial and Gen-Z subscription platforms capture recurring revenue through gummy-based replenishment models with automated personalization algorithms.
- Capsules:Two-piece hard gelatin and vegetarian shells remain the default for clinical-grade certification and physician-dispensed protocols. Pharmacy retail integration in United States chains favors capsule formats for behind-counter credibility.
- Powders:Bulk actives appeal to stack-customizing consumers and functional beverage co-manufacturers.
- Liquid:Liposomal and emulsion technologies command premium positioning through phospholipid-bound absorption claims.
Capsules handle the majority of throughput; liquid formats are gaining share fastest in wellness-focused direct-to-consumer channels.
End User:
Application-specific dosing protocols and claim substantiation requirements vary sharply across demographic stress profiles.
- Adults:Working-age populations between 25-54 constitute the core volume pool for chronic stress mitigation and sleep-quality products. United States corporate wellness mandates are integrating adult-targeted adaptogens into employee benefit packages with institutional procurement bypassing retail markups.
- Students:Academic performance anxiety and examination stress drive demand for nootropic-adjacent formulations combining L-theanine with caffeine modulators. Campus-adjacent health stores and United States-based subscription platforms target this cohort with algorithm-driven personalization.
- Athletes:Cortisol modulation for recovery protocols faces anti-doping scrutiny and NSF Certified for Sport requirements.
- Elderly:Polypharmacy interaction concerns limit formulation complexity and favor single-ingredient transparency.
Adults handle the majority of throughput; students are climbing the fastest on share through digital-native acquisition channels.
Distribution Channel:
Margin capture and customer data ownership separate vertically integrated platforms from fragmented retail intermediaries.
- Online Retail:Direct-to-consumer subscription models with automated replenishment logistics are displacing pharmacy and mass retail for chronic users. United States platforms control formulation, fulfillment, and analytics to concentrate margin capture.
- Pharmacies:Clinical-grade certification and pharmacist consultation support premium pricing for cortisol-modulating and GABAergic formulations. United States chains integrate stress relief supplements into wellness aisles with behind-counter credibility tiers.
- Supermarkets:Mass-market velocity drives volume for vitamin and mineral-based stress products with lower per-unit margins.
- Health Stores:Specialty retailers cater to ingredient-literate consumers seeking specific standardized extracts and fermented adaptogens.
Online retail handles the majority of throughput; pharmacies are expanding most quickly through wellness aisle integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in botanical raw materials are reshaping manufacturing footprints across major consuming economies. Supply chain resilience investments now favor regional processing hubs over single-source dependencies.
United States
Corporate wellness procurement and direct-to-consumer subscription platforms drive institutional demand for adaptogenic formulations. FDA NDI notification requirements filter novel botanical entrants while clarifying compliance pathways for established GRAS compounds. Utah and California host concentrated contract manufacturing clusters serving pharmacy retail integration and personalized algorithm platforms.
Germany
Pharmacy-dispensed stress protocols and consumer preference for clinical-grade certification sustain premium positioning for herbal extracts. EFSA health claims restrictions block explicit stress-reduction marketing, forcing reformulation toward general wellness positioning. Bavaria and Baden-Württemberg concentrate GMP-certified manufacturing serving EU distribution networks.
China
Domestic demand for traditional adaptogenic ingredients and outbound raw material supply to global formulators create dual market dynamics. NMPA regulatory frameworks for health foods impose distinct substantiation requirements from export-market standards. Shandong and Zhejiang provinces anchor ashwagandha and rhodiola processing capacity expansion.
Australia
TGA complementary medicines pathways permit specific stress indications with lower evidence tiers than FDA or EFSA routes, accelerating market entry for novel formulations. Direct-to-consumer platforms leverage this regulatory arbitrage for Asia-Pacific market development. Melbourne and Sydney clusters specialize in liposomal delivery manufacturing and clinical trial services.
India
Agricultural cooperatives scale KSM-66 and Sensoril raw material output for global withanolide-standardized extract demand. FSSAI labeling requirements and export quality certifications shape processor investment priorities. Karnataka and Maharashtra concentrate cultivation and extraction infrastructure serving North American and European contract manufacturers.
Stress Relief Supplements Market Competitive Landscape
Listed leaders compete with private specialists across formulation credibility and channel access dimensions. The vendor base stratifies into clinical-grade certification holders, mass-market scale operators, and direct-sales network deployers. Three archetypes dominate: physician-education platforms, vertical supply chain controllers, and algorithm-driven subscription platforms. Competitive moves concentrate on pharmacy retail integration and personalized replenishment algorithm development.
Within the clinical credibility tier, Life Extension leverages physician-education infrastructure to sustain pharmacy channel positioning. NOW Foods anchors mass-market scale through captive raw material sourcing and manufacturing verticalization. Herbalife International occupies the direct-sales archetype, deploying network structures for emerging-market penetration. These three represent distinct strategic postures rather than interchangeable competitors.
| Leading Market Players |
|---|
| Life Extension |
| ZeinPharma Germany GmbH |
| Amway Corp. |
| NOW Foods |
| Vitalife Ltd |
| Herbalife International, Inc. |
| InnateVitality |
| Natrol, LLC. |
| HUM Nutrition Inc. |
| Others |
Value Network & Pricing Analysis
FDA NDI notification requirements gate both supplier qualification and price differentiation simultaneously, forcing formulators to absorb toxicology documentation costs that separate pharmacy-legitimate tiers from general wellness positioning. Clinical-grade certification holders command premium positioning through physician-education infrastructure, while mass-market operators compete on captive raw material sourcing economies.
Pricing Analysis
Corporate wellness program buyers anchor a three-tier pricing structure across premium, standard, and economy levels in United States stress relief supplement procurement. Price differentiation stems from clinical-grade certification status and volume scale commitments in institutional contracts. Cost compression in economy tiers is intensifying because Indian agricultural cooperatives are expanding KSM-66 and Sensoril cultivation output. Subscription-based direct-to-consumer platforms exhibit lowest price sensitivity; mass-market supermarket buyers remain most responsive to per-unit discounts.
Supply Chain Analysis
Inventory lead times for noble kava extracts stretch unpredictably due to Pacific Island climate exposure and export quota volatility from Vanuatu and Fiji. Raw material dependencies center on Indian withanolide-standardized ashwagandha, Chinese rhodiola processing capacity, and Pacific Island kavalactone sourcing. Single-source vulnerability concentrates in noble kava cultivar supply. Distribution runs through vertically integrated United States subscription platforms controlling formulation, fulfillment, and customer analytics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA NDI notification pathways creates durable defensive moats for compliant formulators, as toxicology documentation investments block rapid competitive replication. Switching costs accumulate through physician-education infrastructure and personalized algorithm platforms.
For Market Incumbents: Secure pharmacy retail integration through behind-counter credibility tiers and clinical-grade certification maintenance. Expand toxicology testing capacity to defend against novel botanical entrants. Deepen backward integration into Indian KSM-66 and Sensoril cultivation cooperatives to lock supply continuity.
For New Entrants and Emerging Players: Anchor in Australia's TGA complementary medicines pathway where lower evidence tiers permit faster stress indication claims than FDA or EFSA routes. Target gummy format expansion among pill-averse millennial and Gen-Z demographics. Deploy algorithm-driven personalization as primary go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liposomal delivery manufacturing and synthetic biology-derived active production. Five-to-ten year viability favors vertically integrated platforms controlling raw material sourcing through subscription analytics. Acquisition target archetype: mid-cap specialists with TGA regulatory arbitrage capabilities and automated replenishment logistics. Signal to watch: FDA enforcement actions against unsubstantiated adaptogenic stress claims.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical-Grade Certification Investment | Physician-education infrastructure sustains pharmacy channel positioning against mass-market erosion. |
| Backward Integration into Cultivation | Captive KSM-66 and Sensoril supply from Karnataka agricultural cooperatives secures withanolide standardization. |
| Direct-to-Consumer Algorithm Platform | Automated replenishment logistics concentrate margin capture from chronically stressed subscriber cohorts. |
| TGA Regulatory Pathway Entry | Lower evidence tier requirements accelerate novel formulation launches across Asia-Pacific markets. |
| Liposomal Delivery Manufacturing Scale-Up | Phospholipid-bound absorption claims command premium pricing in wellness-focused channels. |
Research Methodology
The analysis maps herbal extract standardization, vitamin-based HPA-axis support, amino acid nootropic positioning, and gummy format delivery systems, each validated through contract manufacturing executives, regulatory affairs specialists, pharmacy retail buyers, and corporate wellness procurement officers. Primary interviews combined with secondary validation from FDA NDI notification databases, EFSA health claims registers, TGA complementary medicines listings, and United States customs import records. Bottom-up volume triangulation against top-down category expenditure estimates anchored projection integrity.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. Segmentation dimensions modeled include product type, formulation format, end-user demographic, and distribution channel structure. CAGRs derived from logistic adoption curves fitted to subscription platform growth trajectories and pharmacy retail integration rates. Industry-specific forecast inputs incorporated ashwagandha cultivation expansion timelines and liposomal encapsulation technology penetration rates.
Material uncertainties — FDA enforcement pattern shifts, Pacific Island climate disruption, EFSA adaptogenic claim liberalization — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory stability and raw material supply continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Human Milk Oligosaccharides (HMO) Market
Nutritional Supplements
Europe Nutraceutical Excipients Market
Nutritional Supplements
Lutein Market
Nutritional Supplements
Middle East and Africa Nutraceutical Excipients Market
Nutritional Supplements
Inflammation Supplements Market
Nutritional Supplements
Europe Collagen Peptides Market
Nutritional Supplements
Pulse Products Market
Nutritional Supplements
Coral Calcium Supplements Market
Nutritional Supplements
GLP-1 Diet Food Market
Nutritional Supplements
US Nutraceuticals Market
Nutritional Supplements
Global Elderly Nutrition Market
Nutritional Supplements
Garlic Extract Supplement Market
Nutritional Supplements
Global Hangover Rehydration Supplements Market
Nutritional Supplements
Asia Pacific Nutraceuticals Market
Nutritional Supplements
Vegan Supplements Market
Nutritional Supplements
Ashwagandha Market