
 Microencapsulated Omega-3 Powders Market | 2026-2036
Microencapsulated Omega-3 Powders Market Size, Share, and Industry Trends Forecast 2026-2036
Microencapsulated Omega-3 Powders Market Foresight
Functional foods is pivoting toward microencapsulated omega-3 powders as beverage and bakery brands seek odor-masked fortification without liquid oil handling. BASF SE leverages its lipid chemistry heritage to supply pharmaceutical-grade EPA/DHA precursors for encapsulation houses. Stepan Company sustains technical service networks across North American food labs, helping customers match powder loadings to shelf-life targets. Glanbia Nutritionals anchors sports nutrition demand by integrating omega-3 powders into protein blends for recovery-positioned products.
Microencapsulated omega-3 powders consist of EPA and DHA fatty acids shielded within wall systems of gelatin, modified starch, or plant proteins, with particle sizes typically engineered between 50 and 200 microns for dry-mix compatibility and oxidative stability exceeding 18 months. These powders enable food and supplement manufacturers to incorporate heart-health and cognitive-function claims into shelf-stable formats without lipid oxidation or sensory degradation. Powders within the product type dimension dominate current volume due to their blending flexibility across infant formula and clinical nutrition, while softgels retain margin concentration in premium pharmaceutical channels. Dietary supplements leads application volume, though functional foods represents the fastest-growing application as CPG brands reformulate legacy products with clean-label omega-3 positioning.
FDA GRAS notifications and EPA facility registration requirements govern U.S. market entry for omega-3 powder ingredients, while EFSA health claim authorizations shape permissible marketing language across European Union member states. Health Canada's Natural and Non-prescription Health Products Directorate imposes additional stability and purity benchmarks for products entering the Canadian market. Stakeholders must monitor evolving novel food consultations in major economies, as regulatory recognition of new encapsulation wall materials will determine which suppliers can access reformulation pipelines.
Market Dynamics
EFSA health claim authorizations and FDA GRAS pathways are bifurcating supplier capabilities, forcing encapsulation houses to maintain dual regulatory dossiers while functional food brands demand shelf-life guarantees exceeding 24 months.
Growth Catalysts
- Clean-label bakery reformulation:German and Dutch baked goods manufacturers are substituting liquid fish oils with odor-masked powders to retain heart-health positioning without process line contamination.
- REACH-compliant wall materials:Modified starches and plant protein matrices meeting ECHA purity standards are unlocking infant formula applications previously restricted to gelatin-based systems.
- Sports nutrition powder integration:Protein blenders in the United States are specifying EPA/DHA loadings above 5% to differentiate recovery-positioned SKUs.
Market Restraints
- Algal oil feedstock volatility:Fermentation-derived DHA precursors face price swings tied to sugar substrate costs and bioreactor capacity constraints.
- Single-source gelatin concentration:Bovine and porcine gelatin supply from the Benelux region creates vulnerability for wall system manufacturers.
- Cross-border novel food friction:Divergent recognition timelines between EFSA and Health Canada delay synchronized product launches.
Strategic Opportunities
- Indian clinical nutrition penetration:FSSAI-compliant omega-3 fortification of medical foods remains underdeveloped relative to supplement saturation.
- Cell-cultured lipid convergence:Precision fermentation EPA is merging with spray-drying advances to enable vegan-certified encapsulation.
- Direct-to-brand e-procurement:Encapsulation houses are bypassing traditional ingredient distributors to serve mid-size functional food startups.
Industry Challenges
- Accelerated stability testing talent:Roxidative shelf-life prediction requires rare expertise in lipid oxidation kinetics and accelerated aging protocols.
- Dual certification capex burden:Simultaneous EFSA novel food and FDA GRAS dossiers demand redundant analytical infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microencapsulated Omega-3 Powders Market |
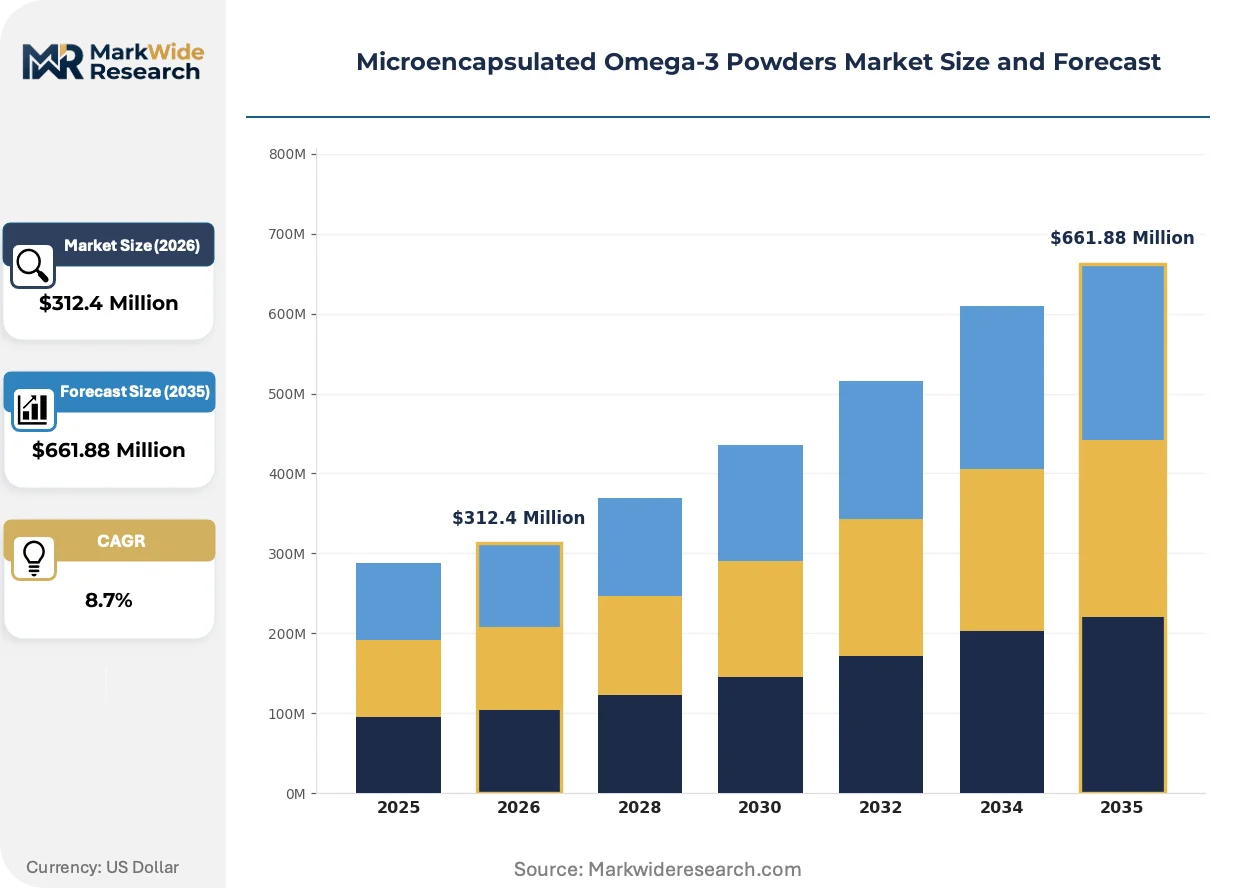
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powders, Softgels, Liquid Emulsions Application: Dietary Supplements, Functional Foods, Pharmaceuticals, Animal Nutrition End User: Health-Conscious Consumers, Athletes, Children, Elderly Population Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies |
| Companies Covered | Wincobel, Stepan Company, Novotech Nutrition, Benexia, Glanbia Nutritionals, KD Pharma Group, Skuny Bioscience Co., Ltd., Clover Corporation, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microencapsulated Omega-3 Powders Market Shifts & Advancements
Encapsulation technology is pivoting from batch spray-drying toward continuous processing architectures that compress manufacturing variability while enabling real-time quality release.
Electrospray encapsulation is automating droplet generation and drying sequences through voltage-controlled atomization, reducing particle size distribution width to under 15 microns. Pharmaceutical compounders in Switzerland and Germany are adopting these systems for medical nutrition applications. The technology is automating quality control checkpoints previously requiring manual microscopy inspection.
EFSA's 2023 updated guidance on oxidative stability markers is compelling suppliers to implement peroxide value and anisidine testing at raw material intake, not just finished powder release. Encapsulation houses serving European infant formula brands are reconfiguring laboratory workflows to meet the tightened analytical burden. German medical nutrition exporters are absorbing the compliance cost to retain EFSA health claim eligibility.
Ingredient procurement is consolidating toward specification-driven contracts where functional food manufacturers demand guaranteed 18-month stability with penalty clauses for oxidation failures. This displaces spot-market purchasing of commodity omega-3 concentrates. Dutch and Danish bakery brands are leading the shift, locking in multi-year supply agreements with encapsulated powder specialists.
Microencapsulated Omega-3 Powders Market Segmentation
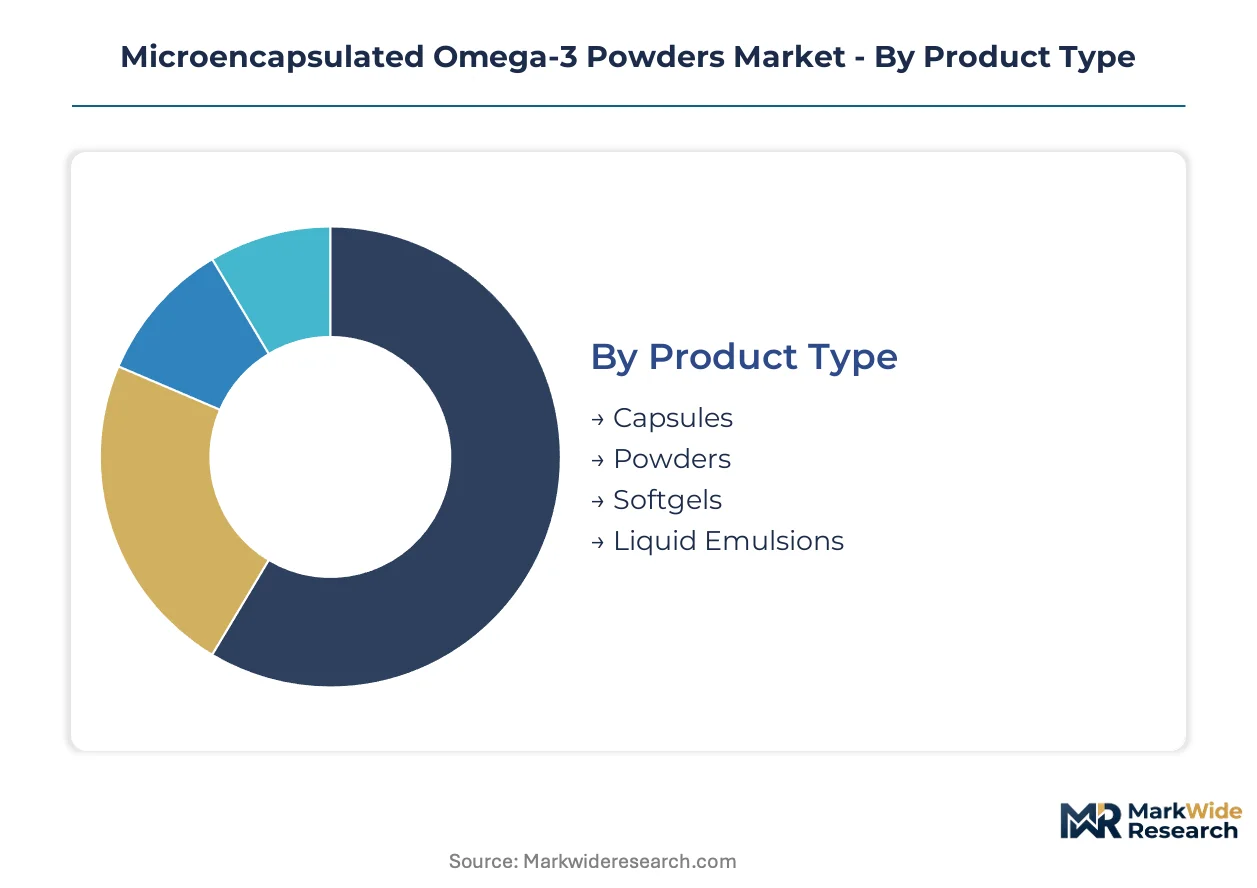
Microencapsulated omega-3 powders serve divergent technical requirements across delivery formats, therapeutic applications, and consumer demographics. Segmentation reveals where capital deployment yields highest returns and which niches resist commoditization.
Product Type:
Capital intensity varies sharply across manufacturing modalities, with encapsulation infrastructure representing the dominant fixed cost barrier.
- Powders:Spray-dried or fluid-bed agglomerated particles with 50-200 micron engineering for dry-mix compatibility. German and Dutch functional food manufacturers drive procurement for bakery and beverage fortification where oxidative stability must exceed 18 months.
- Softgels:Gelatin or plant-based shell encapsulation of oil suspensions, commanding premium positioning in pharmaceutical channels. Swiss medical nutrition compounders specify these for hospital and clinical feeding applications where precise dosing meets regulatory scrutiny.
- Capsules:Two-piece hard shells filled with powder or oil, serving cost-sensitive supplement markets with lower encapsulation equipment thresholds.
- Liquid Emulsions:Oil-in-water dispersions requiring homogenization and stabilization systems, finding niche use in ready-to-drink functional beverages.
Most installed capacity flows through Powders. Expansion is steepest in Softgels.
Application:
Margin structure diverges across end-use channels, with regulatory burden and formulation complexity determining profitability tiers.
- Functional Foods:Bakery, dairy alternative, and beverage fortification requiring odor-masking and heat stability. Clean-label positioning in German retail chains accelerates procurement of modified starch and plant protein wall systems.
- Dietary Supplements:Powder-in-capsule and bulk powder formats for daily omega-3 intake. Sports nutrition blenders in the United States specify EPA/DHA loadings above 5% for recovery-positioned protein SKUs.
- Pharmaceuticals:Medical nutrition and prescription-grade formulations meeting EFSA health claim and FDA GRAS dossier requirements. Infant formula applications demand REACH-compliant wall materials with purity documentation.
- Animal Nutrition:Pet food and livestock feed fortification, currently underdeveloped relative to human applications but attracting algal oil feedstock interest.
Revenue concentration sits with Dietary Supplements. Functional Foods is expanding most quickly.
End User:
Purchasing behavior and price sensitivity segment the addressable market into clinically validated and lifestyle-positioned cohorts.
- Health-Conscious Consumers:Preventive wellness seekers purchasing through online retail and specialty channels, driving clean-label and vegan-certified demand.
- Elderly Population:Cardiovascular and cognitive health positioning in pharmacy and medical nutrition channels, requiring stability data and health claim authorization.
- Athletes:Recovery and inflammation management use cases in sports nutrition, with protein blend integration specifying higher powder loadings.
- Children:Infant formula and pediatric medical nutrition applications, subject to the strictest purity and novel food regulatory requirements.
Volume leadership belongs to Health-Conscious Consumers. Steepest expansion trajectory is in Elderly Population.
Distribution Channel:
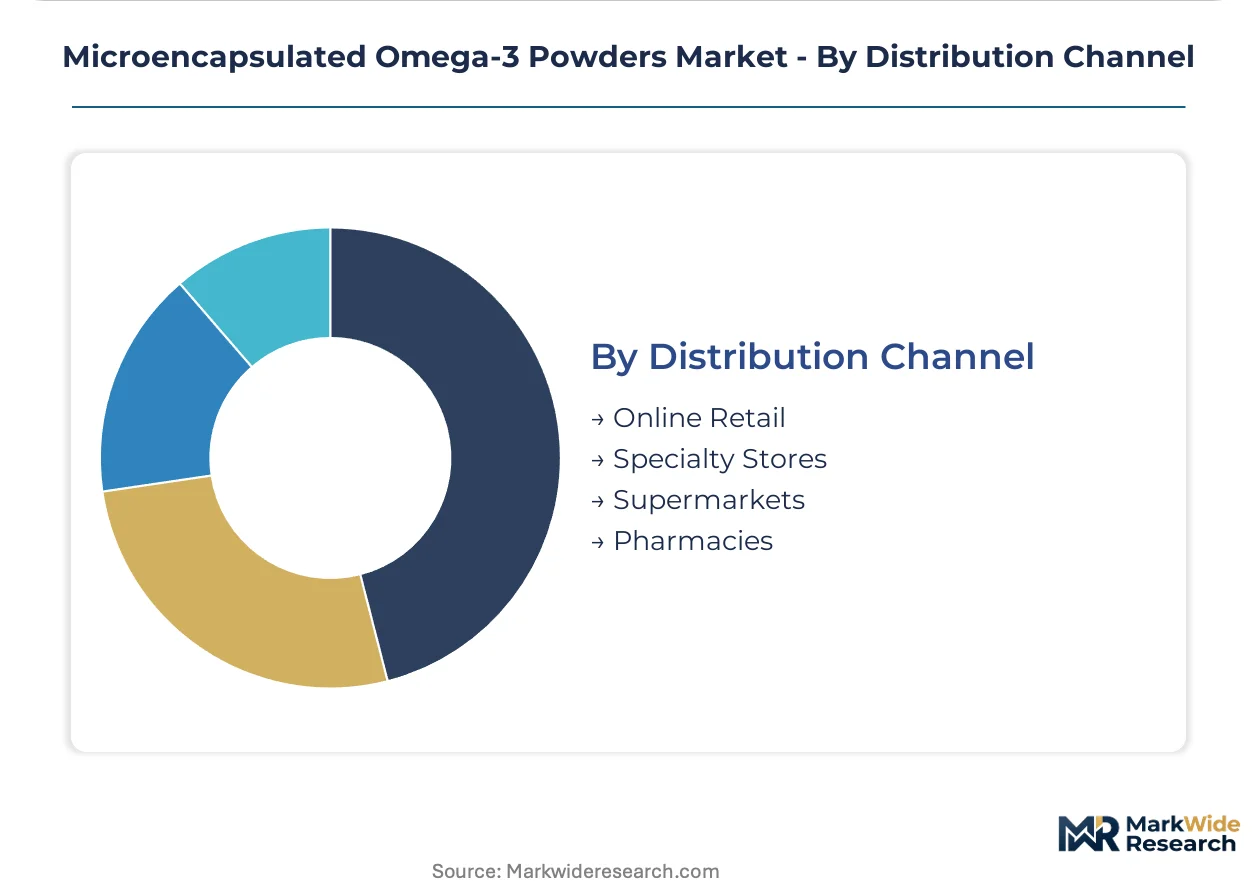
Channel economics determine working capital requirements and customer acquisition cost structures.
- Online Retail:Direct-to-consumer and subscription models for supplement brands, compressing distributor margins while demanding fulfillment infrastructure.
- Pharmacies:Clinical credibility and pharmacist recommendation dependency, requiring health claim authorization and stability documentation.
- Specialty Stores:Sports nutrition and organic retail positioning with educated staff and premium price tolerance.
- Supermarkets:Mass-market functional food placement, requiring scale manufacturing and competitive unit economics.
Most procurement volume moves through Pharmacies. Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as encapsulation houses migrate toward jurisdictions with streamlined novel food pathways and lower analytical compliance costs. Cost-of-compliance gaps between FDA GRAS and EFSA dossier requirements are driving facility placement decisions.
Germany
Pharmaceutical-grade omega-3 ingredient imports serve supplement exporters and medical nutrition compounders concentrated in the Frankfurt-Rhine-Main cluster. EFSA health claim requirements push suppliers toward higher purity documentation and stability testing. BASF SE leverages its Ludwigshafen lipid chemistry heritage to supply EPA/DHA precursors for encapsulation houses across the Benelux border zone.
United States
Sports nutrition blenders specify EPA/DHA loadings above 5% for recovery-positioned protein SKUs, with Stepan Company sustaining technical service networks across North American food labs. FDA GRAS notifications and EPA facility registration requirements govern market entry for omega-3 powder ingredients. California functional food startups drive direct-to-brand e-procurement, bypassing traditional ingredient distributors.
Switzerland
Pharmaceutical compounders in Basel and Zurich adopt electrospray encapsulation systems for medical nutrition applications, automating quality control checkpoints previously requiring manual microscopy inspection. Swissmedic oversight shapes prescription-grade formulation standards. The Lake Geneva corridor anchors precision fermentation EPA convergence with spray-drying advances for vegan-certified encapsulation.
India
FSSAI-compliant omega-3 fortification of medical foods remains underdeveloped relative to supplement saturation, creating penetration opportunities for clinical nutrition suppliers. The country's national food regulator imposes stability and purity benchmarks distinct from Western frameworks. Maharashtra and Gujarat pharmaceutical clusters are absorbing technology transfer for encapsulation wall material production.
Netherlands
Dutch bakery brands lead the shift toward specification-driven contracts demanding guaranteed 18-month stability with penalty clauses for oxidation failures. REACH-compliant modified starches unlock infant formula applications previously restricted to gelatin-based systems. Rotterdam-Antwerp logistics corridors concentrate algal oil feedstock import and toll processing for Northern European encapsulation houses.
Microencapsulated Omega-3 Powders Market Competitive Landscape
Capacity expansion dominates the current landscape as encapsulation houses scale continuous processing architectures to compress manufacturing variability. The supplier base fragments across lipid origin specialists, wall system chemists, and integrated nutrition platforms. Three archetypes occupy distinct positions: fermentation-derived algal oil feedstock controllers, gelatin and modified starch wall material specialists, and sports nutrition integrators. M&A activity concentrates on captive supply of EPA/DHA precursors, while technology licensing spreads electrospray and fluid-bed agglomeration know-how.
Among Germany-based chemical conglomerates, BASF SE anchors the lipid precursor tier with upstream control over pharmaceutical-grade EPA/DHA supply. Stepan Company exemplifies the North American technical service archetype, embedding application scientists within customer food labs to match powder loadings to shelf-life targets. Glanbia Nutritionals occupies the sports nutrition integration position, anchoring demand through omega-3 powder incorporation into protein blends for recovery-positioned SKUs.
| Leading Market Players |
|---|
| Wincobel |
| Stepan Company |
| Novotech Nutrition |
| Benexia |
| Glanbia Nutritionals |
| KD Pharma Group |
| Skuny Bioscience Co., Ltd. |
| Clover Corporation |
| BASF SE |
| Others |
Supply & Pricing Matrix
Encapsulation chemists with lipid oxidation kinetics expertise cluster in the Basel-Zurich corridor and Frankfurt-Rhine-Main region, and this workforce concentration widens pricing spreads between pharmaceutical-grade and commodity powder tiers as labor-cost differentials compound raw material quality gaps.
Pricing Analysis
Distributor margins for omega-3 powders compress as direct-to-brand e-procurement bypasses traditional ingredient channels. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade levels separates EFSA-compliant infant formula suppliers from bakery fortification specialists. Pricing pressure stems from algal oil feedstock volatility tied to fermentation capacity constraints. Sports nutrition blenders exhibit lowest price sensitivity due to premium recovery-positioning, while mass-market bakery brands negotiate aggressively on volume contracts.
Supply Chain Analysis
Algal oil feedstock rests on fermentation capacity concentrated in the United States, Netherlands, and China. Modified starch wall systems draw from Benelux specialty chemical producers, while pharmaceutical-grade gelatin sources cluster in Germany and France. Single-source vulnerability pervades bovine and porcine gelatin supply from the Benelux region. Distribution runs through Rotterdam-Antwerp logistics corridors toll-processing feedstock for Northern European encapsulation houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EFSA's 2023 updated guidance on oxidative stability markers forces suppliers to absorb analytical infrastructure investments to retain health claim eligibility.
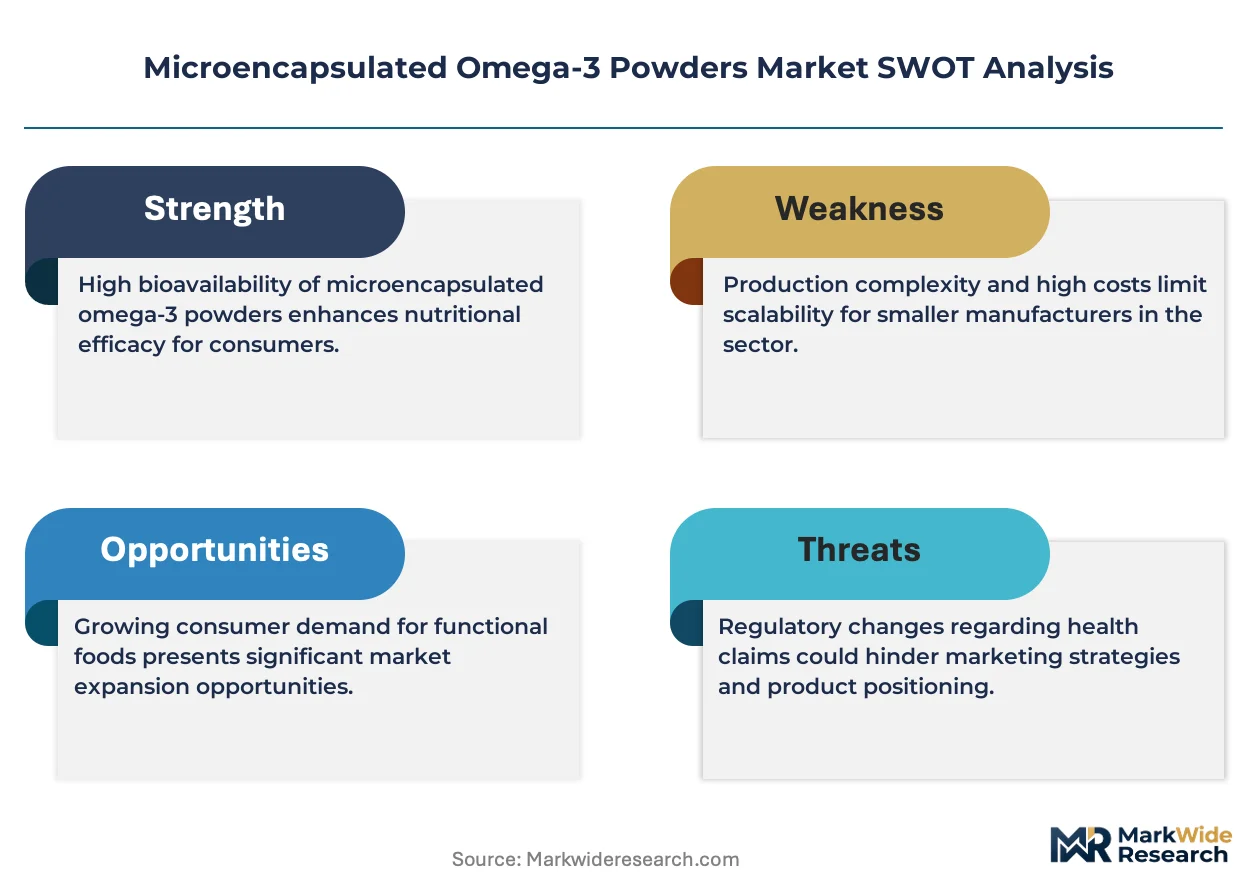
For Market Incumbents: Hedge against algal oil price volatility through backward integration into precision fermentation capacity or long-term offtake agreements with sugar substrate suppliers. BASF SE's Ludwigshafen lipid chemistry heritage demonstrates how upstream EPA/DHA precursor control defends margin position against feedstock swings. Certification investment in REACH-compliant wall materials unlocks infant formula applications previously restricted to gelatin-based systems. For New Entrants and Emerging Players: The premium-to-economy pricing gap in pharmaceutical-grade encapsulation creates entry space for mid-tier suppliers targeting FSSAI-compliant clinical nutrition in India. White-space concentration sits with medical food fortification relative to supplement saturation. Direct-to-brand technical service embedding, modeled on Stepan Company's North American food lab networks, offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Encapsulation houses with continuous processing architectures are the most active acquirer targets in this space as capacity expansion dominates competitive dynamics. Long-term viability favors suppliers with dual EFSA novel food and FDA GRAS dossier capabilities. The signal to watch is Health Canada-FSSAI regulatory harmonization progress as an inflection indicator for synchronized product launch feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Processing Architecture Adoption | Electrospray systems in Swiss pharmaceutical compounders compress manufacturing variability while automating quality release checkpoints. |
| Backward Integration into Fermentation Capacity | Precision fermentation EPA convergence with spray-drying advances enables vegan-certified encapsulation wall systems. |
| Dual Certification Infrastructure Investment | Simultaneous EFSA novel food and FDA GRAS dossier capabilities unlock synchronized European and North American product launches. |
| Direct-to-Brand Technical Service Embedding | Application scientists within customer food labs match powder loadings to shelf-life targets, displacing traditional distributor relationships. |
| REACH-Compliant Wall Material Development | Modified starches and plant protein matrices meeting ECHA purity standards unlock infant formula applications previously restricted to gelatin. |
Research Methodology
Multiple input streams — primary interviews with encapsulation house technical directors, functional food brand formulation scientists, and regulatory affairs specialists at EFSA and FDA; secondary validation through customs trade data, SEC filings of listed nutrition ingredient suppliers, and EFSA novel food register entries; plus REACH registration dossiers — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, application, and end-user segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from modeled volume trajectories incorporating EPA/DHA loading specifications, wall material cost curves, and regulatory approval pathway timelines as industry-specific forecast inputs.
Caveats apply where EFSA-Health Canada novel food recognition divergence, algal oil fermentation capacity constraints, or gelatin supply disruption could materially shift the outlook. A small set of named triggers — regulatory harmonization progress, precision fermentation scale-up rates, and oxidative stability testing standard adoption — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Choline Market
Nutritional Supplements
Canada Nutraceuticals Market
Nutritional Supplements
Organic Whey Protein Market
Nutritional Supplements
Fat Powders Market
Nutritional Supplements
Low-Carb Fat Loss Market
Nutritional Supplements
L Carnitine Market
Nutritional Supplements
Flax Protein Powder Market
Nutritional Supplements
Tryptophan Market
Nutritional Supplements
Global Nutraceuticals Product Market
Nutritional Supplements
Nutritional Drink Market
Nutritional Supplements
Smart Nutrition Scale Market
Nutritional Supplements
Propolis Market
Nutritional Supplements
Krill Oil Phospholipid Market
Nutritional Supplements
Global Protein Market
Nutritional Supplements
Spirulina Purple Blend Market
Nutritional Supplements
Europe Nutritional Beverages Market