
 Personalized Nutrition and Supplements Market | 2026-2036
Personalized Nutrition and Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Personalized Nutrition and Supplements Market Intelligence
AI-driven microbiome analysis is tilting formulation pipelines toward dynamically adjusted supplement regimens. Nestlé Health Science leverages its clinical nutrition infrastructure to anchor precision health portfolios across European and North American markets. BASF SE sustains R&D intensity in micronutrient premixes, competing on bioavailability benchmarks that differentiate custom-blend offerings from commodity alternatives.
Personalized nutrition and supplements encompass tailored dietary interventions formulated to individual genetic profiles, metabolic markers, and lifestyle data, typically manufactured through micro-batch compounding or algorithm-driven premix assembly with specifications for active ingredient stability and dissolution rates. The primary commercial purpose centers on optimizing nutrient delivery beyond population-average dietary guidelines. Custom Blends command premium positioning as formulation complexity rises, while Protein Powders occupy high-volume manufacturing tiers with thinner margins. Online Retail channels are capturing disproportionate growth as subscription algorithms replace episodic purchasing patterns.
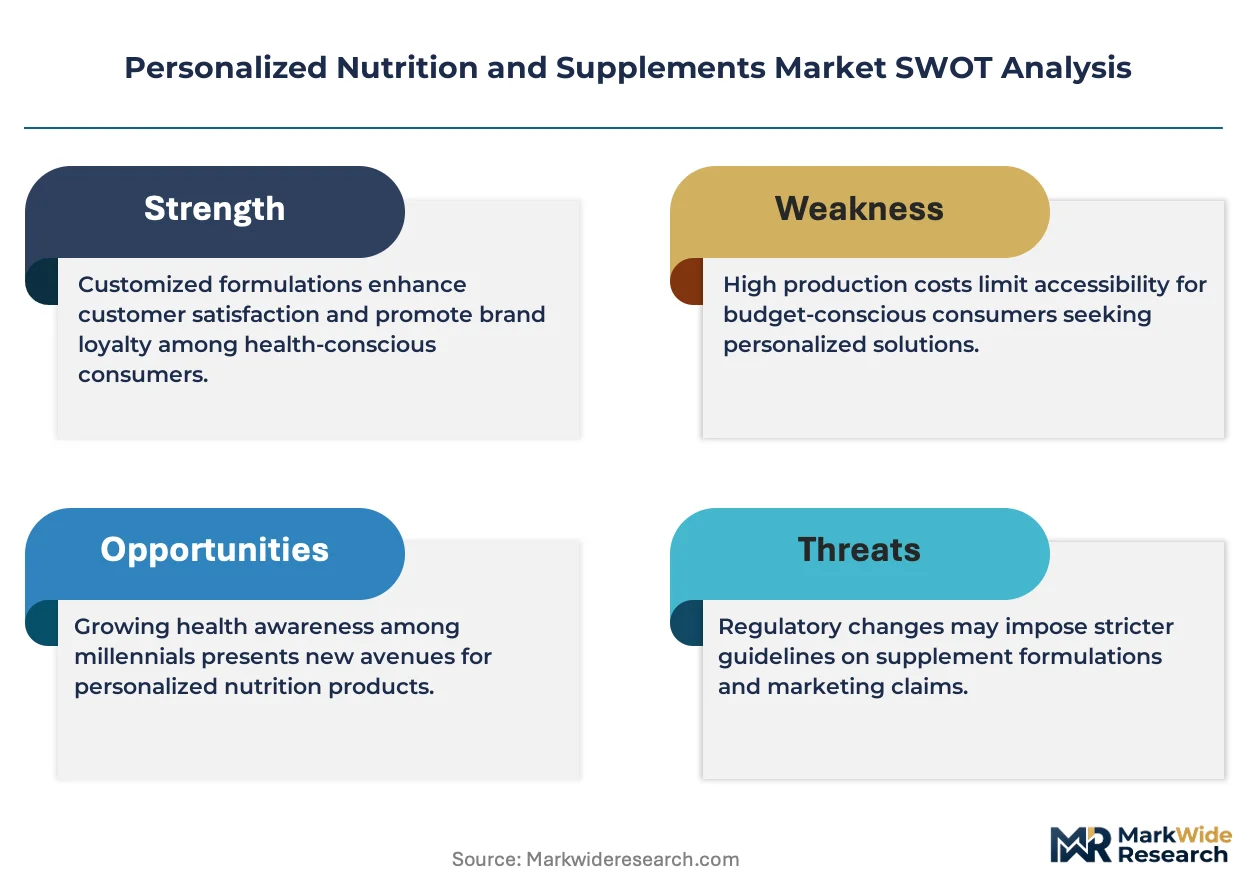
The FDA oversees supplement safety and labeling claims through DSHEA-enforced pathways, while the EMA and national regulators such as BfArM scrutinize nutrigenomic health claims across European jurisdictions. These frameworks elevate compliance costs for cross-border operators but simultaneously filter out unsubstantiated efficacy marketing. Stakeholders must monitor whether microbiome-based personalization triggers medical-device classification thresholds in major jurisdictions.
Market Dynamics
Wearable biometric data integration is compressing formulation cycles from months to weeks, forcing manufacturers to rebuild supply chains around real-time metabolic feedback loops rather than static demographic profiles.
Growth Catalysts
- DSHEA Modernization:The FDA's evolving enforcement pathways for nutrigenomic claims are clarifying permissible health messaging, reducing legal uncertainty for direct-to-consumer genetic testing bundles.
- Continuous Glucose Monitors:CGM adoption among fitness enthusiasts is generating demand for glycemic-response-optimized supplement stacks that adjust micronutrient ratios to postprandial data streams.
- Microbiome Sequencing Cost Collapse:Shotgun metagenomics price points below fifty dollars per sample are democratizing gut-flora-based personalization previously confined to clinical settings.
Market Restraints
- Active Ingredient Volatility:Botanical extract supply from Indian contract farms faces monsoon-dependent yield swings that destabilize custom-blend cost structures.
- Cross-Border Claim Friction:EFSA's strict health-claim substantiation requirements block US-formulated products from European markets despite identical ingredient profiles.
- Stability Limitations:Probiotic viability in ambient-temperature delivery formats caps shelf life at ninety days, constraining subscription model economics.
Strategic Opportunities
- Brazilian Regulatory Tailwind:ANVISA's forthcoming personalized nutrition framework is expected to formalize direct-to-consumer genetic testing, opening Latin America's largest consumer market.
- Menopause-Specific Formulations:Hormonal transition support represents an underserved application vertical with minimal incumbent competition and high willingness-to-pay.
- Pharmacy Channel Integration:CVS and Walgreens pilot programs are embedding supplement personalization kiosks within retail health clinics, creating new prescription-adjacent touchpoints.
Industry Challenges
- Bioinformatics Talent Scarcity:The intersection of nutrigenomics and machine learning requires hybrid skill sets that command premium compensation and resist automation.
- Multi-Jurisdiction Labeling Complexity:Simultaneous compliance with FDA, EFSA, and TGA disclosure requirements fragments packaging runs and extends go-to-market timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personalized Nutrition and Supplements Market |
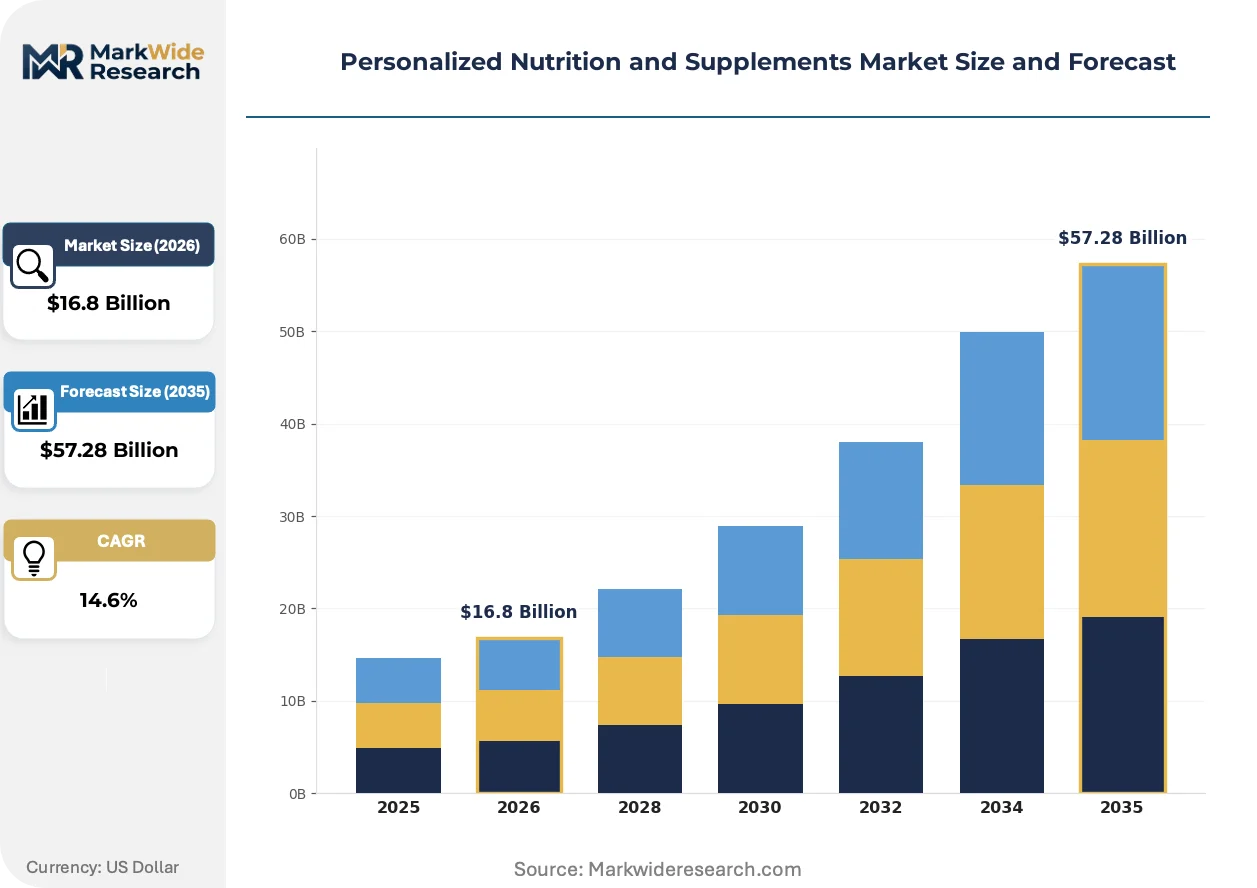
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $57.28 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Protein Powders, Meal Replacement Bars Distribution Channel: Online Retail, Health Food Stores, Pharmacies, Supermarkets Target Consumer: Fitness Enthusiasts, Health-Conscious Individuals, Seniors, Athletes Formulation: Plant-Based, Synthetic, Organic, Custom Blends |
| Companies Covered | Amway Corporation, Nestlé Health Science, Herbalife Nutrition Ltd., BASF SE, DSM SE, Viome Life Sciences, Inc., Nutrigenomix Inc., DNAfit, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personalized Nutrition and Supplements Market Strategic Shifts & Innovations
Algorithmic formulation is collapsing the traditional divide between mass-market and clinical-grade supplements, creating a continuous spectrum of personalization intensity that rewards data infrastructure over manufacturing scale.
Multi-omics integration platforms that combine genomics, metabolomics, and microbiome sequencing are rendering obsolete single-data-source personalization engines that rely solely on SNP arrays. Functional medicine clinics and high-performance athletic programs are adopting these platforms at accelerating rates. The structural consequence is compression of competitive advantage for firms lacking proprietary biomarker databases.
REACH microplastic restrictions are forcing reformulation of time-release capsules previously dependent on synthetic polymer coatings. European manufacturers face twelve-to-eighteen month reformulation cycles to qualify plant-based alternatives through EFSA novel food pathways. Custom-blend operators with existing clean-label capabilities are capturing shelf space from legacy players.
Subscription algorithms now preempt replenishment before depletion signals, replacing the episodic purchasing patterns that dominated supplement retail. Direct-to-consumer brands with integrated wearable data pipelines are disintermediating brick-and-mortar vitamin aisles. This behavioral shift concentrates most visibly in United States metropolitan markets where same-day delivery logistics are mature.
Personalized Nutrition and Supplements Market Segmentation
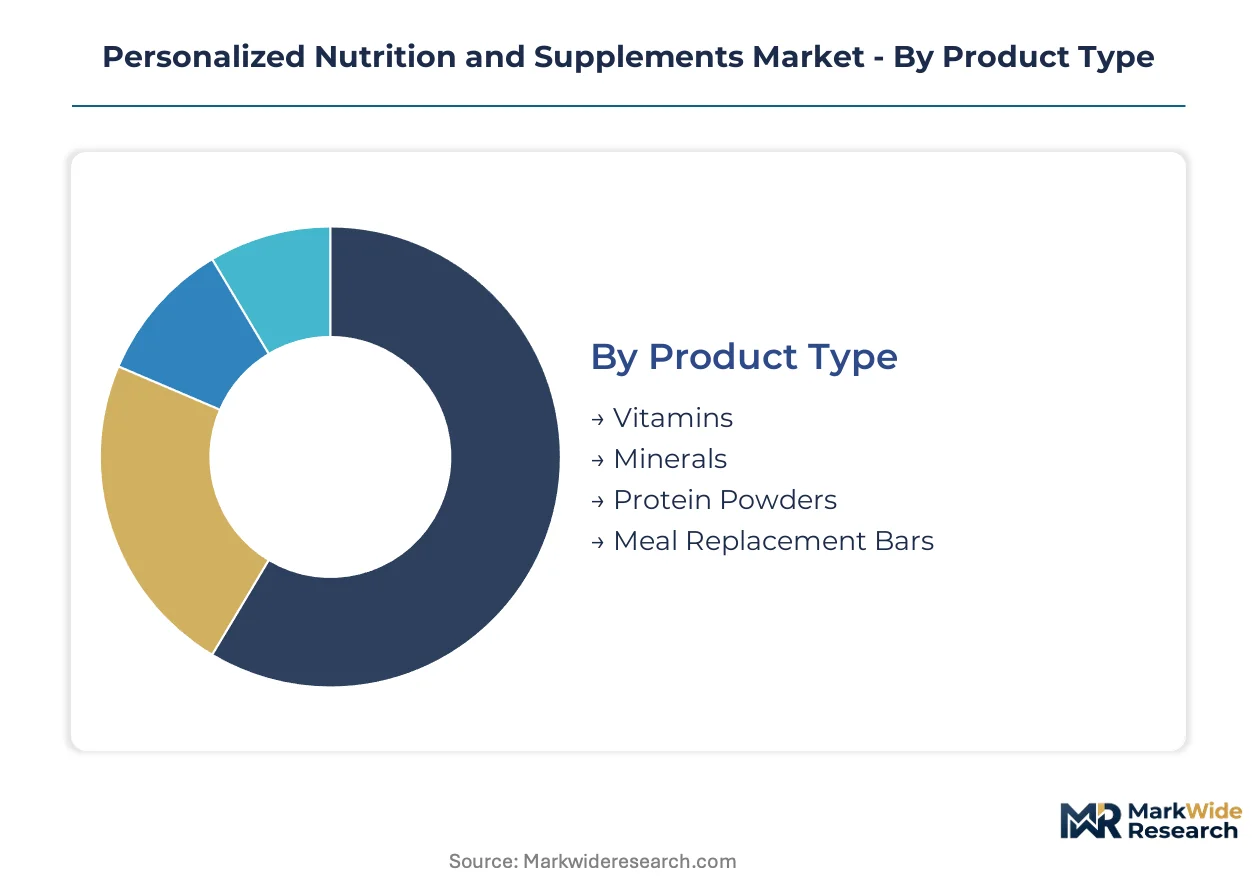
Personalized nutrition segmentation reflects divergent replenishment rhythms across consumer archetypes. Formulation complexity and data integration intensity create tiered margin structures that reward algorithmic customization over commodity manufacturing.
Product Type:
Cycle times compress from quarterly restocking for foundational micronutrients to weekly replenishment for performance-oriented macros. Shelf stability and bioactive degradation curves dictate manufacturing batch frequency and logistics architecture.
- Vitamins:Micronutrient premixes with SNP-targeted dosages address MTHFR polymorphisms and vitamin D receptor variants. Demand clusters among health-conscious individuals in United States metropolitan corridors where direct-to-consumer genetic testing penetration peaks. FDA DSHEA compliance costs elevate barriers for cross-border formulation variants.
- Protein Powders:Whey and plant-isolate formulations with leucine-content optimization for resistance-training protocols dominate high-volume manufacturing tiers. Fitness enthusiasts in California and Texas drive subscription algorithm adoption with CGM-correlated timing. Margins compress as commodity sourcing from Wisconsin dairy cooperatives and Canadian pea-protein processors standardizes.
- Minerals:Chelated forms with glycinate or citrate ligands improve absorption kinetics for aging populations with declining gastric acid production.
- Meal Replacement Bars:Macro-balanced formats with glycemic-index modulation serve time-constrained professionals seeking metabolic consistency.
Vitamins dominate installed base. Protein Powders is where expansion concentrates.
Distribution Channel:
Channel economics stratify by customer acquisition cost and lifetime value capture. Digital-native routes leverage biometric data pipelines for retention, while physical retail trades margin for immediacy and trust transfer.
- Online Retail:Subscription algorithms with predictive replenishment based on wearable depletion signals capture the steepest expansion trajectory. Direct-to-consumer brands bypass wholesale markups while integrating continuous glucose monitor data for dynamic stack adjustments. Same-day delivery infrastructure in New York and Chicago anchors logistics density.
- Pharmacies:CVS and Walgreens pilot kiosks embed personalization within prescription-adjacent workflows, capturing insurance-adjacent consumer trust. Pharmacist consultation layers justify premium positioning for nutrigenomic bundles. Regulatory alignment with FDA labeling requirements streamlines shelf placement versus cross-border entrants.
- Health Food Stores:Staff-curated assortments with local brand discovery serve supplement-literate consumers seeking ingredient transparency.
- Supermarkets:Mass-market placement of basic multivitamins reaches price-sensitive segments with minimal personalization intensity.
Supermarkets dominate installed base. Online Retail is where expansion concentrates.
Target Consumer:
Willingness-to-pay gradients separate performance-obsessed segments from preventive-health adopters. Data-sharing comfort and biomarker access create addressable market boundaries.
- Fitness Enthusiasts:CGM-wearing, wearable-integrated consumers demand real-time formulation adjustments based on recovery metrics and training load. This segment commands premium pricing for microbiome-correlated protein timing and electrolyte replenishment algorithms. Peloton and CrossFit affiliate partnerships concentrate demand in Colorado and Florida fitness corridors.
- Seniors:Sarcopenia-focused formulations with leucine-enriched protein and vitamin D3-K2 combinations address muscle preservation and bone density. Medicare-adjacent pharmacy channels in Arizona and Florida retirement clusters drive volume. Pill burden aversion favors once-daily custom blends over multi-bottle regimens.
- Health-Conscious Individuals:Preventive-oriented consumers with 23andMe or Ancestry genetic profiles seek methylation support and detoxification pathway optimization.
- Athletes:NSF Certified for Sport and Informed Sport verification requirements dominate collegiate and professional procurement with batch-tested purity guarantees.
Health-Conscious Individuals dominate installed base. Fitness Enthusiasts is where expansion concentrates.
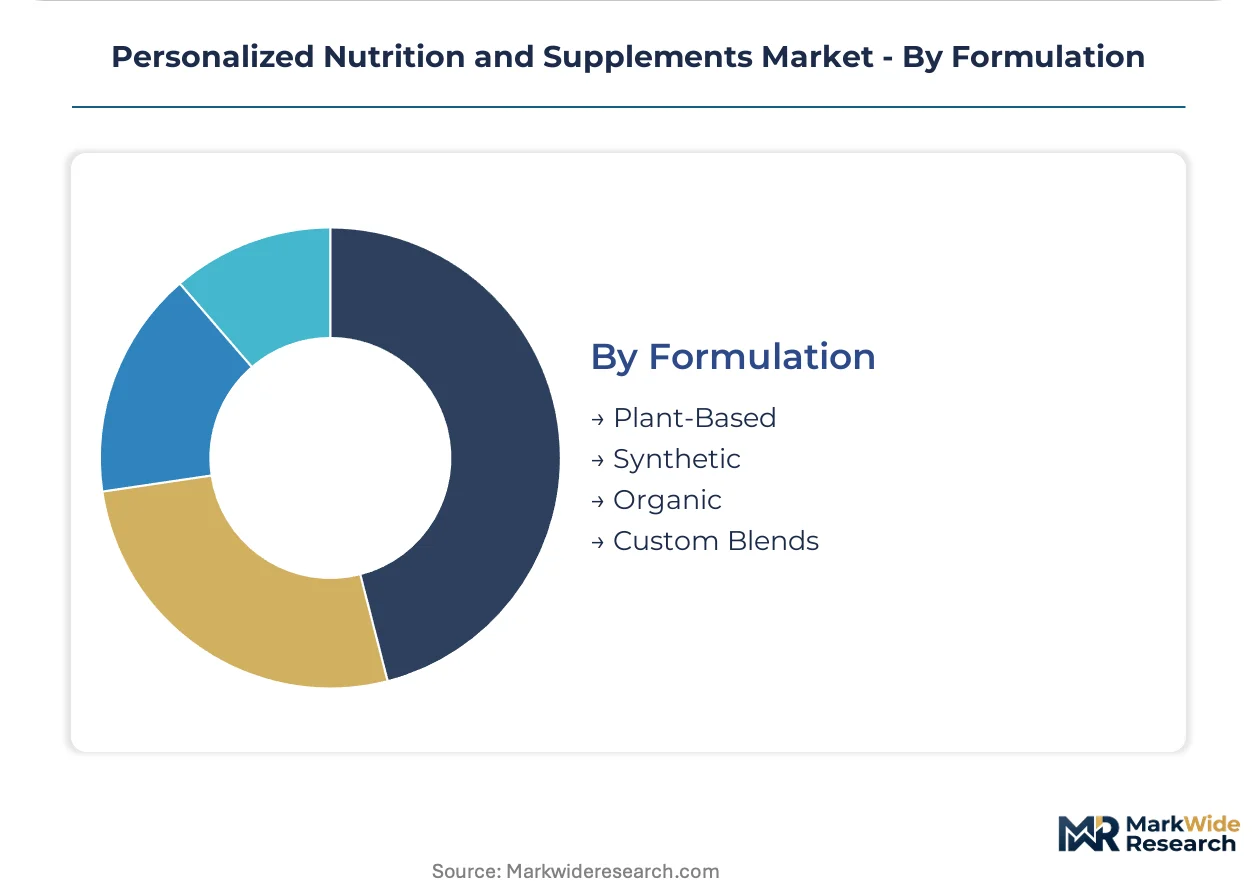
Formulation:
Input sourcing and certification tiering create cost structures that separate mass-market from clinical-grade positioning. Clean-label momentum in European markets accelerates reformulation cycles.
- Custom Blends:Algorithm-assembled micronutrient and botanical combinations with individual genetic and metabolic specifications command premium positioning. Micro-batch compounding with stability-tested dissolution profiles serves functional medicine clinics and executive health programs. REACH microplastic restrictions force twelve-to-eighteen month coating reformulation cycles for European export compliance.
- Plant-Based:Fermented amino acid profiles and algae-derived omega-3 formulations capture sustainability-motivated consumers with ESG-aligned purchasing criteria. Supply concentration in Indian contract farms for ashwagandha and turmeric extracts introduces monsoon-dependent yield volatility.
- Synthetic:Cost-optimized isolated compounds with USP verification serve price-sensitive mass-market channels with established bioequivalence.
- Organic:USDA certification with non-GMO verification addresses parental segments and clean-label adherents with supply chain traceability requirements.
Synthetic dominates installed base. Custom Blends is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German micronutrient premix exports supply North American custom-blend manufacturers, while Indian botanical extract shipments face monsoon-driven volatility that ripples through formulation cost structures worldwide.
United States
Fitness enthusiasts in Colorado and Florida drive CGM-integrated subscription algorithms for glycemic-optimized supplement stacks. FDA DSHEA modernization clarifies permissible nutrigenomic health messaging for direct-to-consumer genetic testing bundles. The New York and Chicago metropolitan corridors anchor same-day delivery logistics density for algorithmic replenishment services.
Germany
REACH microplastic restrictions force twelve-to-eighteen month reformulation cycles for plant-based capsule coatings serving clean-label European demand. BfArM scrutiny of nutrigenomic health claims elevates compliance costs for cross-border operators. The Baden-Württemberg industrial cluster concentrates micronutrient premix R&D facilities competing on bioavailability benchmarks.
China
SAMR oversight of dietary supplement labeling converges with dual carbon goals to accelerate domestic plant-based protein fermentation capacity. NMPA pathways for microbiome-based products remain under development, creating regulatory uncertainty for precision nutrition entrants. The Yangtze River Delta anchors contract manufacturing for fermented amino acid profiles.
Brazil
ANVISA's forthcoming personalized nutrition framework is expected to formalize direct-to-consumer genetic testing, opening Latin America's largest consumer market. São Paulo's executive health programs already pilot algorithm-assembled micronutrient combinations for functional medicine applications. Menopause-specific formulations targeting hormonal transition support show minimal incumbent competition.
Japan
METI promotion of preventive health technologies accelerates adoption of multi-omics integration platforms combining genomics and metabolomics. PMDA classification thresholds for microbiome-based personalization remain under review, shaping product development timelines. The Kanto region's aging population drives demand for sarcopenia-focused formulations with leucine-enriched protein.
Personalized Nutrition and Supplements Market Key Industry Players
Channel-controlling players compete with product-specialist players across a market structure that fragments between data-integrated direct-to-consumer brands and legacy manufacturers rebuilding for algorithmic formulation. Consolidation pressure concentrates among micro-batch compounders lacking proprietary biomarker databases. Three archetypes dominate: clinical nutrition infrastructure deployers, micronutrient premix specialists, and microbiome sequencing platform operators. M&A activity targets bioinformatics talent scarcity, while strategic partnerships bridge wearable data pipelines with compounding capabilities.
Among diversified nutrition conglomerates, Nestlé Health Science and BASF SE exemplify infrastructure-heavy positioning. Nestlé leverages clinical nutrition assets to anchor precision health portfolios across European and North American markets. BASF sustains R&D intensity in micronutrient premixes, competing on bioavailability differentiation from commodity alternatives. Viome Life Sciences occupies the data-native tier, representing microbiome-first personalization engines that compress formulation cycles through real-time metabolic feedback integration.
| Leading Market Players |
|---|
| Amway Corporation |
| Nestlé Health Science |
| Herbalife Nutrition Ltd. |
| BASF SE |
| DSM SE |
| Viome Life Sciences, Inc. |
| Nutrigenomix Inc. |
| DNAfit |
| Bayer AG |
| Others |
Cost & Logistics Intelligence
Monsoon-dependent botanical extract yields from Indian contract farms compress margin buffers for custom-blend manufacturers while simultaneously forcing pricing tier stratification between inventory-heavy incumbents and agile micro-batch operators.
Pricing Analysis
Algorithmic formulation capabilities separate pricing tiers between SNP-targeted micronutrient premixes and commodity multivitamins. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with NSF Certified for Sport verification commanding substantial premiums over basic USP-grade alternatives. Cost compression in protein powder segments is intensifying because Wisconsin dairy cooperative sourcing standardizes whey isolate benchmarks. Fitness enthusiasts with CGM integration show lowest price sensitivity, while supermarket multivitamin buyers exhibit maximal elasticity.
Supply Chain Analysis
Contract manufacturing concentrates among Indian botanical extract processors, German micronutrient premix compounders, and Wisconsin dairy protein cooperatives. Supply draws from monsoon-exposed Indian turmeric and ashwagandha farms, Canadian pea-protein processors, and Baden-Württemberg chelation facilities. Single-source vulnerability runs through Indian monsoon corridors that destabilize custom-blend input costs. Distribution runs through subscription algorithm platforms with predictive replenishment replacing wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among subscription-integrated fitness enthusiasts with wearable data pipelines, fragmenting traditional pharmacy and supermarket procurement influence.
For Market Incumbents: Harden proprietary biomarker database moats against microbiome-sequencing platform entrants lacking clinical validation infrastructure. Deepen backward integration into micronutrient premix manufacturing to offset REACH microplastic reformulation cost shocks. Nestlé Health Science exemplifies infrastructure-heavy positioning that resists disintermediation.
For New Entrants and Emerging Players: Build out menopause-specific formulation white space where hormonal transition support faces minimal incumbent saturation. Target Brazilian executive health programs ahead of ANVISA's personalized nutrition framework formalization. Pharmacy kiosk partnerships with CVS and Walgreens pilots offer prescription-adjacent trust transfer without wholesale margin sacrifice.
For Investors and Strategic Acquirers: The market sits at a platform-consolidation phase that favors data-native microbiome sequencing operators over legacy manufacturers rebuilding algorithmic capabilities. Five-to-ten year viability hinges on multi-omics integration platform control rather than compounding scale. Watch FDA DSHEA modernization enforcement patterns as inflection signal for nutrigenomic claim permissibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Omics Platform Integration | Combines genomics, metabolomics, and microbiome data to compress formulation cycles for fitness enthusiasts. |
| Pharmacy Channel Embedding | CVS and Walgreens kiosk pilots create prescription-adjacent touchpoints with insurance-adjacent consumer trust transfer. |
| Clean-Label Reformulation | REACH microplastic restrictions force twelve-to-eighteen month plant-based coating cycles for European export compliance. |
| Wearable Data Pipeline Partnerships | CGM correlation enables dynamic supplement stack adjustments that preempt replenishment before depletion signals. |
| Biomarker Database Acquisition | Proprietary gut-flora and metabolic datasets render single-data-source personalization engines obsolete. |
Research Approach
Operator-level perspectives from functional medicine clinic directors, compounding pharmacy procurement managers, direct-to-consumer brand supply chain heads, and wearable device integration specialists anchored the qualitative base. These interviews combined with FDA DSHEA enforcement records, EFSA health-claim substantiation databases, customs botanical import data, and subscription platform depletion analytics. Bottom-up algorithmic formulation cost modeling triangulated against top-down market sizing across the analysis window.
Scenario bracketing around regulatory enforcement intensity, monsoon yield volatility bands, and CGM adoption curves structured the projection framework. Segmentation dimensions spanned product type, distribution channel, target consumer archetype, and formulation certification tier across the modeling period. CAGRs derived from biometric data pipeline penetration rates and micro-batch compounding capacity expansion trajectories.
Stress conditions across Indian monsoon severity, REACH enforcement timelines, and FDA nutrigenomic claim clarity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions around wearable integration adoption and subscription algorithm retention benchmarks. Quarterly review of ANVISA framework finalization and EFSA novel food pathway processing velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Garlic Extract Supplement Market
Nutritional Supplements
Insoluble Dietary Fibers Market
Nutritional Supplements
Nutritional Oil Powder Market
Nutritional Supplements
Red Yeast Rice Market
Nutritional Supplements
Smart Nutrition Scale Market
Nutritional Supplements
Testosterone Booster Supplements Market
Nutritional Supplements
South America Collagen Supplements Market
Nutritional Supplements
Japan Dietary Supplements Market
Nutritional Supplements
Australia Nutraceuticals Market
Nutritional Supplements
Nutritional Supplements Market
Nutritional Supplements
Throat Lozenges Market
Nutritional Supplements
Dhea Supplement Market
Nutritional Supplements
Isolate Whey Protein Market
Nutritional Supplements
Dietary Fiber Gummies Market
Nutritional Supplements
Iron Supplement Market
Nutritional Supplements
Diet Pills Market