
 Spirulina Extract Market | 2026-2036
Spirulina Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Spirulina Extract Market Outlook
Modular dosing formats are changing buyer choice as the spirulina extract category is pivoting toward single-serve sachets and stackable capsule systems. DIC Corporation leverages its integrated algae cultivation network across Japan and overseas facilities to secure raw material consistency. Cyanotech Corporation differentiates through Hawaiian-sourced Haematococcus and Spirulina strains with verified astaxanthin content. Givaudan SA extends its position by embedding spirulina-derived natural colorants into beverage and confectionery formulations for European and North American clients.
Spirulina extract denotes a concentrated preparation derived from Arthrospira platensis or Arthrospira maxima biomass, typically standardized to protein content exceeding 60 percent by dry weight and phycocyanin concentrations ranging from five to twenty-five percent depending on extraction method. The material serves primarily as a natural blue pigment, protein fortifier, and antioxidant additive across food, nutraceutical, and cosmetic matrices. Powder formulations dominate volume throughput due to lower unit economics and broader industrial blending compatibility, while liquid extracts command premium positioning in beverage applications where solubility and visual stability determine formulation success. Nutritional Supplements anchors current revenue pools through direct-to-consumer channels, though Cosmetics represents the fastest-growing application as clean beauty brands replace synthetic dyes with phycocyanin-based alternatives.
EFSA novel food evaluations and FDA GRAS self-affirmation pathways create dual compliance burdens for suppliers seeking transatlantic market access, with EFSA's 2013 opinion on Arthrospira biomass establishing the baseline for European safety assessments. China's National Health Commission maintains a separate positive list for algae-derived food ingredients, requiring NMPA registration for imported extracts destined for domestic nutraceutical production. Stakeholders must monitor divergence between regional purity standards—particularly heavy metal limits and microbial specifications—as these technical barriers increasingly determine supplier eligibility rather than cost alone.
Market Dynamics
Clean-label certification mandates from EFSA and FDA are restructuring supplier qualification protocols, forcing biomass processors to invest in traceable cultivation systems and third-party verification infrastructure before accessing transatlantic nutraceutical channels.
Growth Catalysts
- EFSA Novel Food Pathway:The 2013 baseline opinion on Arthrospira biomass establishes European safety precedent, accelerating regulatory clarity for phycocyanin-based colorant applications in beverage and confectionery matrices.
- Protein Fortification Demand:Nutraceutical manufacturers are scaling procurement of high-protein spirulina extract for sports nutrition and functional food formulations targeting fitness-conscious consumer segments.
- Cosmetic Clean Beauty Pivot:Beauty brands are replacing synthetic dyes with phycocyanin-derived natural pigments, creating pull-through demand for standardized extract with verified heavy metal and microbial specifications.
Market Restraints
- Dual Compliance Burden:Suppliers seeking transatlantic access must simultaneously navigate FDA GRAS self-affirmation and EFSA novel food evaluations, doubling regulatory timeline and documentation costs.
- Heavy Metal Divergence:Regional purity standards for arsenic, lead, and cadmium limits vary between US, European, and Chinese specifications, fragmenting quality assurance protocols and disqualifying batch-to-batch suppliers.
- Biomass Input Concentration:Cultivation capacity clusters in subtropical zones with consistent solar exposure, exposing supply chains to climate volatility and irrigation water scarcity in concentrated production regions.
Strategic Opportunities
- Modular Dosing Formats:Single-serve sachets and stackable capsule systems are opening direct-to-consumer channels beyond bulk powder distribution, enabling premium positioning and subscription revenue models.
- NMPA Registration Pathway:China's National Health Commission positive list for algae-derived ingredients creates first-mover advantage for suppliers completing domestic registration ahead of import quota expansion.
- Phycocyanin-Cosmetic Convergence:Antioxidant claims in skincare formulations are driving technical partnerships between extract processors and clean beauty formulators seeking dual-function pigment-active ingredients.
Industry Challenges
- Phycocyanin Stability Expertise:Formulation chemists with specialized knowledge of pH-dependent color degradation and light-stable encapsulation remain scarce relative to demand from beverage and cosmetic developers.
- Cultivation Capital Intensity:Closed photobioreactor systems for contamination-controlled biomass production require substantial upfront investment, limiting processor scale-up speed and geographic diversification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spirulina Extract Market |
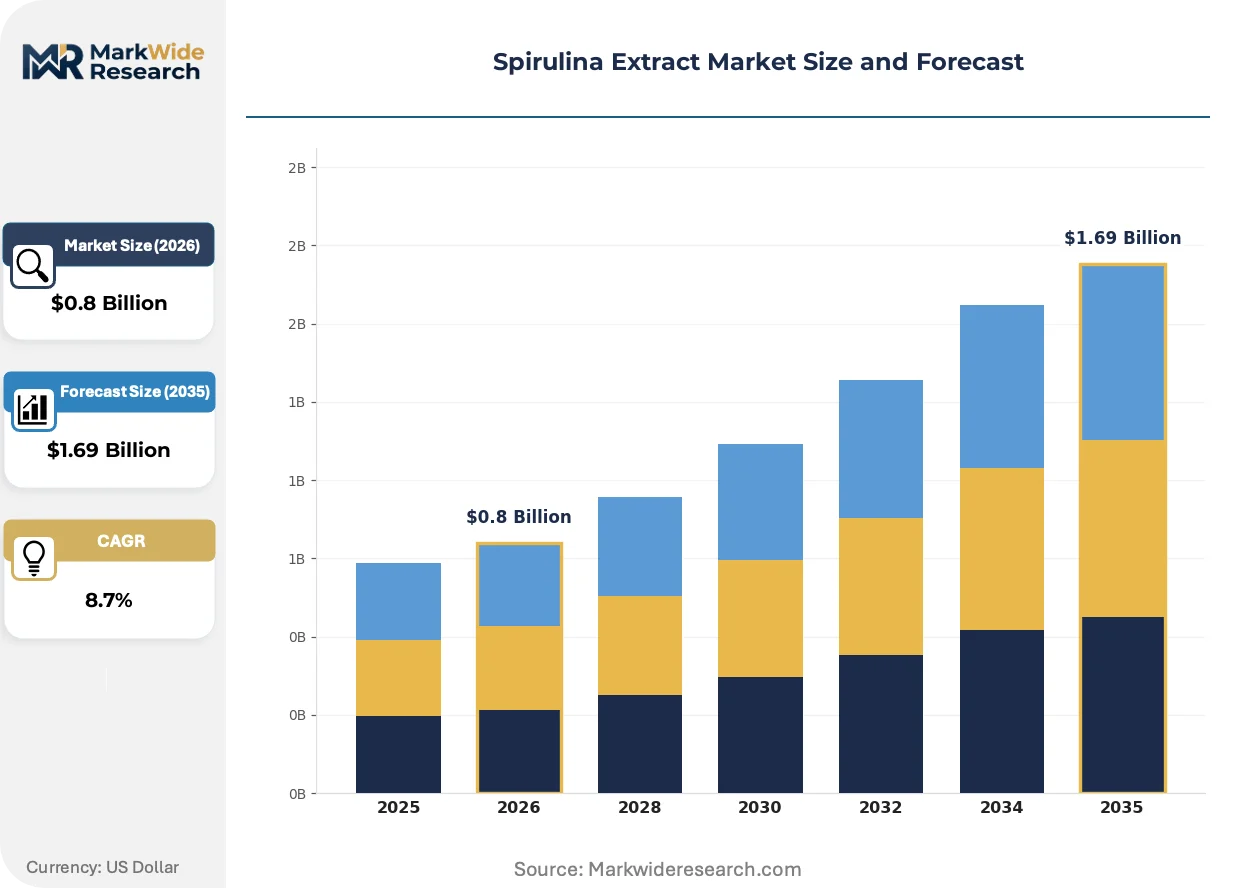
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.69 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Powder, Capsules, Liquid Application: Nutritional Supplements, Food Products, Cosmetics, Animal Feed Distribution Channel: Online Retail, Health Stores, Supermarkets, Pharmacies End User: Health Enthusiasts, Athletes, Vegans, Nutraceutical Manufacturers |
| Companies Covered | Cyanotech Corporation, DIC Corporation, EID Parry India Ltd., Earthrise Nutritionals, Sensient Technologies Corporation, Chr Hansen Holding AS, Givaudan SA, BASF SE, Fuqing King Dnarmsa Spirulina Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spirulina Extract Market Strategic Shifts
Extraction technology advances and regulatory clarity are compressing time-to-market for novel applications, while buyer procurement patterns favor certified suppliers with integrated quality documentation systems over commodity traders.
Closed photobioreactor cultivation is electrifying biomass consistency standards by eliminating open-pond contamination risks. Beverage formulators in Germany and the United States are specifying photobioreactor-sourced extract for premium positioning. This technology is compressing rejection rates and enabling year-round supply contracts previously impossible with seasonal open-pond harvests.
REACH registration requirements for novel food contact substances are tightening purity documentation obligations for European ingredient suppliers. The industrial consequence is accelerated investment in in-house analytical laboratories capable of batch-level heavy metal and microbial testing. Cosmetic and nutraceutical contract manufacturers are responding by consolidating supplier bases to processors with verified REACH-compliant dossiers.
Direct-procurement relationships between end-brand formulators and cultivation facilities are displacing traditional distributor intermediaries in high-volume segments. Stackable capsule and single-serve sachet brands are negotiating long-term offtake agreements directly with Hawaiian and Japanese biomass processors. This pattern is most visible in North American sports nutrition and European clean beauty verticals where traceability claims command shelf price premiums.
Spirulina Extract Market Segmentation
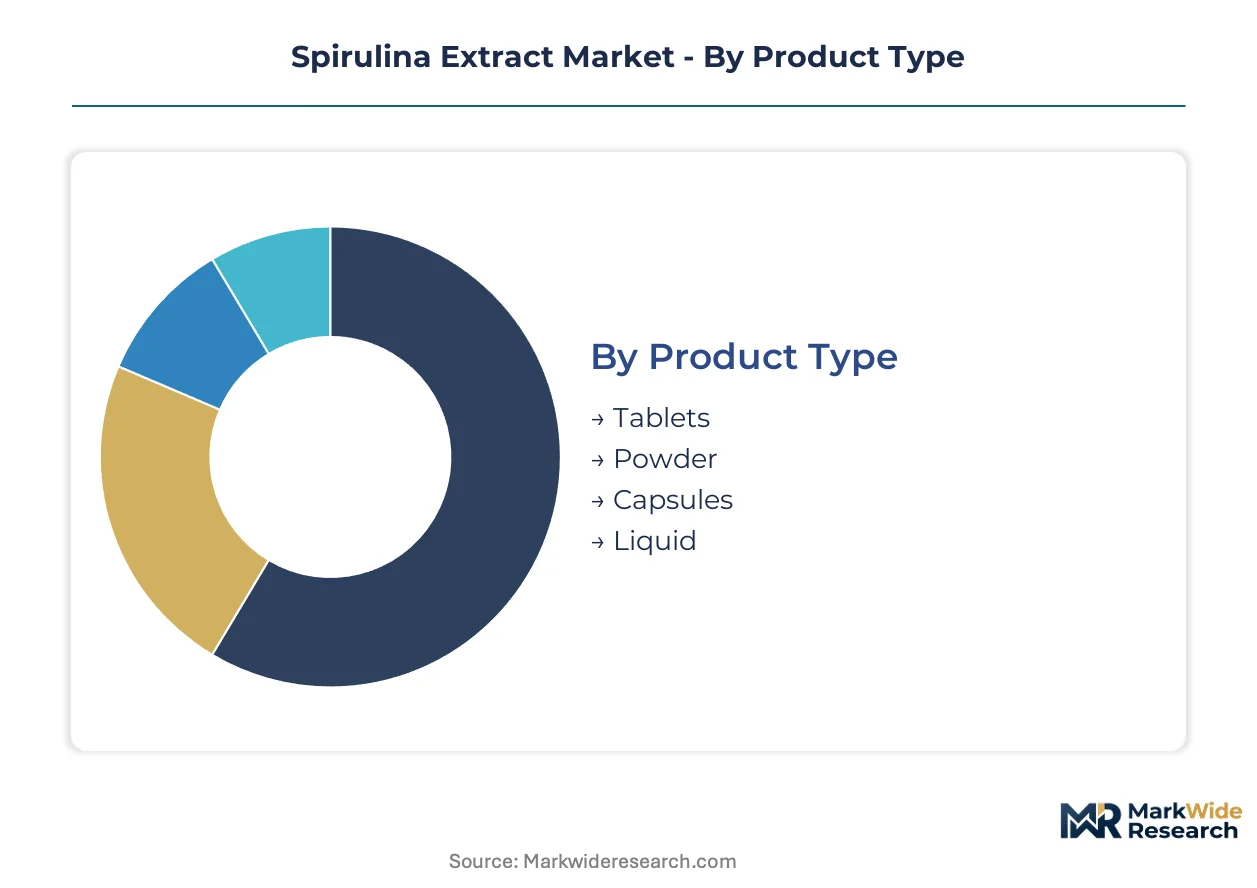
Spirulina extract buyers prioritize format compatibility with existing production lines and formulation stability requirements. Procurement decisions diverge sharply between industrial bulk purchasers and direct-to-consumer brands. Each segmentation dimension reveals distinct margin structures and certification burdens.
Product Type:
Industrial buyers select formats based on blending equipment compatibility and shelf-stability specifications for target applications.
- Powder:Dry extract standardized to protein content exceeding 60 percent by dry weight dominates industrial procurement for food fortification and nutraceutical blending. Food manufacturers in Germany and the United States specify powder for protein bar and functional beverage formulations where unit economics and storage stability determine supplier selection.
- Liquid:Soluble phycocyanin concentrates command premium positioning in beverage applications where visual stability and rapid dispersion are non-negotiable. Cosmetic formulators specify liquid formats for skincare serums requiring precise dosing and homogeneous pigment distribution.
- Tablets:Compressed formats serve direct-to-consumer channels with standardized dosing convenience for health enthusiasts.
- Capsules:Encapsulated extracts target athlete and vegan segments seeking portable, taste-masked delivery systems.
Powder leads on scale; liquid leads on momentum.
Application:
End-use matrices impose divergent purity standards and regulatory documentation requirements on extract suppliers.
- Nutritional Supplements:Protein fortification and antioxidant positioning anchor current revenue pools through sports nutrition and wellness channels. FDA GRAS self-affirmation and EFSA novel food compliance create dual documentation burdens for suppliers accessing transatlantic nutraceutical markets.
- Cosmetics:Clean beauty brands are replacing synthetic dyes with phycocyanin-derived natural pigments, creating pull-through demand for heavy metal-certified extracts. Skincare formulators in France and Germany specify REACH-registered phycocyanin for antioxidant claims combined with colorant functionality.
- Food Products:Natural blue colorant applications in confectionery and beverage matrices require light-stable encapsulation expertise.
- Animal Feed:Aquaculture and poultry producers utilize spirulina for pigment enhancement in farmed salmon and egg yolk coloration.
Nutritional supplements lead on scale; cosmetics expands most quickly.
Distribution Channel:
Channel selection determines margin capture and traceability documentation depth for extract suppliers.
- Online Retail:Direct-to-consumer platforms enable subscription revenue models and modular dosing formats including single-serve sachets. Stackable capsule brands negotiate long-term offtake agreements directly with biomass processors, bypassing traditional distributor intermediaries.
- Health Stores:Specialty retailers command shelf price premiums for certified organic and photobioreactor-sourced extracts with verified origin documentation.
- Supermarkets:Mass retail channels concentrate volume throughput for standard-grade powder in private-label protein fortification products.
- Pharmacies:Regulated channels require NMPA registration in China and compliance with national pharmaceutical standards for therapeutic positioning.
Online retail leads on scale; health stores lead on momentum.
End User:
User segments impose distinct formulation specifications and certification requirements on extract procurement.
- Nutraceutical Manufacturers:Industrial formulators specify batch-level heavy metal and microbial testing for EFSA and FDA compliance. Direct-procurement relationships with cultivation facilities are displacing distributor intermediaries in high-volume segments.
- Athletes:Sports nutrition brands demand protein-standardized extracts with banned-substance testing certification for competitive use.
- Health Enthusiasts:Wellness-focused consumers prioritize clean-label positioning and third-party verification infrastructure.
- Vegans:Plant-based positioning requires algae-sourced certification excluding animal-derived processing aids.
Nutraceutical manufacturers lead on scale; athletes lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spirulina cultivation originated in Lake Texcoco, Mexico, where Aztec harvesters collected Arthrospira biomass for consumption. Modern industrial production now spans subtropical zones with consistent solar exposure, though regulatory divergence and clean-label certification demands are reshaping geographic procurement patterns.
United States
Sports nutrition brands and clean beauty formulators drive procurement of phycocyanin-standardized extracts. FDA GRAS self-affirmation pathways create compliance documentation burdens for suppliers accessing nutraceutical channels. Hawaiian biomass processors supply photobioreactor-cultivated material to North American beverage developers seeking premium positioning.
China
Domestic nutraceutical manufacturers scale spirulina protein fortification for aging population wellness products. NMPA registration requirements under the National Health Commission positive list filter import eligibility for algae-derived ingredients. Fujian and Yunnan provinces concentrate open-pond cultivation capacity serving both domestic consumption and export markets.
Germany
REACH-registered phycocyanin demand accelerates from cosmetic formulators replacing synthetic dyes in skincare applications. EFSA novel food evaluations establish European safety precedent for beverage colorant applications. Bavarian and North Rhine-Westphalian processing facilities integrate batch-level heavy metal testing for transatlantic supplier qualification.
Japan
Integrated algae cultivation networks supply consistent biomass for functional food and beverage integration. METI industrial standards and JIS quality specifications shape domestic procurement protocols. Okinawa and Kyushu regions host closed photobioreactor facilities eliminating seasonal harvest variability.
India
Ayurveda-positioned wellness brands incorporate spirulina extracts into traditional medicine-inspired supplements. FSSAI food safety standards and CDSCO nutraceutical regulations create dual compliance frameworks for domestic and export-bound processors. Tamil Nadu and Gujarat cultivation clusters serve both local consumption and Middle East export channels.
Spirulina Extract Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and traceability documentation. The supplier base stratifies between integrated cultivators with captive biomass production and toll processors dependent on spot market sourcing. Three archetypes dominate: photobioreactor operators commanding price premiums for contamination-controlled supply, open-pond harvesters competing on unit economics, and formulation specialists capturing value through encapsulation and delivery system innovation. Capacity expansion and direct-procurement relationship building constitute the dominant competitive moves as brands bypass distributor intermediaries.
Within the integrated cultivation tier, DIC Corporation and Cyanotech Corporation exemplify geographic specialization strategies. DIC leverages its Japan-based corporate structure to anchor Asian biomass supply networks. Cyanotech occupies a position representing Hawaiian-origin positioning in North American premium channels. Among diversified ingredient suppliers, Givaudan SA and BASF SE sit within the flavor-and-fragrance conglomerate archetype, embedding spirulina-derived colorants into broader natural ingredient portfolios. Sensient Technologies Corporation and Chr Hansen Holding AS represent the specialty colorant specialist tier, with corporate suffixes indicating US and Danish corporate structures respectively.
| Leading Market Players |
|---|
| Cyanotech Corporation |
| DIC Corporation |
| EID Parry India Ltd. |
| Earthrise Nutritionals |
| Sensient Technologies Corporation |
| Chr Hansen Holding AS |
| Givaudan SA |
| BASF SE |
| Fuqing King Dnarmsa Spirulina Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Clean-label certification mandates from EFSA and FDA are forcing biomass processors to upgrade traceability infrastructure and third-party verification systems, compressing margins at the commodity tier while enabling premium capture by photobioreactor operators with documented contamination control. This specification divergence between certified and uncertified supply tiers is widening price spreads as beverage and cosmetic formulators consolidate procurement around qualified suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates photobioreactor-sourced phycocyanin with full EFSA and FDA documentation from open-pond biomass with basic microbial testing and uncertified commodity powder. Price differentiation rests on certification depth and cultivation method transparency, with REACH-registered extracts commanding substantial premiums in European cosmetic channels. Cost compression in the economy tier is intensifying as Chinese open-pond capacity expands and spot-market biomass floods industrial fortification segments. Nutraceutical contract manufacturers exhibit highest price sensitivity due to thin formulation margins, while clean beauty brands demonstrate lowest sensitivity where phycocyanin replaces synthetic dyes in prestige positioning.
Supply Chain Analysis
Biomass supply rests on subtropical cultivation clusters in China, India, and the United States where consistent solar exposure enables year-round open-pond harvests. Raw material dependencies center on agricultural-grade sodium bicarbonate, filtered irrigation water, and proprietary Arthrospira strain inoculums that determine protein and phycocyanin yield profiles. Single-source vulnerability concentrates in Hawaiian photobioreactor facilities supplying North American premium channels, where climate events or equipment failure would disrupt contracted offtake agreements with sports nutrition brands. Distribution runs through direct-procurement relationships between biomass processors and end-brand formulators, bypassing traditional ingredient distributors in high-volume nutritional supplement and clean beauty verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in spirulina extract is achievable through backward integration into closed photobioreactor cultivation, which collapses contamination-related batch rejection rates and unlocks premium-tier positioning in beverage and cosmetic channels.
For Market Incumbents: Acquire closed photobioreactor cultivation assets in subtropical zones with established solar infrastructure to secure contamination-controlled biomass supply and defend against Hawaiian-origin premium positioning. Consolidate supplier qualification documentation by investing in in-house analytical laboratories capable of batch-level heavy metal and microbial testing for EFSA and FDA compliance. This dual move addresses the emerging threat of direct-procurement relationships displacing distributor intermediaries while capturing margin from REACH-registered phycocyanin demand in European cosmetics. For New Entrants and Emerging Players: Photobioreactor cultivation technology adapted from pharmaceutical algae applications offers a technology-first wedge into the premium beverage colorant segment where solubility and visual stability requirements exclude open-pond supply. Target China's domestic nutraceutical market through NMPA registration ahead of import quota expansion, as aging-population wellness products drive protein fortification demand with limited qualified foreign supplier penetration. Establish go-to-market partnerships with sports nutrition brands seeking banned-substance testing certification for competitive athlete positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap processors possessing captive photobioreactor capacity and established EFSA novel food dossiers, as regulatory documentation moats widen against commodity competitors. Long-term viability over the coming decade favors integrated cultivators over toll processors dependent on spot market sourcing, given buyer consolidation around traceability-verified suppliers. Watch NMPA registration completion rates among foreign suppliers as the inflection indicator for Chinese market access premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photobioreactor Cultivation | Eliminates open-pond contamination risks and enables year-round supply contracts with German beverage formulators. |
| REACH Registration Completion | Unlocks European cosmetic channel access as French and German skincare brands replace synthetic dyes. |
| NMPA Registration Pathway | Creates first-mover advantage in China's aging-population wellness product market ahead of import quota expansion. |
| Direct-Procurement Relationship Building | Bypasses distributor intermediaries as North American sports nutrition brands negotiate long-term offtake agreements. |
| In-House Analytical Laboratory Investment | Enables batch-level heavy metal and microbial testing required for EFSA and FDA dual compliance documentation. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biomass cultivation managers, nutraceutical formulation chemists, cosmetic procurement leads, and regulatory affairs specialists at EFSA-notified bodies with secondary validation from FDA GRAS notifications, EFSA novel food opinions, NMPA registration databases, and customs trade data. Bottom-up triangulation across product format volumes and top-down reconciliation against end-use application demand ensured convergence in market sizing estimates.
Segment-weighting across the projection horizon applied differential growth assumptions by product type, application matrix, and distribution channel, with powder, liquid, tablet, and capsule formats modeled separately alongside nutritional supplement, cosmetic, food product, and animal feed end-uses. CAGRs were derived from fitted growth curves calibrated to historical procurement patterns and regulatory approval timelines, incorporating phycocyanin stability expertise scarcity and cultivation capital intensity as supply-side constraints.
The model holds under stable regulatory divergence between EFSA, FDA, and NMPA frameworks; deviation in harmonization of heavy metal limits or accelerated novel food approval timelines would shift competitive positioning toward faster-responding suppliers. Forecasts reflect documented assumptions regarding photobioreactor adoption rates and direct-procurement relationship formation. A small set of named triggers—climate volatility in subtropical cultivation zones, REACH enforcement tightening, and Chinese import quota policy shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Apo-8 Carotenal Market
Nutritional Supplements
Vegan Vitamins and Supplements Market
Nutritional Supplements
US and Canada Beta Glucan Market
Nutritional Supplements
India Whey Protein Market
Nutritional Supplements
Asia-Pacific Nutraceutical Excipients Market
Nutritional Supplements
Ferrous Fumarate Market
Nutritional Supplements
Grass-Fed Collagen Market
Nutritional Supplements
Garcinia Cambogia Extract Market
Nutritional Supplements
Longevity and Anti-Aging Brain Health Supplements Market
Nutritional Supplements
Europe Nutraceutical Excipients Market
Nutritional Supplements
Microencapsulated Omega-3 Powders Market
Nutritional Supplements
Global Beta-Alanine Market
Nutritional Supplements
Middle East and Africa Omega-3 Products Market
Nutritional Supplements
Lactates Market
Nutritional Supplements
Vegan Protein Market
Nutritional Supplements
Cordyceps Product Market