
 Bone Meal Supplement Market | 2026-2036
Bone Meal Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Meal Supplement Market Outlook
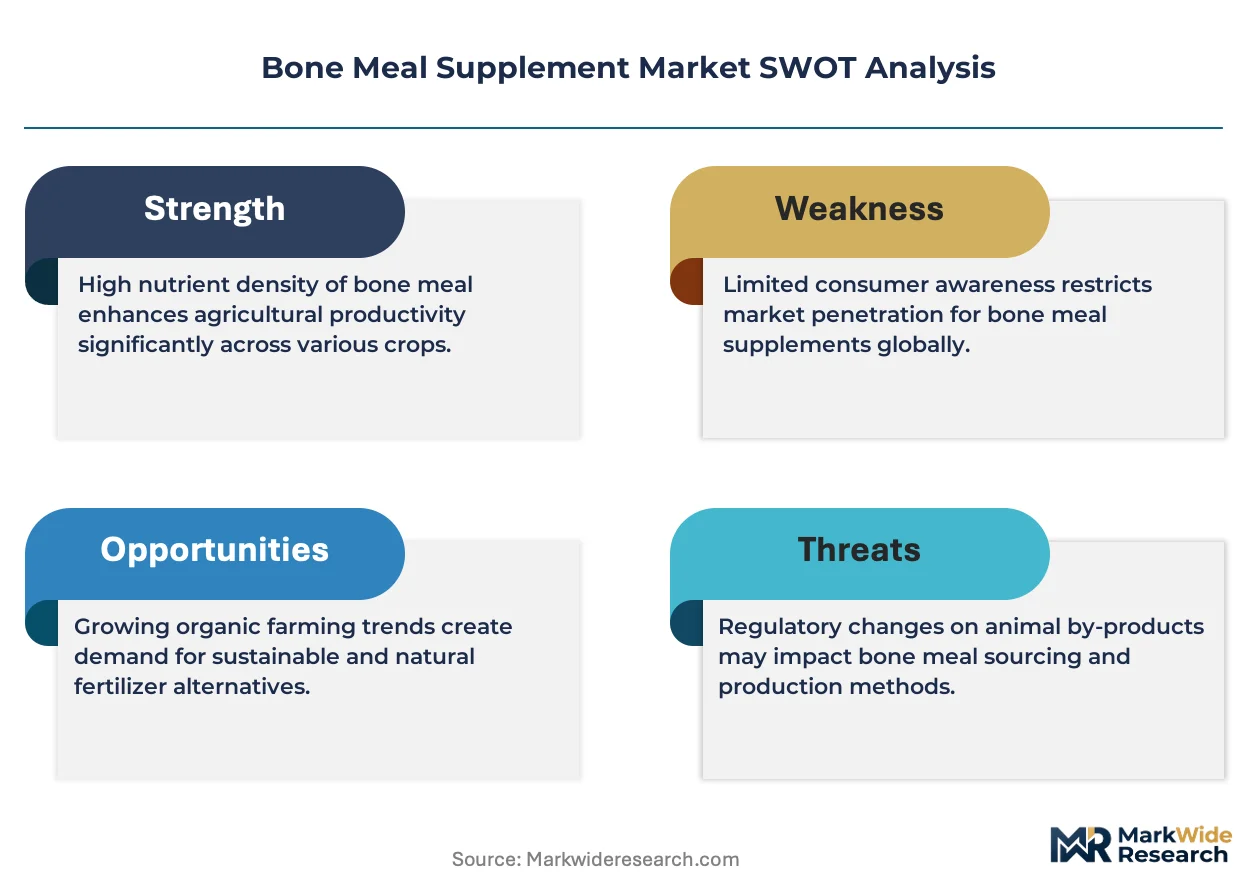
The nutritional supplements industry is pivoting toward mineral-dense natural inputs as health enthusiasts reject synthetic calcium fortification. Darling Ingredients Inc. leverages its integrated rendering network to secure raw bone supply chains across North American processing facilities. ICL Group Ltd. anchors its position through deep specialization in phosphate-derived nutrition products with controlled mineral bioavailability. Cargill Incorporated competes by extending its agricultural commodity infrastructure into value-added animal byproduct refinement.
Bone meal supplement denotes calcined and finely ground animal bone tissue, typically containing 20-25% phosphorus and 30-35% calcium by dry weight, processed through pressure sterilization and milling to eliminate pathogens while preserving mineral matrix integrity. Its primary commercial purpose centers on natural mineral fortification for human dietary supplements, animal feed formulations, and organic agricultural fertilizers. Organic bone meal commands premium positioning within the product type category due to certified supply chain segregation and restricted processing methods. The powdered form dominates manufacturing economics and bulk distribution, while capsule form captures higher margins through health food store and online retailer channels targeting direct-to-consumer wellness segments.
FDA dietary supplement Current Good Manufacturing Practices constrain pathogen testing and heavy metal thresholds for bone-derived ingredients entering human consumption channels. USDA organic certification and EPA biosolid regulations jointly determine which rendering outputs qualify for organic fertilizer and supplement applications, creating tiered market access barriers. Stakeholders must monitor evolving state-level restrictions on specified risk materials in rendering feedstocks, as these rules directly reshape eligible supply pools and regional processing economics.
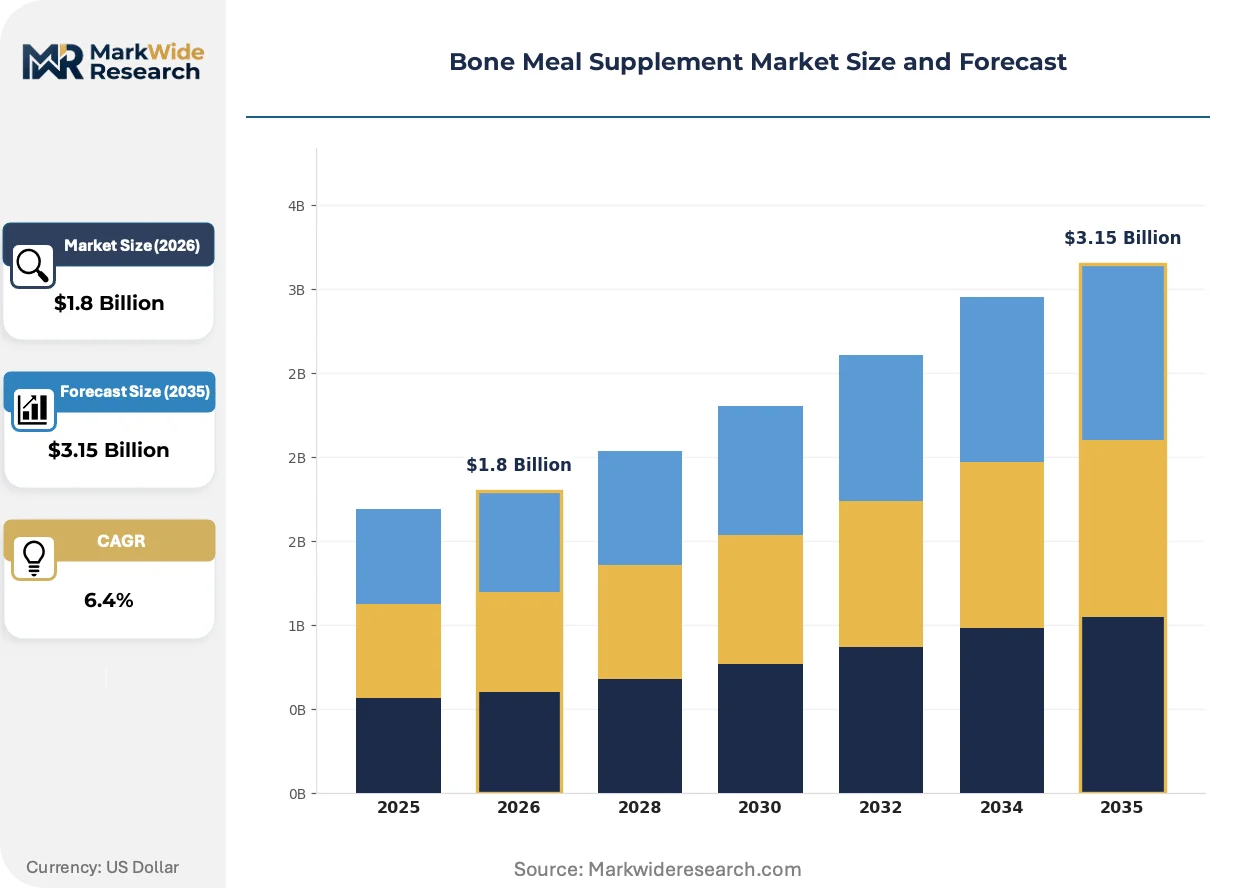
Market Dynamics
The bone meal supplement market pivots on tightening FDA pathogen testing mandates for animal-derived calcium sources, forcing renderers to upgrade sterilization infrastructure while preserving mineral bioavailability through controlled calcination protocols.
Growth Catalysts
- Pet Humanization Trajectory:Companion animal owners in the United States now prioritize traceable mineral fortification for premium pet nutrition, driving certified organic bone meal into veterinary-formulated supplements and raw diet premixes.
- USDA Organic Certification Pipeline:Segregated supply chains for certified organic bone meal unlock premium pricing in human dietary supplements as health food retailers enforce batch-level traceability documentation.
- Aging Demographics Calcium Demand:Osteoporosis-prevention protocols among adults over sixty-five in the United States favor natural mineral matrices over synthetic carbonate or citrate forms, anchoring sustained volume through direct-to-consumer channels.
Market Restraints
- Rendering Feedstock Concentration:Eligible cattle bone supply clusters in Midwestern United States packing facilities, creating geographic dependency and transport-cost sensitivity for coastal processors.
- Specified Risk Material Bans:State-level restrictions on spinal column and skull inclusion in rendering inputs shrink technically eligible raw material pools and complicate procurement compliance.
- Plant-Based Calcium Substitution:Algae-derived and lithothamnion calcium sources capture label-conscious consumers seeking non-animal mineral fortification, compressing addressable market expansion in vegan-adjacent segments.
Strategic Opportunities
- Companion Animal Oral Care Formulations:Dental hygiene chews and water additives represent an underdeveloped application vector for microground bone meal with proven tartar-control mineral release profiles.
- Regenerative Agriculture Fertilizer Integration:USDA organic-certified bone meal bridges human supplement and agricultural input markets, allowing processors to arbitrage price cycles across dual-use certification tiers.
- Direct-to-Consumer Subscription Channels:Vertically integrated brands bypass health food store margin stacking through personalized dosing platforms targeting fitness enthusiasts and paleo-diet adherents.
Industry Challenges
- Heavy Metal Testing Cadence:FDA Current Good Manufacturing Practices mandate lot-level screening for lead and cadmium, extending quality control timelines and elevating analytical chemistry staffing requirements.
- Calcination Equipment Retrofit Costs:Pathogen elimination standards pressure mid-scale renderers to replace legacy pressure sterilization vessels with continuous thermal processing systems requiring seven-figure capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Meal Supplement Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Bone Meal, Protein Supplement, Mineral-Rich Meal, Calcium Source End User: Pet Owners, Nutritional Supplements Industry, Agriculture, Health Enthusiasts Distribution Channel: Online Retailers, Health Food Stores, Specialty Shops, Wholesale Distributors Form: Powdered Form, Capsule Form, Granular Form, Liquid Form |
| Companies Covered | Darling Ingredients Inc., OCP Group, ICL Group Ltd., Haifa Group, Yara International ASA, Sanimax, Cargill Incorporated, Nutrien Ltd., J. Grennan & Sons, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Meal Supplement Market Strategic Shifts
Mineral bioavailability engineering and supply chain digitization are compressing traditional processing economics while opening premium positioning for verified clean-label bone meal sources.
Low-temperature calcination with real-time mineral matrix monitoring is rewriting quality assurance protocols. Premium supplement brands now specify residual moisture and particle size distribution in procurement contracts. This precision is compressing commodity-grade margins while rewarding processors with spectroscopic verification capabilities.
EPA biosolid regulations intersect with USDA organic standards to reshape rendering output eligibility. Fertilizer-grade bone meal must now demonstrate heavy metal thresholds below human supplement thresholds to qualify for organic agriculture applications. California and Washington state enforcement agencies are driving national compliance harmonization through import inspection stringency.
Subscription-based personalized nutrition platforms are disintermediating brick-and-mortar health food distribution. Direct-to-consumer brands now bundle bone meal capsules with microbiome testing and dietitian consultations. This channel rotation concentrates most visibly in United States metropolitan markets with high wellness-tech penetration and established last-mile cold-chain infrastructure.
Bone Meal Supplement Market Segmentation
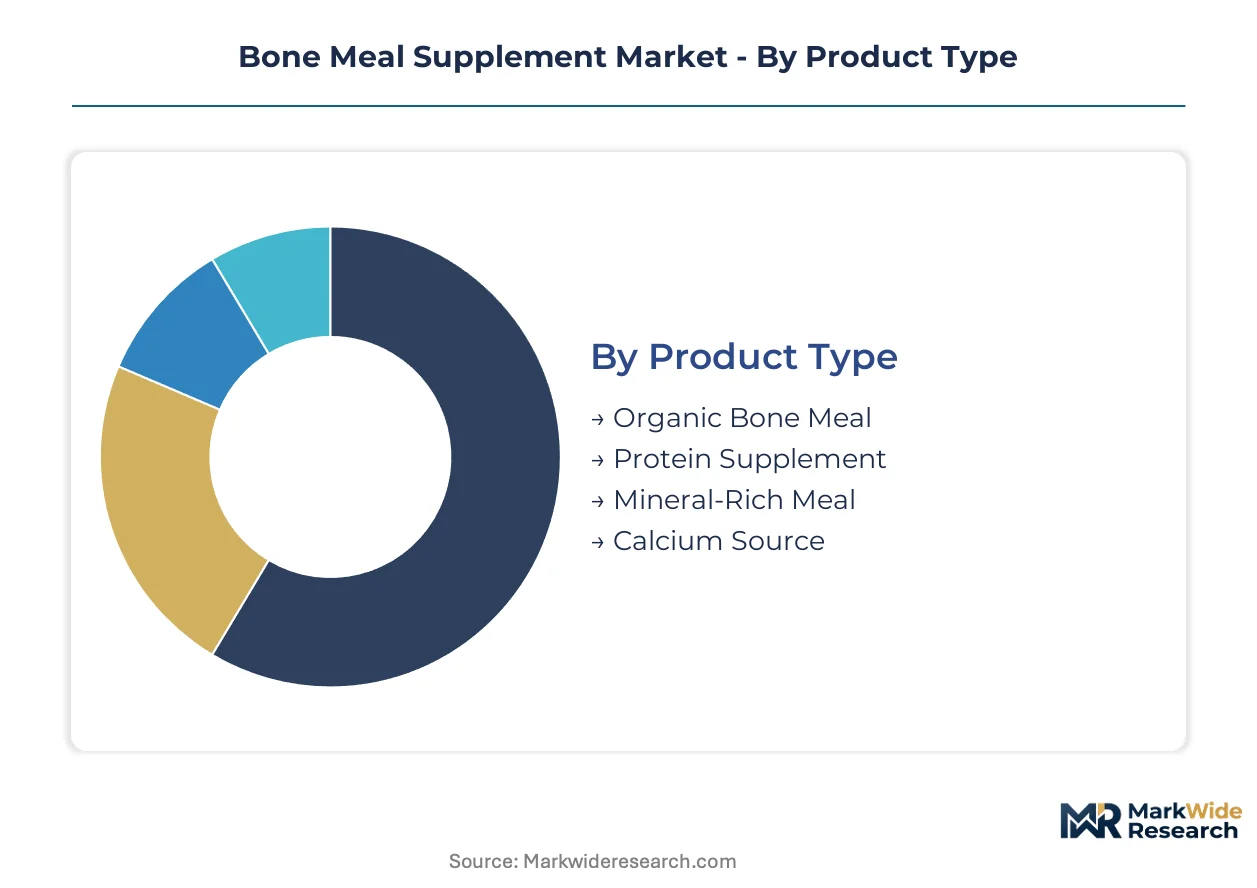
Bone meal supplement segmentation reveals divergent capital requirements across processing tiers. Organic certification and sterilization infrastructure create distinct investment profiles that reshape competitive positioning within each category.
Product Type:
Capital intensity concentrates in supply chain segregation and controlled thermal processing equipment.
- Organic Bone Meal:Certified supply chains require dedicated rendering vessels, batch-level documentation systems, and third-party audit infrastructure. Pet owners in the United States drive premium pricing through veterinary-formulated supplements and raw diet premixes with full traceability documentation.
- Protein Supplement:Higher protein retention demands modified calcination protocols with real-time moisture monitoring. Health food retailers enforce residual protein specifications above standard bone meal grades, compressing commodity margins while rewarding processors with spectroscopic verification capabilities.
- Mineral-Rich Meal:Standardized calcium-phosphate ratios serve agricultural fertilizer blending operations with lower compliance overhead.
- Calcium Source:Generic fortification grade for mass-market dietary supplement manufacturers prioritizing cost over certification.
Organic Bone Meal absorbs the bulk of installed capacity; Protein Supplement is expanding most quickly.
End User:
Customer sophistication determines quality assurance expenditure and channel economics.
- Pet Owners:Companion animal nutrition demands pathogen elimination standards exceeding agricultural applications. FDA Current Good Manufacturing Practices and state-level specified risk material bans reshape eligible supply pools for veterinary-formulated products.
- Nutritional Supplements Industry:Human consumption channels require lot-level heavy metal screening for lead and cadmium under FDA mandates. Aging demographics in the United States favor natural mineral matrices over synthetic carbonate forms for osteoporosis-prevention protocols.
- Agriculture:EPA biosolid regulations intersect with USDA organic standards to determine rendering output eligibility for organic fertilizer applications.
- Health Enthusiasts:Direct-to-consumer subscription channels concentrate in metropolitan markets with established wellness-tech penetration and last-mile cold-chain infrastructure.
Nutritional Supplements Industry commands the highest quality control investment; Pet Owners are gaining share fastest.
Distribution Channel:
Channel selection dictates margin structure and customer acquisition cost profiles.
- Online Retailers:Subscription-based personalized nutrition platforms bundle bone meal capsules with microbiome testing and dietitian consultations. Vertically integrated brands bypass health food store margin stacking through dosing platforms targeting fitness enthusiasts and paleo-diet adherents.
- Health Food Stores:Brick-and-mortar distribution enforces batch-level traceability documentation for certified organic bone meal, concentrating shelf space with processors demonstrating spectroscopic verification capabilities.
- Specialty Shops:Curated assortments serve niche segments including regenerative agriculture practitioners and raw feeding cooperatives.
- Wholesale Distributors:Bulk powder handling infrastructure serves agricultural fertilizer blenders and mass-market supplement manufacturers with volume-driven procurement.
Wholesale Distributors handle the greatest tonnage; Online Retailers are climbing the fastest.
Form:
Processing precision and packaging investment separate manufacturing economics.
- Powdered Form:Dominates bulk distribution through simplified milling operations and flexible packaging formats. Midwestern United States packing facilities supply coastal processors with transport-cost sensitivity for commodity-grade material.
- Capsule Form:Captures higher margins through encapsulation equipment and blister-pack automation serving direct-to-consumer wellness segments. Health food store and online retailer channels specify residual moisture and particle size distribution in procurement contracts.
- Granular Form:Slower-release mineral matrix serves agricultural top-dressing applications with reduced dust handling requirements.
- Liquid Form:Microground suspension technology enables water additive applications for companion animal oral care formulations.
Powdered Form maintains the largest installed base; Capsule Form shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwestern United States packing facilities concentrate raw bone supply, while coastal processors absorb transport-cost premiums. Demand fragmentation across human supplements, pet nutrition, and organic agriculture creates divergent procurement patterns by geography.
United States
Aging demographics and pet humanization drive parallel demand channels for certified organic bone meal. FDA Current Good Manufacturing Practices enforce lot-level heavy metal screening for lead and cadmium across human consumption channels. Nebraska and Iowa rendering clusters supply coastal encapsulation facilities with commodity-grade powder facing state-level specified risk material restrictions.
Germany
Regenerative agriculture practitioners and paleo-diet adherents sustain premium positioning for traceable mineral sources. EFSA novel food assessments and EU organic regulations govern entry of animal-derived calcium into dietary supplement formulations. Bavarian organic fertilizer blenders integrate dual-use bone meal across human supplement and agricultural certification tiers.
China
Domestic livestock processing generates substantial rendering feedstock for regional mineral extraction. SAMR food safety standards and GB standards for feed-grade materials constrain cross-border trade eligibility for bone-derived inputs. Shandong Peninsula rendering facilities serve both domestic agricultural markets and export-qualified supplement manufacturers.
Brazil
Expanding beef processing infrastructure creates surplus bone material for value-added refinement. ANVISA pharmaceutical-grade supplement regulations and Ministry of Agriculture fertilizer standards create dual compliance pathways. São Paulo state processors leverage proximity to port infrastructure for export-oriented organic certification.
Australia
Grass-fed cattle supply chains command premium positioning in export markets for clean-label mineral fortification. TGA therapeutic goods regulations and FSANZ food standards govern human consumption channels with distinct pathogen testing protocols. New South Wales rendering facilities concentrate near Sydney distribution hubs serving Asia-Pacific supplement distributors.
Bone Meal Supplement Market Competitive Environment
Top-tier vendors anchor integrated rendering-to-supply operations, while mid-scale processors compete on certification specialization and regional feedstock access. The vendor base stratifies across multinational agricultural conglomerates, dedicated rendering specialists, and regional organic certifiers. Three archetypes dominate: commodity-scale renderers with captive packing plant relationships, premium organic certifiers with segregated supply chains, and diversified mineral nutrition platforms with phosphate specialization. Competitive moves concentrate on backward integration into rendering assets and geographic expansion of organic certification coverage.
Within the integrated rendering tier, Darling Ingredients Inc. and Sanimax exemplify North American infrastructure scale with packing plant network proximity. ICL Group Ltd. occupies a specialist position in phosphate-derived nutrition matrices with controlled mineral bioavailability engineering. These three entities represent divergent strategic anchors: rendering-integrated supply security, certification-premium channel capture, and mineral chemistry specialization respectively.
| Leading Market Players |
|---|
| Darling Ingredients Inc. |
| OCP Group |
| ICL Group Ltd. |
| Haifa Group |
| Yara International ASA |
| Sanimax |
| Cargill Incorporated |
| Nutrien Ltd. |
| J. Grennan & Sons |
| Others |
Value Chain & Pricing Dynamics
USDA organic certification requirements gate qualified supply pools and premium-tier pricing access, forcing processors to segregate rendering vessels and batch documentation systems before capturing organic price premiums in human supplement and pet nutrition channels.
Pricing Analysis
Cost-down pressure on standard-grade bone meal accelerates because plant-based calcium substitutes from algae and lithothamnion sources compress addressable market expansion in vegan-adjacent segments. Three-tier pricing structure across premium organic, certified standard, and commodity economy levels separates processors by certification investment and spectroscopic verification capabilities. Price differentiation hinges on USDA organic batch-level traceability and residual protein specifications enforced by health food retailers. Mass-market dietary supplement manufacturers exhibit highest price sensitivity; direct-to-consumer wellness brands targeting paleo-diet adherents absorb premium tier pricing with minimal elasticity.
Supply Chain Analysis
Freight cost sensitivity shapes procurement economics as Midwestern United States packing facilities in Nebraska and Iowa supply coastal encapsulation operations with commodity-grade powder facing transport premiums. Raw material supply draws from cattle bone clusters in Midwestern packing plants, rendering feedstock from certified organic slaughterhouses, and pressure-sterilized mineral matrix inputs. Single-source vulnerability concentrates in Midwestern rendering infrastructure where state-level specified risk material bans shrink eligible raw material pools. Distribution runs through wholesale bulk powder handlers serving agricultural blenders, health food store networks enforcing traceability documentation, and direct-to-consumer subscription platforms with last-mile cold-chain requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Low-temperature calcination with real-time mineral matrix monitoring is displacing legacy pressure sterilization vessels, rewriting quality assurance protocols and capital deployment requirements across the processing tier.
For Market Incumbents: To counter plant-based calcium substitution from algae-derived and lithothamnion sources, Darling Ingredients Inc. and Sanimax should deepen backward integration into certified organic rendering assets while deploying continuous thermal processing systems that preserve mineral bioavailability through controlled calcination protocols. Captive supply of USDA organic-certified bone meal secures premium channel access against vegan-adjacent compression. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer the most penetrable entry vector for microground bone meal in companion animal oral care formulations, bundling tartar-control mineral release profiles with microbiome testing and personalized dosing platforms. Target metropolitan United States markets with established wellness-tech penetration and last-mile cold-chain infrastructure, bypassing health food store margin stacking through vertically integrated brand positioning. For Investors and Strategic Acquirers: Seven-figure calcination equipment retrofit mandates at mid-scale renderers are the leading indicator that consolidation pressure is intensifying across the processing tier. Acquisition targets should emphasize processors with spectroscopic verification capabilities and dual-use USDA organic certification bridging human supplement and agricultural fertilizer markets. Watch for state-level specified risk material ban expansions as inflection signals reshaping eligible supply pools and regional processing economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Rendering Assets | Captive USDA-certified supply secures premium tier pricing against plant-based substitution threats. |
| Continuous Thermal Processing System Deployment | Low-temperature calcination with real-time monitoring preserves mineral matrix integrity under FDA pathogen mandates. |
| Dual-Use Certification Arbitrage | USDA organic bone meal bridges human supplement and agricultural fertilizer markets across price cycles. |
| Direct-to-Consumer Subscription Platform Launch | Vertically integrated brands bypass health food store margin stacking through personalized dosing platforms. |
| Spectroscopic Verification Capability Investment | Residual moisture and particle size distribution precision rewards processors with health food retailer shelf space. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs combining primary interviews with rendering facility operations managers, health food store category buyers, veterinary formulation scientists, and organic certification auditors. FDA Current Good Manufacturing Practices guidance documents, EPA biosolid regulations, USDA organic standards, and state-level specified risk material restrictions provided regulatory boundary conditions. Bottom-up volume modeling across product type, end user, distribution channel, and form segments triangulated against top-down industry value estimates.
Data-stream reconciliation across production volume disclosures, import-export trade flows, and channel inventory patterns informed the analytical framework over the projection horizon. Segmentation dimensions modeled include organic certification tier, calcium-phosphate ratio specification, end-use application, and regional regulatory cluster. CAGRs were derived from trend extrapolation of sterilization infrastructure deployment, pet humanization trajectory indicators, and aging demographic mineral fortification demand across the analysis window. Heavy metal testing cadence requirements and calcination equipment retrofit cycles served as industry-specific forecast inputs.
The model holds under stable FDA pathogen testing mandates and USDA organic certification continuity; deviation in state-level specified risk material ban expansions or plant-based calcium technology cost curves would shift supply pool eligibility and pricing tier boundaries. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Prenatal Vitamin Supplements Market
Nutritional Supplements
Global Docosahexaenoic Acid (DHA) Market
Nutritional Supplements
Global Ashwagandha Extract Market
Nutritional Supplements
Lactoferrin Market
Nutritional Supplements
Whey Hydrolysates Market
Nutritional Supplements
Liuweidihuang Market
Nutritional Supplements
Garlic Extract Supplement Market
Nutritional Supplements
Coral Calcium Supplements Market
Nutritional Supplements
Asia-Pacific Amino Acid in Dietary Supplements Market
Nutritional Supplements
Calcium Supplements Market
Nutritional Supplements
Italy Whey Protein Market
Nutritional Supplements
Dextrose Monohydrate Market
Nutritional Supplements
North America Whey Protein Market
Nutritional Supplements
Global Reishi Mushroom Extracts Market
Nutritional Supplements
Krill Oil Supplements Market
Nutritional Supplements
Prickly Pear Seed Oil Nutricosmetic Bases Market