
 Feed Flavor Market | 2026-2036
Feed Flavor Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Flavor Market Analytics
The EU Green Deal is hardening feed ingredient standards across European livestock operations, pushing manufacturers toward cleaner-label flavor systems. Cargill leverages its integrated supply chain to secure botanical extract sources for natural flavor lines. Kerry Group anchors its position through dedicated R&D facilities focused on species-specific palatability solutions.
Feed flavors comprise concentrated aromatic compounds—typically essential oils, oleoresins, and synthetic aldehydes at inclusion rates of 0.01% to 0.5%—engineered to mask off-notes from functional additives and stimulate voluntary feed intake in production animals. Powdered flavors dominate volume shipments due to stability in premix handling, while liquid formats capture premium positioning in aquaculture applications where water dispersibility determines efficacy. Poultry operations generate the largest application share, though aquaculture represents the fastest-growing demand pool as intensive shrimp and salmon farming expands.
Regulators including the European Food Safety Authority, the U.S. Food and Drug Administration, and China's Ministry of Agriculture and Rural Affairs enforce divergent additive approval pathways that fragment product registration strategies. The EU's Feed Additives Regulation 1831/2003 demands full re-authorization for flavoring substances, while the FDA maintains generally recognized as safe exemptions for common botanicals. Stakeholders must monitor evolving maximum residue limits and novel food consultations that could recategorize emerging fermentation-derived flavor precursors.
Market Dynamics
The EU Green Deal's sustainability mandates are hardening ingredient standards across European livestock operations, forcing manufacturers to reconfigure supply chains around cleaner-label botanical extracts and fermentation-derived precursors while maintaining cost parity with conventional synthetic alternatives.
Growth Catalysts
- EU Green Deal implementation:Member states are tightening maximum residue limits for synthetic additives, redirecting procurement toward natural flavor systems that satisfy EFSA re-authorization requirements under Regulation 1831/2003.
- Integrated poultry operations in Brazil:Large-scale producers are expanding flavor-enhanced feed programs to improve feed conversion ratios and shorten production cycles in intensive broiler systems.
- Essential oil microencapsulation:Advances in spray-drying and lipid-coating technologies are extending shelf stability of volatile compounds, enabling broader premix distribution without aroma degradation.
Market Restraints
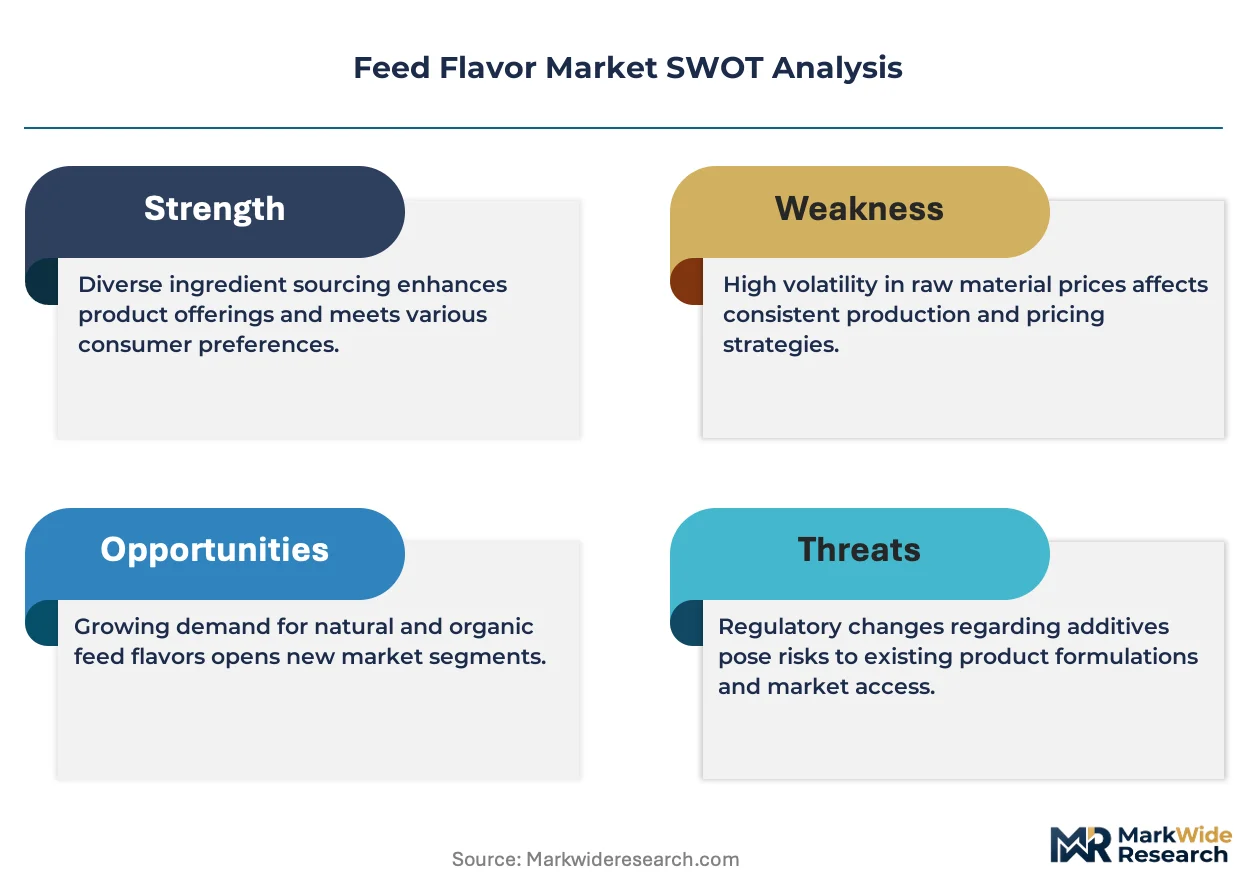
- Botanical raw material volatility:Weather-driven supply disruptions in major herb-growing regions concentrate price risk for oleoresin and essential oil feedstocks.
- Regulatory fragmentation:Divergent approval pathways between EFSA, FDA, and China's Ministry of Agriculture force manufacturers to maintain parallel registration portfolios for identical flavor compounds.
- Enzymatic masking alternatives:Feed enzyme producers are advancing bitter-blocking solutions that reduce reliance on aromatic masking agents in certain applications.
Strategic Opportunities
- Vietnamese aquaculture expansion:Intensive shrimp and pangasius farming operations present underdeveloped demand for water-dispersible liquid flavor systems that improve palatability in high-density pond environments.
- Fermentation-derived precursors:Precision fermentation platforms enable biosynthesis of aldehyde and ketone flavor compounds without agricultural land use, aligning with EU deforestation-free supply chain regulations.
- Direct-to-farm digital channels:E-procurement platforms are disintermediating traditional distributor networks, allowing flavor houses to capture margin and build direct relationships with mid-scale livestock operations.
Industry Challenges
- Species-specific formulation expertise:Shortage of palatability scientists with cross-species sensory training limits R&D throughput for emerging aquaculture and exotic livestock segments.
- Dual certification timelines:Simultaneous pursuit of organic and conventional feed additive approvals stretches regulatory affairs capacity and delays market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Flavor Market |
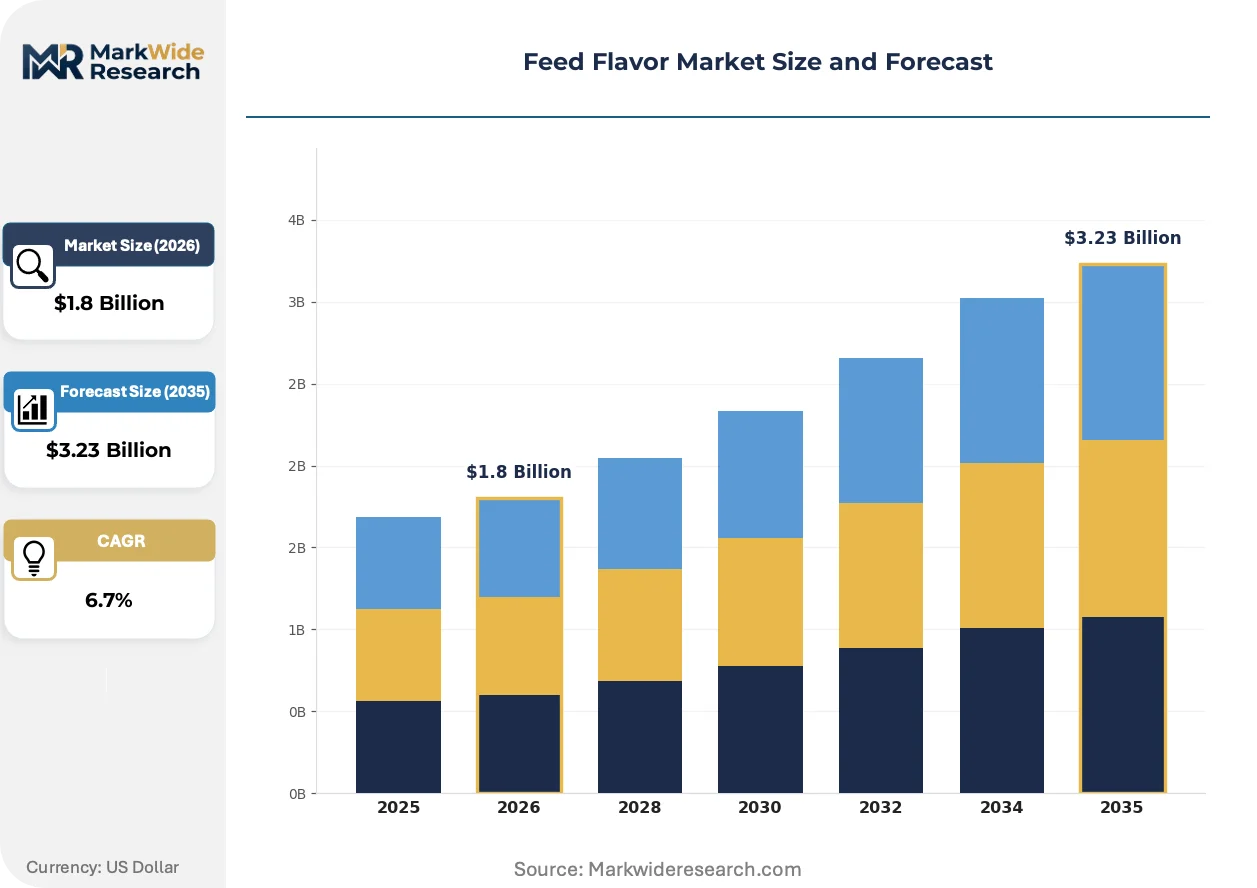
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Flavors, Powdered Flavors, Granulated Flavors, Paste Flavors Application: Poultry, Swine, Ruminants, Aquaculture Distribution Channel: Direct Sales, Distributors, Online Retail, Specialty Stores End User: Feed Manufacturers, Livestock Farmers, Aquaculture Producers, Pet Food Companies |
| Companies Covered | Cargill, Evonik Industries AG, Alltech, DuPont, Kemin Industries, Kerry Group, Givaudan, Symrise, ADM (Archer Daniels Midland), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Flavor Market Evolving Landscape
Active reformulation across the value chain is compressing development cycles as manufacturers race to match regulatory deadlines with viable natural alternatives. Three distinct vectors are reshaping competitive positioning in flavor systems.
Microencapsulation technology using modified starch and lipid bilayer coatings is electrifying stability performance for heat-sensitive terpenes and phenolic compounds. Brazilian and Vietnamese feed compounders are adopting these systems at accelerating rates for tropical storage conditions. The technology is electrifying margin structures by reducing dosage requirements and extending distribution reach into climate-stressed markets previously served by less stable liquid formats.
EFSA's 2023 updated guidance on botanical safety assessments is tightening toxicological data requirements for novel flavoring substances. Manufacturers must now submit extended 90-day feeding studies and metabolite identification packages that extend registration timelines by 18-24 months. European premix producers are responding by consolidating supplier bases toward established EFSA-approved substance lists, compressing opportunities for innovative entrants.
Livestock operations are consolidating procurement authority into centralized technical buying teams that negotiate multi-year supply agreements with volume-tiered pricing. Traditional distributor relationships are yielding to direct manufacturer contracts with embedded technical service support. This pattern is most pronounced in Denmark and the Netherlands, where cooperative farming structures aggregate purchasing across thousands of member farms.
Feed Flavor Market Segmentation
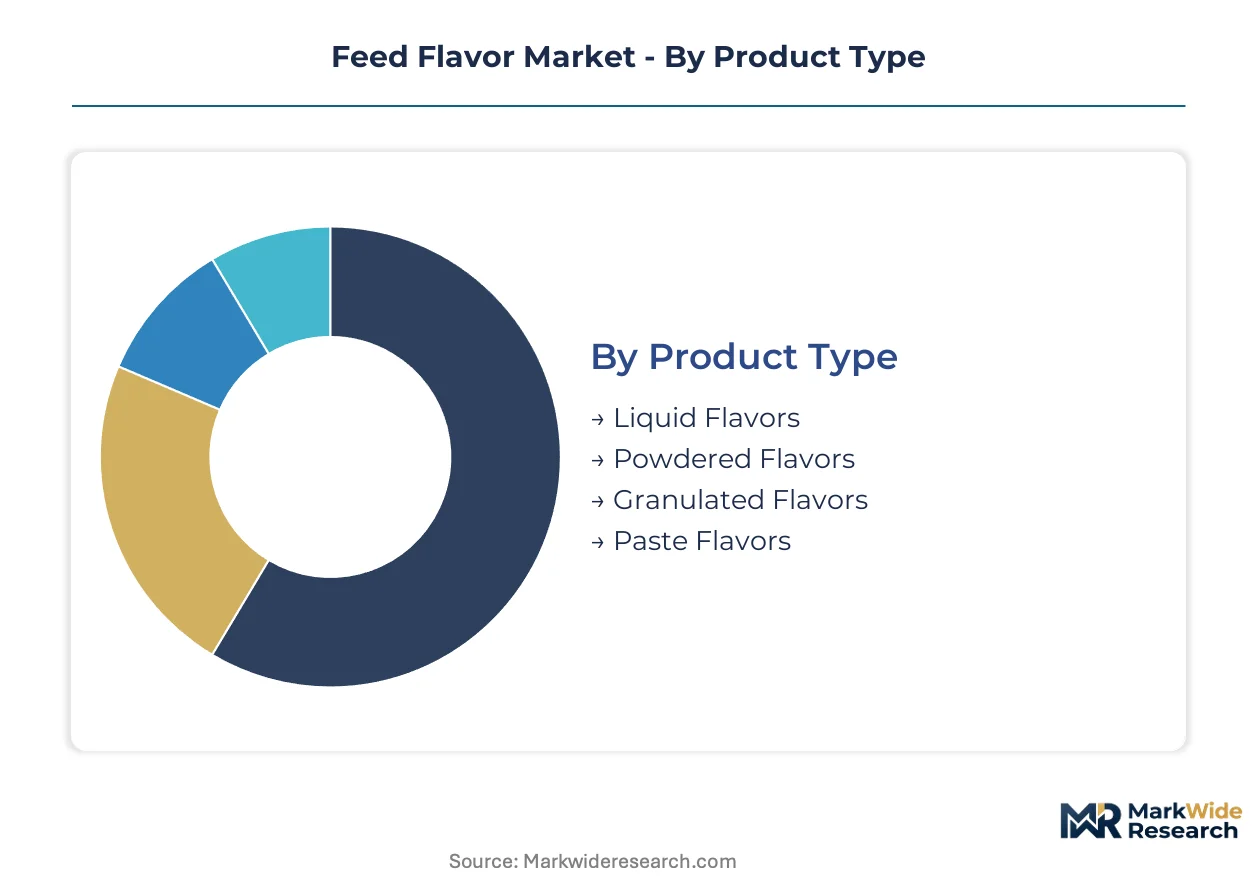
Feed flavor segmentation reflects divergent technical requirements across species physiology, processing conditions, and procurement channels. Manufacturers configure product portfolios around stability demands in premix handling, water dispersibility in aquaculture systems, and direct farm access in consolidated livestock operations.
Product Type:
Stability under thermal stress and mechanical handling during feed processing determines format selection and margin capture.
- Liquid Flavors:Water-dispersible emulsions of essential oils and oleoresins engineered for aquaculture applications where pond distribution uniformity governs efficacy. Vietnamese shrimp operations are expanding procurement of lipid-coated liquid systems to mask bitter functional additives in high-density farming environments.
- Powdered Flavors:Spray-dried microencapsulates using modified starch matrices that protect volatile terpenes through pelleting temperatures exceeding 85°C. Brazilian poultry integrators specify these formats for tropical storage stability across extended distribution networks.
- Granulated Flavors:Fluid-bed agglomerated particles offering intermediate flow properties for automated premix dosing systems.
- Paste Flavors:High-viscosity concentrates for specialized calf starter feeds and pet food palatability enhancement.
Powdered flavors lead on scale; liquid flavors lead on momentum.
Application:
Species-specific sensory thresholds and production intensity dictate formulation complexity and technical service requirements.
- Poultry:Broiler and layer operations generate the largest absolute demand volume, with flavor systems masking off-notes from coccidiostats and synthetic amino acids in high-density confinement systems. Brazilian integrated producers are standardizing flavor-enhanced feed programs to compress production cycles.
- Aquaculture:Intensive shrimp and salmon farming presents the steepest expansion trajectory, requiring water-stable formulations that maintain palatability in recirculating and pond systems where feed conversion directly determines profitability.
- Swine:Palatability solutions for nursery and grower phases addressing bitter zinc oxide and high-fiber ingredient inclusion.
- Ruminants:Protected flavor systems bypassing rumen degradation to influence post-ruminal intake behavior in dairy and beef operations.
Poultry dominates absolute volume; aquaculture climbs the fastest.
Distribution Channel:
Channel selection reflects customer scale, technical support requirements, and margin capture objectives across the value chain.
- Direct Sales:Manufacturer-to-farm contracts embedding formulation technical service and multi-year volume agreements. Danish and Dutch cooperative structures are consolidating procurement through centralized technical buying teams negotiating directly with flavor houses.
- Distributors:Regional stocking points serving mid-scale compounders with fragmented product portfolios and irregular order patterns.
- Online Retail:E-procurement platforms disintermediating traditional networks for specialty and small-batch orders from exotic livestock producers.
- Specialty Stores:Niche channels serving hobby farmers and companion animal feed compounders with premium natural positioning.
Direct sales leads on scale; online retail leads on momentum.
End User:
End-user category determines specification authority, regulatory compliance burden, and technical dialogue intensity.
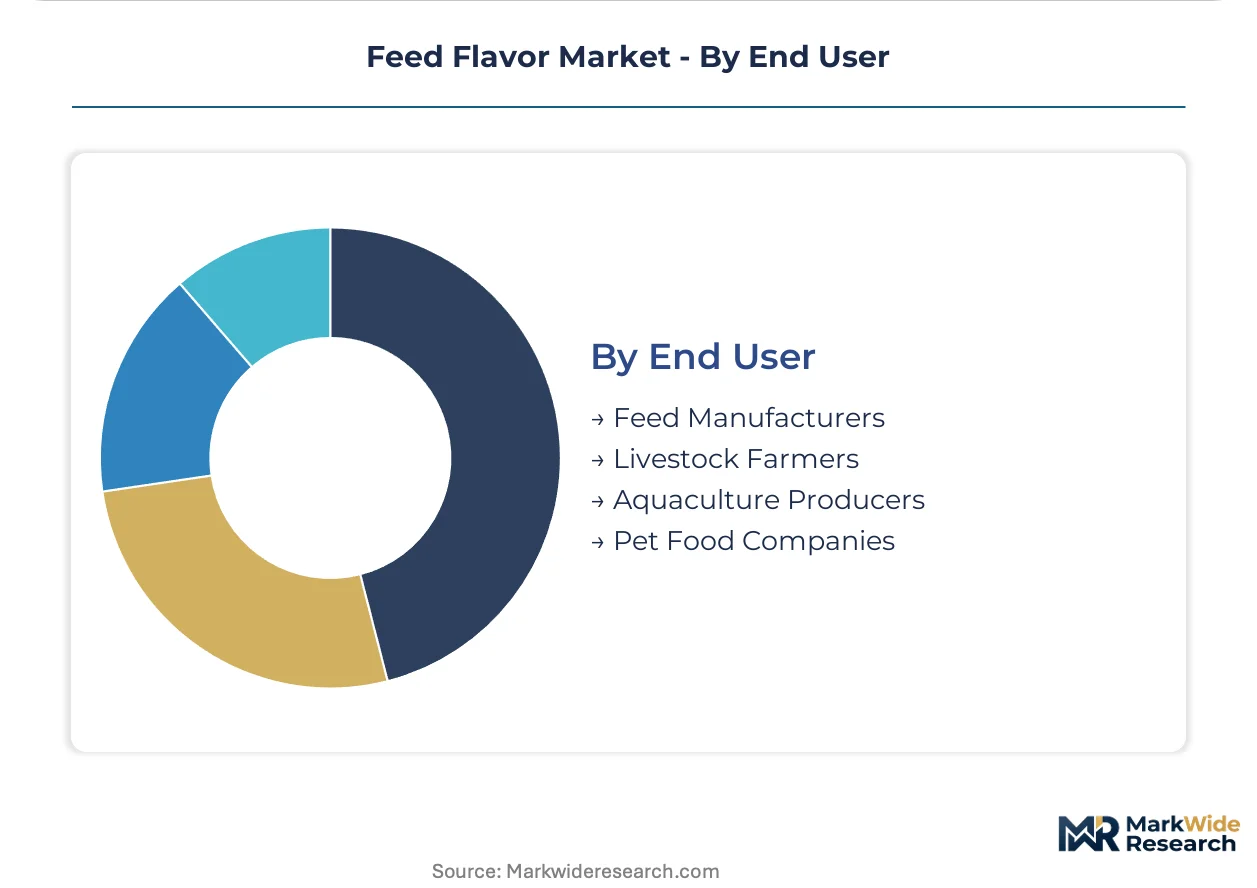
- Feed Manufacturers:Large compounders with internal quality laboratories and species-specific formulation expertise driving standardized procurement of EFSA-compliant natural flavor systems.
- Livestock Farmers:Consolidated operations in Brazil and Vietnam exercising direct sourcing authority over flavor-enhanced programs to improve feed conversion ratios.
- Aquaculture Producers:Intensive shrimp and pangasius operators in Vietnam demanding water-dispersible liquid formats with embedded technical support for pond management integration.
- Pet Food Companies:Premium positioning segment requiring human-grade palatability standards and clean-label botanical positioning for consumer-facing packaging claims.
Feed manufacturers lead on scale; aquaculture producers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized palatability scientists and feed formulation chemists cluster in Brazil, the Netherlands, and Vietnam, anchoring technical service capabilities for species-specific flavor development across poultry, aquaculture, and swine operations.
Brazil
Integrated poultry giants in São Paulo and Paraná states are standardizing flavor-enhanced feed programs to compress broiler production cycles and improve feed conversion ratios. ANVISA enforces additive registration requirements that align with Mercosur harmonization protocols. Campinas anchors the country's largest concentration of feed research facilities serving tropical storage stability needs.
Netherlands
Dutch cooperative farming structures aggregate procurement across thousands of member farms, consolidating technical buying authority into centralized teams negotiating direct manufacturer contracts. The EU Green Deal's deforestation-free supply chain regulations redirect sourcing toward fermentation-derived flavor precursors. Wageningen hosts Europe's densest cluster of feed science research institutions partnering with flavor houses on species-specific solutions.
United States
Midwestern feed compounders in Iowa and Illinois are expanding natural flavor procurement to mask off-notes from high-inclusion functional additives in swine and poultry diets. The FDA maintains generally recognized as safe exemptions for common botanicals, streamlining approval pathways compared to European counterparts. Sioux Falls and Des Moines concentrate the largest feed manufacturing capacity serving integrated livestock operations.
Vietnam
Intensive shrimp and pangasius producers in the Mekong Delta are adopting water-dispersible liquid flavor systems to improve palatability in high-density pond environments. The Ministry of Agriculture and Rural Affairs enforces divergent additive approval pathways that require parallel registration strategies for imported flavor compounds. Cần Thơ anchors the country's aquaculture feed formulation expertise with technical service hubs supporting pond management integration.
Germany
Bavarian and Lower Saxon compounders are consolidating supplier bases toward established EFSA-approved substance lists following tightened toxicological data requirements. EFSA's 2023 updated guidance on botanical safety assessments extends registration timelines for novel flavoring substances. Kassel and Hanover concentrate premix manufacturing operations serving cooperative dairy and swine structures across northern Europe.
Feed Flavor Market Competitive Landscape
Capital-heavy producers with integrated supply chains compete with asset-light specialists focused on species-specific formulation expertise, creating a tiered structure where scale advantages in raw material sourcing confront agility in technical service delivery. The vendor base separates into three archetypes: diversified agricultural conglomerates with captive botanical extraction capabilities, dedicated flavor houses with fermentation technology platforms, and regional compounders with embedded palatability laboratories. Dominant competitive moves include backward integration into oleoresin and essential oil feedstocks, plus geographic expansion through direct-to-farm digital channels disintermediating traditional distributor networks.
Among diversified agricultural conglomerates, Cargill and ADM represent the integrated supply chain archetype, leveraging upstream control over botanical extract sources to secure cost positions in natural flavor lines. Kerry Group and Givaudan occupy positions within the dedicated flavor house tier, anchoring R&D-intensive capabilities in species-specific palatability solutions. Evonik Industries AG exemplifies the specialty chemical player archetype, bridging feed additive and flavor precursor technologies through precision fermentation platforms.
| Leading Market Players |
|---|
| Cargill |
| Evonik Industries AG |
| Alltech |
| DuPont |
| Kemin Industries |
| Kerry Group |
| Givaudan |
| Symrise |
| ADM (Archer Daniels Midland) |
| Others |
Value Network & Pricing Analysis
Integrated poultry operations in Brazil and cooperative farming structures in the Netherlands concentrate procurement authority into centralized technical buying teams that negotiate multi-year supply agreements with volume-tiered pricing, compressing margin capture for flavor houses serving fragmented mid-scale compounders.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified natural flavor systems from conventional synthetic alternatives and unbranded commodity botanicals. Price differentiation hinges on certification grade under Regulation 1831/2003 and volume scale in direct manufacturer contracts. Cost compression in economy-tier synthetic flavors is intensifying because Brazilian integrators are standardizing procurement around natural systems. Mid-scale feed compounders exhibit highest price sensitivity; Dutch cooperative structures demonstrate lowest due to aggregated purchasing power.
Supply Chain Analysis
Regional distribution centers in Campinas, Wageningen, and Cần Thơ anchor hub-and-spoke patterns serving tropical and temperate storage zones with differentiated stability requirements. Raw material sourcing draws from Indian oleoresin processors, Indonesian essential oil distillers, and Brazilian botanical extractors. Single-source vulnerability concentrates in weather-dependent herb harvests for terpene feedstocks. Distribution runs through direct-to-farm digital channels disintermediating traditional distributor networks in consolidated livestock operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EFSA's 2023 updated guidance on botanical safety assessments extends registration timelines and redirects procurement toward established approved substance lists.
For Market Incumbents: Lock in supplier consolidation advantages by accelerating backward integration into oleoresin and essential oil feedstocks before weather-driven price volatility intensifies. Secure multi-year direct contracts with Brazilian integrated poultry operations to preempt enzymatic masking alternatives from displacing aromatic solutions in broiler systems. For New Entrants and Emerging Players: Vietnamese aquaculture distributors represent the most penetrable channel partner type for water-dispersible liquid flavor systems in high-density shrimp and pangasius operations. Target fermentation-derived precursor platforms to bypass agricultural land-use constraints under EU deforestation-free regulations. Lead with embedded technical service support for pond management integration as the primary go-to-market angle. For Investors and Strategic Acquirers: Diversified agricultural conglomerates with captive botanical extraction capabilities are the most active acquirer in this space, seeking to secure cost positions in natural flavor lines. The acquisition target archetype centers on precision fermentation platforms enabling biosynthesis of aldehyde compounds without agricultural feedstocks. Watch EFSA novel food consultations on fermentation-derived precursors as the inflection indicator for recategorized ingredient classifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Botanical Feedstocks | Cargill leverages upstream control over Indian oleoresin sources to secure natural flavor cost positions. |
| Precision Fermentation Platform Investment | Evonik bridges feed additive and flavor precursor technologies through biosynthesis without agricultural land use. |
| Direct-to-Farm Digital Channel Expansion | E-procurement platforms disintermediate distributor networks and capture margin from mid-scale livestock operations. |
| Species-Specific R&D Facility Establishment | Kerry Group anchors technical service capabilities through dedicated palatability laboratories in Wageningen. |
| EFSA Re-Authorization Compliance Investment | European premix producers consolidate supplier bases toward established approved substance lists under tightened toxicological requirements. |
Research Methodology
Bottom-up livestock farmer and aquaculture producer modeling reconciled against top-down botanical extract and fermentation precursor tracking forms the analytical core of this study. Primary interviews with feed formulation chemists, palatability scientists, procurement leads at integrated poultry operations, regulatory affairs specialists, and technical service directors combined with secondary validation from EFSA guidance documents, FDA GRAS notices, ANVISA registration databases, and customs trade data on essential oil imports.
Historical trendline analysis of flavor system adoption rates across poultry, aquaculture, swine, and ruminant segments informed projection frameworks over the analysis window. Segmentation dimensions modeled include product format stability requirements, species-specific sensory thresholds, distribution channel technical service intensity, and end-user specification authority. CAGRs were derived from elasticity-adjusted penetration curves incorporating EU Green Deal implementation timelines and Brazilian integrator standardization patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA metabolite identification requirements, fermentation platform scale-up economics, and weather-driven botanical raw material disruptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Agricultural Surfactants Market
Agricultural Chemicals
Auxin Substitutes Market
Agricultural Chemicals
Argentina Feed Additives Market
Agricultural Chemicals
Strobilurin Fungicide Market
Agricultural Chemicals
Berry Greenhouse Premium Micronutrient Package Market
Agricultural Chemicals
Global Agricultural Colorants Market
Agricultural Chemicals
Artificial Humus Market
Agricultural Chemicals
Middle East and Africa Agricultural Pheromones Market
Agricultural Chemicals
US Home and Garden Fungicides Market
Agricultural Chemicals
Middle East Feed Enzymes Market
Agricultural Chemicals
Africa Feed Antioxidants Market
Agricultural Chemicals
Europe Silage Additives Market
Agricultural Chemicals
Agricultural Insect Pheromones Market
Agricultural Chemicals
Global Agricultural Micronutrients Market
Agricultural Chemicals
China Herbicide Market
Agricultural Chemicals
Global Fertigation and Chemigation Market