
 Prescription Transdermal Patches Market | 2026-2036
Prescription Transdermal Patches Market Size, Share, and Industry Trends Forecast 2026-2036
Prescription Transdermal Patches Market Analytics
Home care patients are rotating toward self-administered transdermal therapies as hospital-based delivery faces cost containment pressures. Teva Pharmaceutical Industries leverages its generic portfolio to compete on price in pain management patches across North American retail pharmacies. Hisamitsu Pharmaceutical anchors its position through sustained R&D investment in adhesive polymer science, while Johnson & Johnson differentiates via brand strength in nicotine cessation and hormonal therapy channels.
Prescription transdermal patches are adhesive dosage forms that deliver active pharmaceutical ingredients through intact skin into systemic circulation, typically incorporating multi-layer laminates of backing film, drug reservoir or matrix, release liner, and pressure-sensitive adhesive with controlled permeation rates measured in micrograms per hour. Their primary commercial purpose centers on maintaining steady plasma drug concentrations over 24- to 72-hour wear periods, improving patient compliance versus oral regimens in chronic conditions. Pain management patches occupy the largest revenue pool given fentanyl and lidocaine demand, while hormonal regulation patches represent the fastest-growing therapy area driven by menopause management and testosterone replacement protocols. Continuous delivery methods dominate manufacturing scale, though pulsatile systems are gaining technical investment for chronotherapeutic applications in cardiovascular segments.
FDA bioequivalence standards and EMA adhesion testing protocols shape product development timelines and market access barriers for new patch entrants. The EPA and OSHA frameworks govern solvent handling in adhesive coating operations, adding compliance costs that favor manufacturers with captive supply chains. Japan's PMDA maintains distinct skin irritation testing requirements that create regional specialization pressures. Stakeholders must monitor evolving pharmacovigilance rules for opioid-containing patches and decide on regional manufacturing footprints before bioequivalence study designs lock in.
Market Dynamics
FDA bioequivalence tightening and EMA adhesion testing mandates are compressing product development timelines while favoring manufacturers with captive polymer supply chains and established pharmacovigilance infrastructure.
Growth Catalysts
- Home care migration:Chronic disease patients in the United States and Germany are abandoning clinic-based administration for self-applied fentanyl and hormone replacement patches, reducing systemic cost burdens.
- REACH polymer innovation:ECHA-compliant pressure-sensitive adhesive formulations are enabling 72-hour wear periods with reduced skin irritation incidence versus legacy acrylic systems.
- Aging demographics:Japan's 65-plus population concentration sustains demand for pain management and cardiovascular patch therapies requiring minimal caregiver intervention.
Market Restraints
- API supply concentration:Fentanyl precursor manufacturing concentrates in Chinese chemical parks, exposing patch producers to export license volatility and tariff friction.
- Silicone adhesive cost volatility:Medical-grade silicone raw material prices fluctuate with electronics sector demand, compressing margins for matrix-type patch manufacturers.
- Skin permeation ceiling:The 500 Dalton molecular weight barrier excludes large-molecule biologics from transdermal delivery, limiting therapeutic expansion beyond small-molecule drugs.
Strategic Opportunities
- Chronotherapeutic pulsatile systems:Cardiovascular patch segments in Germany are piloting circadian-release nicotine and nitroglycerin formulations for morning heart attack prevention.
- PMDA regulatory alignment:Harmonized skin irritation testing protocols between Japan and selected ASEAN markets are reducing duplicate clinical costs for patch exporters.
- Direct-to-patient pharmacy channels:United States retail chains are building specialized transdermal dispensing infrastructure with pharmacist counseling for opioid patch initiation.
Industry Challenges
- Adhesion science talent scarcity:Formulation chemists with expertise in pressure-sensitive polymer rheology command premium compensation, constraining mid-tier manufacturer R&D expansion.
- Bioequivalence study capex:FDA-mandated adhesive performance and residual drug testing add twelve to eighteen months and substantial clinical trial costs to generic patch approvals.
- Legacy coating equipment retrofit:Solvent-based adhesive deposition lines require EPA-compliant emission control upgrades that smaller contract manufacturers cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prescription Transdermal Patches Market |
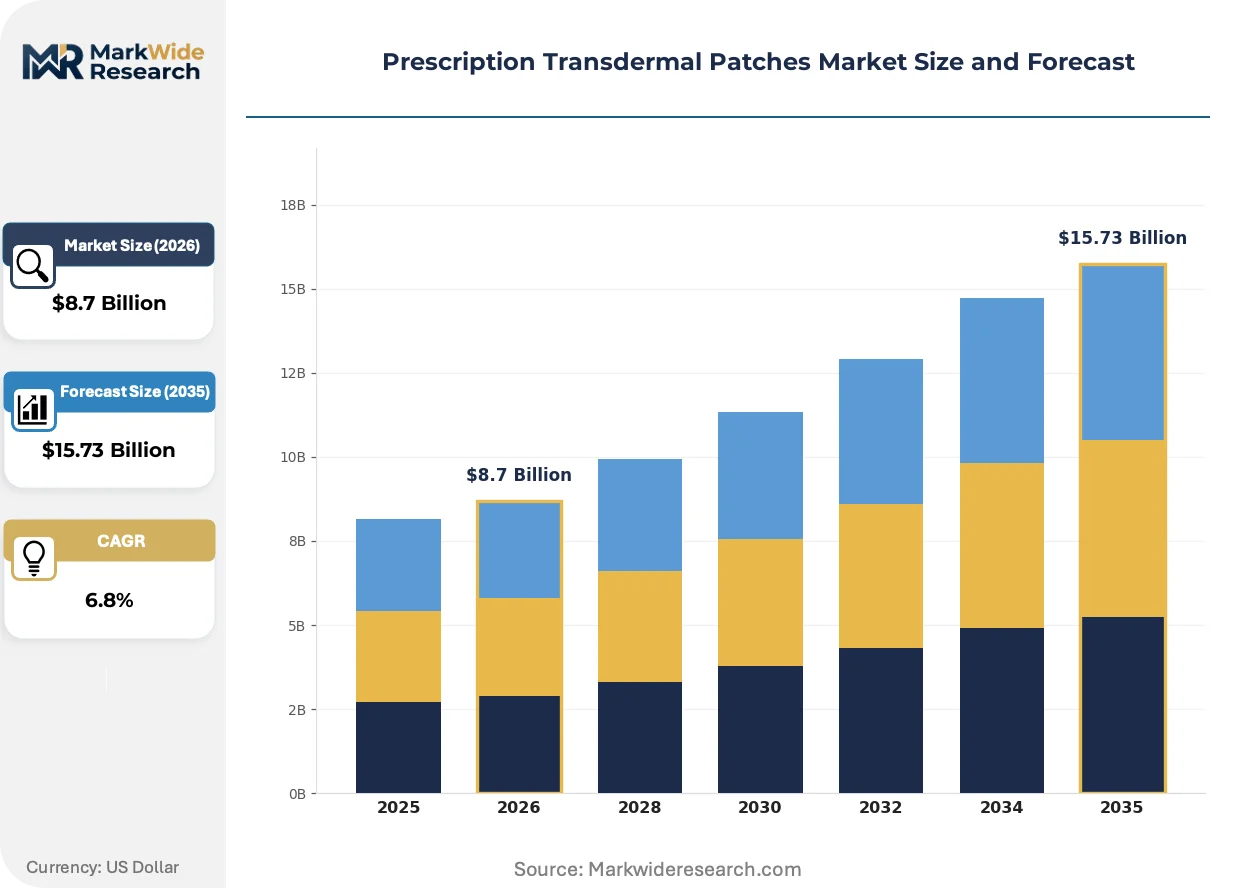
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nicotine Patches, Hormonal Patches, Pain Management Patches, Fentanyl Patches Therapy Area: Cardiovascular, Neurological, Hormonal Regulation, Pain Relief End User: Hospitals, Clinics, Home Care, Pharmacies Delivery Method: Continuous, Pulsatile, On-Demand, Combination |
| Companies Covered | Teva Pharmaceutical Industries Ltd, Novartis AG, Johnson & Johnson, Viatris Inc, Hisamitsu Pharmaceutical Co., Inc, Teikoku Pharma USA Inc., Luye Pharma Group, Purdue Pharma LP, Endo International Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prescription Transdermal Patches Market Evolving Landscape
Active pharmaceutical ingredient microencapsulation and iontophoretic enhancement are redefining permeation control, while regulatory convergence around skin safety testing is reshaping competitive entry barriers.
Silicone-based pressure-sensitive adhesives are displacing traditional acrylic systems in hormone replacement and pain management patches due to superior moisture vapor transmission and reduced cold-flow adhesion failure. German and Japanese patch manufacturers are converting coating lines to two-part silicone technology at accelerated capital deployment schedules. This material transition is displacing commodity acrylic suppliers from premium chronic therapy segments and consolidating formulation expertise among polymer science specialists with captive silicone polymerization capabilities.
EMA's 2023 updated guidance on in-vitro permeation testing and FDA's tightened bioequivalence standards for fentanyl patches are extending generic approval timelines by mandating comparative adhesion performance under heat and humidity stress. European contract research organizations are building specialized skin model testing capacity to serve patch developers seeking streamlined multi-jurisdiction submissions. Pain management and hormonal therapy categories face the steepest compliance cost escalation, driving consolidation among manufacturers with established pharmacovigilance databases and regulatory affairs infrastructure.
Hospital procurement committees in the United States are unbundling transdermal patch purchasing from broader anesthesia and pain service contracts, enabling direct price negotiation with manufacturers for fentanyl and lidocaine formulations. This purchasing autonomy is compressing distributor margins and rewarding patch producers with dedicated hospital sales forces and real-world adherence data packages. The shift is most pronounced in integrated delivery networks across the Midwest and Southeast, where pharmacy benefit managers are building therapeutic substitution protocols favoring patch-based opioid regimens with lower abuse potential profiles.
Prescription Transdermal Patches Market Segmentation
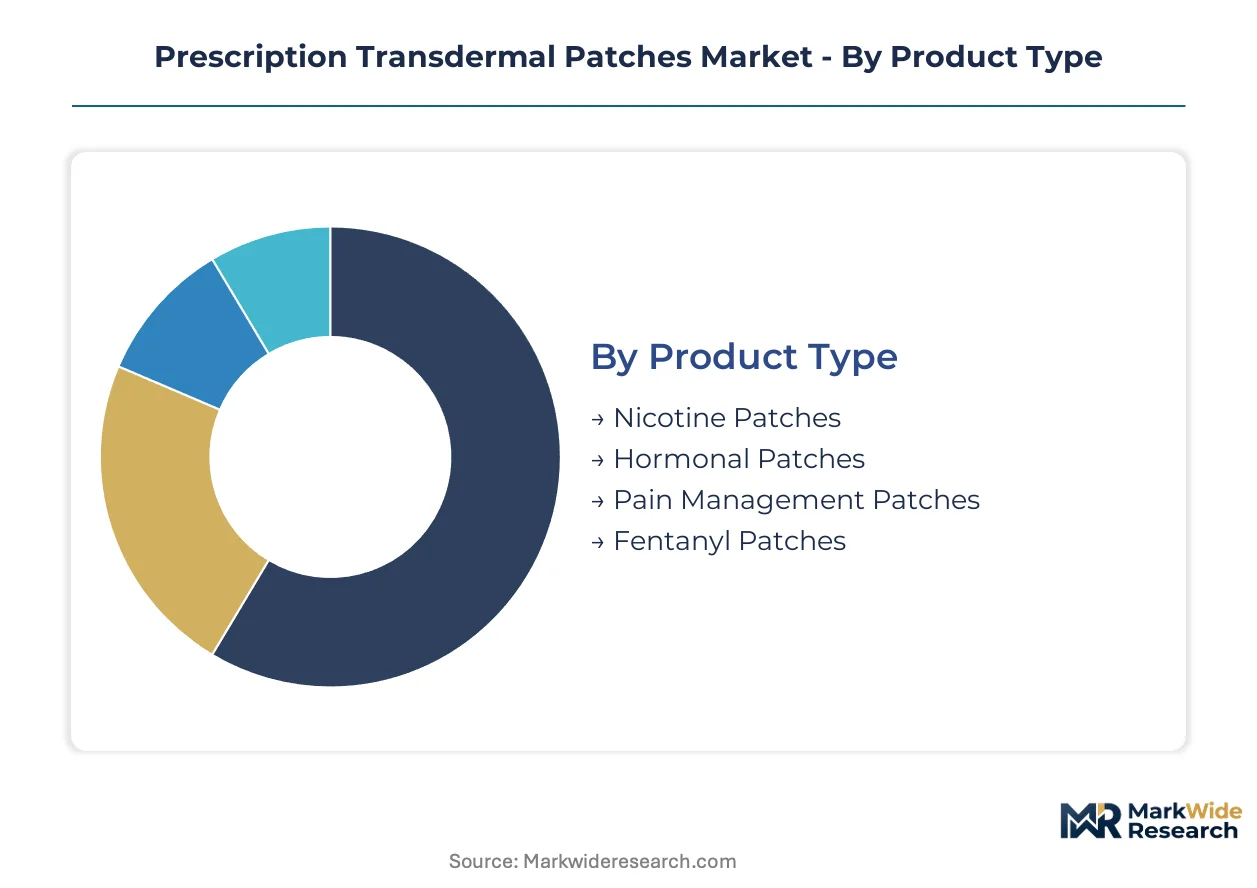
Transdermal patch manufacturers align production capacity with distinct channel requirements. Hospital procurement favors high-unit pain management formats, while retail pharmacy networks prioritize patient-applied hormonal and nicotine cessation products.
Product Type:
Channel distribution varies sharply across product categories, with institutional buyers dominating opioid-containing formats and direct-to-consumer channels driving lifestyle therapy patches.
- Pain Management Patches:Lidocaine and buprenorphine matrix formulations serve post-surgical and chronic neuropathy patients through hospital formularies and specialty pharmacy networks. United States integrated delivery networks in the Midwest and Southeast are unbundling patch procurement from anesthesia contracts, enabling direct manufacturer negotiation.
- Hormonal Patches:Estradiol and testosterone reservoir systems incorporate silicone pressure-sensitive adhesives for 72-hour wear in menopause management and hypogonadism treatment. German retail pharmacies are building dedicated counseling infrastructure for self-administered hormone replacement initiation.
- Nicotine Patches:Matrix-type dosage forms deliver controlled nicotine plasma levels for smoking cessation protocols through over-the-counter and prescription channels.
- Fentanyl Patches:Reservoir construction with rate-controlling membranes maintains steady opioid delivery for breakthrough cancer pain in palliative care settings.
By volume, pain management patches lead. By growth pace, hormonal patches are climbing the fastest.
Therapy Area:
Application-specific formulation requirements drive cost tier differentiation, with cardiovascular and neurological segments commanding premium pricing for specialized chronotherapeutic engineering.
- Pain Relief:Multi-day wear fentanyl and lidocaine systems dominate institutional purchasing through their abuse-deterrent profiles and reduced caregiver burden compared to oral opioid regimens.
- Hormonal Regulation:Menopause management and testosterone replacement protocols are expanding most quickly as aging populations seek alternatives to oral hormone therapies with first-pass hepatic effects.
- Cardiovascular:Nitroglycerin patches for angina prophylaxis and experimental chronotherapeutic formulations target morning cardiovascular events through circadian release timing.
- Neurological:Rivastigmine and rotigotine patches for Parkinson's disease and Alzheimer's dementia require precise dose titration and skin irritation mitigation through polymer selection.
Pain relief generates the highest absolute revenue. Hormonal regulation shows the steepest expansion trajectory.
End User:
Customer type determines packaging, counseling requirements, and reimbursement pathways, with home care migration reshaping demand concentration toward patient-applied formats.
- Home Care:Self-administered fentanyl and hormone patches reduce systemic healthcare costs while requiring pharmacist counseling infrastructure and real-world adherence monitoring programs.
- Hospitals:Acute care settings prioritize abuse-resistant opioid patches with integrated delivery network procurement autonomy and therapeutic substitution protocols favoring transdermal over oral regimens.
- Clinics:Outpatient pain management and endocrinology practices serve as initiation points for patch therapy with follow-up adherence assessment.
- Pharmacies:Retail dispensing channels are building specialized transdermal infrastructure with cold chain capabilities and patient education protocols for hormone replacement products.
By patient volume, home care leads. By infrastructure investment pace, pharmacies are gaining share fastest.
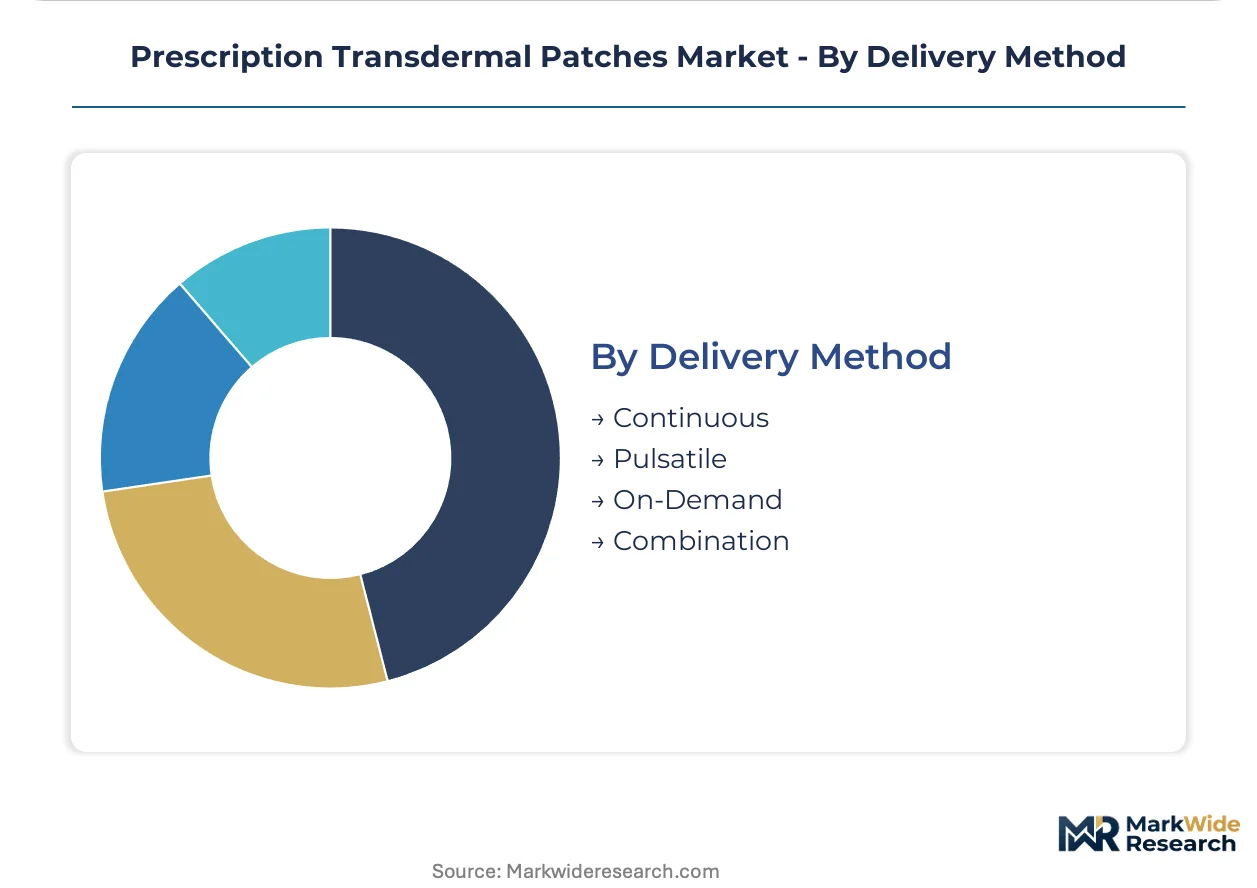
Delivery Method:
Manufacturing scale and technical maturity separate continuous systems from emerging pulsatile and on-demand architectures requiring advanced polymer engineering.
- Continuous:Zero-order kinetics through rate-controlling membranes or matrix diffusion dominate commercial production with established FDA bioequivalence pathways and validated coating line infrastructure.
- Pulsatile:Chronotherapeutic release systems for cardiovascular morning dosing are piloting in German research hospitals with circadian-aligned nitroglycerin and nicotine formulations.
- On-Demand:Patient-activated iontophoretic or thermal trigger mechanisms remain developmental for breakthrough pain and rescue dosing scenarios.
- Combination:Hybrid reservoir-matrix architectures integrate immediate-release and extended-release compartments for complex therapeutic profiles.
Continuous systems dominate manufacturing scale. Pulsatile methods show the most rapid technical investment acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German patch manufacturers export silicone adhesive formulations to Japanese pharmaceutical converters, establishing a trans-Atlantic-Asia technical corridor that shapes regional specialization patterns.
United States
Integrated delivery networks in the Midwest and Southeast unbundle patch procurement from anesthesia contracts, enabling direct manufacturer negotiation for fentanyl and lidocaine formats. FDA bioequivalence tightening for generic opioid patches extends approval timelines and favors established pharmacovigilance infrastructure. The Boston-Cambridge corridor anchors specialized contract research organizations building skin model testing capacity for multi-jurisdiction submissions.
Germany
German retail pharmacies construct dedicated counseling infrastructure for self-administered hormone replacement initiation, accelerating home care migration. ECHA REACH compliance for pressure-sensitive adhesive formulations enables 72-hour wear periods with reduced skin irritation versus legacy systems. The Rhine-Ruhr industrial cluster concentrates coating line conversion to two-part silicone technology at accelerated capital deployment schedules.
Japan
Japan's 65-plus population concentration sustains demand for pain management and cardiovascular patch therapies requiring minimal caregiver intervention. PMDA maintains distinct skin irritation testing requirements that create regional specialization pressures for exporters. The Kansai region around Osaka anchors Hisamitsu Pharmaceutical's sustained R&D investment in adhesive polymer science.
China
Fentanyl precursor manufacturing concentrates in Chinese chemical parks, exposing patch producers to export license volatility and tariff friction. The national pharmaceutical regulator enforces dual-use chemical controls on opioid API shipments that shape supply security planning. The Yangtze River Delta cluster houses contract manufacturers serving both domestic chronic therapy demand and export formulation finishing.
United Kingdom
London-based pharmacy benefit managers build therapeutic substitution protocols favoring patch-based opioid regimens with lower abuse potential profiles. MHRA alignment with EMA bioequivalence standards streamlines generic approval pathways for matrix-type formulations. The Southeast England corridor concentrates specialized transdermal dispensing infrastructure with cold chain capabilities for hormone replacement products.
Prescription Transdermal Patches Market Competitive Landscape
Listed leaders compete with private specialists across polymer science capabilities and regulatory infrastructure depth. The market structures around three tiers: multinational pharmaceutical conglomerates with diversified dosage form portfolios, mid-cap patch specialists with captive adhesive supply chains, and regional contract manufacturers serving local hospital formularies. Consolidation pressures favor players with established FDA and EMA pharmacovigilance databases. Dominant competitive moves include strategic partnerships for silicone polymerization capacity and geographic expansion through specialized hospital sales forces.
Among Israel-based generic specialists, Teva Pharmaceutical Industries occupies a position representing price-competitive volume strategies across North American retail pharmacy channels. Japanese specialists exemplify polymer science depth, with Hisamitsu Pharmaceutical anchoring sustained R&D investment in adhesive formulation. Johnson & Johnson sits within the brand-differentiated tier, representing channel strength in nicotine cessation and hormonal therapy segments.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd |
| Novartis AG |
| Johnson & Johnson |
| Viatris Inc |
| Hisamitsu Pharmaceutical Co., Inc |
| Teikoku Pharma USA Inc. |
| Luye Pharma Group |
| Purdue Pharma LP |
| Endo International Plc |
| Others |
Value Network & Pricing Analysis
Ninety-day silicone adhesive inventory cycles concentrate pricing power among German and Japanese manufacturers with captive polymerization capacity, while spot-market buyers in contract manufacturing face margin compression from electronics-sector demand spikes. This lead-time stratification separates multinationals with backward-integrated adhesive supply from mid-tier patch producers exposed to medical-grade silicone cost volatility.
Pricing Analysis
Three-generation pricing stratification separates legacy acrylic-matrix patches from silicone-adhesive premium tiers and developmental iontophoretic systems. Premium reservoir constructions with rate-controlling membranes command higher unit economics through FDA bioequivalence certification and 72-hour wear claims, while generic matrix formulations compete on pharmacy benefit manager tenders. Pricing pressure intensifies in fentanyl categories as integrated delivery networks unbundle procurement from anesthesia contracts and negotiate direct manufacturer agreements. Hospital procurement committees show highest price sensitivity for chronic pain indications, whereas endocrinology clinics accept premium positioning for hormone replacement patches with adherence monitoring bundling.
Supply Chain Analysis
Strategic stockpiling of fentanyl precursors dominates supply chain risk management given dual-use chemical export controls, while just-in-time silicone monomer delivery feeds coating line operations in the Rhine-Ruhr and Kansai industrial clusters. API manufacturing concentrates in Chinese chemical parks, Japanese specialty chemical producers, and Indian contract synthesis facilities. Raw material dependencies span medical-grade silicone polymers, acrylic adhesive resins, and polyester backing films. Single-source vulnerability in fentanyl precursor licensing creates supply security exposure for North American patch producers. Distribution runs through specialized pharmaceutical wholesalers with cold chain capabilities and direct-to-hospital contracting infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prescription transdermal patch markets fragment across adhesive technology generations and regional regulatory clusters, with home care migration creating specialist niches for patient adherence services and pharmacy counseling infrastructure.
For Market Incumbents: Fortify pharmacovigilance databases and silicone polymerization capacity against generic entrants facing extended FDA bioequivalence timelines. Invest in captive adhesive supply chains to offset medical-grade silicone price volatility from electronics sector demand. Prioritize hospital sales force expansion in Midwest and Southeast integrated delivery networks where procurement unbundling favors established abuse-deterrent patch portfolios. For New Entrants and Emerging Players: FDA 505(b)(2) regulatory pathways offer accelerated entry for reformulated adhesive platforms with improved skin irritation profiles. Target German retail pharmacy counseling infrastructure for self-administered hormone replacement initiation, where patient education requirements create service-based differentiation. Pursue chronotherapeutic cardiovascular segments in research hospital pilot programs as a technical credibility building block. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because bioequivalence study capex and pharmacovigilance infrastructure requirements favor scaled participants with regulatory databases. Acquisition targets should demonstrate captive silicone polymerization or specialized skin model testing capabilities. Watch PMDA-EMA regulatory harmonization progress as the signal indicating reduced duplicate clinical costs and accelerated multi-jurisdiction market access.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Adhesive Capacity Expansion | Rhine-Ruhr coating line conversions to two-part silicone technology displace legacy acrylic suppliers from premium chronic therapy segments. |
| Hospital System Direct Contracting | Midwest and Southeast integrated delivery network procurement autonomy enables therapeutic substitution protocols favoring patch-based opioid regimens. |
| Chronotherapeutic Patch Development | German research hospital pilots of circadian-release nitroglycerin formulations establish technical credibility for cardiovascular morning dosing applications. |
| Regulatory Affairs Infrastructure Buildout | EMA bioequivalence and PMDA skin irritation testing alignment reduces duplicate clinical costs for patch exporters seeking multi-jurisdiction approvals. |
| Patient Adherence Monitoring Programs | Home care migration creates service-based differentiation through real-world adherence data packages supporting pharmacy benefit manager negotiations. |
Research Methodology
A standing panel of adhesive formulation chemists, regulatory affairs directors at patch manufacturers, hospital pharmacy procurement managers, and retail pharmacy chain clinical specialists provided ongoing calibration throughout data collection. Primary interviews with these stakeholders combined with secondary validation against FDA bioequivalence submission databases, EMA scientific advice protocols, PMDA consultation minutes, and hospital formulary databases. Bottom-up patient volume estimates by therapy area triangulated against top-down manufacturer capacity assessments across continuous, pulsatile, and on-demand delivery methods.
Consistency checks validated volume and value outputs against external benchmarks including adhesive raw material consumption patterns, pharmaceutical wholesale distribution records, and regulatory approval timelines. The analytical framework modeled segmentation dimensions spanning product type, therapy area, end user, and delivery method across the projection horizon. CAGRs derived from patient population growth, chronic disease prevalence trends, and home care migration patterns. Forecast inputs incorporated silicone adhesive technology conversion rates, bioequivalence study completion timelines, and hospital procurement unbundling velocity.
Decision-makers should treat outputs as directional under assumptions of sustained FDA bioequivalence tightening and stable fentanyl precursor export licensing; material deviation in either would warrant model refresh. Specific risk factors include tariff friction on Chinese API shipments, REACH polymer compliance cost escalation, and opioid patch pharmacovigilance rule changes. Revision becomes warranted when silicone raw material price volatility crosses thresholds that compress mid-tier manufacturer margins beyond coating line retrofit financing capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Hydroxychloroquine Market
Pharmaceuticals
Canagliflozin Market
Pharmaceuticals
Epigenetics Drugs and Diagnostic Technologies Market
Pharmaceuticals
Throat Sprays Market
Pharmaceuticals
Iron Deficiency Injectables Market
Pharmaceuticals
Angiopoietin Inhibitors Therapeutic Market
Pharmaceuticals
Exocrine Pancreatic Insufficiency Therapeutics Market
Pharmaceuticals
Global Divalproex Sodium Market
Pharmaceuticals
Global Anti-Suicide Drugs Market
Pharmaceuticals
Denmark Pharmaceutical Market
Pharmaceuticals
Cardiometabolic Drugs Market
Pharmaceuticals
Hypertensive Emergency Medications Market
Pharmaceuticals
Global Erythropoietin Stimulating Agents Market
Pharmaceuticals
Global Aminoglycosides Market
Pharmaceuticals
Japan Pharmaceutical 3PL Market
Pharmaceuticals
Hospital Pharmaceuticals Market