
 Metal Fabrication Service Market | 2026-2036
Metal Fabrication Service Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Fabrication Service Market Intelligence
Modular fabrication bundles is expanding across industrial procurement, letting buyers mix cutting, welding, and assembly under single-source contracts rather than sourcing each service separately. O'Neal Manufacturing Services leverages its multi-process footprint to anchor long-term agreements with heavy equipment OEMs. BTD Manufacturing competes through precision stamping and weldment integration across Midwest production corridors. Mayville Engineering Company, Inc. differentiates via its employee-ownership model, sustaining workforce retention in tight labor markets.
Metal fabrication services encompass the cutting, forming, joining, and finishing of raw metal stock into engineered components, typically performed to tolerances ranging from ±0.005 inch for precision work to ±1/16 inch for structural applications, serving as the backbone of capital goods manufacturing. Cutting and welding command the largest share of service revenue due to their ubiquity across construction and energy infrastructure, while machining and titanium-oriented work capture the highest margin pools given certification requirements and material complexity. Steel dominates material throughput by volume, though aluminum fabrication is gaining share in aerospace and electronics applications where weight reduction dictates design.
Fabricators in the United States navigate OSHA workplace safety mandates alongside EPA emissions rules for welding fume capture and surface coating operations. European competitors face REACH chemical restrictions and the EU Green Deal's embodied-carbon tracking requirements, while Chinese shops respond to GB standards and MEE environmental enforcement tightening around metalworking discharge. Stakeholders must monitor how carbon-border adjustment mechanisms and reshoring incentives reshape supplier qualification criteria and capital allocation across fabrication networks.
Market Dynamics
Automotive lightweighting mandates are compressing traditional steel-heavy supply chains and forcing fabricators to recalibrate process portfolios toward aluminum and advanced high-strength alloys. Tier-1 suppliers now demand single-source accountability for multi-material weldments, reshaping competitive positioning around integrated cutting-forming-joining capabilities rather than discrete service offerings.
Growth Catalysts
- US Inflation Reduction Act:Domestic content bonuses for clean energy infrastructure are redirecting capital expenditure toward Ohio, Michigan, and Texas fabrication corridors, expanding demand for structural steel processing.
- Aluminum chassis penetration:EV platforms from Detroit to Stuttgart are specifying aluminum-intensive body-in-white architectures, pulling fabrication capacity toward friction-stir welding and heat-treatment certification.
- India's PLI scheme for specialty steel:Production-linked incentives for value-added metal products are attracting Japanese and Korean fabricators to establish joint ventures in Gujarat and Tamil Nadu.
Market Restraints
- Scrap aluminum price volatility:London Metal Exchange fluctuations above 15% annually are compressing margin predictability for secondary smelter-dependent shops in the US Midwest.
- Welding consumables concentration:Lincoln Electric and ESAB control 60% of North American filler metal supply, exposing regional fabricators to allocation risk during supply shocks.
- REACH substance restrictions:ECHA classification of chromium VI compounds as SVHCs is forcing European coaters to validate alternative pretreatment chemistries at 18-24 month qualification cycles.
Strategic Opportunities
- Saudi giga-project pipeline:NEOM and Red Sea tourism developments are importing German and Korean fabrication expertise for corrosion-resistant coastal infrastructure, creating premium service windows.
- Robotic cobot integration:Collaborative welding arms from Universal Robots and Fanuc are enabling mid-cap US shops to bid on automotive spot-weld contracts previously reserved for tier-1 integrators.
- EU Carbon Border Adjustment Mechanism:CBAM phase-in for steel and aluminum is incentivizing Turkish and Indian exporters to establish EU-located finishing capacity to preserve market access.
Industry Challenges
- Certified welder scarcity:American Welding Society SENSE program graduates fill less than 40% of open positions in Gulf Coast energy fabrication, extending project timelines.
- Legacy ERP integration:Shop-floor data collection from Trumpf and Amada cutting systems requires custom middleware to feed SAP or Oracle planning modules, inflating IT project budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Fabrication Service Market |
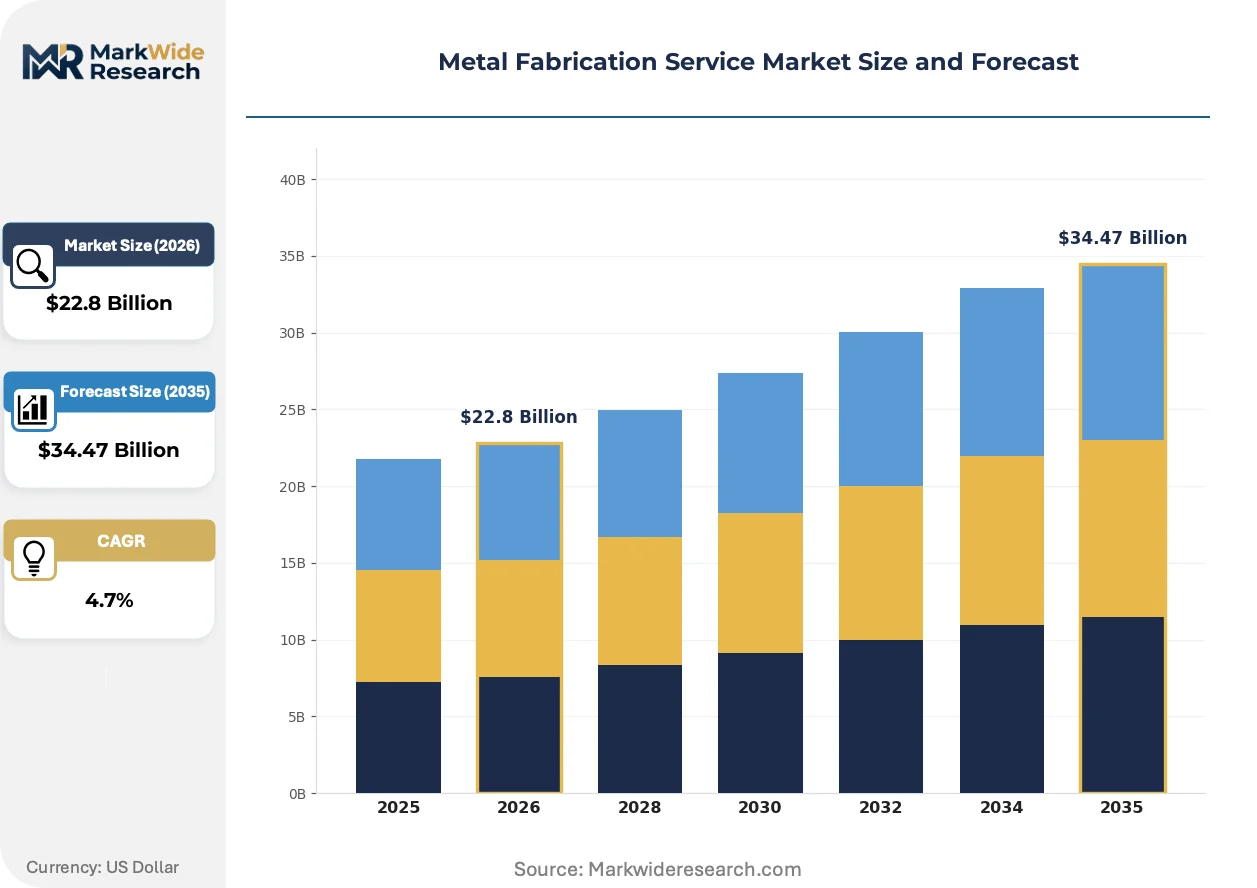
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $34.47 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cutting, Welding, Forming, Assembly, Machining Material Type: Steel, Aluminum, Copper, Titanium, Stainless Steel Application: Construction, Aerospace, Marine, Energy, Electronics End User Industry: Manufacturers, Shipbuilders, Energy Producers, Electronics Makers, Infrastructure Developers |
| Companies Covered | O'Neal Manufacturing Services, BTD Manufacturing, Mayville Engineering Company, Inc., Amada America, Inc., Protolabs, Helander Metal, Schaumburg Specialties LLC, Ark Alloy, LLC, Metal-Fab Service Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Fabrication Service Market Strategic Shifts & Innovations
Digital thread technologies are collapsing the gap between design intent and shop-floor execution, compressing first-article qualification from weeks to days. Fabricators investing in connected workflows are capturing preference from OEMs accelerating platform refresh cycles.
Hybrid laser-arc welding is decentralizing thick-section joining from specialized shipyard facilities to regional job shops. Offshore wind tower fabricators in Denmark and Taiwan are adopting this process to eliminate multipass submerged-arc sequences, cutting heat-affected zone distortion by half. The technology is compressing capital barriers to heavy-gauge work, enabling mid-tier competitors to bid on monopile and transition piece contracts previously reserved for integrated yards.
EU Green Deal embodied-carbon tracking requirements are mandating Environmental Product Declarations for structural steel entering public works. French and German infrastructure authorities now require mill-specific carbon intensity data, forcing fabricators to segment supplier bases by emissions tier. Projects above 50 million euros must document cradle-to-gate CO2 equivalents, advantaging electric-arc furnace mills over basic oxygen furnace competitors.
Automotive OEMs are consolidating supplier panels and demanding design-for-manufacturing collaboration earlier in development cycles. Tier-1 stampers in Stuttgart and Detroit are replacing transactional RFQ models with multi-year co-development agreements, embedding fabrication engineers at vehicle program kickoff. This compresses traditional price-based competition and rewards shops with simulation-backed formability prediction and in-house toolroom capacity.
Metal Fabrication Service Market Segmentation
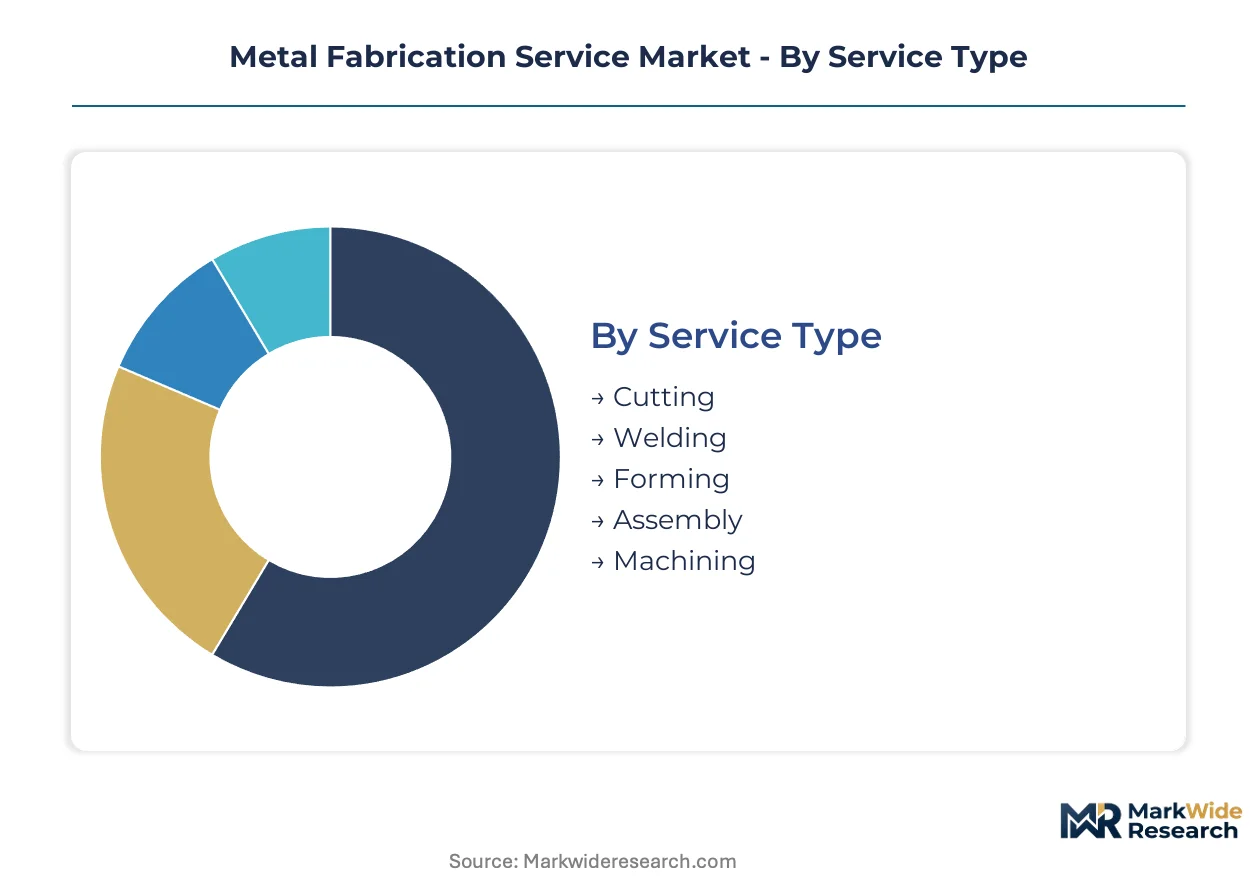
Metal fabrication services fragment across technical capabilities, material specializations, and certification requirements that determine supplier qualification tiers. Procurement teams weight segment selection against project complexity, regulatory burden, and supply base availability.
Service Type:
AWS D1.1 structural welding certification and ISO 3834 quality requirements create the steepest barriers to entry, concentrating premium contract awards among accredited shops.
- Welding:Arc, MIG, TIG, and friction-stir processes dominate revenue pools. Automotive OEMs in Stuttgart and Detroit now mandate single-source weldment accountability for aluminum-intensive EV platforms, compressing supplier panels.
- Cutting:Laser, plasma, and waterjet systems process raw stock to precision tolerances. Demand concentrates in Ohio and Texas fabrication corridors serving Inflation Reduction Act-funded clean energy infrastructure.
- Forming:Press brake and roll-forming operations shape sheet metal into structural profiles.
- Machining:CNC milling and turning deliver tight-tolerance components for aerospace and medical device applications.
- Assembly:Integration of fabricated subcomponents into finished weldments or mechanical systems.
Welding sits at the top of the volume ranking, with machining climbing the fastest on aerospace certification premiums.
Material Type:
Raw material selection dictates process compatibility, margin structure, and end-market access, with exotic alloys commanding qualification premiums.
- Steel:Carbon and alloy grades process through conventional cutting and welding equipment. US Midwest fabricators serving structural construction and energy infrastructure consume the highest tonnage volumes.
- Aluminum:5xxx and 6xxx series alloys require specialized wire feed and heat-treatment protocols. EV chassis programs from Detroit to Stuttgart are pulling capacity toward friction-stir welding certification.
- Stainless Steel:Austenitic and duplex grades serve chemical processing and marine corrosion environments.
- Titanium:Aerospace-grade Ti-6Al-4V demands vacuum or inert-atmosphere welding and NDT traceability.
- Copper:Electrical conductivity applications in busbars and thermal management systems.
Steel anchors volume leadership across construction and energy verticals, while aluminum gains share fastest on transportation lightweighting mandates.
Application:
End-use certification tiers segment the supply base, with aerospace and nuclear applications imposing the most stringent quality system requirements.
- Construction:Structural steel fabrication for commercial buildings and bridges. German and US infrastructure authorities now require Environmental Product Declarations documenting cradle-to-gate carbon intensity.
- Aerospace:Airframe and engine components subject to AS9100 and NADCAP accreditation. Titanium and nickel-alloy work captures the highest margin pools given material complexity and NDT overhead.
- Energy:Power generation and oil and gas equipment including pressure vessels and offshore platforms.
- Marine:Ship hulls and offshore structures requiring corrosion-resistant welding procedures.
- Electronics:Precision enclosures and thermal management components for semiconductor and telecommunications hardware.
Construction commands the largest addressable demand, with aerospace expanding most quickly on platform refresh cycles and supply chain reshoring.
End User Industry:
Customer scale and technical sophistication determine contract structure, with integrated OEMs favoring multi-year co-development agreements over transactional procurement.
- Manufacturers:Industrial equipment and automotive OEMs requiring tiered supplier integration. Heavy equipment producers in the US Midwest are consolidating fabrication spend under single-source modular bundles.
- Energy Producers:Utilities and oil and gas operators specifying pressure-rated weldments. Saudi giga-projects are importing German and Korean fabrication expertise for corrosion-resistant coastal infrastructure.
- Infrastructure Developers:Public and private construction entities with embodied-carbon tracking mandates.
- Shipbuilders:Naval and commercial yards requiring thick-section joining capabilities.
- Electronics Makers:Semiconductor and telecommunications hardware producers demanding precision enclosures.
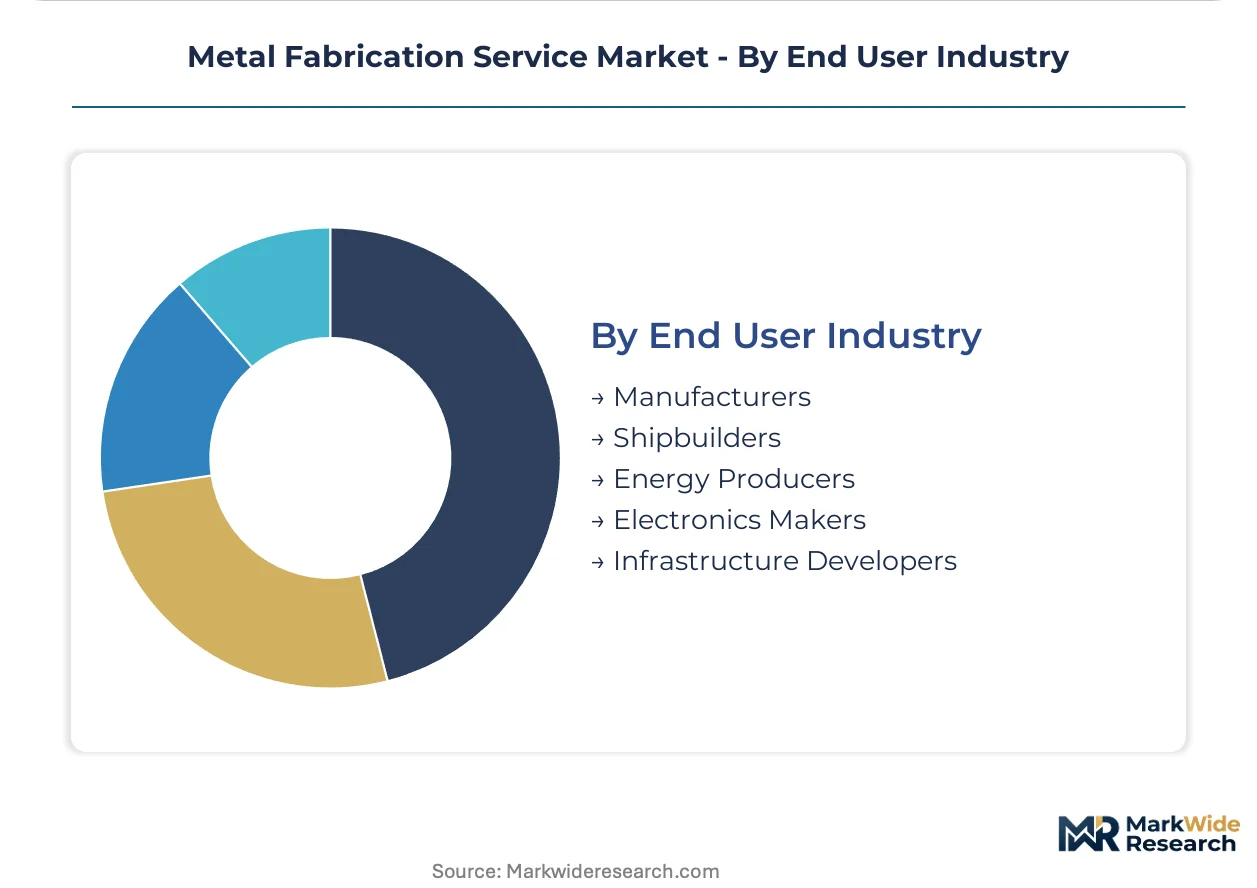
Manufacturers anchor contract volume, with energy producers expanding fastest on clean energy capital reallocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metal fabrication services trace their industrial lineage to 19th-century British shipyards and German toolmaking districts, where standardized cutting and joining techniques first enabled mass production of steam engines and railway infrastructure. Today, fabrication demand concentrates in manufacturing corridors shaped by automotive OEMs, energy infrastructure spending, and reshoring incentives.
United States
Clean energy capital from the Inflation Reduction Act is redirecting fabrication demand toward Ohio, Michigan, and Texas corridors serving wind tower and solar racking projects. OSHA workplace safety mandates and EPA emissions rules for welding fume capture shape operational compliance costs. Houston's Gulf Coast energy fabrication cluster faces certified welder shortages, with American Welding Society SENSE program graduates filling less than 40% of open positions.
Germany
Stuttgart's automotive stamping district and Hamburg's shipyard corridor anchor European fabrication demand, with EV platform lightweighting pulling capacity toward aluminum friction-stir welding. ECHA REACH substance restrictions on chromium VI compounds and EU Green Deal embodied-carbon tracking requirements force 18-24 month qualification cycles for alternative pretreatment chemistries. The Ruhr Valley's steel-processing heritage now pivots toward electric-arc furnace mill partnerships for public works EPD compliance.
China
GB standards and MEE environmental enforcement tightening around metalworking discharge reshape shop-floor compliance in the Yangtze River Delta and Pearl River Delta manufacturing belts. Dual carbon goals accelerate electric-arc furnace adoption, displacing basic oxygen furnace capacity in Shandong and Hebei provinces. Domestic content requirements for infrastructure and energy equipment sustain demand for structural steel processing in Sichuan-Chongqing industrial corridors.
India
Production-linked incentives for specialty steel under the PLI scheme attract Japanese and Korean fabricators to joint ventures in Gujarat and Tamil Nadu. BIS certification requirements and DGFT trade policy shifts shape import substitution strategies for value-added metal products. The Delhi-Mumbai Industrial Corridor concentrates demand for precision enclosures and thermal management components serving electronics and telecommunications hardware makers.
Saudi Arabia
NEOM and Red Sea tourism giga-projects import German and Korean fabrication expertise for corrosion-resistant coastal infrastructure, creating premium service windows for monopile and transition piece contracts. SFDA and MOHAP regulatory frameworks for industrial equipment certification shape supplier qualification criteria. The Eastern Province's energy infrastructure corridor sustains demand for pressure-rated weldments serving utilities and oil and gas operators.
Metal Fabrication Service Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification tiers, with AS9100 aerospace accreditation and AWS D1.1 structural welding credentials creating steep barriers that concentrate contract awards among accredited shops. The vendor base organizes into three tiers: integrated multi-process houses capturing single-source automotive agreements, precision specialists dominating aerospace and medical device niches, and regional job shops competing on turnaround speed for construction and energy maintenance work. Dominant competitive moves include M&A-driven geographic expansion and robotic cobot integration to bid on contracts previously reserved for tier-1 integrators.
Within the integrated multi-process tier, O'Neal Manufacturing Services and BTD Manufacturing occupy positions anchoring long-term agreements with heavy equipment OEMs across Midwest production corridors. Mayville Engineering Company, Inc. exemplifies the employee-ownership archetype, sustaining workforce retention in tight labor markets through its ESOP structure. These three fabricators represent contrasting pathways to supplier consolidation: scale-driven process bundling, precision stamping and weldment integration, and ownership-model differentiation.
| Leading Market Players |
|---|
| O'Neal Manufacturing Services |
| BTD Manufacturing |
| Mayville Engineering Company, Inc. |
| Amada America, Inc. |
| Protolabs |
| Helander Metal |
| Schaumburg Specialties LLC |
| Ark Alloy, LLC |
| Metal-Fab Service Industries, Inc. |
| Others |
Cost & Logistics Intelligence
Hybrid laser-arc welding adoption is collapsing capital barriers for thick-section joining, simultaneously compressing per-unit processing costs and redistributing fabrication capacity from integrated shipyards toward regional job shops across Denmark, Taiwan, and the US Gulf Coast. This technology shift tightens margin pools for legacy submerged-arc specialists while opening premium contract windows for mid-tier competitors with robotic cobot integration.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs contract awards, with AS9100 aerospace accreditation and AWS D1.1 structural welding certification commanding 40-60% premiums over uncertified job shops. Price differentiation hinges on NDT traceability depth and in-house heat-treatment capability. Cost compression in standard-tier structural steel is intensifying because of scrap aluminum price volatility above 15% annually on the London Metal Exchange. Construction procurement teams exhibit highest price sensitivity, while aerospace OEMs prioritize qualification reliability over unit cost.
Supply Chain Analysis
Regional distribution centers in Ohio, Michigan, and Texas form hub-and-spoke patterns serving Inflation Reduction Act-funded clean energy corridors. Geographic supply concentration centers on Germany, China, and India, with Stuttgart's automotive stamping district, Yangtze River Delta manufacturing belts, and Gujarat-Tamil Nadu joint venture zones anchoring throughput. Raw material dependencies draw from electric-arc furnace steel, 5xxx and 6xxx series aluminum, and titanium sponge. Single-source vulnerability in welding consumables—Lincoln Electric and ESAB controlling 60% of North American filler metal supply—exposes regional fabricators to allocation risk. Distribution runs through tier-1 supplier consolidation and OEM direct contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metal fabrication services constitute a late-cycle quality story as automotive OEMs consolidate supplier panels and mandate single-source accountability for aluminum-intensive EV platforms, elevating premium-credentialed shops above commodity competitors.
For Market Incumbents: Acquire friction-stir welding certification capacity and in-house toolroom assets to defend long-term agreement positions against robotic cobot-enabled mid-tier entrants bidding on automotive spot-weld contracts. Consolidate geographic footprint through M&A in Ohio-Texas fabrication corridors where Inflation Reduction Act capital concentrates. Reinforce AS9100 and NADCAP accreditation moats in aerospace titanium work where margin pools remain deepest. For New Entrants and Emerging Players: Regional job shop networks in Saudi Arabia's Eastern Province offer the most penetrable white-space target, importing German and Korean fabrication expertise for NEOM giga-project corrosion-resistant coastal infrastructure. Target mid-cap wind tower and solar racking contracts in US Midwest corridors where certified welder scarcity extends project timelines and creates service windows. Pursue robotic cobot integration from Universal Robots and Fanuc as the primary go-to-market angle to bypass tier-1 integrator incumbency. For Investors and Strategic Acquirers: Valuations sit cheapest among employee-owned ESOP structures with underutilized AWS D1.1 capacity in tight labor markets like Mayville Engineering's archetype. Long-term viability favors shops with simulation-backed formability prediction and electric-arc furnace mill partnerships for EU Carbon Border Adjustment Mechanism compliance. Watch for CBAM phase-in enforcement as the signal indicating accelerated Turkish and Indian exporter establishment of EU-located finishing capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Friction-Stir Welding Certification Investment | Captures aluminum-intensive EV platform contracts from Detroit and Stuttgart OEMs consolidating supplier panels. |
| Robotic Cobot Integration | Enables mid-cap US shops to bid on automotive spot-weld contracts previously reserved for tier-1 integrators. |
| Electric-Arc Furnace Mill Partnership | Secures Environmental Product Declaration compliance for German and French public works above 50 million euros. |
| Backward Integration into Heat Treatment | Reduces 18-24 month qualification cycle exposure from ECHA REACH chromium VI restrictions on European coaters. |
| Employee Ownership Structure Implementation | Sustains workforce retention in Gulf Coast energy fabrication where AWS SENSE graduates fill under 40% of open positions. |
Research Approach
Bottom-up automotive and energy infrastructure modeling reconciled against top-down steel and aluminum processing capacity tracking forms the analytical core of this study. Primary interviews with fabrication plant managers, OEM procurement leads at Tier 1 suppliers, AWS-certified welders, and distribution channel partners combined with secondary validation from EPA emissions filings, OSHA workplace safety records, ECHA REACH substance databases, and GB standards compliance reports. Triangulation across stakeholder inputs and regulatory documentation ensures segmentation integrity.
Input-output matrices map service type, material specialization, and certification tier against end-use demand across construction, aerospace, and energy verticals throughout the forecast period. Segmentation dimensions include welding process protocol, raw material grade, application certification requirements, and regional production cluster. CAGRs derive from capacity utilization trends and capital expenditure patterns. Industry-specific forecast inputs incorporate Inflation Reduction Act domestic content bonus allocation and EU Carbon Border Adjustment Mechanism phase-in timing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to scrap aluminum price volatility, welding consumables supply concentration, and REACH substance restriction expansion. Forecasts reflect assumptions about regulatory enforcement continuity and OEM platform refresh cycle cadence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Metal Joining Services Market
Engineering Services
Asia Pacific Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Geosteering Services Market
Engineering Services
Engineering Services Market
Engineering Services
Well Cementing Services Market
Engineering Services
Foundation Repair Services Market
Engineering Services
Aerospace Engineering Services Market
Engineering Services
Architectural Services Market
Engineering Services
China Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Vacuum Excavation Service Market
Engineering Services
Bridge Inspection System Market
Engineering Services
Vertical Seismic Profile Service Market
Engineering Services
Engineering Design Service Market
Engineering Services
Construction Engineering Services Outsourcing Market
Engineering Services
MEP Services Market
Engineering Services
Bridge Inspection Services Market