
 Chile Freight and Logistics Market | 2026-2036
Chile Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Freight and Logistics Market Outlook
Chile's Framework Law on Climate Change is pivoting fleet operators toward lower-emission vehicles and alternative fuels across the trucking sector. Kuehne + Nagel leverages its integrated sea-air-road network to dominate temperature-controlled cargo moving through Valparaíso. SAAM anchors port terminal operations along the Pacific corridor with specialized container handling capacity. DSV competes on cross-border consolidation services linking Santiago distribution centers to Argentine and Peruvian markets.
Freight and logistics encompasses the physical movement, storage, and information management of goods across multimodal networks including containerized sea transport, bulk road haulage, and temperature-controlled air cargo, typically measured by ton-kilometers and container throughput. The sector's primary purpose is synchronizing inventory flows with production schedules while minimizing transit times and damage rates. Road freight leads service type revenue due to last-mile dominance in Chile's elongated geography, while sea freight captures the highest absolute tonnage through Valparaíso and San Antonio ports. E-commerce end users represent the fastest-growing demand pool as same-day delivery expectations reshape warehousing location strategies. GPS tracking technology sits at the center of margin expansion as fleet operators monetize real-time visibility through premium service tiers.
Chile's Ministry of Transport enforces Euro VI-equivalent emission standards for heavy vehicles entering metropolitan Santiago, directly filtering fleet renewal timelines and engine technology choices. The Superintendency of the Environment monitors carbon footprint disclosures from logistics providers serving mining and energy clients, tightening compliance thresholds quarterly. Stakeholders must weigh electrification capex against diesel residual value risk while monitoring lithium supply chain investments reshaping northern corridor traffic patterns.
Market Dynamics
Chile's Framework Law on Climate Change is forcing fleet operators to accelerate engine replacement cycles while lithium supply chain investments reshape cargo flows across the northern mining corridor. The tension between emission compliance deadlines and residual diesel asset values sits at the center of operator investment decisions.
Growth Catalysts
- Copper export volumes:Mining procurement in the Antofagasta Region is expanding dedicated logistics services across northern Chile's extraction zones.
- Carbon disclosure mandates:The Superintendency of the Environment's quarterly tightening of footprint thresholds is pulling investment into telemetry and alternative fuel infrastructure.
- E-commerce fulfillment:Same-day delivery expectations are reshaping warehousing location strategies around Santiago's ring road network.
Market Restraints
- Electrification capex burden:Battery-electric truck acquisition costs strain mid-size fleet balance sheets before diesel residual values recover.
- Port concentration risk:Container throughput dependence on Valparaíso and San Antonio creates single-point vulnerability during labor actions.
- Andean topography:Steep grades and altitude variations limit payload efficiency for battery-electric heavy vehicles on central corridor routes.
Strategic Opportunities
- Cross-border consolidation:Santiago distribution centers can anchor triangular routing into Argentine and Peruvian markets with bonded warehousing.
- Lithium corridor specialization:Dedicated bulk and container services for cathode precursor shipments from Atacama to Pacific ports remain underdeveloped.
- Telematics monetization:Real-time cargo visibility platforms enable premium service tiering for temperature-controlled pharmaceutical exports.
Industry Challenges
- Technician scarcity:High-voltage drivetrain maintenance skills lag fleet electrification timelines in regional maintenance depots.
- Intermodal synchronization:Rail-sea handoff coordination failures at San Antonio generate demurrage costs and contract penalties.
- Legacy fleet stranding:Euro VI-equivalent engine upgrades for pre-2018 vehicles face parts availability constraints from European suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Freight and Logistics Market |
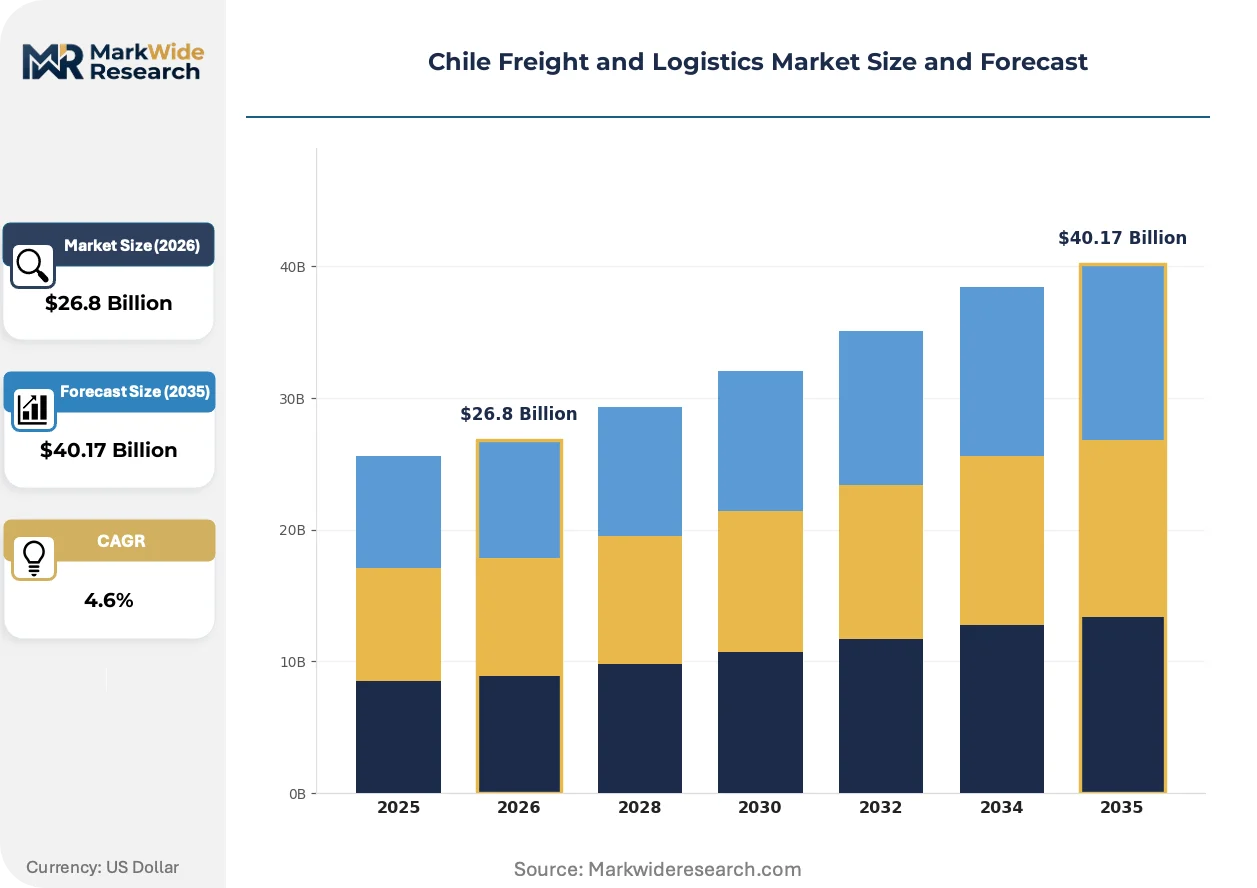
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $40.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Road Freight, Sea Freight, Air Freight, Rail Freight End User: Manufacturing, Retail, Consumer Goods, E-commerce Technology: GPS Tracking, Cargo Management Systems, Blockchain, RFID Distribution Channel: Direct Delivery, Third-party Logistics, Warehousing, Cargo Consolidation |
| Companies Covered | Kuehne + Nagel, Andes Logistics de Chile S.A., Agunsa (Agencias Universales S.A.), Sotraser, Transportes Casablanca, SAAM, DSV, Empresas Taylor, DHL Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Freight and Logistics Market Strategic Shifts
GPS-enabled fleet management platforms are converging with carbon accounting software to create real-time emission visibility products. This integration is compressing the gap between operational optimization and regulatory compliance reporting across Chilean logistics networks.
Telematics hardware is converging with blockchain-based documentation systems to create tamper-proof chain-of-custody records for mining and agricultural exports. Large copper shippers in the Antofagasta Region are piloting these integrated stacks to satisfy European offtaker traceability requirements. The structural consequence is a compression in insurance premiums and letter-of-credit processing times for compliant operators.
Chile's Ministry of Transport enforces Euro VI-equivalent emission standards for heavy vehicles entering metropolitan Santiago. This policy is filtering fleet renewal timelines and restricting market access for non-compliant carriers serving the capital's distribution centers. Road freight operators serving retail and e-commerce fulfillment are responding by accelerating compressed natural gas and battery-electric pilot programs ahead of the 2025 enforcement window.
Consolidation of procurement authority among large mining houses is displacing fragmented spot-market contracting for logistics services. Major copper producers are bundling freight, warehousing, and customs brokerage into multi-year performance contracts with penalty clauses for carbon intensity breaches. This shift is most visible in the Antofagasta Region where integrated logistics providers are capturing volume commitments previously split across ten or more regional carriers.
Chile Freight and Logistics Market Segmentation
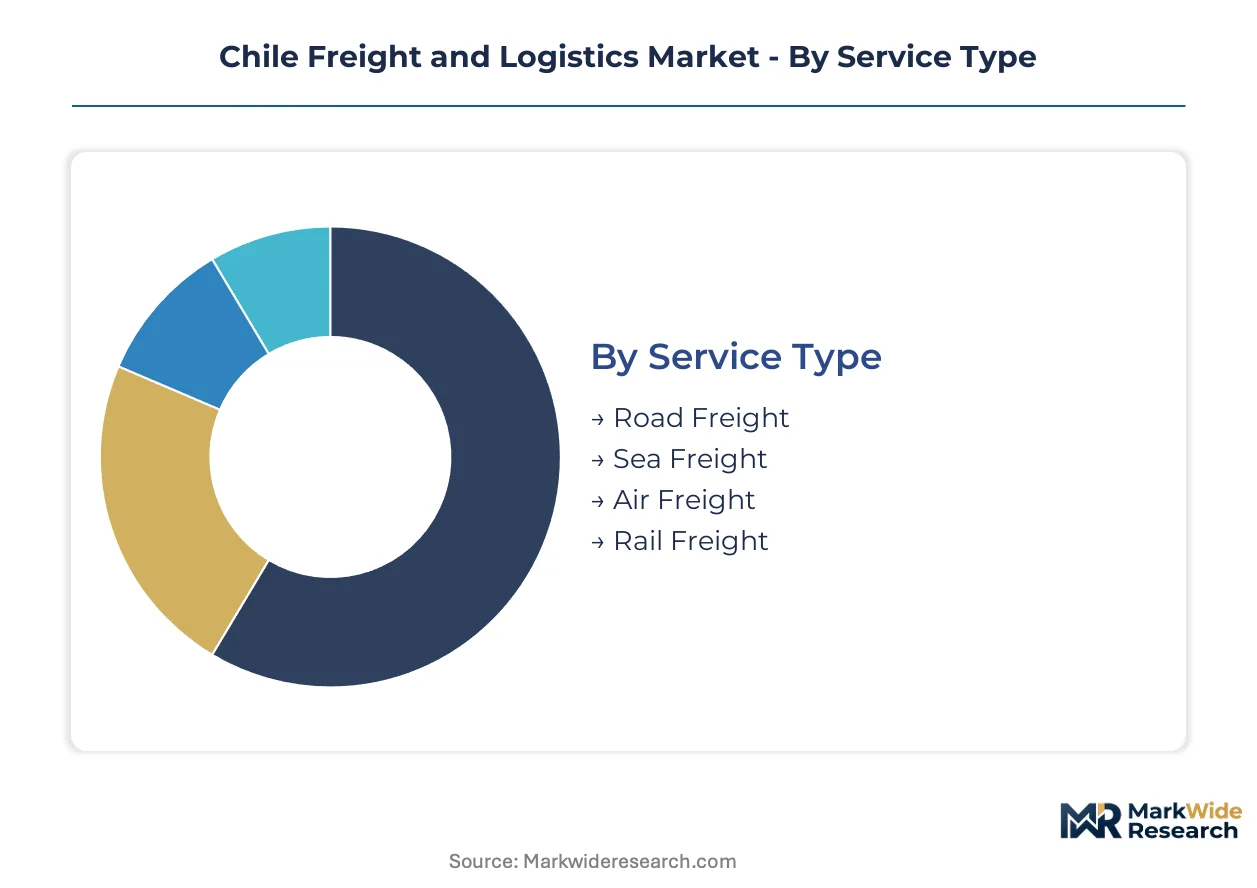
Chile's elongated geography and mining-driven export economy fragment logistics demand across four distinct service modes, each commanding specialized fleet configurations. End-user concentration in copper extraction and Santiago retail creates divergent requirements for payload capacity, transit velocity, and temperature control.
Service Type:
Fleet renewal cycles diverge sharply across modes as Euro VI-equivalent standards force premature retirement of diesel assets in metropolitan corridors.
- Road Freight:Heavy-duty trucking dominates last-mile distribution through Santiago's ring road network and bulk haulage to Antofagasta mining clusters. Demand concentrates in temperature-controlled pharmaceutical runs and copper concentrate trucking where payload efficiency outweighs electrification penalties.
- Sea Freight:Containerized movements through Valparaíso and San Antonio ports handle the highest absolute tonnage in Chilean trade. Volume concentrates in copper cathode exports and automotive imports where San Antonio's dedicated terminals reduce vessel turnaround times.
- Air Freight:Temperature-sensitive pharmaceutical and fresh produce shipments utilize Arturo Merino Benítez International's cargo terminals. High-value lithium battery samples and mining equipment spares drive premium express demand.
- Rail Freight:Bulk mineral transport from Antofagasta to port facilities operates on dedicated mining railway networks. Ferrocarril del Pacífico handles containerized intermodal loads where road congestion penalties exceed rail scheduling inflexibility.
Volume placements concentrate in Road Freight; the faster expansion belongs to Sea Freight as port automation investments accelerate vessel processing.
End User:
Customer procurement authority is consolidating around sustainability metrics that filter carrier selection across Chile's northern extraction zones.
- Manufacturing:Automotive assembly plants in Santiago's outskirts and food processing facilities demand just-in-time delivery windows with penalty clauses for delay. Copper smelters in Ventanas anchor heavy bulk logistics contracts with multi-year volume commitments.
- Retail:Department store chains and supermarket distributors operate regional distribution centers requiring daily replenishment cycles. Santiago's Mall Plaza network drives consolidated truckload programs to reduce empty backhaul kilometers.
- Consumer Goods:Import-dependent categories—electronics, apparel, household durables—flow through Valparaíso customs zones before deconsolidation. Warehouse location strategies prioritize proximity to Ruta 5 Norte for northbound distribution.
- E-commerce:Same-day delivery expectations from Santiago metropolitan consumers are compressing order-to-delivery windows below six hours. Dark store proliferation in Ñuñoa and Providencia neighborhoods reshapes urban freight patterns.
Contract values peak in Manufacturing; E-commerce is gaining share fastest as fulfillment infrastructure spreads beyond capital district limits.
Technology:
Hardware refresh cycles accelerate where carbon accounting mandates require granular emission visibility for mining house compliance.
- GPS Tracking:Real-time fleet positioning enables dynamic route optimization across Chile's 4,300-kilometer north-south corridor. Mining logistics providers in Calama deploy satellite-linked units where cellular coverage fails.
- Cargo Management Systems:Integrated warehouse and transport execution platforms synchronize inventory flows for retail distribution networks. Santiago-based 3PLs monetize system access through per-transaction SaaS pricing.
- Blockchain:Tamper-proof documentation for copper concentrate chain-of-custody satisfies European offtaker traceability requirements. Pilot programs in Antofagasta Region reduce letter-of-credit processing friction.
- RFID:Container and pallet-level tracking automates yard management at San Antonio port terminals. Pharmaceutical cold chains utilize temperature-logging RFID tags for regulatory audit trails.
Adoption concentrates in GPS Tracking; steepest expansion trajectory belongs to Blockchain as mining export compliance tightens.
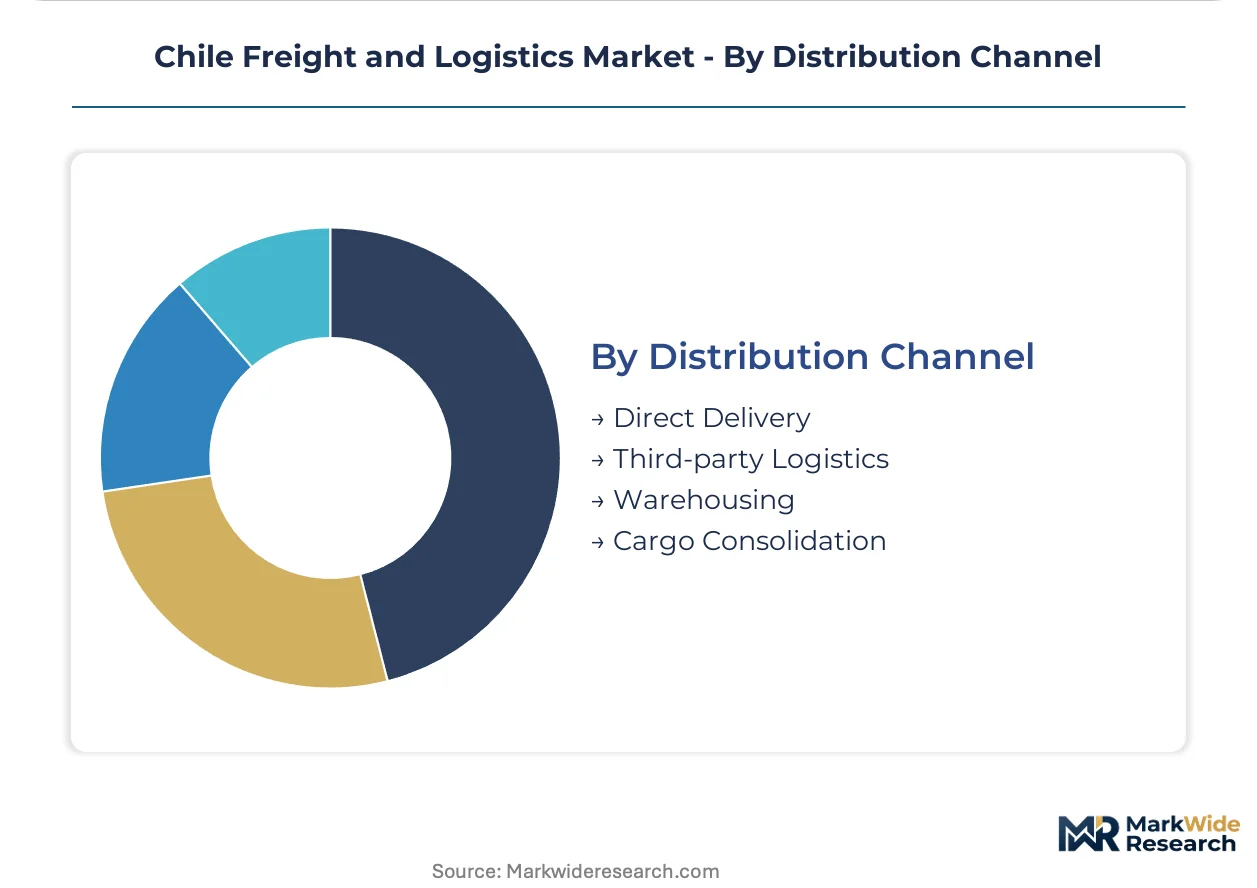
Distribution Channel:
Channel selection hinges on inventory carrying cost tolerance versus control requirements across Chile's concentrated retail landscape.
- Direct Delivery:Manufacturer-operated fleets serve large mining houses with dedicated equipment and driver pools. Codelco and BHP prefer captive transport for high-security copper concentrate movements.
- Third-party Logistics:Outsourced warehousing and transport management captures mid-size retail chains lacking capital for fleet ownership. Santiago's ring road corridor hosts concentrated 3PL campus development.
- Warehousing:Bonded storage facilities in Valparaíso free trade zone defer duty payment for re-export goods. Temperature-controlled pharma vaults near Arturo Merino Benítez airport command premium rates.
- Cargo Consolidation:Less-than-truckload bundling reduces per-unit freight costs for small importers in peripheral regions. Cross-dock operations in La Serena and Concepción aggregate fragmented demand.
Revenue pools concentrate in Third-party Logistics; Cargo Consolidation is climbing the fastest as e-commerce parcel volumes fragment shipment sizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's production geography concentrates extraction in the mineral-rich north while consumption and import processing cluster around Santiago and central port corridors. This spatial mismatch generates asymmetric freight flows that shape infrastructure investment priorities across the country's 4,300-kilometer north-south axis.
Antofagasta Region
Copper concentrate exports from Calama and Antofagasta city drive the highest ton-kilometer demand in Chilean logistics. The Superintendency of the Environment enforces quarterly tightening of carbon disclosure thresholds for mining supply chain operators. Port terminals at Mejillones and Antofagasta are expanding dedicated bulk handling capacity to reduce vessel queuing.
Valparaíso Region
Containerized imports and copper cathode exports converge on Valparaíso and San Antonio ports, creating Chile's densest intermodal traffic. Euro VI-equivalent emission standards enforced by the Ministry of Transport filter heavy vehicle access to metropolitan distribution zones. The Ruta 68 corridor connecting Santiago to Valparaíso hosts concentrated warehousing development for retail fulfillment.
Metropolitan Santiago
E-commerce same-day delivery expectations compress order-to-delivery windows below six hours in Ñuñoa and Providencia neighborhoods. The Ministry of Transport's 2025 enforcement window for low-emission zones accelerates compressed natural gas and battery-electric pilot programs. Ring road logistics campuses in Quilicura and Pudahuel anchor third-party warehousing for national distribution.
Atacama Region
Lithium extraction from the Salar de Atacama is generating new bulk and containerized cargo flows toward Pacific port facilities. Carbon accounting mandates from the Superintendency of the Environment require granular emission visibility for cathode precursor shipments. Copiapó and Chañaral are emerging as consolidation points for mining equipment and chemical inputs.
Bío Bío Region
Manufacturing assembly and food processing in Concepción and Talcahuano generate regional distribution demand with penalty clauses for delivery delay. The Ministry of Transport coordinates port-rail intermodal investments at Coronel to reduce road congestion penalties. The Concepción metropolitan area supports specialized cold chain infrastructure for agricultural exports.
Chile Freight and Logistics Market Competitive Environment
The competitive structure tilts toward integrated logistics providers with captive port terminal access and cross-border consolidation capabilities. Mid-size regional carriers retain fragmentation in bulk mining haulage where spot contracting still dominates. Two strategic archetypes predominate: global freight forwarders with temperature-controlled networks, and domestic operators with bonded warehousing and customs brokerage integration. Capacity expansion and strategic partnerships constitute the dominant competitive moves as operators position for lithium corridor specialization.
Among global forwarders operating in Chile, Kuehne + Nagel and DSV exemplify the integrated sea-air-road archetype with established Santiago distribution presence. SAAM anchors the domestic port-centric tier through specialized container handling infrastructure along the Pacific corridor. These three occupy positions spanning temperature-controlled pharmaceuticals, mining supply chains, and cross-border consolidation into Argentine and Peruvian markets.
| Leading Market Players |
|---|
| Kuehne + Nagel |
| Andes Logistics de Chile S.A. |
| Agunsa (Agencias Universales S.A.) |
| Sotraser |
| Transportes Casablanca |
| SAAM |
| DSV |
| Empresas Taylor |
| DHL Group |
| Others |
Value Chain & Pricing Dynamics
Large mining house procurement consolidation in the Antofagasta Region anchors Chilean logistics pricing around multi-year performance contracts with carbon intensity penalty clauses. This buyer concentration shifts pricing power toward operators with integrated port terminal access and alternative fuel fleets.
Pricing Analysis
Margin tightening in temperature-controlled pharmaceutical runs reflects certification-grade differentiation between GDP-compliant cold chains and standard freight tiers. Three-tier pricing structure across premium, standard, and economy levels separates operators with real-time telemetry from asset-light brokers. Cost-down pressure on bulk copper concentrate haulage accelerates because mining houses bundle freight, warehousing, and customs brokerage into single-source agreements. Retail distribution centers exhibit highest price sensitivity as e-commerce fulfillment squeezes per-unit margins.
Supply Chain Analysis
Euro VI-equivalent engine certification gates market access for heavy vehicles serving metropolitan Santiago, filtering fleet procurement toward compliant suppliers. Geographic supply concentration for battery-electric truck drivetrains centers on China, South Korea, and Germany, while lithium-ion cell production feeds from regional Atacama extraction. Single-source vulnerability sits with European suppliers of pre-2018 diesel engine upgrade parts. Distribution runs through bonded warehousing campuses along Santiago's ring road corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's Framework Law on Climate Change erects a compliance moat that rewards operators with capital reserves for fleet electrification and carbon accounting infrastructure. The Superintendency of the Environment's quarterly disclosure tightening filters marginal players from mining supply chains.
For Market Incumbents: Deploy captive port terminal investments to lock in lithium corridor volume commitments before cathode precursor flows mature. Accelerate compressed natural gas and battery-electric pilot programs ahead of Santiago's low-emission zone enforcement. Consolidate regional maintenance depot networks to address technician scarcity for high-voltage drivetrain servicing.
For New Entrants and Emerging Players: GPS-enabled carbon accounting platforms offer a technology-first wedge into mining house compliance budgets. White-space targets concentrate in lithium supply chain logistics from Salar de Atacama to Pacific ports and cross-border consolidation into Argentine markets. A SaaS-based telemetry partnership model with established carriers reduces capital barriers to fleet visibility services.
For Investors and Strategic Acquirers: The window for entry favors domestic operators with bonded warehousing integration and customs brokerage licenses. Long-term viability hinges on positioning ahead of lithium export volume inflection. Watch for Ferrocarril del Pacífico intermodal coordination failures triggering port congestion penalties as the demand signal for rail-sea synchronization investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Fuel Fleet Conversion | Battery-electric and CNG pilot programs satisfy Santiago's Euro VI-equivalent standards before enforcement windows. |
| Lithium Corridor Specialization | Dedicated bulk and container services for cathode precursor shipments capture emerging Atacama-to-port flows. |
| Telematics Platform Integration | Real-time carbon visibility monetizes premium service tiers for mining house compliance reporting. |
| Cross-Border Consolidation Expansion | Bonded warehousing in Santiago anchors triangular routing into Argentine and Peruvian distribution networks. |
| Port Terminal Capacity Addition | Mejillones and Antofagasta bulk handling expansion reduces vessel queuing for copper concentrate exports. |
Study Parameters
Independent corroboration across fleet operations directors, mining procurement managers, and port terminal executives underwrites the qualitative findings. Primary interviews with third-party logistics providers, customs brokerage leads, and Ministry of Transport officials combined with secondary validation from Chile's customs trade data, Superintendency of the Environment disclosure filings, and Ferrocarril del Pacífico throughput statistics. Bottom-up service mode sizing and top-down GDP-adjusted trade flow analysis triangulate volume estimates.
Rate-of-change decomposition across the projection horizon segments demand by service type, end user vertical, and technology adoption tier. Modeled dimensions include road-sea-air-rail freight splits, mining-retail-e-commerce end-use concentration, and GPS-blockchain-RFID technology penetration. CAGRs derive from elasticity-adjusted trade flow projections and fleet renewal cycle modeling. Lithium supply chain investment trajectories and carbon disclosure mandate compliance timelines feed industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unscheduled labor actions at Valparaíso and San Antonio ports, abrupt Euro VII standard acceleration, and lithium price collapse dampening extraction expansion. Forecasts reflect assumptions about continued copper export volume stability and gradual electric truck total-cost-of-ownership convergence. A model refresh is warranted upon material change in Ministry of Transport low-emission zone enforcement timing or Superintendency of the Environment disclosure threshold trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Spain Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Global Connected Logistics Market
Logistics and Shipping
Netherlands Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Peru Cold Chain Logistics Market
Logistics and Shipping
Global Container Terminal Operations Market
Logistics and Shipping
Government and Education Logistics Market
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
Global Freight Broker Software Market
Logistics and Shipping
United Kingdom Third Party Logistics (3PL) Market
Logistics and Shipping
Shipping Container Modification Market
Logistics and Shipping
France Freight and Logistics Market
Logistics and Shipping
France Last Mile Delivery Market
Logistics and Shipping
Event Logistics Market
Logistics and Shipping
Australia Freight Forwarding Market
Logistics and Shipping
Thailand E-Commerce Logistics Market
Logistics and Shipping
India Courier, Express, and Parcel (CEP) Market