
 Georgia Freight and Logistics Market | 2026-2036
Georgia Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Georgia Freight and Logistics Market Insights
Truck driver availability is collapsing across Georgia's interstate corridors, forcing carriers to accelerate automation and retention investments. Old Dominion Freight Line anchors its southeastern density through dedicated lane networks and terminal ownership. FedEx Freight leverages its national LTL platform to sustain overnight coverage from Atlanta and Savannah. XPO Logistics competes on technology density, deploying proprietary freight optimization tools across its Georgia footprint.
Georgia freight and logistics encompasses the physical movement, storage, and coordination of goods across road, rail, air, and water modes, typically involving cargo weights from 150 pounds to 50,000 pounds and transit requirements ranging from same-day to two-week delivery windows. The sector serves manufacturers, retailers, and e-commerce platforms by synchronizing inventory flows with consumption patterns. Road transportation dominates volume throughput due to Georgia's central position along I-75, I-85, and I-20 corridors, though warehousing is expanding fastest near the Port of Savannah as import containerization rises. E-commerce end users command premium service tiers with compressed delivery windows, while brokerage segments capture margin from spot market volatility.
The Federal Motor Carrier Safety Administration governs hours-of-service limits and electronic logging device mandates that constrain fleet utilization across Georgia operations. The Georgia Department of Transportation coordinates port-rail-highway infrastructure investments that determine capacity access for Savannah-Atlanta freight corridors. EPA SmartWay certification shapes shipper procurement criteria and carrier eligibility for contracted freight lanes. Stakeholders must monitor how autonomous trucking pilot programs and warehouse robotics deployment alter labor-to-capital ratios before committing to long-term facility investments.
Market Dynamics
The Georgia freight and logistics sector is experiencing acute labor scarcity along its interstate corridors, forcing carriers to reconfigure capital deployment toward automation and retention infrastructure. This structural compression is accelerating technology adoption across warehousing and fleet operations statewide.
Growth Catalysts
- Port of Savannah expansion:Container volume growth along the Garden City Terminal corridor is generating demand for drayage capacity and transload facilities. Rail intermodal connections to Atlanta and inland Southeast markets are deepening hinterland access.
- EPA SmartWay certification:Shipper procurement criteria increasingly mandate verified emissions performance, directing contracted freight toward certified carriers. Fleet operators are retrofitting with aerodynamic equipment and low-rolling-resistance tires to maintain lane eligibility.
- E-commerce fulfillment density:Last-mile node construction across Metro Atlanta is pulling parcel sortation and regional distribution center investment. Same-day delivery commitments are compressing inventory positioning requirements.
Market Restraints
- Diesel price volatility:Fuel represents the largest variable cost component for Georgia trucking operations, with spot market exposure amplifying margin pressure on non-contracted lanes. Small fleet operators lack hedging mechanisms available to national carriers.
- Driver labor shortage:FMCSA hours-of-service limits constrain fleet utilization rates while demographic shifts reduce new entrant supply. Training pipeline capacity at Georgia technical colleges has not expanded to meet replacement demand.
- Chassis availability constraints:Port of Savannah operations face intermittent equipment shortages during peak import seasons, extending container dwell times and disrupting drayage scheduling reliability.
Strategic Opportunities
- Central Savannah River Area industrial sites:Underutilized acreage within fifty miles of the port offers lower land costs than Chatham County for distribution center development. Rail-served parcels are attracting cold chain and manufacturing logistics tenants.
- Electric vehicle infrastructure incentives:Georgia's electric vehicle tax credits and utility rebate programs are reducing total cost of ownership calculations for medium-duty fleet electrification. Charging corridor development along I-75 is enabling range confidence for regional routes.
- Autonomous trucking pilot corridors:Designated highway segments between Savannah and Atlanta are permitting supervised autonomous operations, creating regulatory sandboxes for technology validation. Insurers and shippers are developing risk frameworks for graduated deployment.
Industry Challenges
- Warehouse management system integration:Legacy WMS platforms at established Georgia distribution centers require substantial customization to interface with robotic material handling equipment and autonomous mobile robots. Implementation timelines often exceed eighteen months.
- ELD mandate compliance complexity:FMCSA electronic logging device specifications continue evolving, forcing carriers to manage hardware refresh cycles and driver training on compressed schedules. Non-compliance penalties threaten operating authority.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Georgia Freight and Logistics Market |
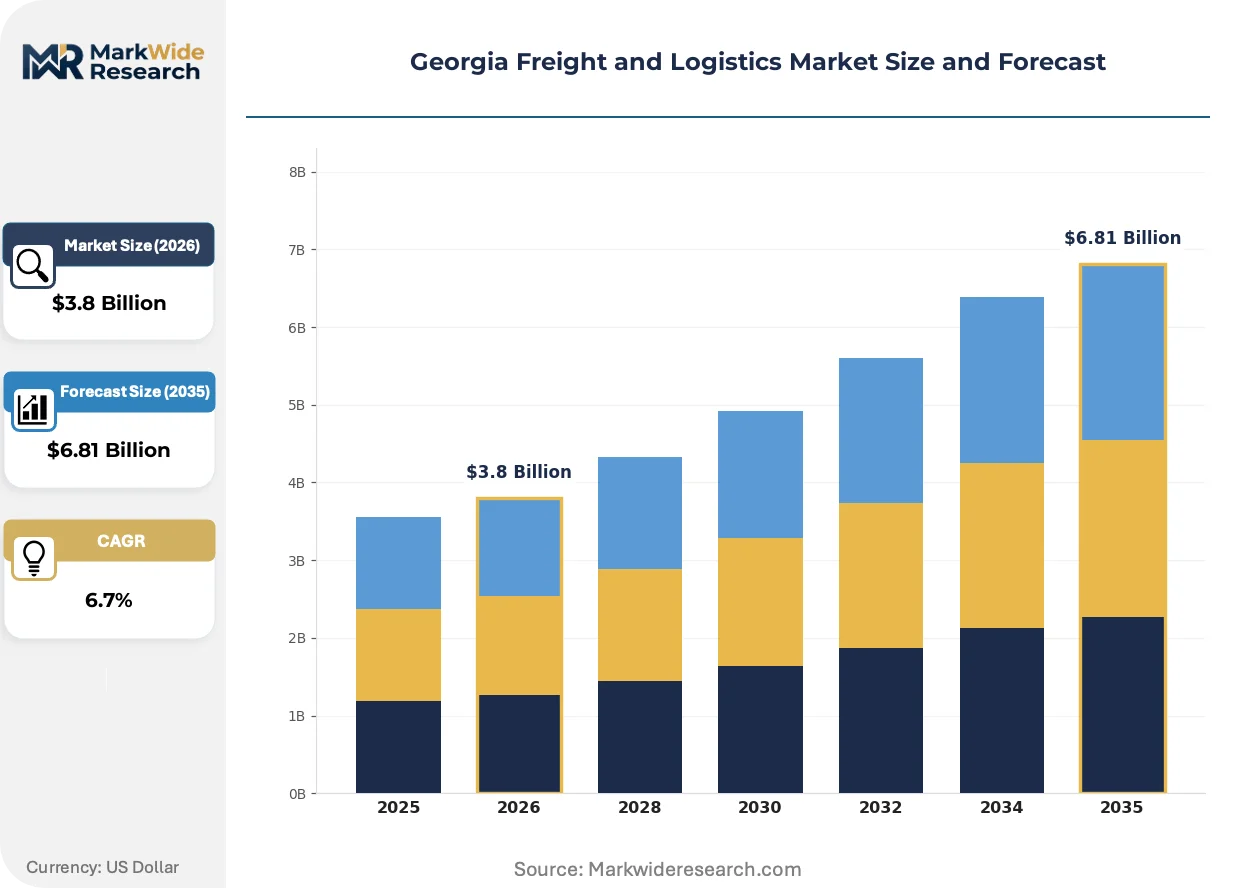
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Brokerage End User: Retailers, Manufacturers, E-commerce, Wholesalers Technology: GPS Tracking, TMS, RFID, Robotics Delivery Mode: Road, Rail, Air, Water |
| Companies Covered | FedEx Freight, XPO Logistics, Old Dominion Freight Line, AJC Freight Solutions, Value Logistics, Falcon International, American Global Logistics, Syfan Logistics, TRT International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Georgia Freight and Logistics Market Trends and Innovations
Technology deployment across Georgia's freight infrastructure is fragmenting operational models, with automation investments concentrating in specific corridors while traditional methods persist elsewhere. Three distinct patterns are emerging from this uneven adoption landscape.
Autonomous yard trucks are bifurcating distribution center operations across the Port of Savannah hinterland. Large import receivers at Garden City and Pooler are deploying driverless terminal tractors for container repositioning, compressing turn times and reducing labor dependency. Mid-sized warehouses lacking capital depth continue manual yard operations, creating a two-tier productivity gap that is reshaping competitive positioning in drayage contracting.
FMCSA has expanded its Safety Measurement System to incorporate vehicle maintenance severity weights, elevating preventive maintenance compliance to a determinative factor in carrier selection. Georgia-based fleets are accelerating telematics deployment to predict component failures before roadside inspection triggers. Refrigerated carriers serving the state's poultry and produce corridors face the steepest compliance cost escalation due to reefer unit complexity.
Shippers are consolidating freight procurement through transportation management platforms that aggregate spot market access with contracted lane pricing. Large retail and manufacturing buyers in Metro Atlanta are displacing traditional broker relationships with direct API connections to carrier networks. This disintermediation is most pronounced among e-commerce fulfillment operations where delivery window compression demands real-time capacity visibility.
Georgia Freight and Logistics Market Segmentation
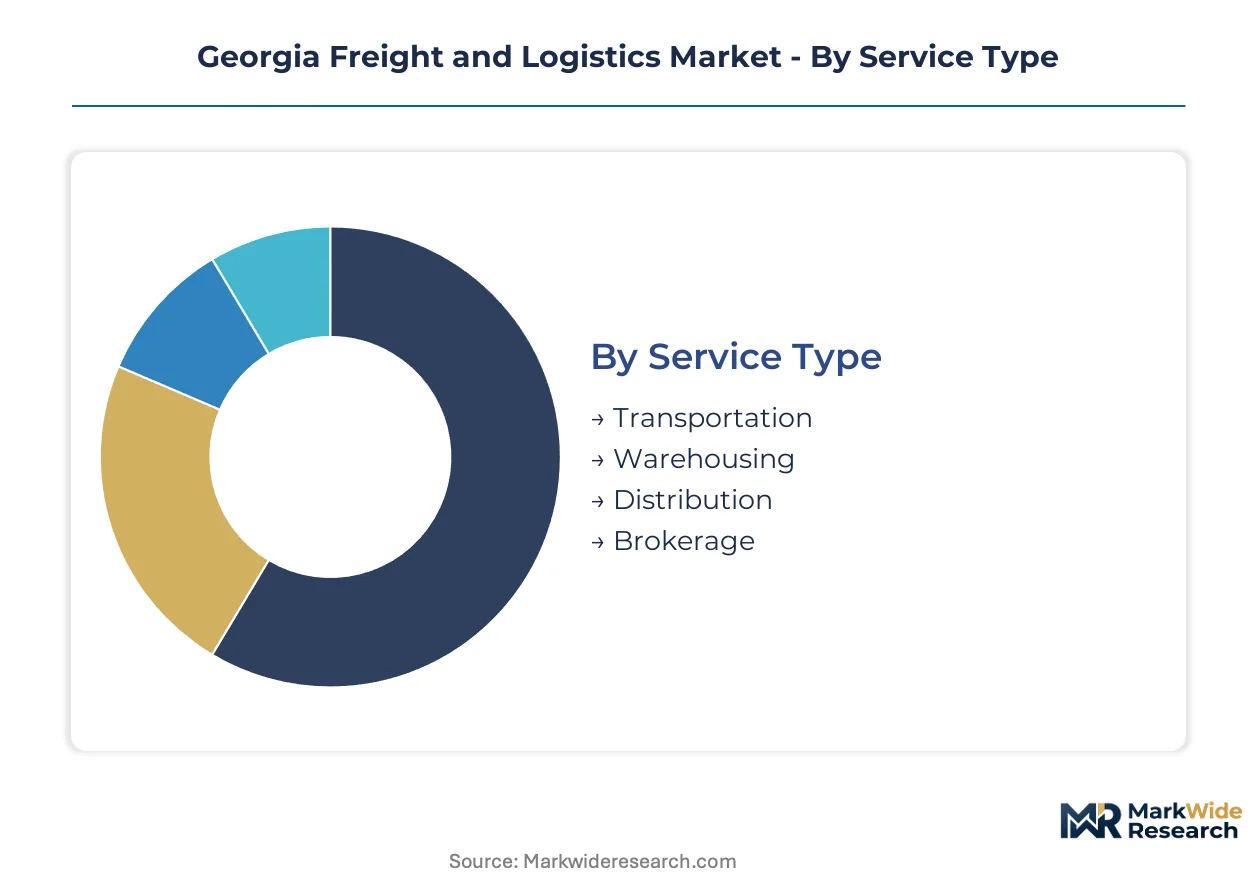
Segmentation reveals how capital allocation and operational priorities diverge across Georgia's freight corridors. Understanding these divisions exposes where automation investments concentrate and which customer types command premium service tiers.
Service Type:
Transportation services dominate contract volumes through dedicated lane networks, while warehousing and brokerage capture margin from volatility and inventory positioning needs.
- Transportation:Full truckload and LTL operations move cargo across I-75, I-85, and I-20 corridors with fleet assets owned or contracted by carriers. Demand concentrates around Atlanta's distribution hub and the Port of Savannah drayage radius as container volume expands.
- Warehousing:Facilities provide storage, cross-docking, and value-added services with square footage multiplying near Garden City Terminal. E-commerce fulfillment requirements are pulling speculative development into Central Savannah River Area industrial parks.
- Distribution:Consolidated fulfillment operations synchronize last-mile delivery with inventory staging across Metro Atlanta nodes. Retailers and manufacturers leverage these networks for regional market coverage.
- Brokerage:Non-asset intermediaries match spot market freight with available capacity, capturing margin from lane imbalances and seasonal demand surges.
By volume, Transportation leads. By growth pace, Warehousing is expanding most quickly.
End User:
Customer type determines service specifications, with e-commerce platforms demanding compressed delivery windows that reshape facility location decisions.
- E-commerce:Online retailers require same-day and next-day fulfillment capabilities with automated sortation and dense last-mile node networks. Metro Atlanta's population concentration supports this tier's infrastructure investments.
- Retailers:Brick-and-mortar chains maintain regional distribution centers for store replenishment with predictable seasonal patterns. Their procurement emphasizes contracted lane stability over spot market flexibility.
- Manufacturers:Industrial shippers coordinate inbound raw materials and outbound finished goods through synchronized production schedules. Port of Savannah rail connections serve their import-dependent supply chains.
- Wholesalers:Intermediate distributors aggregate smaller shipments for redistribution to independent retailers with less frequent delivery requirements.
E-commerce commands the steepest rate premiums. Manufacturers anchor the largest contract volumes.
Technology:
Technology deployment separates capital-intensive operators from competitors relying on legacy systems, with adoption clustering around specific corridor infrastructure.
- GPS Tracking:Real-time location monitoring enables dynamic routing adjustments and delivery window predictions. Fleet operators across Georgia's interstate network treat this as baseline capability.
- TMS:Transportation management systems optimize load matching, carrier selection, and freight audit processes. Large shippers in Metro Atlanta displace manual procurement with platform-based automation.
- RFID:Radio-frequency identification automates inventory visibility without line-of-sight scanning requirements. Distribution centers serving retail and manufacturing deploy this for yard management and asset tracking.
- Robotics:Autonomous mobile robots and automated storage systems compress labor dependency in high-throughput fulfillment operations. Garden City Terminal hinterland facilities lead deployment due to land availability and capital depth.
GPS Tracking saturates the market. Robotics is gaining share fastest among new facility investments.
Delivery Mode:
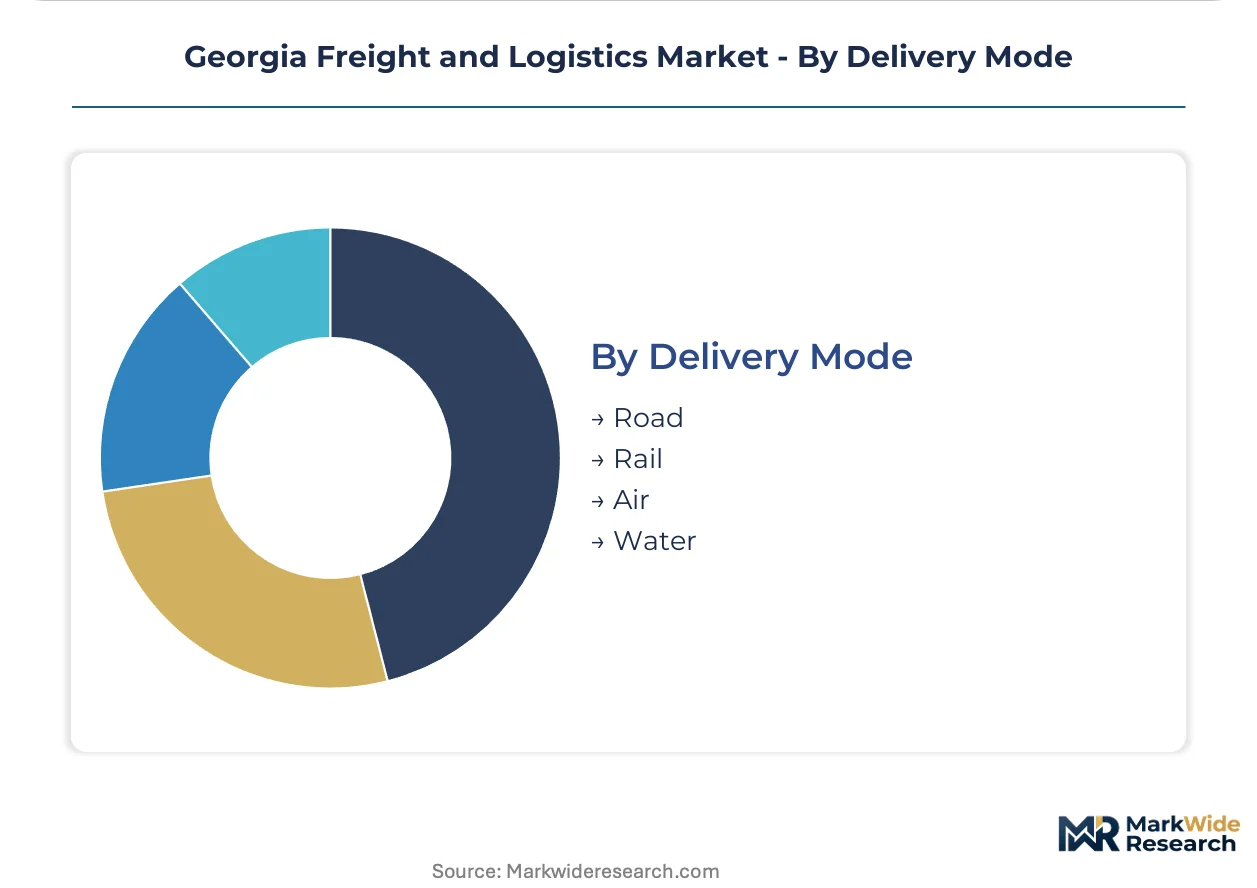
Modal choice reflects distance, cargo characteristics, and infrastructure access, with road transportation dominating due to network density.
- Road:Trucking handles the majority of freight weight and value with door-to-door flexibility across Georgia's interstate grid. Driver availability constraints are accelerating automation interest in this segment.
- Rail:Intermodal service connects Port of Savannah to inland Southeast markets with lower per-ton costs for bulk and containerized cargo. Norfolk Southern and CSX operate the primary corridors.
- Air:Hartsfield-Jackson Atlanta International Airport supports time-definite express shipments and high-value cargo with integrated carrier networks. Premium pricing limits this mode to urgent or lightweight freight.
- Water:Barge and coastal shipping moves bulk commodities through Georgia's river systems and Atlantic access. Savannah Harbor deepening has expanded vessel capacity for international container trade.
Road carries the greatest tonnage. Rail is climbing the fastest on Port of Savannah volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metro Atlanta consumes logistics services differently than the Port of Savannah corridor, with the former demanding compressed last-mile fulfillment and the latter prioritizing container drayage and transload capacity. This geographic split shapes infrastructure investment patterns across Georgia's freight network.
Metro Atlanta
E-commerce fulfillment nodes and retail distribution centers drive warehousing demand across Fulton and Gwinnett counties. The Georgia Department of Transportation coordinates interstate capacity expansion along I-285 and I-85 to relieve congestion. Hartsfield-Jackson Atlanta International Airport anchors air cargo operations for time-definite shipments.
Port of Savannah Corridor
Container volume through Garden City Terminal generates drayage demand and transload facility construction in Chatham County. EPA SmartWay certification requirements shape carrier eligibility for shipper contracts. Pooler and Richmond Hill industrial parks attract cold chain and manufacturing logistics tenants seeking rail-served acreage.
Central Savannah River Area
Underutilized industrial land within fifty miles of the port offers lower development costs than Chatham County. Georgia's electric vehicle tax credits reduce total cost of ownership for medium-duty fleet electrification. Augusta and surrounding counties host manufacturing logistics operations leveraging Norfolk Southern rail connections.
I-75 Corridor
Manufacturing supply chains coordinate inbound materials and outbound finished goods through Macon and Valdosta distribution points. FMCSA hours-of-service limits constrain fleet utilization on north-south trucking routes. Perry and Tifton serve as staging locations for agricultural product consolidation.
Georgia Freight and Logistics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Georgia's freight market. National LTL carriers and global parcel networks command contracted lane volumes through terminal ownership and density advantages. Regional brokers and drayage specialists capture spot market margin from port corridor volatility. Competitive moves concentrate on terminal network expansion and technology platform deployment.
Among national LTL operators, Old Dominion Freight Line, FedEx Freight, and XPO Logistics occupy positions across the premium service tier. These carriers exemplify scale-driven density strategies through dedicated lane networks and proprietary optimization tools. Their presence anchors service expectations for shipper procurement decisions statewide.
| Leading Market Players |
|---|
| FedEx Freight |
| XPO Logistics |
| Old Dominion Freight Line |
| AJC Freight Solutions |
| Value Logistics |
| Falcon International |
| American Global Logistics |
| Syfan Logistics |
| TRT International |
| Others |
Pricing and Supply Chain Analysis
EPA SmartWay certification gates carrier access to contracted freight lanes while simultaneously stratifying rate tiers across Georgia's interstate corridors. Shippers with verified emissions procurement criteria pay premiums for certified capacity, compressing margins for non-compliant operators locked into spot market exposure.
Pricing Analysis
Long-term contracted offtake agreements dominate volume commitments between national LTL carriers and Metro Atlanta retail networks, insulating pricing from diesel volatility. Three-tier pricing structure across EPA-certified premium, standard-compliant, and non-certified economy tiers separates Old Dominion and FedEx Freight from regional brokers. Cost compression in the spot drayage tier is intensifying because chassis shortages at Garden City Terminal extend container dwell times. Small fleet operators exhibit highest price sensitivity due to absent hedging mechanisms.
Supply Chain Analysis
Inventory positioning requirements have compressed to same-day fulfillment windows across Metro Atlanta e-commerce nodes, forcing regional distribution centers to hold safety stock within fifteen-mile delivery radii. Equipment manufacturing for aerodynamic retrofits and telematics hardware draws from Mexico, China, and domestic Midwest suppliers. Semiconductor content in ELD units and autonomous yard systems creates single-source vulnerability through Taiwanese foundry concentration. Distribution runs through asset-light brokerage networks for spot capacity and dedicated terminal networks for contracted lanes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Georgia freight and logistics is cycling through a recovery phase as Port of Savannah container volumes rebuild import-dependent supply chain velocity. Inventory restocking across Southeast manufacturing corridors is pulling contracted lane demand ahead of spot market stabilization.
For Market Incumbents: Consolidate terminal density around I-75 and I-85 corridors to defend against asset-light brokers capturing margin from lane imbalances. Expand proprietary fleet optimization platforms to deepen vertical integration into dispatch automation. Prioritize EPA SmartWay recertification investments to maintain shipper procurement eligibility as emissions criteria tighten.
For New Entrants and Emerging Players: Lead with electric vehicle fleet deployments targeting Central Savannah River Area industrial parks where Georgia tax credits reduce total cost of ownership. Target cold chain drayage from Garden City Terminal to underpenetrated Augusta manufacturing corridors. Position through API-first brokerage platforms offering real-time capacity visibility to displace traditional phone-based dispatch relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across autonomous trucking pilot corridors between Savannah and Atlanta as supervised deployment scales. Long-term viability favors terminal-owning LTL operators with density advantages in the 5-10 year automation transition. Watch FMCSA autonomous vehicle regulatory framework expansion as the signal for accelerated technology deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Network Expansion | Old Dominion and XPO deepen southeastern density through owned facilities along I-75. |
| Electric Fleet Conversion | Georgia utility rebates reduce medium-duty electrification costs for regional route operators. |
| Autonomous Yard Deployment | Garden City Terminal receivers compress container turn times with driverless terminal tractors. |
| SmartWay Recertification | Shipper procurement criteria increasingly mandate verified emissions performance for lane eligibility. |
| API Platform Integration | Large Atlanta retailers displace traditional brokers with direct carrier network connections. |
Research Methodology
A standing panel of fleet operations directors, shipper procurement managers, port authority planners, and FMCSA compliance officers provided ongoing calibration against secondary data from Georgia Department of Transportation infrastructure disclosures, EPA SmartWay carrier certification records, and Norfolk Southern intermodal volume reports. Primary fieldwork combined structured interviews with terminal managers and warehouse operators across Chatham, Fulton, and Gwinnett counties with bottom-up capacity modeling and top-down trade flow validation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled transportation mode, service tier, end-user vertical, and technology adoption rate as segmentation dimensions. CAGRs were derived from trend extrapolation of port container volume, e-commerce fulfillment square footage expansion, and fleet electrification penetration curves calibrated to Georgia-specific incentive programs.
The analysis sits within stated boundaries; outcomes outside sustained diesel price stability or accelerated FMCSA autonomous vehicle rulemaking would require recalibration. Forecasts reflect assumptions about labor availability, chassis fleet sizing, and shipper procurement criteria evolution. Revision becomes warranted when Port of Savannah volume growth or electric vehicle infrastructure deployment crosses thresholds outside modeled ranges.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Sri Lanka Freight and Logistics Market
Logistics and Shipping
Asia Pacific (APAC) Contract Logistics Market
Logistics and Shipping
ISO Shipping Container Market
Logistics and Shipping
China less than-Truck-Load (LTL) Market
Logistics and Shipping
GCC Trailer Market
Logistics and Shipping
Germany Automotive 3PL Market
Logistics and Shipping
North America Cargo Handling Equipment Market
Logistics and Shipping
Pharmaceutical Logistics Market
Logistics and Shipping
United Kingdom Third Party Logistics (3PL) Market
Logistics and Shipping
Latin America Freight Forwarding Market
Logistics and Shipping
Global Container Terminal Operations Market
Logistics and Shipping
South America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Asia-Pacific Last Mile Delivery Market
Logistics and Shipping
Remanufacturing and Core Returns Logistics Management Market
Logistics and Shipping
Finished Vehicle Logistics Market
Logistics and Shipping
Air Freight Market