
 Poland Courier, Express, and Parcel (CEP) Market | 2026-2036
Poland Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Courier, Express, and Parcel (CEP) Market Insights
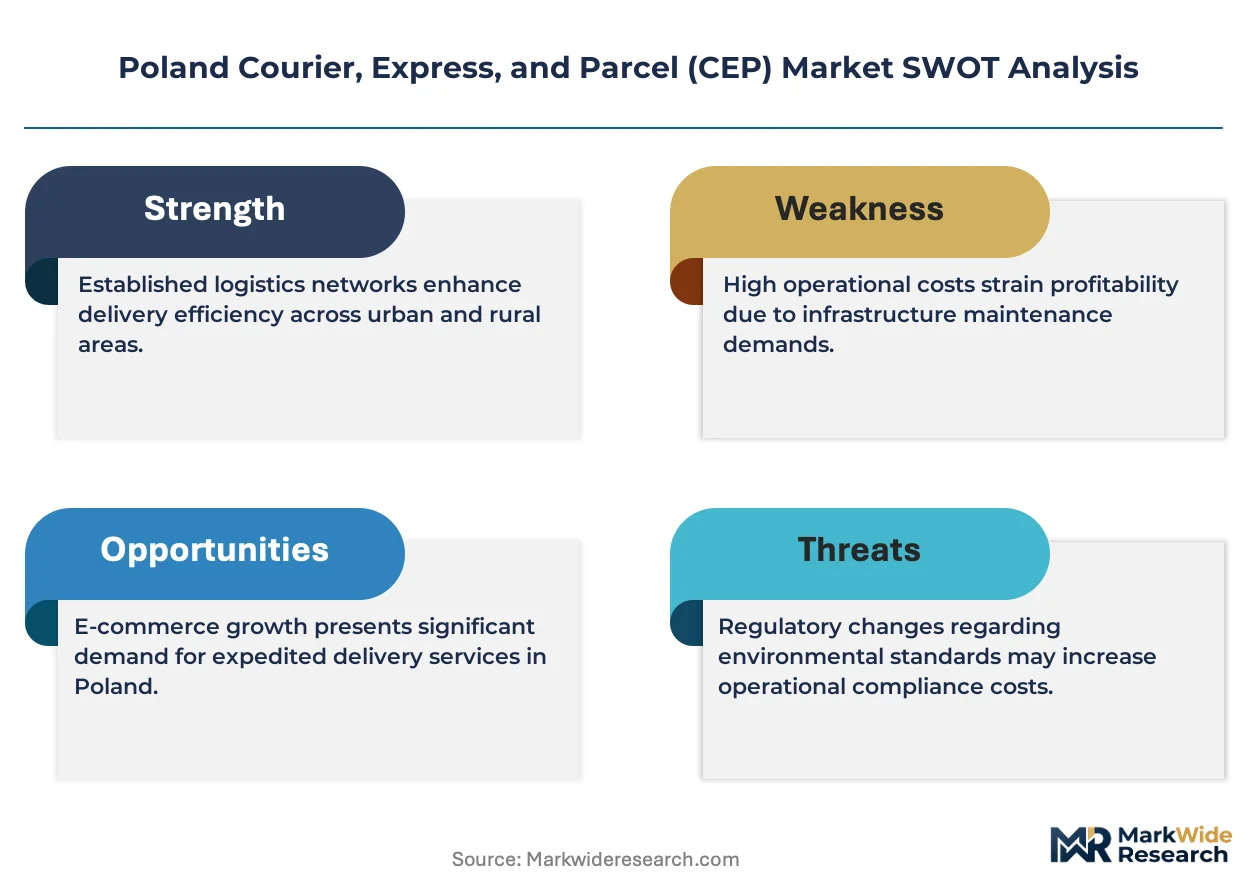
E-commerce retail is restructuring Poland's CEP demand profile, pulling volume away from traditional B2B document services toward home-delivered parcels. InPost leverages Europe's largest automated parcel locker network to dominate last-mile density in Polish cities. DPD Polska sustains next-day coverage through a hub-and-spoke infrastructure anchored near Łódź. GLS Poland competes on cross-border connectivity into Germany and the Czech Republic.
Courier, Express, and Parcel services encompass time-definite shipment of documents and goods through integrated collection, sorting, line-haul, and last-mile distribution networks operating on standardized service level agreements with track-and-trace capability. Same-day delivery commands premium pricing but remains operationally concentrated in Warsaw and Kraków, where micro-fulfillment nodes enable sub-two-hour cycles. Locker service is expanding fastest among delivery models as InPost's open-network model reduces failed-delivery costs for multiple carriers. Small parcels generate the highest unit margin within package size tiers due to automated sortation compatibility and minimal manual handling.
Poland's CEP sector operates under EU Green Deal emission targets enforced by national climate regulators, while the Polish Financial Supervision Authority monitors payment integrations within digital delivery platforms. The EU AI Act will shape automated route-optimization and customer-data processing investments. Stakeholders must weigh locker-network saturation against drone-delivery pilot programs as they allocate capital across last-mile modalities.
Market Dynamics
E-commerce parcel volumes are compressing traditional B2B document flows while EU Green Deal emission mandates force fleet electrification across Polish last-mile networks. This dual pressure is restructuring carrier economics and infrastructure deployment priorities.
Growth Catalysts
- EU Green Deal fleet mandates:National climate regulators enforce progressive emission reductions, accelerating electric van and cargo-bike adoption in urban delivery zones.
- Warsaw-Kraków corridor density:Metropolitan population clustering enables route consolidation and micro-fulfillment node placement that cuts per-stop costs.
- Automated parcel locker networks:Open-network locker infrastructure reduces failed-delivery rates and carrier handoff friction in dense residential districts.
Market Restraints
- Driver labor scarcity:HGV operator shortages in the Silesian logistics belt constrain line-haul capacity expansion during peak volume windows.
- Last-mile real estate inflation:Micro-fulfillment site rents in central Warsaw have outpaced sortation automation savings, squeezing urban delivery margins.
- Cross-border customs friction:Non-EU origin parcels face enhanced documentation requirements at Polish border checkpoints, delaying east-west transit.
Strategic Opportunities
- Łódź hub-and-spoke modernization:Central Poland's existing freight infrastructure supports expanded next-day coverage into underserved secondary cities.
- Renewable fleet financing:EU Green Deal subsidy frameworks offset electric commercial vehicle acquisition costs for compliant operators.
- Locker-to-locker international routing:Cross-border locker interoperability with Czech and German networks opens parcel consolidation arbitrage.
Industry Challenges
- Route optimization software integration:Legacy dispatch systems require costly API overhauls to interface with real-time traffic and locker availability data.
- Electric vehicle charging infrastructure:Depot and public fast-charging gaps in eastern voivodeships limit range planning for battery-electric delivery fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Courier, Express, and Parcel (CEP) Market |
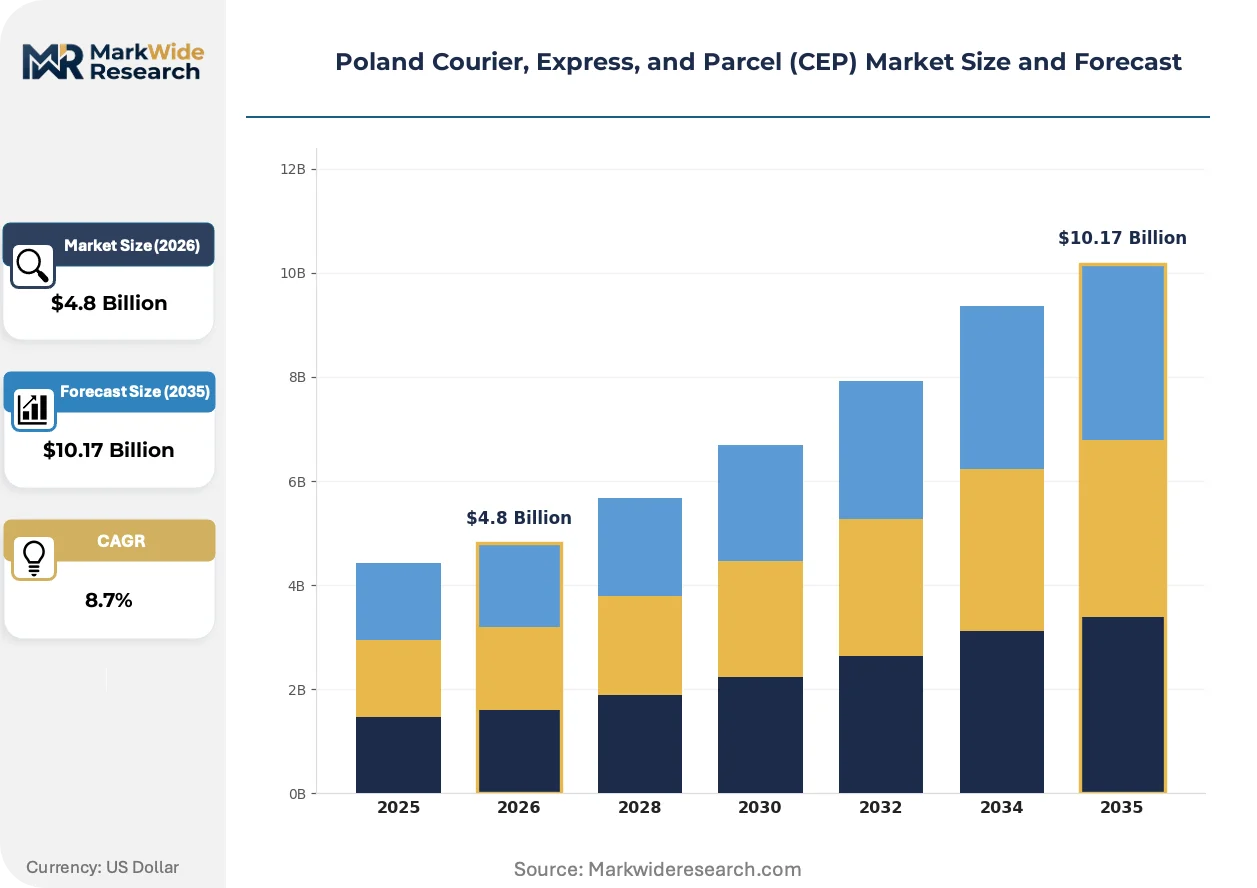
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Delivery, Same-Day Delivery, Next-Day Delivery, International Shipping Package Size: Small Parcels, Medium Parcels, Large Parcels, Pallets Delivery Model: Door-to-Door, Drop-Off, Locker Service, Click & Collect End User: E-Commerce, Retail, Manufacturing, Pharmaceuticals |
| Companies Covered | GLS Poland, Orlen Paczka, InPost, UPS, Geis Parcel PL, DPD Polska, DHL Group, FedEx, Poczta Polska, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Courier, Express, and Parcel (CEP) Market Trends and Innovations
Digital delivery platforms are embedding payment and tracking into unified interfaces, compressing the traditional separation between logistics execution and customer transaction layers. This convergence is altering how carriers monetize delivery data and customer relationships.
Automated parcel locker networks are expanding into residential complexes and transit stations across Polish metropolitan areas. Major e-commerce merchants and grocery chains are installing proprietary and third-party locker banks at accelerating pace. This infrastructure is expanding into secondary cities and suburban zones previously dependent on door delivery, enabling carriers to consolidate drop density and reduce per-parcel last-mile costs.
EU AI Act provisions on automated decision-making are shaping route-optimization algorithm deployments across Polish CEP operations. Carriers must document logic transparency and human oversight protocols for AI-driven dispatch systems. Express and same-day segments face the steepest compliance burden given their reliance on real-time dynamic routing engines that optimize driver assignments and delivery sequences.
Polish consumers are consolidating purchase volumes around fewer, larger e-commerce baskets to qualify for free shipping thresholds. This basket-size inflation is shifting parcel weight distributions toward heavier, bulkier shipments that strain automated sortation compatibility. Fashion and home goods verticals show the most pronounced concentration of multi-item orders, pressuring carriers to adapt handling protocols and pricing structures for non-standard parcel dimensions.
Poland Courier, Express, and Parcel (CEP) Market Segmentation
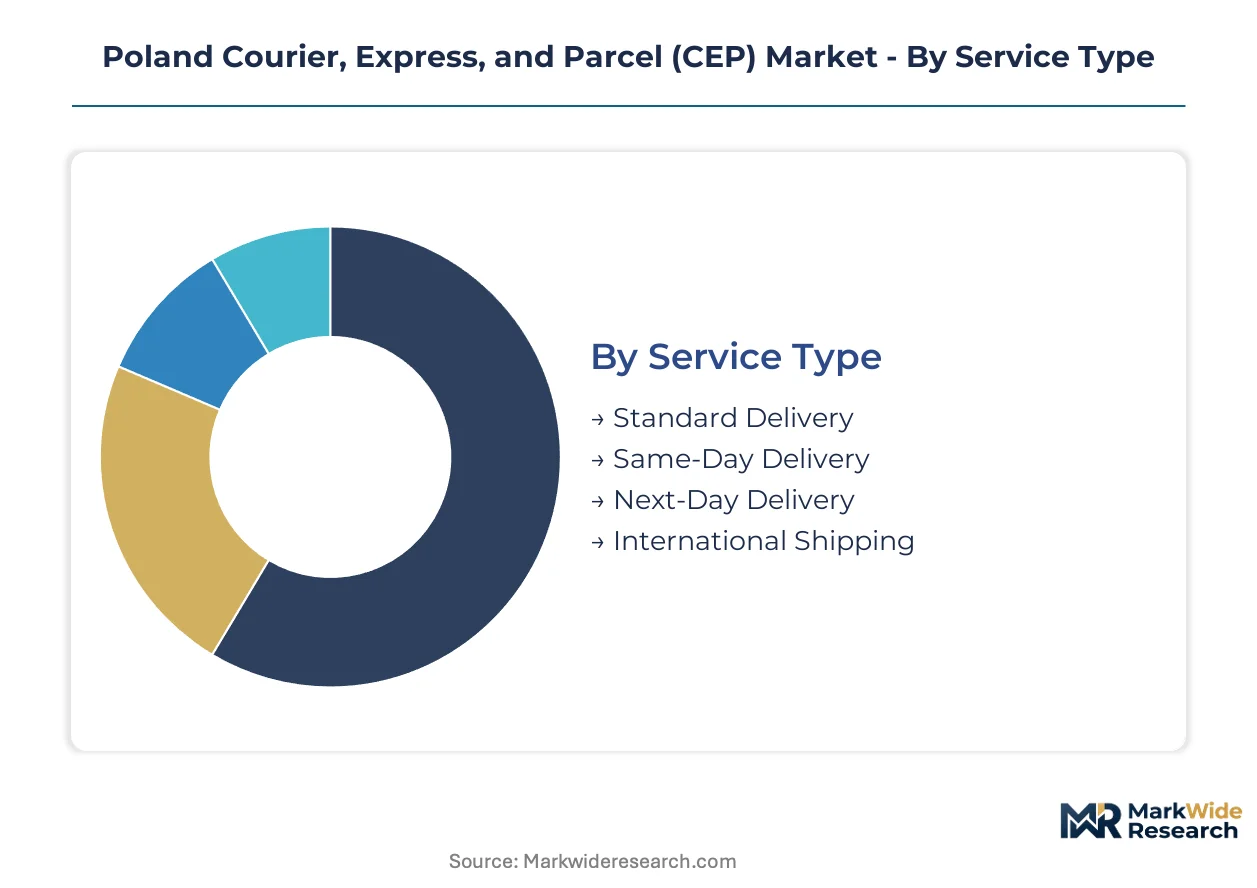
Poland's CEP market segments reflect divergent infrastructure requirements and margin profiles. Service velocity, package dimensions, delivery modality, and end-use vertical each command distinct operational investments and pricing power.
Service Type:
Upgrade cycles in delivery speed preferences are shortening as Polish e-commerce platforms compete on fulfillment promises. Carriers must balance network density against premium service premiums.
- Standard Delivery:Two-to-three-day ground transit dominates parcel volumes through consolidated line-haul networks. Warsaw and Silesian corridor shippers favor this tier for non-urgent inventory replenishment where cost minimization outweighs velocity.
- Same-Day Delivery:Sub-two-hour urban cycles require micro-fulfillment nodes and dynamic dispatch algorithms. Kraków and Warsaw concentration enables premium pricing, though EU AI Act compliance burdens constrain automated routing deployments.
- Next-Day Delivery:Overnight hub sorting at Łódź facilities supports nationwide coverage. National climate regulators scrutinize diesel-powered night-line emissions under EU Green Deal fleet mandates.
- International Shipping:Cross-border flows face documentation friction at non-EU origin checkpoints. Czech and German corridor routes absorb the densest east-west parcel traffic.
Volume placements concentrate in Standard Delivery; the faster expansion belongs to Same-Day Delivery.
Package Size:
Cost tier segmentation aligns sortation automation compatibility with manual handling intensity. Polish carriers optimize hub configurations around dimensional weight pricing breakpoints.
- Small Parcels:Automated belt sortation handles standardized dimensions with minimal labor intervention. E-commerce fashion and electronics verticals in metropolitan districts drive the densest small-parcel flows.
- Medium Parcels:Semi-automated handling accommodates home goods and multi-item baskets. Basket-size inflation from free-shipping thresholds is pushing parcel weight distributions toward this tier.
- Large Parcels:Manual sortation and dedicated vehicle compartments increase per-unit handling costs. Furniture and appliance merchants in Warsaw suburbs generate concentrated demand.
- Pallets:Full-truckload line-haul integration serves manufacturing and retail distribution centers. Silesian industrial zones anchor pallet volume concentration.
Margin optimization targets Small Parcels; dimensional complexity is climbing fastest in Medium Parcels.
Delivery Model:
Customer type preferences are fragmenting across convenience-versus-control trade-offs. Residential density and building access patterns shape model viability.
- Door-to-Door:Direct residential delivery maintains premium service positioning despite failed-delivery cost exposure. Central Warsaw apartment blocks sustain highest per-stop density.
- Drop-Off:Recipient absence drives alternative collection point utilization. Secondary city coverage gaps limit model penetration outside metropolitan cores.
- Locker Service:Automated parcel locker networks eliminate redelivery costs through 24-hour accessibility. InPost's open-network infrastructure dominates Polish urban residential deployment.
- Click & Collect:Retail chain integration enables order consolidation with existing store visits. Grocery and electronics merchants are expanding proprietary pickup location density.
Locker Service captures the steepest adoption trajectory; Door-to-Door retains the largest revenue base.
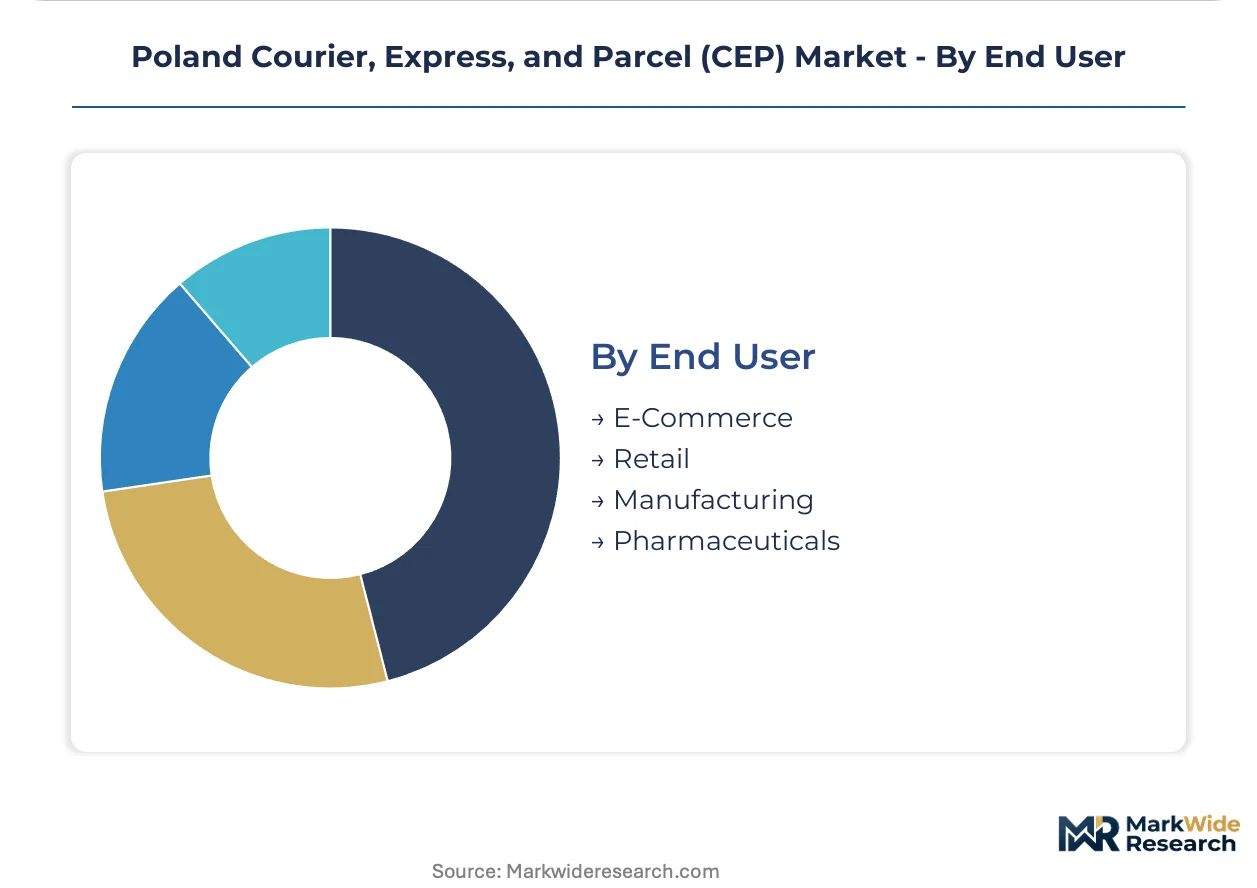
End User:
Application-specific requirements dictate service level agreements and handling protocols. Vertical specialization determines carrier technology investments.
- E-Commerce:Platform-integrated tracking and returns management dominate volume flows. Polish marketplace merchants are consolidating purchase volumes around fewer, larger baskets.
- Retail:Omnichannel fulfillment bridges physical and digital inventory pools. Store-based micro-fulfillment nodes support same-day coverage expansion.
- Manufacturing:Just-in-line parts delivery synchronizes with production schedules. Silesian automotive and electronics clusters generate time-definite shipment demand.
- Pharmaceuticals:Temperature-controlled transport and chain-of-custody documentation impose specialized fleet requirements. The Polish Financial Supervision Authority monitors payment integrations for prescription delivery platforms.
E-Commerce anchors current volume; Pharmaceuticals is gaining share fastest on premium service margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Katowice Special Economic Zone and adjacent logistics corridors concentrate Poland's CEP infrastructure investment, drawing parcel-sorting hubs and last-mile depots through tax incentives and proximity to Silesian manufacturing clusters.
Warsaw
E-commerce platform fulfillment contracts and same-day delivery velocity requirements dominate parcel volume generation in the capital. The Polish Financial Supervision Authority monitors payment integrations within digital delivery platforms operating from Warsaw headquarters. Micro-fulfillment nodes in Mokotów and Włochy districts enable sub-two-hour delivery cycles for premium service tiers.
Silesian Metropolitan Corridor
Automotive and electronics manufacturing clusters generate time-definite B2B shipment demand alongside consumer parcel flows. EU Green Deal emission targets enforced by national climate regulators accelerate electric van adoption in Katowice and Gliwice urban delivery zones. The Dąbrowa Górnicza logistics park anchors cross-border line-haul connections toward Czech and German networks.
Łódź
Central geographic positioning supports overnight hub sorting operations for nationwide next-day coverage. The city's freight infrastructure expansion receives EU cohesion fund allocations for sustainable logistics modernization. Pabianice and Konstantynów Łódzki subzones concentrate automated sortation facilities serving east-west parcel corridors.
Kraków
University-driven e-commerce consumption and tourism-related retail logistics sustain dense last-mile demand. The Lesser Poland voivodeship implements EU AI Act compliance protocols for automated route-optimization systems deployed by local carriers. Podgórze and Nowa Huta industrial zones host emerging locker-network installations.
Tri-City Metropolitan Area
Port logistics integration and Baltic Sea freight connections distinguish Gdańsk, Gdynia, and Sopot from inland distribution patterns. The Pomeranian special economic zone offers incentives for renewable fleet financing compliant with EU Green Deal frameworks. Container terminal proximity enables consolidated international parcel routing through maritime corridors.
Poland Courier, Express, and Parcel (CEP) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated carriers controlling premium express tiers while open-network operators capture locker-service density. The vendor base clusters around three strategic archetypes: automated locker-network specialists, hub-and-spoke integrators with central sorting infrastructure, and cross-border connectivity providers leveraging geographic adjacency. Consolidation pressure concentrates among mid-tier regional operators facing capital requirements for electric fleet conversion. Dominant competitive moves include locker-network territorial expansion and API-based platform integrations with e-commerce merchants.
Within the locker-network archetype, InPost anchors open-network infrastructure deployment across Polish residential districts. DPD Polska and GLS Poland exemplify hub-and-spoke integrators competing on next-day coverage density. Among international carriers, DHL Group and FedEx occupy positions bridging domestic last-mile networks with cross-border express corridors.
| Leading Market Players |
|---|
| GLS Poland |
| Orlen Paczka |
| InPost |
| UPS |
| Geis Parcel PL |
| DPD Polska |
| DHL Group |
| FedEx |
| Poczta Polska |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal fleet mandates gate both qualified supply and premium-tier pricing access, as national climate regulators enforce emission reductions that electric van and cargo-bike compliance costs feed into service rate structures. Polish carriers absorbing these conversion investments pass selective premiums through express and same-day tiers while standard delivery rates face compression from automated locker-network density gains.
Pricing Analysis
Lead-time-driven pricing stratification rewards velocity with premium capture: same-day delivery commands substantial markups in Warsaw and Kraków where micro-fulfillment nodes enable sub-two-hour cycles, while standard two-to-three-day ground transit minimizes unit costs through consolidated line-haul networks. Three-tier pricing structure across premium, standard, and economy levels differentiates by service velocity, parcel dimensional weight, and delivery modality convenience. Price erosion runs through standard delivery as locker-network expansion reduces failed-delivery costs and intensifies carrier competition. E-commerce merchants consolidating purchase volumes around free-shipping thresholds show least price sensitivity for premium velocity, while small marketplace sellers face acute margin pressure on standard-tier shipments.
Supply Chain Analysis
Logistics and freight costs concentrate supply chain investment around the Silesian metropolitan corridor and Warsaw logistics belt where warehouse density and population clustering enable route consolidation economies. The Łódź hub anchors east-west parcel flows through overnight sorting infrastructure, drawing from Czech and German cross-border connectivity. Electric vehicle charging infrastructure gaps in eastern voivodeships create single-source vulnerability for battery-electric fleet range planning. Distribution runs through hub-and-spoke sortation facilities feeding last-mile depots and automated locker terminals in metropolitan residential districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's CEP market is becoming a vertical-integration race as carriers pursue upstream control over locker-network infrastructure to capture last-mile margin and customer data assets.
For Market Incumbents: Deepen locker-network territorial density before saturation peaks, securing exclusive residential complex placements that lock out competitor access. Acquire proprietary micro-fulfillment sites in central Warsaw to defend against real estate inflation squeezing urban delivery margins. Electric fleet conversion subsidies from EU Green Deal frameworks offer cost-offset leverage against emerging entrants lacking scale for compliance investment. For New Entrants and Emerging Players: Launch via cross-border locker-to-locker routing partnerships with Czech and German networks, exploiting parcel consolidation arbitrage in east-west corridors underserved by incumbent density. Target secondary cities beyond Warsaw-Kraków concentration where hub-and-spoke coverage gaps persist and local carrier fragmentation creates partnership entry points. White-label API integrations with mid-tier e-commerce platforms bypass direct customer acquisition costs. For Investors and Strategic Acquirers: Łódź hub modernization announcements are the leading indicator that next-day coverage expansion into secondary cities is accelerating capital deployment. Mid-tier regional operators facing electric fleet conversion requirements represent prime acquisition targets for consolidation plays. Long-term viability hinges on locker-network saturation timing against drone-delivery pilot program maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Locker Network Territorial Expansion | InPost's open-network model reduces failed-delivery costs for multiple carriers across Polish residential districts. |
| Electric Fleet Conversion | EU Green Deal subsidy frameworks offset acquisition costs for compliant operators serving Warsaw urban zones. |
| API-Based Platform Integration | E-commerce merchant embedded tracking and payment compresses logistics-transaction separation layers. |
| Micro-Fulfillment Node Deployment | Mokotów and Włochy district sites enable sub-two-hour delivery cycles for premium service tiers. |
| Cross-Border Locker Interoperability | Czech and German network connections open parcel consolidation arbitrage for east-west routing efficiency. |
Research Methodology
Multi-period observation of parcel volume flows, locker-network deployment density, and fleet electrification progress anchored the trend analysis, supplemented by interviews with CEP operations directors, e-commerce logistics procurement managers, last-mile depot supervisors, and EU regulatory compliance officers. Secondary validation drew from Polish Financial Supervision Authority payment integration disclosures, national climate regulator emission target filings, EU AI Act implementation guidance, and customs documentation requirement updates at non-EU border checkpoints. Bottom-up carrier capacity modeling and top-down e-commerce spending trajectory analysis were triangulated against infrastructure investment announcements.
Segment-weighting across service type, package size, delivery model, and end-use vertical dimensions shaped volume and value distribution outputs across the analysis window. CAGRs were derived from trend extrapolation of e-commerce penetration rates, locker-network expansion curves, and fleet conversion timelines. Industry-specific forecast inputs included micro-fulfillment site rent inflation in central Warsaw and HGV operator shortage severity in the Silesian logistics belt.
Regulatory enforcement intensity shifts, cross-border customs friction escalation, and electric vehicle charging infrastructure deployment delays are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented operating parameters and stakeholder guidance. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Express Delivery Market
Logistics and Shipping
Freight and Logistics Market
Logistics and Shipping
Global Courier Market
Logistics and Shipping
Canada Freight and Logistics Market
Logistics and Shipping
China Cold Chain Logistics Market
Logistics and Shipping
Myanmar Freight and Logistics Market
Logistics and Shipping
Europe Sea Freight Forwarding Market
Logistics and Shipping
Chile Third-Party Logistics (3PL) Market
Logistics and Shipping
Shipping Container Market
Logistics and Shipping
Egypt Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
ASEAN Warehousing and Distribution Logistics Market
Logistics and Shipping
Global Automated Container Terminal Market
Logistics and Shipping
Ocean Freight Forwarding Market
Logistics and Shipping
Peru Cold Chain Logistics Market
Logistics and Shipping
Government and Education Logistics Market
Logistics and Shipping
Illinois Freight and Logistics Market