
 North America Dietary Supplements Market | 2026-2036
North America Dietary Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dietary Supplements Market Intelligence
Direct-to-consumer sales through online channels is reconfiguring margin pools away from traditional brick-and-mortar retail. Herbalife Nutrition Ltd. leverages its extensive distributor network to capitalize on this trend. Meanwhile, Glanbia PLC differentiates through its performance nutrition brands, while Amway Corp. sustains a strong presence via its independent business owner model.
Dietary supplements are products intended to supplement the diet, containing one or more dietary ingredients like vitamins, minerals, herbs, or amino acids. Their primary purpose is to provide nutrients that may otherwise not be consumed in sufficient quantities, delivered in forms such as tablets, capsules, or powders. The vitamins product type constitutes a mature and foundational segment of the market. Capsules remain a dominant form factor due to consumer convenience, while the online distribution channel is experiencing rapid expansion.
The regulatory environment in North America is principally governed by the United States' Food and Drug Administration (FDA) and Health Canada. These agencies enforce guidelines on labeling, good manufacturing practices (GMPs), and new dietary ingredient (NDI) notifications, directly influencing market access and product safety standards. Navigating the distinct regulatory requirements for marketing and claims substantiation between the U.S. and Canadian markets remains a critical strategic consideration for manufacturers.
Market Dynamics
The central structural force in the North America dietary supplements market is the tension between consumer demand for novel, effective ingredients and the stringent regulatory frameworks of the FDA and Health Canada, which govern product safety, formulation, and marketing claims.
Growth Catalysts
- Athlete Demand:Sustained demand from the athlete end-user segment for performance-enhancing and recovery-focused supplements, particularly those with clean-label and third-party certifications, stimulates product development in the sports nutrition category.
- Regulatory Clarity:The Dietary Supplement Health and Education Act (DSHEA) in the United States provides a defined, albeit strict, regulatory pathway for bringing many categories of supplements to market, which provides a degree of predictability for manufacturers.
- Preventative Health Focus:An aging population in both the United States and Canada is increasingly turning to supplements like vitamins and minerals for preventative healthcare and to address age-related health concerns, supporting foundational market segments.
Market Restraints
- Regulatory Hurdles:The FDA's New Dietary Ingredient (NDI) notification process is often a lengthy and expensive undertaking, creating a significant barrier to entry for innovative ingredients and slowing the pace of new product introductions.
- Raw Material Volatility:Heavy reliance on botanical ingredients sourced from specific international geographies exposes manufacturers to supply chain disruptions, quality inconsistencies, and significant price volatility driven by climate and geopolitical factors.
- Functional Food Substitution:The growing availability of functional foods and fortified beverages that offer similar health benefits in a more convenient format presents a direct substitution threat, competing for consumer spending on health and wellness.
Strategic Opportunities
- Personalized Nutrition:The convergence of digital health platforms with at-home biomarker testing creates an opportunity for data-driven, personalized supplement regimens delivered through direct-to-consumer subscription models, enhancing customer loyalty and lifetime value.
- Mexican Market Expansion:Mexico's growing middle class and rising health consciousness represent a significant, underpenetrated market within North America, offering expansion opportunities for brands that can navigate its distinct regulatory and distribution landscape.
- Specialized Formulations:There is white-space potential for developing supplements targeting niche but growing consumer needs, such as cognitive health for esports athletes, sleep support, and stress management linked to specific lifestyle factors.
Industry Challenges
- GMP Compliance Complexity:Maintaining consistent Good Manufacturing Practices (GMP) as mandated by the FDA and Health Canada is a major operational challenge, particularly for companies relying on a fragmented network of contract manufacturers and global suppliers.
- Claims Substantiation:The high cost and complexity of conducting the scientific research required to substantiate structure/function claims to the satisfaction of both the FDA and the Federal Trade Commission (FTC) remains a significant challenge.
- Counterfeit Product Proliferation:The rapid growth of online marketplaces creates challenges in policing the sale of counterfeit and adulterated supplements, which can erode consumer trust in legitimate brands and pose serious public health risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dietary Supplements Market |
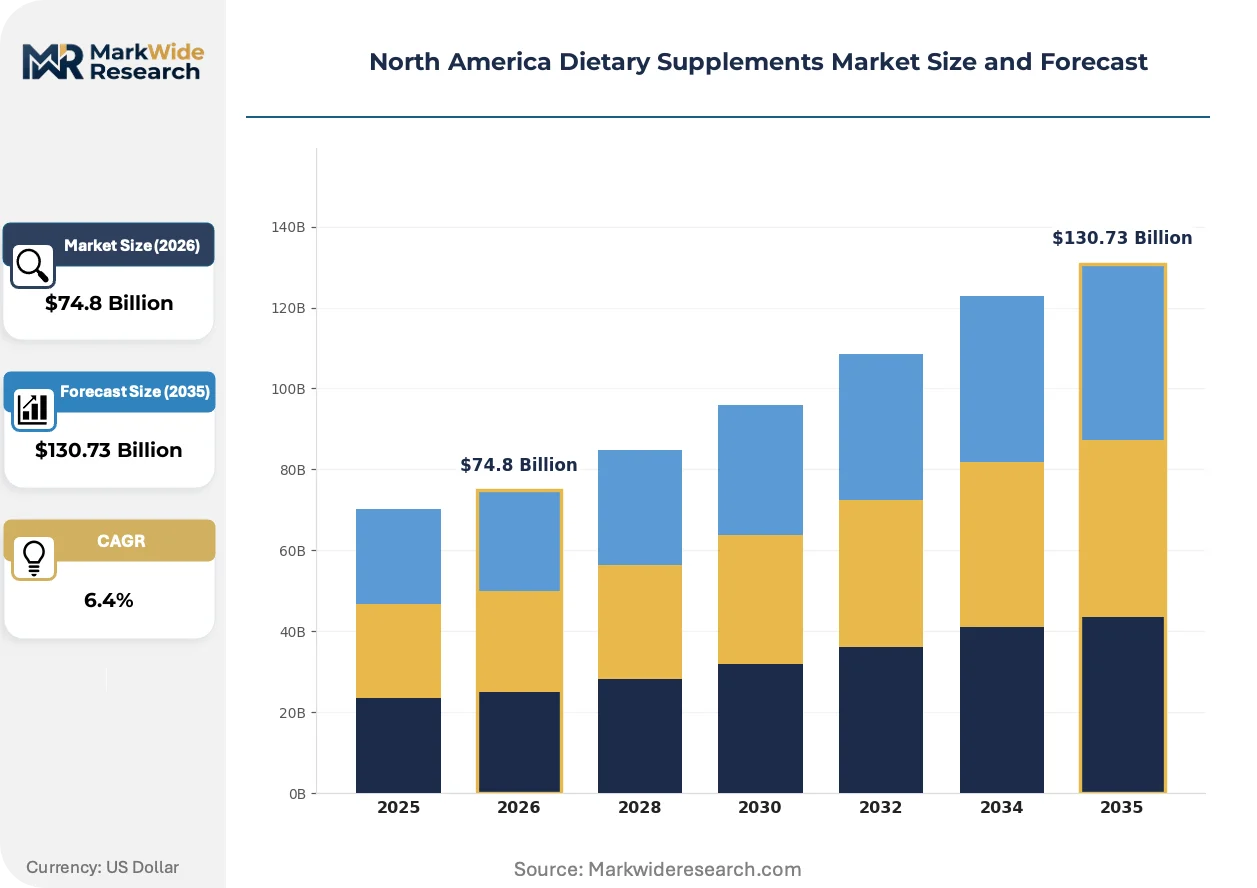
| Market Size in 2026 | $74.8 Billion |
| Market Size in 2035 | $130.73 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbs, Amino Acids End User: Adults, Children, Seniors, Athletes Form: Tablets, Capsules, Powders, Liquids Distribution Channel: Online, Drugstores, Supermarkets, Health Food Stores |
| Companies Covered | Amway Corp., Abbott Laboratories, Glanbia PLC, Bayer AG, Pfizer Inc., Herbalife Nutrition Ltd., ADM, GSK plc., Nature's Sunshine Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dietary Supplements Market Strategic Shifts & Innovations
The North America dietary supplements market is reshaping around the convergence of digital health technologies and consumer demand for greater transparency and personalization. This movement is reconfiguring product discovery, formulation science, and the very nature of brand-to-consumer relationships.
Personalized nutrition algorithms analyze user-provided health data, lifestyle questionnaires, and occasionally at-home biomarker test results to recommend supplement regimens. Health-conscious consumers and early adopters in the biohacking community are embracing these services for tailored nutritional support. This technology is virtualizing the role of a traditional nutritionist, enabling direct-to-consumer brands to create and scale customized vitamin and mineral packs.
The FDA's heightened enforcement of GMP standards and increased scrutiny of New Dietary Ingredient (NDI) notifications are raising the barrier for market entry. This regulatory pressure is forcing manufacturers to invest more substantially in quality control systems, supply chain verification, and clinical data to validate ingredient safety and identity. The herbal and botanical supplement segment is most affected, as firms must provide more rigorous data to satisfy both FDA and Health Canada requirements.
Consumers are increasingly shifting from purchasing single-ingredient bottles in retail stores to adopting curated subscription box models. This behavior disrupts the traditional brick-and-mortar channel, which is constrained by physical shelf space, and favors agile D2C brands that can offer customization and convenience. The trend is most visible in major metropolitan areas across the United States and Canada, where digital commerce adoption and wellness spending are highest.
North America Dietary Supplements Market Segmentation
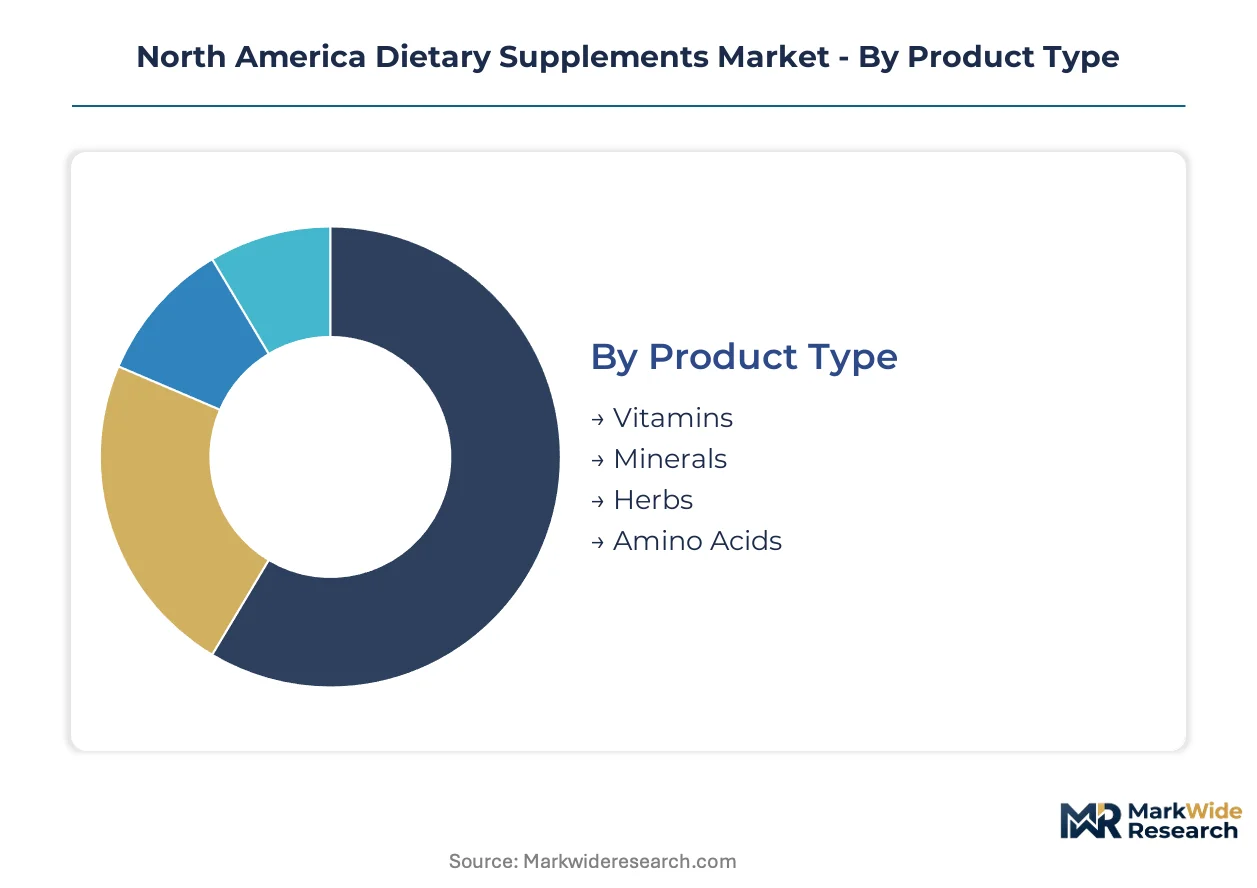
Segmenting the North America dietary supplements market reveals the diverse consumer needs, regulatory implications, and varied distribution strategies employed by manufacturers. This granular understanding allows stakeholders to tailor product development and marketing efforts effectively across the United States and Canada.
Product Type:
The innovation cycle and ingredient turnover rates vary significantly across different product types within the dietary supplements market.
- Vitamins:These essential micronutrients, including A, C, D, E, and B-complex, address foundational nutritional gaps. Demand remains consistently strong among the aging population in the United States and Canada for preventative health benefits.
- Minerals:This segment includes essential elements like calcium, magnesium, and zinc, vital for various bodily functions. Consumers in North America seek these for bone health and immune support.
- Herbs:Derived from botanical sources, such as turmeric or ashwagandha, these supplements often target specific health concerns like stress or inflammation. Increased regulatory scrutiny from the FDA and Health Canada impacts new product introductions.
- Amino Acids:These organic compounds, including BCAAs and creatine, are crucial for protein synthesis and muscle recovery. Athletes in both the United States and Canada drive significant demand for performance enhancement.
Vitamins dominate the installed base due to their widespread acceptance. Herbs are where expansion concentrates, driven by interest in natural health solutions.
End User:
Different end-user demographics drive distinct product formulations and marketing approaches across the North American market.
- Adults:This broad consumer base seeks supplements for general wellness, energy, and specific health concerns. Demand for foundational vitamins and minerals is consistent across the United States and Canada.
- Children:Formulations for this group often focus on immune support and healthy development, typically in palatable forms. Parents in North America prioritize safety and efficacy for their children's health.
- Seniors:This demographic increasingly uses supplements for age-related health issues like bone density, cognitive function, and joint health. Preventative health trends in the United States and Canada sustain demand.
- Athletes:This segment demands performance-enhancing, recovery-focused, and clean-label supplements to support rigorous training. Strong demand for third-party certified products comes from both US and Canadian athletes.
Growth in the Seniors segment reflects preventative health trends. Targeted solutions for Children are gaining traction in the North American market.
Form:
Consumer convenience and bioavailability considerations significantly influence product form preferences within the North American market.
- Tablets:These compressed solid dosage forms offer stability and precise dosing, making them a traditional choice for many supplements. They remain a cost-effective and widely available option.
- Capsules:Encapsulated ingredients provide ease of swallowing and mask unpleasant tastes, ensuring consumer compliance. Demand is high across all consumer segments in the United States and Canada due to convenience.
- Powders:This versatile form allows for higher dosages and customizability, often mixed into beverages or foods. Athletes and consumers seeking tailored regimens in North America drive demand for this format.
- Liquids:Offering rapid absorption and ease of consumption, liquid supplements are popular for those with swallowing difficulties or specific nutrient delivery needs. This form often appeals to children and seniors.
Capsules retain significant market share due to convenience. Powders show the steepest expansion trajectory, especially in sports nutrition.
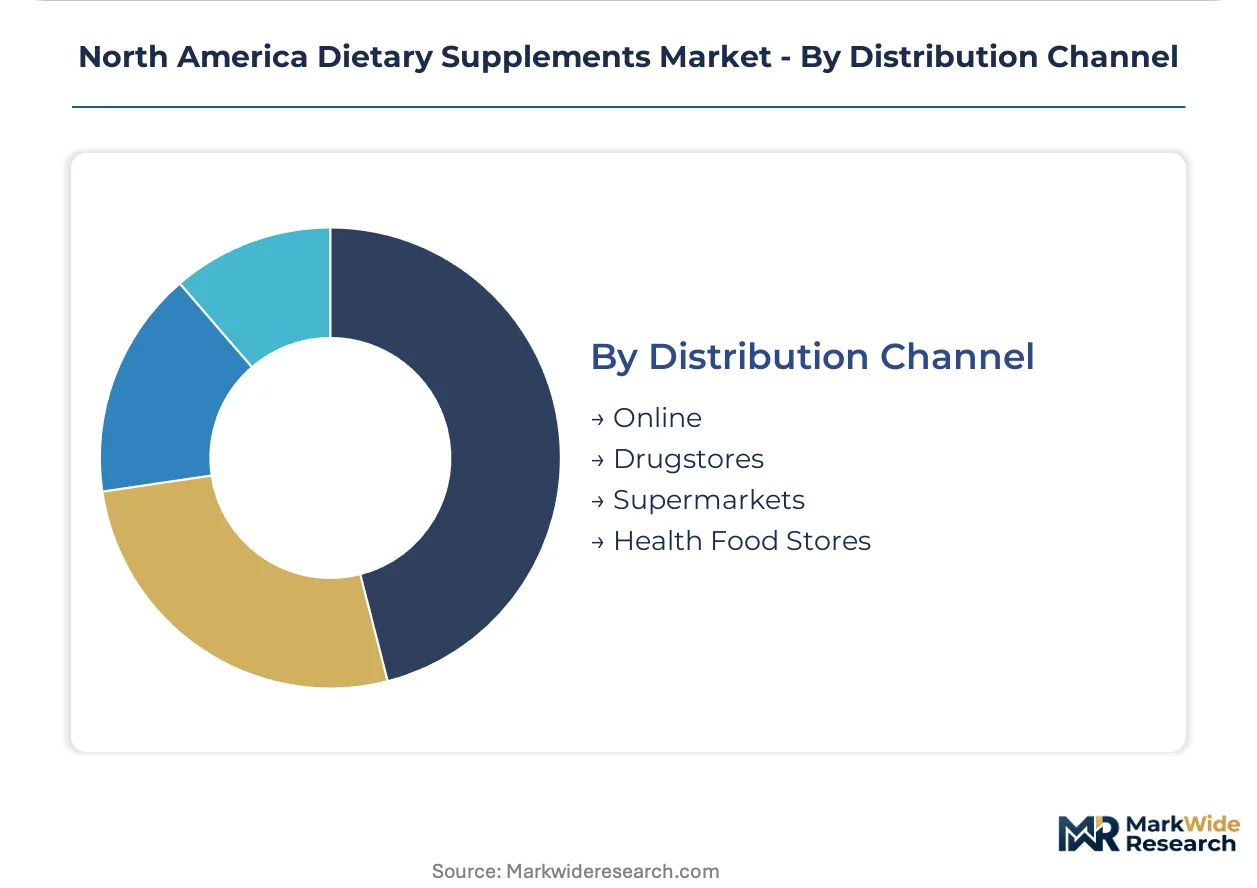
Distribution Channel:
Consumer purchasing habits and brand reach dictate the effectiveness of various distribution channels for dietary supplements in North America.
- Online:E-commerce platforms offer a wide selection, competitive pricing, and direct-to-consumer models. Demand for personalized subscriptions and niche products is strong in the United States and Canada.
- Drugstores:These retail outlets provide convenient access and a trusted environment for purchasing health products. Demand for established brands and over-the-counter vitamins remains consistent across North America.
- Supermarkets:Grocery stores offer accessibility for everyday shoppers, integrating supplement purchases into regular routines. This channel caters to general wellness products and mainstream brands.
- Health Food Stores:These specialized retailers cater to health-conscious consumers seeking natural, organic, and specialty supplements. They often provide expert advice and a curated product selection.
Traditional retail channels maintain broad reach across the region. Digital platforms are capturing new consumer segments with direct-to-consumer models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North America dietary supplements market exhibits varying demand elasticities, with some consumer segments showing price sensitivity for basic vitamins, while others prioritize premium, specialized formulations. This regional landscape is shaped by diverse health trends, regulatory frameworks, and distribution channel preferences. Manufacturers must adapt strategies to address these distinct market dynamics.
United States
Demand in the United States is driven by preventative health focus and a large, aging population seeking age-related solutions. The FDA's DSHEA provides a regulatory framework, with stringent requirements for new dietary ingredients. Major metropolitan areas like Los Angeles serve as innovation hubs, with strong consumer adoption of personalized nutrition.
Canada
Canadian consumers show consistent demand for foundational vitamins and minerals, alongside growing interest in natural health products. Health Canada regulates supplements under the Natural Health Products Regulations, emphasizing product safety. Toronto and Vancouver are key centers for product development, reflecting high health consciousness and digital commerce.
Mexico
Mexico's market expansion is fueled by a rising middle class, increasing health consciousness, and interest in wellness supplements. COFEPRIS oversees the regulatory environment, influencing product registration and marketing claims. Mexico City and Guadalajara represent significant consumer bases and emerging distribution networks.
California
California's demand is characterized by a strong wellness culture, early adoption of health trends, and high spending on specialized formulations. While under federal FDA oversight, California's Proposition 65 also influences labeling requirements. Silicon Valley is an innovation hotspot for personalized nutrition platforms and plant-based supplement development.
New York Metro
Consumers in the New York metropolitan area drive demand for premium, science-backed supplements, particularly those targeting cognitive health. The region operates under federal FDA regulations, but also sees heightened consumer scrutiny for product transparency. New York City acts as a major hub for health and wellness startups.
North America Dietary Supplements Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a dynamic competitive landscape. The market exhibits a tiered structure, ranging from large pharmaceutical and food conglomerates to specialized direct-to-consumer brands. Strategic archetypes include diversified health product giants, multi-level marketing powerhouses, and agile e-commerce-focused innovators. Portfolio diversification and strategic partnerships are dominant competitive moves, alongside continuous product innovation.
On the multi-level marketing vector, Herbalife Nutrition Ltd. and Amway Corp. exemplify extensive distributor networks, crucial for direct-to-consumer sales and sustained customer engagement. Glanbia PLC, a publicly traded company, represents a leader in performance nutrition brands, leveraging its global presence and established product portfolio across various athletic segments. These companies occupy distinct positions, reflecting varied strategies for market penetration, product innovation, and customer loyalty within the North American market. Their approaches highlight the diverse business models succeeding in the competitive dietary supplements space.
| Leading Market Players |
|---|
| Amway Corp. |
| Abbott Laboratories |
| Glanbia PLC |
| Bayer AG |
| Pfizer Inc. |
| Herbalife Nutrition Ltd. |
| ADM |
| GSK plc. |
| Nature's Sunshine Products, Inc. |
| Others |
Cost & Logistics Intelligence
Heavy reliance on botanical ingredients sourced from diverse international regions creates significant cost volatility upstream, directly influencing margin pools for finished products downstream. This upstream concentration of specialized raw materials shapes pricing power for manufacturers.
Pricing Analysis
Subscription models for personalized nutrition regimens drive significant customer lifetime value within the North America dietary supplements market. This market primarily utilizes a hybrid pricing model combining per-unit transactional sales with subscription-tiered offerings. Price differentiation stems from quality certifications, such as third-party testing for athletes, and the level of product customization. Pricing pressure intensifies for basic vitamins due to their commodity nature, while specialized formulations command premium pricing, reflecting lower price sensitivity among their target consumers.
Supply Chain Analysis
Strict regulatory controls on new dietary ingredients (NDIs) by the FDA and Health Canada effectively limit the flow of novel compounds into the North American market. The supply chain for dietary supplements draws from diverse international regions for botanical ingredients and specialized global suppliers for synthetic vitamins and minerals. Raw material price volatility and quality inconsistencies represent structural risks across this supply chain. Downstream, distribution runs through a hybrid model encompassing online direct-to-consumer channels and traditional retail outlets like drugstores and supermarkets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America dietary supplements market is experiencing a platform-economics inflection, driven by the emergence of digital health ecosystems enabling personalized nutrition solutions.
For Market Incumbents:Pre-empt competitive threats from agile direct-to-consumer brands by investing in digital platform capabilities and personalized nutrition algorithms. Consolidate supply chains for critical botanical ingredients to mitigate raw material volatility and ensure consistent quality. Strategic partnerships with digital health companies can extend reach and integrate supplement offerings into broader wellness programs, countering margin pressure from generic product lines.
For New Entrants and Emerging Players:Build out niche product lines targeting underserved or emerging consumer needs, such as cognitive health for esports athletes or specialized sleep support. The personalized nutrition segment, delivered via direct-to-consumer subscription models, represents a highly penetrable white-space opportunity. A strong go-to-market angle involves leveraging digital marketing and influencer partnerships to build community around specific health outcomes.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with established brands struggling to adapt to digital transformation or smaller, innovative D2C players seeking scale. Long-term viability in this market depends on acquiring companies with strong intellectual property in personalized nutrition algorithms or proprietary ingredient formulations. The signal to watch for inflection is sustained growth in subscription-based revenue models coupled with robust customer retention metrics.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Personalized Nutrition Platforms | Enhances customer loyalty and drives recurring revenue through tailored supplement regimens. |
| Strengthen Supply Chain Resilience | Mitigates risks from raw material volatility and ensures consistent product quality and availability. |
| Expand Direct-to-Consumer Channels | Captures new consumer segments and reconfigures margin pools away from traditional retail. |
| Obtain Third-Party Certifications | Builds consumer trust and differentiates products in competitive segments like sports nutrition. |
| Develop Niche Formulations | Addresses specific, unmet consumer health needs, opening new market segments for growth. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to build a comprehensive view of the North America dietary supplements market. Primary interviews included regulatory affairs leads, product development executives, brand managers, and procurement specialists. These insights were validated against secondary data from health and wellness publications, government health agency reports like those from the FDA and Health Canada, and industry association statistics. This approach allowed for robust bottom-up and top-down triangulation.
The calibration approach involved segmenting the market across product type, end-user demographics, form factor, and distribution channel, alongside an industry-specific dimension of regulatory compliance. Our analytical framework modeled volume and value outputs across the analysis window, with compound annual growth rates derived from historical trends and projected future demand. Key forecast inputs included consumer health spending patterns and new dietary ingredient approval rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large pharmaceutical conglomerates or innovative D2C disruptors would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and sustained consumer interest in preventative health. Material shifts in regulatory enforcement or major supply chain disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Low-Carb Fat Loss Market
Nutritional Supplements
Brain Health Supplement Market
Nutritional Supplements
Isoleucine Market
Nutritional Supplements
Coq10 Gummies Market
Nutritional Supplements
GLP-1 Hydration Product Market
Nutritional Supplements
Japan Whey Protein Market
Nutritional Supplements
Garcinia Cambogia Extract Market
Nutritional Supplements
Vegan Protein Supplements Market
Nutritional Supplements
Vitamin D Supplements Market
Nutritional Supplements
Plant Sterol Supplements Market
Nutritional Supplements
Direct Fed Microbials Market
Nutritional Supplements
North America Prenatal Supplements Market
Nutritional Supplements
Apo-8 Carotenal Market
Nutritional Supplements
Older Adults Health Supplements Market
Nutritional Supplements
Global Reishi Mushroom Extracts Market
Nutritional Supplements
Vitamin B12 Market