
 Tocotrienol Market | 2026-2036
Tocotrienol Market Size, Share, and Industry Trends Forecast 2026-2036
Tocotrienol Market Analysis
The EU Green Deal's Farm to Fork strategy is shifting demand toward sustainably sourced bioactive ingredients across European nutraceutical supply chains. ExcelVite leverages its Malaysian palm oil vertical integration to secure raw material traceability for European buyers. American River Nutrition specializes in annatto-derived tocotrienols, competing on non-palm positioning in North American clean-label channels. BASF SE anchors industrial-scale tocotrienol production through its nutrition ingredients division, extending formulation support to multinational pharmaceutical clients.
Tocotrienols constitute a vitamin E subfamily of four isomers—alpha, beta, gamma, and delta—distinguished from tocopherols by unsaturated side chains that confer superior cellular uptake and antioxidant potency at lower concentrations. Commercial extraction relies on molecular distillation of palm fatty acid distillate or annatto seed oil, yielding fractions standardized to delta-tocotrienol content for cholesterol management applications. Nutraceuticals dominates value capture due to clinical validation of delta- and gamma-tocotrienol isomers in lipid regulation, while Cosmetics segments are expanding fastest as formulators incorporate tocotrienols for oxidative stress protection in premium dermocosmetics. Natural Tocotrienols command margin premiums over synthetic alternatives, reflecting clean-label certification requirements and supply chain transparency investments.
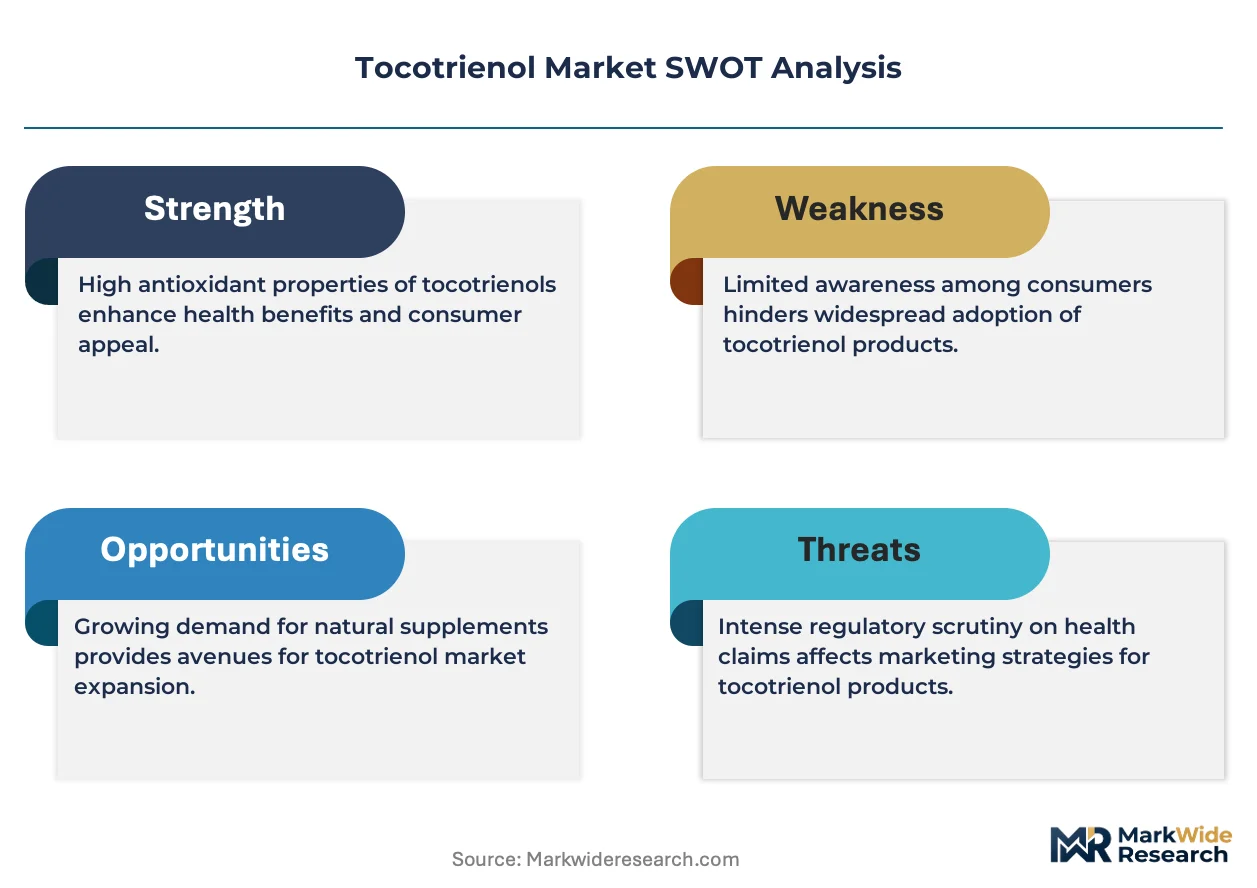
FDA GRAS self-affirmation and EFSA novel food opinions govern tocotrienol market access in North America and Europe, with Japan's Ministry of Health, Labour and Welfare maintaining distinct FOSHU standards for cholesterol-related health claims. These frameworks elevate R&D and documentation burdens, filtering out smaller suppliers unable to sustain clinical substantiation investments. Stakeholders must monitor evolving pharmacopeial monograph standards and regional bioequivalence requirements that will determine which isomer-specific formulations achieve reimbursable status in preventive healthcare programs.
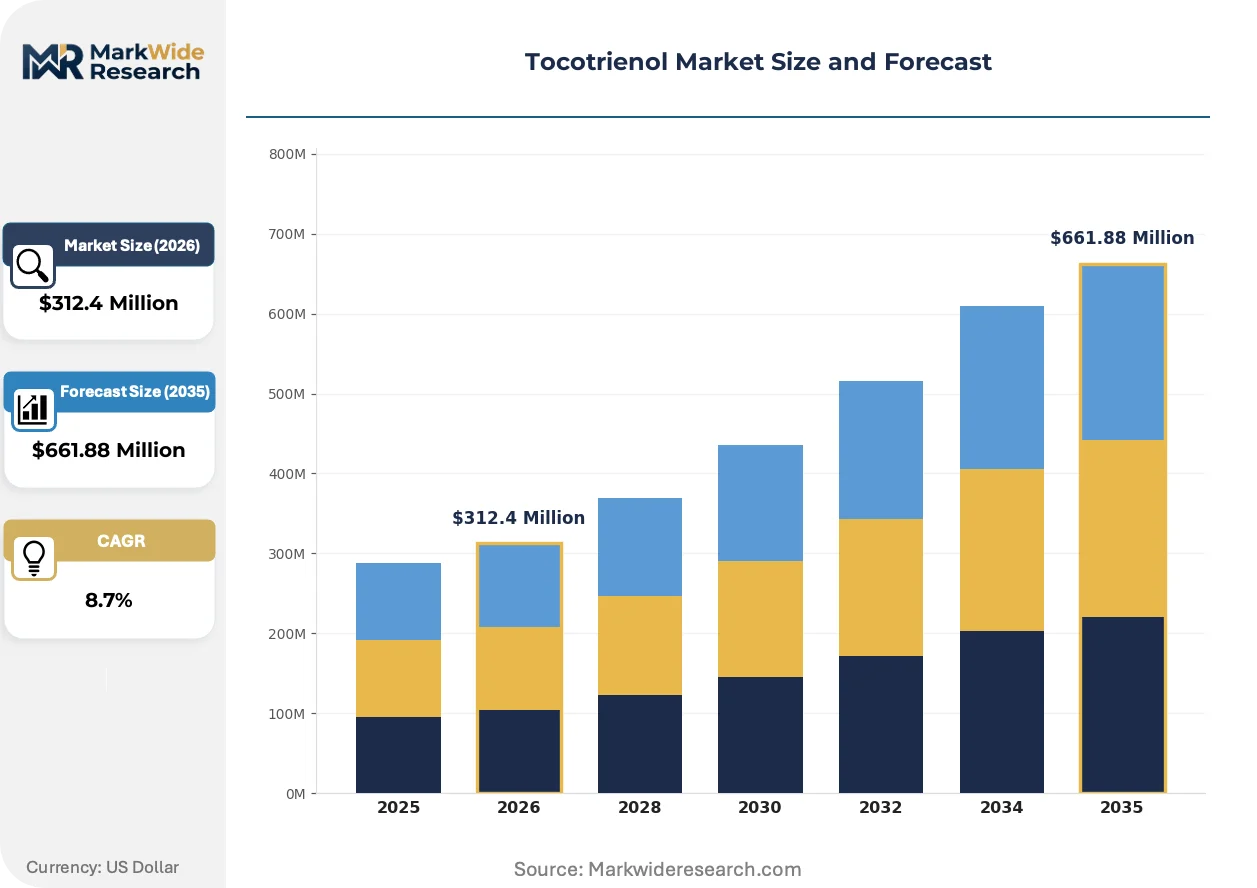
Market Dynamics
Feedstock concentration in Malaysia's Klang Valley palm oil belt is consolidating extraction capacity around vertically integrated processors, while EU Novel Food compliance requirements are filtering out smaller ingredient suppliers unable to sustain clinical substantiation investments.
Growth Catalysts
- EFSA Novel Food pathway:European nutraceutical manufacturers are accelerating tocotrienol procurement for cardiovascular formulations as positive safety opinions reduce regulatory uncertainty for new entrants.
- Japan's FOSHU approval framework:Cholesterol-related health claims for delta-tocotrienol fractions are expanding reimbursable preventive healthcare coverage and driving pharmaceutical-grade demand.
- Annatto seed oil extraction:Non-palm sourcing technologies are capturing clean-label premiums in North American dietary supplement channels as buyers seek supply chain transparency.
Market Restraints
- Crude palm oil price volatility:Feedstock costs for molecular distillation fluctuate with Malaysian ringgit exchange rates and El Niño weather patterns affecting harvest yields.
- Single-origin supply risk:Over 70% of global tocotrienol extraction capacity clusters within 50 kilometers of Port Klang, creating concentrated disruption exposure.
- Synthetic tocopherol substitution:Low-cost alpha-tocopherol continues displacing natural tocotrienols in mass-market antioxidant applications where isomer-specific efficacy claims are not required.
Strategic Opportunities
- German nutraceutical contract manufacturing:Specialized cardiovascular formulation houses in Bavaria and Baden-Württemberg are seeking qualified tocotrienol suppliers for white-label production.
- Premium dermocosmetic integration:Oxidative stress protection claims are driving tocotrienol incorporation into Korean and Japanese skincare lines targeting photodamage repair.
- EU Green Deal Farm to Fork incentives:Sustainable sourcing certification subsidies are reducing compliance cost burdens for traceable palm oil derivatives entering European supply chains.
Industry Challenges
- Isomer-specific analytical chemistry talent:Chromatographic separation expertise for delta- and gamma-tocotrienol standardization remains concentrated among a narrow pool of European pharmacopeial laboratories.
- GRAS self-affirmation documentation timelines:FDA notification preparation for new delivery formats typically requires 18-24 months of toxicology and exposure assessment work.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tocotrienol Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tocotrienol Rich Fraction, Mixed Tocotrienols, Tocopherols, Natural Tocotrienols Application: Food & Beverages, Nutraceuticals, Cosmetics, Pharmaceuticals Form: Liquid, Powder, Capsule, Spray End User: Health-conscious Consumers, Manufacturers, Research Institutions, Pharmacies |
| Companies Covered | BASF SE, ExcelVite, Eisai Co., Ltd., American River Nutrition, Kuala Lumpur Kepong Berhad, Fuji Chemical Industries Co., Ltd., Cayman Chemical, Davos Life Science, Parchem Fine & Specialty Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tocotrienol Market Emerging Trajectories
Extraction technology maturation and regulatory science advancement are converging to reshape competitive positioning around isomer purity and supply chain traceability rather than raw volume scale.
Supercritical CO2 extraction systems are decentralizing tocotrienol production geography by enabling smaller-scale processors to achieve pharmaceutical-grade purity without the capital intensity of molecular distillation towers. Regional supplement manufacturers in North America and Europe are adopting these modular units to reduce dependence on Malaysian feedstock imports. This distributed production model is compressing lead times for custom isomer ratios while fragmenting supplier concentration.
REACH registration requirements for novel food ingredients are tightening substance characterization standards for tocotrienol mixtures entering European cosmetic and nutraceutical channels. ECHA's expanded data requirements for reproductive toxicity endpoints are extending dossier preparation timelines by 12-18 months for new market entrants. German and Dutch ingredient distributors are responding by consolidating supplier relationships around established registrants with complete toxicology packages.
Direct-to-practitioner distribution is displacing traditional wholesale channels for clinical-grade tocotrienol formulations targeting lipid management protocols. Functional medicine clinics and integrative cardiology practices are establishing preferred supplier agreements with isomer-specific extractors capable of providing batch-level certificates of analysis. This channel shift is most pronounced in California, Texas, and Florida where cash-pay preventive healthcare models concentrate.
Tocotrienol Market Segmentation
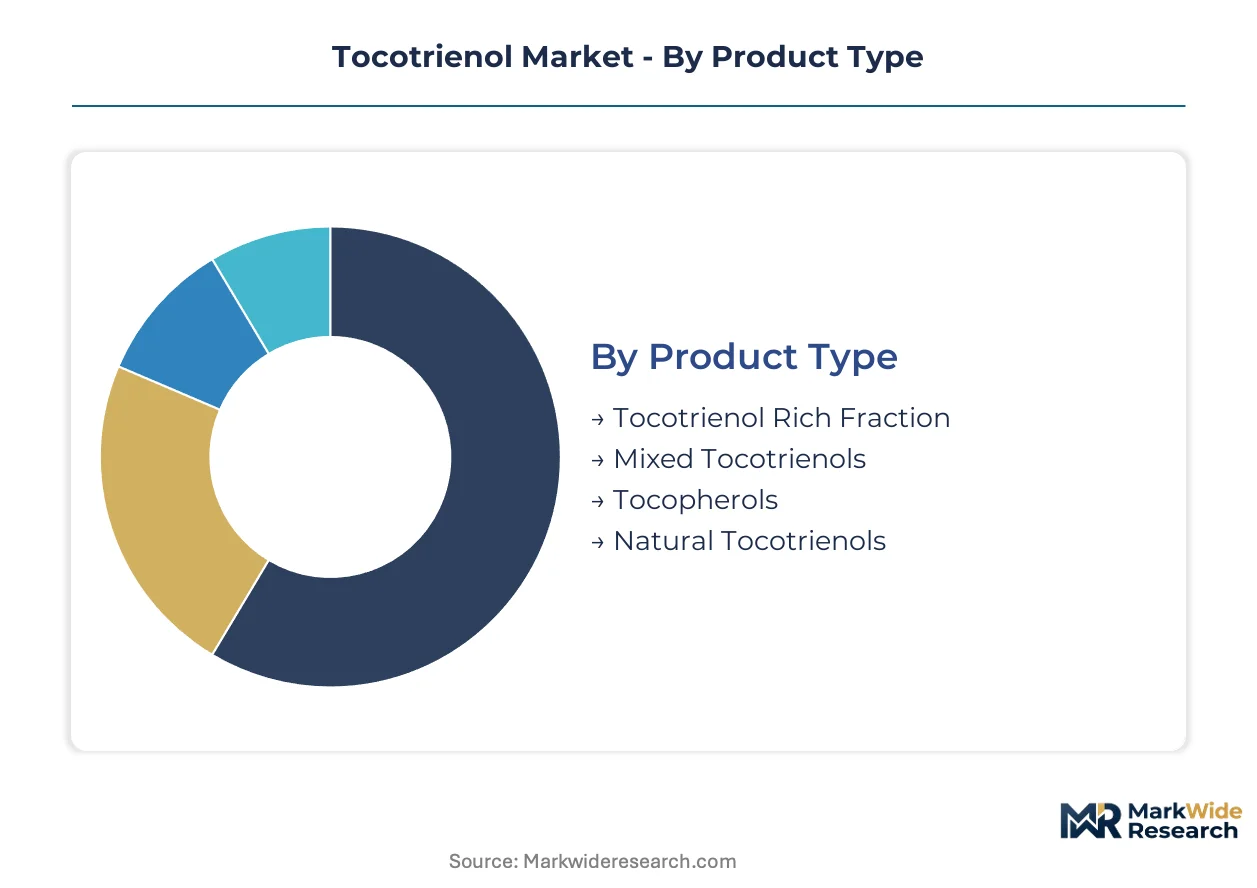
Tocotrienol procurement decisions hinge on isomer specificity, regulatory compliance grade, and end-use formulation requirements. Manufacturers segment supply chains to align delta-tocotrienol concentrations with cardiovascular health claims or cosmetic oxidative protection profiles.
Product Type:
Buyers prioritize isomer purity and sourcing transparency when selecting tocotrienol fractions for clinical or clean-label positioning.
- Tocotrienol Rich Fraction:Concentrated extracts from palm fatty acid distillate containing 15-20% total tocotrienols with elevated gamma and delta isomer ratios. Demand concentrates in German cardiovascular supplement manufacturing where EFSA novel food compliance requires documented isomer profiles. The Klang Valley supply base dominates procurement contracts for this grade.
- Mixed Tocotrienols:Standardized blends of alpha, beta, gamma, and delta isomers in varying ratios optimized for broad-spectrum antioxidant applications. Japanese FOSHU-approved formulations drive pharmaceutical-grade demand for cholesterol management protocols with specific delta-tocotrienol thresholds.
- Tocopherols:Vitamin E compounds lacking the unsaturated side chains that distinguish tocotrienols, serving as lower-cost alternatives in mass-market antioxidant applications where isomer-specific bioactivity claims are not required.
- Natural Tocotrienols:Non-synthetic extracts from annatto seed oil or palm sources commanding traceability premiums in North American clean-label channels.
Volume sits with Tocotrienol Rich Fraction; growth tilts toward Natural Tocotrienols.
Application:
Regulatory pathway complexity and clinical substantiation requirements determine margin capture across end-use categories.
- Nutraceuticals:Dietary supplements and functional foods leveraging delta- and gamma-tocotrienol clinical validation for lipid regulation claims. German and Japanese manufacturers are expanding procurement for cardiovascular and neuroprotective formulations as regulatory opinions reduce market access uncertainty.
- Cosmetics:Premium dermocosmetic lines incorporating tocotrienols for photodamage repair and oxidative stress protection. Korean and Japanese skincare brands are driving fastest category expansion through practitioner-distributed clinical beauty channels.
- Food & Beverages:Fortified edible oils and functional beverages with antioxidant positioning, constrained by thermal stability limitations during processing.
- Pharmaceuticals:Prescription-grade formulations requiring batch-level certificates of analysis and pharmacopeial monograph compliance for reimbursable preventive healthcare coverage.
Revenue concentrates in Nutraceuticals; Cosmetics climbs the fastest.
Form:
Delivery format selection reflects bioavailability engineering, shelf stability requirements, and consumer compliance preferences.
- Capsule:Gelatin and plant-based shells containing standardized tocotrienol oil suspensions, dominating practitioner-distributed clinical protocols for lipid management in California and Texas functional medicine markets.
- Liquid:Oil-based concentrates enabling flexible dosing for compounding pharmacies and custom formulation houses in Bavaria and Baden-Württemberg.
- Powder:Microencapsulated tocotrienols for dry blend applications in fortified foods and beverage premixes requiring extended shelf stability.
- Spray:Novel delivery systems targeting sublingual absorption and topical cosmetic applications with convenience positioning.
Capsule commands current volume; spray formats gain share fastest.
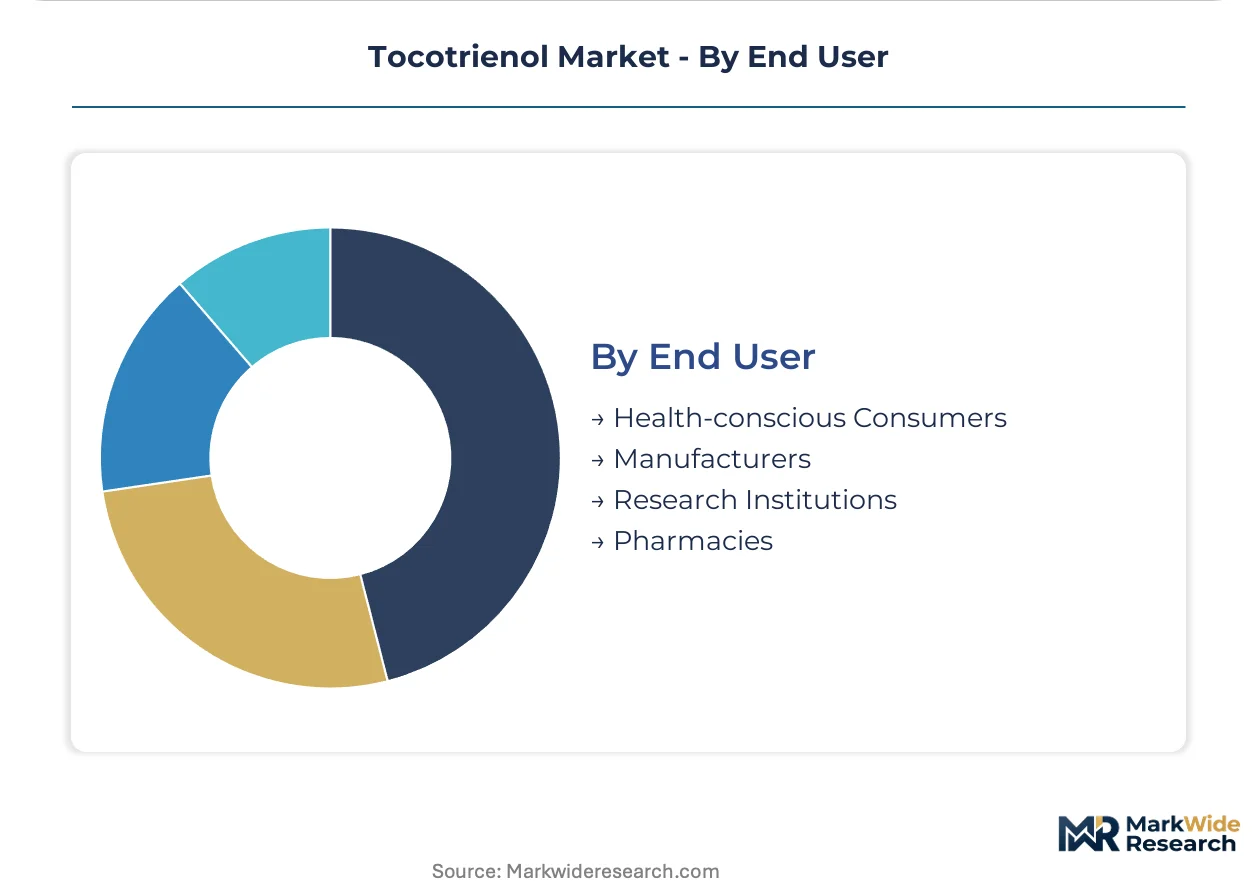
End User:
Channel structure and purchasing authority determine supplier relationship intensity and technical service requirements.
- Manufacturers:Nutraceutical contract manufacturers and cosmetic formulators requiring qualified ingredient supplies with complete regulatory dossiers for white-label production.
- Health-conscious Consumers:Direct purchasers of premium supplements through practitioner networks and specialty retail, prioritizing clean-label certification and supply chain transparency.
- Research Institutions:Academic and clinical trial sponsors investigating isomer-specific bioactivity, driving small-volume high-purity demand for analytical standards.
- Pharmacies:Compounding and retail dispensaries serving integrative medicine protocols with clinical-grade inventory requirements.
Manufacturers anchor procurement volume; health-conscious consumers expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia concentrates extraction capacity while Germany and Japan drive formulation demand. European regulatory pathways and Japanese health claim systems shape procurement patterns. Regional supply chains fragment as North American buyers seek non-palm alternatives.
Malaysia
The Klang Valley palm oil belt hosts over 70% of global tocotrienol extraction capacity through molecular distillation of crude palm oil derivatives. The Malaysian Palm Oil Board enforces sustainability certification under MSPO standards for export eligibility. Port Klang clusters vertically integrated processors serving German and Japanese nutraceutical contract manufacturers.
Germany
Bavarian and Baden-Württemberg formulation houses specialize in cardiovascular supplement manufacturing requiring EFSA novel food compliance. The EU Green Deal's Farm to Fork strategy subsidizes traceable bioactive ingredient procurement. Frankfurt-Rhine-Main logistics hubs distribute clinical-grade tocotrienols across European practitioner networks.
Japan
Tokyo and Osaka pharmaceutical manufacturers leverage FOSHU-approved delta-tocotrienol fractions for reimbursable cholesterol management protocols. The Ministry of Health, Labour and Welfare maintains distinct standards for preventive healthcare coverage. Kansai region skincare brands incorporate tocotrienols into premium dermocosmetic lines targeting photodamage repair.
United States
California, Texas, and Florida functional medicine clinics drive direct-to-practitioner demand for isomer-specific formulations. FDA GRAS self-affirmation governs market access with 18-24 month documentation timelines. American River Nutrition's annatto-derived production in Massachusetts exemplifies non-palm sourcing for clean-label channels.
China
Guangdong and Fujian provinces process palm fatty acid distillate imports for domestic nutraceutical and cosmetic applications. The National Medical Products Administration oversees novel food ingredient registration with tightening substance characterization requirements. Yangtze River Delta formulation clusters seek pharmaceutical-grade tocotrienol supplies for lipid management supplements.
Tocotrienol Market Vendor Landscape
The competitive structure tilts toward vertically integrated feedstock controllers and isomer-purity specialists. Two distinct tiers operate: Malaysian palm oil processors with captive raw material access, and North American/European extractors competing on non-palm positioning and regulatory dossier completeness. Dominant competitive moves include capacity consolidation around Port Klang and technology licensing for supercritical CO2 extraction systems.
Within the integrated extraction tier, BASF SE and Kuala Lumpur Kepong Berhad represent scale-driven archetypes with Malaysian feedstock control. ExcelVite occupies a position bridging vertical integration and European regulatory compliance. Among specialty extractors, American River Nutrition exemplifies non-palm positioning through annatto seed oil sourcing. Eisai Co., Ltd. and Fuji Chemical Industries Co., Ltd. anchor Japanese pharmaceutical-grade production with FOSHU pathway expertise. Cayman Chemical and Davos Life Science sit within the analytical standards and clinical research supply segment.
| Leading Market Players |
|---|
| BASF SE |
| ExcelVite |
| Eisai Co., Ltd. |
| American River Nutrition |
| Kuala Lumpur Kepong Berhad |
| Fuji Chemical Industries Co., Ltd. |
| Cayman Chemical |
| Davos Life Science |
| Parchem Fine & Specialty Chemicals |
| Others |
Supply Flow & Price Mechanics
German nutraceutical contract manufacturers anchor procurement volume for clinical-grade tocotrienol fractions, concentrating pricing power among vertically integrated Malaysian processors with captive palm oil feedstock access.
Pricing Analysis
Margin tightening in pharmaceutical-grade tocotrienol tiers reflects EFSA novel food compliance documentation burdens and isomer-specific analytical chemistry scarcity. Three-tier pricing structure across premium, standard, and economy levels separates FOSHU-certified Japanese pharmaceutical grades from nutraceutical intermediates and mass-market antioxidant blends. Price differentiation hinges on delta-tocotrienol purity certification and MSPO sustainability traceability. Cost-down pressure on standard-grade fractions accelerates as synthetic alpha-tocopherol substitution erodes natural tocotrienol share in non-clinical applications. Cosmetic formulators in Korea and Japan demonstrate lowest price sensitivity due to oxidative stress protection claim premiums.
Supply Chain Analysis
Chromatographic separation expertise for delta- and gamma-tocotrienol standardization concentrates in Bavarian and Dutch pharmacopeial laboratories, constraining quality control capacity expansion. Malaysian processors in the Klang Valley, Chinese refiners in Guangdong, and Japanese pharmaceutical manufacturers in Osaka and Tokyo constitute the geographic supply triangle. Raw material dependencies draw from crude palm oil derivatives, annatto seed oil, and molecular distillation equipment. Single-origin vulnerability clusters extraction capacity within fifty kilometers of Port Klang, exposing downstream buyers to El Niño harvest disruptions and ringgit exchange volatility. Distribution runs through Frankfurt-Rhine-Main logistics hubs for European practitioner networks and direct-to-clinic channels in California and Texas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tocotrienol sector is consolidating around regulatory dossier completeness and feedstock control, with EFSA and FOSHU compliance investments filtering out undercapitalized ingredient suppliers.
For Market Incumbents: Anticipate supercritical CO2 extraction technology licensing from North American equipment vendors as a defensive priority against decentralized production geography. Secure backward integration into Malaysian MSPO-certified palm oil estates to defend raw material access against Port Klang concentration risk. Prioritize isomer-specific analytical chemistry talent acquisition in European pharmacopeial hubs to maintain pharmaceutical-grade certification leadership. For New Entrants and Emerging Players: Modular supercritical CO2 extraction systems offer a technology-first wedge for regional supplement manufacturers seeking pharmaceutical-grade purity without molecular distillation capital intensity. Target Bavarian and Baden-Württemberg contract manufacturing white-space for cardiovascular formulation partnerships requiring EFSA novel food compliance support. Pursue annatto-derived non-palm positioning to capture clean-label premiums in North American direct-to-practitioner channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap extractors with incomplete REACH dossiers in German and Dutch distribution corridors, where ECHA reproductive toxicity data requirements extend preparation timelines. Long-term viability centers on isomer-purity specialization rather than volume scale, with FOSHU pathway expertise as the durable moat. Monitor EFSA novel food opinion velocity as the inflection signal for European market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MSPO-Certified Palm Oil | Captive feedstock secures traceability premiums for EU Green Deal Farm to Fork compliance. |
| Supercritical CO2 Extraction Licensing | Modular systems enable pharmaceutical-grade production without Port Klang feedstock dependence. |
| EFSA Novel Food Dossier Investment | Complete toxicology packages filter competitors from European nutraceutical supply chains. |
| Isomer-Specific Analytical Chemistry Acquisition | Chromatographic expertise concentration in European labs creates scarce capability moats. |
| Direct-to-Practitioner Channel Development | California and Texas functional medicine clinics drive cash-pay preventive healthcare demand. |
Methodological Framework
Multi-period observation of EFSA novel food opinion timelines, FOSHU approval velocities, and Klang Valley extraction capacity utilization anchored the trend analysis, supplemented by interviews with nutraceutical contract manufacturing executives, cosmetic formulators, palm oil procurement leads, pharmacopeial laboratory directors, and integrative cardiology practitioners. Secondary validation drew from EU Novel Food regulations, Japan's FOSHU standards, FDA GRAS notifications, Malaysian Palm Oil Board sustainability certifications, and customs trade data for palm fatty acid distillate movements. Bottom-up segment sizing triangulated against top-down market aggregation from extraction capacity and isomer-specific demand modeling.
Segment-weighting across product type, application, form, and end-user dimensions structured the analytical framework, with isomer purity grades and regulatory compliance tiers as cross-cutting variables. CAGRs were derived from feedstock availability projections, clinical trial publication trajectories for delta-tocotrienol cholesterol management, and practitioner channel penetration rates across the analysis window. Forecast inputs incorporated El Niño cycle impacts on Malaysian harvest yields and REACH registration completion timelines for new market entrants.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained crude palm oil price volatility or abrupt EFSA regulatory opinion shifts. Projections reflect assumptions on FOSHU pathway continuity, supercritical CO2 technology adoption curves, and clean-label preference persistence in North American channels. Material deviation in EFSA novel food opinion velocity or Klang Valley logistics disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Prenatal Vitamin Supplements Market
Nutritional Supplements
Medium-Chain Triglycerides Market
Nutritional Supplements
Micronutrient Powders (Mnps) Market
Nutritional Supplements
Protein Powder Market
Nutritional Supplements
Spirulina Powder Market
Nutritional Supplements
Vegan Collagen Protein Market
Nutritional Supplements
Japan Protein Market
Nutritional Supplements
Global Adaptogens Market
Nutritional Supplements
Global Egg Protein Market
Nutritional Supplements
Chaga Mushroom Extract Market
Nutritional Supplements
Global Elderly Nutrition Market
Nutritional Supplements
Energy Supplements Market
Nutritional Supplements
Medicinal Mushroom Supplement Market
Nutritional Supplements
Global General Well-Being Dietary Supplements Market
Nutritional Supplements
Grass-Fed Collagen Market
Nutritional Supplements
Enteral Nutrition Market