
 Activated Charcoal Supplement Market | 2026-2036
Activated Charcoal Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Activated Charcoal Supplement Market Analysis
Clean-label formulation technology is narrowing the gap between pharmaceutical-grade purity standards and mass-market supplement accessibility. NOW Foods leverages its vertically integrated manufacturing infrastructure to sustain cost advantages across capsule and powder formats. Holland & Barrett Retail Ltd anchors European distribution through its brick-and-mortar network, while Bulletproof 360 Inc. differentiates via ketogenic-aligned branding that commands premium positioning.
Activated charcoal supplements consist of carbonaceous material processed at high temperatures to create a porous adsorptive surface, typically yielding a fine black powder with surface areas exceeding 800 square meters per gram designed to bind toxins and gases in the gastrointestinal tract. The capsules segment dominates volume due to dosing precision and portability, though gummies represent the fastest-expanding format as palatability drives trial among general consumers. Organic formulation claims command margin premiums, while non-GMO certification has become table stakes for health food store placement.
FDA oversight under DSHEA and evolving cGMP enforcement shapes manufacturing compliance burdens, particularly for imported coconut-shell and bamboo-derived raw materials. EFSA's pending novel food evaluations for activated charcoal in several EU member states create regulatory uncertainty for cross-border sellers. Stakeholders must monitor how FDA warning letter trends and EU harmonization efforts reshape permissible structure-function claims before committing to regional expansion strategies.
Market Dynamics
DSHEA modernization efforts by the FDA are compressing formulation disclosure timelines and forcing manufacturers to rebuild supply chain documentation from raw material sourcing through finished goods labeling. This regulatory pressure is restructuring competitive advantage around compliance infrastructure rather than marketing scale.
Growth Catalysts
- Detoxification wellness culture:Mainstream consumers in the United States are adopting gut-health routines previously confined to alternative medicine circles, expanding addressable demand beyond traditional supplement users.
- FDA cGMP enforcement alignment:Stricter manufacturing practice oversight is filtering out substandard operators and consolidating volume among facilities capable of pharmaceutical-grade documentation.
- Coconut-shell carbon sourcing:Southeast Asian agricultural waste streams provide renewable feedstock for high-porosity activated charcoal, decoupling production from petrochemical dependencies.
Market Restraints
- Raw material import concentration:Premium coconut-shell activated carbon concentrates in Indonesian and Philippine processing facilities, exposing buyers to shipping cost volatility and customs documentation complexity.
- EFSA novel food uncertainty:Pending evaluations in multiple EU member states block market access for non-traditional delivery formats and limit cross-border e-commerce expansion.
- Pharmaceutical substitution:Prescription binders for specific toxin exposures offer clinician-directed alternatives with reimbursement coverage, constraining medical-positioning strategies for supplement brands.
Strategic Opportunities
- Gummy format penetration:Palatable delivery systems are unlocking trial among general wellness consumers who reject capsule regimens, creating new shelf-space negotiations in mass retail.
- Organic certification premium capture:USDA Organic and equivalent EU organic claims command margin expansion in health food channels where ingredient provenance drives purchase decisions.
- Subscription direct-to-consumer infrastructure:Recurring revenue models bypass wholesale margin compression and build proprietary customer data assets for personalized cross-selling.
Industry Challenges
- Adsorption consistency validation:Batch-to-batch surface area variability requires sophisticated quality control protocols that strain mid-tier manufacturing operations.
- Structure-function claim documentation:FDA warning letter precedents constrain permissible marketing language, forcing legal review cycles that delay campaign launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Activated Charcoal Supplement Market |
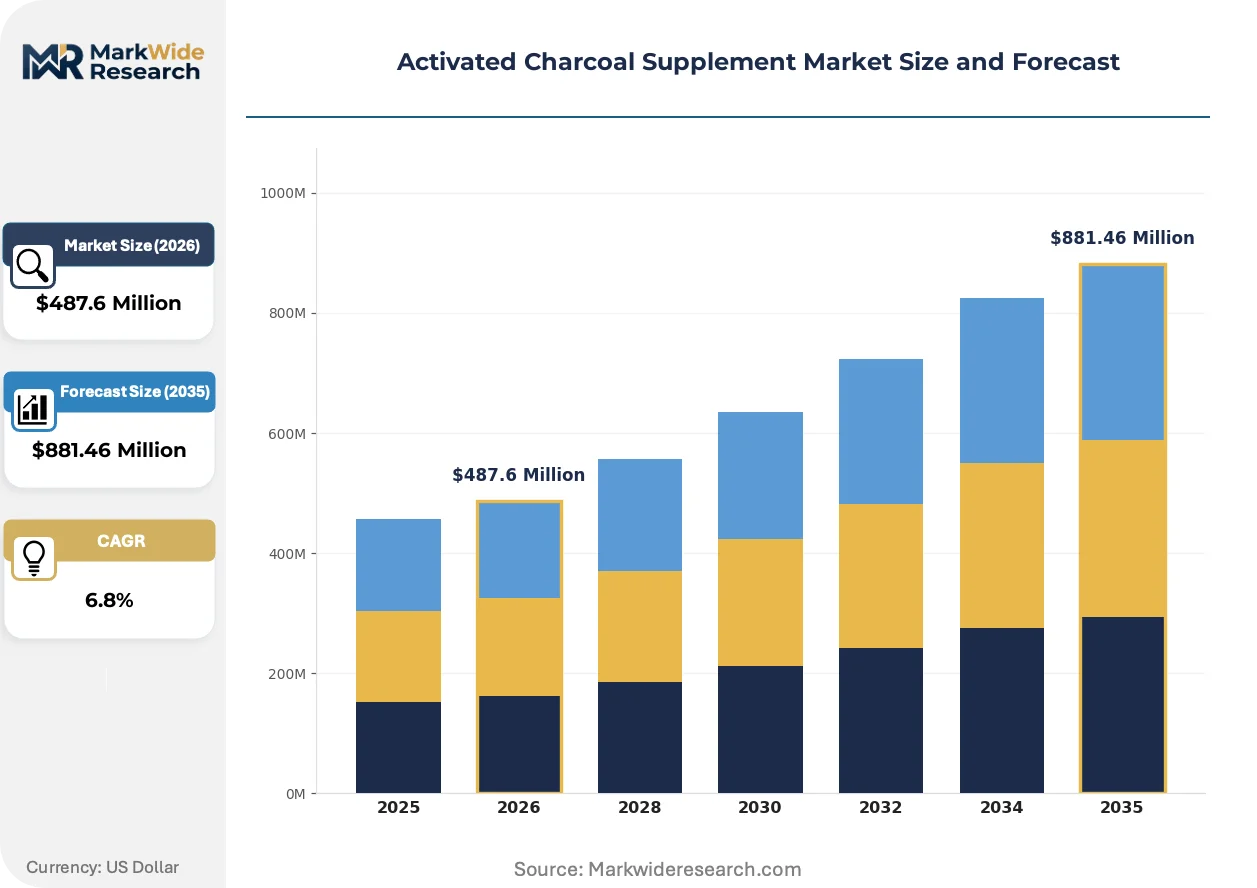
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pills, Powder, Capsules, Gummies End User: Health Enthusiasts, Fitness Buffs, Detox Seekers, General Consumers Distribution Channel: Online Retailers, Pharmacies, Health Food Stores, Supermarkets Formulation: Organic, Non-GMO, Gluten-Free, Vegan |
| Companies Covered | Holland & Barrett Retail Ltd, Dr. Schwabe Holding, Country Life LLC, Bulletproof 360 Inc., FORZA, NOW Foods, Nature’s Way, Schizandu Organics, Swanson Health Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Activated Charcoal Supplement Market Emerging Trajectories
Clean-label formulation protocols are redefining manufacturing excellence standards, compressing the gap between pharmaceutical purity benchmarks and mass-market accessibility. Three intersecting developments are restructuring competitive positioning.
Nano-activation processing technology is collapsing the cost differential between food-grade and pharmaceutical-grade charcoal specifications. Supplement manufacturers with in-house carbon activation capabilities are capturing margin previously ceded to specialized chemical suppliers. This capability compression is enabling mid-tier brands to enter clinical-channel conversations previously reserved for compounding pharmacies.
EFSA's pending novel food evaluations for activated charcoal applications are forcing European sellers to maintain dual formulation inventories pending regulatory clarity. Manufacturers serving multiple EU member states face fragmented compliance obligations as national authorities interpret harmonization timelines differently. This regulatory friction is accelerating facility relocation discussions toward jurisdictions with established charcoal-in-food precedents.
Subscription-based replenishment models are displacing traditional retail replenishment cycles among detox-seeking consumers. Direct-to-consumer wellness brands capture lifetime value through personalized dosing protocols and bundled gut-health assortments. This channel shift concentrates most visibly in the United States, where fulfillment infrastructure and consumer comfort with auto-ship terms exceed other developed markets.
Activated Charcoal Supplement Market Segmentation
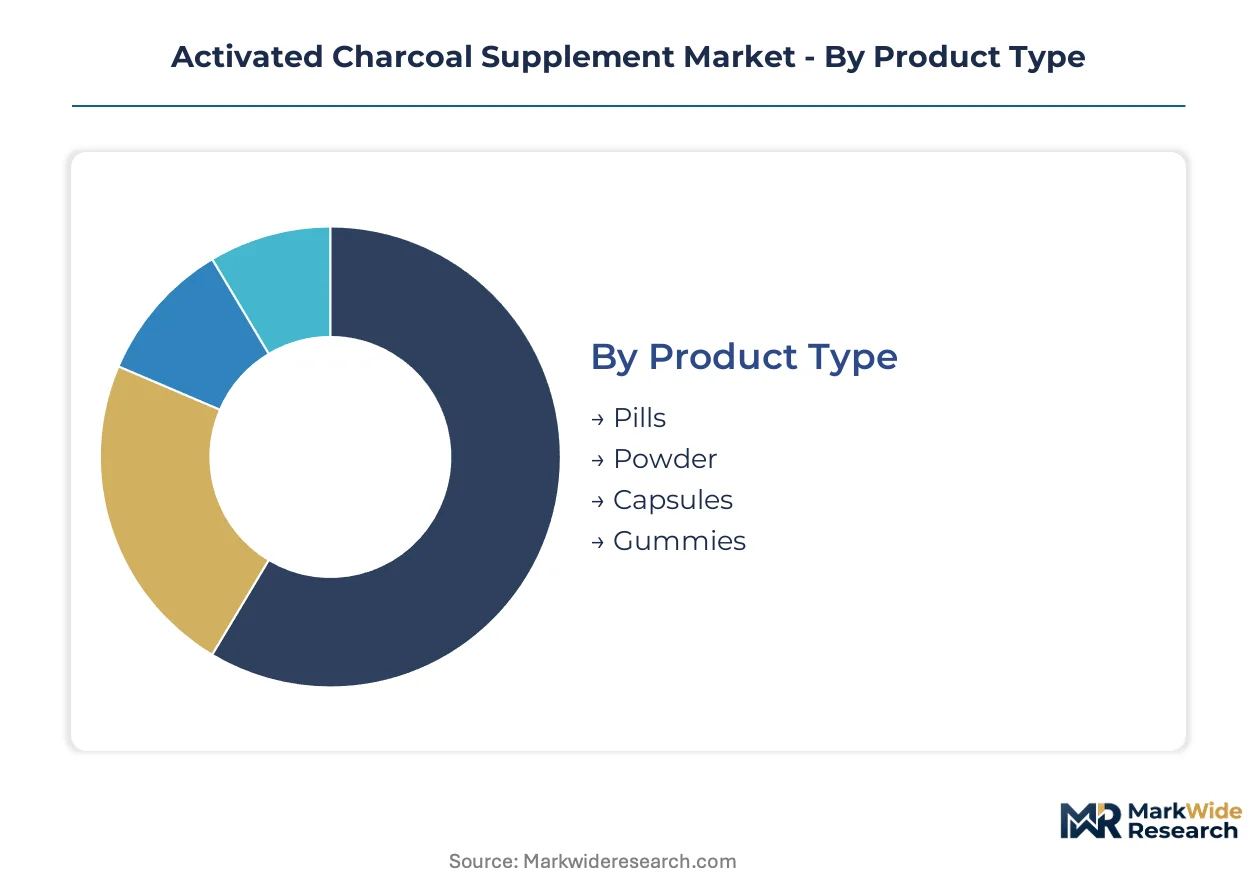
Segmentation in the activated charcoal supplement market reveals how delivery format preferences and wellness positioning strategies divide purchasing behavior. Manufacturers must align production capabilities with the specific compliance and palatability demands of each segment cluster.
Product Type:
The use-case spectrum spans clinical precision dosing to casual wellness snacking, with each format demanding distinct manufacturing infrastructure and stability testing protocols.
- Capsules:Hard-shell gelatin or vegetable-based encapsulation delivers precise milligram dosing with minimal taste interference. Demand concentrates among detox seekers in the United States who prioritize portability and stackable supplement regimens alongside probiotics and digestive enzymes.
- Gummies:Palatable gelatin or pectin matrices mask charcoal's gritty texture through flavor masking technology. General consumers in mass retail channels drive trial expansion, though moisture-sensitive stability requires specialized packaging investments.
- Pills:Compressed tablet forms offer cost-efficient manufacturing at scale. Fitness buffs favor this format for gym bag convenience.
- Powder:Bulk containers support flexible dosing for smoothie integration. Health enthusiasts in home-blending routines sustain this segment.
The dominant share belongs to capsules, while gummies are closing the gap fastest through flavor innovation and mass retail shelf space negotiations.
End User:
Customer archetypes range from biohacking extremists to mainstream wellness dabblers, with detoxification narratives bridging these cohorts.
- Detox Seekers:Consumers pursuing gut-reset protocols and hangover remediation represent the addressable core. This cohort commands premium pricing tolerance and drives subscription auto-ship adoption.
- Health Enthusiasts:Early adopters of functional ingredients integrate charcoal into broader supplement stacks. Their purchasing gravitates toward health food stores with certified organic inventory.
- Fitness Buffs:Gym-oriented consumers target bloating reduction and post-workout recovery support. Sports nutrition retail channels capture this volume.
- General Consumers:Mainstream wellness dabblers respond to social media influencer recommendations and impulse supermarket placements. Price sensitivity constrains margin here.
Detox seekers anchor volume concentration, though general consumers are expanding the addressable base through mass-market accessibility.
Distribution Channel:
Channel strategy determines margin structure and customer data ownership, with direct-to-consumer infrastructure separating premium positioning from commodity competition.
- Online Retailers:E-commerce platforms and brand-owned storefronts capture recurring revenue through subscription mechanics. Amazon and specialized wellness marketplaces dominate this channel in the United States.
- Health Food Stores:Brick-and-mortar specialty retail demands organic certification and transparent sourcing documentation. Staff education requirements elevate this channel's service intensity.
- Pharmacies:Drugstore placement requires navigating FDA structure-function claim constraints more rigorously than wellness channels. Pharmacist recommendation drives credibility.
- Supermarkets:Mass grocery placement signals mainstream acceptance but compresses margins through slotting fee structures and promotional depth requirements.
Online retailers command the steepest expansion trajectory, while health food stores defend margin through certification premiums and educated staff mediation.
Formulation:
Certification stacking creates tiered pricing architecture, with organic claims commanding the widest premium spreads.
- Organic:USDA Organic or equivalent EU certification requires charcoal derived from certified organic coconut shells or bamboo. Supply chain documentation burdens favor vertically integrated manufacturers.
- Non-GMO:Project Verified or equivalent labeling has become baseline expectation for health food store placement. This certification no longer differentiates but rather prevents exclusion.
- Vegan:Plant-based capsule materials and processing agent exclusions target ethical consumption segments. Gelatin-free claims support this positioning.
- Gluten-Free:Celiac-safe certification expands addressability to autoimmune wellness communities. Cross-contamination protocols add manufacturing complexity.
Organic formulations capture the widest margin premiums, while non-GMO certification has shifted to table-stakes necessity without pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency on Southeast Asian coconut-shell carbon concentrates supply risk in consuming markets. The United States runs a structural trade deficit in activated charcoal raw materials, sourcing predominantly from Indonesian and Philippine processing facilities. European buyers face additional regulatory friction from EFSA novel food evaluations that disrupt cross-border shipment flows.
United States
Detoxification wellness culture and direct-to-consumer subscription models drive demand concentration. FDA cGMP enforcement under DSHEA modernization elevates compliance costs for imported finished goods. Los Angeles and Austin host the densest clusters of DTC wellness brands building proprietary customer data assets through auto-ship replenishment infrastructure.
Germany
Health food store channel density and organic certification premiums sustain margin capture for premium-positioned products. BfR (Federal Institute for Risk Assessment) evaluations of activated charcoal food applications create documentation burdens for cross-border sellers. Berlin and Hamburg anchor distribution networks serving the broader EU market with specialized logistics for temperature-sensitive gummy formats.
United Kingdom
Holland & Barrett's brick-and-mortar network defends market position through staff education and certified organic inventory depth. MHRA borderline product classifications for charcoal supplements require careful claim structuring to avoid medicinal reclassification. London and Manchester concentrate e-commerce fulfillment infrastructure for pan-European subscription servicing.
Indonesia
Coconut-shell agricultural waste streams provide renewable feedstock for high-porosity activated carbon exports. Ministry of Trade export licensing and customs documentation complexity create bottlenecks for unconsolidated processors. Java and Sulawesi host the primary carbon activation facilities supplying pharmaceutical-grade specifications to international supplement manufacturers.
Philippines
Coconut industry byproduct utilization supports circular economy positioning for EU and US buyers seeking sustainable sourcing narratives. Bureau of Customs valuation disputes and preferential tariff certificate requirements delay shipment clearances. Davao and Cebu concentrate integrated processing operations combining shell carbonization with activation furnace capacity.
Activated Charcoal Supplement Market Vendor Landscape
On the supply side, the industry is bifurcating between vertically integrated raw material processors and brand-focused marketers dependent on toll manufacturing. Mid-tier manufacturers face margin compression as pharmaceutical-grade documentation requirements strain quality control infrastructure. Two strategic archetypes dominate: coconut-shell carbon specialists with captive Southeast Asian supply chains, and DTC-native wellness brands leveraging subscription mechanics for lifetime value capture. Consolidation pressure manifests through backward integration into carbon activation capacity and forward integration into proprietary fulfillment networks.
Within the vertically integrated tier, NOW Foods exemplifies manufacturing-scale archetypes with in-house encapsulation and powder processing infrastructure. Bulletproof 360 Inc. and Holland & Barrett Retail Ltd occupy contrasting positions on the brand spectrum—one ketogenic-aligned and premium-positioned, the other brick-and-mortar anchored with European geographic density. Country Life LLC represents the specialist organic certification tier where supply chain documentation burdens favor concentrated operational footprints. These three entities collectively illustrate how compliance infrastructure, channel strategy, and sourcing control separate sustainable competitive position from commodity exposure.
| Leading Market Players |
|---|
| Holland & Barrett Retail Ltd |
| Dr. Schwabe Holding |
| Country Life LLC |
| Bulletproof 360 Inc. |
| FORZA |
| NOW Foods |
| Nature's Way |
| Schizandu Organics |
| Swanson Health Products |
| Others |
Supply Flow & Price Mechanics
Indonesian and Philippine coconut-shell carbon processing clusters concentrate upstream supply, feeding margin capture downstream into organic-certified finished goods and direct-to-consumer subscription channels. Premium pricing power pools with brands commanding captive Southeast Asian sourcing and pharmaceutical-grade documentation infrastructure.
Pricing Analysis
Detox seekers anchor subscription-based pricing structures that extract lifetime value through auto-ship replenishment mechanics. Three-tier pricing separates USDA Organic premium SKUs from non-GMO baseline offerings and mass-market economy capsules. Pricing pressure stems from raw material shipping cost volatility between Southeast Asian ports and US fulfillment centers. General consumers in supermarket channels exhibit highest price sensitivity, while certified organic buyers in health food stores tolerate significant premiums.
Supply Chain Analysis
Tariff exposure between Indonesia and the United States dominates supply chain risk calculations for coconut-shell activated carbon importers. Feedstock draws from Indonesian and Philippine agricultural waste streams, with secondary processing capacity concentrated in Java and Sulawesi. Single-source vulnerability concentrates in customs documentation bottlenecks at Bureau of Customs clearance points. Distribution runs through vertically integrated manufacturers with in-house encapsulation, toll processors serving brand marketers, and direct-to-consumer fulfillment networks bypassing wholesale margin compression.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prescription pharmaceutical binders with clinician-directed positioning and reimbursement coverage pose a substitution threat that supplement incumbents must navigate through differentiation and channel control.
For Market Incumbents: Harden compliance infrastructure around FDA cGMP documentation and DSHEA modernization requirements to filter out substandard competitors. Deepen backward integration into Southeast Asian carbon activation capacity to secure feedstock cost advantages. Build proprietary subscription auto-ship platforms that capture customer data assets and reduce churn vulnerability to emerging DTC brands. For New Entrants and Emerging Players: Gummy format penetration in mass retail channels represents the most penetrable entry point for general wellness consumers rejecting capsule regimens. European health food stores awaiting EFSA novel food clarity offer white-space opportunity for organic-certified entrants with established supply chain documentation. Deploy influencer-driven social media campaigns to unlock trial among mainstream detox seekers before incumbent brands consolidate shelf space. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated manufacturers with captive Indonesian or Philippine sourcing and in-house pharmaceutical-grade processing capabilities. Long-term viability over the projection horizon hinges on compliance infrastructure scalability rather than marketing scale alone. Watch FDA warning letter trends as the inflection indicator for which operators will survive DSHEA modernization enforcement waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Activation | Captures margin previously ceded to specialized chemical suppliers in Indonesia and the Philippines. |
| USDA Organic Certification Investment | Unlocks premium pricing in health food stores where ingredient provenance drives purchase decisions. |
| Direct-to-Consumer Subscription Launch | Bypasses wholesale margin compression and builds proprietary customer data assets for cross-selling. |
| Gummy Format Development | Penetrates mass retail channels where palatability drives trial among general wellness consumers. |
| DSHEA Compliance Infrastructure Buildout | Creates defensive moats as FDA cGMP enforcement filters out substandard manufacturing operations. |
Methodological Framework
Cross-validation between primary interviews with supplement brand executives, contract manufacturing operators, and health food store category buyers anchors the qualitative findings. Secondary sources include FDA warning letter databases, EFSA novel food evaluation registers, US customs import records, and DSHEA regulatory guidance documents. Bottom-up demand modeling triangulates against top-down market sizing across product format, certification tier, and distribution channel dimensions.
Calibration against historical volume trajectories in detoxification and gut-health supplement categories informs the analytical framework across the analysis window. Segmentation dimensions span delivery format, end-user archetype, distribution channel, and formulation certification tier. CAGRs derive from fitted growth curves applied to validated baseline estimates, with specific inputs including coconut-shell carbon feedstock availability and FDA enforcement intensity indices.
Macroeconomic conditions sit as an overlay; deviation in shipping cost indices between Southeast Asia and US ports, or abrupt shifts in FDA cGMP enforcement timelines, would shift the trajectory. Forecasts reflect documented assumptions about regulatory harmonization progress and raw material supply continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global General Well-Being Dietary Supplements Market
Nutritional Supplements
Whey Protein Concentrate Market
Nutritional Supplements
Lactates Market
Nutritional Supplements
Testosterone Booster Market
Nutritional Supplements
Energy Gums Market
Nutritional Supplements
Fat Powders Market
Nutritional Supplements
Global Beta Glucan Market
Nutritional Supplements
Iron Supplement Market
Nutritional Supplements
Weight Loss Supplements Market
Nutritional Supplements
Nutraceutical Oral Thin Films Market
Nutritional Supplements
Sports Food Market
Nutritional Supplements
Dietary Supplements Market
Nutritional Supplements
Hydrolyzed Whey Protein Market
Nutritional Supplements
Lion's Mane Market
Nutritional Supplements
Spain Whey Protein Market
Nutritional Supplements
Vitamin K2 Market