
 Asia-Pacific Digestive Health Supplements Market | 2026-2036
Asia-Pacific Digestive Health Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Digestive Health Supplements Market Outlook
India's FSSAI label-claim verification mandate for imported supplements is recalibrating the cost-of-entry calculus for foreign brands seeking shelf space in multi-brand outlets. Yakult Honsha Co., Ltd. leverages its fermented dairy heritage to dominate refrigerated probiotic channels across Japan and Southeast Asia. Abbott Laboratories anchors its position through pharmacy-centric distribution and clinician endorsement programs. Herbalife Nutrition Ltd. competes via direct-selling networks that bypass traditional retail markup structures entirely.
Asia-Pacific digestive health supplements comprise orally administered formulations containing live microbial cultures, non-digestible oligosaccharides, hydrolytic enzymes, or soluble/insoluble fiber matrices, typically standardized to colony-forming units or enzymatic activity levels, intended to modulate gastrointestinal microbiota composition or accelerate macronutrient breakdown. Probiotics lead product-type revenue due to strain-specific patent portfolios and cold-chain infrastructure investments, while digestive enzymes represent the fastest-expanding category as lactose-intolerant and aging demographics seek targeted relief. Online retail channels capture margin pools through subscription models and direct-to-consumer personalization, though pharmacies retain structural importance in markets with active pharmacist consultation cultures.
Japan's PMDA and Australia's TGA enforce divergent stability-testing protocols for live-culture products, creating formulation complexity for manufacturers serving both markets simultaneously. China's NMPA and India's CDSCO impose distinct import-registration timelines that shape market-entry sequencing and capital allocation priorities. Stakeholders must monitor harmonization efforts between ASEAN regulatory frameworks and national pharmacopeia standards to anticipate where compliance burdens will concentrate or dissipate.
Market Dynamics
Strain-specific patent portfolios and cold-chain infrastructure investments are consolidating competitive advantage around clinically validated probiotic formulations, while regulatory divergence between Japan's PMDA and Australia's TGA forces manufacturers to maintain parallel stability-testing protocols.
Growth Catalysts
- Aging demographics across Japan and South Korea:Expanding lactose-intolerant and geriatric populations drive targeted demand for digestive enzyme formulations and specialized probiotic strains.
- FSSAI label-claim verification mandate:India's tightening import regulations, while raising barriers, simultaneously validate premium-positioned brands with documented clinical evidence.
- Pharmacy-centric distribution networks:Abbott Laboratories and similar players leverage clinician endorsement programs to anchor prescription-adjacent sales channels across Southeast Asian markets.
Market Restraints
- Live-culture cold-chain dependency:Refrigerated logistics requirements impose 15-25% cost premiums on finished goods, compressing margins for mid-tier entrants.
- Regulatory fragmentation:Divergent ASEAN national pharmacopeia standards and China's NMPA registration timelines create multi-year market-entry sequencing delays.
- Plant-based enzyme substitution:Fermented food alternatives and traditional medicine systems in Vietnam and Thailand displace standardized supplement uptake in rural demographics.
Strategic Opportunities
- Subscription direct-to-consumer models:Online retail channels in Australia and urban India capture recurring revenue pools through microbiome personalization services.
- MFDS fast-track approval pathways:South Korea's streamlined functional food certification incentivizes probiotic portfolio expansion by domestic and regional manufacturers.
- Enzyme-fiber combination formulations:Converging hydrolytic enzyme and soluble fiber technologies open positioning against single-ingredient competitors in aging-population segments.
Industry Challenges
- Strain characterization expertise shortage:Qualified microbiologists capable of PMDA-compliant stability documentation command 40% salary premiums, constraining R&D scaling.
- Multi-jurisdiction compliance capex:Simultaneous TGA and NMPA registration requires redundant manufacturing line investments for distinct packaging and labeling standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Digestive Health Supplements Market |
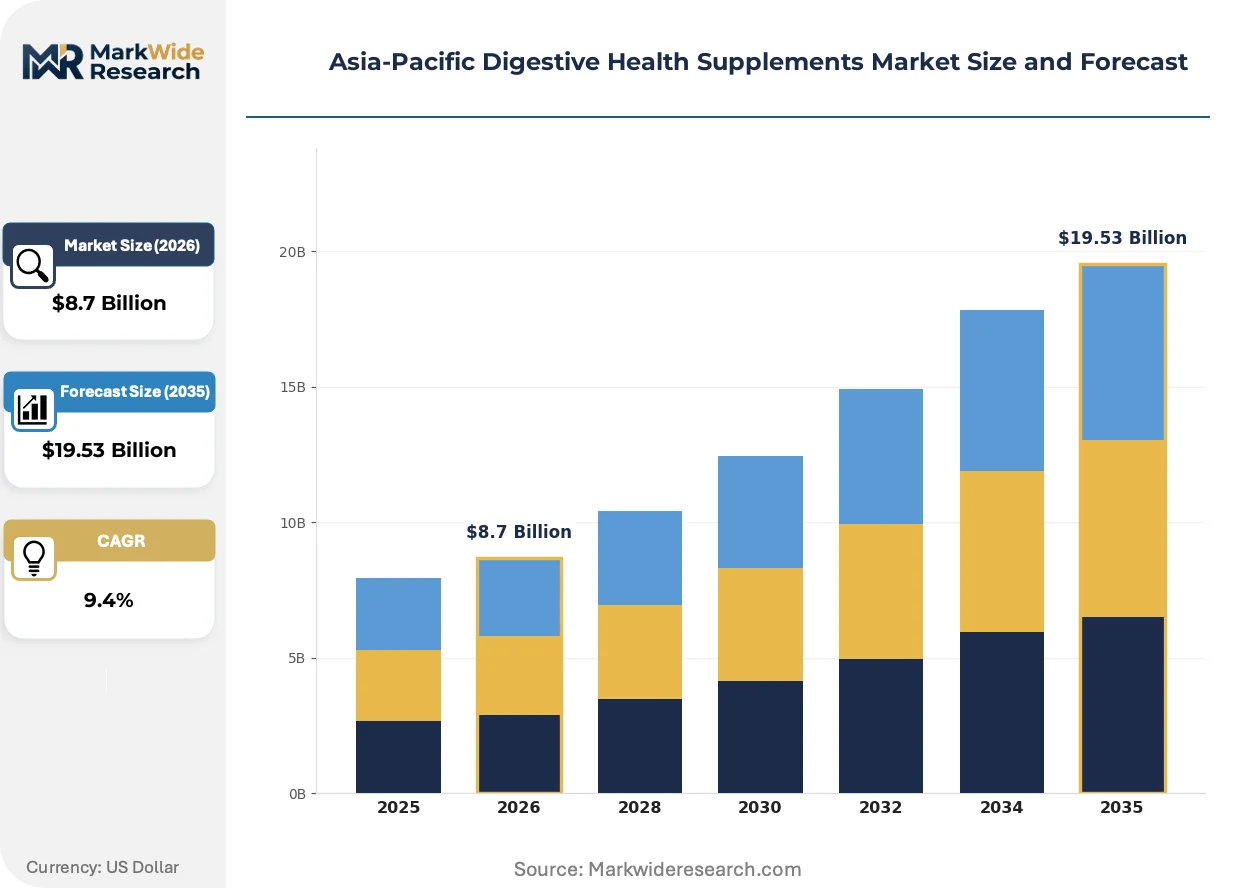
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Prebiotics, Digestive Enzymes, Fiber Supplements Application: Gut Health, Weight Management, Immune Support, Nutritional Enhancement Formulation: Tablets, Powders, Liquids, Capsules Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Bayer AG, Herbalife Nutrition Ltd., Abbott Laboratories, Amway, Pfizer Inc., NOW Foods, Yakult Honsha Co., Ltd., Blackmores Limited, Kalbe Farma, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Digestive Health Supplements Market Strategic Shifts
Formulation science and distribution architecture are undergoing parallel transformation as manufacturers respond to divergent regulatory demands and channel fragmentation.
Microencapsulation technology for live-culture protection is modularizing supply chain requirements by enabling ambient-temperature distribution for previously cold-chain-dependent strains. Australian and Japanese manufacturers adopting this platform compress logistics costs while expanding retail placement in convenience stores and vending channels. The structural consequence is tier collapse between premium refrigerated and economy shelf-stable positioning.
PMDA's 2023 stability-testing guideline revisions for multi-strain products mandate accelerated shelf-life validation protocols that extend registration timelines by 8-14 months. Japanese manufacturers absorb compliance costs through dedicated in-house analytical laboratories, while importers face partnership-dependent verification bottlenecks. Probiotic blends with five or more declared strains bear disproportionate documentation burdens under the new framework.
Pharmacist consultation cultures in Thailand and the Philippines resist pure e-commerce displacement, yet telehealth-integrated subscription models capture urban professional segments seeking convenience without sacrificing expert guidance. Hybrid fulfillment—online ordering with physical pharmacy pickup—is displacing traditional multi-brand outlet stocking for premium positioned SKUs. This pattern concentrates in Bangkok and Metro Manila metropolitan corridors where digital payment penetration exceeds national averages by 30 percentage points.
Asia-Pacific Digestive Health Supplements Market Segmentation
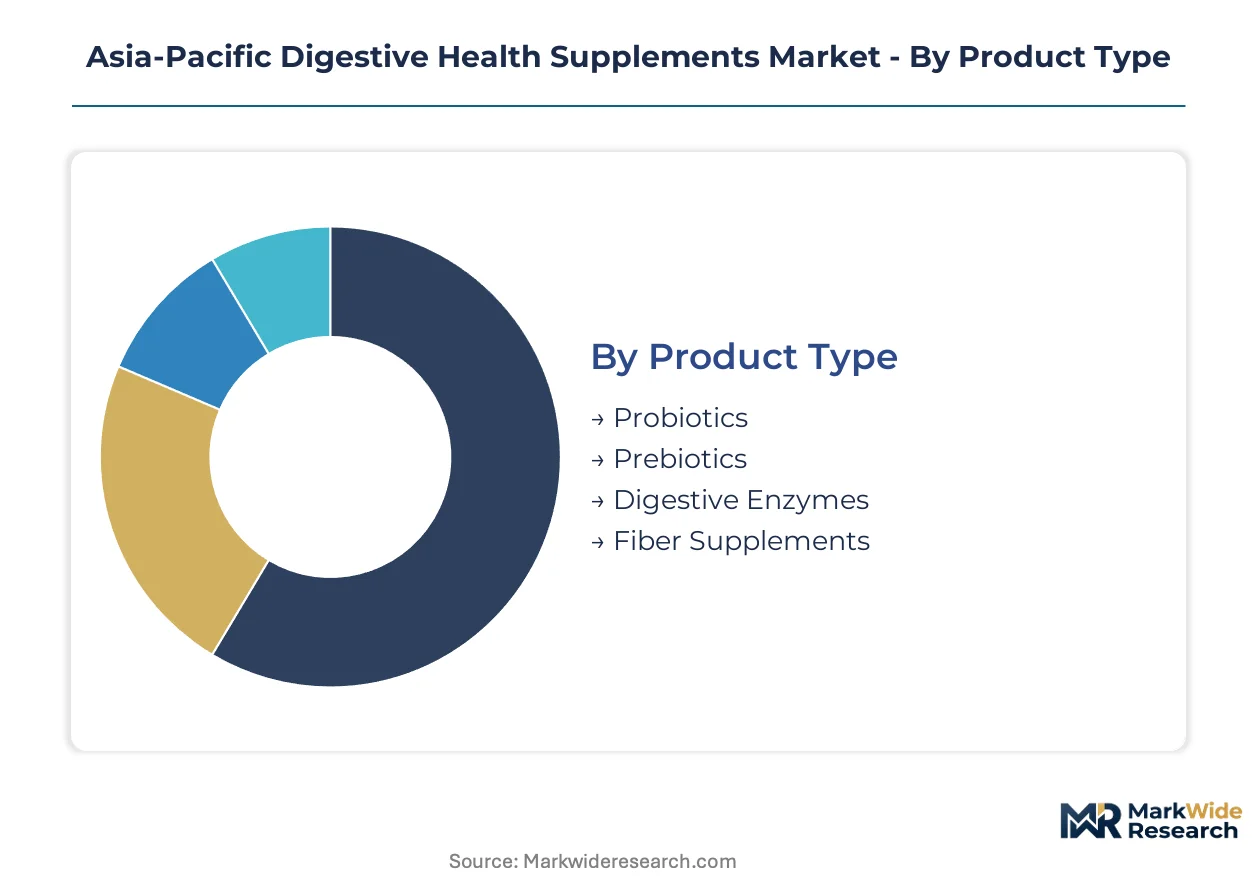
Segmentation in Asia-Pacific digestive health supplements reveals how capital deployment, regulatory compliance burdens, and cold-chain infrastructure requirements concentrate competitive advantage across distinct product architectures. Manufacturers must align portfolio breadth with specific strain-documentation capabilities and channel-access investments.
Product Type:
Capital intensity varies sharply across microbial versus non-microbial segments, driven by fermentation infrastructure, live-culture stabilization R&D, and multi-jurisdiction stability-testing documentation requirements.
- Probiotics:Live microbial cultures standardized to colony-forming units demand refrigerated fermentation tanks, lyophilization capacity, and accelerated shelf-life validation per PMDA and TGA protocols. Demand concentrates in Japan and Australia where clinician endorsement programs validate strain-specific claims for aging populations with antibiotic-associated dysbiosis.
- Prebiotics:Non-digestible oligosaccharides require lower temperature-controlled investment but face FSSAI purity verification for inulin and FOS imports into India. South Korean functional food manufacturers expand galacto-oligosaccharide portfolios through MFDS fast-track pathways.
- Digestive Enzymes:Hydrolytic proteins and lipases target lactose-intolerant demographics across Southeast Asia with ambient-stable distribution economics.
- Fiber Supplements:Soluble and insoluble matrices bypass cold-chain dependencies entirely, enabling mass-market penetration in Vietnam and Thailand where traditional fermented food alternatives compete.
Most installed capacity flows through Probiotics. Expansion is steepest in Digestive Enzymes.
Application:
End-use positioning determines margin structure and channel access, with prescription-adjacent applications commanding premium pricing against wellness-positioned alternatives.
- Gut Health:IBS and constipation relief formulations dominate pharmacy-centric distribution in Thailand and the Philippines where pharmacist consultation cultures resist pure e-commerce displacement.
- Weight Management:Microbiome-modulation claims face tightening substantiation requirements under Australia's TGA advertising codes, compressing marketing flexibility for direct-to-consumer brands.
- Immune Support:Clinically validated probiotic strains with IgA-modulation documentation capture urban professional segments in Metro Manila and Bangkok through telehealth-integrated subscription models.
- Nutritional Enhancement:Protein digestion aids and micronutrient absorption boosters target geriatric populations in Japan with hospital discharge protocol integrations.
Gut Health commands the largest revenue pool. Immune Support is gaining share fastest through hybrid fulfillment channels.
Formulation:
Physical delivery format shapes manufacturing capex, with enteric-coating and microencapsulation technologies enabling ambient-temperature distribution previously restricted to cold-chain-dependent alternatives.
- Tablets:Compressed formulations with enteric coatings protect acid-labile strains through gastric passage, reducing refrigeration requirements for retail placement in convenience stores across Japanese urban corridors.
- Powders:Sachet packaging dominates South Korean functional food channels and Indian direct-selling networks where portion-controlled dosing aligns with subscription model economics.
- Liquids:Ready-to-drink fermented dairy formats anchor Yakult's refrigerated channel dominance but impose 15-25% logistics cost premiums limiting rural penetration.
- Capsules:Two-piece hard gelatin and vegetarian shells enable strain-specific dosing precision for clinician-directed regimens in Australian pharmacy networks.
Tablets absorb the majority of probiotic R&D investment. Powders show the steepest volume climb through e-commerce personalization services.
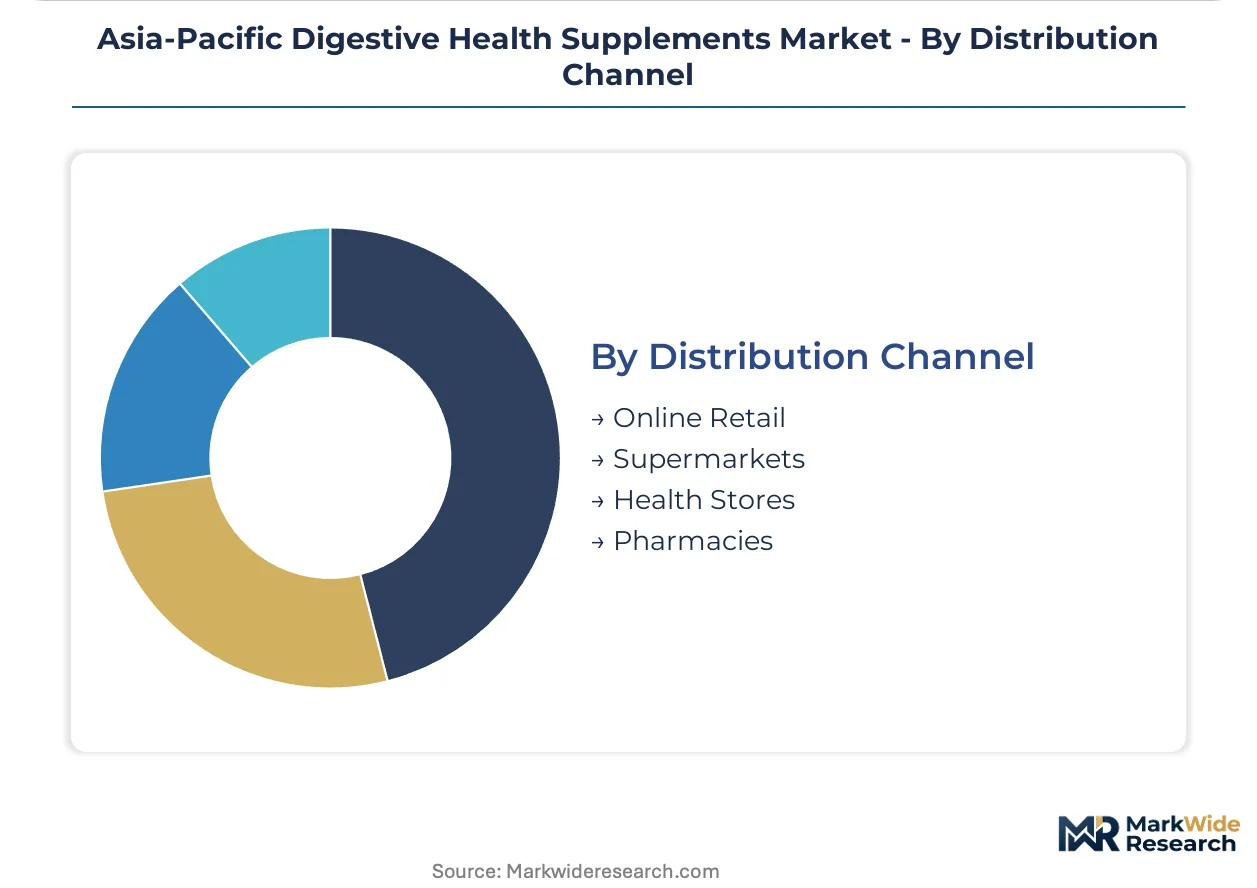
Distribution Channel:
Channel selection determines margin retention and customer data access, with direct-to-consumer models capturing recurring revenue pools while pharmacy networks provide clinical credibility transfer.
- Online Retail:Subscription platforms and microbiome testing integrations capture urban India and Australian professional segments seeking convenience without sacrificing personalization.
- Supermarkets:Mass-market shelf-stable fiber and enzyme products compete on price density in Vietnam and Thailand where traditional medicine systems displace premium supplement uptake in rural demographics.
- Health Stores:Specialty retailers concentrate demand for organic-certified and clean-label positioned SKUs in Australian metropolitan clusters with above-average digital payment penetration.
- Pharmacies:Clinician endorsement programs and prescription-adjacent positioning anchor Abbott Laboratories' Southeast Asian presence through pharmacist consultation cultures.
Pharmacies retain structural importance in markets with active professional guidance traditions. Online Retail is expanding most quickly through telehealth integrations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Microbiologists and fermentation specialists cluster around Tokyo, Seoul, and Melbourne, anchoring strain-development capabilities that shape product pipelines across the region.
Japan
PMDA's 2023 stability-testing guideline revisions for multi-strain probiotics extend registration timelines by 8-14 months, filtering out undercapitalized entrants. The Kanto region surrounding Tokyo houses dedicated in-house analytical laboratories that absorb compliance costs through accelerated shelf-life validation protocols. Refrigerated channel dominance by fermented dairy formats persists in convenience stores across Osaka and Nagoya corridors.
South Korea
MFDS fast-track approval pathways for functional foods incentivize domestic manufacturers to expand galacto-oligosaccharide portfolios. Seoul Capital Area concentration of R&D facilities drives strain-specific patent development for aging demographics with antibiotic-associated dysbiosis. Sachet packaging formats align with subscription model economics in direct-selling networks penetrating Busan-Ulsan metropolitan clusters.
Australia
TGA advertising codes tighten substantiation requirements for microbiome-modulation claims, compressing marketing flexibility for direct-to-consumer brands. Sydney and Melbourne metropolitan areas concentrate demand for clinically validated strains through telehealth-integrated subscription models. Health stores in these clusters capture organic-certified and clean-label positioned SKUs where digital payment penetration exceeds national averages.
India
FSSAI label-claim verification mandates for imported supplements recalibrate cost-of-entry calculus for foreign brands seeking multi-brand outlet shelf space. Maharashtra and Gujarat manufacturing corridors develop domestic fermentation capacity to bypass import-registration bottlenecks. Direct-selling networks in Delhi-NCR and Bangalore bypass traditional retail markup structures through portion-controlled powder formulations.
Thailand
Pharmacist consultation cultures in Bangkok and Metro Manila metropolitan corridors resist pure e-commerce displacement through hybrid fulfillment models. Traditional medicine systems in rural provinces displace standardized supplement uptake, limiting mass-market penetration beyond urban professional segments. Telehealth-integrated platforms capture recurring revenue pools where digital payment infrastructure exceeds national penetration by 30 percentage points.
Asia-Pacific Digestive Health Supplements Market Competitive Environment
The competitive structure tilts toward multinational pharmaceutical and nutrition conglomerates with cold-chain infrastructure and clinician endorsement capabilities. Strain-specific patent portfolios and refrigerated logistics networks consolidate advantage around clinically validated formulations. Three archetypes dominate: fermented dairy heritage players with convenience store channel control, pharmacy-centric distributors leveraging prescription-adjacent positioning, and direct-selling networks bypassing retail markups entirely. Competitive moves concentrate on microencapsulation technology licensing and subscription platform acquisitions.
Among heritage-anchored Japanese manufacturers, Yakult Honsha Co., Ltd. exemplifies refrigerated channel dominance through ready-to-drink fermented dairy formats. Abbott Laboratories occupies a position within the pharmacy-centric archetype, anchoring clinician endorsement programs across Southeast Asian markets. Herbalife Nutrition Ltd. represents the direct-selling network model, bypassing traditional retail structures through personalized portion-controlled distribution. These three players illustrate how divergent channel strategies segment competitive terrain without requiring overlapping infrastructure investments.
| Leading Market Players |
|---|
| Bayer AG |
| Herbalife Nutrition Ltd. |
| Abbott Laboratories |
| Amway |
| Pfizer Inc. |
| NOW Foods |
| Yakult Honsha Co., Ltd. |
| Blackmores Limited |
| Kalbe Farma |
| Others |
Value Chain & Pricing Dynamics
FSSAI label-claim verification mandates in India are forcing foreign brands to absorb documentation and testing costs that compress margins or force exit from multi-brand outlet channels, while domestic fermentation capacity in Maharashtra and Gujarat captures displaced demand through lower landed costs. This regulatory-driven procurement preference reshapes how supply must configure across the region and where pricing power concentrates.
Pricing Analysis
Bundled clinician endorsement programs command premiums against unbundled direct-to-consumer subscriptions across Southeast Asian pharmacy networks. Three-tier pricing structure across premium refrigerated probiotics, standard shelf-stable enzymes, and economy fiber matrices reflects cold-chain investment differentials and certification grade. Cost compression in mid-tier probiotics is intensifying because microencapsulation technology licensing spreads ambient-stable alternatives. Rural demographics in Vietnam and Thailand exhibit highest price sensitivity, while Australian urban professionals show lowest sensitivity to microbiome personalization premiums.
Supply Chain Analysis
Direct-to-pharmacy channels handle prescription-adjacent demand in Bangkok and Metro Manila, while hybrid fulfillment with physical pickup serves telehealth-integrated subscriptions in Australian metropolitan clusters. Manufacturing concentrates in Japan, South Korea, and India, with strain-development capabilities clustering around Tokyo, Seoul, and Melbourne. Live-culture fermentation draws from specialized lyophilization equipment and refrigerated logistics networks. Single-source vulnerability in PMDA-compliant stability documentation creates bottlenecks for multi-strain probiotic entrants. Distribution runs through pharmacy-centric networks in Thailand, direct-selling platforms in India, and convenience store channels in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific digestive health supplements function as a regulatory compounder where PMDA's 2023 stability-testing guideline revisions extend multi-strain registration timelines and filter out undercapitalized competitors, accelerating consolidation around clinically validated portfolios.
For Market Incumbents: Anticipate microencapsulation technology licensing wars as ambient-stable formulations collapse tier boundaries between refrigerated and shelf-stable positioning. Defend advantage through captive in-house analytical laboratories that absorb PMDA compliance costs without partnership-dependent verification delays. Prioritize MFDS fast-track pathway exploitation in South Korea before domestic manufacturers saturate galacto-oligosaccharide portfolios.
For New Entrants and Emerging Players: MFDS fast-track approval in South Korea opens a window for functional food positioning without Japan's extended registration timelines. Target digestive enzyme formulations in Southeast Asian lactose-intolerant demographics where ambient-stable distribution avoids cold-chain capital intensity. Pursue subscription direct-to-consumer models in urban India and Australia with microbiome testing integrations as the primary go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier enzyme specialists possessing ambient-stable formulation expertise but lacking cold-chain infrastructure. Long-term viability centers on acquisition targets with strain-specific patent portfolios and existing pharmacy network relationships rather than pure-play e-commerce brands. Watch harmonization progress between ASEAN regulatory frameworks as the inflection indicator for where compliance burdens will concentrate or dissipate.
| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Enables ambient-temperature distribution for previously cold-chain-dependent strains, collapsing tier boundaries. |
| MFDS Fast-Track Certification Pursuit | South Korea's streamlined pathway accelerates functional food market entry before domestic saturation. |
| In-House Analytical Laboratory Investment | Absorbs PMDA compliance costs and eliminates partnership-dependent verification bottlenecks for multi-strain products. |
| Telehealth-Integrated Subscription Launch | Captures urban professional segments in Bangkok and Metro Manila where digital payment penetration exceeds national averages. |
| Domestic Fermentation Capacity Buildout | Maharashtra and Gujarat manufacturing corridors bypass FSSAI import-registration bottlenecks and reduce landed costs. |
Study Parameters
Direct dialogue with regulatory affairs specialists at PMDA and TGA, supply chain directors at refrigerated logistics providers, pharmacy procurement managers in Bangkok and Manila, and microbiome testing platform executives grounded qualitative insights. Secondary validation drew from MFDS functional food registration databases, FSSAI import compliance filings, ASEAN harmonization working group minutes, and customs trade data for oligosaccharide and enzyme imports. Bottom-up strain-level demand modeling triangulated against top-down category spend projections.
Segmentation outputs across product type, application, formulation, and distribution channel dimensions were generated through the projection horizon. CAGRs were derived from regression analysis against aging demographic trajectories, regulatory timeline shifts, and cold-chain infrastructure investment patterns. Forecast inputs incorporated PMDA stability-testing protocol revisions, MFDS fast-track approval velocity, and digital payment penetration differentials between metropolitan and rural corridors.
Revisions become necessary when ASEAN regulatory harmonization accelerates or stalls, when microencapsulation technology licensing costs drop below cold-chain depreciation thresholds, or when major markets impose additional import documentation requirements. Forecasts reflect assumptions about strain characterization expertise availability and refrigerated logistics capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Stress Relief Supplements Market
Nutritional Supplements
Red Yeast Rice Market
Nutritional Supplements
Milk Thistle Market
Nutritional Supplements
Asia-Pacific Arachidonic Acid Market
Nutritional Supplements
Europe Omega-3 Products Market
Nutritional Supplements
Asia-Pacific Feed Prebiotics Market
Nutritional Supplements
Europe Beta-Glucan Market
Nutritional Supplements
Folate Market
Nutritional Supplements
Europe Digestive Health Supplements Market
Nutritional Supplements
Europe Moringa Supplement Market
Nutritional Supplements
Dhea Supplement Market
Nutritional Supplements
Tongkat Ali Market
Nutritional Supplements
Asia Pacific Nutritional Supplements Market
Nutritional Supplements
Hangover Cure Products Market
Nutritional Supplements
Dextrose Monohydrate Market
Nutritional Supplements
Australia Protein Market