
 Asia-Pacific Amino Acid in Dietary Supplements Market | 2026-2036
Asia-Pacific Amino Acid in Dietary Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Amino Acid in Dietary Supplements Market Outlook
Buyer concentration among fitness enthusiasts and bodybuilders is shifting toward specialized sports nutrition channels across Southeast Asia. Ajinomoto Co., Inc. leverages its fermentation technology leadership to dominate L-glutamine supply chains. CJ CheilJedang anchors regional production through integrated amino acid manufacturing in South Korea. Kyowa Hakko Bio Co., Ltd. differentiates via pharmaceutical-grade purity standards for clinical nutrition applications.
Amino acids in dietary supplements comprise nitrogen-containing organic compounds synthesized through fermentation or enzymatic extraction, typically formulated at 2-5 gram serving thresholds for muscle protein synthesis and metabolic support. The primary commercial purpose centers on enhancing athletic recovery, lean mass retention, and immune function in physically active populations. L-glutamine and L-leucine command the largest volume positions, reflecting entrenched demand from strength-training segments. Powder formulations capture the fastest growth trajectory, driven by dose flexibility and flavor customization preferences among millennial consumers in Australia and Japan.
China's NMPA health food registration requirements, Japan's FOSHU approval framework, and Australia's TGA listing obligations collectively elevate compliance costs while filtering substandard entrants from distribution channels. India's FSSAI recently tightened amino acid labeling thresholds for imported supplements, redirecting some procurement toward domestic contract manufacturers. Stakeholders must monitor regulatory divergence between ASEAN harmonization efforts and national registration regimes when allocating regional product development budgets.
Market Dynamics
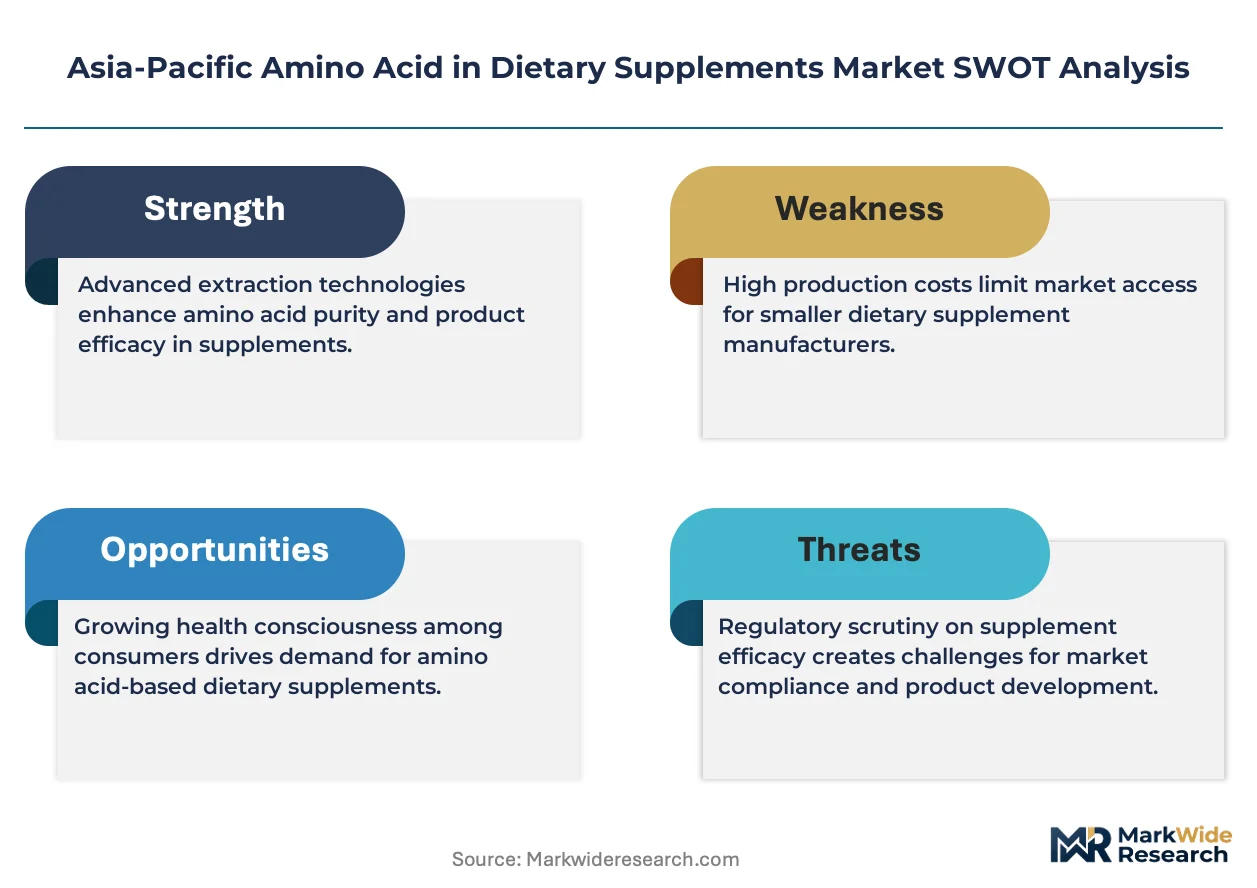
China's NMPA health food registration tightening is compressing product approval timelines and forcing reformulation investments, while fermentation technology advances reshape manufacturing economics across South Korea and Japan.
Growth Catalysts
- FSSAI Labeling Thresholds:India's tightened amino acid labeling rules for imports redirect procurement toward domestic contract manufacturers, accelerating local production capacity expansion.
- Fermentation Technology Maturation:Microbial strain engineering advances in South Korea reduce L-glutamine production costs while improving purity profiles for clinical-grade applications.
- Metropolitan Fitness Corridors:Concentrated demand from bodybuilders and strength-training populations in India's Mumbai-Delhi-Bengaluru axis sustains volume absorption for branched-chain amino acid formulations.
Market Restraints
- Input Cost Volatility:Corn and soybean feedstock price swings for fermentation substrates compress margin predictability for amino acid manufacturers dependent on agricultural inputs.
- Regulatory Friction:Divergent ASEAN harmonization timelines against national registration regimes in Thailand, Indonesia, and Vietnam fragment compliance pathways and extend product launch cycles.
- Substitution Threat:Plant-based protein isolates and collagen peptides capture functional positioning in recovery nutrition, displacing amino acid share in casual fitness segments.
Strategic Opportunities
- Vietnam and Philippines Underpenetration:Emerging gym culture and rising disposable incomes in Ho Chi Minh City and Manila metro areas present first-mover positioning for sports nutrition brands.
- Dual Carbon Goals Alignment:China's MEE carbon intensity targets incentivize fermentation process optimization investments that yield both regulatory compliance and operational cost advantages.
- Direct-to-Consumer Subscription Models:Powder formulation personalization via flavor customization and dose flexibility captures recurring revenue streams from millennial consumers in Australia and Japan.
Industry Challenges
- Pharmaceutical-Grade Certification Timelines:Japan's PMDA and Australia's TGA clinical nutrition purity standards demand 18-24 month validation cycles that strain working capital for mid-scale manufacturers.
- Bioprocess Engineering Talent Scarcity:Specialized fermentation optimization and downstream purification expertise concentrates in South Korea and Japan, constraining regional production scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Amino Acid in Dietary Supplements Market |
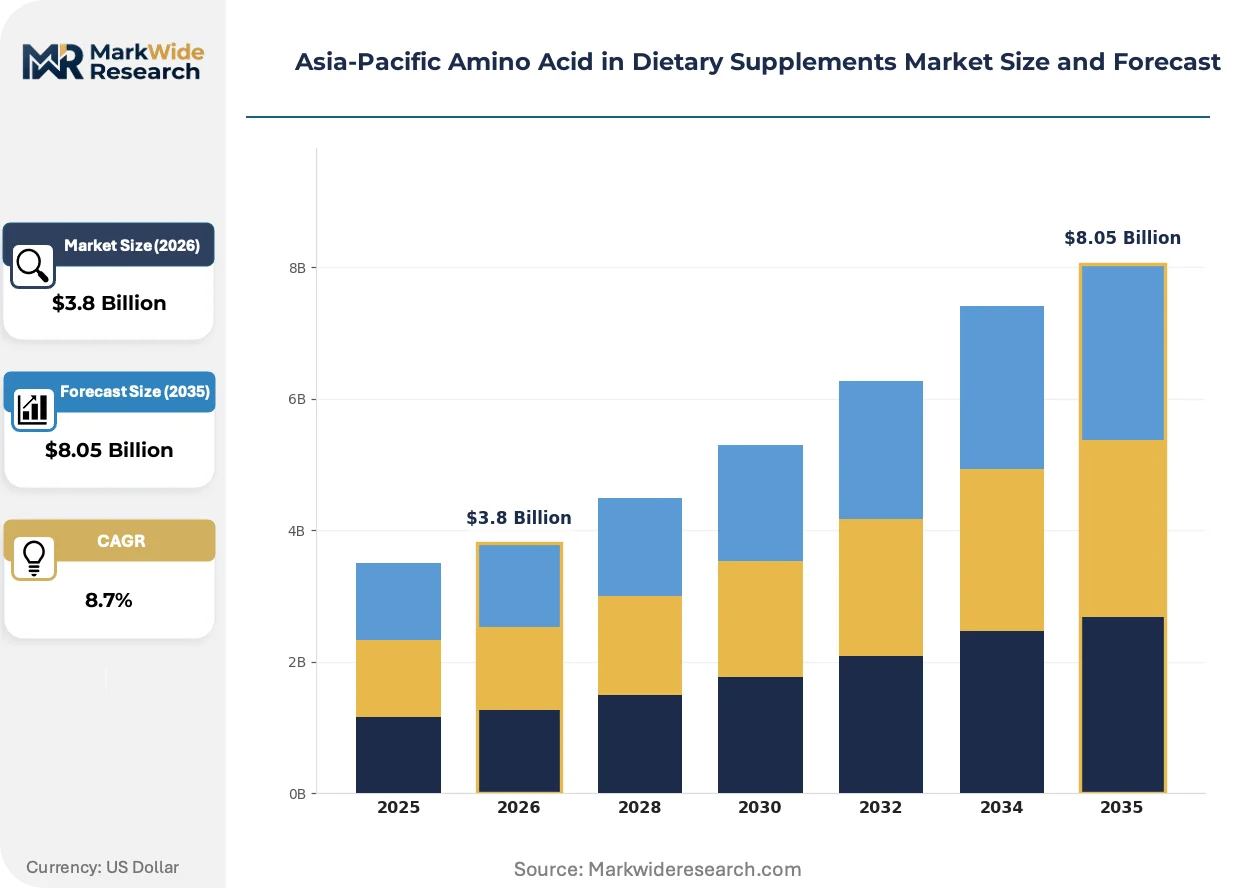
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: L-Glutamine, L-Leucine, L-Arginine, L-Taurine Form: Pills, Powder, Liquid, Chewable End User: Athletes, Fitness Enthusiasts, Bodybuilders, Vegetarians Packaging Type: Bottles, Sachets, Jars, Pouches |
| Companies Covered | Ajinomoto Co., Inc., Evonik Industries AG, MusclePharm, NOW Foods, Solgar Inc., Optimum Nutrition, CJ CheilJedang, Kyowa Hakko Bio Co., Ltd., Universal Nutrition, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Amino Acid in Dietary Supplements Market Strategic Shifts
Continuous fermentation monitoring and enzymatic extraction advances are compressing batch-to-batch variability while enabling real-time quality assurance that satisfies tightening pharmaceutical-grade specifications.
Precision fermentation platforms incorporating AI-driven metabolic pathway optimization are decentralizing amino acid production economics. Mid-scale manufacturers in South Korea and Australia adopt these systems to achieve parity with integrated giants on L-leucine purity metrics. The technology is decentralizing geographic concentration of pharmaceutical-grade supply, enabling distributed manufacturing nodes closer to Southeast Asian demand centers.
Japan's FOSHU approval framework revision is extending functional claim substantiation requirements for immune-support amino acid products. The policy compresses permissible marketing language while elevating clinical trial investment thresholds. Supplement brands targeting Japan's aging demographic are responding with repositioning toward general wellness positioning rather than specific physiological claims.
Millennial consumers in Australia and Japan are abandoning brick-and-mortar pharmacy channels for specialized sports nutrition e-commerce platforms offering subscription personalization. Direct brand relationships are displacing traditional distributor networks. This channel rotation is most visible in Sydney and Tokyo metropolitan zones where same-day delivery infrastructure supports just-in-time replenishment of powder formulations.
Asia-Pacific Amino Acid in Dietary Supplements Market Segmentation
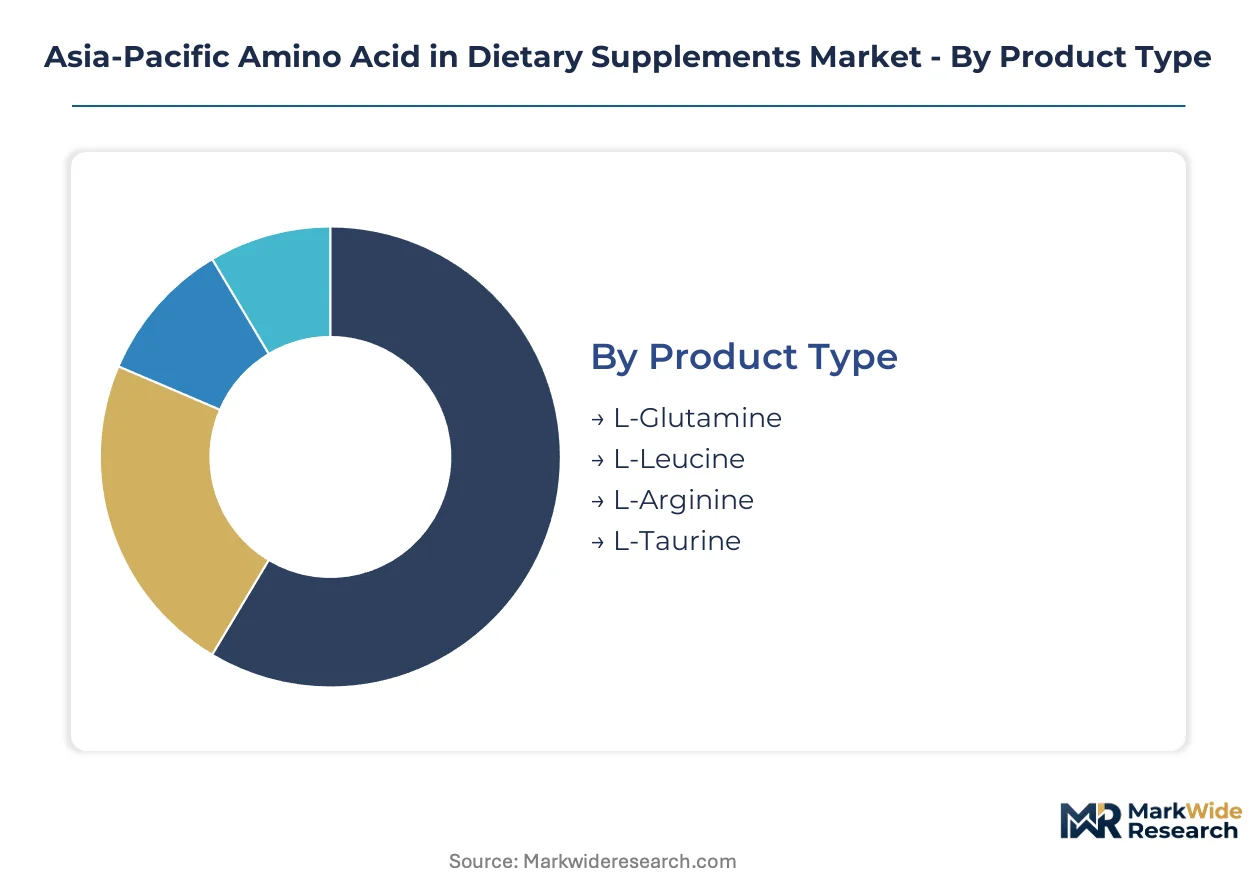
Segmentation in the Asia-Pacific amino acid supplements market reveals divergent value capture between mass-market formulations and clinical-grade products. Manufacturers optimize production allocation by tracking how form factor preferences and end-user intensity vary across China's tier-one cities versus India's emerging fitness corridors.
Product Type:
Volume leadership concentrates in commodity-grade amino acids serving bodybuilders, while premium positioning targets pharmaceutical-grade specifications for clinical nutrition applications.
- L-Glutamine:This conditionally essential amino acid dominates fermentation output volumes across South Korean and Japanese manufacturing facilities. Demand concentrates in India's Mumbai-Delhi-Bengaluru fitness corridor where strength-training populations prioritize recovery formulations. NMPA registration tightening in China elevates purity documentation requirements for imported L-glutamine shipments.
- L-Leucine:The primary branched-chain amino acid drives muscle protein synthesis signaling at 2-3 gram serving thresholds. Australia's TGA listing obligations and Japan's FOSHU framework create dual compliance pathways that fragment supplier certification investments. Precision fermentation advances in South Korea are compressing production costs for this segment.
- L-Arginine:Nitric oxide precursor formulations target vascular function positioning in aging consumer segments across Japan and Australia.
- L-Taurine:Sulfur-containing amino acid captures energy drink co-formulation demand and cardiac function claims in Southeast Asian markets.
Mature deployment sits with L-glutamine. Newer deployment is concentrated in L-leucine precision fermentation platforms.
Form:
Consumer convenience preferences split between portable dosing formats and bulk value propositions, with channel strategy determining optimal form factor allocation.
- Powder:Dose flexibility and flavor customization capabilities capture millennial preference share in Australia's Sydney metropolitan zone and Japan's Tokyo corridor. Direct-to-consumer subscription models exploit powder formulation personalization to secure recurring revenue streams. Same-day delivery infrastructure supports just-in-time replenishment cycles.
- Pills:Pre-measured dosing convenience dominates pharmacy channel distribution across India's urban centers and China's tier-one cities. FSSAI labeling threshold compliance costs redirect some pill procurement toward domestic Indian contract manufacturers.
- Liquid:Rapid absorption positioning targets intra-workout consumption occasions in Vietnam and Philippines gym culture emergence.
- Chewable:Palatability-focused formats capture entry-level fitness enthusiasts and vegetarian segment conversion in Southeast Asian markets.
Volume concentration favors powder formats. Margin optimization concentrates in pill manufacturing for regulated pharmacy channels.
End User:
Intensity of consumption and price sensitivity create distinct service requirements across performance-focused versus wellness-oriented segments.
- Bodybuilders:High-dose consumption patterns (10-15 grams daily) sustain volume absorption for bulk powder formulations. Concentrated demand in India's metropolitan fitness corridors and Australia's competitive bodybuilding communities supports specialized sports nutrition channel development. Protein synthesis optimization drives premium-grade amino acid specification requirements.
- Athletes:Team sport and endurance competitors prioritize batch-tested certifications and anti-doping compliance documentation. Australia's TGA and Japan's anti-doping agency protocols elevate supplier qualification barriers. Recovery timing protocols drive consumption occasion segmentation.
- Fitness Enthusiasts:Casual gym attendance patterns support sachet and trial-size packaging formats across Southeast Asia's emerging gym culture.
- Vegetarians:Dietary restriction-driven demand concentrates in L-lysine and L-methionine supplementation for plant-based protein completeness in Indian and Australian markets.
Established demand concentration sits with bodybuilders. Emerging expansion is concentrated in fitness enthusiasts across Vietnam and Philippines metropolitan areas.
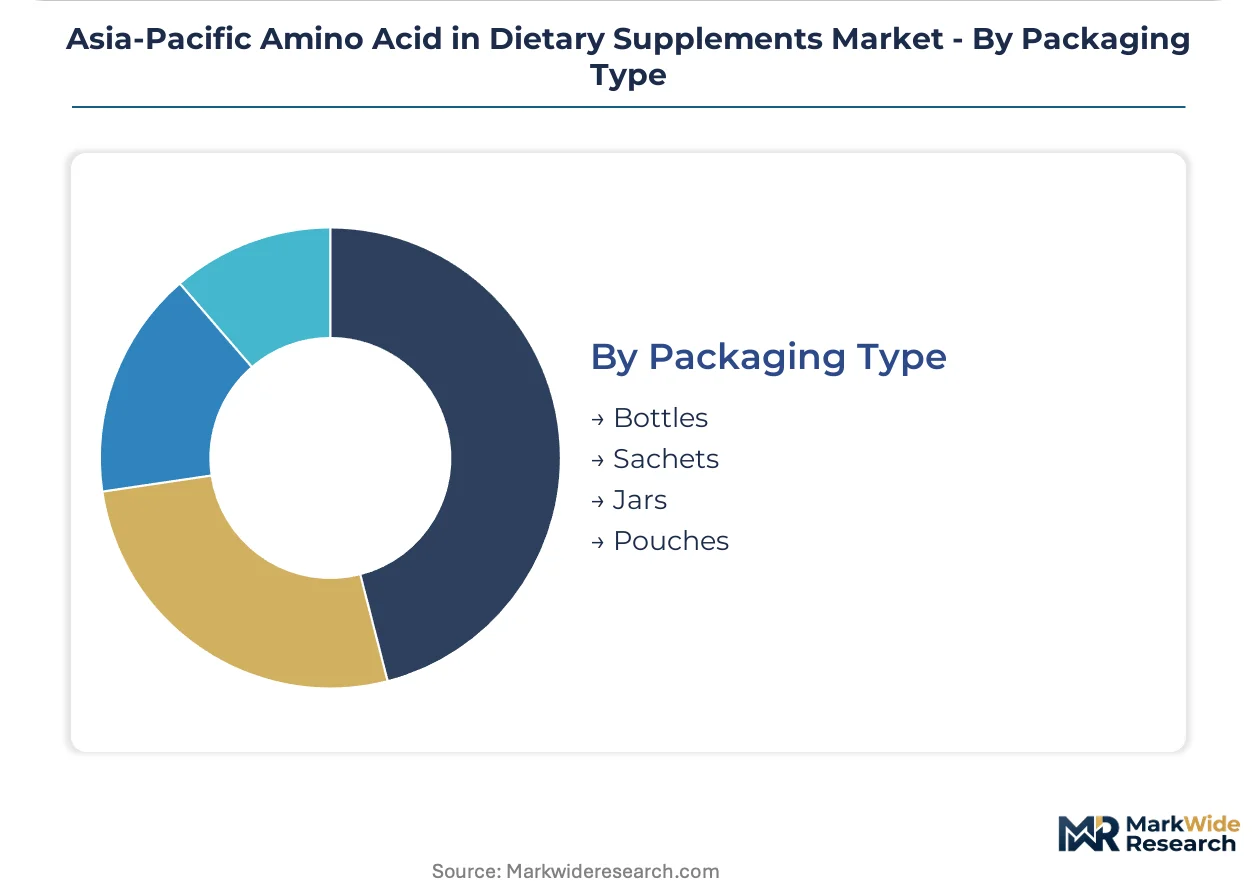
Packaging Type:
Distribution channel economics and consumption occasion portability requirements determine packaging format viability across e-commerce versus traditional retail pathways.
- Sachets:Single-serve portability aligns with gym bag consumption occasions and trial-size sampling strategies. Millennial channel migration toward specialized sports nutrition e-commerce platforms in Australia and Japan favors sachet-based subscription curation. Lower shipping weight reduces direct-to-consumer fulfillment costs.
- Bottles:Standard container format dominates pharmacy and mass retail shelf presence across China and India. NMPA and FSSAI labeling compliance documentation integrates most efficiently with bottle packaging production lines.
- Jars:Bulk powder storage optimization serves committed bodybuilder replenishment cycles in South Korean and Japanese markets.
- Pouches:Flexible format innovation targets sustainability positioning and reduced material cost in ASEAN distribution channels.
Traditional retail concentration sits with bottles. Digital-native deployment is concentrated in sachet formats for subscription personalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China's tier-one cities and India's metropolitan fitness corridors, with fermentation technology hubs in South Korea and Japan anchoring supply-side capacity.
China
Beijing, Shanghai, and Shenzhen drive consumption among affluent fitness enthusiasts seeking premium recovery formulations. NMPA health food registration tightening compresses product approval timelines and elevates purity documentation requirements for imported shipments. Yangtze River Delta manufacturing clusters optimize fermentation processes to align with MEE carbon intensity targets.
India
Mumbai, Delhi, and Bengaluru sustain volume absorption for branched-chain amino acid formulations through concentrated bodybuilder populations. FSSAI labeling threshold enforcement redirects procurement toward domestic contract manufacturers. Gujarat and Maharashtra production facilities expand capacity to capture redirected import demand.
Japan
Tokyo and Osaka metropolitan zones exhibit millennial channel migration toward specialized sports nutrition e-commerce platforms. PMDA pharmaceutical-grade certification timelines strain working capital for clinical nutrition suppliers. Kanto region precision fermentation adopters achieve parity with integrated giants on purity metrics.
South Korea
Seoul Capital Area anchors integrated amino acid manufacturing through fermentation technology leadership. MFDS regulatory alignment with international standards facilitates export-oriented production scaling. Busan-Ulsan industrial corridors concentrate bioprocess engineering expertise for downstream purification optimization.
Australia
Sydney metropolitan consumers favor powder formulation personalization via direct-to-consumer subscription models. TGA listing obligations and anti-doping compliance documentation elevate supplier qualification barriers. Victoria and New South Wales distribution infrastructure supports same-day delivery replenishment cycles.
Asia-Pacific Amino Acid in Dietary Supplements Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue precision fermentation platforms and direct-to-consumer channel capture. The vendor base stratifies across integrated fermentation giants, specialized pharmaceutical-grade suppliers, and branded sports nutrition formulators. Three archetypes dominate: technology-led manufacturers leveraging microbial strain engineering, compliance-focused specialists targeting regulated clinical channels, and brand-led marketers exploiting e-commerce personalization. Capacity expansion and strategic partnerships represent the dominant competitive moves, with fermentation optimization investments yielding both cost advantages and regulatory alignment.
Within the technology-led tier, Ajinomoto Co., Inc. and CJ CheilJedang occupy positions reflecting integrated fermentation capabilities and regional production anchoring. Kyowa Hakko Bio Co., Ltd. exemplifies the pharmaceutical-grade specialist archetype, sitting within the compliance-intensive clinical nutrition segment. These three entities represent distinct strategic postures: scale-driven manufacturing integration, regional supply chain control, and purity-standard differentiation respectively.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Evonik Industries AG |
| MusclePharm |
| NOW Foods |
| Solgar Inc. |
| Optimum Nutrition |
| CJ CheilJedang |
| Kyowa Hakko Bio Co., Ltd. |
| Universal Nutrition |
| Others |
Value Chain & Pricing Dynamics
FSSAI labeling threshold enforcement for imported amino acid supplements is redirecting procurement volumes toward domestic Indian contract manufacturers, forcing supply chain reconfiguration and compressing margin structures for foreign suppliers dependent on export positioning.
Pricing Analysis
Volume concentration in commodity-grade L-glutamine powder runs through bulk contract manufacturing, while margin capture concentrates in pharmaceutical-grade L-leucine certified for clinical nutrition applications. Three-tier pricing structure separates pharmaceutical-grade, sports nutrition-grade, and economy-grade amino acids based on purity documentation and certification investment. Price differentiation hinges on NMPA registration compliance costs and TGA listing obligations that elevate supplier qualification barriers. Cost compression in economy-grade segments is intensifying because corn and soybean feedstock volatility compresses fermentation substrate economics. Casual fitness enthusiasts in Southeast Asia exhibit highest price sensitivity, while clinical nutrition buyers in Japan demonstrate lowest elasticity due to pharmaceutical-grade specification requirements.
Supply Chain Analysis
India's tightened domestic-content mandates for amino acid supplement labeling are reshaping sourcing patterns, accelerating capacity expansion at Gujarat and Maharashtra production facilities. Supply concentration centers on South Korea, Japan, and China, with fermentation technology leadership anchoring pharmaceutical-grade output. Raw material dependencies rest on corn-derived glucose, soybean meal, and specialized microbial strains engineered for L-glutamine and L-leucine production. Single-source vulnerability concentrates in bioprocess engineering talent scarcity across South Korea and Japan, constraining regional scaling. Distribution runs through specialized sports nutrition e-commerce platforms in Australia and Japan, pharmacy channels in India and China, and direct-to-consumer subscription models capturing millennial preference share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific amino acid supplements market is becoming a vertical-integration race. Players are pursuing backward integration into fermentation substrate supply to insulate margin structures from agricultural commodity volatility.
For Market Incumbents: Deploy precision fermentation platform investments to achieve parity with integrated giants on L-leucine purity metrics. Ajinomoto and CJ CheilJedang should deepen captive supply of pharmaceutical-grade specifications to defend against emerging South Korean precision fermentation adopters. Certification investment in NMPA and TGA compliance creates switching costs that lock in clinical nutrition channel relationships. For New Entrants and Emerging Players: Capture white-space positioning in Vietnam and Philippines metropolitan fitness corridors where gym culture emergence outpaces established brand penetration. Direct-to-consumer subscription models with flavor customization capabilities offer the most penetrable go-to-market angle for millennial consumers in Ho Chi Minh City and Manila. Sachet-based trial formats reduce customer acquisition costs in underdeveloped sports nutrition retail infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale precision fermentation specialists given AI-driven metabolic pathway optimization compressing production cost curves. Long-term viability favors manufacturers achieving dual carbon goals alignment through fermentation process optimization. Acquisition target archetype: South Korean or Australian precision fermentation adopters with pharmaceutical-grade purity capabilities. Signal to watch: NMPA registration approval velocity as indicator of regulatory barrier height and incumbent protection durability.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Platform Deployment | AI-driven metabolic pathway optimization enables mid-scale manufacturers to achieve integrated-giant parity on L-leucine purity metrics. |
| Domestic Contract Manufacturing Expansion | FSSAI labeling compliance redirects procurement toward Gujarat and Maharashtra facilities, capturing redirected import demand volume. |
| Direct-to-Consumer Subscription Launch | Flavor customization and dose flexibility secure recurring revenue from millennial consumers in Sydney and Tokyo metropolitan zones. |
| Pharmaceutical-Grade Certification Investment | PMDA and TGA validation cycles create 18-24 month barriers that strain working capital for mid-scale competitors. |
| Dual Carbon Goals Alignment Program | MEE carbon intensity targets incentivize fermentation optimization yielding both regulatory compliance and operational cost advantages. |
Study Parameters
Independent corroboration across regulatory filing databases, customs trade records, and pharmaceutical registration systems underwrites the qualitative findings. Primary interviews with fermentation technology directors, sports nutrition brand managers, FSSAI compliance officers, and clinical nutrition procurement leads combined with secondary validation from NMPA registration databases, TGA listing records, and MFDS approval filings. Bottom-up volume modeling triangulates against top-down market sizing from trade flow analysis and production capacity surveys.
Rate-of-change decomposition separates volume growth drivers from value capture dynamics across the projection horizon. Segmentation dimensions modeled include amino acid type, form factor, end-user intensity, and packaging format crossed with regional regulatory cluster. CAGRs derive from regression analysis against historical production output, import-export flows, and consumption intensity metrics. Forecast inputs incorporate fermentation technology maturation curves and regulatory approval timeline compression.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA registration policy shifts, corn and soybean feedstock price volatility, and precision fermentation technology diffusion rates. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and consumer channel migration velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Middle-East and Africa Dietary Supplement Market
Nutritional Supplements
Krill Oil Phospholipid Market
Nutritional Supplements
Andro Supplements Market
Nutritional Supplements
Garlic Extract Supplement Market
Nutritional Supplements
Canada Protein Market
Nutritional Supplements
L-Leucine Market
Nutritional Supplements
Calcium Supplements Market
Nutritional Supplements
Marine Hydrolyzed Collagen Market
Nutritional Supplements
Grass Fed Protein Market
Nutritional Supplements
Lactoferrin Supplements Market
Nutritional Supplements
Lactates Market
Nutritional Supplements
Water Soluble Vitamin and Mineral Feed Supplements Market
Nutritional Supplements
Wellness Supplements Market
Nutritional Supplements
Iron Supplement Market
Nutritional Supplements
North America Beta-Glucan Market
Nutritional Supplements
Africa Beta Glucan Market