
 Vehicle Security System Market | 2026-2036
Vehicle Security System Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Security System Market Intelligence
The capability gap between advanced semiconductor design and full-system integration is reorganizing the competitive landscape. NXP Semiconductors Inc. specializes in the core microcontrollers and secure elements that power modern security modules. Robert Bosch GmbH leverages its system-level expertise to integrate these components into comprehensive vehicle security solutions for OEMs. Continental AG competes by offering a broad portfolio from keyless entry systems to advanced driver monitoring for passenger and commercial vehicles.
A vehicle security system is an electronic assembly designed to prevent unauthorized access, use, or theft of a motor vehicle. It typically integrates components like immobilizers that use RFID technology to authenticate a key fob, and central locking systems controlled via radio frequency signals. Demand from OEMs for factory-installed immobilizer and central locking systems constitutes the market's foundational volume. The vehicle aftermarket providers segment, however, sees higher growth in advanced GPS tracker and biometric recognition solutions, particularly for commercial fleets.
Global standards are influenced by regulations like the UNECE WP.29 framework for vehicle cybersecurity and the Federal Motor Vehicle Safety Standards in the United States. In China, GB standards mandate specific anti-theft device performance, shaping market access for all component and system suppliers. The key decision for system developers is balancing compliance costs with the feature sets demanded by distinct regional consumer preferences and vehicle types.
Market Dynamics
The market's central dynamic is the tension between component-level specialization and the growing demand for full-system, cyber-resilient security architectures. This pressure, intensified by regulatory frameworks like UNECE WP.29, forces a realignment between semiconductor suppliers and system integrators.
Growth Catalysts
- Regulatory Mandates:The UNECE WP.29 regulations require verifiable cybersecurity management systems for all new vehicles, compelling OEMs to integrate more sophisticated, compliant security modules and software across their platforms.
- Commercial Fleet Demands:Operators of commercial fleets are driving adoption of advanced telematics and GPS tracking systems to protect high-value assets from theft and monitor driver behavior, boosting the aftermarket segment.
- Biometric Authentication:The integration of fingerprint or facial recognition for vehicle access and ignition authorization is expanding beyond the luxury segment, creating new demand for advanced sensor and processing components.
Market Restraints
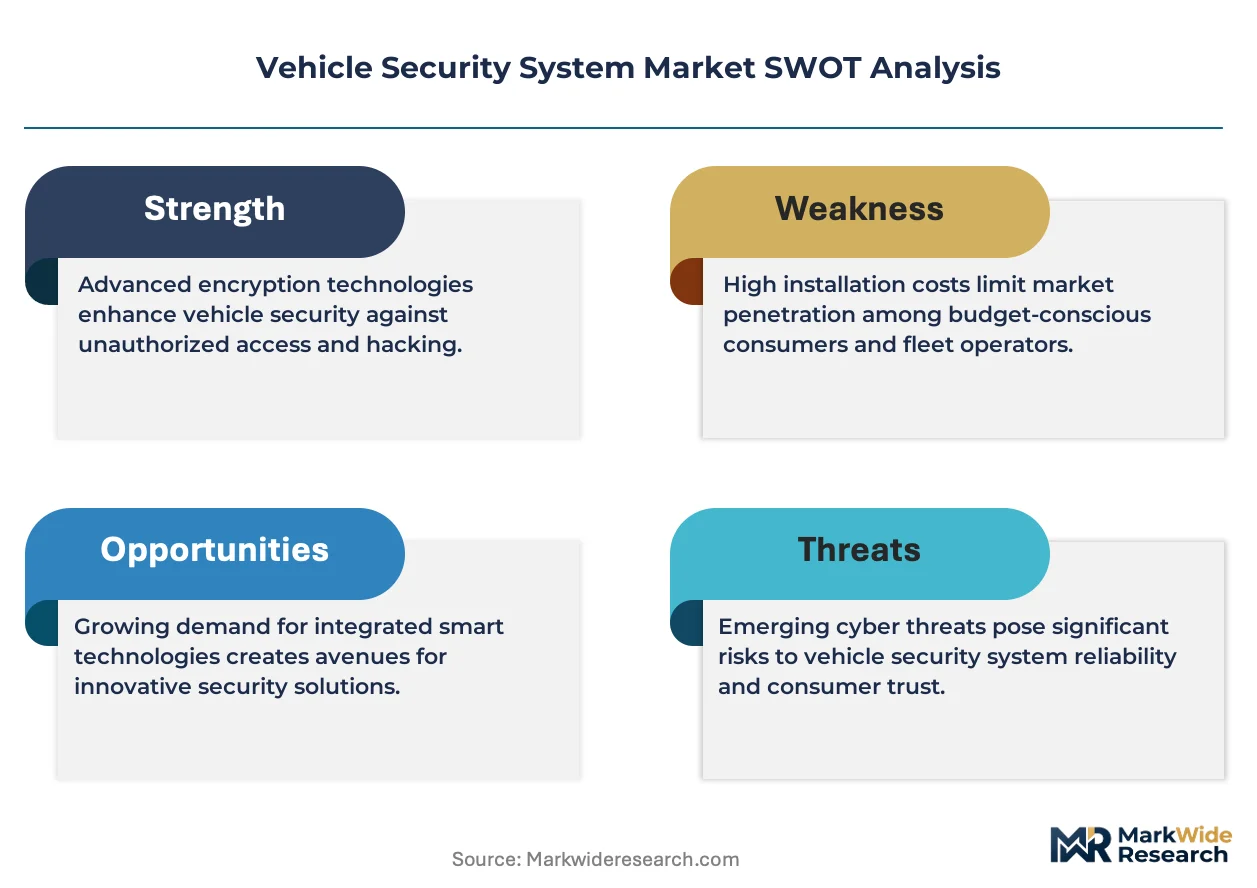
- System Integration Costs:The high upfront cost and complexity of integrating disparate security components, such as immobilizers, sensors, and telematics units, into a cohesive and secure system can strain OEM profit margins.
- Interoperability Failures:A lack of standardization between components from different suppliers creates significant technical hurdles, risking system vulnerabilities and delaying vehicle development timelines for automakers.
- Divergent Regional Standards:Suppliers face increased design and compliance costs to meet conflicting requirements, such as China's GB standards for anti-theft devices versus the Federal Motor Vehicle Safety Standards in the United States.
Strategic Opportunities
- Aftermarket for Legacy Fleets:A significant opportunity exists in equipping older commercial trucks and light vehicles in emerging economies with modern GPS trackers and immobilizers, as these vehicles often lack factory-fitted security.
- V2X Security Integration:The convergence of vehicle-to-everything (V2X) communication with onboard security systems enables new services like remote threat detection, secure over-the-air updates, and coordinated anti-theft responses.
- Driver Monitoring Systems:Expanding security systems to include camera-based driver monitoring creates a dual-purpose product that addresses both anti-theft and driver safety regulations, appealing to passenger and commercial vehicle OEMs.
Industry Challenges
- Legacy System Integration:Incorporating modern, cloud-connected security features into vehicles with older electrical architectures presents a major challenge, often creating new attack surfaces if not executed properly.
- Cybersecurity Talent Scarcity:The industry faces a shortage of engineers possessing the dual expertise in automotive systems engineering and advanced cybersecurity protocols required to design and validate secure vehicle platforms.
- Software Lifecycle Management:Meeting UNECE regulations requires suppliers and OEMs to establish processes for continuous monitoring, vulnerability patching, and secure software updates for the entire vehicle lifespan, a significant operational burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Security System Market |
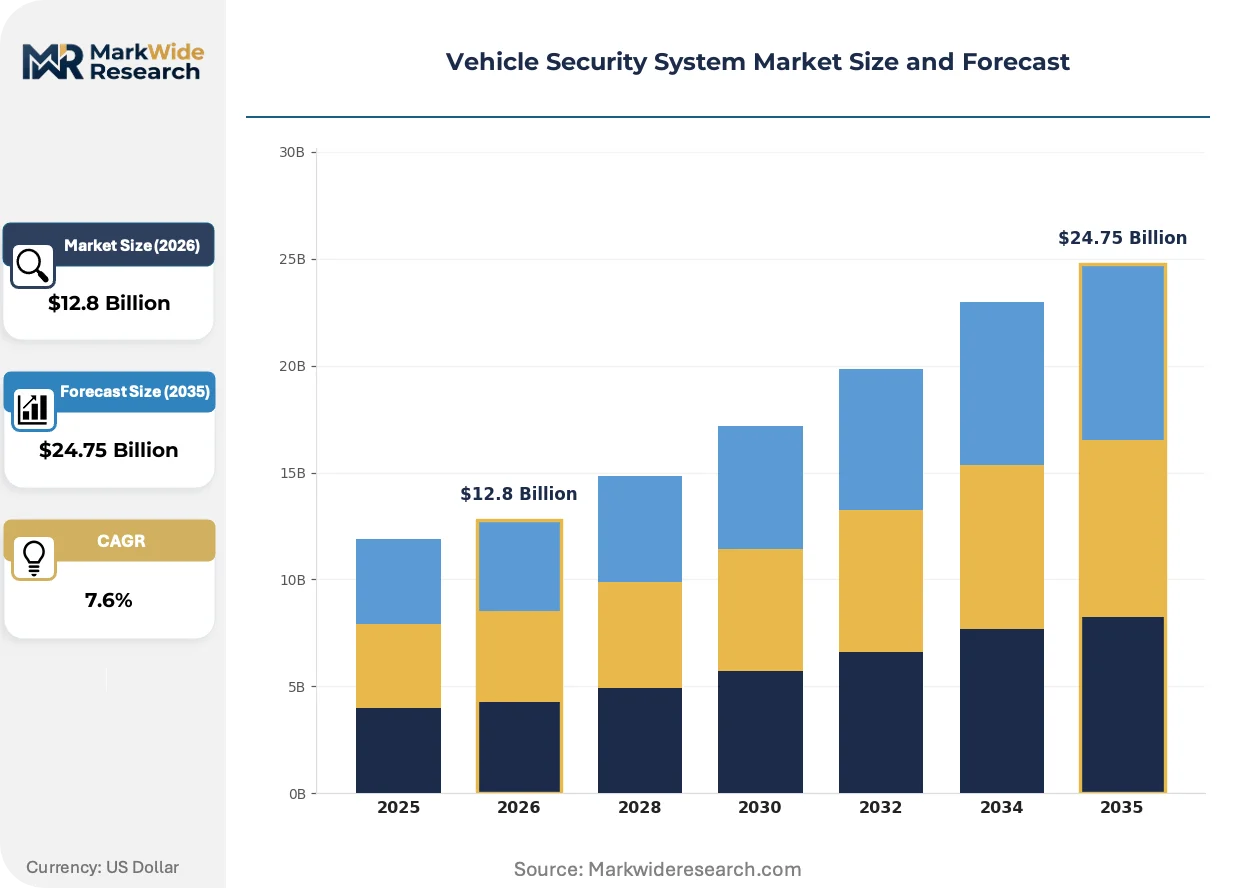
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $24.75 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alarm System, Immobilizer, GPS Tracker, Keyless Entry, Smart Locks, Central Locking Technology: RFID, Infrared Sensors, Biometric Recognition, Ultrasonic Sensors, Radio Frequency, Magnetic Sensors Application: Personal Vehicles, Commercial Fleets, Government Vehicles, Rental Cars, Emergency Vehicles, Public Transport End User: OEMs, Vehicle Aftermarket Providers, Dealerships, Automotive Tier-1 Suppliers, Auto Service Centers, Surveillance Firms |
| Companies Covered | ZF Friedrichshafen AG, Magna International Inc., Continental AG, Autoliv Inc., NXP Semiconductors Inc., Robert Bosch GmbH, Aptiv plc, Veoneer AB, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Security System Market Strategic Shifts & Innovations
The market's evolution is defined by a fundamental shift from isolated, hardware-centric security devices toward integrated, software-defined systems. This transition prioritizes connectivity, remote management, and lifecycle security in response to emerging cyber threats and regulatory pressures.
The centralized Electronic Control Unit (ECU) traditionally managed discrete security tasks like key authentication. Automakers are rapidly adopting new distributed architectures for their next-generation vehicle platforms. This shift is decomposing the monolithic security ECU into a network of zonal controllers and smart sensors, enabling more resilient and updateable security functions across the vehicle.
Regulations such as the UNECE WP.29 framework for cybersecurity are fundamentally altering product development. This standard mandates a security-by-design approach, forcing manufacturers to manage and document cyber risks throughout the vehicle's lifecycle. Component suppliers for telematics and infotainment systems are most affected, now required to provide verifiable software update mechanisms and vulnerability management plans.
A notable behavioral shift involves the move from one-time hardware sales to subscription-based security services. This model disrupts the conventional aftermarket parts channel, with OEMs and telematics service providers now offering features like remote vehicle immobilization for a recurring fee. This trend is most prominent within commercial fleet management in Europe and North America, where asset tracking and recovery are key performance indicators.
Vehicle Security System Market Segmentation
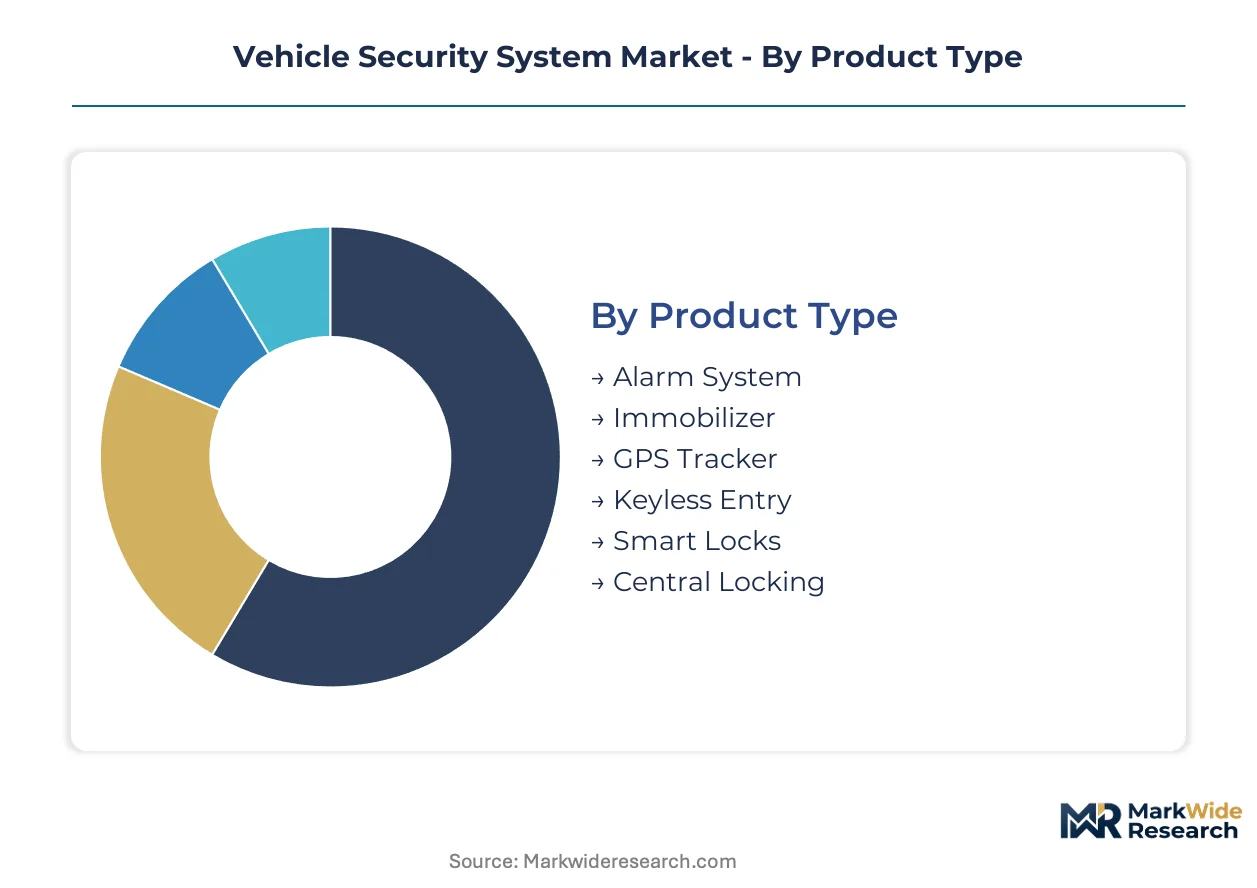
The vehicle security system market segments reflect diverse functional needs and regulatory pressures shaping product development. Understanding these distinctions reveals where innovation is concentrated and where established technologies maintain foundational volume. Market segmentation also highlights the varying demands across different vehicle types and end-user ecosystems.
Product Type:
Regulatory mandates, such as UNECE WP.29, significantly differentiate product types based on required compliance levels and cybersecurity features.
- Immobilizer:An electronic device prevents engine operation without an authenticated key or fob, often using RFID technology. Demand for factory-installed immobilizers concentrates in new vehicle production globally, driven by anti-theft regulations in Europe and China.
- GPS Tracker:These systems use satellite navigation to determine and track a vehicle's precise location, often combined with telematics. Commercial fleets in North America and Europe drive significant demand for asset protection and operational monitoring.
- Alarm System:Acoustic and visual alerts activate upon unauthorized entry or tampering.
- Keyless Entry:Allows vehicle access and ignition without a physical key, using remote frequency signals.
- Smart Locks:Integrates with vehicle systems for remote locking/unlocking via smartphone applications.
- Central Locking:Simultaneously locks or unlocks all vehicle doors from a single control point.
Immobilizer systems handle the majority of foundational volume throughput; GPS trackers are the fastest mover on share, particularly within commercial applications.
Technology:
Technology segmentation highlights the foundational sensing mechanisms and advanced authentication methods employed across various security applications.
- RFID:Radio-frequency identification uses electromagnetic fields to automatically identify and track tags attached to objects, fundamental for key fob authentication in immobilizers. Its application is widespread in factory-fitted security systems across all vehicle types.
- Biometric Recognition:This technology uses unique biological characteristics, such as fingerprints or facial patterns, for vehicle access and ignition authorization. Demand is expanding beyond luxury vehicles into commercial fleets for enhanced driver authentication and asset security.
- Infrared Sensors:Detect changes in temperature or motion within the vehicle cabin.
- Ultrasonic Sensors:Emit sound waves to detect intrusions into the vehicle interior.
- Radio Frequency:Utilized for remote keyless entry and central locking system communication.
- Magnetic Sensors:Detect unauthorized opening of doors, hoods, or trunks.
Maturity of technology plays a key role, with RFID systems forming the established backbone while biometric recognition technologies demonstrate the steepest expansion trajectory.
Application:
Application segments differentiate security system requirements based on vehicle ownership models and operational profiles, influencing feature sets and scale of deployment.
- Commercial Fleets:These applications involve high-value assets requiring advanced telematics, GPS tracking, and remote immobilization for theft prevention and operational efficiency. Operators across Europe and North America prioritize robust, integrated security solutions.
- Personal Vehicles:This segment represents the largest volume market for factory-installed security features like immobilizers and central locking systems. Consumer preferences in China and the United States influence the adoption of convenient keyless entry and smart lock technologies.
- Government Vehicles:Require specialized security for sensitive data protection and operational integrity.
- Rental Cars:Benefit from remote tracking and disabling features for asset management.
- Emergency Vehicles:Need reliable security that does not impede rapid access and deployment.
- Public Transport:Focuses on passenger safety and asset protection in high-usage environments.
The volume is dominated by personal vehicles, while commercial fleets exhibit higher growth in advanced, integrated security solutions due to asset value.
End User:
End user segments define the primary purchasers and integrators of vehicle security systems, reflecting distinct procurement channels and value chain positions.
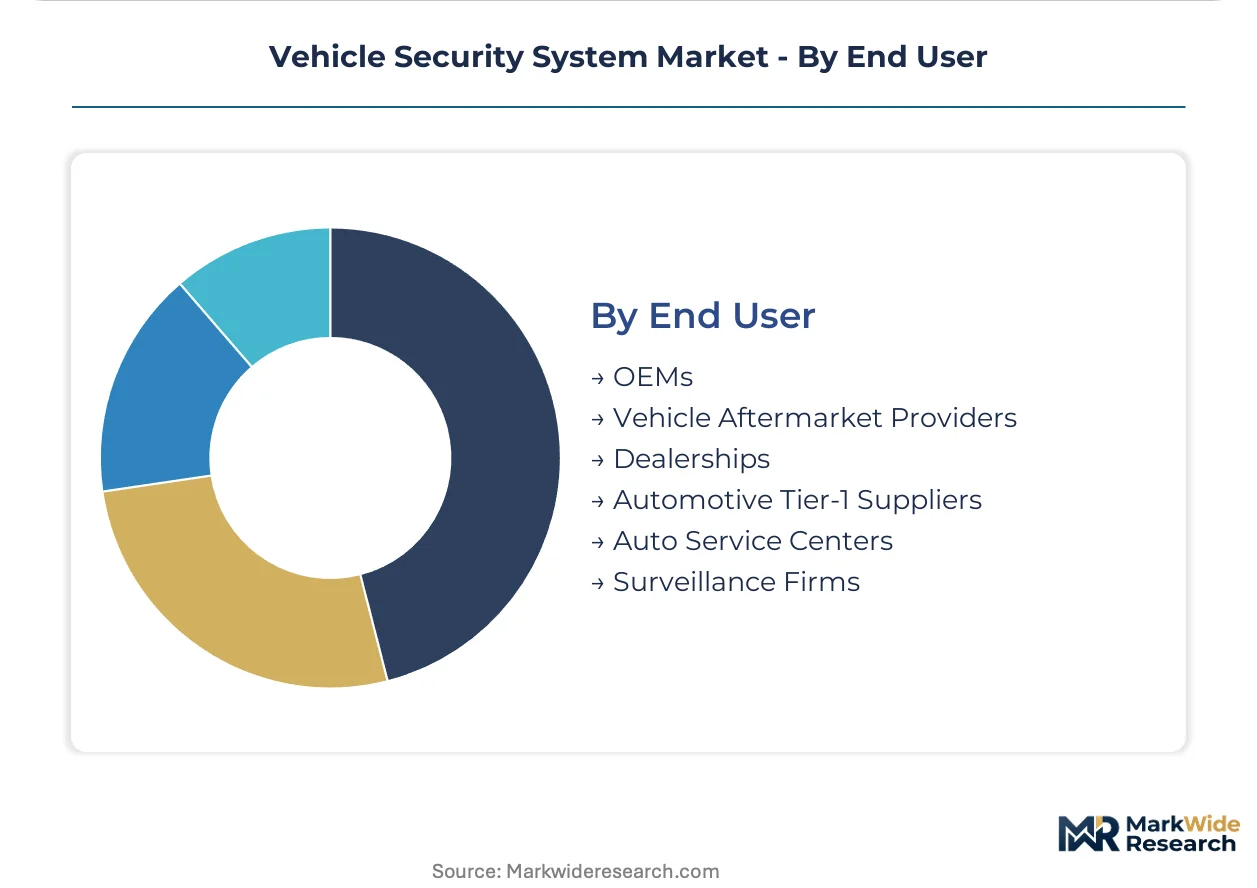
- OEMs:These entities integrate security systems directly into new vehicles during the manufacturing process, driven by regulatory compliance and consumer safety expectations. Their demand centers on foundational and advanced factory-fitted solutions.
- Vehicle Aftermarket Providers:These suppliers offer security enhancements and upgrades post-purchase, catering to legacy fleets and drivers seeking advanced features like GPS tracking or biometric access. This segment shows higher growth in specialized solutions for commercial assets.
- Dealerships:Primarily install optional security features or aftermarket solutions during vehicle sales.
- Automotive Tier-1 Suppliers:Develop and supply components and modules directly to OEMs.
- Auto Service Centers:Provide installation and maintenance services for security systems.
- Surveillance Firms:Utilize vehicle security data for monitoring and recovery services.
Profitability varies significantly, with OEMs driving volume-based procurement while aftermarket providers capture higher margins on specialized, value-added solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing power asymmetry defines the market for vehicle security systems, with high-volume manufacturing in China influencing component costs, while advanced regulatory demands in Europe drive premium solutions. This creates distinct market dynamics across major automotive production hubs. Demand for advanced features like biometric recognition and telematics varies significantly by region.
China
China's large-scale vehicle manufacturing and technology-forward policies stimulate demand for both foundational and advanced security systems. GB standards mandate specific anti-theft device performance, shaping market access for suppliers. Automotive technology clusters in Shanghai and Shenzhen concentrate research and development for connected vehicle security solutions.
Germany
Germany drives demand for sophisticated security modules in its premium vehicle segment and commercial fleets. The UNECE WP.29 regulations compel verifiable cybersecurity management systems for all new vehicles produced there. Automotive hubs like Stuttgart and Munich are centers for integrating these complex security architectures into vehicle platforms.
United States
United States personal vehicle owners and commercial fleet operators seek a blend of factory-installed and aftermarket security features. Federal Motor Vehicle Safety Standards influence foundational anti-theft device requirements. Detroit remains a key center for automotive innovation, focusing on integrating advanced driver assistance and security systems.
Japan
Japanese automakers prioritize integrated security within advanced automotive platforms, particularly for export markets. JIS standards guide the development of reliable and high-performance electronic components for vehicle security. Nagoya's automotive manufacturing region sees continuous investment in secure vehicle communication and control systems.
South Korea
South Korea exhibits strong demand for connected car security and biometric authentication technologies. National cybersecurity initiatives support the development of resilient automotive software and hardware. Automotive R&D centers in Seoul and Ulsan focus on next-generation vehicle access and data protection solutions.
Vehicle Security System Market Key Industry Players
Concentration sits with established automotive suppliers and semiconductor specialists who provide foundational components and integrated systems. The market features a tiered structure, from component manufacturers to full-system integrators. Strategic partnerships between hardware providers and software developers, alongside portfolio diversification into cybersecurity services, are common competitive moves.
Among key technology providers, NXP Semiconductors Inc. exemplifies specialization in core microcontrollers and secure elements. Robert Bosch GmbH represents comprehensive system integration, leveraging its extensive automotive expertise to deliver full vehicle security solutions. Continental AG occupies a broad position, offering a wide array of products from keyless entry to advanced driver monitoring systems.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Magna International Inc. |
| Continental AG |
| Autoliv Inc. |
| NXP Semiconductors Inc. |
| Robert Bosch GmbH |
| Aptiv plc |
| Veoneer AB |
| Denso Corporation |
| Others |
Cost & Logistics Intelligence
High-volume vehicle manufacturing economies of scale in China dictate component price floors, which influences global supply concentration for basic security modules. This dynamic shapes pricing power across the value chain, particularly for standardized hardware.
Pricing Analysis
Configured-to-order pricing for advanced security solutions, such as integrated telematics for commercial fleets, commands a premium over standard per-unit transactional pricing for foundational immobilizers. Price differentiation stems from the customization level required by OEMs and the after-sales service bundles offered by aftermarket providers. Pricing pressure stems from intense competition in the high-volume component segment, particularly for RFID chips. Personal vehicle OEMs are particularly price-sensitive for factory-installed basic features, while commercial fleets prioritize value-based pricing for advanced asset protection and operational monitoring.
Supply Chain Analysis
Just-in-time inventory strategies dominate for high-volume, standardized components supplied to OEMs, while aftermarket providers may maintain strategic stockpiles for specialized solutions. Geographic supply concentration primarily centers on China, Germany, and Japan for both semiconductor components and integrated systems. The industry relies on microcontrollers, secure elements, and various sensor components. Single-source vulnerability for specialized semiconductor components represents a structural supply chain risk. Distribution runs through direct channels to OEMs and a fragmented aftermarket network of distributors and service centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OEM consolidation increases buyer power for foundational security systems, while commercial fleet fragmentation creates diverse demand for advanced aftermarket solutions. This shift necessitates targeted strategies for market participants.
For Market Incumbents:
Consolidate component supply chains to mitigate single-source risks and deepen software integration capabilities. This addresses cybersecurity talent scarcity and regulatory shifts like UNECE WP.29, which demand full-lifecycle software management. Invest in advanced R&D for AI-powered threat detection to stay ahead of evolving cyber threats. Secure key partnerships with cloud service providers to enhance remote management and data analytics offerings.
For New Entrants and Emerging Players:
Differentiate on advanced biometric authentication or V2X security solutions, targeting commercial fleets in emerging economies. This offers a white-space opportunity where legacy systems are prevalent, and a go-to-market angle through telematics service providers. Focus on agile software development and rapid deployment cycles to capture niche markets. Build strong intellectual property around novel encryption and authentication protocols.
For Investors and Strategic Acquirers:
Mid-cycle technology positioning favors specialized software developers with verifiable cybersecurity expertise. Long-term viability rests on firms capable of managing secure over-the-air updates and compliance with evolving regulations like UNECE WP.29. Acquirers should target companies with strong embedded software security platforms or unique sensor fusion capabilities. Watch for increasing M&A activity focused on embedded software security firms as an inflection indicator for market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Security Platform Development | Enhances remote management and lifecycle security for connected vehicles. |
| Biometric Authentication IP Acquisition | Expands advanced access control offerings beyond traditional key fobs. |
| Cybersecurity Talent Development Programs | Addresses the industry's critical shortage of specialized engineering expertise. |
| Global Regulatory Compliance Certification | Ensures market access and competitive advantage in regulated automotive markets. |
| Telematics Integration Partnerships | Boosts advanced tracking and remote immobilization services for commercial fleets. |
Research Approach
Findings reconcile primary fieldwork against secondary review of UNECE WP.29 documentation, GB standards, Federal Motor Vehicle Safety Standards, and automotive industry reports. Primary interviews included automotive Tier-1 procurement leads, OEM platform engineers, commercial fleet managers, and cybersecurity architects. This approach leverages both bottom-up and top-down triangulation for robust data validation.
Segmentation dimensions modeled include product type, technology, application, end user, and regional regulatory frameworks across the analysis window. Compound annual growth rates were derived from historical data, an assessment of market drivers, and expert projections. Key industry-specific forecast inputs included vehicle production volumes and cybersecurity regulation adoption rates.
Decision-makers should treat outputs as directional under assumptions of regulatory stability and consistent technological evolution; material deviation would warrant model refresh. Forecasts reflect assumptions concerning market dynamics and competitive shifts. Revision becomes warranted when unforeseen geopolitical shifts or rapid shifts in cyberattack sophistication cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Home Control and Security Systems Market
Access Control Systems
Global Automated Border Control Market
Access Control Systems
Global Home Security Systems Market
Access Control Systems
Mechanical Locks Market
Access Control Systems
China Access Control Market
Access Control Systems
Latin America Pin-Based Access Control Market
Access Control Systems
GCC Home Security Systems Market
Access Control Systems
Latin America Card-Based Access Control Market
Access Control Systems
Keyless Entry System Market
Access Control Systems
Building Access Control Security Market
Access Control Systems
Europe Access Control Software Market
Access Control Systems
US Access Control Market
Access Control Systems
Asia-Pacific Proximity Access Control Market
Access Control Systems
Global Smart Lock Market
Access Control Systems
North America Access Control Market
Access Control Systems
Automated Smart Locker System Market