
 Noise Monitoring System Market | 2026-2036
Noise Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Noise Monitoring System Market Outlook
Direct-to-municipality digital procurement is rewriting how noise monitoring contracts reach end users. Bruel & Kjaer leverages its decades-long calibration heritage to sustain premium positioning in permanent installation networks. Svantek competes aggressively on portable instrument portability, while Acoem Group anchors its revenue in environmental compliance services bundled with hardware.
A noise monitoring system comprises calibrated microphones, signal processing units, and data-logging infrastructure designed to capture, analyze, and report acoustic pressure levels across defined frequency ranges, typically from 20 Hz to 20 kHz with precision within ±1 dB. These systems serve industrial safety managers, urban planners, and environmental regulators who require continuous or periodic verification that ambient or occupational noise remains within legally prescribed thresholds. Wireless noise monitors are capturing the fastest expansion as battery life and mesh networking protocols eliminate cabling costs in remote construction and rail corridors. Environmental monitoring applications command the deepest installed base, though event management deployments are narrowing the gap as temporary venue permitting tightens across jurisdictions. Government agencies represent the most price-sensitive buyer class, pressuring vendors toward subscription-based cloud deployment models.
EPA noise level criteria and OSHA occupational exposure limits shape product design specifications in the United States, while the EU Environmental Noise Directive forces member states toward standardized measurement protocols and public reporting infrastructure. Japan's METI energy efficiency guidelines indirectly influence power consumption benchmarks for outdoor monitoring stations. Stakeholders must weigh whether to prioritize sensor accuracy certifications or platform interoperability as procurement criteria diverge across regulatory regimes.
Market Dynamics
Wireless mesh networking and cloud-native architectures are compressing deployment timelines for municipal noise monitoring networks, forcing vendors to reprice hardware-software bundles around recurring SaaS metrics rather than capital expenditure cycles.
Growth Catalysts
- EU Environmental Noise Directive:Member states must deploy standardized measurement infrastructure and public reporting portals, mandating permanent installation systems in urban agglomerations.
- Rail corridor expansion:Battery-powered wireless monitors eliminate trenching costs along electrified track beds, accelerating adoption by national railway operators.
- MEMS microphone advances:Silicon-based acoustic sensors reduce calibration drift and unit cost, enabling dense sensor grids for smart city pilots.
Market Restraints
- Precision-grade microphone supply:German and Danish specialty manufacturers control 1/2-inch measurement microphone output, creating input bottlenecks for tier-two system integrators.
- OSHA calibration mandates:Annual recertification requirements for occupational monitors inflate total cost of ownership beyond initial hardware purchase.
- Smartphone decibel apps:Free consumer-grade alternatives satisfy non-regulatory users, eroding demand for entry-level handheld instruments.
Strategic Opportunities
- Japanese municipal cloud migration:METI efficiency guidelines favor centralized data platforms, opening subscription revenue for vendors with compliant architectures.
- Convergence of noise and air quality monitoring:Combined environmental stations reduce site permit complexity and maintenance overhead for urban deployment.
- Event management permitting:Temporary venue noise caps in Australia and Canada create rental demand for rapid-deployment trailer systems.
Industry Challenges
- Acoustic calibration technician scarcity:ISO 17025-accredited personnel shortages delay field verification schedules and contract handovers.
- Legacy SCADA integration:Industrial buyers require protocol translation layers to feed noise data into existing plant control systems, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Noise Monitoring System Market |
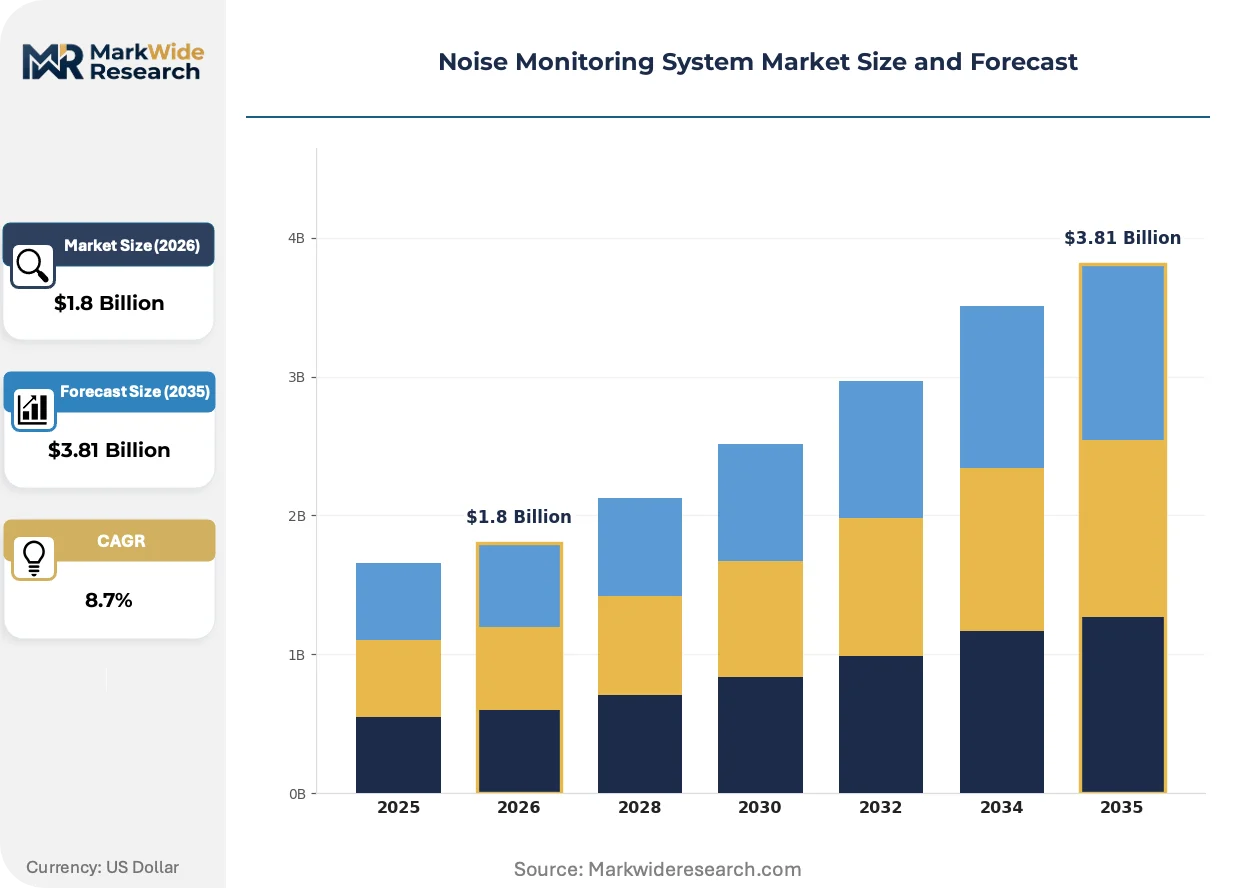
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Sound Level Meters, Distributed Acoustic Sensors, Wireless Noise Monitors, IoT Devices Application: Environmental Monitoring, Industrial Safety, Urban Planning, Event Management End User: Government Agencies, Construction Firms, Educational Institutions, Environmental Organizations Deployment: Cloud-Based, On-Premise, Hybrid, Mobile Solutions |
| Companies Covered | Bruel & Kjaer, RION Co. Ltd., 3M, Cirrus Research Plc., Svantek, Acoem Group, Larson Davis, Pulsar Instruments Plc, Norsonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Noise Monitoring System Market Strategic Shifts
Edge computing and AI inference at the sensor level are redefining what constitutes a noise event, shifting value capture from hardware accuracy to real-time classification and automated compliance reporting.
Edge AI processors embedded in outdoor monitoring stations is digitizing acoustic pattern recognition, enabling on-device identification of aircraft overflight versus construction impulsive noise without cloud round-trips. German airport authorities are deploying these units around Frankfurt and Munich perimeters, compressing incident response from hours to minutes. The shift is digitizing how environmental agencies purchase systems, prioritizing inference throughput over raw microphone specifications.
REACH restrictions on persistent organic pollutants are forcing microphone membrane suppliers to reformulate electret materials, triggering recertification cycles for IEC 61672 Class 1 instruments. Manufacturers must resubmit pattern approvals to national metrology institutes, delaying new product launches by 8-14 months. Environmental monitoring OEMs with pre-validated alternative materials are capturing specification wins from competitors caught in regulatory lag.
Municipal procurement offices are consolidating noise monitoring into broader environmental IoT tenders, bundling acoustic sensors with air quality and meteorological stations under single-vehicle contracts. This aggregation is displacing standalone noise specialists who lack multi-parameter portfolios. Japanese prefectural governments and Australian state environmental agencies have issued the first consolidated RFPs, with evaluation criteria weighting platform interoperability above sensor precision.
Noise Monitoring System Market Segmentation
Noise monitoring procurement splits sharply between regulatory compliance mandates and operational risk management. Vendors must architect product lines that span precision-grade certification requirements for government buyers alongside ruggedized portability for construction and event deployment.
Technology:
Cost tier structures the technology landscape, separating precision-calibrated laboratory instruments from mass-deployable sensor networks.
- Sound Level Meters:Handheld or tripod-mounted instruments with IEC 61672 Class 1 or Class 2 certification for regulatory-grade measurement. Environmental agencies in Germany and Japan specify these for stationary compliance verification. Precision microphone supply bottlenecks from Danish and German specialty manufacturers inflate procurement timelines for certified units.
- Wireless Noise Monitors:Battery-powered nodes with mesh networking protocols eliminating trenching costs along rail corridors and construction perimeters. Railway operators in Japan and national infrastructure agencies in Germany deploy these for continuous corridor monitoring. Battery chemistry advances and solar harvesting extend unattended operation beyond 18 months.
- Distributed Acoustic Sensors:Fiber-optic cable-based systems capturing acoustic signatures along linear infrastructure. Pipeline operators and perimeter security buyers in the United States deploy these for intrusion detection and leak monitoring.
- IoT Devices:MEMS microphone-based compact units for dense urban grids and smart city pilots. Municipal buyers in Japan pilot these for neighborhood-scale noise mapping at unit costs below precision-grade alternatives.
Sound Level Meters command the established base. The steepest expansion runs through Wireless Noise Monitors.
Application:
Application scope determines sensor density, calibration frequency, and integration complexity across buyer workflows.
- Environmental Monitoring:Continuous ambient noise assessment for regulatory compliance and public health protection. Government agencies in Germany deploy permanent station networks per EU Environmental Noise Directive mandates. Public reporting portal requirements force integration with municipal data infrastructure.
- Industrial Safety:Occupational noise exposure tracking for OSHA compliance and hearing conservation programs. Manufacturing facilities and construction sites in the United States require annual recertification cycles that inflate total cost of ownership. Integration with existing plant SCADA systems demands protocol translation layers.
- Urban Planning:Strategic noise mapping for zoning decisions and infrastructure impact assessment. City planning departments in Japan and Australia combine acoustic data with air quality and meteorological parameters in consolidated IoT tenders.
- Event Management:Temporary noise cap enforcement for concerts, festivals, and sporting venues. Permit authorities in Australia and Canada specify rapid-deployment trailer systems with real-time alerting. Rental revenue models emerge as procurement shifts from capital purchase to operational expenditure.
Environmental Monitoring commands the established base. The steepest expansion runs through Event Management.
End User:
Customer type dictates pricing tolerance, procurement cycle length, and service bundling requirements.
- Government Agencies:Municipal, state, and national environmental regulators with standardized procurement protocols and public reporting mandates. Price sensitivity pressures vendors toward subscription-based cloud deployment models. Japanese prefectural governments and German federal environmental agencies represent concentrated demand.
- Construction Firms:Project-based buyers requiring temporary monitoring for permit compliance and community relations. German construction firms expand procurement of permanent installation systems ahead of stricter EU environmental noise directives. Site mobility demands favor wireless and solar-powered configurations.
- Educational Institutions:Universities and research centers conducting acoustic studies and campus environmental management. Limited capital budgets favor shared regional facility models and rental access to precision instrumentation.
- Environmental Organizations:Non-governmental advocacy groups conducting independent monitoring and public interest litigation. Low-cost IoT alternatives and smartphone-based crowdsourcing erode demand for certified handheld instruments in this segment.
Government Agencies command the established base. The steepest expansion runs through Construction Firms.
Deployment:
Deployment architecture determines data sovereignty, latency requirements, and recurring revenue potential for vendors.
- Cloud-Based:Centralized data platforms with browser-based dashboards and API access for third-party integration. Municipal buyers in Japan capture disproportionate interest per METI energy efficiency guidelines favoring centralized infrastructure. Subscription pricing compresses upfront capital requirements.
- On-Premise:Local server installations with air-gapped security for sensitive industrial and defense applications. Data sovereignty requirements in Germany and critical infrastructure operators in the United States specify this architecture despite higher implementation cost.
- Hybrid:Edge processing with selective cloud synchronization for bandwidth-constrained or intermittently connected sites. Rail corridor and remote construction deployments balance real-time alerting with periodic data consolidation.
- Mobile Solutions:Smartphone and tablet-based applications for rapid assessment and citizen science participation. Free consumer-grade alternatives satisfy non-regulatory users, eroding addressable market for entry-level handheld instruments.
On-Premise commands the established base. The steepest expansion runs through Cloud-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German municipalities extract pricing premiums for permanent installation networks while Japanese buyers compress vendor margins through centralized cloud procurement. This asymmetry reflects divergent regulatory enforcement timelines and data sovereignty requirements across the two markets.
United States
Rail corridor electrification and airport perimeter expansion drive wireless monitor deployment along the Northeast Corridor and California high-speed rail routes. EPA noise level criteria and OSHA occupational exposure limits shape Class 1 precision requirements for environmental and industrial buyers. Dallas-Fort Worth International Airport maintains one of the densest edge-AI perimeter networks for real-time aircraft noise classification.
Germany
Construction firms accelerate permanent system procurement ahead of stricter EU Environmental Noise Directive implementation deadlines. REACH restrictions on electret membrane materials force IEC 61672 recertification cycles, advantaging OEMs with pre-validated alternatives. The Frankfurt-Rhine-Main metropolitan region hosts the continent's most extensive municipal noise mapping infrastructure with standardized public reporting portals.
Japan
METI energy efficiency guidelines redirect prefectural procurement toward centralized cloud platforms with browser-based dashboards. Municipal buyers in Tokyo, Osaka, and Nagoya issue consolidated environmental IoT tenders bundling acoustic, air quality, and meteorological sensors. Kanto region pilots deploy MEMS-based dense sensor grids at unit costs below precision-grade alternatives.
Australia
Event management permitting tightens across New South Wales and Victoria, creating rental demand for rapid-deployment trailer systems with real-time alerting. State environmental agencies mirror Japanese procurement patterns with consolidated multi-parameter station tenders. Sydney and Melbourne festival circuits now require temporary noise cap verification as a standard permit condition.
United Kingdom
Post-Brexit regulatory divergence creates dual certification burdens for vendors serving both UK and EU markets. Industrial safety managers in the Midlands manufacturing belt face annual OSHA-equivalent recertification mandates inflating total cost of ownership. London's expanded Ultra Low Emission Zone boundaries incorporate noise monitoring into integrated environmental enforcement infrastructure.
Noise Monitoring System Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying precision microphones and calibration services. The vendor base separates into three distinct strata: heritage acoustics houses with decades-long calibration legacies, industrial instrumentation conglomerates leveraging cross-product distribution, and emerging IoT-native players attacking the dense urban sensor grid segment. Consolidation pressure intensifies as municipal procurement aggregates noise monitoring into broader environmental IoT contracts, disadvantaging standalone specialists. Dominant competitive moves include backward integration into MEMS microphone supply and strategic partnerships with cloud infrastructure providers.
Within the heritage calibration tier, Bruel & Kjaer and Norsonic occupy positions sustained by IEC 61672 Class 1 certification authority and national metrology institute relationships. Svantek exemplifies the portability-focused archetype competing on instrument ruggedness and field deployment speed. Acoem Group anchors the environmental compliance services model, bundling hardware with regulatory reporting and maintenance contracts. Japanese precision instrument specialists including RION Co. Ltd. leverage domestic METI relationships and JIS standard influence to capture prefectural cloud migration contracts.
| Leading Market Players |
|---|
| Bruel & Kjaer |
| RION Co. Ltd. |
| 3M |
| Cirrus Research Plc. |
| Svantek |
| Acoem Group |
| Larson Davis |
| Pulsar Instruments Plc |
| Norsonic |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Danish and German precision microphone manufacturing tightens input availability for tier-two system integrators, compressing margins on Class 1 certified instruments while pushing buyers toward extended lead-time premiums or downgraded Class 2 alternatives.
Pricing Analysis
Configured-to-order pricing for permanent installation networks commands spreads of 40-60 percent above standard portable instrument SKUs, reflecting site-specific calibration protocols and integration engineering. Three-tier pricing structure across premium, standard, and economy levels stratifies by IEC 61672 certification class, with Class 1 units capturing municipal procurement in Germany and Japan while Class 2 alternatives satisfy construction firm budgets. Pricing pressure stems from municipal buyers migrating toward subscription SaaS models that front-load vendor costs against deferred recurring revenue. Government agencies exhibit the highest price sensitivity, forcing margin compression through consolidated environmental IoT tenders.
Supply Chain Analysis
Tariff exposure between the United States and Chinese MEMS component suppliers dominates supply chain risk planning for IoT-native monitor manufacturers. Precision microphone production concentrates in Denmark and Germany, with electret membrane materials drawing from Japanese specialty chemical suppliers. Silicon wafer supply for MEMS sensors rests on Taiwanese foundry capacity. Single-source vulnerability in 1/2-inch measurement microphone capsules creates input bottlenecks during IEC 61672 recertification cycles. Distribution runs through authorized calibration laboratories and direct municipal procurement channels, with cloud platform vendors disintermediating traditional instrumentation distributors in Japanese prefectural markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by delayed EU Environmental Noise Directive implementation timelines, with procurement acceleration expected as member state deadlines crystallize compliance investment.
For Market Incumbents: Harden calibration service networks against emerging IoT-native competitors by securing ISO 17025-accredited technician pipelines in German and Japanese markets. Backward integration into MEMS microphone supply insulates margin pressure from Danish-German precision capsule bottlenecks. Defensive patenting around edge-AI noise classification algorithms preserves premium positioning in airport perimeter and rail corridor deployments. For New Entrants and Emerging Players: Australian event management permitting creates the most penetrable white-space for rapid-deployment trailer systems with rental revenue models. Municipal cloud procurement in Japanese prefectures offers entry through METI-compliant platform architectures bypassing heritage calibration incumbents. Target construction firm procurement in Germany ahead of stricter EU directive enforcement, emphasizing wireless solar-powered configurations against permanent installation alternatives. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among environmental compliance service bundlers with maintenance-contract anchoring. Five-to-ten year viability favors platform integrators spanning multi-parameter environmental IoT rather than standalone noise specialists facing consolidation displacement. Monitor consolidated tender issuance in Australian state agencies and Japanese prefectural governments as inflection signals for platform-scale M&A activity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Supply | Captive silicon microphone production insulates margin pressure from Taiwanese foundry bottlenecks. |
| Cloud Platform Certification | METI-compliant centralized architectures unlock Japanese prefectural subscription revenue streams. |
| Edge-AI Inference Investment | On-device noise classification compresses incident response times for Frankfurt and Munich airport authorities. |
| Multi-Parameter Station Development | Combined acoustic-air quality-meteorological units satisfy Australian consolidated IoT tender requirements. |
| Calibration Service Network Expansion | ISO 17025-accredited technician density accelerates contract handovers in German municipal markets. |
Study Parameters
The analysis maps sound level meters, wireless noise monitors, distributed acoustic sensors, and IoT device sub-sectors, each validated through environmental agency procurement officers, industrial safety managers, municipal IT directors, and calibration laboratory technicians. Primary interviews triangulated against EPA noise criteria documentation, EU Environmental Noise Directive implementation schedules, METI efficiency guideline filings, and OSHA occupational exposure limit databases. Bottom-up unit deployment estimates cross-checked with top-down municipal budget appropriations across the analysis window.
Assumptions held regulatory enforcement timelines and battery chemistry improvement curves fixed while varying rail corridor electrification pace and smart city pilot funding levels. Segmentation models incorporated technology tier, application mandate, end-user procurement authority, and deployment architecture dimensions. CAGRs derived from slope analysis of annual procurement volumes against compliance deadline proximity, with MEMS cost curves and cloud infrastructure pricing as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by industrial instrumentation conglomerates or platform acquisitions by hyperscale cloud providers would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Safety
Environmental Health and Safety Market
Environmental Safety
Europe Pest Control Services Market
Environmental Safety
US Home Decontamination Services Market
Environmental Safety
Air Audit Equipment Market
Environmental Safety
Global Air Sampling Pumps Market
Environmental Safety
Latin America Hazardous Waste Handling Automation Market
Environmental Safety
Europe Process Safety Services Market
Environmental Safety
China Home Decontamination Services Market
Environmental Safety
Noise Control System Market
Environmental Safety
Environment Health & Safety Market
Environmental Safety
UV Air Sanitizer Market
Environmental Safety
Asia-Pacific Rockfall Radar Market
Environmental Safety
Industrial Noise Control Market
Environmental Safety
Europe Hazardous Waste Handling Automation Market
Environmental Safety
North America Rockfall Radar Market
Environmental Safety
Germany Environment Health & Safety Market