
 Latin America Hazardous Waste Handling Automation Market | 2026-2036
Latin America Hazardous Waste Handling Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Hazardous Waste Handling Automation Market Foresight
Aftermarket service revenue for automated waste handling systems is tilting toward predictive maintenance contracts and remote diagnostics platforms. Konecranes PLC leverages its crane automation heritage to anchor port and industrial waste transfer installations across Brazilian coastal zones. Veolia Argentina sustains integrated service contracts that bundle equipment with long-term operation, competing against pure hardware vendors. Clean Harbors Inc specializes in North American-derived remediation protocols that it extends into Latin American chemical plant retrofits.
Latin America hazardous waste handling automation encompasses electromechanical systems engineered to manipulate, transport, process, and neutralize toxic, corrosive, flammable, or reactive waste streams with minimal human contact, typically operating within temperature-controlled enclosures rated for aggressive chemical environments and pressure differentials that prevent fugitive emissions. The primary purpose centers on eliminating worker exposure to carcinogenic and mutagenic substances while ensuring chain-of-custody traceability from generation through final disposal. Robotic Systems dominate current capital deployment due to their adaptability for drum handling, tank cleaning, and sampling operations in confined spaces. IoT Integration represents the fastest-expanding technology layer as facilities deploy connected sensors for real-time leachate monitoring and equipment health tracking. Chemical Plants constitute the most concentrated end-user segment given their generation of reactive byproducts and their capital capacity for integrated automation retrofits.
Brazil's ANA water agency and CONAMA environmental resolutions shape effluent and residue handling standards that directly mandate containment automation for Class I hazardous generators. Argentina's Secretariat of Environment and Sustainable Development enforces cradle-to-grave tracking that elevates demand for sensor-linked treatment units with audit-ready data logging. Mexico's PROFEPA inspection regime accelerates compliance-driven replacement of manual handling infrastructure in border maquiladora chemical operations. Stakeholders must weigh the trade-off between imported European-certified systems and emerging local assembly capacity when configuring procurement strategy for multi-site deployments.
Market Dynamics
CONAMA resolutions mandating Class I hazardous generator containment automation are compressing deployment timelines across Brazil's chemical corridor, forcing capital allocation toward sensor-integrated drum handling systems before legacy infrastructure reaches end-of-life.
Growth Catalysts
- ANA effluent standards:Brazil's water agency mandates real-time leachate monitoring, compelling petrochemical facilities to retrofit enclosed conveyor networks with IoT-linked sensors.
- Reactive byproduct generation:Chemical plants in São Paulo state generate concentrated hazardous streams that require robotic tank cleaning and sampling operations in confined spaces.
- Argentina's cradle-to-grave tracking:The Secretariat of Environment and Sustainable Development enforces audit-ready data logging, elevating demand for automated treatment units with embedded chain-of-custody documentation.
Market Restraints
- European-certified system dependency:Local assembly capacity remains nascent, forcing buyers to absorb import tariffs and extended lead times for pressure-rated enclosures.
- Specialized alloy input volatility:Hastelloy and titanium components for corrosive waste handling face price swings tied to mining supply concentration in non-regional geographies.
- PROFEPA inspection friction:Mexico's enforcement regime creates compliance uncertainty that delays capital commitment for border maquiladora automation retrofits.
Strategic Opportunities
- Remote diagnostics convergence:Predictive maintenance platforms combining crane automation heritage with waste transfer applications are opening service revenue streams in Brazilian coastal zones.
- Integrated service bundling:Long-term operation contracts that merge equipment provision with ongoing management are displacing pure hardware sales in Argentina's federal jurisdiction.
- Chilean mining waste expansion:Copper and lithium extraction tailings present underpenetrated demand for autonomous neutralization systems in the Atacama industrial corridor.
Industry Challenges
- Pressure-rated welding certification:ASME and NR-13 qualified technicians for aggressive chemical environment enclosures face acute scarcity across the Mercosur labor pool.
- Legacy manual infrastructure integration:Retrofitting enclosed conveyor systems into existing drum handling workflows requires custom engineering that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Hazardous Waste Handling Automation Market |
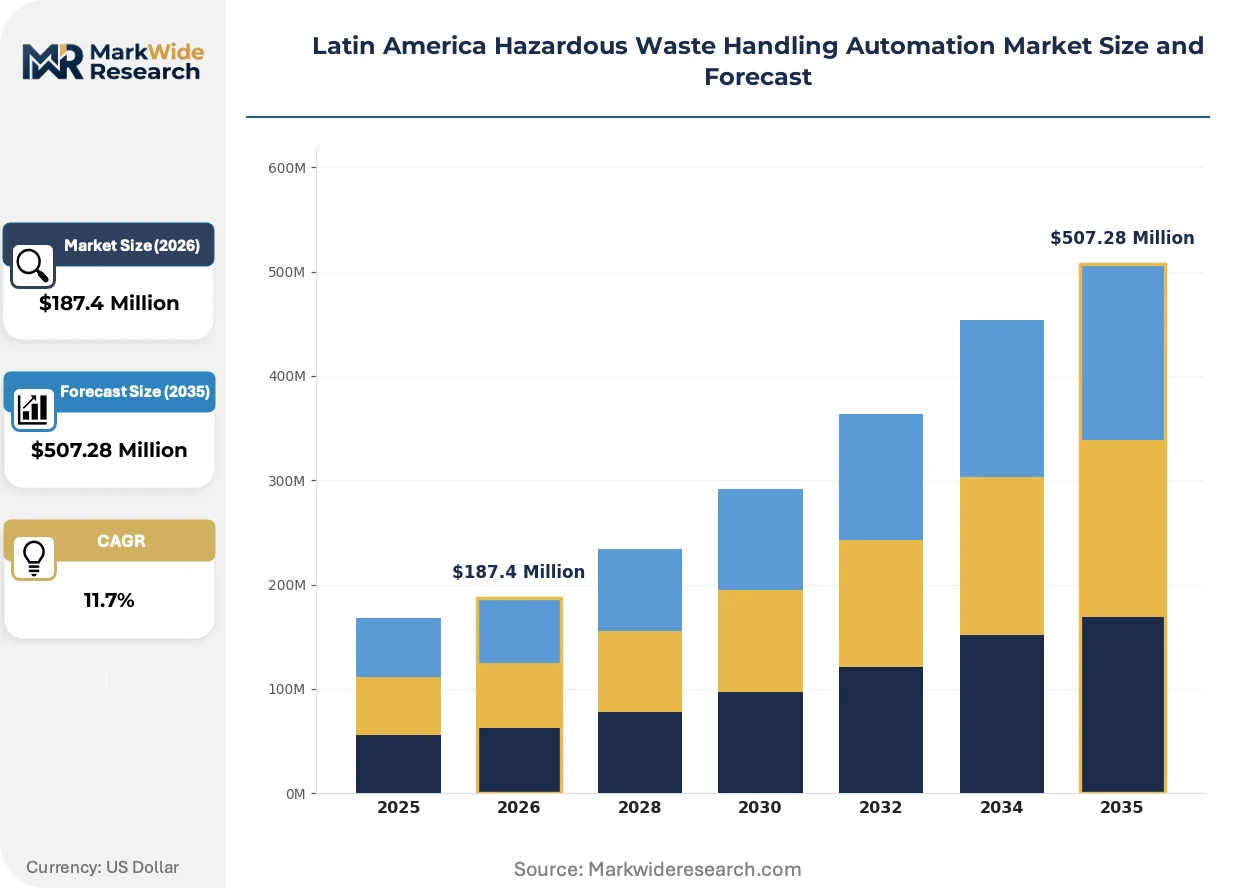
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Systems, Conveyor Systems, Sorting Equipment, Treatment Units Technology: AI-Based Solutions, IoT Integration, Automation Software, Sensor Technology Installation Type: On-Site Solutions, Remote Operations, Custom Installations, Bulk Installations End User: Manufacturing Facilities, Municipal Waste Sites, Chemical Plants, Research Labs |
| Companies Covered | PaR Systems Inc, Konecranes PLC, DX Engineering, Floatograph, Veolia Argentina, Estre Ambiental, Solví Participações, Clean Harbors Inc, Konecranes Oyj, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Hazardous Waste Handling Automation Market Shifts & Advancements
Automation architecture is pivoting from fixed electromechanical installations toward adaptive robotic platforms capable of reconfiguration across multiple waste stream chemistries without line shutdowns.
Collaborative robotic arms with force-torque sensing and chemical-resistant jacketing are rendering obsolete fixed-gantry drum handling systems in Brazilian petrochemical complexes. Facilities in the São Paulo industrial corridor are deploying these units for tank cleaning and sampling operations. The shift is compressing capital recovery timelines by enabling single-robot deployment across heterogeneous waste classes.
Argentina's updated federal hazardous waste law tightens handling protocols for carcinogenic and mutagenic substances, mandating pressure differential containment that prevents fugitive emissions. Chemical plant operators must demonstrate real-time environmental boundary monitoring to maintain operating licenses. The regulatory pressure is accelerating sensor-linked treatment unit procurement ahead of scheduled capital cycles.
Service unbundling is fragmenting traditional equipment supply relationships in Latin American hazardous waste handling. End-users in Mexico's border maquiladora operations are separating hardware acquisition from predictive maintenance and remote diagnostics, creating openings for specialized service platforms. This behavioral shift is most pronounced among multi-site chemical generators seeking operational continuity guarantees without captive technical staff.
Latin America Hazardous Waste Handling Automation Market Segmentation
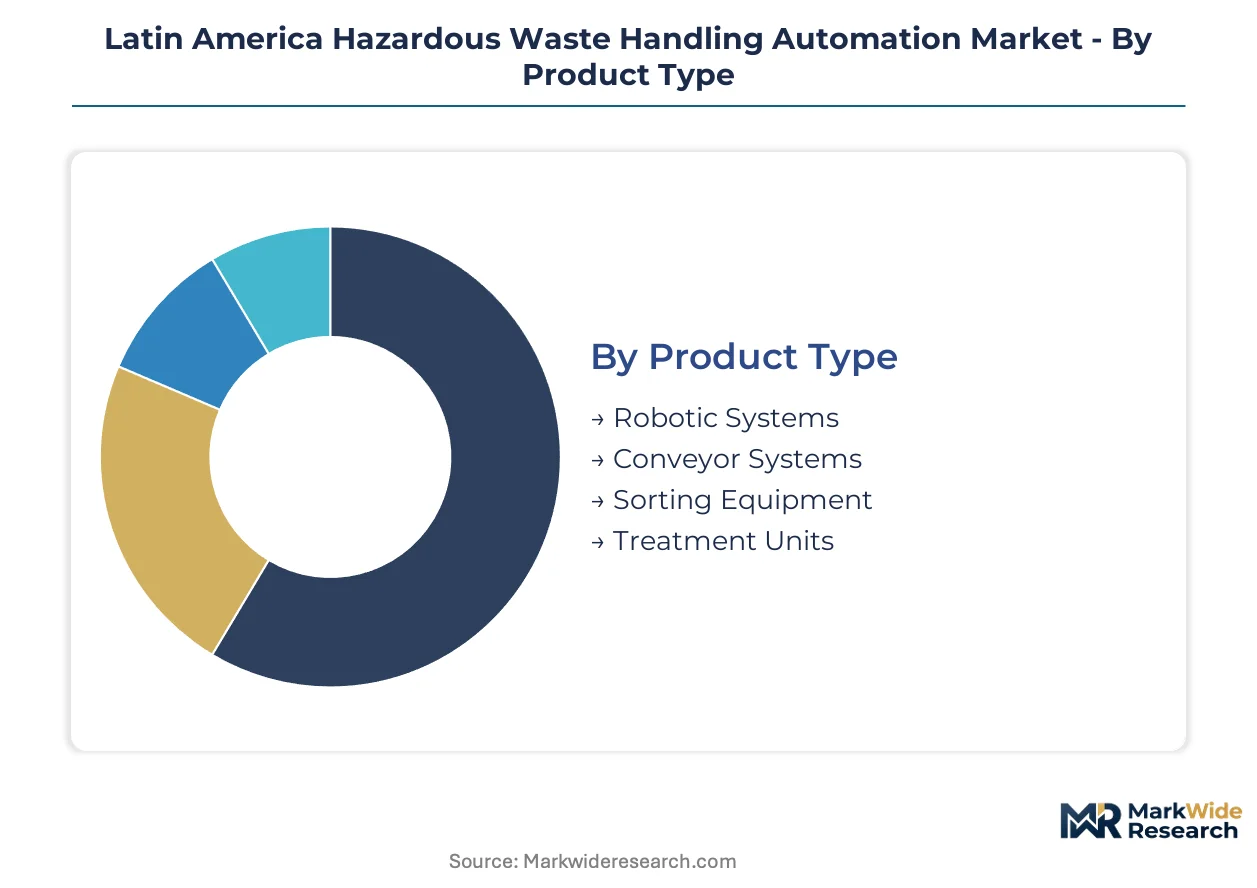
Segmentation reveals how hazardous waste automation deploys across distinct operational contexts in Latin America. Each dimension—product hardware, intelligence layer, deployment mode, and facility type—carries unique regulatory and technical imperatives that shape procurement patterns.
Product Type:
The use-case spectrum spans precision manipulation to continuous material flow, with each product category matching specific waste stream characteristics and enclosure requirements.
- Robotic Systems:Articulated arms with force-torque sensing and chemical-resistant jacketing execute drum handling, tank cleaning, and confined-space sampling. Brazilian petrochemical complexes in São Paulo state deploy these units for heterogeneous waste classes, compressing capital recovery through multi-application flexibility.
- Conveyor Systems:Enclosed, pressure-differential belt networks transport bulk hazardous materials while preventing fugitive emissions. ANA effluent standards mandate IoT-linked leachate monitoring, driving retrofit demand across Class I generator facilities.
- Sorting Equipment:Automated optical and density-based separators classify mixed hazardous streams by chemical compatibility. Argentina's cradle-to-grave tracking requirements elevate sensor-integrated sorting for audit-ready waste characterization.
- Treatment Units:Self-contained neutralization and stabilization systems process reactive byproducts at point of generation. Chemical plants favor these for integrated retrofits that eliminate external transport risks.
The dominant share belongs to Robotic Systems, while Treatment Units are closing the gap fastest.
Technology:
Intelligence layers differentiate systems by data depth and decision autonomy, with cost tiers separating experimental deployments from production-scale installations.
- AI-Based Solutions:Machine learning models optimize waste stream classification and predictive equipment scheduling. Early adoption concentrates in Brazilian coastal zones where Konecranes PLC integrates crane automation heritage with waste transfer intelligence.
- IoT Integration:Connected sensor networks enable real-time leachate monitoring and equipment health tracking. This layer expands most quickly as CONAMA resolutions compress deployment timelines for environmental boundary monitoring.
- Automation Software:Control platforms orchestrate multi-system workflows and generate chain-of-custody documentation. Argentina's federal hazardous waste law tightens audit requirements, elevating demand for embedded compliance logging.
- Sensor Technology:Chemical-specific detectors and pressure differential monitors ensure enclosure integrity. Hastelloy and titanium component volatility constrains price predictability for corrosive environment specifications.
IoT Integration commands the steepest expansion trajectory, though AI-Based Solutions retain premium pricing power.
Installation Type:
Deployment modes reflect customer type and capital cycle positioning, from integrated greenfield builds to reactive compliance retrofits.
- On-Site Solutions:Permanently installed automation infrastructure tailored to facility-specific waste profiles. Chemical plants with concentrated reactive byproduct generation favor this mode for integrated control.
- Remote Operations:Centrally monitored, geographically distributed equipment with minimal local technical staffing. Service unbundling trends in Mexico's border maquiladora operations accelerate this model.
- Custom Installations:Engineering-intensive retrofits adapting enclosed systems to legacy manual workflows. NR-13 qualified technician scarcity across Mercosur extends project timelines for pressure-rated welding.
- Bulk Installations:Standardized multi-unit deployments across corporate facility portfolios. Procurement strategy weighs European-certified system dependency against emerging local assembly capacity.
On-Site Solutions maintain the largest installed base, yet Remote Operations is gaining share fastest among multi-site generators.
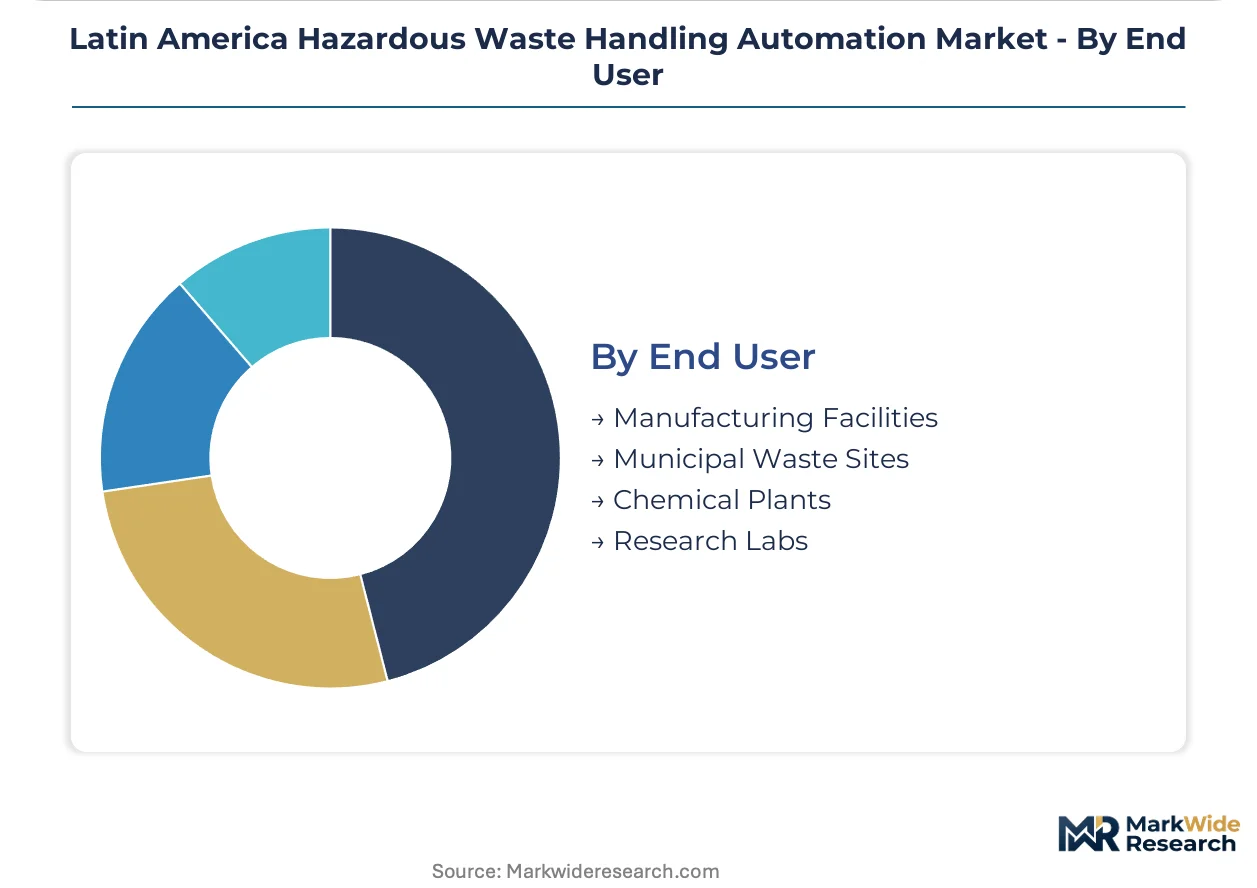
End User:
Facility categories separate by waste stream concentration, regulatory exposure, and capital capacity for automation retrofits.
- Chemical Plants:Primary generators of reactive, carcinogenic, and mutagenic byproducts with capital resources for integrated automation. São Paulo state industrial corridor concentrates demand for robotic tank cleaning and sampling operations.
- Manufacturing Facilities:Diverse industrial operations generating solvent, coating, and metalworking waste streams. PROFEPA inspection friction in Mexican border operations delays capital commitment for manual infrastructure replacement.
- Municipal Waste Sites:Public-sector handling of household hazardous waste and legacy contaminated materials. Budget constraints favor service bundling over pure hardware acquisition.
- Research Labs:Small-volume, high-toxicity waste generation with stringent chain-of-custody requirements. Specialized containment needs drive demand for adaptive robotic platforms.
Chemical Plants anchor category revenue, while Research Labs show the fastest adoption velocity per facility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil concentrates petrochemical automation demand while Argentina and Mexico diverge toward compliance-driven retrofits and service unbundling respectively. Chile's mining corridor presents emerging neutralization system opportunities distinct from the chemical plant focus elsewhere.
Brazil
Petrochemical complexes in São Paulo state drive robotic sorting arm deployment for heterogeneous waste stream handling. ANA effluent standards and CONAMA resolutions mandate real-time leachate monitoring and Class I generator containment automation. The São Paulo industrial corridor concentrates capital allocation toward sensor-integrated drum handling systems ahead of legacy infrastructure replacement cycles.
Mexico
Border maquiladora chemical operations face PROFEPA inspection friction that delays manual infrastructure replacement commitments. The enforcement regime creates compliance uncertainty while accelerating demand for remote operations models that minimize captive technical staffing. Northern border states concentrate service unbundling trends separating hardware acquisition from predictive maintenance contracts.
Argentina
Federal hazardous waste law updates tighten handling protocols for carcinogenic substances across chemical plant operators. The Secretariat of Environment and Sustainable Development enforces cradle-to-grave tracking with audit-ready data logging requirements. Buenos Aires province industrial zones elevate procurement of automated treatment units with embedded chain-of-custody documentation.
Chile
Copper and lithium extraction tailings generate underpenetrated demand for autonomous neutralization systems distinct from chemical plant applications. Mining waste streams in the Atacama industrial corridor require adaptive robotic platforms capable of reconfiguration across acidic leachate chemistries. Antofagasta region facilities present greenfield automation opportunities without legacy manual infrastructure integration constraints.
Latin America Hazardous Waste Handling Automation Market Competitive Landscape
Capability concentration sits with specialized automation integrators; scale advantage sits with diversified environmental service conglomerates. The market structures around three tiers: crane automation heritage players porting industrial lifting expertise into waste transfer, integrated service providers bundling equipment with long-term operation contracts, and North American remediation specialists extending protocols into chemical plant retrofits. Dominant competitive moves include strategic partnerships linking European-certified hardware with emerging local assembly capacity, and predictive maintenance platform rollouts converting capital sales into recurring service revenue.
Among crane automation heritage players, Konecranes PLC and Konecranes Oyj occupy positions leveraging industrial lifting expertise for port and waste transfer installations. Veolia Argentina exemplifies the integrated service archetype through bundled equipment-operation contracts competing against pure hardware vendors. Clean Harbors Inc represents North American-derived remediation protocol extension into Latin American chemical facility retrofits.
| Leading Market Players |
|---|
| PaR Systems Inc |
| Konecranes PLC |
| DX Engineering |
| Floatograph |
| Veolia Argentina |
| Estre Ambiental |
| Solví Participações |
| Clean Harbors Inc |
| Konecranes Oyj |
| Others |
Supply & Pricing Matrix
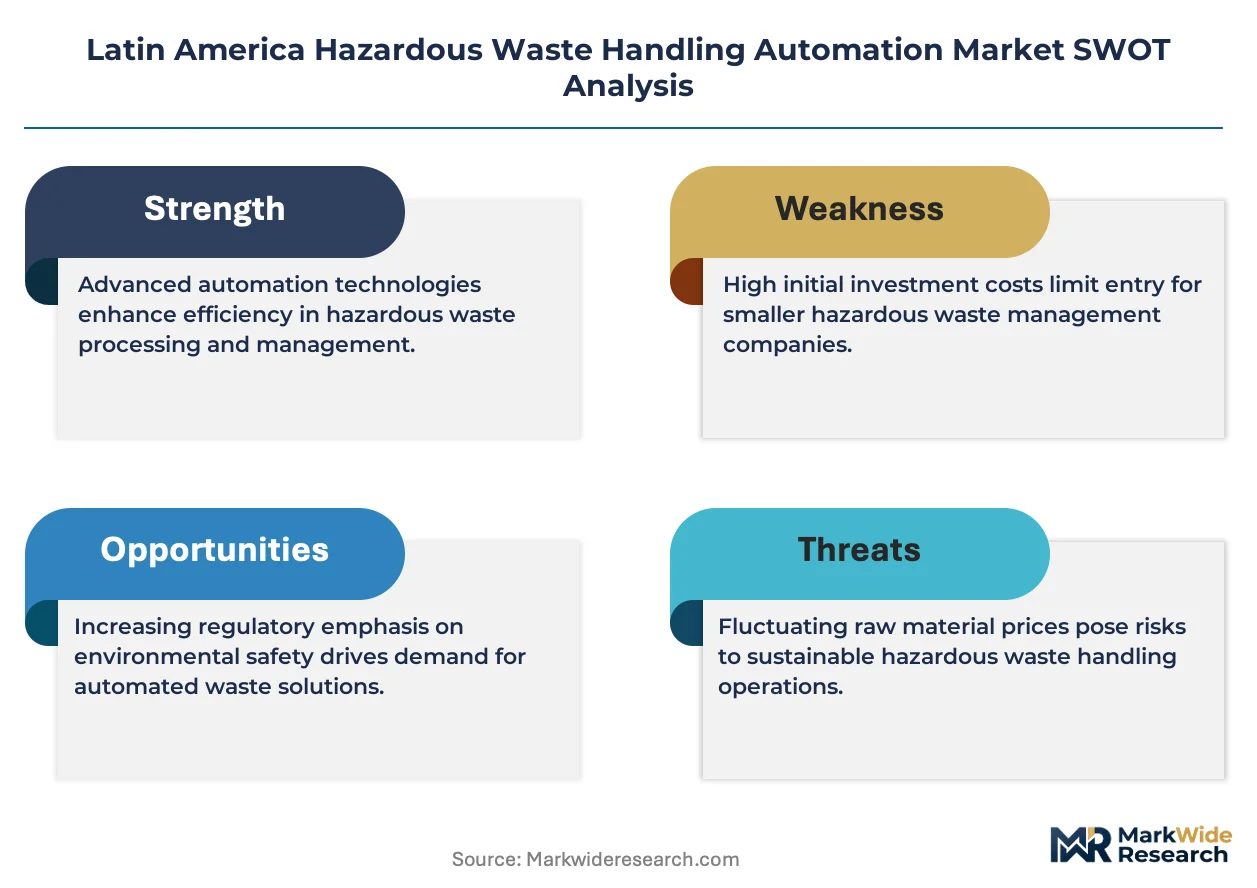
Import tariff exposure on European-certified pressure-rated enclosures determines both pricing tier spreads and supply chain shape across Latin American hazardous waste automation procurement. Buyers absorbing extended lead times for Hastelloy and titanium components face compressed margins that stratify vendor offerings by certification grade and after-sales service bundling.
Pricing Analysis
Long-term integrated service contracts displace spot equipment purchases as Veolia Argentina and similar providers bundle hardware with multi-year operation management. Price differentiation centers on ASME certification tier and predictive maintenance platform inclusion, with premium tiers commanding substantial uplifts for embedded chain-of-custody documentation. Cost compression in economy-tier robotic systems intensifies as local assembly capacity emerges in Brazilian coastal zones. Municipal waste sites exhibit highest price sensitivity due to budget constraints, while São Paulo petrochemical complexes prioritize compliance-grade specifications over unit economics.
Supply Chain Analysis
EU dual-use export controls on advanced robotic control systems limit technology flows to Latin American integrators, compressing local access to force-torque sensing platforms. Manufacturing concentrates in Germany, Finland, and Italy for precision automation hardware, while specialty alloy inputs draw from Australian titanium and Chinese rare earth processing. Single-source vulnerability around ASME-qualified welding certification creates bottlenecks for pressure-rated enclosure fabrication. Distribution runs through authorized integrator networks rather than direct OEM channels, with Konecranes PLC and comparable heritage players anchoring port and industrial waste transfer installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment: CONAMA and ANA mandates create switching costs that lock facilities into compliant automation architectures, protecting incumbents from price-based displacement.
For Market Incumbents: Build switching-cost moats by embedding predictive maintenance platforms into long-term service contracts that penalize premature termination. Deepen backward integration into ASME-qualified technician training programs across Mercosur to capture scarce welding certification capacity. Defend against emerging local assembly competitors by accelerating IoT sensor integration ahead of regulatory minimums, creating performance gaps that pure hardware vendors cannot bridge. For New Entrants and Emerging Players: Build out remote operations capabilities for Mexican border maquiladora chemical facilities where PROFEPA inspection friction delays incumbent capital commitment. Target Chilean mining waste neutralization in the Atacama corridor, where copper and lithium tailings present greenfield automation demand without legacy infrastructure integration burdens. Lead with collaborative robotic arms featuring rapid reconfiguration across acidic leachate chemistries, bypassing fixed-gantry incumbents in tank cleaning applications. For Investors and Strategic Acquirers: Argentina's federal hazardous waste law update reshapes the acquisition landscape by mandating audit-ready data logging that elevates automated treatment unit valuations. Prioritize targets with embedded chain-of-custody software and existing Veolia-style integrated service contracts. Watch for CONAMA resolution acceleration signals as the inflection indicator: compressed deployment timelines for Class I generator containment automation would force distressed asset sales from unprepared pure hardware vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into ASME Welding Certification | Captures scarce NR-13 qualified technician capacity across Brazilian and Argentine industrial corridors. |
| Predictive Maintenance Platform Rollout | Converts Konecranes-style crane automation heritage into recurring service revenue streams. |
| Remote Operations Capability Buildout | Addresses PROFEPA-driven compliance uncertainty in Mexican border maquiladora chemical operations. |
| Collaborative Robotic Arm Product Launch | Displaces fixed-gantry systems in São Paulo petrochemical tank cleaning and sampling workflows. |
| Joint Venture with Local Assembly Partners | Mitigates European-certified system dependency and import tariff exposure for multi-site deployments. |
Research Methodology
A standing panel of plant engineers at Brazilian petrochemical complexes, Argentine environmental compliance officers, Mexican maquiladora operations directors, and aftermarket service heads at automation integrators provided ongoing calibration across the research cycle. Primary fieldwork combined structured interviews with secondary validation through ANA effluent standard filings, CONAMA resolution texts, SEC 10-K disclosures from listed environmental service providers, and customs records for European automation hardware imports. Bottom-up facility-level automation spend estimates triangulated against top-down market sizing from regional industrial production indices.
Scenario bracketing around regulatory enforcement intensity and commodity alloy price volatility anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product hardware type, intelligence technology layer, installation deployment mode, and end-user facility category, with additional granularity on waste stream chemistry reactivity tiers. CAGRs derived from facility retrofit pipeline analysis and capital cycle timing patterns specific to chemical plant automation budgeting. Industry-specific forecast inputs incorporated ANA real-time monitoring mandate compliance deadlines and Argentina's cradle-to-grave tracking implementation trajectory.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by European OEMs through local assembly partnerships would shift outcomes beyond modeled ranges. Material shifts in Hastelloy and titanium supply concentration or accelerated CONAMA resolution enforcement timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Safety
Europe Hazardous Waste Handling Automation Market
Environmental Safety
Noise Control System Market
Environmental Safety
Germany Environment Health & Safety Market
Environmental Safety
US Home Decontamination Services Market
Environmental Safety
Air Audit Equipment Market
Environmental Safety
Environment Health & Safety Market
Environmental Safety
Europe Pest Control Services Market
Environmental Safety
Asia-Pacific Rockfall Radar Market
Environmental Safety
UV Air Sanitizer Market
Environmental Safety
North America Rockfall Radar Market
Environmental Safety
China Home Decontamination Services Market
Environmental Safety
Environmental Health and Safety Market
Environmental Safety
Europe Process Safety Services Market
Environmental Safety
Industrial Noise Control Market
Environmental Safety
Home Decontamination Services Market
Environmental Safety
Noise Monitoring System Market