
 Environment Health & Safety Market | 2026-2036
Environment Health & Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Environment Health & Safety Market Analytics
Market Context
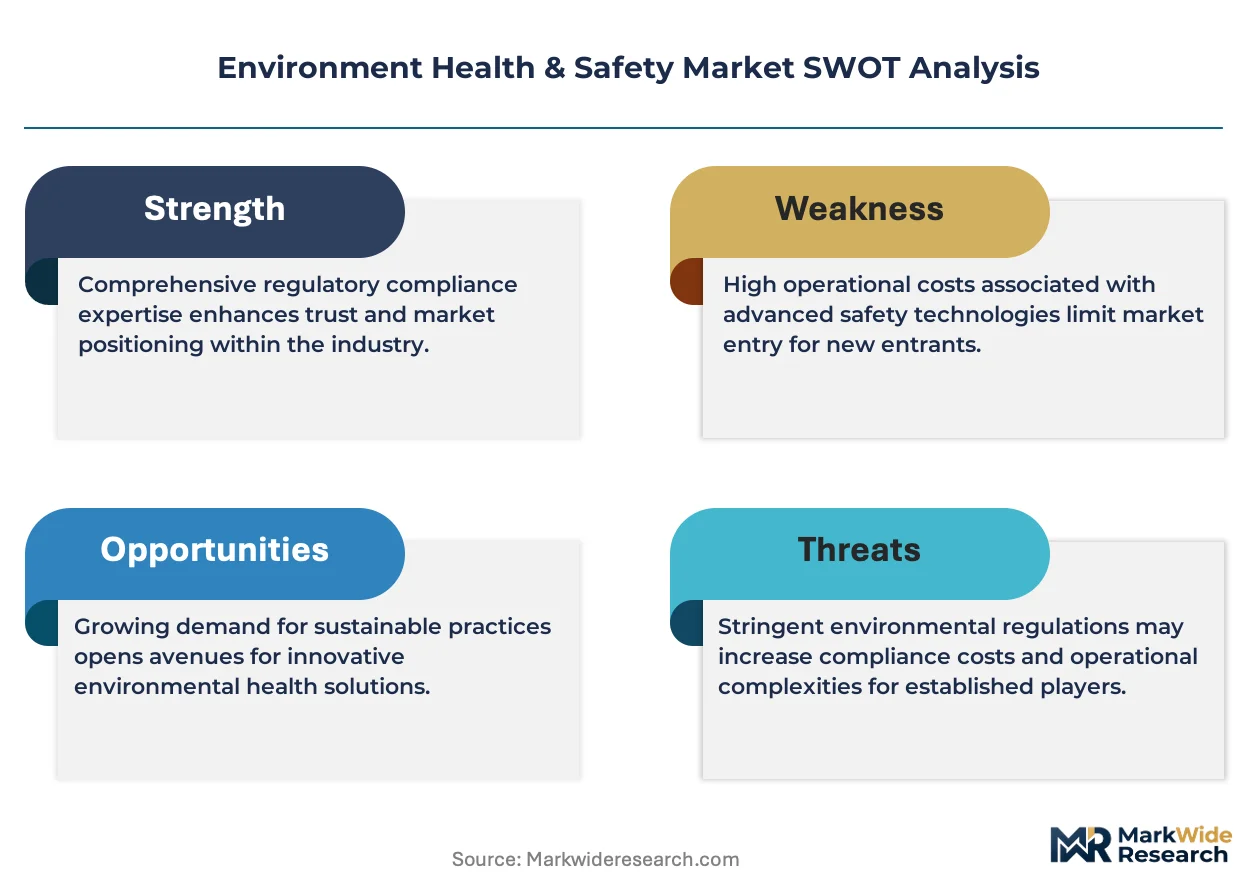
The capital-intensity divergence between cloud-native platforms and legacy on-premise systems is reorganizing competitive dynamics across the EHS software landscape. VelocityEHS leverages its modular architecture to serve mid-market industrial clients without heavy implementation overhead. Wolters Kluwer anchors its position through deep regulatory content libraries that embed compliance logic directly into workflow tools. Sphera differentiates via specialized risk modeling capabilities for chemical and process industries.
Technical Definition and Segments
Environment Health & Safety encompasses integrated systems for workplace hazard identification, exposure monitoring, incident tracking, and regulatory compliance management, typically deployed through software platforms that aggregate sensor data, audit records, and training documentation into unified risk dashboards. Occupational Safety Equipment and Environmental Monitoring Instruments represent mature revenue pools with established procurement cycles, while IoT Solutions and AI Analytics constitute the fastest-expanding segments as facilities retrofit legacy infrastructure with real-time predictive capabilities. Cloud Computing services capture disproportionate margin expansion by reducing total cost of ownership and enabling subscription-based revenue models across multi-site enterprises.
Regulatory Frame and Outlook
OSHA recordkeeping mandates, EPA Clean Air Act enforcement protocols, and ISO 45001 certification requirements collectively shape product development priorities and customer procurement criteria across the United States and export-oriented manufacturing economies. The EU's CSRD disclosure rules and REACH chemical registration obligations are extending compliance data requirements deeper into supply chain tiers. Stakeholders must monitor how fragmented national regulatory timelines will strain platform configurability and determine whether modular or monolithic architectures prove more adaptable.
Market Dynamics
The migration from reactive compliance reporting to predictive risk analytics is compressing procurement cycles for EHS platforms as industrial facilities prioritize real-time hazard detection over periodic audit documentation.
Growth Catalysts
- OSHA Recordkeeping Modernization:Updated electronic submission mandates in the United States are forcing mid-sized manufacturers to replace paper-based incident logs with integrated digital platforms that automate regulatory filings.
- Process Safety Analytics:Chemical processing facilities are embedding IoT sensor networks into legacy distributed control systems to enable continuous emissions monitoring and instantaneous leak detection.
- Rhine-Ruhr Industrial Cluster:Germany's dense concentration of chemical, automotive, and steel production is generating concentrated demand for multilingual EHS platforms configured to EU REACH and CSRD disclosure requirements.
Market Restraints
- Semiconductor Component Volatility:Persistent supply tightness for industrial-grade sensors and edge computing hardware is extending lead times for IoT-enabled EHS deployments by four to eight months.
- Data Sovereignty Fragmentation:Conflicting national requirements for environmental data localization are forcing platform vendors to maintain redundant cloud infrastructure across jurisdictions.
- Legacy System Entrenchment:Decades-old on-premise compliance databases in heavy manufacturing resist API integration, trapping data in siloed formats incompatible with modern analytics layers.
Strategic Opportunities
- India's PLI Manufacturing Expansion:Pharmaceutical and electronics production incentives are creating first-mover advantage for EHS vendors offering Hindi-localized training modules and BIS-aligned audit frameworks.
- AI-Computer Vision Convergence:Automated PPE detection and behavioral safety monitoring are opening subscription revenue streams in construction and logistics where manual supervision costs dominate.
- EU CSRD Supply Chain Mandate:Extended reporting obligations for Scope 3 emissions are compelling tier-two suppliers to adopt EHS data-sharing protocols previously limited to multinational enterprises.
Industry Challenges
- Industrial Hygiene Talent Scarcity:The retirement of experienced safety engineers is outpacing university program output, forcing software vendors to embed automated exposure assessment algorithms that reduce specialist dependency.
- Multi-Standard Certification Burden:Simultaneous pursuit of ISO 45001, ISO 14001, and industry-specific certifications is stretching implementation timelines and inflating consulting costs for platform rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Environment Health & Safety Market |
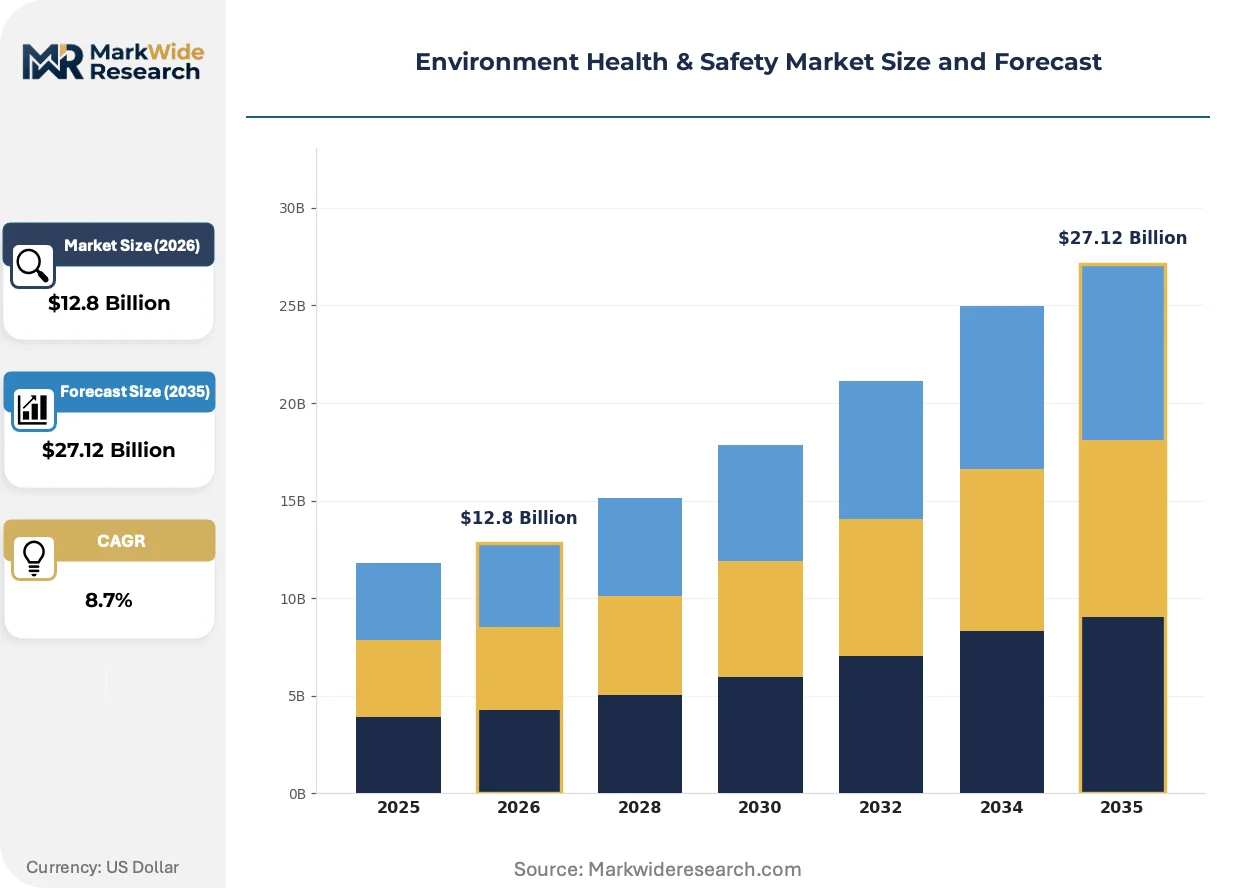
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Occupational Safety Equipment, Hazardous Material Handling, Environmental Monitoring Instruments, Fire Safety Products End User: Manufacturing, Construction, Oil & Gas, Healthcare Service Type: Consulting Services, Training Programs, Compliance Audits, Waste Management Services Technology: IoT Solutions, Cloud Computing, AI Analytics, Wearable Devices |
| Companies Covered | VelocityEHS, Enablon, Intelex Technologies, Cority Software, Sphera, Wolters Kluwer, AECOM, Jacobs, SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Environment Health & Safety Market Evolving Landscape
Real-time data infrastructure is displacing batch-processed compliance workflows across industrial safety operations. Platform architectures are fragmenting between lightweight mobile-first tools for field workers and heavy analytical engines for corporate risk officers.
Edge computing for hazard detection is bifurcating the sensor hardware market. High-frequency vibration and acoustic monitoring devices now preprocess data locally before cloud transmission, reducing latency for critical safety alerts. Oil refineries and offshore platforms are deploying these systems fastest due to connectivity constraints. The technology is bifurcating vendor strategies between specialized edge-hardware manufacturers and cloud-native software platforms that rely on third-party sensor integration.
REACH authorization timelines are accelerating substitution planning for hazardous substances. Chemical manufacturers must now document safer alternatives for substances of very high concern years ahead of sunset dates. Specialty chemical producers serving EU export markets are restructuring product portfolios to preempt registration bottlenecks.
Subscription pricing for EHS software is displacing perpetual license models in enterprise procurement. Chief financial officers prefer operational expenditure treatment for compliance technology, particularly in cyclical industries with volatile capital budgets. North American manufacturing and European automotive supply chains are converting fastest to annual recurring revenue arrangements with usage-based tiers.
Environment Health & Safety Market Segmentation
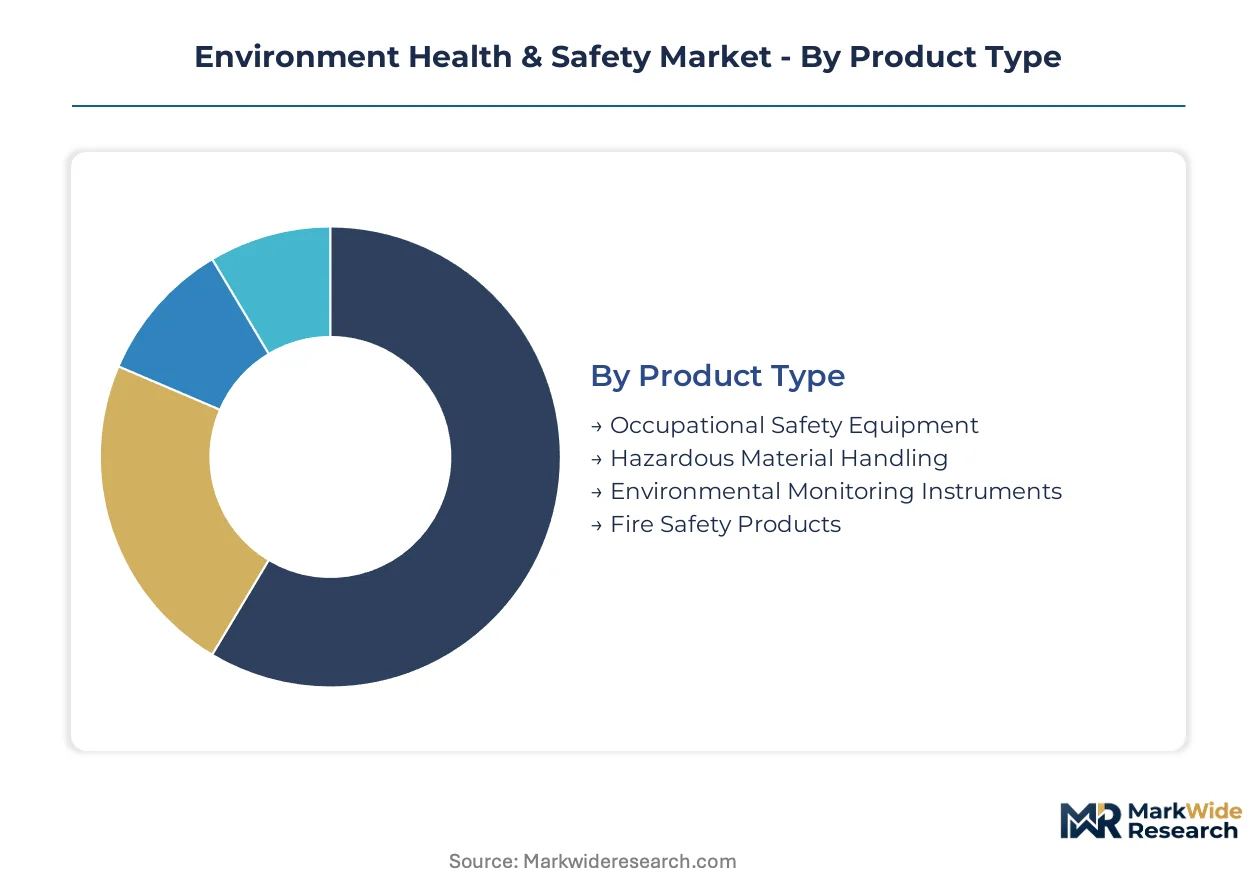
EHS procurement patterns diverge sharply across product categories and service models, with technology-enabled segments capturing disproportionate margin expansion while traditional equipment markets consolidate around price-competitive supply chains. Understanding where value concentrates within each dimension enables vendors to align R&D investment with actual buyer willingness to pay.
Product Type:
Margin pools concentrate in instrumentation and connected safety systems where sensor precision and data integration capabilities justify premium positioning against commoditized personal protective equipment.
- Occupational Safety Equipment:Personal protective equipment including respiratory protection, fall arrest systems, and protective eyewear. Manufacturing facilities in Germany's Rhine-Ruhr corridor and US Gulf Coast petrochemical complexes drive replacement cycles as OSHA and EU PPE directives tighten certification requirements.
- Hazardous Material Handling:Containment systems, chemical storage infrastructure, and spill response equipment engineered for corrosive substance isolation. Oil and gas operators across Texas, Louisiana, and Alberta prioritize API-certified containment solutions amid intensified EPA and Alberta Energy Regulator enforcement on secondary containment failures.
- Environmental Monitoring Instruments:Fixed and portable devices for air quality, water contamination, and noise level measurement with regulatory-grade calibration.
- Fire Safety Products:Suppression systems, detection sensors, and emergency response equipment for industrial facility protection.
The dominant share belongs to Occupational Safety Equipment, while Environmental Monitoring Instruments is closing the gap fastest.
End User:
Procurement sophistication varies dramatically by sector, with oil and gas and healthcare buyers demanding integrated platform solutions while construction and manufacturing segments remain price-sensitive for discrete equipment purchases.
- Manufacturing:Automotive, electronics, and food processing facilities requiring systematic hazard controls across repetitive production environments. German automotive OEMs and their tier-one suppliers in Baden-Württemberg and Bavaria are converting fastest to ISO 45001-aligned integrated management systems.
- Oil and Gas:Upstream exploration, midstream pipeline operations, and downstream refining with process safety management obligations under OSHA PSM and EU Seveso III directives. Offshore platforms in the North Sea and US Gulf of Mexico deploy edge-computing gas detection networks where connectivity constraints demand local preprocessing.
- Construction:Commercial and infrastructure project sites with transient workforces and variable hazard profiles.
- Healthcare:Hospital systems and pharmaceutical manufacturing with biosafety, radiation protection, and chemical hygiene requirements.
Oil and Gas commands the highest per-facility spending intensity, though Manufacturing delivers the largest aggregate revenue pool by site count.
Service Type:
Revenue stability concentrates in recurring compliance audits and waste management contracts, while consulting and training face pricing pressure from self-service digital alternatives.
- Consulting Services:Risk assessment, management system design, and regulatory interpretation delivered by specialized engineering firms. REACH authorization preparation for EU chemical exporters and OSHA VPP certification support for US manufacturers sustain premium billing rates.
- Compliance Audits:Systematic evaluation of regulatory adherence against ISO 45001, ISO 14001, and jurisdiction-specific mandates. Third-party audit demand is climbing fastest in India as BIS standards alignment becomes mandatory for PLI scheme beneficiaries in pharmaceutical and electronics manufacturing.
- Training Programs:Workforce certification in hazard recognition, emergency response, and equipment operation.
- Waste Management Services:Hazardous waste characterization, transportation, and disposal with cradle-to-grave documentation.
Waste Management Services locks in the longest contract tenures, yet Compliance Audits is expanding most quickly as regulatory complexity multiplies audit frequency requirements.
Technology:
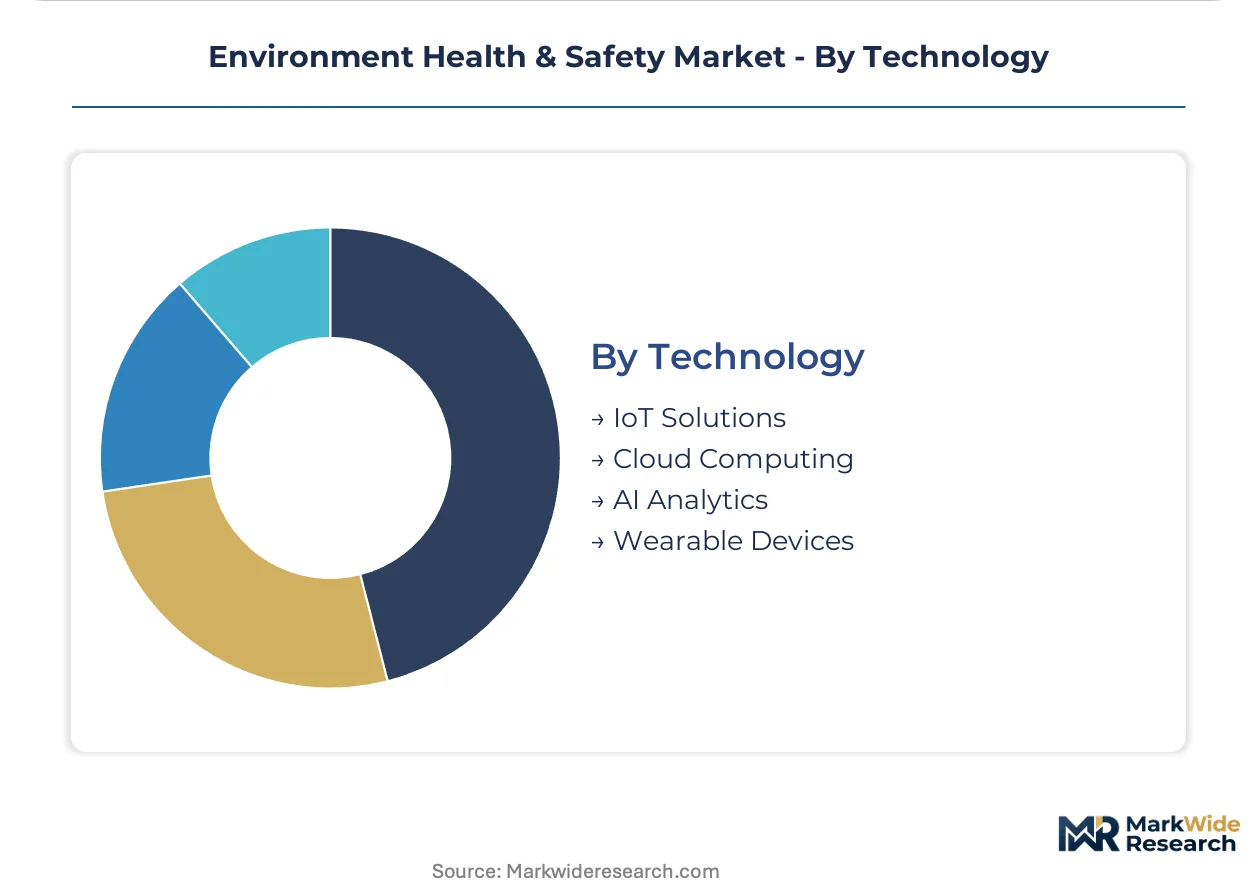
Platform economics favor cloud-native architectures and AI analytics where development costs amortize across subscriber bases, while IoT hardware and wearables grapple with component cost volatility.
- Cloud Computing:Subscription-based software platforms for document management, incident tracking, and regulatory reporting with multi-tenant architecture. North American manufacturing CFOs prefer operational expenditure treatment, accelerating displacement of perpetual license models.
- AI Analytics:Machine learning models for predictive risk scoring, anomaly detection in sensor streams, and automated compliance gap analysis. Computer vision applications for PPE detection and behavioral safety monitoring are opening construction and logistics segments where manual supervision costs dominate.
- IoT Solutions:Networked sensor infrastructure for real-time environmental and safety parameter monitoring.
- Wearable Devices:Body-worn sensors for physiological monitoring, location tracking, and proximity alerting in hazardous zones.
Cloud Computing captures the highest gross margins, though AI Analytics is gaining share fastest as facilities prioritize predictive capabilities over retrospective compliance documentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive procurement in Indian manufacturing contrasts sharply with premium platform adoption in German chemical corridors, while US facilities navigate compliance cost pressures between these extremes.
United States
OSHA electronic recordkeeping mandates are compressing procurement cycles for mid-sized manufacturers. EPA Clean Air Act enforcement actions in Texas and Louisiana are accelerating emissions monitoring upgrades. Gulf Coast petrochemical complexes in Houston and Beaumont are deploying edge-computing gas detection networks where connectivity constraints demand local preprocessing.
Germany
REACH authorization timelines are restructuring product portfolios for chemical exporters serving EU markets. CSRD disclosure rules are extending compliance data requirements deeper into automotive supply chains. The Rhine-Ruhr corridor's dense concentration of steel and chemical production is generating concentrated demand for multilingual platforms configured to EU regulatory frameworks.
China
Dual carbon goals are tightening emissions monitoring obligations for heavy industry. MEE enforcement protocols are standardizing environmental data reporting across provincial manufacturing zones. Yangtze River Delta chemical processors are retrofitting legacy infrastructure with real-time predictive capabilities to preempt regulatory penalties.
India
PLI scheme incentives for pharmaceutical and electronics manufacturing are creating first-mover opportunities for localized EHS platforms. BIS standards alignment is becoming mandatory for scheme beneficiaries. Maharashtra and Gujarat industrial corridors are converting fastest to integrated management systems as export compliance requirements intensify.
United Kingdom
Post-Brexit regulatory divergence from EU frameworks is forcing platform vendors to maintain separate compliance logic for UK operations. HSE enforcement priorities are shifting toward process safety management in North Sea oil operations. Aberdeen's offshore engineering cluster is prioritizing real-time hazard detection over periodic audit documentation.
Environment Health & Safety Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the EHS software landscape. Cloud-native platforms with AI analytics capabilities command premium positioning against modular solutions serving price-sensitive mid-market segments. Three archetypes dominate: regulatory content specialists, integrated platform providers, and vertical-specific risk modelers. Competitive moves concentrate on M&A for data integration capabilities and strategic partnerships for sensor hardware supply.
Within the regulatory content tier, Wolters Kluwer anchors positioning through embedded compliance logic, while VelocityEHS exemplifies the modular architecture approach for rapid deployment. Sphera occupies a position among specialized risk modelers serving chemical and process industries. These three represent distinct strategic bets on whether deep content libraries, implementation speed, or vertical specialization will capture disproportionate margin expansion as facilities migrate from reactive compliance to predictive analytics.
| Leading Market Players |
|---|
| VelocityEHS |
| Enablon |
| Intelex Technologies |
| Cority Software |
| Sphera |
| Wolters Kluwer |
| AECOM |
| Jacobs |
| SAP SE |
| Others |
Value Network & Pricing Analysis
Cloud-native SaaS platforms displacing legacy on-premise installations are simultaneously redrawing supply geography toward software development clusters and compressing pricing economics for perpetual-license incumbents. Subscription models amortize development costs across multi-tenant architectures while edge-computing hardware vendors absorb semiconductor volatility in sensor procurement.
Pricing Analysis
After-sales service revenue through compliance audit retainers and training certification renewals drives lifetime value for EHS platform vendors. Three-tier pricing structure across premium, standard, and economy levels segments buyers by ISO 45001 certification complexity and multi-site deployment scale. Pricing pressure stems from CFO preference for operational expenditure treatment in cyclical manufacturing sectors. Mid-market discrete manufacturers exhibit highest price sensitivity, while oil and gas majors prioritize predictive analytics capabilities over license cost.
Supply Chain Analysis
Germany and the United States anchor industrial-grade sensor fabrication and cloud infrastructure provisioning for EHS platform deployment. Semiconductor components for edge-computing gas detection devices draw from Taiwan and South Korea fabrication capacity. Single-source vulnerability in MEMS sensor supply creates procurement risk for IoT-enabled safety monitoring networks. Distribution runs through direct enterprise sales teams for multinational accounts and regional system integrators for mid-market manufacturing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks industrial capital expenditure cycles, with procurement acceleration tied to OSHA electronic recordkeeping enforcement waves and EU CSRD disclosure phase-ins.
For Market Incumbents: Consolidate regulatory content libraries through targeted acquisition of specialized compliance data providers to defend against modular cloud-native entrants. Embed automated exposure assessment algorithms that reduce specialist dependency as industrial hygiene talent scarcity intensifies. Anchor platform stickiness through deep ISO 45001 workflow integration that raises switching costs for enterprise accounts.
For New Entrants and Emerging Players: Anchor in India's PLI scheme beneficiary corridors where BIS standards alignment mandates create first-mover advantage for Hindi-localized training modules. Target tier-two automotive suppliers in Baden-Württemberg facing EU CSRD Scope 3 data-sharing obligations previously limited to multinationals. Deploy AI-computer vision PPE detection through construction channel partners where manual supervision costs dominate safety budgets.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed modular platform providers serving mid-market industrial clients without heavy implementation overhead. Long-term viability hinges on predictive analytics capability depth rather than compliance documentation breadth. Watch for inflection signals in REACH authorization substitution planning timelines that accelerate chemical manufacturer portfolio restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Content Acquisition | Deepens compliance logic embedding for OSHA and EPA filing automation. |
| Edge-Computing Sensor Partnership | Secures supply chain priority for industrial-grade MEMS devices amid semiconductor tightness. |
| AI-Computer Vision Platform Launch | Opens construction and logistics subscription revenue through automated PPE detection. |
| India Localization Investment | Captures PLI scheme manufacturing expansion with BIS-aligned audit frameworks. |
| REACH Substitution Planning Service | Preempts chemical manufacturer registration bottlenecks ahead of sunset dates. |
Research Methodology
A spread of perspectives from EHS software product managers, industrial plant safety directors, regulatory compliance officers, and cloud infrastructure procurement leads converged on the working assumptions. Primary fieldwork combined with secondary validation from OSHA enforcement databases, EPA Clean Air Act compliance records, EU REACH registration filings, and ISO certification body disclosures. Bottom-up deployment sizing across manufacturing, oil and gas, and chemical processing facilities triangulated against top-down platform revenue aggregation.
Segmentation dimensions modeled span deployment architecture, organization size tier, vertical industry, geographic regulatory cluster, and integration complexity level across the projection horizon. CAGRs derive from fitted growth curves applied to technology adoption S-cycles and regulatory mandate phase-in schedules. Forecast inputs incorporate OSHA electronic recordkeeping compliance deadlines and EU CSRD disclosure timeline accelerations.
Decision-makers should treat outputs as directional under sustained OSHA enforcement intensity and REACH authorization pacing; material deviation would warrant model refresh. Recalibration cycles align with material shifts in semiconductor component availability and industrial capital expenditure sentiment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Safety
Europe Pest Control Services Market
Environmental Safety
Latin America Hazardous Waste Handling Automation Market
Environmental Safety
Europe Hazardous Waste Handling Automation Market
Environmental Safety
Home Decontamination Services Market
Environmental Safety
Noise Control System Market
Environmental Safety
Europe Process Safety Services Market
Environmental Safety
US Home Decontamination Services Market
Environmental Safety
UV Air Sanitizer Market
Environmental Safety
China Home Decontamination Services Market
Environmental Safety
Germany Environment Health & Safety Market
Environmental Safety
Global Air Sampling Pumps Market
Environmental Safety
Environmental Health and Safety Market
Environmental Safety
Industrial Noise Control Market
Environmental Safety
Air Audit Equipment Market
Environmental Safety
Noise Monitoring System Market
Environmental Safety
North America Rockfall Radar Market