
 Germany Environment Health & Safety Market | 2026-2036
Germany Environment Health & Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Environment Health & Safety Market Insights
Multi-source EHS service procurement is restructuring how German industrial firms manage compliance risk across dispersed manufacturing footprints. TÜV SÜD AG leverages its testing heritage to anchor premium certification contracts with automotive OEMs. DEKRA competes aggressively on workforce training scale, while Quentic differentiates through cloud-native software platforms that centralize incident reporting.
Germany Environment Health & Safety encompasses systematic identification, evaluation, and control of workplace hazards, environmental emissions, and occupational health risks through engineered controls, administrative protocols, and personal protective systems. The discipline applies ISO 45001 and ISO 14001 management system standards to reduce incident frequency, ensure regulatory conformity, and sustain operational continuity across hazardous production environments. Compliance management services command the deepest margin pools as German firms absorb escalating documentation burdens under the Supply Chain Due Diligence Act. Software solutions are expanding fastest as mid-sized manufacturers abandon spreadsheet-based tracking for integrated platforms. Monitoring systems remain mature, with sensor hardware commoditizing and value migrating to analytics layers.
KBA enforces vehicle-sector safety standards that cascade into supplier EHS obligations, while ECHA's REACH implementation shapes chemical handling protocols across German process industries. The EU Green Deal's carbon border adjustments are forcing industrial facilities to retrofit emissions monitoring infrastructure ahead of compliance deadlines. Stakeholders must weigh capital deployment between predictive safety analytics and decarbonization tracking systems as regulatory reporting requirements converge.
Market Dynamics
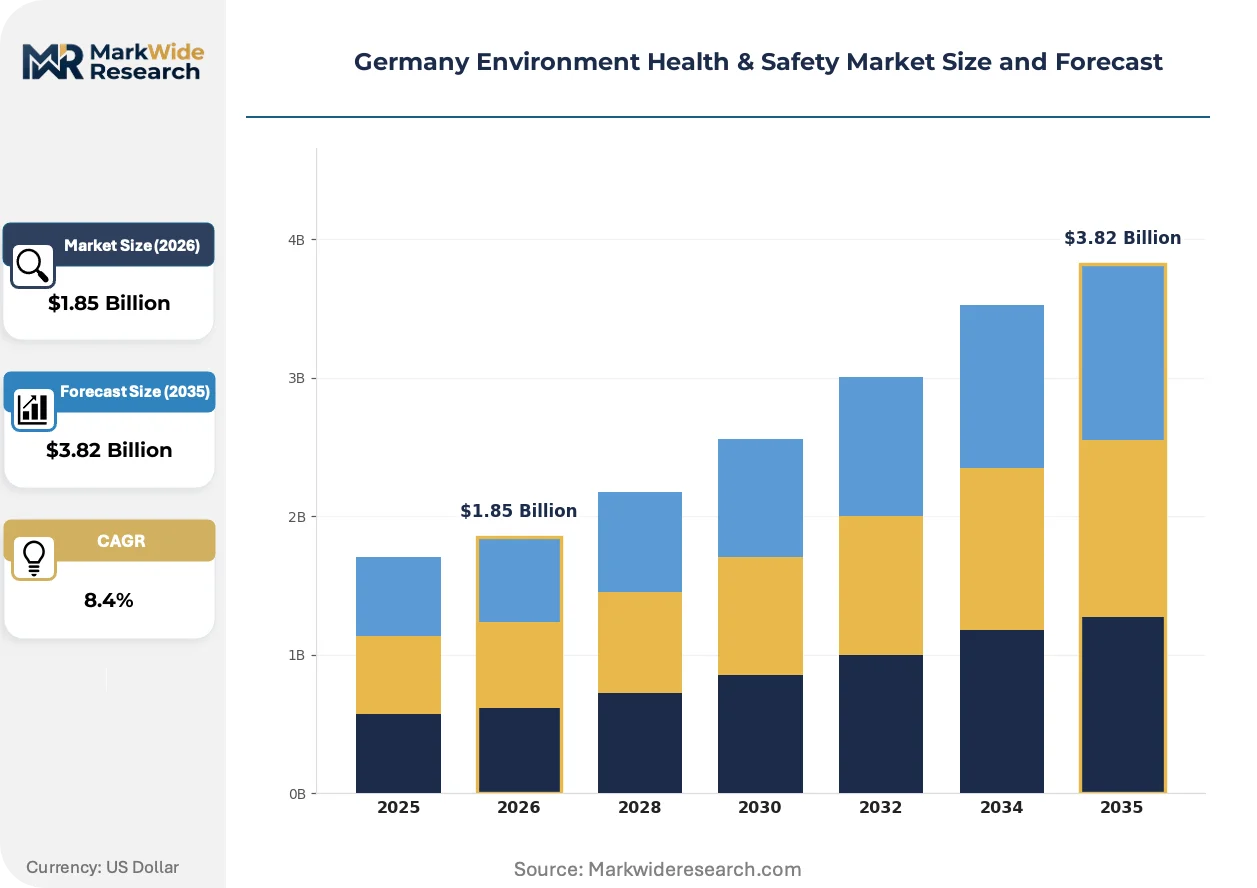
Germany's EHS market is restructuring around the Supply Chain Due Diligence Act's documentation burdens, which force mid-sized manufacturers to abandon fragmented compliance approaches for integrated platforms that unify incident reporting, emissions tracking, and supplier audits.
Growth Catalysts
- EU Green Deal carbon border adjustments:Industrial facilities in North Rhine-Westphalia's chemical corridor must retrofit emissions monitoring infrastructure ahead of compliance deadlines, creating sustained demand for integrated tracking systems.
- Automotive outsourcing expansion:German OEMs are transferring EHS program management to specialized providers as supplier networks extend into Eastern European manufacturing zones.
- ISO 45001 certification mandates:Workplace safety standardization is accelerating across steel and heavy machinery clusters, requiring systematic hazard identification protocols and engineered control investments.
Market Restraints
- Sensor hardware commoditization:Monitoring equipment margins are compressing as value migrates to analytics layers, squeezing traditional hardware vendors.
- Skilled EHS auditor scarcity:Certification bodies face capacity constraints in deploying qualified personnel across dispersed manufacturing footprints.
- REACH chemical registration costs:ECHA's evolving substance restrictions impose recurring compliance expenditures that deter smaller process industry participants.
Strategic Opportunities
- Cloud-native platform consolidation:Mid-sized manufacturers seek unified software solutions replacing spreadsheet-based tracking, creating openings for integrated incident and emissions management systems.
- Predictive safety analytics:Convergence of IoT sensor networks with machine learning enables real-time hazard prediction, shifting value from reactive to preventive EHS spend.
- Bavarian semiconductor expansion:New fabrication facilities in the region require specialized cleanroom safety protocols and chemical handling compliance services.
Industry Challenges
- Legacy system integration complexity:Manufacturing execution systems from the 1990s resist seamless data exchange with modern EHS platforms, requiring costly middleware development.
- Decarbonization tracking convergence:Safety analytics and carbon accounting systems demand unified capital deployment, stretching IT budgets across competing priorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Environment Health & Safety Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Risk Assessment, Compliance Management, Training Services, Environmental Audits End User: Manufacturing, Construction, Healthcare, Transportation Technology: Monitoring Systems, Safety Equipment, Software Solutions, Personal Protective Equipment Application: Waste Management, Incident Management, Indoor Air Quality, Chemical Safety |
| Companies Covered | TÜV SÜD AG, DEKRA, Quentic, SGS, Bureau Veritas, DQS, Intertek, Siemens, BASF, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Environment Health & Safety Market Trends and Innovations
Digital instrumentation is compressing the gap between environmental monitoring and occupational safety, creating unified data architectures that serve dual regulatory reporting obligations simultaneously.
AI-powered predictive analytics is electrifying hazard detection capabilities across German process industries. Machine learning models now process real-time sensor streams from chemical plants to forecast equipment failures before they trigger safety incidents. BASF and Bayer facilities in Ludwigshafen and Leverkusen are piloting these systems, compressing incident response windows from hours to minutes.
KBA's enforcement of vehicle-sector safety standards is cascading into supplier EHS obligations throughout the automotive value chain. The regulator's expanded audit scope now covers tier-two and tier-three component manufacturers, forcing smaller stamping and casting shops to adopt formalized safety management systems. Suppliers in Baden-Württemberg are consolidating compliance documentation to satisfy both KBA inspections and OEM contractual requirements.
Buyer consolidation among German automotive OEMs is compressing EHS service procurement cycles. Volkswagen, BMW, and Mercedes-Benz are unbundling after-sales safety training from equipment supply contracts, creating standalone purchasing decisions that favor specialized workforce development providers. This pattern is most visible in Stuttgart's supplier ecosystem, where tier-one firms now separately source training from certification bodies rather than accepting bundled packages from equipment vendors.
Germany Environment Health & Safety Market Segmentation
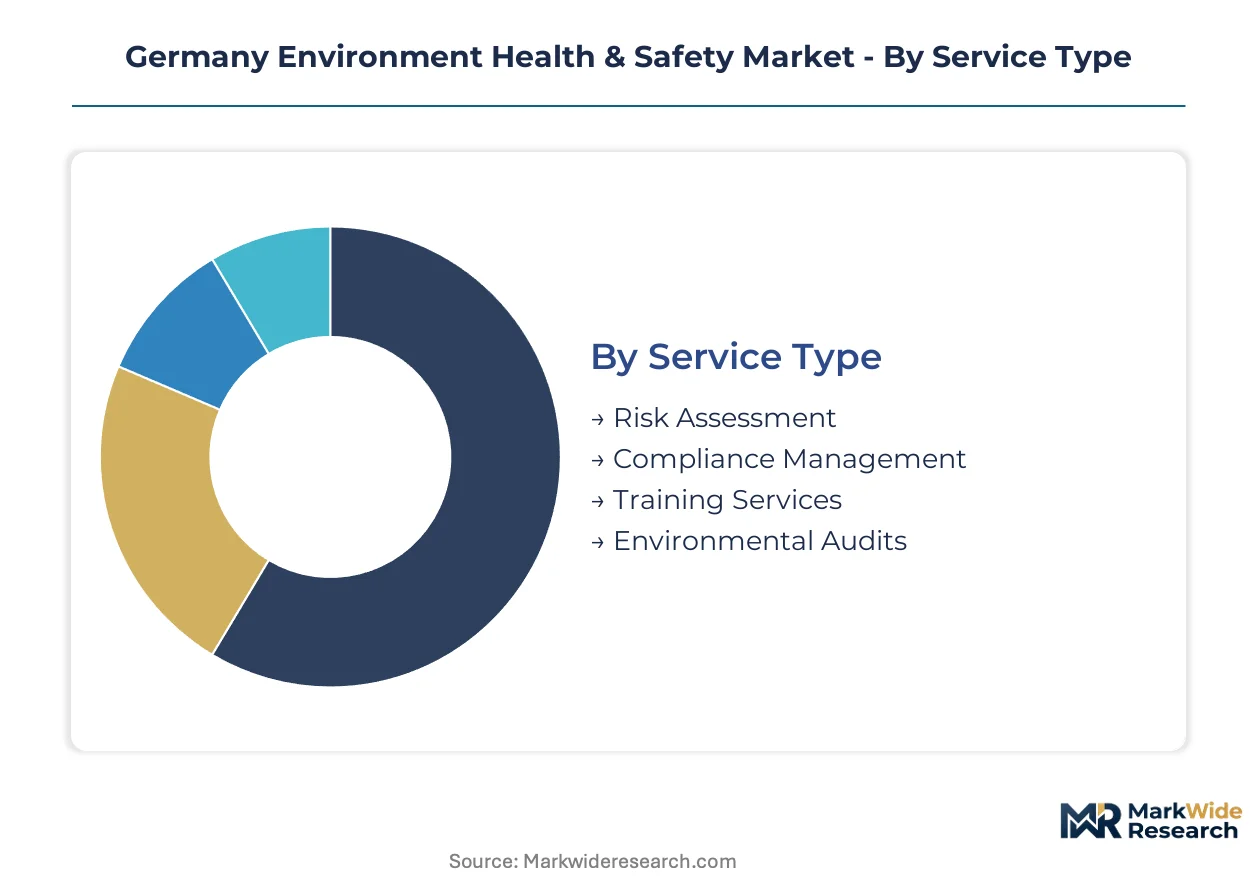
Segmentation in the German EHS market reveals how regulatory pressure and industrial structure concentrate value across distinct service modalities and technology layers. Understanding these partitions clarifies where capital deployment generates compliance leverage versus operational efficiency.
Service Type:
Risk assessment protocols vary in computational intensity and documentation depth, creating distinct margin profiles across the service spectrum.
- Risk Assessment:Systematic hazard identification protocols evaluate workplace conditions against ISO 45001 benchmarks and sector-specific exposure limits. Demand concentrates in North Rhine-Westphalia's chemical corridor, where BASF and Bayer facilities require continuous process hazard analysis under ECHA's evolving substance restrictions.
- Compliance Management:Documentation and audit preparation services absorb the deepest margin pools as German firms absorb escalating burdens under the Supply Chain Due Diligence Act. Mid-sized manufacturers in Baden-Württemberg's automotive supplier ecosystem are abandoning fragmented approaches for integrated platforms that unify incident reporting, emissions tracking, and supplier audits.
- Training Services:Workforce certification programs address ISO 45001 mandates across steel and heavy machinery clusters, with KBA's expanded audit scope cascading into tier-two and tier-three automotive suppliers.
- Environmental Audits:Facility inspections verify conformance with EU Green Deal carbon border adjustment requirements and REACH chemical handling protocols.
Mature deployment sits with Risk Assessment. Newer deployment is concentrated in Compliance Management.
End User:
Industrial concentration and regulatory exposure create divergent EHS procurement patterns across German economic sectors.
- Manufacturing:Chemical, automotive, and steel production facilities generate the deepest service demand, driven by process hazard complexity and emissions scrutiny. Volkswagen, BMW, and Mercedes-Benz are unbundling after-sales safety training from equipment contracts, creating standalone purchasing decisions.
- Construction:Site-specific safety protocols address fall protection, excavation hazards, and temporary electrical systems under Germany's occupational safety enforcement framework.
- Healthcare:Hospital systems require specialized biological hazard containment and radiation safety programs distinct from industrial EHS modalities.
- Transportation:KBA enforcement of vehicle-sector standards cascades through logistics and fleet operations, extending compliance obligations to commercial transport operators.
Procurement scale peaks in Manufacturing. Regulatory complexity is expanding fastest in Transportation.
Technology:
Hardware commoditization and software value migration are restructuring competitive positioning across the technology stack.
- Software Solutions:Cloud-native platforms centralize incident reporting, emissions tracking, and supplier audit documentation for mid-sized manufacturers abandoning spreadsheet-based systems. Quentic and competitors are capturing this transition as integrated systems replace fragmented point solutions.
- Monitoring Systems:Sensor networks for emissions and occupational exposure face margin compression as value migrates to analytics layers, squeezing traditional hardware vendors despite sustained retrofit demand from EU Green Deal carbon border adjustments.
- Safety Equipment:Engineered controls and machine guarding systems serve ISO 45001 certification mandates across steel and heavy machinery clusters.
- Personal Protective Equipment:Respiratory, hearing, and chemical protective systems address residual risk after hierarchy-of-controls implementation.
Margin expansion concentrates in Software Solutions. Price pressure is most severe in Monitoring Systems.
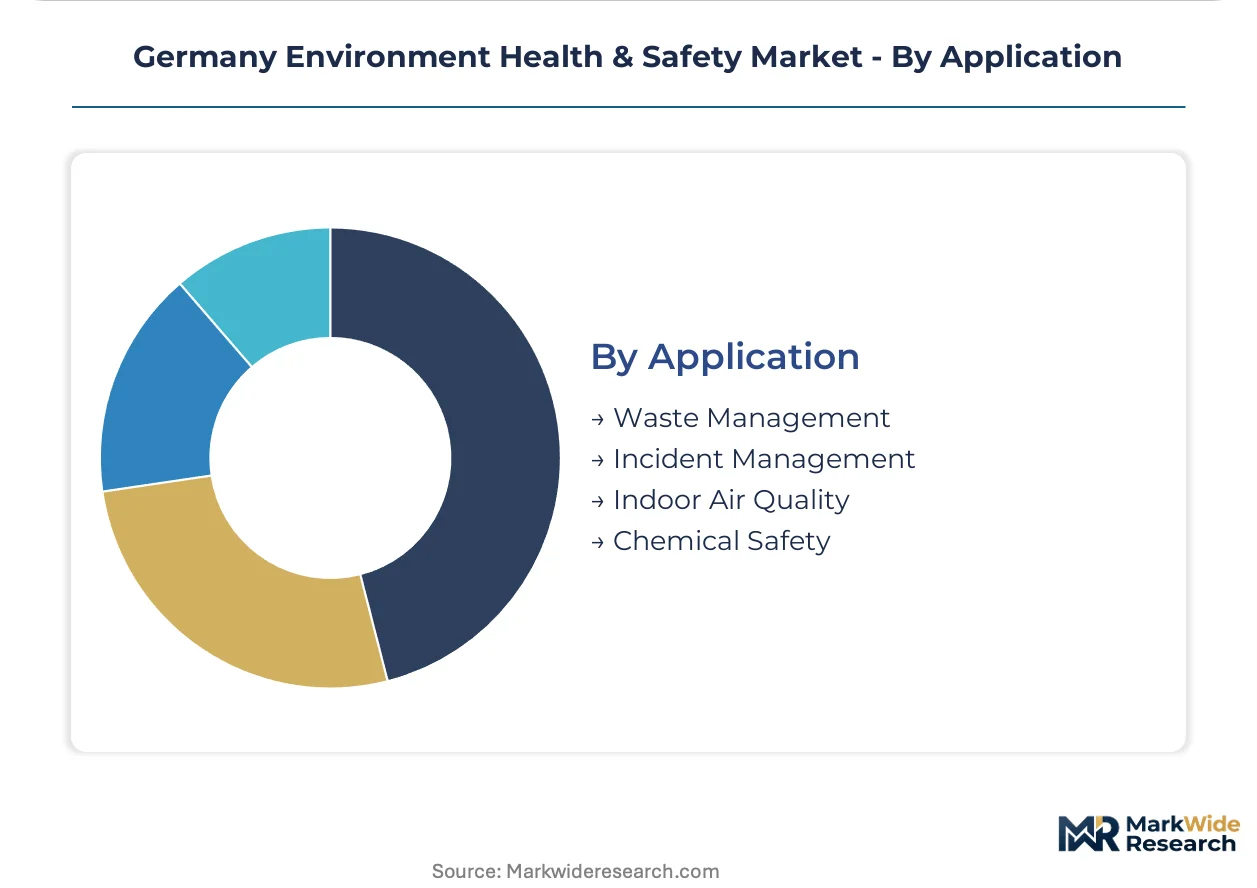
Application:
Regulatory convergence between environmental and occupational domains is unifying data architectures across historically separate compliance functions.
- Chemical Safety:ECHA's REACH implementation shapes handling protocols, storage requirements, and emergency response systems across German process industries. Substance restriction updates impose recurring compliance expenditures that deter smaller participants.
- Incident Management:Real-time reporting systems compress response windows from hours to minutes through AI-powered predictive analytics processing sensor streams from Ludwigshafen and Leverkusen facilities.
- Waste Management:Circular economy regulations and hazardous waste tracking requirements drive specialized audit and documentation services.
- Indoor Air Quality:Ventilation assessment and contaminant monitoring address occupational exposure limits in manufacturing and healthcare environments.
Integration depth is greatest in Chemical Safety. Platform adoption is climbing the fastest in Incident Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr coal basin's industrial heritage anchors EHS service demand across German manufacturing corridors. Regulatory enforcement intensity varies sharply between western chemical clusters and southern automotive belts.
North Rhine-Westphalia
Chemical processing hazards and steel mill emissions drive concentrated compliance spending in Germany's most industrialized state. ECHA's REACH substance restrictions cascade through BASF and Bayer facilities in Leverkusen and Ludwigshafen, forcing continuous process hazard analysis investments. The Rhine-Ruhr metropolitan corridor hosts the deepest pool of certified EHS auditors serving heavy industry.
Baden-Württemberg
Automotive supplier networks generate tiered safety certification demand across Stuttgart's manufacturing ecosystem. KBA enforcement extends through tier-two and tier-three component manufacturers, compelling formalized safety management system adoption. The region's precision engineering clusters require specialized machine guarding and occupational exposure protocols.
Bavaria
Semiconductor fabrication expansion creates novel cleanroom safety and chemical handling compliance requirements in Munich's technology corridor. New wafer production facilities demand specialized ventilation assessment and contaminant monitoring systems. The state's pharmaceutical manufacturing base adds biological hazard containment protocols to regional EHS service portfolios.
Lower Saxony
Volkswagen's Wolfsburg headquarters anchors automotive EHS program outsourcing across northern production networks. The company's unbundling of safety training from equipment contracts creates standalone procurement opportunities for workforce development specialists. Regional supplier parks absorb cascading certification mandates from OEM audit programs.
Hesse
Frankfurt's financial and logistics hub generates transportation-sector EHS demand distinct from industrial manufacturing patterns. Commercial fleet operators face KBA safety standard enforcement extending into logistics subcontractor networks. The state's chemical distribution corridor along the Rhine Main requires hazardous materials handling compliance services.
Germany Environment Health & Safety Market Competitive Landscape
Strategic partnerships dominate the current landscape as certification bodies and software vendors converge on integrated platform offerings. The vendor base organizes into three tiers: heritage testing institutions with audit heritage, cloud-native software specialists, and diversified industrial conglomerates with captive EHS divisions. Two archetypes define competitive positioning: audit-scale players competing on personnel deployment capacity, and platform-centric vendors capturing mid-market digitalization budgets. M&A activity and technology licensing arrangements represent the dominant competitive moves reshaping market structure.
Within the heritage certification tier, TÜV SÜD AG and DEKRA exemplify contrasting scale strategies. The former leverages its Munich-based testing heritage to anchor premium automotive OEM contracts, while the latter competes aggressively on workforce training deployment capacity across dispersed manufacturing footprints. Quentic occupies a distinct position among cloud-native specialists, representing the software-centric archetype that captures mid-sized manufacturers abandoning spreadsheet-based compliance tracking. These three anchors illustrate how competitive positioning fragments across audit heritage, training scale, and platform architecture vectors.
| Leading Market Players |
|---|
| TÜV SÜD AG |
| DEKRA |
| Quentic |
| SGS |
| Bureau Veritas |
| DQS |
| Intertek |
| Siemens |
| BASF |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal carbon border adjustments gate qualified supply and premium-tier pricing access, as only certified EHS providers with emissions-tracking capabilities capture automotive OEM contracts while uncertified competitors face margin compression from excluded procurement pools.
Pricing Analysis
Warranty and service bundling separates premium EHS contracts from transactional engagements, with TÜV SÜD and DEKRA anchoring multi-year automotive certification packages while mid-market software vendors pursue unbundled SaaS subscriptions. Pricing stratifies across premium, standard, and economy tiers based on auditor qualification grade and ISO 45001 certification depth. Cost compression in sensor hardware is intensifying because value migrates to analytics layers, squeezing traditional equipment vendors. Mid-sized manufacturers in Baden-Württemberg's supplier ecosystem show highest price sensitivity, while BASF and Bayer facilities in North Rhine-Westphalia absorb premium rates for specialized chemical safety protocols.
Supply Chain Analysis
Dual-sourcing requirements from German automotive OEMs mandate multi-supplier qualification across EHS service procurement, preventing single-provider dependence in tier-one supplier networks. Geographic supply concentration draws from Germany, Switzerland, and the Netherlands for high-grade certification services, while sensor hardware sources from China, Taiwan, and South Korea. Raw material dependencies rest on semiconductor components for IoT monitoring systems, specialized chemical reagents for testing protocols, and rare earth elements for sensor manufacturing. Single-source vulnerability concentrates in cloud infrastructure for SaaS platforms. Distribution runs through direct enterprise sales teams serving major OEMs, supplemented by channel partnerships reaching mid-sized manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified EHS auditor scarcity props pricing power across the German market, as certification bodies face capacity constraints deploying personnel across dispersed manufacturing footprints.
For Market Incumbents: Extend platform architecture investments to capture mid-sized manufacturers abandoning spreadsheet-based compliance tracking, while consolidating audit capacity in North Rhine-Westphalia's chemical corridor to defend against cloud-native software entrants. Backward integration into predictive analytics capabilities anchors long-term automotive contracts against specialized AI vendors. For New Entrants and Emerging Players: Germany's Supply Chain Due Diligence Act opens a window for compliance management software targeting mid-tier automotive suppliers in Baden-Württemberg, where documentation burdens outstrip incumbent service capacity. Bavarian semiconductor fabrication expansion offers a penetrable geography requiring specialized cleanroom safety protocols absent established provider presence. A channel partnership strategy with regional industrial associations accelerates credibility building against heritage certification brands. For Investors and Strategic Acquirers: Volkswagen's unbundling of safety training from equipment contracts is the leading indicator that standalone workforce development providers will command acquisition premiums across the analysis window. Target cloud-native EHS platforms with automotive OEM references and scalable incident-reporting architectures. Watch for tier-two supplier consolidation in Stuttgart's ecosystem as the signal that integrated platform demand is accelerating beyond point-solution capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies incident reporting, emissions tracking, and supplier audits for mid-sized manufacturers under EU Green Deal obligations. |
| Acquisition of Specialist Firm | Captures predictive analytics capabilities serving BASF and Bayer facilities in Ludwigshafen and Leverkusen. |
| Geographic Expansion | Establishes cleanroom safety service capacity in Munich's semiconductor fabrication corridor. |
| Strategic Partnership | Aligns cloud-native software vendors with heritage certification bodies for integrated compliance offerings. |
| Product Launch | Introduces AI-powered hazard detection compressing incident response windows from hours to minutes. |
Research Methodology
Multi-period observation of EHS certification volumes, software adoption rates, and automotive outsourcing patterns anchored the trend analysis, supplemented by interviews with EHS directors at chemical and automotive facilities, compliance officers managing Supply Chain Due Diligence Act implementation, procurement leads at tier-one suppliers, and platform engineers developing predictive analytics systems. Secondary validation drew from KBA enforcement disclosures, ECHA substance restriction updates, EU Green Deal regulatory texts, and German federal occupational safety statistics. Bottom-up service provider capacity assessments triangulated against top-down manufacturing sector compliance spending estimates.
Segment-weighting across service type, end-user industry, technology layer, and application domain structured the analytical framework, with manufacturing, construction, healthcare, and transportation verticals receiving distinct elasticity parameters. CAGRs were derived from regression analysis of historical certification growth and projected regulatory compliance deadlines. Cloud platform adoption curves and sensor hardware replacement cycles served as industry-specific forecast inputs across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for AI-powered predictive analytics would alter the outlook if machine learning deployment lags in process industries. Deviation in EU Green Deal carbon border adjustment implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Safety
US Home Decontamination Services Market
Environmental Safety
Noise Monitoring System Market
Environmental Safety
Europe Process Safety Services Market
Environmental Safety
Europe Hazardous Waste Handling Automation Market
Environmental Safety
Environment Health & Safety Market
Environmental Safety
Asia-Pacific Rockfall Radar Market
Environmental Safety
Noise Control System Market
Environmental Safety
Latin America Hazardous Waste Handling Automation Market
Environmental Safety
Industrial Noise Control Market
Environmental Safety
North America Rockfall Radar Market
Environmental Safety
UV Air Sanitizer Market
Environmental Safety
Global Air Sampling Pumps Market
Environmental Safety
Europe Pest Control Services Market
Environmental Safety
China Home Decontamination Services Market
Environmental Safety
Home Decontamination Services Market
Environmental Safety
Air Audit Equipment Market