
 Asia-Pacific Rockfall Radar Market | 2026-2036
Asia-Pacific Rockfall Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Rockfall Radar Market Insights
Market Context
China's GB standards for geological hazard monitoring is rebalancing compliance costs across the Asia-Pacific rockfall radar supply base. IDS GeoRadar (Hexagon) leverages its Hexagon group integration to sustain integrated sensor-to-software workflows across Australian and Southeast Asian mine sites. GroundProbe anchors the premium ground-based segment with specialized interferometric radar systems purpose-built for pit wall monitoring.
Technical Definition and Segments
Asia-Pacific rockfall radar encompasses ground-based, aerial, portable, and stationary units that emit microwave signals and analyze Doppler-shifted returns to detect millimeter-scale rock slope deformations across operating ranges from short-range pit benches to long-range mountain corridors. These systems serve mining companies, construction firms, government agencies, and environmental consultants by enabling early warning of catastrophic slope failures before human exposure occurs. Ground-based systems dominate current procurement volumes due to their proven reliability in high-dust mining environments, while aerial systems represent the fastest-growing category as drone-mounted radar platforms reduce survey labor requirements across inaccessible terrain. Radar-based systems command the largest technology share, though sensor arrays are gaining traction where multi-modal detection improves classification accuracy between rockfall events and environmental noise.
Regulatory Outlook
China's MEE enforces geological disaster prevention standards that mandate continuous slope monitoring for mines above specified production thresholds, while Australia's state-level mining safety regulators impose duty-of-care obligations that drive radar adoption across Western Australia and Queensland operations. Japan's METI coordinates infrastructure resilience guidelines that incorporate rockfall detection into tunnel and highway risk management protocols. Stakeholders must weigh certification requirements against total cost of ownership when selecting between laser-based and radar-based monitoring architectures for multi-decade mine life cycles.
Market Dynamics
China's GB standards for geological hazard prevention are compressing deployment timelines across Australian and Indonesian mining operations, forcing suppliers to accelerate certification cycles while expanding local technical support infrastructure.
Growth Catalysts
- GB Standard Compliance Deadlines:China's MEE mandates for continuous slope monitoring are pulling forward replacement demand across adjacent Asia-Pacific jurisdictions as mining operators preempt regulatory harmonization.
- Pilbara Basin Concentration:Australia's iron ore corridor generates concentrated procurement volumes where single-site deployments exceed fifty radar units, creating reference installations that accelerate adjacent mine adoption.
- Interferometric Reliability:Ground-based radar systems demonstrate sub-millimeter deformation detection in high-dust Pilbara conditions, establishing performance benchmarks that displace laser-based alternatives in open-pit environments.
Market Restraints
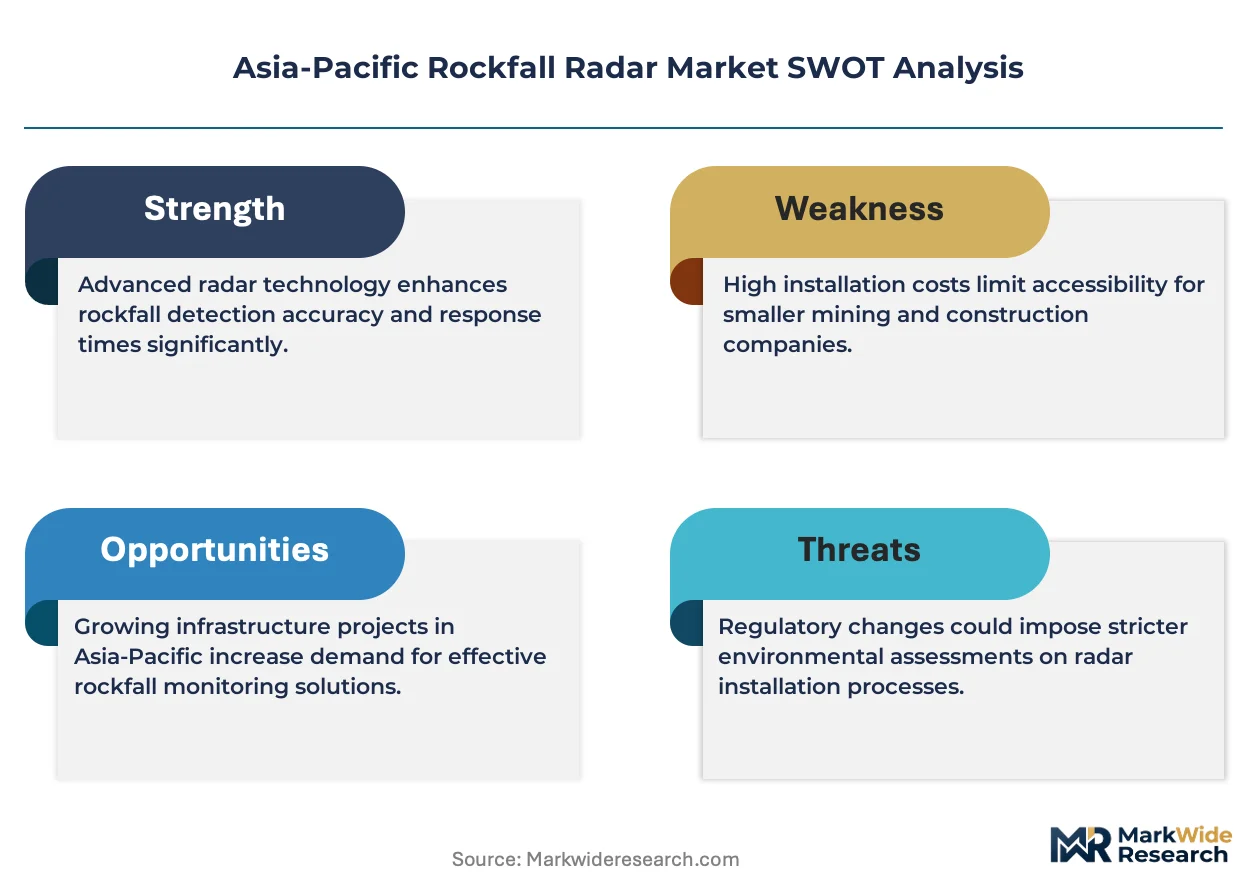
- Specialized Component Supply:High-frequency microwave components concentrate among German and Japanese precision manufacturers, exposing lead time volatility to semiconductor foundry allocation decisions.
- Calibration Labor Intensity:Each installation requires site-specific geotechnical calibration by certified surveyors, creating deployment bottlenecks that extend project timelines beyond equipment delivery schedules.
- Lidar Substitution Pressure:Terrestrial laser scanning offers comparable accuracy at lower capital cost for short-range applications, constraining radar pricing power in construction and quarrying segments.
Strategic Opportunities
- Vietnam Underground Mining:Coal expansion in Quang Ninh province lacks established monitoring infrastructure, presenting first-mover positioning for radar suppliers before regulatory frameworks mature.
- Drone-Mounted Convergence:Synthetic aperture radar integration with heavy-lift UAV platforms is unifying aerial survey efficiency with ground-based precision, opening inaccessible terrain applications in Papua New Guinea and Indonesian archipelago operations.
- Western Australia Duty-of-Care:State mining safety regulators are tightening pit wall monitoring obligations beyond federal baselines, mandating redundant sensor arrays that expand per-site equipment counts.
Industry Challenges
- Geotechnical Data Scientist Scarcity:Interpretation of radar deformation time-series requires specialized slope stability expertise that outpaces university program output across Australia and Southeast Asia.
- Legacy SCADA Integration:Mine site control systems operate on proprietary protocols that demand custom middleware development, extending commissioning timelines and inflating project engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Rockfall Radar Market |
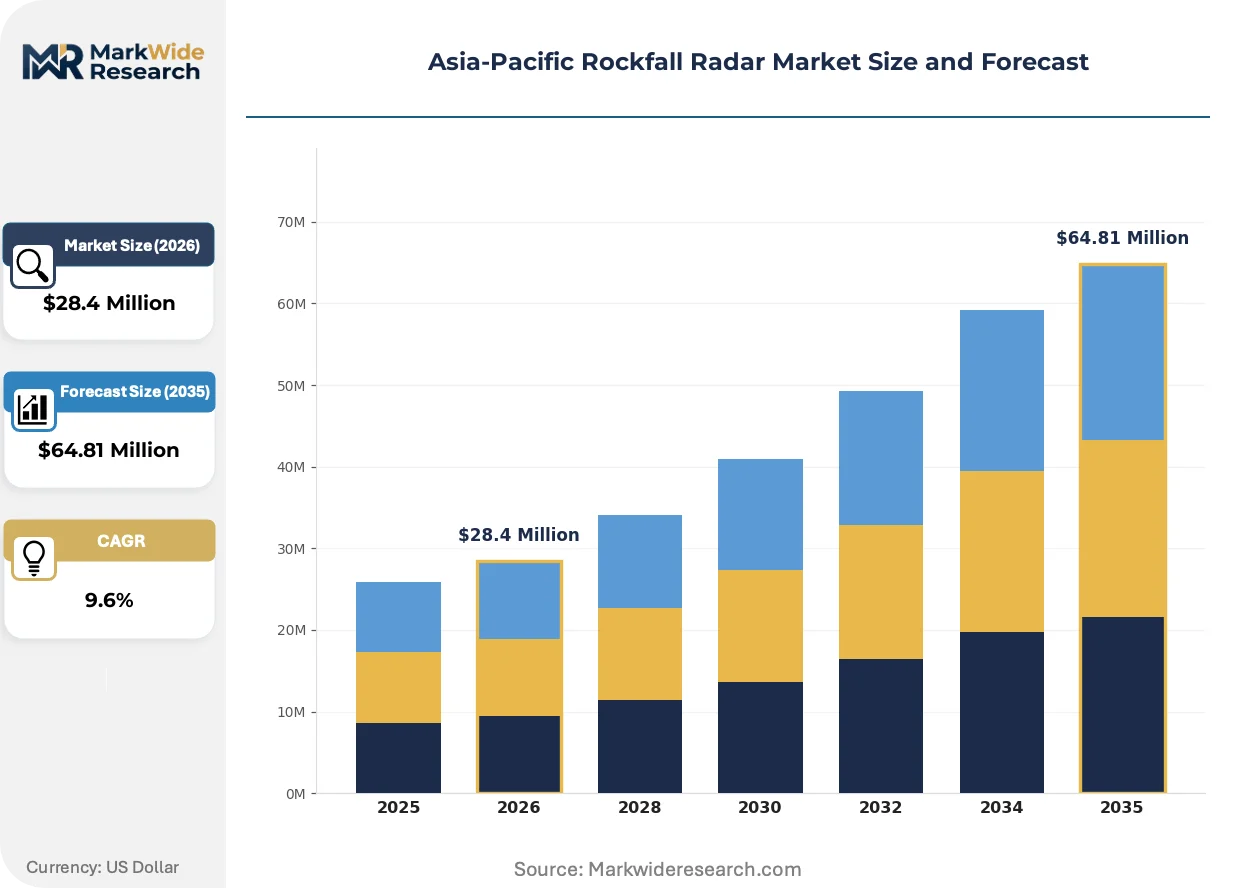
| Market Size in 2026 | $28.4 Million |
| Market Size in 2035 | $64.81 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground-based Systems, Aerial Systems, Portable Units, Stationary Units End User: Mining Companies, Construction Firms, Government Agencies, Environmental Consultants Operating Range: Short-range, Medium-range, Long-range, Variable-range Monitoring Technology: Radar-based Systems, Laser-based Systems, Sensor Arrays, Acoustic Sensors |
| Companies Covered | SkyGeo, Geomotion Australia, IDS GeoRadar (Hexagon), GSSI, GRTIZN, GroundProbe, Canary Systems, GeoSIG Ltd, Geobrugg AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Rockfall Radar Market Trends and Innovations
Sensor fusion architectures are compressing the distinction between detection and classification systems, enabling automated alert generation that reduces human monitoring labor across multi-pit operations.
Multi-static radar networks are unifying data from distributed ground-based units into coherent slope stability models. Mining operators in Queensland's Bowen Basin deploy these configurations across pit perimeters exceeding five kilometers. The technology is unifying previously siloed monitoring points into centralized decision-support systems that compress response latency from hours to minutes.
Australia's state-level mining safety regulators are mandating independent third-party verification of slope monitoring system performance. Western Australia's Department of Mines, Industry Regulation and Safety now requires annual recertification of radar calibration accuracy. Underground operations in New South Wales face equivalent compliance obligations, driving demand for embedded self-diagnostic capabilities that reduce external audit frequency.
Equipment procurement is consolidating under mine site engineering departments rather than distributed through regional safety managers. Tier-one iron ore producers in Western Australia now mandate centralized vendor qualification programs that pre-approve radar suppliers for multi-site deployment. This concentration is visible across BHP and Rio Tinto operations, where standardization reduces spare parts inventory complexity and technician training overhead.
Asia-Pacific Rockfall Radar Market Segmentation
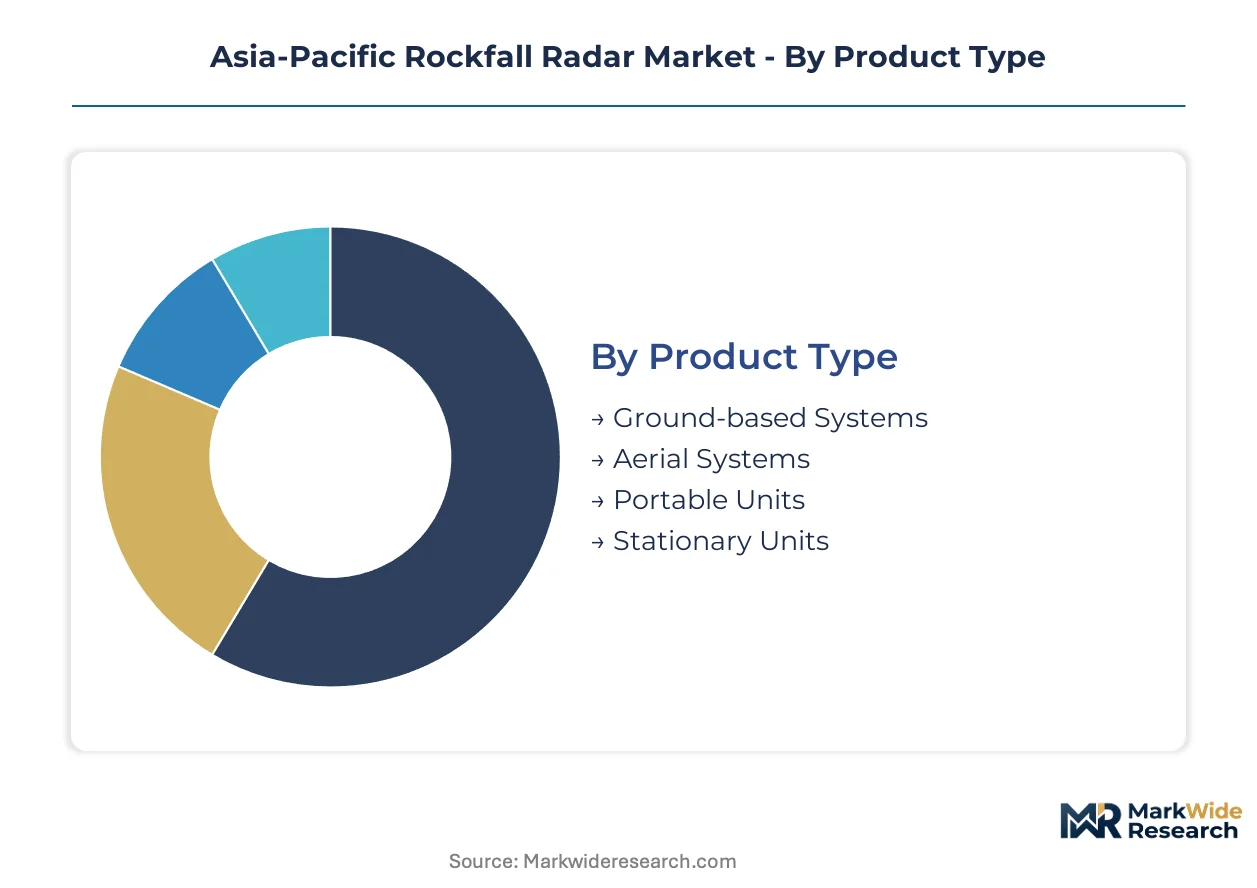
Procurement decisions across Asia-Pacific mining corridors hinge on matching radar specifications to pit wall geometry, dust exposure, and regulatory compliance timelines. Equipment selection varies sharply between Pilbara iron ore basins requiring long-range perimeter coverage and Indonesian archipelago operations prioritizing portable rapid-deployment units.
Product Type:
Site accessibility and installation permanence drive product selection, with mining operators balancing capital commitment against operational flexibility needs.
- Ground-based Systems:Fixed-position interferometric radar units deliver sub-millimeter deformation detection across multi-kilometer pit perimeters. Procurement concentrates in Western Australia's Pilbara and Queensland's Bowen Basin where iron ore and coal producers operate decade-long open-pit campaigns under state-level duty-of-care obligations.
- Aerial Systems:Drone-mounted synthetic aperture radar platforms compress survey timelines across inaccessible terrain. Demand accelerates in Papua New Guinea and Indonesian archipelago mining where road infrastructure limits ground crew access to high-risk slopes.
- Portable Units:Rapid-deployment radar systems serve construction firms and quarrying operations requiring temporary monitoring during blasting phases or emergency response.
- Stationary Units:Permanent installations anchor highway and tunnel monitoring infrastructure under Japan's METI resilience guidelines.
Ground-based systems lead on scale; aerial systems lead on momentum.
End User:
Budget authority and risk tolerance shape procurement patterns across four distinct buyer archetypes with diverging technical requirements.
- Mining Companies:Tier-one iron ore and coal producers dominate procurement volumes, deploying redundant sensor arrays across pit walls exceeding five kilometers in strike length. Western Australia's Department of Mines, Industry Regulation and Safety mandates drive per-site equipment counts above fifty units at major Pilbara operations.
- Construction Firms:Highway and tunnel contractors prioritize portable and short-range systems for temporary slope monitoring during cut-and-fill operations. Procurement concentrates in Japan and South Korea where infrastructure resilience protocols incorporate rockfall detection into project risk management.
- Government Agencies:National geological survey organizations and transport ministries acquire long-range systems for mountain corridor monitoring. China's MEE geological disaster prevention standards pull forward replacement demand across provincial highway networks.
- Environmental Consultants:Third-party slope stability specialists deploy mixed-technology sensor arrays for client compliance verification. Calibration labor requirements limit segment growth relative to direct mining procurement.
Mining companies anchor procurement volume; government agencies are expanding most quickly under regulatory harmonization pressures.
Operating Range:
Pit wall dimensions and terrain accessibility dictate range requirements, with procurement clustering at extremes of the spectrum.
- Short-range:Bench-scale monitoring systems cover individual excavation faces from 50-500 meters. Quarrying and construction applications in Vietnam and Thailand favor these units for localized hazard detection.
- Medium-range:Systems spanning 500 meters to 2 kilometers serve mid-scale open-pit operations and multi-bench coal mines. Procurement runs through mine site engineering departments consolidating vendor qualification programs.
- Long-range:Extended coverage units monitor mountain corridors and full pit perimeters exceeding 5 kilometers. Australia's iron ore majors deploy these across Pilbara operations where single-site installations require coordinated multi-static networks.
- Variable-range:Reconfigurable systems adapt to evolving mine geometries through software-defined beam steering. Adoption remains constrained by calibration complexity and specialized technician requirements.
Long-range systems dominate capital deployment; variable-range configurations are gaining share fastest through software upgrade pathways.
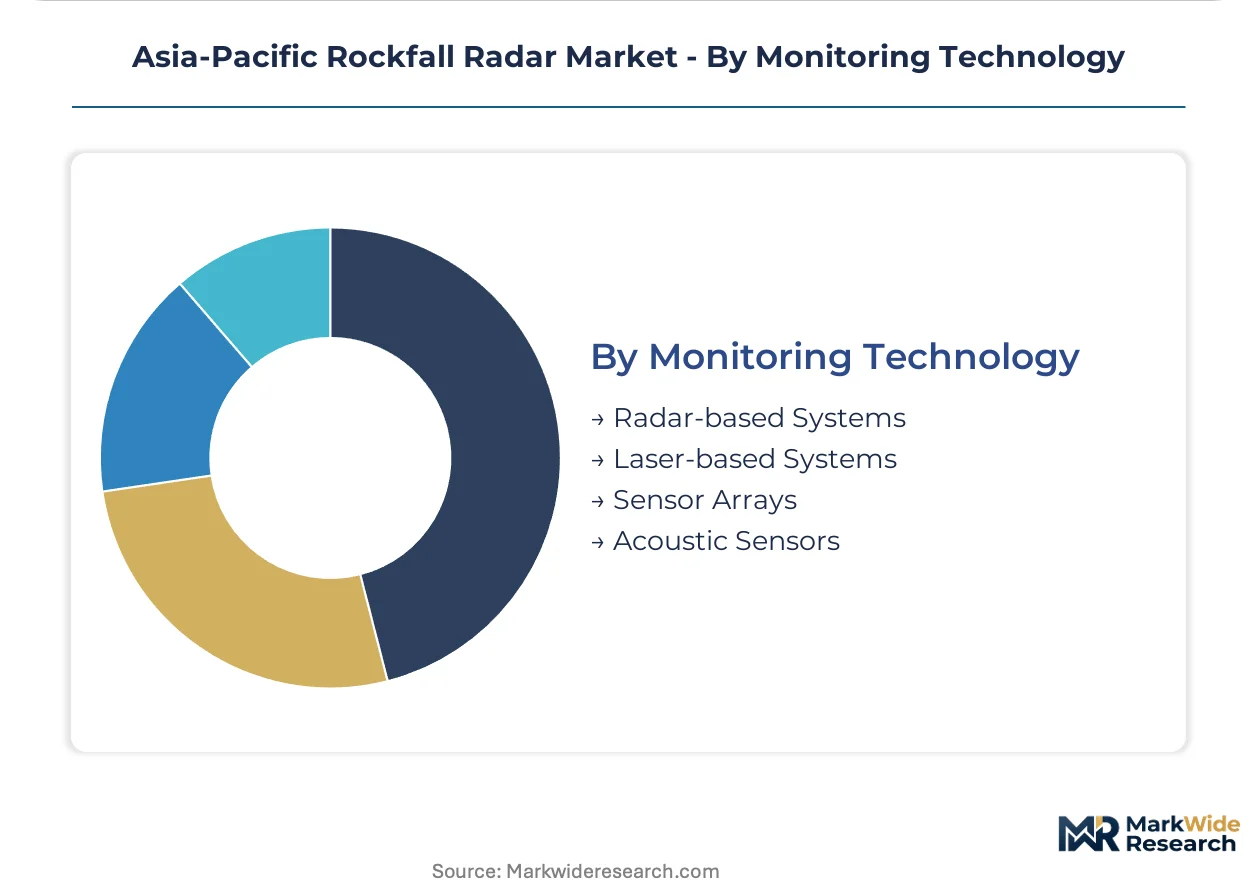
Monitoring Technology:
Detection modality selection balances accuracy requirements against total cost of ownership across multi-decade mine life cycles.
- Radar-based Systems:Microwave interferometry dominates open-pit mining applications, demonstrating reliable performance in high-dust Pilbara conditions where laser systems suffer signal attenuation. Sub-millimeter deformation detection establishes performance benchmarks displacing alternative technologies in premium procurement tiers.
- Laser-based Systems:Terrestrial laser scanning offers comparable accuracy at lower capital cost for short-range construction and quarrying applications. Lidar substitution pressure constrains radar pricing power in segments where dust exposure remains manageable.
- Sensor Arrays:Multi-modal detection architectures fuse radar, seismic, and tiltmeter inputs to improve classification accuracy between rockfall events and environmental noise. Adoption accelerates in Queensland's Bowen Basin where automated alert generation reduces human monitoring labor.
- Acoustic Sensors:Passive listening systems detect rockfall impact signatures for supplementary verification. Integration with primary radar networks expands in underground mining applications where line-of-sight constraints limit electromagnetic coverage.
Radar-based systems command installed base; sensor arrays show steepest expansion trajectory through fusion architecture advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rockfall radar technology first achieved commercial scale in Australian open-pit mining during the 2000s, with Western Australia's Pilbara iron ore operations establishing the template for interferometric slope monitoring that now spreads across Asia-Pacific extraction corridors.
Australia
Western Australia's Department of Mines, Industry Regulation and Safety mandates independent third-party verification of slope monitoring systems, driving redundant sensor arrays at Pilbara iron ore operations where single-site deployments exceed fifty radar units. Queensland's Bowen Basin coal producers deploy multi-static radar networks across pit perimeters exceeding five kilometers, compressing emergency response latency from hours to minutes. Perth anchors technical support infrastructure for regional mining clients.
China
MEE geological disaster prevention standards mandate continuous slope monitoring for mines above specified production thresholds, pulling forward replacement demand across provincial highway networks and adjacent mining jurisdictions. GB standards for geological hazard prevention tighten detection requirements, forcing suppliers to accelerate certification cycles while expanding local technical support infrastructure. Shanxi and Inner Mongolia coal basins concentrate procurement under harmonizing compliance deadlines.
Indonesia
Archipelago mining operations prioritize portable rapid-deployment units and drone-mounted synthetic aperture radar platforms where road infrastructure limits ground crew access to high-risk slopes. State-owned coal producers in Kalimantan expand slope monitoring programs as regulatory frameworks mature toward Australian duty-of-care models. Papua New Guinea copper-gold projects adopt aerial survey efficiency for inaccessible terrain.
Japan
METI infrastructure resilience guidelines incorporate rockfall detection into tunnel and highway risk management protocols, driving stationary unit installations along mountain corridors. Construction firms prioritize short-range laser and radar systems for temporary slope monitoring during cut-and-fill operations. Kanto and Kansai metropolitan highway networks anchor government procurement volumes.
Vietnam
Coal expansion in Quang Ninh province lacks established monitoring infrastructure, presenting first-mover positioning for radar suppliers before regulatory frameworks mature. Bench-scale monitoring systems serve localized hazard detection at quarrying and construction applications in northern limestone belts. Hanoi-based environmental consultants deploy mixed-technology sensor arrays for compliance verification.
Asia-Pacific Rockfall Radar Market Competitive Landscape
The competitive structure tilts toward integrated sensor-to-software specialists with mine site engineering relationships. Two distinct tiers operate: premium ground-based interferometric providers serving decade-long open-pit campaigns, and agile aerial-platform integrators capturing inaccessible terrain applications. Dominant competitive moves include backward integration into embedded self-diagnostic capabilities and geographic expansion through local technical support infrastructure.
Among Australia-based monitoring specialists, Geomotion Australia and GroundProbe exemplify the premium ground-based archetype with deep Pilbara operational experience. IDS GeoRadar (Hexagon) represents the integrated conglomerate model, leveraging group-level software workflows across Australian and Southeast Asian mine sites. These three anchors demonstrate how vendor qualification programs at BHP and Rio Tinto concentrate procurement under centralized engineering departments.
| Leading Market Players |
|---|
| SkyGeo |
| Geomotion Australia |
| IDS GeoRadar (Hexagon) |
| GSSI |
| GRTIZN |
| GroundProbe |
| Canary Systems |
| GeoSIG Ltd |
| Geobrugg AG |
| Others |
Pricing and Supply Chain Analysis
High-frequency microwave components from German and Japanese precision manufacturers cascade through three-tier pricing structures across premium, standard, and economy levels, with sub-millimeter interferometric systems commanding premiums against portable units serving Vietnamese quarrying operations. Calibration labor intensity and site-specific geotechnical survey requirements embed service costs that widen spreads between turnkey installations and equipment-only procurement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments procurement by certification grade and after-sales service bundling, with GroundProbe and IDS GeoRadar systems carrying brand premiums against emerging aerial-platform integrators. Price differentiation hinges on MEE compliance certification for Chinese deployments and Western Australian duty-of-care verification protocols. Cost compression in the standard tier intensifies as terrestrial laser scanning encroaches on short-range construction applications. Quarrying contractors in Vietnam and Thailand exhibit highest price sensitivity, while Pilbara iron ore majors prioritize performance reliability over capital cost.
Supply Chain Analysis
Direct-to-mine-engineering channels handle tier-one producer demand, with centralized vendor qualification programs at BHP and Rio Tinto consolidating procurement decisions. Component manufacturing concentrates in Germany, Japan, and Switzerland for precision microwave elements, while system integration and calibration services anchor in Perth and Brisbane. Raw material dependencies span gallium nitride semiconductors, precision aluminum castings, and specialized coaxial cabling. Single-source vulnerability in high-frequency component supply exposes lead time volatility to semiconductor foundry allocation decisions. Distribution runs through certified technical partners providing site-specific commissioning support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory momentum into durable demand, with China's GB standards for geological hazard prevention mandating continuous slope monitoring and pulling forward replacement cycles across adjacent Asia-Pacific jurisdictions.
For Market Incumbents: Lock in calibration technician certification programs across Australian and Indonesian mining corridors to defend against emerging drone-mounted SAR integrators. Backward integration into embedded self-diagnostic capabilities reduces external audit frequency and deepens switching costs. Expand Perth-based technical support infrastructure to capture Indonesian regulatory harmonization toward Australian duty-of-care models.
For New Entrants and Emerging Players: Cloud-based deformation analytics platforms offer low-friction entry into Vietnam's Quang Ninh coal basin before regulatory frameworks mature. Target Papua New Guinea copper-gold projects with heavy-lift UAV SAR integration where road infrastructure limits incumbent ground crew deployment. Partner with Hanoi-based environmental consultants for compliance verification credibility.
For Investors and Strategic Acquirers: Consolidation pressure builds where multi-static radar network expertise concentrates among Australian specialists with deep Pilbara operational experience. Long-term viability favors vendors with integrated sensor-to-software workflows and mine site engineering relationships spanning decade-long open-pit campaigns. Watch for Indonesian regulatory adoption of Australian-style duty-of-care obligations as inflection signal for regional demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Static Radar Network Deployment | Western Australia's DMIRS mandates compress emergency response latency across Pilbara pit perimeters exceeding five kilometers. |
| Drone-Mounted SAR Integration | Papua New Guinea and Indonesian archipelago operations access inaccessible terrain without ground crew road infrastructure. |
| Embedded Self-Diagnostic Development | Annual recertification requirements from Western Australian regulators drive demand for reduced external audit frequency. |
| Calibration Technician Certification Programs | Site-specific geotechnical expertise scarcity creates bottlenecks that extend commissioning timelines beyond equipment delivery. |
| Cloud-Based Deformation Analytics | Automated alert generation reduces human monitoring labor across Queensland's Bowen Basin multi-pit operations. |
Research Methodology
Multiple input streams — primary interviews with mine site engineers, geotechnical consultants, and radar system procurement leads, alongside secondary validation through MEE regulatory filings, Australian state mining safety regulator guidance documents, and customs trade data for microwave component flows — were reconciled through bottom-up equipment deployment counts and top-down market sizing across the Asia-Pacific region.
Historical deployment trajectories in Western Australia's Pilbara were cross-referenced against expert panel input on Indonesian regulatory evolution and Vietnamese infrastructure buildout plans. Segmentation modeling spanned product type, end user, operating range, and monitoring technology dimensions. CAGRs were derived from slope monitoring program expansion timelines and compliance deadline clustering. Industry-specific forecast inputs incorporated iron ore production forecasts from major Pilbara operators and coal expansion schedules from Quang Ninh province.
The model assumes a particular technology adoption path; alternative pathways for drone-mounted synthetic aperture radar convergence with ground-based precision would alter the outlook for portable unit demand. Forecasts reflect assumptions regarding MEE enforcement intensity and Australian state-level regulatory harmonization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Safety
Europe Hazardous Waste Handling Automation Market
Environmental Safety
Industrial Noise Control Market
Environmental Safety
UV Air Sanitizer Market
Environmental Safety
Noise Monitoring System Market
Environmental Safety
Home Decontamination Services Market
Environmental Safety
Germany Environment Health & Safety Market
Environmental Safety
Latin America Hazardous Waste Handling Automation Market
Environmental Safety
Global Air Sampling Pumps Market
Environmental Safety
Noise Control System Market
Environmental Safety
US Home Decontamination Services Market
Environmental Safety
North America Rockfall Radar Market
Environmental Safety
China Home Decontamination Services Market
Environmental Safety
Environment Health & Safety Market
Environmental Safety
Europe Pest Control Services Market
Environmental Safety
Air Audit Equipment Market
Environmental Safety
Environmental Health and Safety Market