
 UV Air Sanitizer Market | 2026-2036
UV Air Sanitizer Market Size, Share, and Industry Trends Forecast 2026-2036
UV Air Sanitizer Market Analytics
Multi-source component procurement is broadening across the UV air sanitizer supply chain as manufacturers reduce dependence on single UV-C lamp suppliers. Daikin Industries, Ltd. leverages captive semiconductor fabrication for ballast controls, while Samsung Electronics anchors its position through vertical integration into sensor arrays and IoT modules. Xiaomi competes aggressively on cost-optimized portable units, using direct-to-consumer channel control to bypass traditional distributor markups.
UV air sanitizers employ ultraviolet germicidal irradiation, typically in the 253.7 nanometer UV-C band, to inactivate airborne microorganisms by disrupting nucleic acid structures within HVAC airflow or standalone chamber designs. These systems serve primary commercial purposes in infection control, allergen reduction, and volatile organic compound mitigation across enclosed environments. Portable units dominate residential volume but carry thinner margins, while duct-mounted systems command premium pricing in healthcare facilities where ASHRAE compliance mandates specify minimum equivalent air changes. UV-C technology leads installed base, though hybrid systems integrating photocatalytic oxidation are gaining fastest in commercial spaces seeking multi-pollutant coverage.
The EPA regulates pesticidal device claims under FIFRA, requiring substantiated efficacy data before manufacturers market pathogen-killing performance, while ASHRAE Standard 62.1 establishes ventilation rates that increasingly reference UVGI as supplementary air cleaning. OSHA workplace air quality guidelines and FDA medical device classifications for hospital-grade units further segment compliance requirements by installation environment. Stakeholders must monitor pending amendments to ASHRAE's ultraviolet air treatment standards and state-level building code adoptions that could mandate UV-C in new commercial construction.
Market Dynamics
Healthcare infrastructure mandates and ASHRAE ventilation guideline updates are forcing rapid UV-C adoption into mechanical specifications, compressing procurement cycles and rewiring supplier relationships around compliance documentation rather than pure performance metrics.
Growth Catalysts
- ASHRAE Standard 62.1:Ventilation rate mandates increasingly reference ultraviolet germicidal irradiation as supplementary air cleaning, compelling facility managers to specify UV-C in HVAC retrofits across acute care environments.
- Hospital-acquired infection protocols:Infection control committees are embedding UV air sanitizers into airborne pathogen mitigation stacks, particularly in operating theaters and isolation rooms where equivalent air changes must exceed baseline ventilation capacity.
- Photocatalytic oxidation convergence:Hybrid systems combining UV-C with titanium dioxide catalysts are capturing specification share in commercial real estate seeking multi-pollutant coverage beyond microbial inactivation.
Market Restraints
- Mercury supply concentration:Low-pressure amalgam lamp production clusters in East Asian manufacturing zones, exposing procurement schedules to raw material volatility and export control friction.
- FIFRA substantiation burden:EPA pesticidal device claims require efficacy data packages that extend product launch timelines and elevate compliance costs for pathogen-specific marketing.
- LED UV-C wavelength gap:Solid-state alternatives at 265-280 nanometer bands remain efficiency-limited below 3 mW/cm² output, constraining substitution in high-volume duct applications.
Strategic Opportunities
- India building code adoption:BIS indoor air quality standards under development are expected to mandate UV-C in new commercial construction above 50,000 square feet, opening specification windows for duct-mounted systems.
- Direct-to-consumer channel control:Portable unit manufacturers are bypassing distributor markups through owned e-commerce platforms, capturing margin compression as a competitive weapon in residential segments.
- IoT sensor convergence:Integration of real-time UV intensity monitoring with building management systems is creating subscription revenue streams and sticky specification relationships in enterprise accounts.
Industry Challenges
- Photometric calibration expertise:Field service networks lack sufficient technicians trained in UV-C dose verification using calibrated radiometers, creating deployment bottlenecks and warranty exposure.
- Legacy HVAC integration complexity:Retrofit installations in aging mechanical infrastructure require custom plenum modifications and airflow modeling that extend project timelines and elevate engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV Air Sanitizer Market |
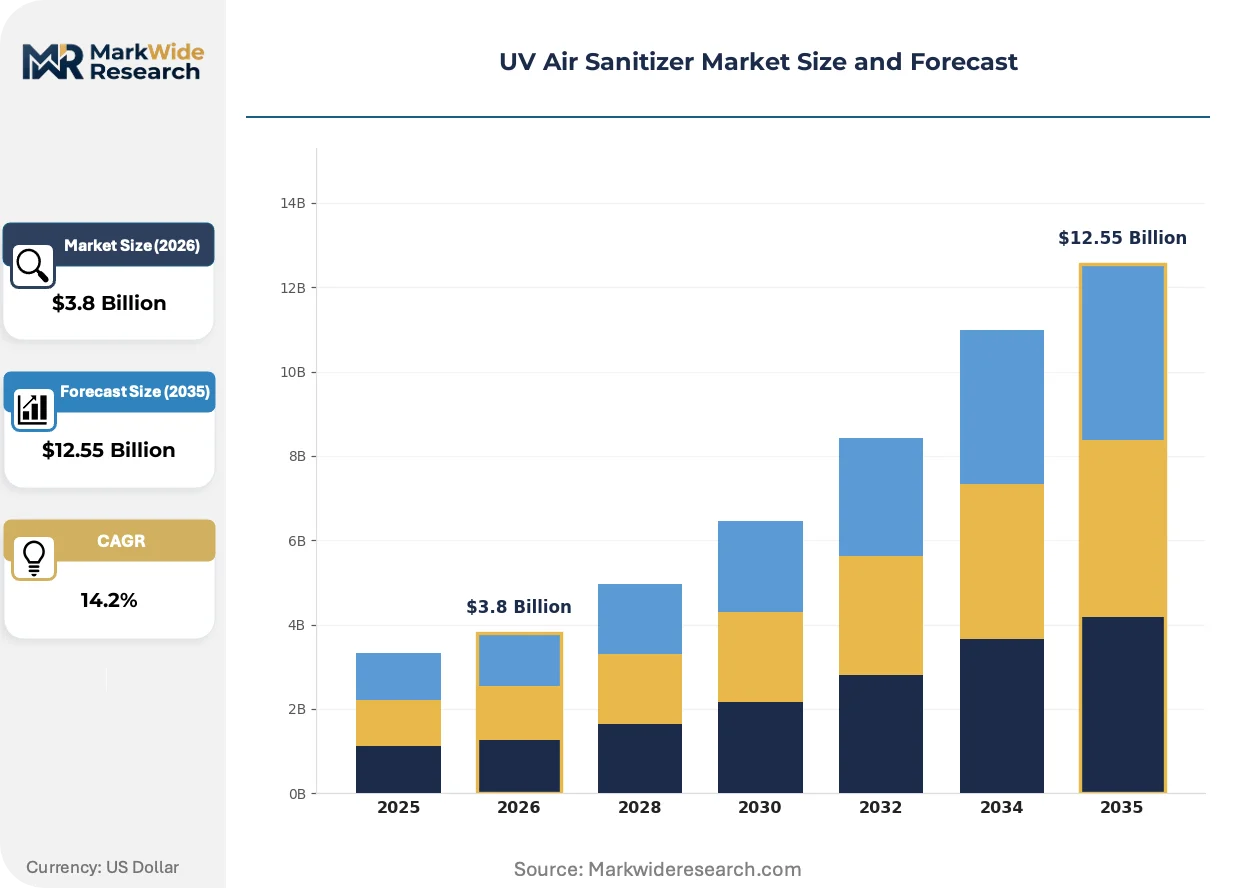
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Ceiling-Mounted Systems, Duct-Mounted Systems, Wall-Mounted Devices Application: Residential Use, Commercial Spaces, Healthcare Facilities, Indoor Air Quality Improvement Technology: UV-C, UV-V, Hybrid Systems, Ozone Generators Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Honeywell International Inc., Daikin Industries, Ltd., LG Electronics, Resideo Technologies Inc., Samsung Electronics, Xiaomi, Eureka Forbes Limited, Air Oasis LLC, Guardian Technologies LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV Air Sanitizer Market Evolving Landscape
UV air sanitizer architecture is fragmenting into configurable subsystems as buyers demand application-specific performance without full system replacement, compressing product development cycles and rewiring competitive advantage around software-defined control layers.
Excimer lamp technology is modularizing. These noble gas discharge sources emit at 172 nanometers for advanced oxidation processes without mercury content, enabling semiconductor cleanroom and pharmaceutical manufacturing adopters to satisfy sustainability procurement criteria. Equipment manufacturers are compressing their UV subsystem supplier lists to favor vendors offering field-replaceable excimer modules with standardized electrical interfaces.
REACH restrictions on mercury-containing products are tightening industrial specifications. The European Chemicals Agency regulatory trajectory is accelerating LED UV-C and excimer alternatives in EU-27 commercial building tenders, with facility managers now requiring 10-year mercury-free roadmaps in capital equipment RFPs. German and Dutch healthcare consortia are piloting excimer-based upper-room UV systems as ASHRAE compliance alternatives.
Facility managers are unbundling hardware procurement from validation services. Enterprise buyers are separating UV-C equipment purchase from third-party dose mapping and commissioning, shifting vendor relationships toward component suppliers while outsourcing performance verification to specialized environmental testing firms. This bifurcation is most pronounced in United States hospital systems responding to Joint Commission surveyor scrutiny on infection control documentation.
UV Air Sanitizer Market Segmentation
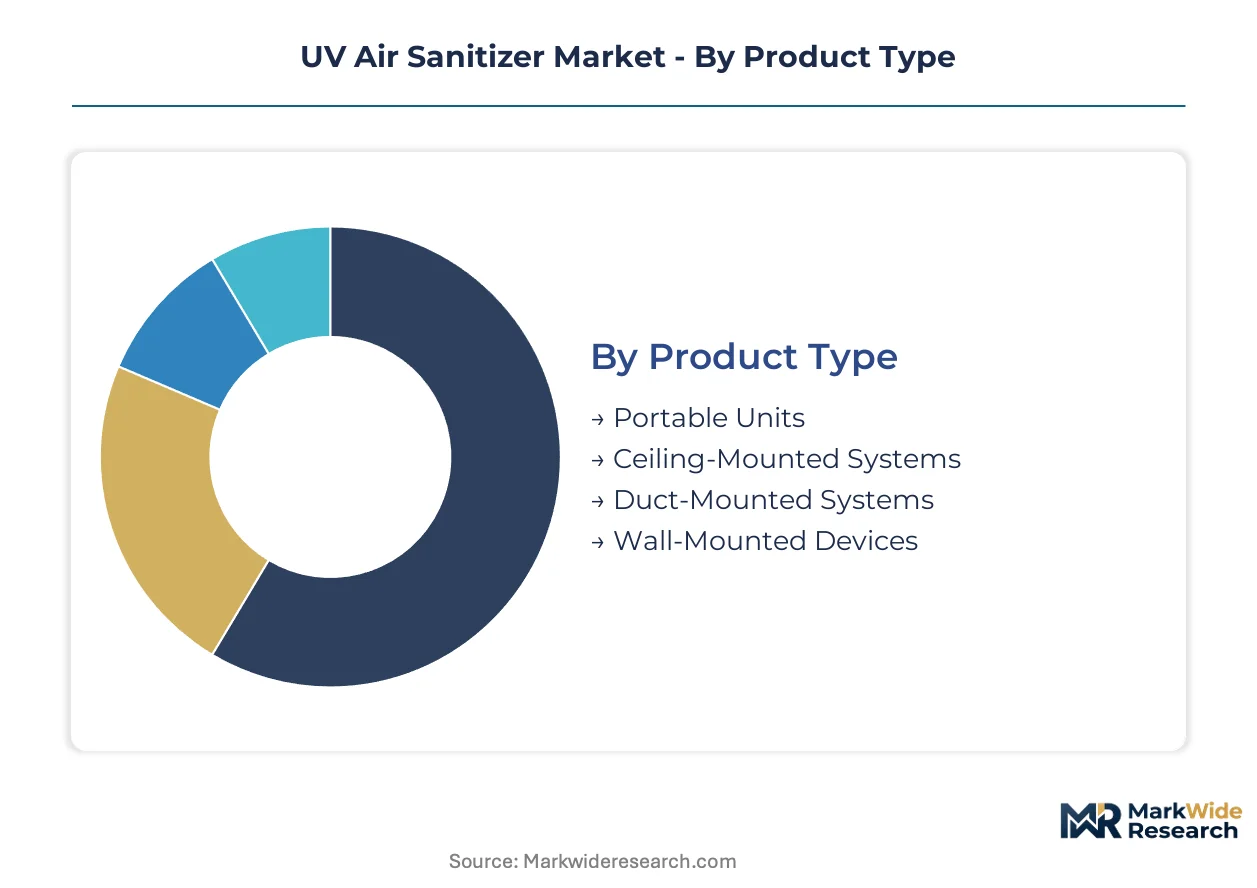
UV air sanitizer procurement patterns diverge sharply across installation environments, with specification requirements, compliance burdens, and margin structures varying by orders of magnitude between residential portable units and healthcare-grade duct-mounted systems. Understanding these segment boundaries enables targeted positioning against distinct buyer decision criteria and regulatory thresholds.
Product Type:
Specification intensity escalates with installation permanence, from plug-and-play consumer devices to engineered mechanical subsystems requiring airflow modeling and commissioning protocols.
- Duct-Mounted Systems:These permanent HVAC-integrated installations position UV-C lamp arrays within commercial air handling units, requiring ASHRAE 62.1 compliance documentation and third-party dose verification. Hospital systems in the United States specify these for operating theater and isolation room applications where equivalent air changes must exceed baseline ventilation capacity.
- Portable Units:Freestanding chamber designs with 253.7 nanometer UV-C sources and variable speed fans serve residential and small commercial environments without mechanical infrastructure modification. Xiaomi and direct-to-consumer brands dominate this segment through e-commerce channel control, capturing price-sensitive demand in urban apartments and home office configurations.
- Ceiling-Mounted Systems:Upper-room UVGI configurations suspend emitter arrays at ceiling height, creating germicidal zones above occupied spaces in high-density commercial environments.
- Wall-Mounted Devices:Fixed-position units with localized airflow patterns serve retrofit applications where duct access is impractical or where targeted zone treatment is preferred.
Duct-mounted systems lead on scale; portable units lead on momentum.
Application:
End-use environments impose distinct performance validation requirements, with healthcare procurement subject to FDA medical device classification and Joint Commission documentation scrutiny.
- Healthcare Facilities:Acute care hospitals, outpatient surgical centers, and long-term care facilities specify UV air sanitizers as airborne pathogen mitigation infrastructure. Infection control committees in United States hospital systems embed these systems into mandatory engineering controls, with procurement tied to CMS reimbursement eligibility and state department of health licensing requirements.
- Commercial Spaces:Office buildings, hospitality properties, and retail environments adopt UV-C as supplementary air cleaning to satisfy tenant wellness certifications and lease renewal negotiations. Class A commercial real estate in major metropolitan markets increasingly references UVGI in mechanical specifications as a competitive amenity.
- Residential Use:Individual consumer purchases concentrate in portable formats, with buying decisions driven by allergen sensitivity, immunocompromised household members, or post-pandemic air quality awareness.
- Indoor Air Quality Improvement:This cross-cutting application spans schools, transportation hubs, and government facilities where federal or state mandates drive procurement.
Healthcare facilities command premium pricing; commercial spaces are climbing the fastest.
Technology:
Wavelength specificity and energy source architecture determine efficacy profiles, regulatory classification, and operational constraints across deployment scenarios.
- UV-C:Low-pressure mercury amalgam lamps emitting at 253.7 nanometers remain the installed base standard for nucleic acid disruption in HVAC and standalone applications. REACH restrictions in the European Union are accelerating mercury-free alternative development, with German healthcare consortia piloting excimer-based substitutions.
- Hybrid Systems:Configurations combining UV-C with titanium dioxide photocatalytic oxidation capture specification share in commercial real estate seeking multi-pollutant coverage beyond microbial inactivation. These systems command 40-60% price premiums over baseline UV-C in United States commercial building tenders.
- UV-V:Vacuum ultraviolet bands below 200 nanometers generate ozone as a secondary oxidant, restricting deployment to unoccupied spaces and industrial applications with controlled access protocols.
- Ozone Generators:Non-UV electrochemical or corona discharge systems occupy a regulatory-complex niche, with EPA FIFRA registration requirements and OSHA workplace exposure limits constraining commercial adoption.
UV-C leads on installed base; hybrid systems lead on specification momentum.
Distribution Channel:
Channel selection determines margin capture, buyer relationship depth, and technical support obligations across segment tiers.
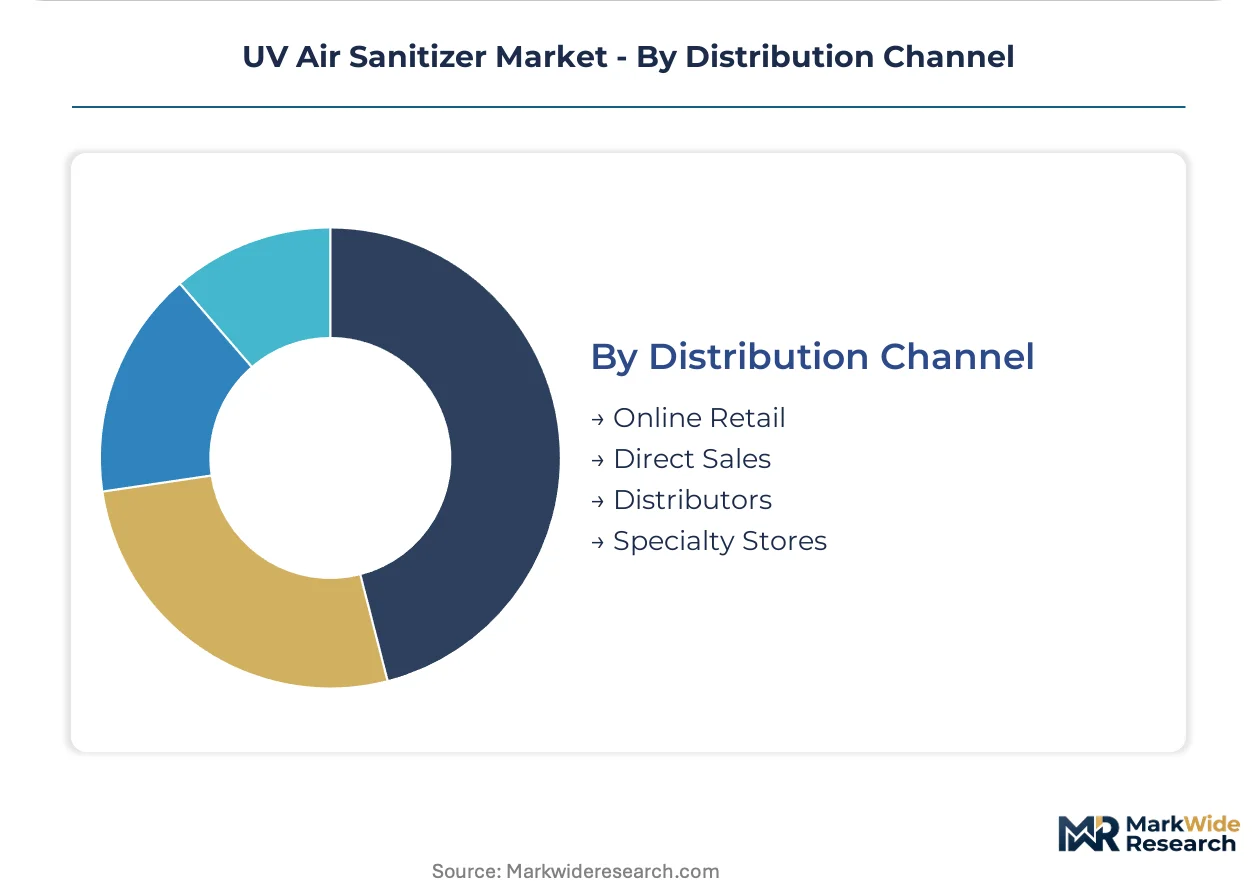
- Direct Sales:Manufacturer-led specification engineering and project management dominates healthcare and large commercial procurement, with Daikin Industries and dedicated UV-C specialists maintaining captive sales organizations for ASHRAE compliance consultation.
- Distributors:HVAC wholesale networks handle duct-mounted system logistics for mechanical contractor channels, with inventory positioning and field service capabilities creating sticky relationships in retrofit markets.
- Online Retail:E-commerce platforms concentrate portable unit volume, with Amazon and direct-to-consumer sites enabling price transparency and bypassing traditional distributor markups.
- Specialty Stores:Home improvement and wellness retail channels serve residential buyers seeking in-person product demonstration and immediate fulfillment.
Direct sales leads on contract value; online retail leads on transaction velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital infrastructure upgrades and federal indoor air quality mandates concentrate procurement clusters in acute care environments. Healthcare facilities expand UV-C installations to reduce airborne pathogen transmission. Compliance-driven procurement accelerates under EPA Indoor airPLUS and ASHRAE ventilation guidelines.
United States
Hospital infrastructure retrofits and CMS reimbursement eligibility drive specification intensity in acute care settings. Joint Commission surveyor scrutiny on infection control documentation elevates third-party dose verification requirements. Procurement clusters concentrate in Texas Medical Center and Greater Boston hospital systems.
Germany
REACH restrictions on mercury-containing products accelerate LED UV-C and excimer alternatives in commercial building tenders. Facility managers require mercury-free roadmaps in capital equipment RFPs. German healthcare consortia pilot excimer-based upper-room UV systems as ASHRAE compliance alternatives.
China
Low-pressure amalgam lamp production clusters expose procurement schedules to raw material volatility and export control friction. GB standards for indoor air quality shape domestic specification requirements. Manufacturing concentration in Yangtze River Delta sustains global supply chain positioning.
India
BIS indoor air quality standards under development mandate UV-C in new commercial construction above 50,000 square feet. Specification windows open for duct-mounted systems in metropolitan office developments. Demand concentrates in Delhi-NCR and Mumbai commercial real estate markets.
Japan
Semiconductor cleanroom and pharmaceutical manufacturing adopters satisfy sustainability procurement criteria through mercury-free alternatives. METI efficiency standards shape product development priorities. Industrial demand clusters in Kansai and Chubu manufacturing corridors.
UV Air Sanitizer Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cost-optimized portable formats and direct-to-consumer channel control. The vendor base stratifies across captive semiconductor fabricators, HVAC-integrated system specialists, and volume-driven consumer electronics platforms. Three archetypes dominate: vertically integrated conglomerates with ballast control in-house production, direct-to-consumer specialists bypassing distributor markups, and HVAC OEMs with specification engineering capabilities. Competitive moves center on backward integration into sensor arrays and IoT modules, plus strategic compression of UV subsystem supplier lists.
Among diversified conglomerates, Daikin Industries, Ltd. and Samsung Electronics occupy positions anchored by captive supply of control electronics and upstream integration into connected device platforms. Xiaomi exemplifies the cost-optimized archetype through direct-to-consumer channel control. Honeywell International Inc. represents the specification-engineering tier with ASHRAE compliance consultation capabilities.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Daikin Industries, Ltd. |
| LG Electronics |
| Resideo Technologies Inc. |
| Samsung Electronics |
| Xiaomi |
| Eureka Forbes Limited |
| Air Oasis LLC |
| Guardian Technologies LLC |
| Others |
Value Network & Pricing Analysis
Excimer lamp modularization and mercury-free technology transitions are compressing cost curves for semiconductor cleanroom adopters while fragmenting supplier power across East Asian lamp manufacturing zones. REACH restrictions in the European Union are accelerating specification premiums for mercury-free alternatives, creating dual-tier cost structures that reward early compliance investment.
Pricing Analysis
Input-cost pass-through from low-pressure amalgam lamp production clusters in China directly affects duct-mounted system pricing, with mercury supply volatility translating into contract renegotiation cycles. Three-tier pricing structure across premium, standard, and economy levels separates ASHRAE-compliant healthcare-grade systems from commercial retrofit units and portable consumer devices. Cost compression in residential portable segments is intensifying because direct-to-consumer channel control eliminates distributor markups. Healthcare facilities demonstrate lowest price sensitivity due to CMS reimbursement eligibility and Joint Commission documentation requirements.
Supply Chain Analysis
Single-source vulnerability sits with East Asian mercury amalgam lamp production, where Yangtze River Delta manufacturing concentration exposes procurement schedules to export control friction. Geographic supply concentration centers on China for lamp fabrication, Germany for excimer module engineering, and Japan for semiconductor-grade ballast controls. Raw material dependencies rest on mercury supply chains, quartz glass envelopes, and rare gas noble mixtures for excimer alternatives. Tariff exposure represents the primary structural risk as trade policy shifts affect component sourcing economics. Distribution runs through HVAC wholesale networks for commercial duct systems and direct-to-consumer platforms for residential portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UV air sanitizer market functions as a stable compounder anchored by permanent healthcare infrastructure mandates and evolving ASHRAE ventilation standards that embed UV-C into mechanical specifications regardless of economic cycles.
For Market Incumbents: Hedge against LED UV-C wavelength efficiency gaps by maintaining dual-source lamp procurement strategies across mercury amalgam and excimer alternatives. Secure captive supply of IoT sensor arrays to defend against direct-to-consumer specialists encroaching on enterprise accounts. Invest in ASHRAE compliance documentation capabilities to differentiate from emerging entrants lacking specification engineering depth.
For New Entrants and Emerging Players: LED UV-C solid-state efficiency breakthroughs above 3 mW/cm² output represent the most penetrable technology wedge for duct-mounted retrofits. Target India commercial construction above 50,000 square feet where BIS indoor air quality standards create specification windows without entrenched incumbent relationships. Pursue direct-to-consumer channel control for portable units, bypassing traditional HVAC distributor networks entirely.
For Investors and Strategic Acquirers: Valuations sit cheapest among HVAC-integrated system specialists with ASHRAE consultation capabilities but limited brand recognition in consumer segments. Long-term viability over the next decade rests on regulatory embedding rather than discretionary demand, favoring enterprises with compliance documentation infrastructure. Watch for LED UV-C efficiency inflection above 3 mW/cm² as the signal triggering substitution acceleration in high-volume duct applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Mercury-Free Technology Transition | REACH restrictions in the European Union are accelerating excimer and LED UV-C alternatives in commercial tenders. |
| IoT Sensor Integration | Real-time UV intensity monitoring with building management systems creates subscription revenue streams in enterprise accounts. |
| Direct-to-Consumer Channel Control | Owned e-commerce platforms enable margin capture as a competitive weapon in residential portable segments. |
| ASHRAE Compliance Documentation Investment | Third-party dose verification capabilities satisfy Joint Commission scrutiny in United States hospital procurement. |
| Backward Integration into Ballast Controls | Captive semiconductor fabrication reduces dependence on external suppliers for UV-C lamp driver electronics. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with HVAC specification engineers, infection control committee members at hospital systems, commercial facility managers, and UV-C equipment procurement leads. Secondary validation draws from ASHRAE standard documentation, EPA FIFRA registration databases, REACH regulatory filings, and customs trade data for lamp component flows. Bottom-up segment sizing triangulates against top-down market construction across product type, application, technology, and distribution channel dimensions.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include installation permanence, end-use environment compliance burden, wavelength technology architecture, and channel relationship depth. CAGRs derive from fitted trend extrapolation adjusted for regulatory mandate timing and infrastructure replacement cycles. Industry-specific forecast inputs incorporate hospital capital expenditure patterns and commercial real estate mechanical specification refresh rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to LED UV-C efficiency breakthroughs, mercury supply disruptions, and ASHRAE standard amendment schedules. Forecasts reflect documented assumptions about technology substitution curves and regulatory adoption timelines. Specific risks that could revise projections include excimer lamp cost reduction acceleration, export control expansion affecting East Asian lamp production, and state-level building code mandates outpacing federal guideline development. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Safety
Latin America Hazardous Waste Handling Automation Market
Environmental Safety
Environmental Health and Safety Market
Environmental Safety
China Home Decontamination Services Market
Environmental Safety
Europe Pest Control Services Market
Environmental Safety
Air Audit Equipment Market
Environmental Safety
Germany Environment Health & Safety Market
Environmental Safety
North America Rockfall Radar Market
Environmental Safety
Industrial Noise Control Market
Environmental Safety
Noise Control System Market
Environmental Safety
Europe Process Safety Services Market
Environmental Safety
Environment Health & Safety Market
Environmental Safety
Europe Hazardous Waste Handling Automation Market
Environmental Safety
Global Air Sampling Pumps Market
Environmental Safety
US Home Decontamination Services Market
Environmental Safety
Asia-Pacific Rockfall Radar Market
Environmental Safety
Noise Monitoring System Market